
 Global Polyoxymethylene (POM) Market | 2026-2036
Global Polyoxymethylene (POM) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Polyoxymethylene (POM) Market Foresight
Direct distribution from resin producers to tier-one automotive parts suppliers is rewriting traditional channel economics in engineered polymers. Celanese Corporation leverages its integrated acetal resin manufacturing network to sustain supply security for North American automotive customers. Korea Engineering Plastics Co., Ltd. anchors its position through captive feedstock access and dedicated homo-polymer capacity serving domestic electronics manufacturers. BASF SE competes by extending its technical service reach into precision instrument applications across Western Europe.
Polyoxymethylene is a high-crystalline thermoplastic engineering polymer synthesized primarily from formaldehyde via anionic polymerization, yielding a linear chain structure with repeating oxymethylene units and melting points between 165°C and 175°C. Its primary industrial purpose centers on replacing metal in precision mechanical components requiring low friction, dimensional stability, and fatigue resistance. Co-Polymer POM dominates volume consumption due to superior thermal and chemical stability relative to homo-polymer grades, while Modified POM captures margin pools through glass-filled and lubricated formulations targeting gear and bearing applications. High-Flow POM represents the fastest-expanding product category as thin-wall molding requirements intensify in electrical components and miniaturized consumer goods.
REACH registration requirements and RoHS substance restrictions in Europe, alongside EPA formaldehyde emission standards in the United States, shape product formulation decisions and market access conditions for POM manufacturers worldwide. Japan's METI chemical substance reporting framework and China's GB standards for plastic materials in electrical applications add compliance layers that favor producers with established regulatory affairs capabilities. Stakeholders must monitor evolving PFAS restrictions and formaldehyde reclassification debates, as these regulatory trajectories will determine which polymer grades retain market access and which applications face forced material substitution.
Market Dynamics
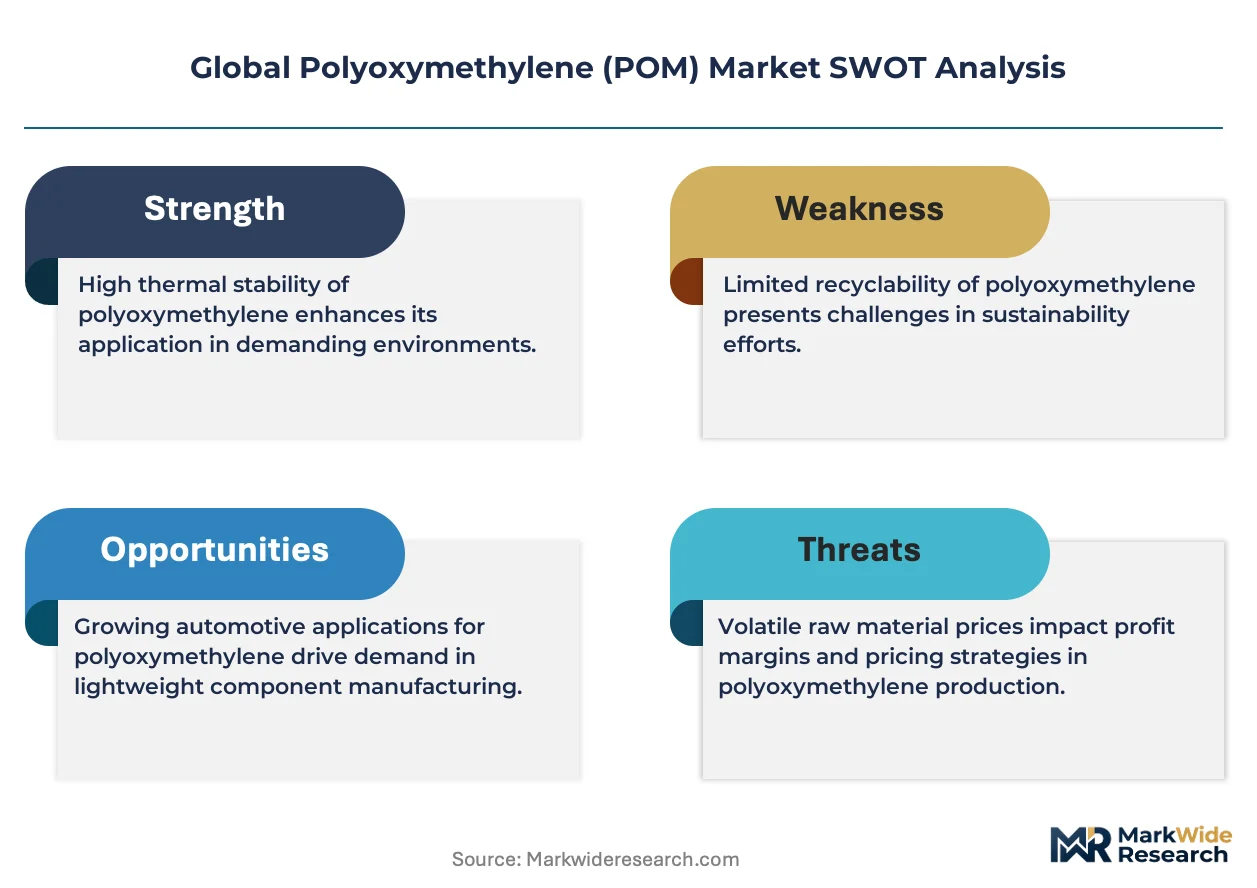
Automotive lightweighting mandates and formaldehyde emission regulations are compressing formulation cycles while forcing resin producers to requalify grades across multiple jurisdictions simultaneously.
Growth Catalysts
- Fuel system component demand:Automotive suppliers in Germany and the United States specify POM for fuel sender units and quick-connect fittings to meet EPA and NHTSA durability standards.
- REACH low-emission grade substitution:ECHA registration deadlines accelerate replacement of legacy acetal resins in European appliance manufacturing.
- Thin-wall molding:High-Flow POM enables miniaturized electrical housings for precision electronics clusters in Shenzhen and Seoul.
Market Restraints
- Formaldehyde feedstock volatility:Methanol-to-formaldehyde cost swings compress margins for non-integrated compounders.
- Homo-polymer supply concentration:Captive production in South Korea and Japan limits spot market liquidity for specialty grades.
- PFAS scrutiny:Proposed EPA restrictions on fluorinated processing aids threaten lubricated POM formulations.
Strategic Opportunities
- Medical device precision parts:ISO 10993 biocompatibility certification opens surgical instrument handles and drug delivery mechanisms to POM substitution.
- India appliance manufacturing:BIS standards alignment and domestic washing machine production create import substitution potential for co-polymer grades.
- Closed-loop recycling:Mechanical regrind protocols for automotive scrap establish circular material flows qualifying for EU Green Deal procurement.
Industry Challenges
- Multi-jurisdiction registration:Simultaneous REACH, EPA, and METI filing requirements strain regulatory affairs capacity.
- Legacy mold requalification:Tooling designed for homo-polymer grades requires redesign to accommodate high-flow co-polymer shrinkage profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Polyoxymethylene (POM) Market |
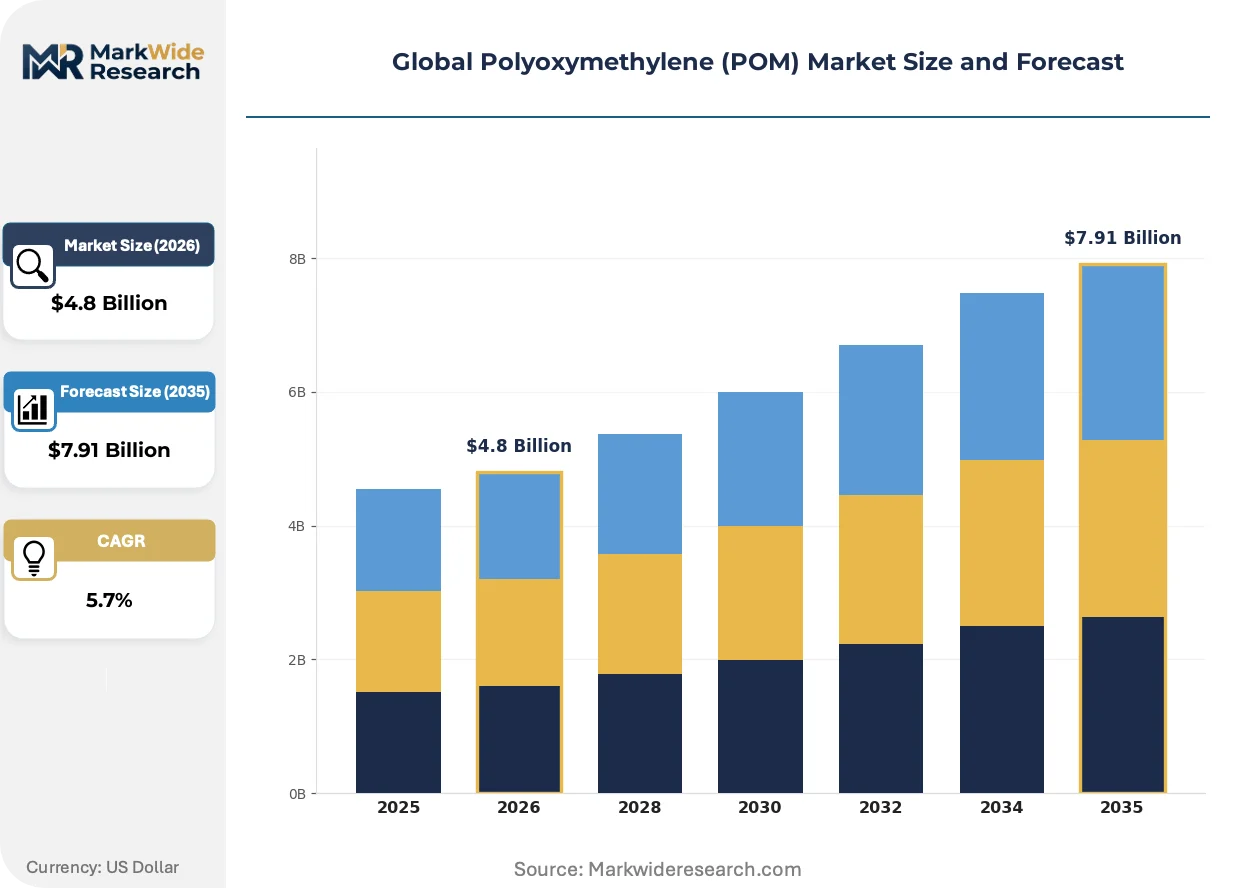
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Homo-Polymer POM, Co-Polymer POM, Modified POM, High-Flow POM, High-Impact POM Application: Electrical Components, Consumer Goods, Industrial Machinery, Precision Instruments, Packaging Equipment End User Industry: Electronics Manufacturing, Appliance Production, Automotive Parts Suppliers, Textile Equipment, Sports Equipment Fabrication Form: Granules, Pellets, Powder, Sheets, Films |
| Companies Covered | DuPont de Nemours, Inc., LG Chem Ltd., Celanese Corporation, Korea Engineering Plastics Co., Ltd., Asahi Kasei Corporation, Polyplastics Co., Ltd., Mitsubishi Chemical Corporation, Ensinger GmbH, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Polyoxymethylene (POM) Market Shifts & Advancements
Material science advances and regulatory chemistry restrictions are converging to redefine which POM grades retain market access and which applications face forced substitution.
Glass-filled and carbon-reinforced modified POM is migrating from conventional gear applications into structural automotive pedals and seat recliner mechanisms. Tier-one suppliers in Stuttgart and Detroit specify these grades to replace metal stampings while maintaining crash-load requirements. The shift compresses the addressable market for unreinforced homo-polymer in load-bearing components.
REACH Annex XIV authorization and RoHS substance restrictions tighten allowable additive packages in European electrical housings. ECHA evaluations of formaldehyde reclassification trigger reformulation of heat-stabilized grades used in connector applications. Producers with pre-registered low-emission portfolios capture requalification windows at appliance OEMs in Italy and Poland.
Direct resin producer-to-automotive tier contracts displace traditional distributor stocking models in North American fuel system supply chains. Tier-one buyers in Michigan and Ontario negotiate annual volume commitments with Celanese and DuPont for just-in-line delivery. This consolidation concentrates procurement leverage among the largest stampers while marginalizing regional compounders lacking dedicated automotive technical service teams.
Global Polyoxymethylene (POM) Market Segmentation
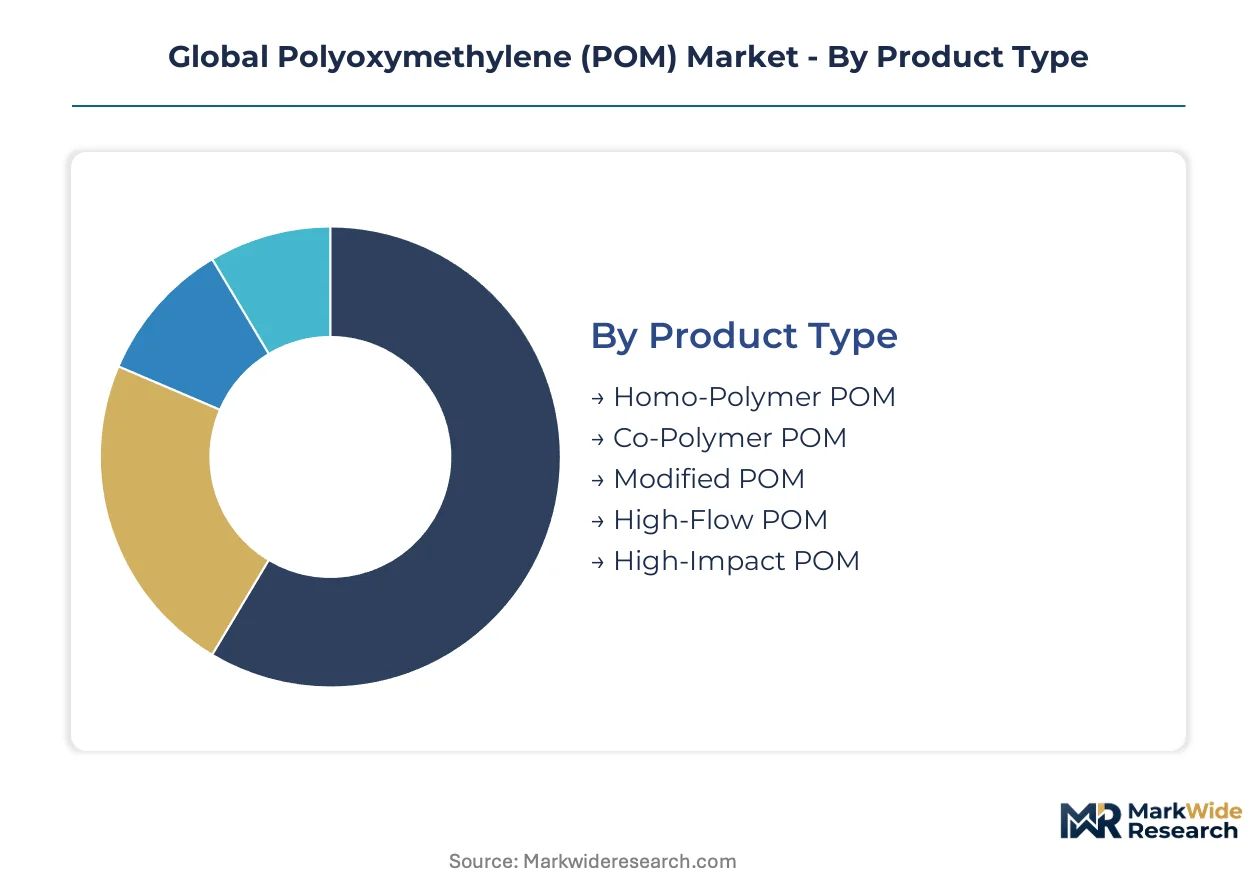
POM grade selection determines molding cycle efficiency, regulatory compliance pathways, and end-use qualification timelines across automotive, electronics, and industrial supply chains. Segment boundaries in this market reflect crystallinity differences, flow characteristics, and additive packages that lock processors into specific tooling and processing windows.
Product Type:
Cycle times vary dramatically across POM grades, with high-flow formulations enabling thinner walls and faster cooling while modified grades require longer residence times for fiber dispersion and dimensional stability.
- Homo-Polymer POM:Maximum crystallinity grade synthesized via anionic polymerization of formaldehyde, delivering tensile strength above 70 MPa and fatigue resistance for gear and bearing applications. Demand concentrates in Japanese and South Korean precision machinery clusters where captive producers supply domestic electronics molders with just-in-time granule delivery. Formaldehyde emission regulations in Germany and the United States are forcing requalification of legacy homo-polymer grades in fuel system applications.
- Co-Polymer POM:Ethylene oxide co-monomer incorporation disrupts crystalline regularity, improving thermal stability and hydrolysis resistance for hot-water appliance components and under-hood automotive parts. Chinese appliance manufacturers in Guangdong and Zhejiang provinces specify co-polymer grades for washing machine pump housings and dishwasher spray arms, prioritizing GB standard compliance and supply security from regional compounders.
- Modified POM:Glass-filled and lubricated formulations targeting structural load-bearing applications with enhanced stiffness and wear resistance.
- High-Flow POM:Low molecular weight distribution enabling thin-wall molding below 0.5 mm thickness for miniaturized electrical connectors and mobile device structural frames.
- High-Impact POM:Elastomer-modified grades absorbing impact energy for snap-fit assemblies and sporting equipment components subject to dynamic loading.
Co-Polymer POM dominates installed base across appliance and automotive applications. High-Flow POM is where expansion concentrates as electronics miniaturization accelerates mold complexity requirements.
Application:
Application segments stratify by qualification burden, with automotive fuel system components requiring multi-year validation cycles and consumer goods permitting rapid grade switching based on resin pricing.
- Electrical Components:Connector housings, switch mechanisms, and coil bobbins demanding tight dimensional tolerances and UL94 flammability ratings. Shenzhen and Seoul electronics clusters specify high-flow grades for USB-C housings and circuit breaker internals, with RoHS compliance and REACH SVHC screening determining supplier qualification.
- Consumer Goods:Zippers, fasteners, and appliance buttons where cost optimization and colorability drive grade selection. Indian appliance OEMs in Pune and Chennai are substituting co-polymer POM for metal in washing machine dial mechanisms, supported by BIS standards alignment and domestic molding capacity expansion.
- Industrial Machinery:Conveyor system components and pump valves requiring chemical resistance and mechanical durability in continuous operation environments.
- Precision Instruments:Surgical tool handles and laboratory equipment where ISO 10993 biocompatibility certification opens medical device substitution opportunities.
- Packaging Equipment:Bottle cap molds and filling machine components subject to FDA food contact regulations in the United States and EFSA compliance in Europe.
Industrial Machinery commands the longest replacement cycles and deepest supplier relationships. Electrical Components is where formulation innovation and regulatory requalification activity concentrates.
End User Industry:
End user concentration patterns reflect regional manufacturing specialization, with electronics fabrication anchoring East Asian demand and automotive supply chains driving European and North American offtake.
- Electronics Manufacturing:Printed circuit board hardware, connector systems, and mobile device structural elements. Korean Engineering Plastics supplies homo-polymer grades to Samsung and LG affiliates for smartphone button mechanisms, leveraging captive formaldehyde integration and METI substance reporting compliance.
- Appliance Production:Washing machine pumps, dishwasher spray arms, and refrigerator compressor components. Chinese domestic brands Haier and Midea specify co-polymer grades with enhanced hydrolysis resistance for 10-year warranty compliance under GB standards.
- Automotive Parts Suppliers:Fuel sender units, seat belt components, and interior mechanisms subject to OEM material approvals and emission regulations.
- Textile Equipment:Loom components and knitting machine parts requiring low friction and abrasion resistance in high-speed fiber processing.
- Sports Equipment Fabrication:Ski binding mechanisms and bicycle derailleur systems where impact resistance and UV stability determine grade selection.
Automotive Parts Suppliers maintains the highest barrier to entry through OEM qualification protocols. Appliance Production is where regional supply chain localization and import substitution efforts concentrate.
Form:
Form factor selection locks processors into specific feeding and drying infrastructure, with pellet uniformity and moisture content specifications determining molding yield rates.
- Granules:Irregular particle morphology for compounding operations and masterbatch incorporation, dominating custom color matching workflows.
- Pellets:Cylindrical extruded form with tight dimensional tolerances for automated feeding systems in high-volume injection molding. Celanese and DuPont supply automotive tier-one processors in Michigan and Ontario with pelletized co-polymer grades optimized for consistent melt flow index and low formaldehyde emission profiles.
- Powder:Fine particle size distribution for rotational molding, sintering, and coating applications in industrial lining and porous filter manufacturing.
- Sheets:Extruded flat stock for thermoforming into equipment housings and machinery guards requiring chemical resistance and rigidity.
- Films:Thin-gauge extruded product for release liners and separation membranes in battery and fuel cell assembly processes.
Pellets dominate high-volume injection molding infrastructure globally. Powder and film forms are where specialized application development and niche specification growth concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH authorization timelines and EPA formaldehyde emission standards are redirecting procurement flows toward jurisdictions with established regulatory compliance infrastructure. Germany, China, the United States, South Korea, and Japan concentrate the bulk of formulation innovation and automotive qualification activity.
Germany
Fuel system component demand from Stuttgart-based automotive suppliers specifies low-emission POM grades for quick-connect fittings. ECHA REACH Annex XIV deadlines accelerate substitution of legacy acetal resins in appliance manufacturing. The Baden-Württemberg precision engineering cluster sustains homo-polymer consumption for gear and bearing applications despite formaldehyde reclassification pressures.
China
Domestic appliance production by Haier and Midea anchors co-polymer offtake for washing machine pumps and dishwasher spray arms. GB standards for plastic materials in electrical applications tighten additive specifications for connector housings. The Pearl River Delta electronics manufacturing corridor in Shenzhen drives high-flow POM specification for miniaturized USB-C housings and circuit breaker internals.
United States
EPA formaldehyde emission standards and NHTSA durability requirements compress formulation cycles for fuel sender units. Michigan and Ontario-based tier-one automotive processors negotiate direct resin contracts for just-in-line delivery. The Detroit automotive supply chain concentrates procurement leverage among stampers with dedicated technical service relationships.
South Korea
Captive homo-polymer production serves Samsung and LG affiliates for smartphone button mechanisms and precision electronics components. METI chemical substance reporting frameworks shape export compliance protocols for Japanese-bound shipments. The Busan-Ulsan petrochemical corridor sustains backward integration into formaldehyde feedstock for dedicated polymer capacity.
Japan
Precision machinery clusters in the Chubu/Nagoya region maintain demand for maximum crystallinity grades in gear and bearing applications. METI substance reporting and JIS standards alignment create compliance layers favoring producers with established regulatory affairs capabilities. Domestic electronics molders receive just-in-time granule delivery from captive producers with integrated acetal resin networks.
Global Polyoxymethylene (POM) Market Competitive Landscape
On the supply side, the industry is consolidating around integrated resin producers with captive formaldehyde capacity and established automotive qualification protocols. Three archetypes dominate: multinational chemical conglomerates with diversified polymer portfolios, regional specialists with backward integration into feedstock, and compounders serving niche electrical and medical device specifications. Competitive moves concentrate on direct tier-one automotive contracts displacing distributor models, and capacity expansion in China and South Korea to serve regional appliance and electronics demand.
Among multinational chemical conglomerates, Celanese Corporation and BASF SE exemplify the integrated archetype with technical service reach extending into precision instrument and automotive applications. Korea Engineering Plastics Co., Ltd. occupies a position within the regional specialist tier, leveraging captive feedstock access and dedicated homo-polymer capacity. These three companies represent distinct strategic postures: North American supply security, European technical service depth, and East Asian captive integration.
| Leading Market Players |
|---|
| DuPont de Nemours, Inc. |
| LG Chem Ltd. |
| Celanese Corporation |
| Korea Engineering Plastics Co., Ltd. |
| Asahi Kasei Corporation |
| Polyplastics Co., Ltd. |
| Mitsubishi Chemical Corporation |
| Ensinger GmbH |
| BASF SE |
| Others |
Supply & Pricing Matrix
Captive formaldehyde production in South Korea and Japan anchors margin capture at the resin synthesis stage, while non-integrated compounders in Europe and North America face feedstock cost volatility that compresses their position in downstream formulation tiers.
Pricing Analysis
Volume-discount tiering structures separate automotive tier-one annual contracts from spot purchases by regional appliance molders. Pricing stratifies across premium, standard, and economy tiers based on REACH pre-registration status and formaldehyde emission certification levels. Cost compression in standard grades is intensifying because methanol-to-formaldehyde cost swings transmit directly to non-integrated producers. Regional appliance molders exhibit highest price sensitivity, while fuel system suppliers prioritize supply security over unit cost.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk assessment for electrical housing producers serving dual-region OEMs. Production gravity centers on China, South Korea, and Germany, with formaldehyde feedstock and ethylene oxide co-monomer availability tethered to regional petrochemical corridor capacity. Single-source vulnerability persists for high-purity homo-polymer grades where Japanese and Korean producers maintain dedicated lines. Distribution runs through direct resin producer-to-tier contracts in automotive, with distributor stocking models persisting in appliance and consumer goods channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The POM market sits in early-cycle expansion as medical device precision parts and closed-loop automotive recycling create new addressable demand pools beyond traditional metal substitution applications.
For Market Incumbents: Pre-empt regulatory requalification windows by accelerating low-emission grade portfolios ahead of ECHA formaldehyde reclassification deadlines. Backward integration into methanol-to-formaldehyde capacity defends margin position against feedstock volatility that threatens non-integrated compounders. Channel control through dedicated technical service teams locks in tier-one automotive procurement leverage.
For New Entrants and Emerging Players: India's domestic appliance manufacturing corridor offers white-space penetration as BIS standards alignment and washing machine production expansion outpace regional resin supply. Medical device precision parts present a second avenue, with ISO 10993 certification gaps among incumbent producers creating qualification opportunities for focused entrants. A co-polymer specialization strategy targeting hydrolysis-resistant grades for hot-water appliance components enables faster OEM approval cycles than multi-grade portfolios.
For Investors and Strategic Acquirers: Capital is best deployed toward regional specialists with captive feedstock access and established automotive qualification protocols rather than pure-play compounders lacking backward integration. Long-term viability hinges on regulatory affairs capacity spanning REACH, EPA, and METI filing requirements. The signal to watch is PFAS restriction implementation timelines, which will determine which lubricated formulation portfolios retain market access versus face forced substitution.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Formaldehyde Feedstock | Celanese and Korea Engineering Plastics sustain margin capture through captive methanol-to-formaldehyde capacity. |
| REACH Low-Emission Grade Pre-Registration | Producers with pre-registered portfolios capture requalification windows at appliance OEMs in Italy and Poland. |
| Direct Tier-One Automotive Contracts | Annual volume commitments with Michigan and Ontario processors displace distributor stocking models in fuel systems. |
| Medical Device Biocompatibility Certification | ISO 10993 qualification opens surgical instrument handles and drug delivery mechanisms to POM substitution. |
| Closed-Loop Automotive Recycling Protocols | Mechanical regrind flows for automotive scrap establish circular material qualification under EU Green Deal procurement. |
Research Methodology
Desk research of trade customs data, SEC chemical segment filings, and ECHA registration databases preceded structured interviews with resin plant managers, tier-one automotive procurement leads, appliance OEM technical directors, and distribution channel partners. Primary fieldwork across the Baden-Württemberg precision engineering cluster, Shenzhen electronics corridor, and Michigan automotive supply chain informed grade-specific demand segmentation. Bottom-up volume modeling triangulated against top-down industry association aggregates.
Assumptions held formaldehyde feedstock cost volatility within observed methanol pricing bands while varying REACH authorization timelines and PFAS restriction implementation across scenario cases. Segmentation dimensions spanned crystallinity grade, flow characteristics, end-use industry qualification burden, and regional regulatory compliance infrastructure. CAGRs derived from fitted trend extrapolation validated against historical substitution elasticities between POM and competing engineering polymers. Industry-specific inputs included automotive lightweighting content-per-vehicle trajectories and electronics miniaturization mold complexity indices.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-backed petrochemical producers or accelerated PFAS bans would shift outcomes materially. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Europe Engineering Plastics Market
Polymers & Resins
Isosorbide-Based Engineering Polymer Monomers Market
Polymers & Resins
Middle East and Africa Polyurethane Market
Polymers & Resins
Bio-Sourced Nylon Market
Polymers & Resins
Linear Low Density Polyethylene Lldpe Market
Polymers & Resins
North America Polymer Emulsion Market
Polymers & Resins
South America Polymer Emulsion Market
Polymers & Resins
Acrylic Resins Market
Polymers & Resins
Germany Engineering Plastics Market
Polymers & Resins
Europe Polyolefin Foam Market
Polymers & Resins
Fluorine Polymer Films Market
Polymers & Resins
Global Cyanate Ester Resins Market
Polymers & Resins
Global Low Density Polyethylene (LDPE) Foams Market
Polymers & Resins
Asia-Pacific Polyamide Market
Polymers & Resins
Global Polypropylene Random Copolymer Market
Polymers & Resins
Europe Polycarbonate (PC) Market