
 Global Epoxy Primer Market | 2026-2036
Global Epoxy Primer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Epoxy Primer Market Foresight
Infrastructure developers is reorganizing procurement priorities toward corrosion-resistant steel coatings for bridges, ports, and industrial facilities. PPG Industries sustains manufacturing scale across North American and European production networks. Akzo Nobel NV specializes in marine-grade epoxy systems with extended salt-spray performance. Jotun A/S dominates Nordic and Middle Eastern shipyard supply chains through direct technical service models.
Epoxy primer is a two-component thermosetting coating based on epoxy resin and polyamine or polyamide curing agents, formulated to achieve dry film thickness of 75–250 microns for substrate adhesion and barrier protection. Its primary industrial purpose is to seal ferrous and non-ferrous surfaces against moisture ingress while providing a chemically resistant base for subsequent topcoat layers. Waterborne formulations are gaining fastest in jurisdictions with stringent VOC limits, though solvent-based systems still anchor marine and heavy-equipment segments where recoat windows and surface tolerance matter most. Among end users, steel fabricators represent the broadest volume pool, while aircraft manufacturers command premium pricing through qualification-intensive specification chains.
EPA regulates VOC emissions from architectural and industrial maintenance coatings under 40 CFR Part 59, directly constraining solvent-based epoxy primer formulations in the United States. ECHA administers REACH restrictions on chromium trioxide and isocyanate content, reshaping anti-corrosion additive choices across European supply chains. China's MEE enforces GB standards on hazardous substance limits in coatings, compelling domestic and imported producers to reformulate. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and redundant certification costs.
Market Dynamics
Regulatory divergence between jurisdictions is fragmenting formulation standards and forcing producers to maintain parallel product lines, while waterborne chemistry advances erode the performance gap with solvent-based systems.
Growth Catalysts
- Shipbuilding procurement:Hull protection specifications in Chinese and South Korean shipyards are expanding epoxy primer volumes for newbuild and maintenance cycles.
- REACH compliance pressure:ECHA restrictions on chromium trioxide and isocyanate content are accelerating reformulation toward compliant anti-corrosion additives across European supply chains.
- Infrastructure steel coating:Bridge and port developers in India and Brazil are specifying corrosion-resistant primers for structural longevity in coastal environments.
Market Restraints
- Petrochemical feedstock volatility:Epoxy resin prices track bisphenol-A and epichlorohydrin markets, compressing margin predictability for formulators.
- Specialty amine supply concentration:Polyamide curing agent production clusters in Germany and China create geographic vulnerability for non-integrated coating manufacturers.
- Recoat window limitations:Waterborne systems require extended cure times versus solvent-based alternatives, restricting adoption in maintenance turnaround schedules.
Strategic Opportunities
- Wind turbine OEM specifications:Offshore wind foundation manufacturers in Denmark and the UK are qualifying high-build epoxy primers for splash-zone protection.
- GB standards harmonization:China's MEE enforcement of hazardous substance limits is creating compliance service demand for foreign producers entering domestic distribution.
- Direct technical service models:Shipyard supply chains in the Middle East are consolidating procurement around integrated coating system providers with on-site application support.
Industry Challenges
- Formulation chemist scarcity:Expertise in low-VOC waterborne epoxy chemistry remains concentrated among senior technologists at established producers.
- Qualification timeline compression:Aircraft manufacturers and defense contractors require 18-36 month certification cycles for new primer specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Epoxy Primer Market |
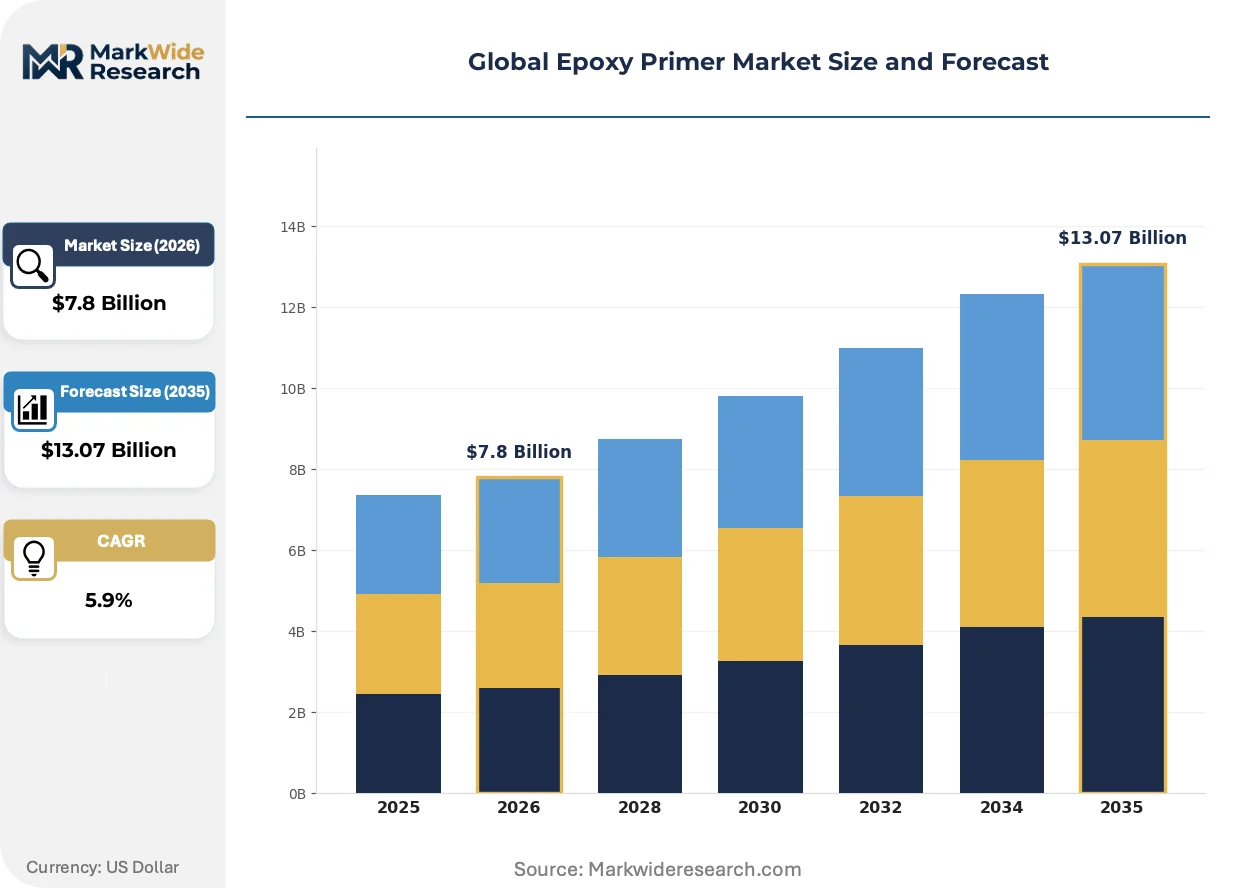
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.07 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Waterborne, Solvent-based, High Solid, Low VOC, Powder Coating Application: Marine Coatings, Aerospace Coatings, Building & Construction, Metal Fabrication, Transportation Equipment Technology: Curing Agents, Anti-corrosion, UV Resistance, Thermal Stability, Adhesion Enhancement End User: Shipbuilders, Aircraft Manufacturers, Steel Fabricators, Automotive OEMs, Infrastructure Developers |
| Companies Covered | The Sherwin-Williams Company, Kansai Paint Co.,Ltd, NIPPON PAINT, BASF SE, Axalta Coating Systems, PPG Industries, Inc, Asian Paints, Jotun A/S, Akzo Nobel NV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Epoxy Primer Market Shifts & Advancements
Formulation chemistry and application protocols are converging around sustainability mandates and performance verification requirements, reshaping how producers compete on specification compliance.
Waterborne epoxy primer systems are supplanting solvent-based alternatives in jurisdictions with stringent VOC limits while closing the performance gap on humidity tolerance and recoat windows. Automotive refinishing shops in California and Germany are adopting these systems ahead of regulatory deadlines. The shift is compressing demand for high-solvent formulations in decorative and light industrial segments.
ECHA REACH restrictions on chromium trioxide are eliminating hexavalent chrome from anti-corrosion primer formulations across European marine and industrial maintenance markets. Formulators are pivoting toward phosphate-based and rare-earth modified alternatives with comparable salt-spray performance. Nordic shipyards are qualifying these reformulated systems through extended field trials.
Specification-driven procurement now dominates capital-intensive end uses, with buyers unbundling coating selection from application contractor decisions. Offshore platform operators in the North Sea and Gulf of Mexico are mandating third-party performance verification for primer systems prior to contract award. This pattern elevates technical documentation and warranty terms above price in supplier selection.
Global Epoxy Primer Market Segmentation
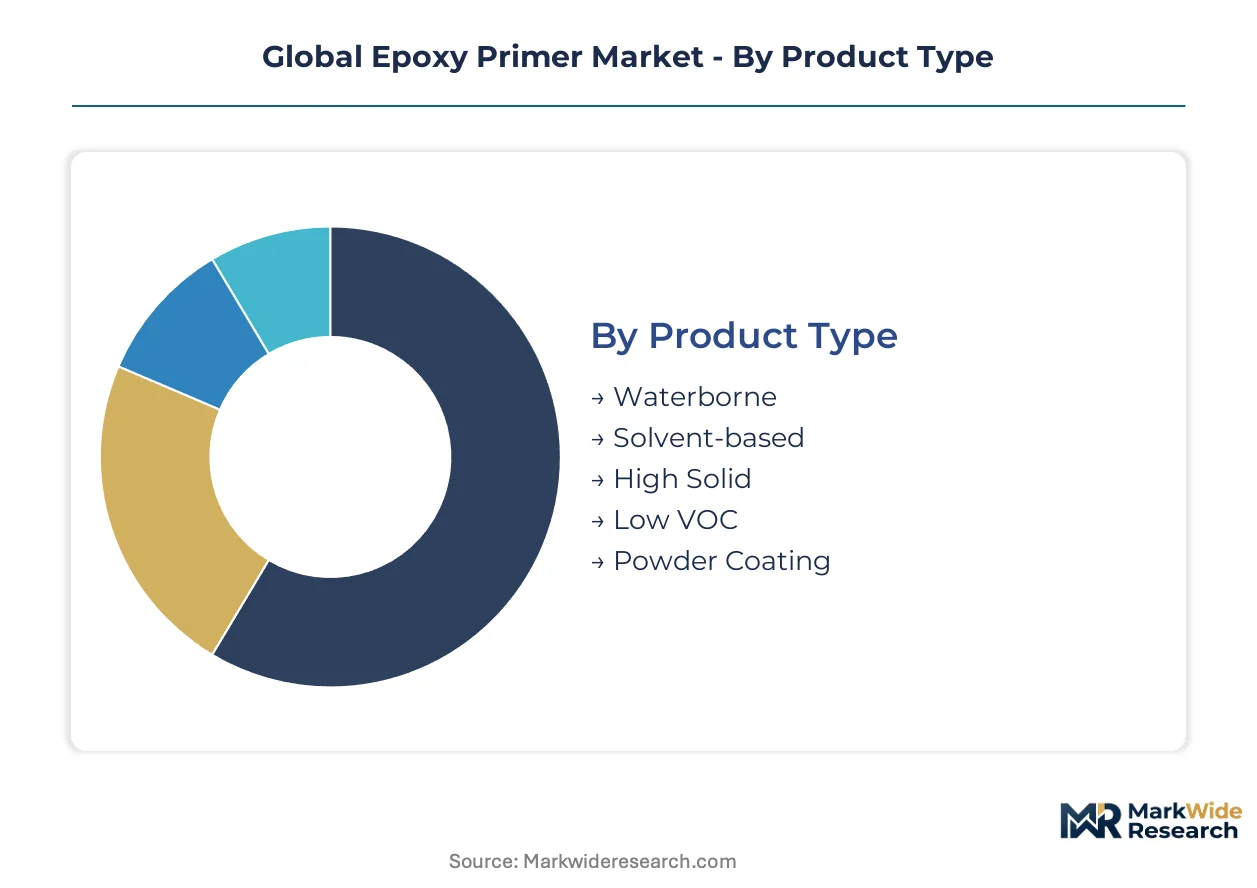
Epoxy primer procurement patterns diverge sharply across formulation chemistry and end-use specifications. Buyers segment demand by regulatory compliance thresholds, performance requirements, and application environment severity.
Product Type:
Margin pools concentrate in specialty formulations that command specification premiums while absorbing feedstock volatility through technical differentiation.
- Waterborne:These systems displace solvent-based alternatives in jurisdictions with stringent VOC limits. Automotive refinishing shops in California and Germany are adopting waterborne epoxy primers ahead of regulatory deadlines, though extended cure times constrain maintenance turnaround applications.
- Solvent-based:Conventional formulations retain dominance in marine and heavy-equipment segments where recoat windows and surface tolerance outweigh emissions considerations. Shipyards in South Korea and China specify solvent-based systems for hull protection where humidity tolerance is paramount.
- High Solid:Reduced solvent content meets intermediate regulatory thresholds without sacrificing application speed. Industrial maintenance contractors in Texas and Rotterdam favor high-solid formulations for bridge steel rehabilitation.
- Low VOC:Compliant formulations target architectural and light industrial segments where EPA 40 CFR Part 59 or REACH limits apply. Formulators blend these systems for California South Coast Air Quality Management District compliance.
- Powder Coating:Thermoset powder epoxy primers serve automotive and appliance manufacturers requiring zero-VOC factory-applied finishes. OEM coating lines in Michigan and Bavaria integrate these systems for chassis and structural components.
The dominant share belongs to Solvent-based, while Waterborne is closing the gap fastest.
Application:
Volume concentration tracks capital-intensive asset classes with extended coating replacement cycles and corrosion failure costs.
- Marine Coatings:Hull protection specifications in Chinese and South Korean shipyards drive substantial epoxy primer procurement for newbuild and maintenance cycles. Salt-spray performance requirements exceed 3,000 hours for ballast tank applications.
- Aerospace Coatings:Aircraft manufacturers command premium pricing through qualification-intensive specification chains requiring 18-36 month certification cycles. Boeing and Airbus tier-1 suppliers specify chromate-free alternatives under REACH pressure.
- Building & Construction:Bridge and port developers in India and Brazil specify corrosion-resistant primers for structural longevity in coastal environments. Epoxy zinc-rich systems dominate steel superstructure protection.
- Metal Fabrication:Steel fabricators represent the broadest volume pool across industrial equipment, structural steel, and OEM components. Job shops in Guangdong and Ohio specify quick-dry formulations for throughput maximization.
- Transportation Equipment:Rail car and heavy truck manufacturers apply epoxy primers prior to polyurethane or fluoropolymer topcoats. Freight wagon builders in Poland and Illinois specify systems for chemical resistance in tank car interiors.
Marine Coatings captures the largest revenue pool, though Aerospace Coatings sustains the steepest margin structure.
Technology:
Functional additive packages determine specification win rates in performance-critical end uses.
- Curing Agents:Polyamide and polyamine chemistries control pot life, cure speed, and final film properties. Polyamide production clusters in Germany and China create geographic supply vulnerability for non-integrated formulators.
- Anti-corrosion:Phosphate-based and rare-earth modified additives are displacing hexavalent chrome under ECHA REACH restrictions. Nordic shipyards are qualifying these reformulated systems through extended field trials.
- UV Resistance:Hindered amine light stabilizers and UV absorbers extend primer durability in exterior exposures. Wind turbine OEMs in Denmark specify these systems for offshore foundation splash-zone protection.
- Thermal Stability:High-temperature epoxy formulations serve exhaust systems and industrial ovens. Specialty curing agents enable continuous service above 180°C for petrochemical processing equipment.
- Adhesion Enhancement:Silane coupling agents and surface-active additives improve substrate wetting on blasted steel and aluminum. Aircraft manufacturers mandate these technologies for fatigue-critical bonded assemblies.
Anti-corrosion additives command the highest formulation cost contribution, while Adhesion Enhancement is expanding most quickly in qualification-driven segments.
End User:
Procurement sophistication varies from commodity spot purchasing to integrated coating system partnerships with on-site technical service.
- Shipbuilders:Chinese and South Korean yards are consolidating procurement around integrated coating system providers with direct technical service models. Hull protection specifications span newbuild and maintenance cycles with 15-25 year asset life expectations.
- Aircraft Manufacturers:Boeing, Airbus, and tier-1 suppliers enforce 18-36 month qualification timelines for new primer specifications. Chromate-free alternatives are advancing through certification under REACH and OEM sustainability mandates.
- Steel Fabricators:Job shops and structural steel producers represent the broadest volume pool with price-sensitive spot purchasing. Indian and Brazilian infrastructure steel coating requirements continue to climb for bridge and port construction.
- Automotive OEMs:Factory-applied epoxy primers serve body-in-white corrosion protection prior to electrocoat and topcoat layers. Michigan and Bavaria assembly plants specify zero-defect adhesion for warranty compliance.
- Infrastructure Developers:Bridge and port authorities in coastal environments specify corrosion-resistant primers for structural longevity. Third-party performance verification is becoming mandatory prior to contract award in North Sea and Gulf of Mexico projects.
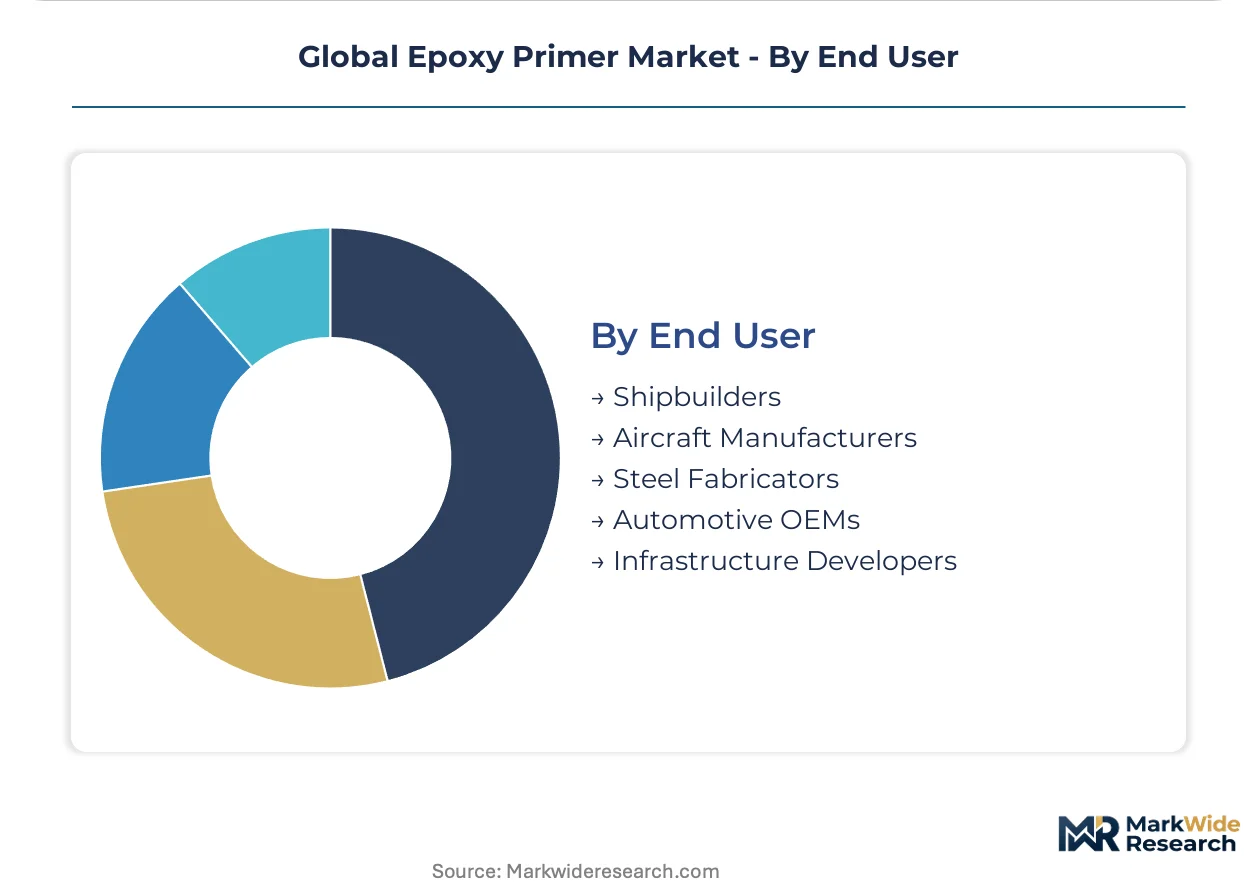
Steel Fabricators anchor volume demand, though Infrastructure Developers are gaining procurement sophistication fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta's deepwater port infrastructure underwrites China's dominance in shipyard output and steel coating procurement. German chemical clusters supply polyamide curing agents to European formulators facing REACH compliance deadlines. South Korean shipbuilders on the Geoje Island complex drive specification-intensive hull protection demand.
China
Shipyard output at Dalian and Shanghai facilities consumes substantial epoxy primer volumes for newbuild hull protection. MEE enforcement of GB standards on hazardous substance limits compels domestic producers to reformulate chromium-free anti-corrosion systems. The Pearl River Delta's steel fabrication clusters are adopting waterborne primers ahead of provincial VOC deadlines.
United States
Bridge rehabilitation programs across the Interstate Highway System specify corrosion-resistant primers for structural steel longevity. EPA 40 CFR Part 59 constrains solvent-based formulations in industrial maintenance coatings. Gulf Coast petrochemical facilities near Houston demand high-temperature epoxy systems for processing equipment protection.
Germany
Automotive OEM coating lines in Bavaria integrate powder epoxy primers for zero-VOC chassis finishes. ECHA REACH restrictions on isocyanate content reshape additive choices across marine and industrial supply chains. The Ruhr industrial corridor's steel fabricators are qualifying phosphate-based anti-corrosion alternatives to hexavalent chrome.
South Korea
Geoje Island shipyards specify salt-spray performance exceeding 3,000 hours for ballast tank primer applications. MFDS alignment with international chemical safety standards influences import formulation requirements. Busan-Ulsan heavy equipment manufacturers favor solvent-based systems for humidity tolerance in maintenance cycles.
Brazil
Port expansion at Santos and Itaguaí drives infrastructure steel coating procurement for coastal structural protection. ANVISA chemical substance regulations create compliance barriers for imported coating formulations. São Paulo state's automotive refinishing sector is transitioning toward waterborne systems ahead of environmental enforcement.
Global Epoxy Primer Market Competitive Landscape
Listed leaders compete with private specialists across formulation chemistry and technical service capabilities. The vendor base stratifies between integrated resin producers, regional coating specialists, and application-focused distributors. Three archetypes dominate: petrochemical-integrated formulators with captive raw material supply, specification-driven marine specialists with direct shipyard relationships, and diversified industrial coating houses with broad end-user coverage. Competitive moves concentrate on backward integration into curing agent production and geographic expansion through technical service partnerships.
Among integrated chemical conglomerates, BASF SE and Akzo Nobel NV occupy positions spanning resin production through formulated systems. Jotun A/S exemplifies the marine-specialist archetype with concentrated shipyard technical service models. These three anchors represent distinct competitive vectors: petrochemical scale, specification compliance, and application expertise.
| Leading Market Players |
|---|
| The Sherwin-Williams Company |
| Kansai Paint Co.,Ltd |
| NIPPON PAINT |
| BASF SE |
| Axalta Coating Systems |
| PPG Industries, Inc |
| Asian Paints |
| Jotun A/S |
| Akzo Nobel NV |
| Others |
Supply & Pricing Matrix
REACH and RoHS compliance regimes gate both supplier qualification and price differentiation simultaneously, forcing formulators to maintain parallel product lines that segment procurement pools by regulatory jurisdiction and performance tier.
Pricing Analysis
Volume-discount tiering structures separate specification-grade marine systems from commodity industrial formulations. Three-tier pricing stratifies across aerospace qualification-intensive grades, marine performance tiers, and economy-grade metal fabrication batches. Cost compression in waterborne segments is intensifying because feedstock volatility in bisphenol-A markets squeezes margin predictability. Steel fabricators exhibit highest price sensitivity through spot purchasing, while aircraft manufacturers accept premium positioning for certification-intensive supply chains.
Supply Chain Analysis
Strait of Malacca transit routes feed epoxy resin feedstocks from Middle Eastern petrochemical complexes to Asian formulators. Polyamide curing agent production clusters in Germany and China, drawing from epichlorohydrin and fatty acid derivative streams. Single-source vulnerability concentrates in specialty amine intermediates where non-integrated producers lack captive supply. Distribution runs through direct technical service partnerships for shipyard accounts and regional coating distributors for job shop fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where qualification timelines and certification investments create switching costs that protect incumbent positions.
For Market Incumbents: Consolidate backward integration into polyamide curing agent production to neutralize supply concentration risks in Germany and China. Deepen captive resin manufacturing to absorb bisphenol-A price volatility. Defend specification positions by accelerating chromate-free anti-corrosion additive qualification ahead of REACH enforcement deadlines.
For New Entrants and Emerging Players: Anchor in waterborne formulation services for automotive refinishing shops in California and São Paulo state, where regulatory deadlines outpace incumbent reformulation capacity. Target compliance consulting bundles for foreign producers entering Chinese distribution under MEE GB standards enforcement. Build technical service partnerships with provincial steel fabrication clusters ahead of VOC deadline adoption.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates seeking to divest non-core coating assets with stranded solvent-based product lines. Long-term viability hinges on waterborne chemistry capabilities and direct shipyard relationships. Monitor ECHA restriction expansion timelines as inflection indicators for reformulation capex cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Curing Agents | Captive polyamide production neutralizes supply vulnerability concentrated in German and Chinese chemical clusters. |
| Chromate-Free Additive Qualification | Phosphate-based and rare-earth modified systems secure REACH compliance ahead of hexavalent chrome elimination deadlines. |
| Waterborne Formulation Scale-Up | California and German automotive refinishing adoption accelerates ahead of EPA and ECHA VOC enforcement windows. |
| Direct Technical Service Expansion | On-site application support consolidates procurement decisions at Geoje Island and Dalian shipyard complexes. |
| Long-Term Supply Agreements | Contracted offtake with Yangtze River Delta steel fabricators locks volume against feedstock volatility. |
Research Methodology
Cross-validation between plant manager interviews at coating manufacturing facilities and customs trade data anchors the qualitative findings. Primary fieldwork engaged formulation chemists, procurement leads at downstream shipyards, distribution channel partners, and technical R&D directors across marine, aerospace, and industrial maintenance segments. Secondary validation drew from SEC 10-K filings, Cefic chemical industry reports, EPA enforcement databases, and ECHA restriction dossiers. Bottom-up volume estimates from end-use application rates triangulate against top-down resin consumption figures.
Sensitivity analysis tested demand elasticity across the projection horizon under alternative regulatory enforcement scenarios. Segmentation modeling spanned formulation chemistry, end-use industry, performance grade tier, and regional production hub clusters. CAGRs derive from iterative convergence of historical consumption patterns and forward-looking specification adoption curves. Key inputs include shipyard orderbook projections, bridge rehabilitation program announcements, and wind turbine installation forecasts.
Material uncertainties — feedstock price spikes, regulatory restriction expansion, and qualification timeline extensions — sit outside the modeled envelope. Forecasts reflect assumptions about enforcement consistency and technology substitution rates. Practitioners should keep alternative scenarios live as ECHA restriction reviews and MEE GB standard updates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Semi-Crystalline Polymers Market
Polymers & Resins
Global Corrosion Resistant Resin Market
Polymers & Resins
Global Bio Based Polyurethane Market
Polymers & Resins
Europe Superabsorbent Polymers Market
Polymers & Resins
Global Water-Based Resins Market
Polymers & Resins
Ionomer Resins Market
Polymers & Resins
Polyvinyl Butyral (PVB) Resins Market
Polymers & Resins
Plastisols Market
Polymers & Resins
EVA Copolymer Market
Polymers & Resins
Asia-Pacific Polycarbonate (PC) Market
Polymers & Resins
Silicon Anode Binder Polymers for Lithium-Ion Batteries Market
Polymers & Resins
Global Unsaturated Polyester Resins Market
Polymers & Resins
Middle-East and Africa Fluoropolymers Market
Polymers & Resins
Thermoplastic Polyester Engineering Resin (TPER) Market
Polymers & Resins
United States Geopolymer Market
Polymers & Resins
Polyvinyl Alcohol Resins Market