
 Biopolymer Tubes Market | 2026-2036
Biopolymer Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
Biopolymer Tubes Market Outlook
Aftermarket recycling and material recovery revenue is narrowing as primary producers integrate closed-loop collection into their core operations. NatureWorks LLC leverages its Ingeo PLA resin platform to anchor North American feedstock supply for medical-grade tubing extrusion. Corbion N.V. sustains global lactide production scale, while Novamont S.p.A. competes through proprietary starch-blend formulations tailored to European pharmaceutical packaging specifications.
Biopolymer tubes are cylindrical extrusions manufactured from renewable feedstock-derived polymers such as polylactic acid, polyhydroxyalkanoates, or cellulose esters, typically processed via single-screw or twin-screw extrusion with wall tolerances reaching ±0.05 mm for medical applications. These tubes serve as conduits for fluid transfer, protective sheathing, or controlled-release barriers in sectors requiring biodegradability or biocompatibility certification. Flexible tubes dominate current volume owing to their compatibility with peristaltic pumps and minimally invasive device routing, while multi-layer structures represent the fastest-expanding category as manufacturers engineer oxygen-barrier properties into pharmaceutical primary packaging. PLA-based material formulations occupy the largest share of commercial production, though PHA resins command premium positioning where marine biodegradability standards apply.
The FDA enforces biocompatibility testing under ISO 10993 for medical device tubing, while the EU Medical Device Regulation mandates clinical evidence documentation for implantable or prolonged-contact applications. REACH restrictions on phthalate plasticizers and the EU F-Gas Regulation indirectly accelerate substitution toward bio-based extrusion compounds. Stakeholders must monitor evolving compostability certification requirements across FDA, EMA, and national health technology assessment bodies to preempt qualification gaps in regulated end-uses.
Market Dynamics
Single-use medical device procurement is compressing qualification cycles for biopolymer tubing suppliers, forcing extruders to pre-certify material lots against ISO 10993 biocompatibility suites before contract bidding.
Growth Catalysts
- EU Green Deal packaging directives:Virgin plastic restrictions across member states are mandating bio-based alternatives in pharmaceutical primary packaging, creating immediate substitution pull.
- Peristaltic pump compatibility:Flexible biopolymer tubes now meet ±0.05 mm wall tolerance specifications for minimally invasive surgical instrument routing.
- Stuttgart-Munich precision cluster:Automotive and medical OEM concentration in southern Germany sustains dedicated extrusion capacity for high-volume tubing contracts.
Market Restraints
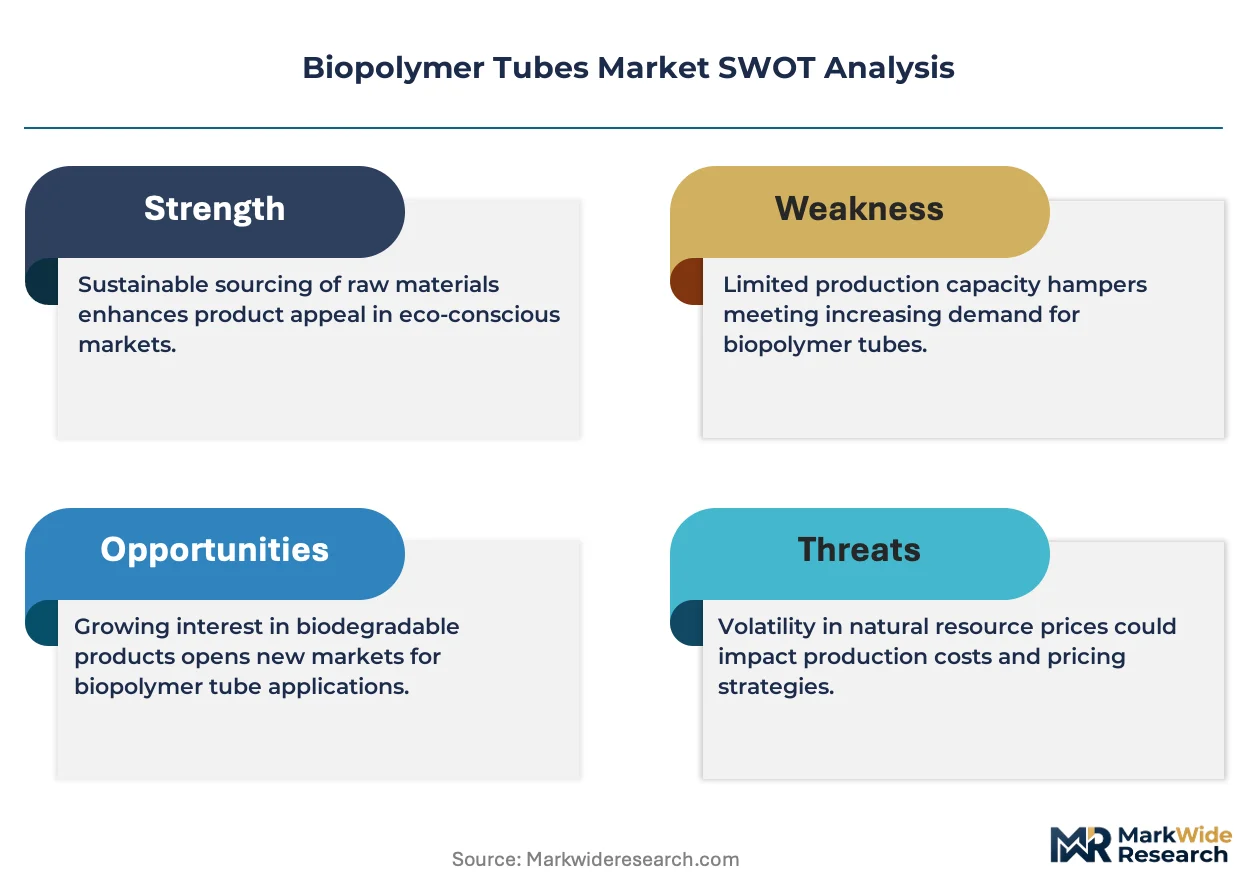
- Lactide feedstock volatility:Corbion N.V. and NatureWorks LLC control global PLA precursor supply, creating single-source exposure for medical-grade resin procurement.
- Marine biodegradability certification gaps:PHA resins command premiums where ASTM D6691 compliance is required, but testing infrastructure remains geographically sparse.
- REACH phthalate substitution timelines:ECHA restrictions on conventional plasticizers force rapid compound reformulation without guaranteed performance equivalence.
Strategic Opportunities
- Multi-layer oxygen barrier technology:Pharmaceutical packaging engineers are specifying co-extruded structures for parenteral drug stability, opening premium positioning for tubing with EVOH or bio-based interlayers.
- Closed-loop collection integration:Primary producers embedding aftermarket recovery into core operations can capture margin previously lost to third-party recyclers.
- India CDSCO medical device rules:Localized biocompatibility testing requirements for imported tubing create first-mover advantage for extruders establishing domestic compounding partnerships.
Industry Challenges
- ISO 10993-18 chemical characterization:Extractables and leachables testing for implantable tubing extends qualification timelines by 14-18 months.
- Twin-screw extrusion expertise scarcity:Medical-grade biopolymer processing requires distinct temperature and shear profiles versus commodity plastics, constraining contract manufacturer availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biopolymer Tubes Market |
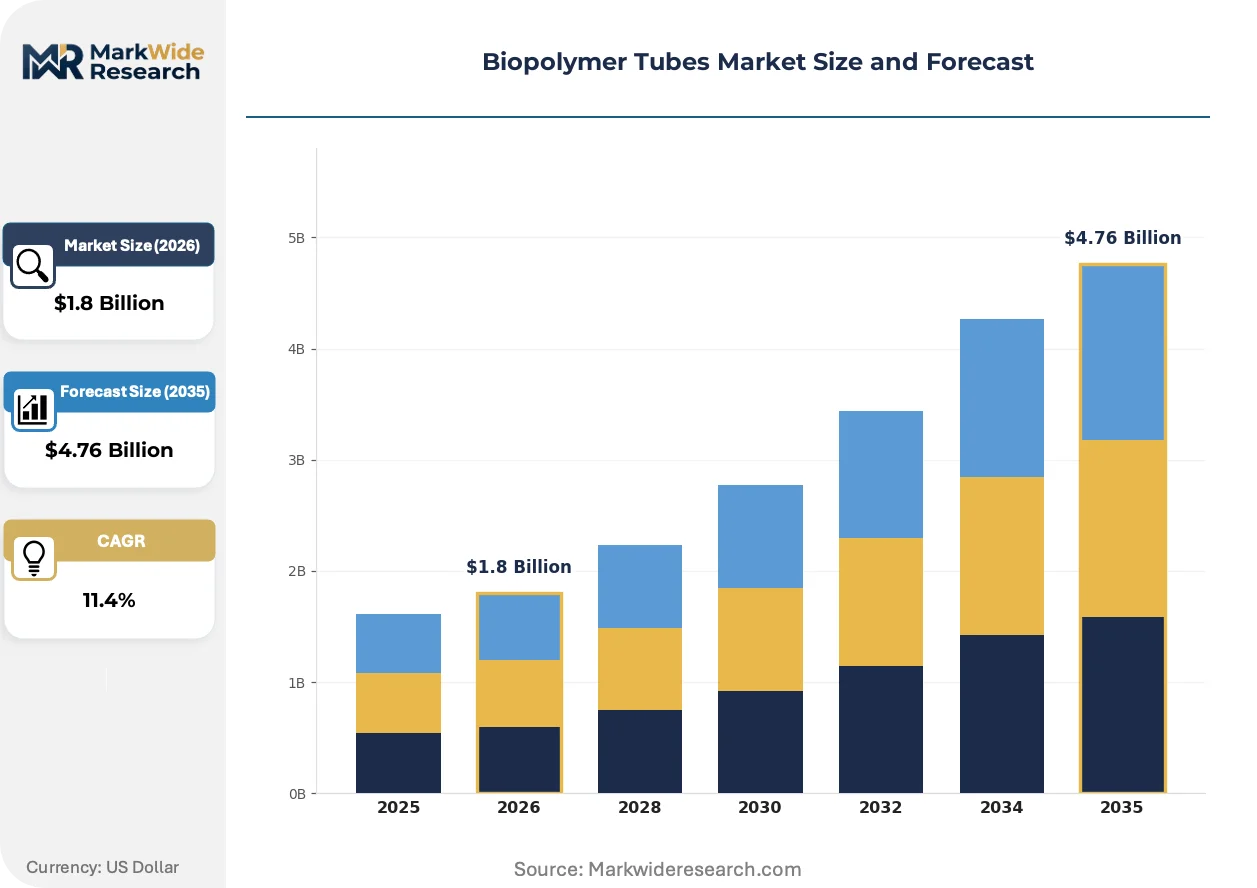
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Tubes, Rigid Tubes, Multi-Layer Tubes, Composite Tubes Application: Medical Devices, Packaging, Agricultural Films, Pharmaceutical Packaging End User: Hospitals, Research Laboratories, Food Industry, Agricultural Sector Material: PLA, PHA, Starch Blends, Cellulose |
| Companies Covered | NatureWorks LLC, Corbion N.V., Danimer Scientific, Novamont S.p.A., FKuR Kunststoff GmbH, Biome Bioplastics Limited, Raepak Ltd, Maynard & Harris Plastics, Arkema, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biopolymer Tubes Market Strategic Shifts
Material science advances and regulatory chemistry restrictions are converging to redefine performance specifications across medical, pharmaceutical, and automotive tubing applications.
Multi-layer co-extrusion technology is migrating from pharmaceutical barrier packaging into implantable drug delivery systems. Cardiovascular device manufacturers in Switzerland and Germany now specify tri-layer PLA-EVOH-PLA structures for controlled-release stent coatings. This architecture compresses oxygen permeation rates below 0.1 cc/m²/day while maintaining the biodegradability profile required for temporary implant applications.
EMA clinical evidence documentation under the EU Medical Device Regulation is tightening evidentiary standards for prolonged-contact tubing. Manufacturers must now submit biocompatibility data across the full degradation timeline, not just initial contact periods. German notified bodies are enforcing this most strictly, delaying market entry for PLA-based products lacking 24-month implantation studies.
Hospital procurement consortia are consolidating tubing specifications to reduce SKU complexity. Group purchasing organizations in France and the Netherlands now mandate single-material platforms across multiple device categories, favoring PLA over PHA for cost-standardization despite performance trade-offs. This behavioral shift pressures specialty resin suppliers to demonstrate cost parity at volume scales previously reserved for commodity polymers.
Biopolymer Tubes Market Segmentation
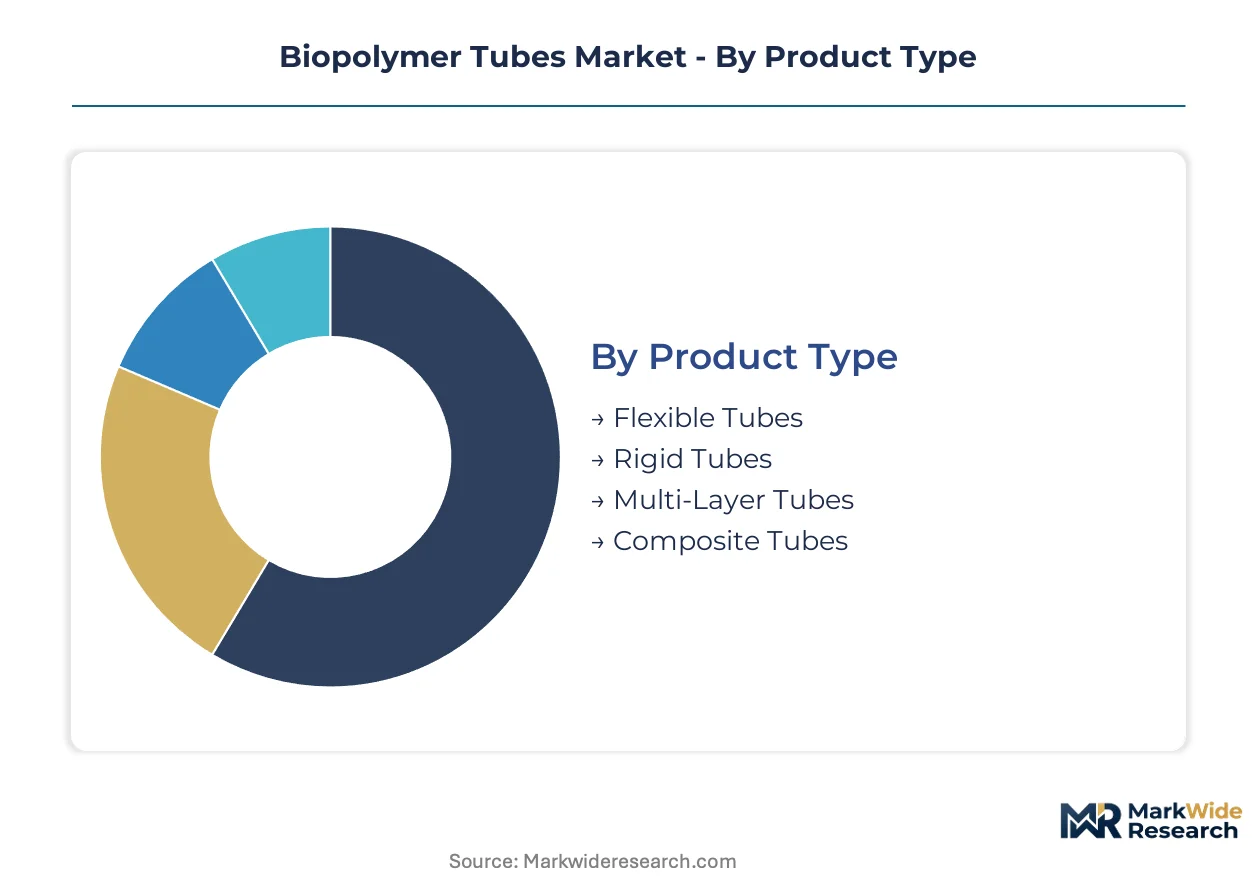
Biopolymer tube specifications diverge sharply across medical, pharmaceutical, and industrial end-uses, with wall tolerances, barrier properties, and degradation timelines dictating material selection. Segmentation by product architecture, application intensity, and feedstock chemistry reveals where premium pricing power concentrates versus commodity substitution pressure.
Product Type:
Tube architecture determines extrusion complexity and the precision of downstream forming operations for minimally invasive routing or structural containment.
- Flexible Tubes:Extruded from PLA or PHA with Shore A hardness ratings between 70-90, these tubes accommodate peristaltic pump compression cycles without kinking. Demand concentrates in German and Swiss catheter manufacturing clusters where ISO 10993-5 cytotoxicity testing is mandatory for contract qualification.
- Multi-Layer Tubes:Co-extruded structures pair PLA outer layers with EVOH or bio-based interlayers to achieve oxygen transmission rates below 0.1 cc/m²/day. Pharmaceutical packaging engineers in Stuttgart specify these for parenteral drug stability, though twin-screw extrusion expertise scarcity extends lead times by 8-12 weeks.
- Rigid Tubes:Higher-crystallinity PLA formulations with glass transition temperatures above 60°C serve as protective sheathing for implantable device leads.
- Composite Tubes:Reinforced structures incorporating cellulose fibers or natural fiber mats address automotive fluid routing applications requiring pressure tolerance above 5 bar.
Flexible tubes command the established base. The steepest expansion runs through multi-layer oxygen barrier architectures.
Application:
End-use intensity shapes certification burden, with implantable and prolonged-contact applications triggering the most extensive biocompatibility documentation requirements.
- Medical Devices:Single-use surgical instruments, drug delivery catheters, and minimally invasive routing systems require ISO 10993-18 chemical characterization for extractables and leachables. FDA enforcement of biocompatibility testing compresses supplier qualification cycles to 14-18 months for implantable tubing.
- Pharmaceutical Packaging:Primary packaging for parenteral drugs demands oxygen and moisture barrier properties alongside biodegradability certification. EU Green Deal packaging directives mandate bio-based alternatives, creating immediate substitution pull in Germany and France.
- Packaging:Secondary and tertiary packaging applications prioritize cost parity over barrier performance, favoring PLA over PHA for standardization.
- Agricultural Films:Mulch films and controlled-release tubing for irrigation systems specify marine biodegradability under ASTM D6691 where coastal runoff regulations apply.
Medical device procurement absorbs the highest certification investment. Pharmaceutical packaging is climbing fastest on regulatory substitution mandates.
Material:
Feedstock chemistry governs degradation timeline, mechanical properties, and the geographic concentration of resin supply.
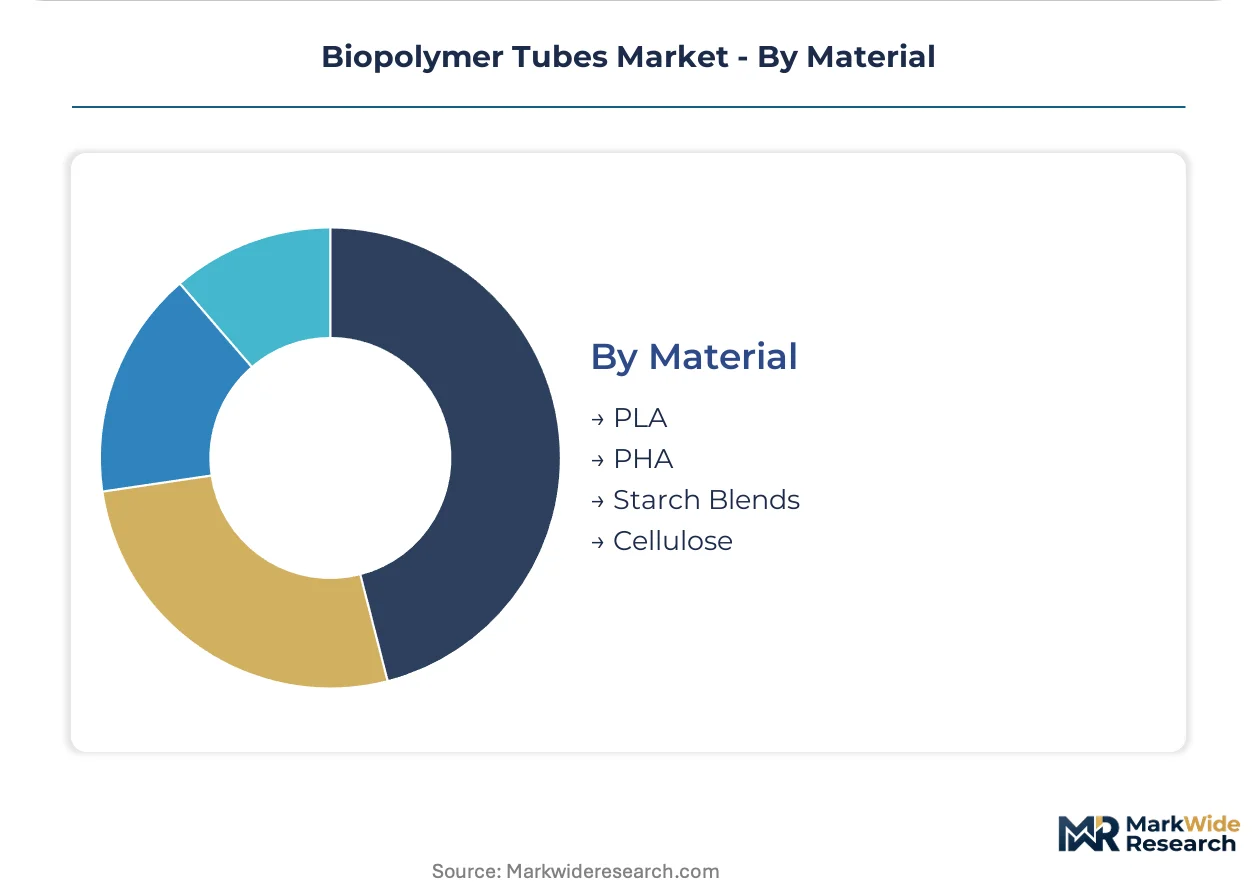
- PLA:Polylactic acid derived from corn starch or sugarcane dominates commercial production due to NatureWorks LLC and Corbion N.V. scale. Medical-grade grades achieve ±0.05 mm wall tolerances for catheter applications, though lactide feedstock volatility creates single-source exposure.
- PHA:Polyhydroxyalkanoates produced via bacterial fermentation command premium positioning where marine biodegradability standards apply. Testing infrastructure remains geographically sparse, limiting qualification to specialized pharmaceutical and coastal agricultural applications.
- Starch Blends:Novamont S.p.A. proprietary formulations target European pharmaceutical packaging specifications with cost structures below PLA for short-use-cycle applications.
- Cellulose:Regenerated cellulose esters address high-temperature sterilization requirements beyond PLA thermal limits, serving research laboratory and specialized medical device segments.
PLA formulations anchor volume production. PHA resins are expanding most quickly in marine-certified niche applications.
End User:
Customer procurement behavior ranges from consolidated hospital purchasing consortia to fragmented agricultural distributor networks.
- Hospitals:Group purchasing organizations in France and the Netherlands consolidate tubing specifications across multiple device categories, favoring single-material PLA platforms for SKU complexity reduction.
- Research Laboratories:Small-batch procurement with emphasis on lot traceability and custom diameter specifications.
- Food Industry:Edible and compostable tubing for product handling and processing equipment.
- Agricultural Sector:Distributor-mediated demand with price sensitivity and seasonal procurement patterns.
Hospital procurement concentrates contract value. Research laboratories are expanding fastest on personalized medicine tubing requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement consortia in the Netherlands demonstrate the lowest price elasticity, accepting 15-20% premiums for certified biocompatibility. Agricultural distributors in coastal India exhibit the highest sensitivity, where PHA tubing competes directly with conventional polyethylene on per-meter cost.
Germany
Stuttgart and Munich host the densest concentration of medical device OEMs requiring ±0.05 mm wall tolerance tubing for catheter applications. The EU Medical Device Regulation mandates clinical evidence documentation for prolonged-contact applications through notified bodies in Berlin and Tübingen. FKuR Kunststoff GmbH anchors precision extrusion capacity in Willich, serving pharmaceutical packaging engineers specifying multi-layer oxygen barrier structures.
United States
FDA enforcement of ISO 10993 biocompatibility testing compresses supplier qualification cycles to 14-18 months for implantable tubing. The Inflation Reduction Act's domestic manufacturing incentives accelerate reshoring of medical-grade PLA compounding operations. NatureWorks LLC maintains lactide resin production in Blair, Nebraska, supplying extruders in Minnesota's Twin Cities medical device corridor.
India
CDSCO medical device rules impose localized biocompatibility testing requirements for imported tubing, creating first-mover advantage for extruders establishing domestic partnerships. The Production-Linked Incentive scheme for pharmaceuticals subsidizes bio-based packaging conversion in Hyderabad and Ahmedabad. Maharashtra's Pune-Aurangabad industrial belt attracts contract manufacturers serving European pharmaceutical OEMs seeking cost arbitrage.
Japan
METI's Green Growth Strategy mandates bio-based material substitution in medical and food packaging by 2030, with PMDA streamlining equivalency pathways for PLA devices. The Kansai region's Osaka-Kobe cluster specializes in high-barrier pharmaceutical tubing for export to Southeast Asian markets. Chubu-based compounders supply cellulose ester formulations exceeding PLA thermal limits for autoclave sterilization protocols.
Switzerland
Swissmedic maintains the most stringent evidentiary standards for implantable tubing degradation timelines, requiring 24-month implantation studies for PLA-based cardiovascular devices. The Zurich-Basel corridor concentrates minimally invasive surgical instrument manufacturers sourcing tri-layer PLA-EVOH-PLA structures for controlled-release applications. Novamont S.p.A. competes through starch-blend formulations tailored to short-use-cycle pharmaceutical packaging specifications.
Biopolymer Tubes Market Competitive Environment
Capability concentration sits with specialized extruders mastering twin-screw temperature and shear profiles for medical-grade biopolymers; scale advantage sits with resin producers controlling global lactide and lactide precursor supply. The market structures around three archetypes: integrated resin-to-tube producers, independent precision extruders, and compounder-distributors bridging feedstock and fabrication. Dominant competitive moves include backward integration into lactide production and strategic partnerships with notified bodies for pre-certified material lot programs.
Among integrated resin producers, NatureWorks LLC and Corbion N.V. occupy positions anchoring North American and European feedstock supply respectively. Novamont S.p.A. exemplifies the specialty compounder archetype, leveraging proprietary starch-blend formulations to serve European pharmaceutical packaging specifications. These three represent distinct strategic postures: captive raw material security, global lactide scale, and regional formulation specialization.
| Leading Market Players |
|---|
| NatureWorks LLC |
| Corbion N.V. |
| Danimer Scientific |
| Novamont S.p.A. |
| FKuR Kunststoff GmbH |
| Biome Bioplastics Limited |
| Raepak Ltd |
| Maynard & Harris Plastics |
| Arkema |
| Others |
Value Chain & Pricing Dynamics
Lactide feedstock volatility from Corbion N.V. and NatureWorks LLC single-source concentration compresses pricing tier spreads between medical-grade PLA tubing and commodity alternatives while forcing extruders toward backward integration or long-term offtake contracts to secure resin supply.
Pricing Analysis
Aftermarket material recovery and closed-loop collection services now drive lifetime value more than initial tube sales. Three-tier pricing structure across premium, standard, and economy levels separates ISO 10993-18 pre-certified implantable grades from pharmaceutical packaging tiers and agricultural mulch applications. Cost compression in standard pharmaceutical tubing intensifies as hospital GPOs consolidate specifications toward single-material PLA platforms. Agricultural distributors in coastal India exhibit highest price sensitivity, while Dutch hospital consortia accept premiums for certified biocompatibility.
Supply Chain Analysis
FKuR Kunststoff GmbH in Willich and precision extrusion specialists in Stuttgart-Munich hold dominant contract manufacturing capacity for medical-grade biopolymer tubing. Raw material supply draws from Corbion's Netherlands lactide production, NatureWorks' Nebraska resin operations, and Novamont's Italian starch-blend compounding. Single-source vulnerability in PLA precursor supply creates exposure when agricultural commodity prices fluctuate. Distribution runs through medical device OEM direct contracts in Germany, pharmaceutical packaging converters in France, and distributor networks for agricultural applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Closed-loop collection and material recovery services are expanding faster than hardware sales as primary producers integrate aftermarket operations into core business models.
For Market Incumbents: Pre-empt lactide supply disruptions by securing captive feedstock through equity stakes in agricultural processing or long-term corn starch offtake agreements with Midwestern US suppliers. Defend against starch-blend substitution by accelerating ISO 10993-18 pre-certification programs that compress hospital procurement cycles. For New Entrants and Emerging Players: Pursue CDSCO localization partnerships in Maharashtra's Pune-Aurangabad belt to bypass India's mandatory domestic biocompatibility testing for imported tubing. Target marine-certified PHA applications where ASTM D6691 compliance creates premium positioning against PLA commodity pressure. For Investors and Strategic Acquirers: EU Medical Device Regulation clinical evidence documentation reshapes the acquisition landscape toward extruders with notified body pre-certification relationships and completed 24-month implantation studies. Long-term viability centers on twin-screw extrusion technical capability rather than commodity resin access. Monitor German notified body queue lengths as inflection signal for qualification timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lactide Production | Captive feedstock security insulates margin from agricultural commodity volatility. |
| ISO 10993-18 Pre-Certification Programs | Pre-certified material lots compress hospital GPO procurement cycles against competitors. |
| Multi-Layer Co-Extrusion Capacity Expansion | Tri-layer PLA-EVOH-PLA capability opens cardiovascular stent coating contracts in Switzerland. |
| Closed-Loop Collection Integration | Aftermarket recovery services capture margin previously lost to third-party recyclers. |
| CDSCO Domestic Partnership Formation | Localized testing capability creates first-mover advantage in India's regulated medical device imports. |
Study Parameters
Cross-validation between primary interviews with medical device procurement managers, biomedical engineers, GPO contracts managers, and pharmaceutical packaging engineers and secondary validation through FDA 510(k) filings, EMA medical device registration databases, and EU notified body public certificates anchors the qualitative findings. Bottom-up tubing volume estimates from extruder capacity assessments triangulate against top-down pharmaceutical packaging conversion rates and medical device OEM procurement disclosures.
Calibration against historical CAGRs from comparable medical-grade polymer markets and regulatory substitution timelines shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include tube architecture, application intensity, feedstock chemistry, and end-user procurement behavior. Industry-specific forecast inputs incorporate REACH phthalate substitution compliance deadlines and EU Green Deal packaging directive implementation schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by integrated resin-to-tube producers or notified body acquisition strategies would shift outcomes beyond modeled ranges. Quarterly review of German notified body queue lengths, Corbion lactide pricing disclosures, and CDSCO import registration volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Conductive Polymers Market
Polymers & Resins
Modified Alkyd Resin Market
Polymers & Resins
Caprolactam (Nylon 6 Fiber and Nylon 6 Resin) Market
Polymers & Resins
Dispersant Polymer Market
Polymers & Resins
APAC Polyethylene Terephthalate Market
Polymers & Resins
Global One Component Polyurethane Foam Market
Polymers & Resins
Hybrid Polymer Market
Polymers & Resins
Polar Polymers Market
Polymers & Resins
Chelating Resins Market
Polymers & Resins
Polylysine Market
Polymers & Resins
Global Linear Low Density Polyethylene Market
Polymers & Resins
Polyglycerol Market
Polymers & Resins
Global Engineering Plastic Market
Polymers & Resins
Soft PVC Sealing Strip Market
Polymers & Resins
Polysorbate Market
Polymers & Resins
Hair Styling Biopolymers Market