
 Middle-East and Africa Polyethylene Terephthalate (PET) Resin Market | 2026-2036
Middle-East and Africa Polyethylene Terephthalate (PET) Resin Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Polyethylene Terephthalate (PET) Resin Market Foresight
Buyer concentration among beverage bottlers in the Gulf Cooperation Council is expanding as multinational soft-drink and bottled-water brands consolidate regional supply contracts. SABIC leverages its integrated cracker-to-polymer infrastructure across Jubail and Yanbu to capture captive feedstock economics. Indorama Ventures Public Company Limited anchors its African supply position through Egyptian and Nigerian conversion assets. Equate Petrochemical Company dominates Kuwait's export-oriented PET output, shipping resin to Pakistan and East African converters.
Polyethylene Terephthalate (PET) resin is a thermoplastic polyester polymerized from purified terephthalic acid and ethylene glycol, exhibiting intrinsic viscosity between 0.70 and 0.84 dL/g for bottle-grade specifications and melting points near 260°C. The material serves primarily as a lightweight, barrier-capable substrate for blow-molded containers and melt-spun synthetic fibers. Bottle Grade commands the dominant value share across Middle-East and Africa demand pools, driven by carbonated and still-water packaging volumes in Egypt, Nigeria, and South Africa. Food Grade resin carries premium positioning where SFDA and MOHAP compliance certifications filter import eligibility. Industrial Grade occupies a narrower but defensible niche in strapping and engineering film applications serving construction and logistics sectors.
SFDA's food-contact substance notifications and MOHAP's technical conformity assessments shape import clearance protocols for PET resin entering Saudi Arabia and the UAE, respectively. Egypt's EOS (Egyptian Organization for Standardization and Quality) labeling mandates and Nigeria's SONCAP certification requirements add compliance layers for non-Gulf suppliers. REACH-aligned substance declarations, though not directly binding across the region, increasingly appear in procurement specifications from European-owned bottlers operating African subsidiaries. Stakeholders must monitor how Gulf national industrial strategies redirect petrochemical feedstock allocations between domestic polymerization and higher-margin specialty chemicals.
Market Dynamics
SFDA and MOHAP food-contact purity mandates are compressing import eligibility windows for non-Gulf PET suppliers while integrated Saudi producers capture captive feedstock economics. This regulatory tightening concentrates procurement authority among beverage bottlers with direct cracker-to-polymer supply relationships.
Growth Catalysts
- Bottled water penetration:GCC consumer packaged goods expansion drives PET procurement scaling among multinational soft-drink and water brands consolidating regional supply contracts.
- SFDA compliance certification:Saudi food-contact material standards filter import eligibility, creating preference pull for resin meeting technical purity specifications.
- Jubail-Yanbu infrastructure:Saudi Arabia's Eastern Province petrochemical cluster feeds downstream conversion plants serving domestic and re-export packaging demand.
Market Restraints
- Feedstock volatility:Purified terephthalic acid and ethylene glycol input costs fluctuate with regional naphtha and natural gas liquid pricing.
- Gulf supply concentration:SABIC and Equate Petrochemical dominate export-oriented output, creating single-source dependency risk for Pakistani and East African converters.
- Technical limitation:Intrinsic viscosity specifications between 0.70 and 0.84 dL/g restrict resin interchangeability across blow-molding equipment generations.
Strategic Opportunities
- Nigerian conversion capacity:Underpenetrated West African demand pools offer white space for resin suppliers establishing local compounding and preform manufacturing.
- Food Grade premium positioning:EOS labeling mandates and SONCAP certification requirements create tiered pricing separation for compliant imports into Egypt and Nigeria.
- Industrial Grade niche expansion:Strapping and engineering film applications in construction and logistics sectors represent defensible specialty volume outside beverage packaging saturation.
Industry Challenges
- Certification timeline compression:REACH-aligned substance declarations increasingly appear in European-owned bottler procurement specifications, extending African subsidiary qualification cycles.
- Feedstock allocation reconfiguration:Gulf national industrial strategies redirect cracker output between domestic polymerization and higher-margin specialty chemicals, constraining PET-dedicated supply commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Polyethylene Terephthalate (PET) Resin Market |
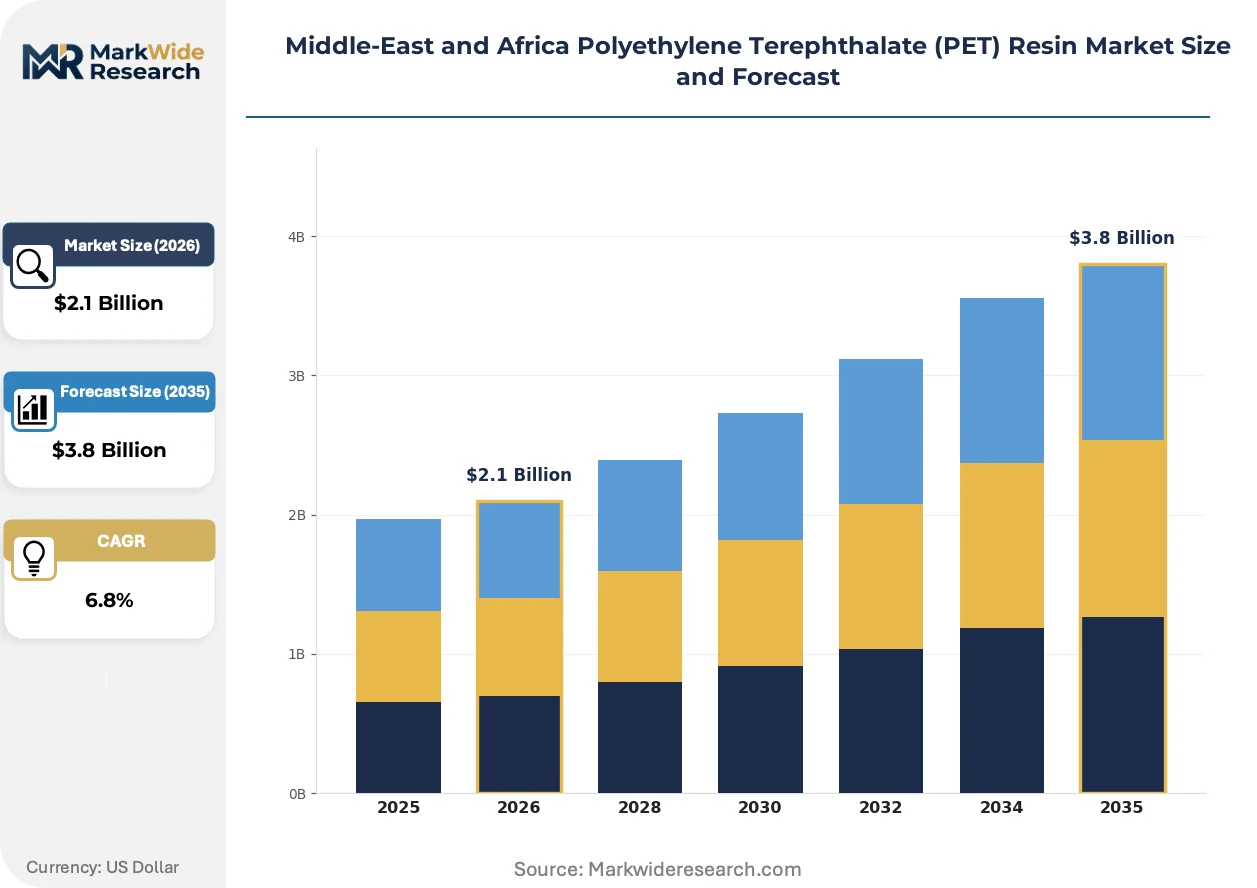
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Industrial Grade, Bottle Grade, Fiber Grade Application: Packaging, Textiles, Automotive, Electronics End User: Food & Beverage, Textile Manufacturers, Automotive OEMs, Consumer Electronics Distribution Channel: Direct Sales, Distributors, Online Retail, Others |
| Companies Covered | Equate Petrochemical Company, Eastman Chemical Company, SABIC, Invista, Alpek S.A.B. de C.V., Indorama Ventures Public Company Limited, Dow, KAP Industrial, BASF SE, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Polyethylene Terephthalate (PET) Resin Market Shifts & Advancements
Active integration of rPET flake into virgin resin streams is compressing the technical gap between mechanical recycling output and food-contact performance requirements. This material evolution is reshaping converter qualification protocols and procurement specifications across the Middle-East and Africa.
Barrier-enhancing co-injection technology is integrating oxygen-scavenging and UV-blocking layers into single-stage blow-molding processes. Egyptian and Nigerian converters serving carbonated soft-drink bottlers are adopting these systems at accelerated replacement cycles. The technology is integrating premium bottle-grade specifications with extended shelf-life claims, compressing commodity resin differentiation.
MOHAP technical conformity assessments now mandate third-party laboratory verification of acetaldehyde and heavy metal content for UAE-bound resin shipments. Industrial consequence includes extended customs clearance timelines and bonded warehousing requirements for non-pre-certified lots. Food Grade resin imports face the most stringent scrutiny, with Dubai-based bottlers consolidating supplier qualification around pre-approved certification bodies.
Buyer concentration among GCC beverage bottlers is compressing procurement decision cycles from annual tenders to semi-annual volume commitments with price renegotiation clauses. Regional supply contracts now incorporate feedstock indexation mechanisms previously limited to spot market transactions. This pattern is most visible in Saudi Arabia's Eastern Province, where SABIC-aligned converters serve multinational brand packaging lines under multi-year offtake agreements.
Middle-East and Africa Polyethylene Terephthalate (PET) Resin Market Segmentation
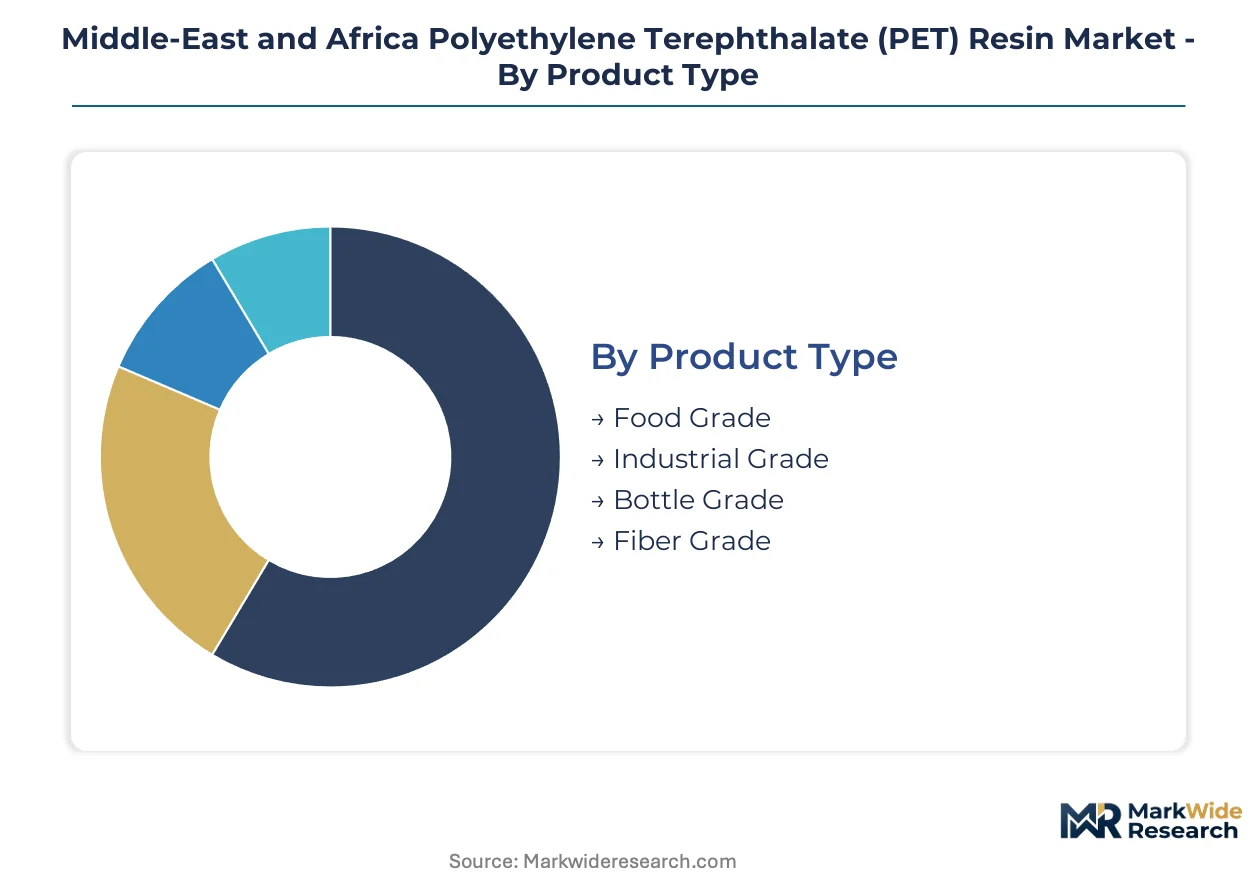
PET resin specifications diverge sharply across end-use requirements, with SFDA and MOHAP food-contact mandates creating tiered import eligibility that reshapes supplier qualification protocols. Segmentation clarity enables procurement teams to align technical purity standards with conversion equipment capabilities and regional regulatory thresholds.
Product Type:
SFDA food-contact notifications and MOHAP technical conformity assessments apply differentially across these grades, with Bottle Grade and Food Grade carrying the heaviest certification burdens for Gulf-bound shipments.
- Bottle Grade:Intrinsic viscosity specifications between 0.70 and 0.84 dL/g define this segment for blow-molded container production. Demand concentrates in Saudi Arabia's Eastern Province petrochemical cluster, where SABIC-aligned converters supply multinational beverage bottlers under multi-year offtake agreements with feedstock indexation clauses.
- Food Grade:Premium purity positioning requires acetaldehyde and heavy metal verification through third-party laboratories for UAE customs clearance. Egyptian and Nigerian converters prize this grade for carbonated soft-drink packaging lines, though SONCAP and EOS labeling mandates extend qualification timelines for non-pre-certified lots.
- Industrial Grade:Strapping and engineering film applications serve construction and logistics sectors with narrower purity requirements.
- Fiber Grade:Melt-spun synthetic fiber production for textile manufacturers operates outside food-contact regulatory scope.
Bottle Grade sits at the top of the volume ranking, with Food Grade climbing the fastest as SFDA compliance filters reshape procurement preferences.
Application:
Cost tier differentiation separates commodity packaging volumes from specialty automotive and electronics specifications that command formulation premiums.
- Packaging:Barrier-enhancing co-injection technology integrates oxygen-scavenging layers into single-stage blow-molding processes. Egyptian and Nigerian converters adopt these systems at accelerated replacement cycles, compressing commodity resin differentiation while extending shelf-life claims for carbonated beverages.
- Textiles:Fiber-grade PET feeds melt-spinning operations serving apparel and industrial fabric producers across North African manufacturing zones.
- Automotive:Engineering resin specifications for under-hood components and interior trim require thermal stability beyond standard bottle-grade parameters.
- Electronics:Film and sheet applications for device housings and insulation layers demand dimensional precision and dielectric performance.
Packaging dominates absolute volume, with Automotive gaining share fastest as regional vehicle assembly expands component localization mandates.
End User:
Customer type concentration drives procurement pattern divergence, with multinational beverage brands consolidating supply contracts differently than fragmented textile or electronics manufacturers.
- Food & Beverage:Buyer concentration among GCC beverage bottlers compresses decision cycles from annual tenders to semi-annual volume commitments with price renegotiation clauses. Dubai-based bottlers consolidate supplier qualification around pre-approved certification bodies to streamline MOHAP clearance.
- Textile Manufacturers:Dispersed demand across Egyptian and Moroccan spinning operations favors distributor-mediated procurement with smaller lot sizes.
- Automotive OEMs:Direct sales relationships dominate as tier-one suppliers qualify resin streams against OEM material specifications.
- Consumer Electronics:Regional assembly operations for smartphones and appliances source through specialized compounders with formulation customization capabilities.
Food & Beverage commands the largest revenue pool, with Automotive OEMs expanding procurement most quickly as domestic vehicle production scales.
Distribution Channel:
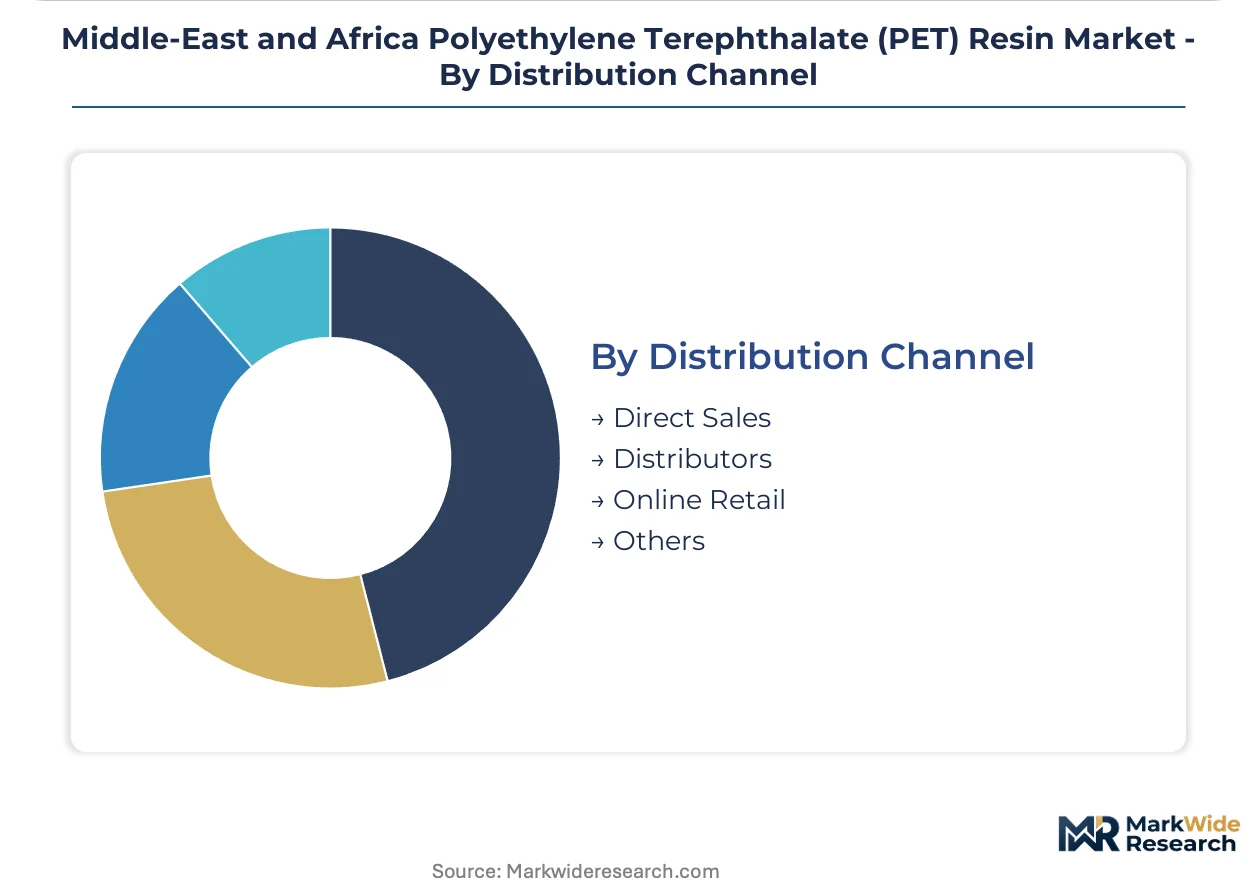
Supply concentration in Saudi Arabia and Kuwait shapes channel economics, with direct sales capturing integrated producer volumes while distributors serve fragmented African markets.
- Direct Sales:SABIC and Equate Petrochemical leverage captive cracker-to-polymer infrastructure for direct relationships with Eastern Province converters and Pakistani re-export customers.
- Distributors:Nigerian and Egyptian preform manufacturers rely on regional distributors to manage bonded warehousing and SONCAP certification complexity.
- Online Retail:Industrial resin procurement through digital platforms remains nascent, constrained by lot size minimums and technical qualification requirements.
- Others:Agent-mediated transactions serve smaller converters lacking direct supplier relationships.
Direct Sales captures the highest volume flow, with Distributors expanding fastest as West African conversion capacity builds local compounding infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical engineering talent clusters around Saudi Arabia's Eastern Province and the UAE's Dubai industrial corridor, anchoring regional resin production and conversion capabilities.
Saudi Arabia
Beverage bottlers in Riyadh and Jeddah scale PET procurement for carbonated soft-drink and bottled-water packaging lines. SFDA food-contact material standards mandate acetaldehyde and heavy metal verification for all resin imports. The Eastern Province petrochemical cluster around Jubail and Yanbu feeds downstream conversion plants serving domestic demand and re-export markets to Pakistan and East Africa.
United Arab Emirates
Dubai-based multinational beverage brands consolidate regional supply contracts under semi-annual volume commitments with price renegotiation clauses. MOHAP technical regulations require third-party laboratory verification of purity specifications for customs clearance. The Jebel Ali industrial zone hosts preform manufacturing operations supplying bottling lines across the Gulf Cooperation Council.
Egypt
Cairo and Alexandria converters serve carbonated soft-drink bottlers adopting barrier-enhancing co-injection technology at accelerated replacement cycles. EOS labeling mandates extend qualification timelines for non-pre-certified resin imports. The Suez Canal Economic Zone attracts regional distribution hubs managing bonded warehousing for North African markets.
Nigeria
Lagos and Kano preform manufacturers represent underpenetrated West African demand pools for local compounding operations. SONCAP certification requirements filter import eligibility for food-contact resin grades. The Lekki Free Trade Zone hosts emerging conversion capacity targeting domestic beverage packaging and re-export to neighboring ECOWAS states.
South Africa
Gauteng and Western Cape textile manufacturers consume fiber-grade PET for melt-spinning operations serving apparel and industrial fabric producers. The country's national standards body enforces technical specifications for polymer imports. The Durban industrial corridor anchors packaging material distribution serving Southern African Development Community markets.
Middle-East and Africa Polyethylene Terephthalate (PET) Resin Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the Middle-East and Africa PET resin supply base. Integrated petrochemical producers leverage captive cracker-to-polymer infrastructure to capture feedstock economics, while regional conversion specialists build import-dependent positions around distributed African markets. Three archetypes dominate: Gulf-based integrated producers with backward control over upstream feedstock, Asian-headquartered global resin networks with African conversion assets, and European chemical majors with specialty-grade positioning. Competitive moves concentrate on capacity expansion in underpenetrated West African markets and strategic partnerships to secure pre-certified supply status under tightening SFDA and MOHAP protocols.
Among Gulf-based integrated producers, SABIC and Equate Petrochemical occupy positions shaped by captive supply advantages and export-oriented output commitments. SABIC leverages its Eastern Province infrastructure to serve multinational beverage bottlers under multi-year offtake agreements. Equate Petrochemical anchors Kuwait's resin export position with shipments directed toward Pakistani and East African converters. Indorama Ventures Public Company Limited represents the Asian-headquartered network archetype, with Egyptian and Nigerian conversion assets supporting African supply penetration. These three companies exemplify how geographic origin and integration depth determine competitive positioning under divergent regulatory and feedstock cost structures across the region.
| Leading Market Players |
|---|
| Equate Petrochemical Company |
| Eastman Chemical Company |
| SABIC |
| Invista |
| Alpek S.A.B. de C.V. |
| Indorama Ventures Public Company Limited |
| Dow |
| KAP Industrial |
| BASF SE |
| Others |
Supply & Pricing Matrix
Sovereign-backed producers anchored in Saudi Arabia and Kuwait command pricing discipline through captive naphtha feedstock access, while family-owned Egyptian and Nigerian converters absorb margin compression from imported purified terephthalic acid exposure. This ownership-financing split concentrates cost advantage in Gulf integrated operations and transmits volatility to African distributed manufacturing.
Pricing Analysis
Contract-based long-term offtage agreements dominate the Gulf Cooperation Council, with spot-indexed clauses for purified terephthalic acid and ethylene glycol inputs. Price differentiation separates Food Grade resin commanding SFDA and MOHAP certification premiums from Industrial Grade commodity volumes. Cost compression in Egyptian and Nigerian import-dependent tiers is intensifying because bonded warehousing and SONCAP clearance extend working capital cycles. Small-lot textile manufacturers prove most price-sensitive, while multinational beverage bottlers under multi-year agreements show least elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Saudi Arabia and Kuwait for virgin resin output, while Egypt and Nigeria remain import-dependent for food-contact grades. Raw material flows draw from regional naphtha crackers, Asian purified terephthalic acid merchant supply, and natural gas liquid fractions. Regulatory restriction through SFDA food-contact notifications and MOHAP conformity assessments creates customs clearance chokepoints. Distribution runs through Jebel Ali bonded hubs serving African converters and direct sales from Jubail-Yanbu to Pakistani re-export markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
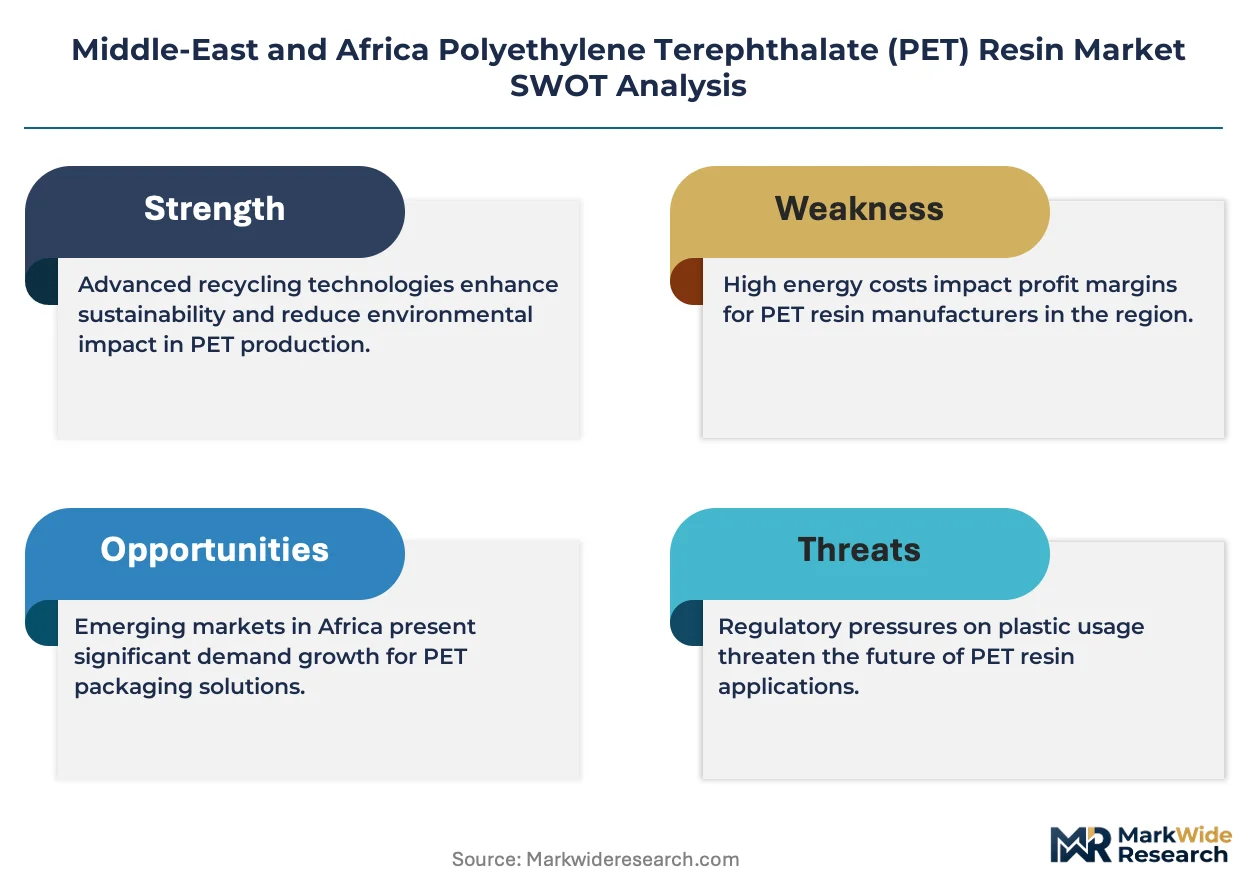
The Middle-East and Africa PET resin market functions as a geographic-arbitrage play where Egyptian and Nigerian converters pay feedstock premiums that Saudi integrated producers capture as margin expansion. SFDA compliance costs in Saudi Arabia versus SONCAP administrative burdens in Nigeria create divergent cost-to-serve economics.
For Market Incumbents: To counter feedstock volatility transmission from Asian purified terephalic acid suppliers, SABIC-aligned producers should deepen captive ethylene glycol production and lock Eastern Province cracker output under polymer-dedicated allocations. Certification investment in pre-approved MOHAP laboratory partnerships defends Gulf market access against European resin networks seeking African footholds. For New Entrants and Emerging Players: SONCAP in Nigeria opens a window for regional compounding operations serving Lagos and Kano preform manufacturers with localized food-grade purification. West African demand pools remain the most penetrable geography, with barrier-enhancing co-injection technology adoption creating equipment-financing entry angles alongside resin supply. For Investors and Strategic Acquirers: Asian-headquartered petrochemical conglomerates are the most active acquirer in this space, targeting Egyptian and Nigerian conversion assets to bypass Gulf supply concentration. Five-to-ten-year viability hinges on rPET flake integration capabilities meeting tightening food-contact purity mandates. The signal to watch is MOHAP expanding third-party verification requirements to acetaldehyde thresholds beyond current heavy metal screening.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cracker Feedstock | SABIC captures naphtha cost advantage through Jubail-Yanbu infrastructure control. |
| Long-term Supply Agreement with Certification Binding | Dubai bottlers consolidate procurement around pre-approved MOHAP laboratory partnerships. |
| Capacity Expansion in Underpenetrated West Africa | Lekki Free Trade Zone conversion assets target ECOWAS re-export demand growth. |
| Green Manufacturing Transition via rPET Integration | Mechanical recycling output compression narrows technical gap to food-contact performance. |
| Joint Venture for Local Compounding Infrastructure | Egyptian converters adopt barrier-enhancing co-injection through technology licensing partnerships. |
Research Methodology
Multiple input streams — primary interviews with plant managers at Saudi and Kuwaiti petrochemical facilities, procurement leads at Egyptian preform manufacturers, and distribution channel partners across Dubai's Jebel Ali zone — were reconciled against customs trade data, SFDA regulatory filings, and SEC disclosures from integrated chemical majors. Bottom-up resin volume estimates from converter throughput and top-down cracker capacity allocations were triangulated to constrain forecast ranges.
Historical production and trade flow patterns were cross-referenced against expert panel inputs from technical R&D directors and regulatory affairs specialists across the analysis window. Segmentation dimensions modeled include grade tier (Bottle, Food, Industrial, Fiber), end-use industry (beverage packaging, textiles, automotive), packaging format (preform, sheet, fiber), and regional production hub (Eastern Province, Jebel Ali, Suez Canal Economic Zone, Lekki Free Trade Zone). CAGRs were derived from elasticity-adjusted demand projections incorporating bottled water penetration curves and rPET substitution rates.
Revisions become necessary when Gulf national industrial strategies redirect cracker output toward specialty chemicals, or when MOHAP and SFDA tighten food-contact purity thresholds beyond current verification protocols. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Novolac Resins Market
Polymers & Resins
Resorbable Polymers Market
Polymers & Resins
Polyglycerol Polyricinoleate Market
Polymers & Resins
Global Flexible Polyurethane Foam Market
Polymers & Resins
Polybenzoxazine Resins Market
Polymers & Resins
Synthetic and Bio Thermosets Market
Polymers & Resins
Hydrophobic Interaction Chromatography Resins Market
Polymers & Resins
Global Anti-Vibration Polymer Market
Polymers & Resins
Non-Ionic Polyacrylamide Market
Polymers & Resins
Glutathione Resin Market
Polymers & Resins
Cast Polymers Market
Polymers & Resins
Bio-Based Polypropylene in Medical Devices Market
Polymers & Resins
Global Liquid Crystal Polymer (LCP) Market
Polymers & Resins
Flame Retardant Polyester Resins Market
Polymers & Resins
South America Polyamide Market
Polymers & Resins
Polymer Antioxidants Market