
 Polyurethane (PU) Foam Market | 2026-2036
Polyurethane (PU) Foam Market Size, Share, and Industry Trends Forecast 2026-2036
Polyurethane (PU) Foam Market Intelligence
China is rewriting capacity dynamics in polyurethane foam manufacturing through state-backed chemical parks and polyol expansion. Wanhua Chemical Group leverages captive MDI supply to dominate upstream feedstock economics. Covestro AG sustains technology leadership in low-emission rigid foam formulations for European construction codes. BASF SE anchors global flexible foam supply through integrated polyurethane systems houses across three continents.
Polyurethane foam denotes a polymer system formed by reacting polyols with diisocyanates, typically MDI or TDI, yielding cellular structures with tunable density from 10 to 800 kg per cubic meter depending on blowing agent and catalyst selection. The material serves as both a structural cushion and thermal barrier across furniture, transportation, and building envelopes. Flexible foam commands the largest volume share within furniture and bedding applications where open-cell architecture delivers pressure distribution and durability. Rigid foam generates the fastest value expansion as insulation demand intensifies under escalating energy efficiency mandates in residential and commercial construction. Spray foam occupies a specialized margin pool in retrofit building envelopes and industrial pipe insulation where application speed and air-sealing performance justify premium positioning.
EPA Significant New Alternatives Policy and EU F-Gas Regulation are restricting hydrofluorocarbon blowing agents, forcing reformulation toward hydrofluoroolefins, hydrocarbons, or water-blown systems across foam producers. REACH chemical registration and CE marking for construction products govern market access in Europe, while OSHA workplace exposure limits on isocyanates shape plant investment decisions in the United States. Stakeholders must monitor blowing agent transition timelines and isocyanate feedstock cost volatility to preserve margin structure through the forecast window.
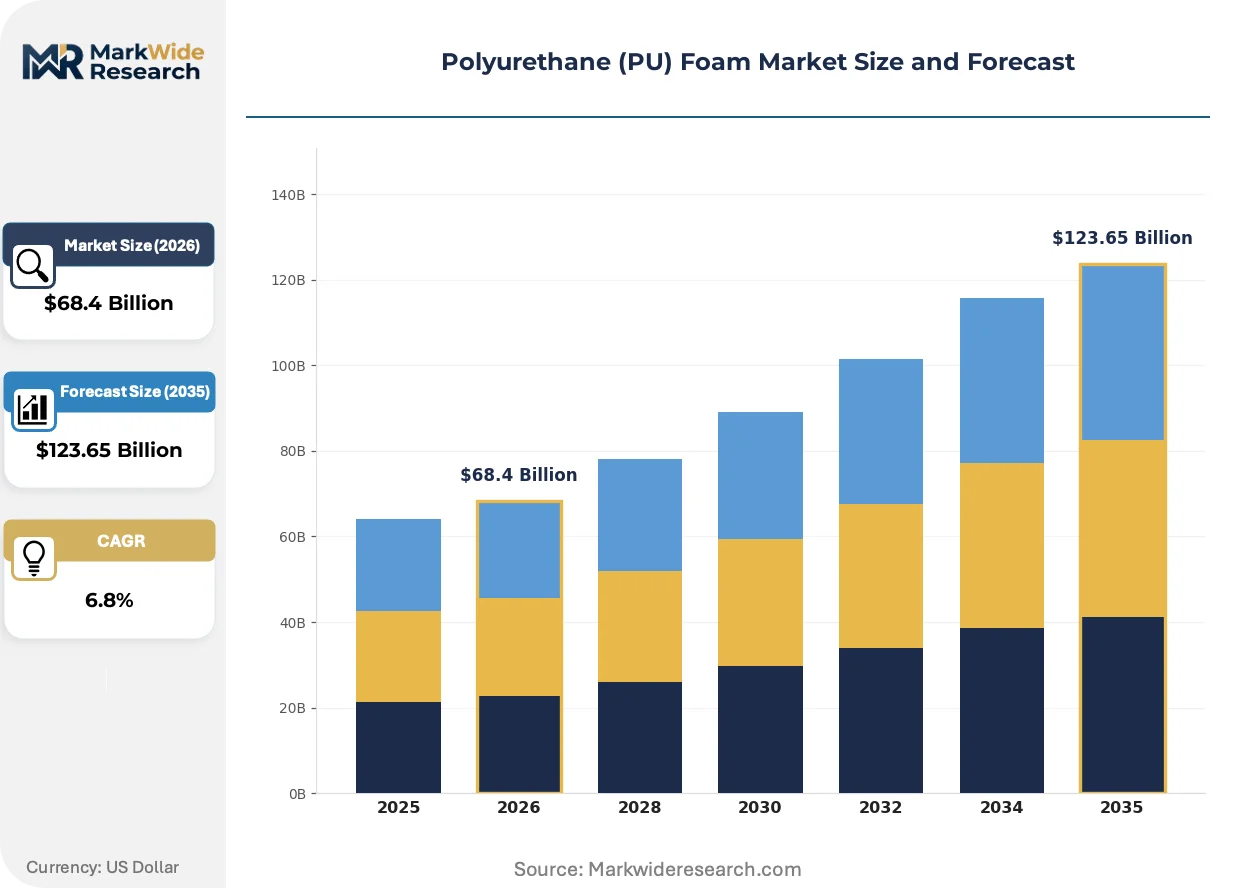
Market Dynamics
The PU foam market is undergoing forced reformulation as the EPA Significant New Alternatives Policy and EU F-Gas Regulation phase down hydrofluorocarbon blowing agents, compelling producers to retool formulations toward hydrofluoroolefins, hydrocarbons, or water-blown systems within compressed timelines.
Growth Catalysts
- Building energy codes in Germany and France:Tightening thermal performance standards for residential and commercial envelopes are mandating thicker rigid foam insulation layers, driving specification upgrades across cold-climate construction.
- Cold-chain logistics expansion in China:Megacity residential development and refrigerated warehouse construction are accelerating rigid foam consumption for temperature-controlled storage and transport infrastructure.
- Water-blown foam technology:Advances in catalyst systems enabling water-only blowing are reducing formulation complexity and supply chain exposure to fluorinated gas price volatility.
Market Restraints
- MDI feedstock concentration:Wanhua Chemical Group and a handful of Asian producers control upstream methylene diphenyl diisocyanate supply, creating margin squeeze risk for downstream foam compounders during capacity tightness.
- Isocyanate workplace exposure limits:OSHA permissible exposure limits on toluene diisocyanate and methylene diphenyl diisocyanate are elevating plant ventilation and personal protective equipment capital requirements across US manufacturing sites.
- Mineral wool substitution in high-rise construction:Fire safety codes in certain jurisdictions are favoring non-combustible insulation alternatives for tall building envelopes, constraining rigid PU foam addressable market in specific vertical segments.
Strategic Opportunities
- Retrofit building envelope spray foam:Aging housing stock in Germany and France presents underpenetrated demand for air-sealing and insulation upgrades where application speed justifies premium positioning over batt alternatives.
- EU Green Deal renovation wave:The building renovation mandate is creating regulatory tailwind for high-performance insulation materials meeting combined thermal and air-barrier specifications in single-package systems.
- Bio-based polyol convergence with mechanical recycling:Integration of soy-derived and recycled content polyols with emerging chemical recycling infrastructure is opening circular economy positioning for sustainability-specified construction projects.
Industry Challenges
- Formulation chemist specialization:The transition from hydrofluorocarbon to hydrofluoroolefin and hydrocarbon blowing agents requires scarce expertise in catalyst-blowing agent interaction kinetics, constraining producer R&D bandwidth.
- CE marking certification timelines:Construction product regulation compliance for new foam formulations in Europe involves extended fire reaction and thermal performance testing, delaying market entry for reformulated systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyurethane (PU) Foam Market |
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Foam, Rigid Foam, Semi-Rigid Foam, Spray Foam Application: Furniture, Automotive Interiors, Bedding, Insulation End User: Residential, Commercial, Industrial, Healthcare Density: Low Density, Medium Density, High Density, Very High Density |
| Companies Covered | Huntsman Corporation, Wanhua Chemical Group Co., Ltd., Covestro AG, Recticel NV/SA, Saint-Gobain, BASF SE, Sekisui Chemical Co., Ltd., INOAC Corporation, Dow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyurethane (PU) Foam Market Strategic Shifts & Innovations
Formulation chemistry is pivoting rapidly as regulatory deadlines compress, with producers racing to maintain thermal performance while eliminating high-global-warming-potential blowing agents from rigid foam systems.
Hydrofluoroolefin blowing agents are migrating from niche pilot applications to mainstream rigid foam production in European construction markets. Covestro AG and BASF SE are scaling HFO-1234ze and HFO-1336mzz systems for spray and boardstock applications where lambda value preservation matters. This migration from hydrofluorocarbon baselines is enabling producers to maintain CE marking compliance under tightening F-Gas phase-down schedules while avoiding hydrocarbon flammability handling constraints.
The EU F-Gas Regulation quota system is forcing accelerated capital deployment into alternative blowing agent infrastructure. Foam producers are reconfiguring storage and metering systems for low-pressure hydrocarbon or high-pressure HFO delivery, with compliance deadlines compressing investment timelines. Germany and France are seeing the fastest facility retooling as national building codes simultaneously ratchet thermal performance requirements, creating dual pressure on formulation teams.
Cold-chain logistics operators are consolidating procurement specifications around combined thermal performance and fire safety certification tiers. Large refrigerated warehouse developers in China are unbundling insulation specification from general contractor packages, creating direct purchasing relationships with systems houses capable of delivering certified rigid foam with documented lambda values and reaction-to-fire classifications. This buyer concentration is most visible in Shanghai and Beijing megacity logistics corridors where multinational cold-chain operators are standardizing pan-Asian material specifications.
Polyurethane (PU) Foam Market Segmentation
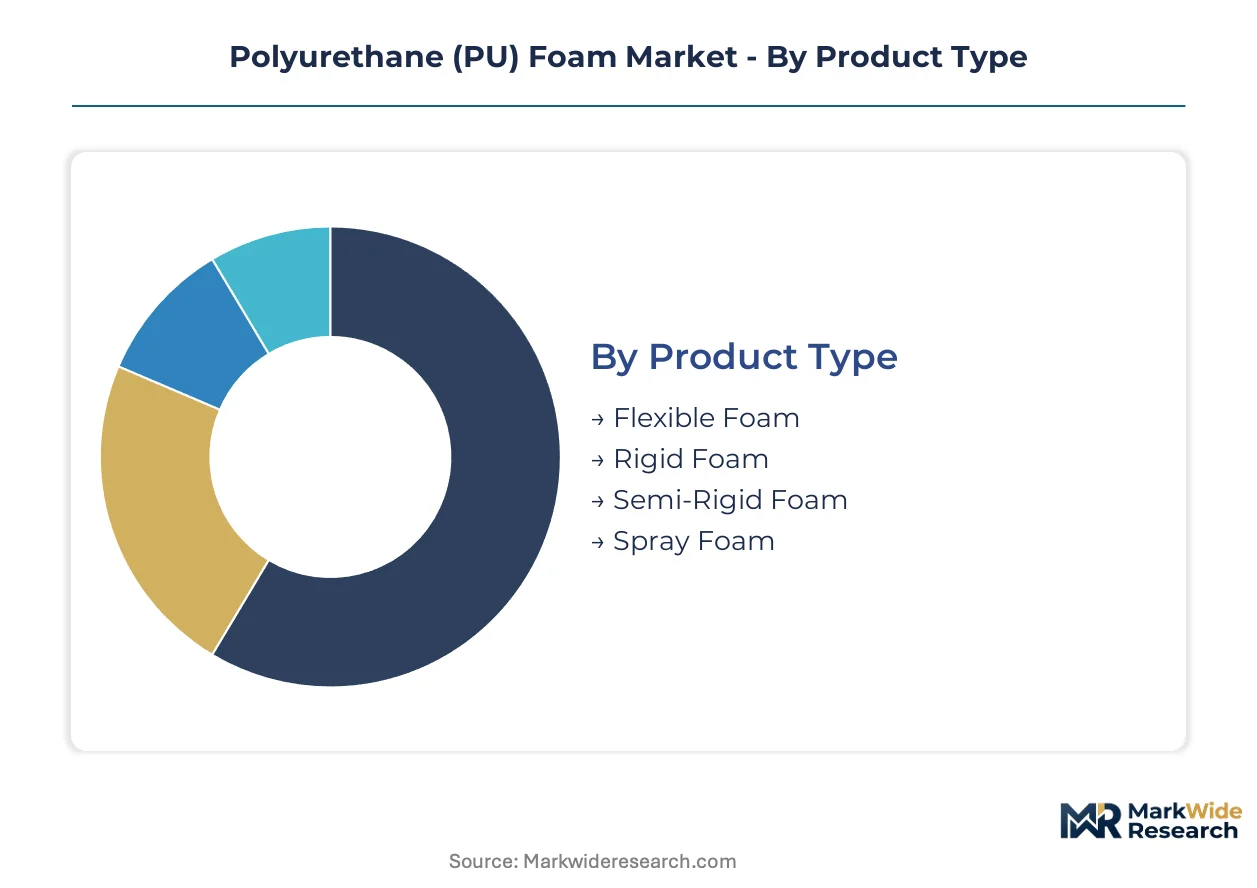
Polyurethane foam segmentation reveals how formulation chemistry and density tuning align with distinct performance requirements across thermal insulation, cushioning, and structural applications. Understanding these category boundaries helps identify where specification upgrades and regulatory compliance investments concentrate.
Product Type:
Use-case spectrum spans compressible comfort layers to rigid thermal barriers, with each foam architecture demanding specialized catalyst and blowing agent systems.
- Flexible Foam:Open-cell structures with tunable resilience serve furniture and bedding where pressure distribution and durability drive specification. Demand concentrates in China for megacity residential development and cold-chain logistics infrastructure expansion.
- Rigid Foam:Closed-cell configurations deliver thermal resistance values critical for building envelope and refrigerated transport applications. Germany and France construction codes mandate thicker insulation layers, accelerating specification upgrades for energy-efficient envelopes.
- Semi-Rigid Foam:Intermediate density range supports automotive interior panels and packaging where structural integrity meets moderate flexibility requirements.
- Spray Foam:Field-applied systems enable rapid air-sealing in retrofit building envelopes and industrial pipe insulation where application speed justifies premium positioning.
Established volume favors Flexible Foam; emerging adoption favors Rigid Foam.
Application:
Cost tier segmentation separates commodity cushioning from specification-driven thermal performance markets where certification requirements elevate margin structures.
- Furniture:Molded and slabstock configurations dominate seating and upholstery applications. REACH chemical registration and CE marking govern market access in Europe for flame-retardant formulations.
- Automotive Interiors:Dashboard padding, headliners, and seat cushions require low-VOC emissions compliance under EPA and CARB regulations in US markets.
- Bedding:Memory foam and high-resilience variants command premium positioning in mattress cores where pressure relief specifications differentiate product tiers.
- Insulation:Boardstock and spray systems for wall, roof, and foundation applications face F-Gas Regulation reformulation mandates across EU member states.
Volume concentration sits with Furniture; steepest expansion trajectory belongs to Insulation.
End User:
Customer type determines specification stringency, with institutional buyers enforcing certified thermal performance and fire reaction classifications unavailable in consumer-direct channels.
- Residential:Single-family and multifamily construction drives flexible foam for furnishings and rigid foam for envelope insulation under tightening building energy codes.
- Commercial:Office, retail, and hospitality projects specify combined thermal and air-barrier systems where EU Green Deal renovation wave creates regulatory tailwind.
- Industrial:Refrigerated warehouse and cold-chain logistics operators in China unbundle insulation procurement from general contractor packages, creating direct purchasing relationships with systems houses.
- Healthcare:Hospital mattresses and medical seating demand antimicrobial and pressure-ulcer-prevention certifications under FDA and EMA device regulations.
Procurement scale favors Commercial; specification complexity peaks in Healthcare.
Density:
Supply concentration in MDI feedstock creates margin tiering, with high-density formulations absorbing isocyanate cost volatility more effectively than commodity low-density grades.
- Low Density:Below 30 kg per cubic meter serves packaging and disposable cushioning where cost minimization dominates purchasing decisions.
- Medium Density:30-80 kg per cubic meter balances comfort and durability for standard furniture and automotive seating applications.
- High Density:80-250 kg per cubic meter supports structural insulation boards and memory foam bedding where compression set resistance justifies material investment.
- Very High Density:Above 250 kg per cubic meter enables specialty applications including shoe soles, industrial wheels, and medical devices requiring abrasion resistance and dimensional stability.
Production volume centers on Medium Density; value per kilogram climbs fastest in Very High Density.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT and MEE are tightening dual carbon goals and GB standards for building materials, anchoring the dominant geography where megacity construction and cold-chain logistics drive rigid foam consumption. Regulatory pressure on blowing agents and thermal performance codes is reshaping investment patterns across four additional national markets.
China
Megacity residential development in Shanghai and Beijing, alongside refrigerated warehouse construction, accelerates rigid foam consumption for temperature-controlled infrastructure. The country's GB standards and dual carbon goals under MEE oversight mandate lower-emission blowing agent transitions. Yangtze River Delta chemical parks concentrate polyol expansion and captive MDI supply integration.
Germany
Retrofit building envelope demand and cold-climate housing insulation upgrades drive specification for spray and boardstock systems. The KBA and federal building energy codes, aligned with EU F-Gas Regulation phase-down schedules, enforce thermal performance thresholds. Industrial clusters in North Rhine-Westphalia and Bavaria host systems houses retooling for HFO and hydrocarbon blowing agent infrastructure.
United States
Residential construction recovery and commercial refrigeration infrastructure sustain flexible and rigid foam demand across furniture and cold-chain applications. EPA Significant New Alternatives Policy restricts hydrofluorocarbon blowing agents, while OSHA workplace exposure limits on isocyanates elevate plant capital requirements. Gulf Coast petrochemical corridors and Midwest manufacturing belts concentrate foam compounding and systems house operations.
France
EU Green Deal renovation wave mandates and tightening RT 2012 thermal regulations drive air-sealing and insulation upgrades in aging housing stock. ANSM and CE marking requirements govern construction product market access for reformulated low-emission systems. The Île-de-France and Auvergne-Rhône-Alpes regions concentrate retrofit project pipelines and certified systems house distribution.
Japan
Automotive interior applications and high-performance bedding sustain medium-density flexible foam demand amid demographic shifts. METI energy efficiency standards for buildings and JIS certification requirements shape insulation specification in commercial construction. Kanto and Kansai industrial corridors host integrated polyurethane operations serving domestic appliance and transportation OEMs.
Polyurethane (PU) Foam Market Key Industry Players
Capability concentration sits with integrated chemical producers commanding upstream MDI and polyol supply; scale advantage sits with global systems houses operating across three continents. The market structure reflects a tiered hierarchy where feedstock integration determines margin resilience and formulation expertise secures specification in regulated construction markets. Three archetypes dominate: Asian state-backed chemical conglomerates with captive isocyanate supply, European technology leaders in low-emission rigid foam formulations, and diversified materials multinationals with continental distribution networks. Competitive moves center on blowing agent transition partnerships and polyol capacity expansion in chemical park clusters.
Among integrated chemical producers, Wanhua Chemical Group Co., Ltd. and Covestro AG exemplify divergent geographic and strategic positioning. Wanhua represents the state-backed Asian archetype with captive feedstock economics, while Covestro occupies the European technology-specialist tier. BASF SE anchors the diversified multinational segment with systems house presence across multiple continents. These three entities illustrate how feedstock integration, regulatory compliance capability, and geographic footprint combine to structure competitive position in a reformulation-intensive market environment.
| Leading Market Players |
|---|
| Huntsman Corporation |
| Wanhua Chemical Group Co., Ltd. |
| Covestro AG |
| Recticel NV/SA |
| Saint-Gobain |
| BASF SE |
| Sekisui Chemical Co., Ltd. |
| INOAC Corporation |
| Dow |
| Others |
Cost & Logistics Intelligence
Wanhua Chemical Group's captive MDI supply in China's Yangtze River Delta chemical parks concentrates upstream pricing power, forcing downstream foam compounders to absorb feedstock volatility while margin pools concentrate in rigid insulation grades serving EU energy code compliance.
Pricing Analysis
European spray foam commands 40-60% premiums over Asian boardstock equivalents, reflecting CE marking certification costs and F-Gas Regulation compliance investments. Pricing stratifies across premium certified systems, standard construction grades, and economy packaging foams. Cost compression in flexible furniture grades is intensifying because of polyol oversupply in Chinese chemical parks. Cold-chain logistics operators show least price sensitivity; disposable packaging buyers absorb margin squeeze fastest.
Supply Chain Analysis
Systems house concentration rests on BASF SE, Covestro AG, and Huntsman Corporation operating integrated formulation facilities across Germany, China, and the United States. Feedstock draws from methylene diphenyl diisocyanate, polyether polyols, and blowing agent precursors. Single-source vulnerability concentrates in MDI supply during Asian plant maintenance cycles. Distribution runs through direct procurement relationships with large refrigerated warehouse developers and construction systems houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The polyurethane foam market is accelerating through forced reformulation as EPA and EU F-Gas deadlines eliminate hydrofluorocarbon blowing agents, compressing investment timelines for alternative chemistry infrastructure.
For Market Incumbents: Entrench feedstock security through backward integration into polyol production or long-term offtake agreements with Yangtze River Delta chemical parks. Defend specification share in German and French retrofit envelopes by accelerating HFO-1234ze and hydrocarbon system certifications ahead of CE marking deadlines. Mineral wool substitution in high-rise fire codes threatens rigid foam addressable market; counter with combined thermal-air-barrier system positioning. For New Entrants and Emerging Players: Southeast Asian cold-chain logistics corridors offer underpenetrated demand for certified rigid foam systems as regional refrigerated warehouse construction accelerates. Target spray foam retrofit applications in aging EU housing stock where application speed justifies premium positioning over mineral wool batt alternatives. Partner with established systems houses for toll formulation capacity rather than greenfield plant investment. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across HFO and hydrocarbon blowing agent infrastructure as compliance deadlines compress retooling timelines. Five-to-ten year viability favors integrated producers with captive isocyanate supply and CE marking capabilities. Monitor EU F-Gas quota auction prices as inflection indicator for reformulation cost pass-through feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyol Production | Yangtze River Delta chemical parks anchor feedstock economics for Wanhua and downstream compounders. |
| HFO Blowing Agent System Certification | Covestro and BASF are scaling HFO-1234ze formulations to maintain CE marking under F-Gas phase-down. |
| Direct Procurement Relationship Development | Chinese cold-chain operators unbundle insulation specification from general contractor packages. |
| Bio-based Polyol Convergence Investment | Soy-derived and recycled content integration opens circular economy positioning for EU Green Deal projects. |
| Spray Foam Application Training Infrastructure | Retrofit envelope demand in Germany and France requires certified installer networks for air-sealing performance. |
Research Approach
The analysis maps rigid insulation, flexible cushioning, and spray foam sub-sectors, each validated through plant managers at systems houses, procurement leads at cold-chain operators, and technical R&D directors at chemical producers. Primary interviews combined with secondary validation from customs/trade data, Cefic industry reports, SEC 10-K filings, and EPA SNAP regulatory filings. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates.
Assumptions held F-Gas Regulation phase-down schedules and EU building energy code tightening as fixed conditions, while varying MDI feedstock cost scenarios and blowing agent transition timelines across the projection horizon. Segmentation dimensions modeled include foam architecture, density tier, end-use industry, and regional regulatory cluster. CAGRs derived from weighted average of historical trajectory and policy-driven inflection analysis, with catalyst system availability and CE marking certification timelines as key forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by state-backed Asian chemical conglomerates or accelerated mineral wool substitution in fire codes would shift outcomes. Quarterly review of EU F-Gas quota auction results and Chinese chemical park utilization rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Unsaturated Polyester Resins Market
Polymers & Resins
Thermoplastic Polyester Engineering Resin (TPER) Market
Polymers & Resins
Europe Polycarbonate (PC) Market
Polymers & Resins
Polyether Ketone (PEK) Market
Polymers & Resins
Polysiloxane Market
Polymers & Resins
Polymer Gel Market
Polymers & Resins
Thermoplastic Polyamide Elastomer (TPE) Market
Polymers & Resins
Liquid Polybutadiene [LPBD] Market
Polymers & Resins
Poly (Butylene Adipate-Co-Terephthalate) Market
Polymers & Resins
Global UV Curable Resins and Formulated Products Market
Polymers & Resins
Copolyesters Market
Polymers & Resins
HDPE Large Blow Molded Products Market
Polymers & Resins
Global Polyoxymethylene (POM) Market
Polymers & Resins
Bio-Based Polycarbonate Market
Polymers & Resins
Medical Polymers Market
Polymers & Resins
Expanded Polystyrene (EPS) Market