
 Global Terpene Market | 2026-2036
Global Terpene Market Size, Share, and Industry Trends Forecast 2026-2036
Global Terpene Market Foresight
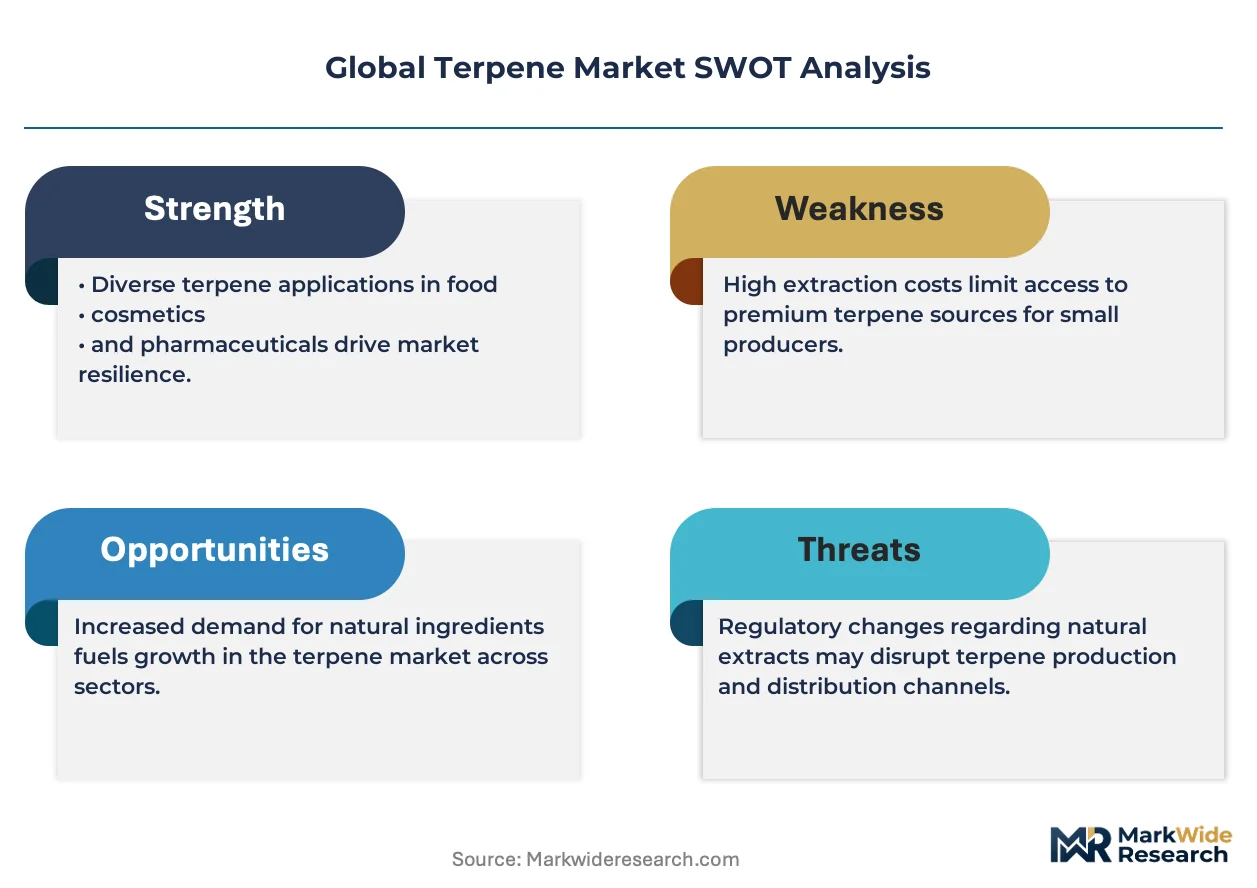
REACH is decoupling commodity-grade terpene supply from premium fragrance and pharmaceutical channels. International Flavors & Fragrances leverages captive citrus processing assets across Spain and Brazil to secure raw material continuity. Givaudan anchors its terpene portfolio on rare and proprietary botanical sources that command formulation premiums. Firmenich differentiates through biotechnology-derived terpenes that bypass agricultural yield volatility.
Terpene denotes a diverse class of hydrocarbon compounds built from isoprene units, with monoterpenes (C10H16) and sesquiterpenes (C15H24) constituting the most commercially extracted fractions via steam distillation or supercritical CO2. These molecules serve as aromatic precursors, solubilizing agents, and bioactive intermediaries across industrial chemistry. Monoterpenes dominate volume throughput due to their abundance in citrus peel oils and established use in flavor compounding. Sesquiterpenes capture disproportionate margin pools owing to their scarcity in nature and concentrated demand from pharmaceutical synthesis. Supercritical CO2 extraction is displacing solvent-based methods in premium segments as cosmetic manufacturers and nutraceutical producers impose residual solvent thresholds below detectable limits.
EMA pharmaceutical guidelines, EPA environmental release standards, and F-Gas Regulation in Europe collectively tighten specifications for terpene purity, volatile organic compound emissions, and fluorinated solvent alternatives. BIS certification requirements in India and CDSCO pharmaceutical excipient standards further fragment market access for non-compliant suppliers. Stakeholders must monitor regulatory divergence between jurisdictions to determine where to site extraction capacity and which purity grades to prioritize for cross-border shipment.
Market Dynamics
REACH compliance in Europe is bifurcating terpene supply chains into commodity and certified-grade channels, forcing extractors to choose between volume throughput and premium market access. Pharmaceutical formulators now demand residual solvent thresholds below detectable limits, compressing margins for conventional steam distillation operations while rewarding supercritical CO2 investments.
Growth Catalysts
- Pharmaceutical Excipient Demand:Drug delivery enhancement applications are absorbing high-purity monoterpenes as solubilizing agents for lipophilic APIs, with CDSCO standards in India and EMA guidelines in Europe mandating documented purity certificates.
- F-Gas Regulation:Europe's phase-down of fluorinated solvents is redirecting industrial cleaning and precision degreasing demand toward d-limonene and pinene derivatives as drop-in replacements.
- Brazil Citrus Belt Expansion:Orange processing capacity in São Paulo state continues scaling, securing raw material continuity for fragrance houses and flavor compounders dependent on cold-pressed peel oils.
Market Restraints
- Agricultural Yield Volatility:Citrus greening disease and climate stress in Florida and Mediterranean growing regions inject supply uncertainty into limonene and pinene feedstock markets.
- Purification Cost Escalation:Multi-stage fractional distillation and molecular distillation required for pharmaceutical-grade terpenes consume 40-60% of production costs, compressing returns for mid-scale operators.
- Substitution Pressure:Synthetic aroma chemicals and petroleum-derived solvents compete on price in industrial cleaning and basic fragrance applications where natural provenance carries no premium.
Strategic Opportunities
- Biotechnology-Derived Terpenes:Microbial fermentation and yeast cell factories bypass agricultural constraints, enabling Firmenich and specialty biotech firms to produce rare sesquiterpenes unavailable from conventional extraction.
- Underpenetrated Indian Market:BIS certification requirements and FSSAI flavor standards are formalizing previously informal supply chains, creating first-mover advantages for compliant international suppliers.
- Cosmetic Clean Beauty Mandates:EU Green Deal sustainability reporting and CSRD disclosure requirements favor botanical-derived inputs with traceable supply chains over petrochemical alternatives in prestige skincare.
Industry Challenges
- Supercritical CO2 Engineering Talent Scarcity:Design and operation of high-pressure extraction systems requires specialized process engineering expertise concentrated in Germany, Switzerland, and select US research universities.
- Cross-Border Certification Timelines:REACH registration dossiers and EPA environmental release permits demand 18-36 month approval cycles, delaying market entry for novel botanical sources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Terpene Market |
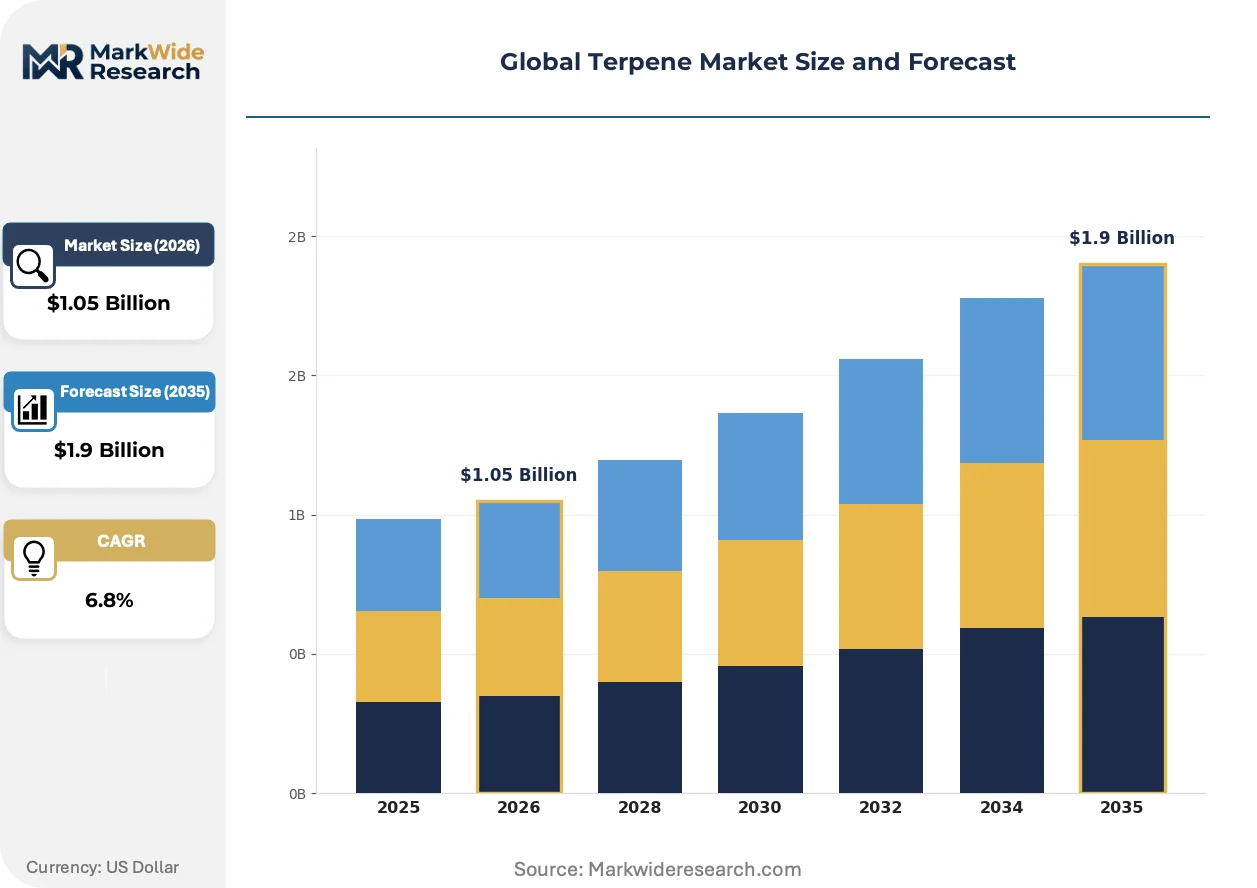
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.9 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoterpenes, Sesquiterpenes, Diterpenes, Triterpenes, Others Application: Flavors & Fragrances, Pharmaceuticals, Personal Care, Food & Beverages, Agrochemicals Extraction Method: Steam Distillation, Solvent Extraction, Cold Pressing, Supercritical CO2, Molecular Distillation End User Industry: Cosmetic Manufacturers, Nutraceutical Producers, Food Processing Units, Agricultural Firms, Chemical Synthesizers |
| Companies Covered | International Flavors & Fragrances, Privi Organics, Firmenich, Florachem Corporation, Sensient Technologies, Givaudan, Vigon International, Flotek Industries, Symrise, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Terpene Market Shifts & Advancements
Extraction technology convergence and regulatory disclosure mandates are compressing traditional supply chain tiers, forcing closer coordination between raw material processors and finished goods manufacturers. Three developments dominate strategic planning.
Supercritical CO2 extraction is unifying purification and solvent removal into single-unit operations, eliminating residual hexane or ethanol traces that disqualify outputs from pharmaceutical and infant-grade cosmetic applications. European fragrance houses and Japanese nutraceutical contract manufacturers now specify CO2-derived terpenes exclusively for premium positioning. This technology is compressing the traditional separation between commodity extractors and specialty chemical refiners.
REACH SVHC candidate list expansion is compelling downstream formulators to document full substance composition throughout their supply chains, elevating analytical testing costs for imported terpene batches. ECHA enforcement in Germany and the Netherlands has intensified border inspections, diverting non-compliant shipments to less regulated markets. Fragrance compounders serving EU-based multinational personal care brands now require third-party REACH compliance certificates as standard procurement terms.
Direct sourcing contracts between citrus processors and end-use manufacturers are displacing traditional merchant market transactions, with fragrance houses and pharmaceutical excipient suppliers establishing multi-year offtake agreements with Brazilian and Spanish cooperatives. This channel compression eliminates intermediary traders and enables lot-level traceability demanded by clean beauty and natural health product certifications. The pattern is most visible in California and European markets where consumer-facing brands market supply chain transparency as a competitive attribute.
Global Terpene Market Segmentation
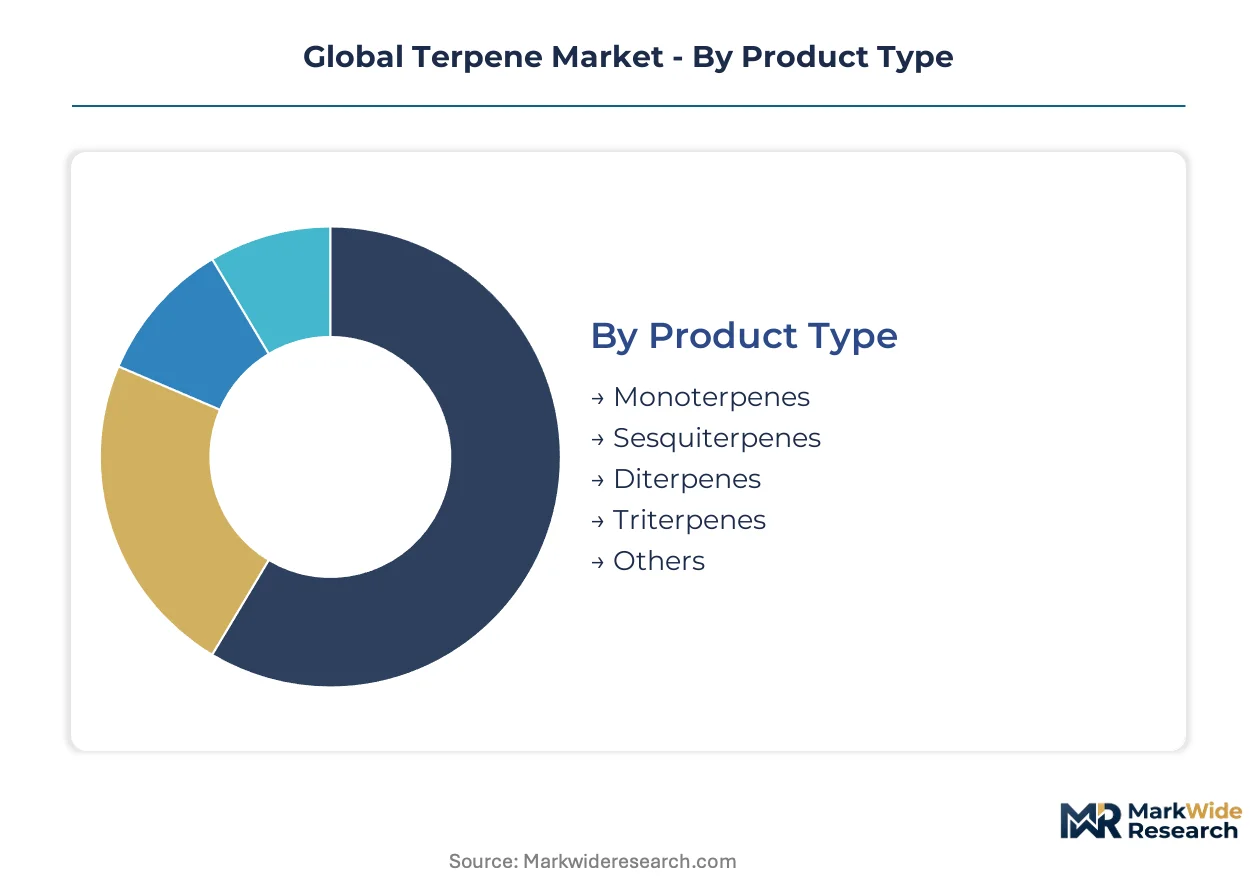
Terpene market segmentation reveals how extraction economics, regulatory thresholds, and end-use specifications fragment supply into distinct commercial channels. Buyers select grades based on residual solvent limits, botanical provenance requirements, and volume scale rather than molecular class alone.
Product Type:
Buyers prioritize molecular size and scarcity when specifying terpene inputs, with pharmaceutical formulators paying premiums for rare sesquiterpenes unavailable from commodity citrus processing.
- Monoterpenes:These C10H16 hydrocarbons constitute the dominant volume fraction, extracted primarily from orange and lemon peel oils via cold pressing or steam distillation. Demand concentrates in São Paulo state's citrus belt, where fragrance houses secure multi-year offtake agreements to guarantee limonene supply for flavor compounding.
- Sesquiterpenes:C15H24 structures command disproportionate margins due to scarcity in conventional botanical sources and concentrated demand from pharmaceutical synthesis. Biotechnology firms in Switzerland and Germany now deploy yeast cell factories to bypass agricultural yield constraints for rare variants like bisabolol and caryophyllene.
- Diterpenes:C20H32 compounds serve specialized applications in resin chemistry and traditional medicine extracts.
- Triterpenes:C30H48 molecules function as bioactive intermediaries in nutraceutical formulations.
- Others:Polyterpenes and irregular terpenoids address niche industrial applications.
Monoterpenes lead on scale; sesquiterpenes lead on momentum.
Application:
Application selection tracks regulatory jurisdiction, with EU REACH compliance and US FDA pharmaceutical excipient standards bifurcating demand into certified and commodity channels.
- Flavors & Fragrances:Formulators specify d-limonene and pinene derivatives for citrus and woody aromatic profiles. European fragrance houses now require REACH-compliant certificates as standard procurement terms, diverting non-certified batches to less regulated markets.
- Pharmaceuticals:High-purity monoterpenes function as solubilizing agents for lipophilic APIs. EMA guidelines and CDSCO standards in India mandate documented purity certificates, compressing margins for conventional extraction operations.
- Personal Care:Clean beauty mandates favor botanical-derived inputs with traceable supply chains over petrochemical alternatives.
- Food & Beverages:FSSAI flavor standards in India and FDA GRAS listings govern permissible terpene concentrations.
- Agrochemicals:Natural terpenoid-based pesticides gain share as EU Green Deal restrictions tighten on synthetic alternatives.
Flavors and fragrances dominate volume throughput; pharmaceuticals expand most quickly.
Extraction Method:
Technology selection hinges on residual solvent thresholds, with supercritical CO2 commanding premiums for pharmaceutical and infant-grade cosmetic applications.
- Supercritical CO2:This method unifies purification and solvent removal into single-unit operations, eliminating hexane or ethanol traces. Japanese nutraceutical contract manufacturers and European fragrance houses now specify CO2-derived terpenes exclusively for premium positioning.
- Steam Distillation:Conventional thermal separation remains cost-competitive for commodity-grade outputs where residual solvent limits are less stringent. Operations in Brazil's citrus belt leverage this method for high-volume limonene production.
- Solvent Extraction:Hexane and ethanol methods face displacement as cosmetic manufacturers impose detectable-limit thresholds.
- Cold Pressing:Mechanical expression preserves heat-sensitive aromatic compounds for top-grade citrus oils.
- Molecular Distillation:High-vacuum fractional separation achieves pharmaceutical-grade purity for specialized API applications.
Steam distillation retains volume leadership; supercritical CO2 gains share fastest.
End User Industry:
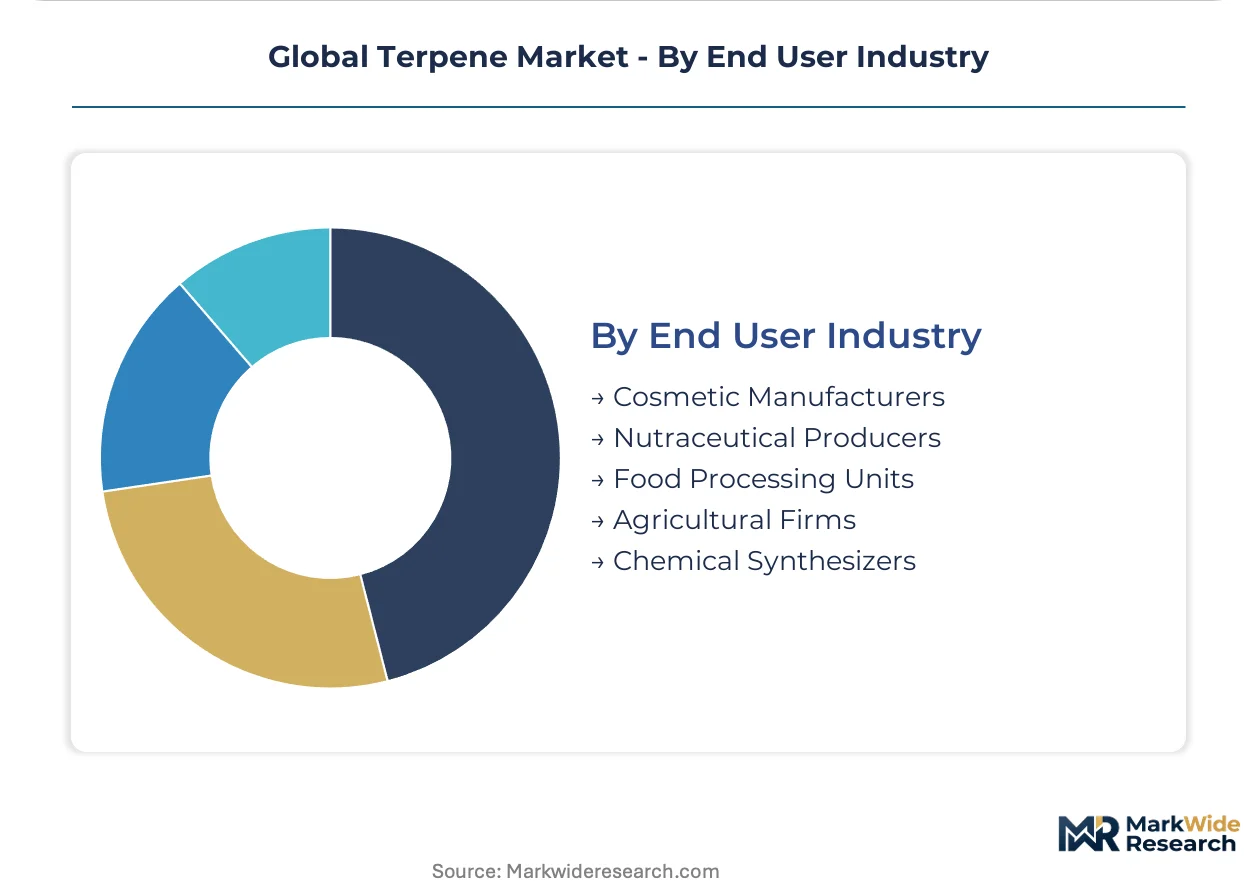
Customer procurement patterns diverge between multinational brands demanding supply chain transparency and industrial buyers prioritizing unit economics.
- Cosmetic Manufacturers:EU CSRD disclosure requirements and Green Deal sustainability reporting favor botanical inputs with documented provenance. Prestige skincare brands market supply chain transparency as a competitive attribute.
- Nutraceutical Producers:Japanese and North American contract manufacturers specify supercritical CO2 extraction to meet residual solvent thresholds below detectable limits.
- Food Processing Units:Flavor compounders source monoterpenes for citrus-based formulations under FSSAI and FDA oversight.
- Agricultural Firms:Natural pesticide formulators seek terpenoid alternatives to restricted synthetic chemistries.
- Chemical Synthesizers:Industrial cleaning and degreasing operations substitute d-limonene for fluorinated solvents under Europe's F-Gas Regulation phase-down.
Cosmetic manufacturers lead on specification intensity; nutraceutical producers lead on growth trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Process engineering talent concentrates in Germany, Switzerland, and select US research universities, anchoring supercritical CO2 extraction system design. This technical specialization shapes where premium-grade terpene purification capacity locates.
United States
Florida citrus groves supply limonene feedstock despite greening disease pressure, while California cosmetic brands demand traceable botanical inputs. EPA environmental release standards govern industrial terpene solvent applications. Houston hosts chemical engineering firms deploying high-pressure extraction systems for pharmaceutical-grade outputs.
Brazil
São Paulo state's orange processing belt scales cold-pressed peel oil extraction for fragrance house offtake agreements. ANVISA pharmaceutical standards elevate purity documentation requirements for exported terpenes. Campinas clusters citrus cooperatives integrating directly with multinational flavor compounders.
Germany
EMA pharmaceutical guidelines and ECHA REACH enforcement bifurcate terpene supply into certified and commodity channels. Ludwigshafen and Leverkusen host chemical conglomerates with captive steam distillation and molecular distillation capabilities. Border inspections in Hamburg and Rotterdam intensify compliance verification.
India
CDSCO pharmaceutical excipient standards and BIS certification requirements formalize previously informal terpene supply chains. Mumbai and Gujarat house flavor compounders sourcing monoterpenes for domestic FSSAI-regulated food applications. Hyderabad pharmaceutical formulators absorb high-purity terpenes as API solubilizing agents.
Japan
METI industrial standards and PMDA pharmaceutical regulations mandate residual solvent thresholds below detectable limits for nutraceutical applications. Osaka contract manufacturers specify supercritical CO2-derived terpenes exclusively. Kobe hosts precision extraction equipment fabricators serving domestic cosmetic and nutraceutical producers.
Global Terpene Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across fragmented supply tiers. The vendor base spans multinational fragrance houses with captive citrus assets, regional extraction cooperatives, and biotechnology startups deploying microbial fermentation. Three archetypes dominate: vertically integrated flavor/fragrance conglomerates controlling raw material continuity; specialized botanical extractors serving pharmaceutical and cosmetic certification channels; and synthetic biology firms bypassing agricultural constraints. Competitive moves concentrate on backward integration into citrus processing assets and supercritical CO2 capacity expansion.
Among diversified fragrance and flavor conglomerates, International Flavors & Fragrances, Givaudan, and Firmenich occupy positions defined by raw material control strategies. International Flavors & Fragrances exemplifies the citrus-belt integration archetype through Spanish and Brazilian captive processing assets. Givaudan represents the proprietary botanical sourcing model commanding formulation premiums. Firmenich anchors the biotechnology-derived segment, bypassing agricultural yield volatility through microbial production platforms.
| Leading Market Players |
|---|
| International Flavors & Fragrances |
| Privi Organics |
| Firmenich |
| Florachem Corporation |
| Sensient Technologies |
| Givaudan |
| Vigon International |
| Flotek Industries |
| Symrise |
| Others |
Supply & Pricing Matrix
Supercritical CO2 extraction adoption simultaneously compresses production costs for pharmaceutical-grade outputs and concentrates premium supply among German, Swiss, and Japanese engineering clusters with scarce high-pressure system expertise. This technological transition bifurcates terpene markets into commodity steam-distillation channels and certified CO2-derived tiers where residual solvent documentation commands formulation premiums from fragrance houses and nutraceutical contract manufacturers.
Pricing Analysis
Certification-bundled pricing separates REACH-compliant pharmaceutical grades from unbundled commodity citrus terpenes sold through spot markets. Price differentiation rests on documented purity thresholds and supercritical CO2 processing premiums versus conventional steam distillation. Cost compression in mid-scale fractional distillation operations is intensifying because pharmaceutical formulators now mandate detectable-limit residual solvent certificates. Industrial cleaning buyers exhibit highest price sensitivity, while cosmetic manufacturers absorbing CSRD disclosure requirements show lowest sensitivity for traceable botanical provenance.
Supply Chain Analysis
Limonene feedstock draws from Brazil's São Paulo citrus belt, Florida's disease-pressured groves, and Spanish Mediterranean cooperatives integrated with European fragrance houses. Raw material dependencies center on orange peel oil supply, supercritical CO2 equipment fabrication, and molecular distillation catalysts. Single-source vulnerability concentrates in Brazilian orange processing during seasonal harvest windows. Distribution runs through direct multi-year offtake agreements displacing traditional merchant traders, enabling lot-level traceability for clean beauty certifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where REACH compliance costs in Europe exceed BIS certification investments in India, creating margin expansion opportunities for suppliers relocating purification capacity to formalizing Asian markets.
For Market Incumbents: Deepen backward integration into Brazilian citrus processing assets to secure raw material continuity against agricultural yield volatility from Florida greening disease. Fortify supercritical CO2 engineering capabilities in Germany and Switzerland to defend against biotechnology-derived terpene substitution from microbial fermentation platforms. Prioritize CDSCO and EMA dual-certification investments to capture pharmaceutical excipient demand expansion.
For New Entrants and Emerging Players: Microbial fermentation platforms for rare sesquiterpenes unavailable from conventional extraction offer a technology-first wedge into pharmaceutical synthesis markets. Target India's formalizing flavor and pharmaceutical supply chains where BIS certification creates first-mover advantages against informal incumbent networks. Pursue white-label supercritical CO2 toll processing contracts for Japanese nutraceutical manufacturers demanding exclusive CO2-derived specifications.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional extraction cooperatives in Brazil and India lacking certification infrastructure but holding captive citrus assets. Long-term viability hinges on regulatory divergence between REACH-tier European markets and formalizing Asian pharmaceutical standards. Watch biotechnology scale-up milestones as the inflection signal for agricultural-terpene demand displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Citrus Processing | Secures limonene feedstock continuity for fragrance houses against Florida supply volatility. |
| Supercritical CO2 Capacity Expansion | Captures pharmaceutical-grade premiums from EMA and CDSCO certified demand channels. |
| Biotechnology-Derived Terpene Scale-Up | Bypasses agricultural yield constraints for rare sesquiterpenes like bisabolol and caryophyllene. |
| Dual Certification Investment | Enables cross-border shipment into both REACH-regulated Europe and BIS-formalizing India. |
| Direct Sourcing Contract Structuring | Eliminates intermediary traders while satisfying EU CSRD supply chain transparency mandates. |
Research Methodology
Bottom-up extraction capacity modeling reconciled against top-down end-use demand tracking forms the analytical core of this study. Primary interviews with citrus cooperative managers, supercritical CO2 equipment fabricators, fragrance house procurement directors, pharmaceutical formulators, and Indian flavor compounders combined with secondary validation from ECHA REACH registration databases, ANVISA export filings, FSSAI flavor standard notifications, and customs trade flow records. Triangulation across supply-side installation capacity and demand-side offtake agreements ensures volume reconciliation.
Historical trendline analysis of citrus processing capacity expansion, supercritical CO2 system deployments, and regulatory certification timelines informed projection parameters across the analysis window. Segmentation modeling incorporated molecular class, extraction method, application vertical, and geographic regulatory cluster dimensions. CAGRs derived from fitted growth curves adjusted for agricultural yield volatility patterns and biotechnology substitution thresholds. Forecast inputs included citrus greening disease progression rates and F-Gas Regulation phase-down implementation pacing.
The model holds under stable regulatory divergence between REACH-tier and emerging-market certification regimes; deviation in biotechnology scale-up economics or synchronized citrus disease outbreaks would shift supply-side assumptions. Forecasts reflect documented stakeholder input and disclosed regulatory frameworks. A small set of named triggers warrants ongoing watch: microbial fermentation cost parity milestones, Brazilian citrus belt climate stress indicators, and ECHA SVHC list expansion pacing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavor and Fragrance Chemicals
Musk Aroma Chemicals Market
Flavor and Fragrance Chemicals
Fragrance Fixatives Market
Flavor and Fragrance Chemicals
Fragrance Ingredients Market
Flavor and Fragrance Chemicals
Coumarin Market
Flavor and Fragrance Chemicals
Global Natural Cinnamic Aldehyde Market
Flavor and Fragrance Chemicals
Essential Oil Blends Market
Flavor and Fragrance Chemicals
Phenethyl Alcohol Market
Flavor and Fragrance Chemicals
Estragole Market
Flavor and Fragrance Chemicals
Anethole Market
Flavor and Fragrance Chemicals
Ferulic Acid Market
Flavor and Fragrance Chemicals
Hydroxycitronellal Market
Flavor and Fragrance Chemicals
Scent Eliminators Market
Flavor and Fragrance Chemicals
Massoia Bark Essential Oil Market
Flavor and Fragrance Chemicals
Tannic Acid Market
Flavor and Fragrance Chemicals
4-Allylanisole Market
Flavor and Fragrance Chemicals
Cedrol Methyl Ether Market