
 Soil-Release Functional Polymers for Performance Apparel Care Market | 2026-2036
Soil-Release Functional Polymers for Performance Apparel Care Market Size, Share, and Industry Trends Forecast 2026-2036
Soil-Release Functional Polymers for Performance Apparel Care Market Insights
The end-use vertical mix is broadening beyond traditional sportswear into military uniform suppliers and workwear brands. Dow leverages its silicone-based polymer expertise to anchor supply relationships with outdoor gear producers. BASF sustains R&D intensity in polyester-based soil-release chemistries for high-durability applications. Lubrizol competes through specialized emulsion formulations that target liquid concentrate channels.
Soil-release functional polymers are macromolecular compounds engineered with hydrophilic and hydrophobic segments that enable particulate and oily soil detachment from synthetic and blended fabrics during aqueous washing, typically requiring active polymer content between 15-40% in finished formulations. Polyester-based variants dominate current volume due to compatibility with PET and nylon substrates, while silicone-based grades capture premium margin pools in water-repellent dual-function finishes. Block copolymers lead structural innovation for low-temperature wash effectiveness, and textile finishing applications represent the fastest-growing demand channel as brands bring soil-release treatment in-house rather than relying on detergent additives.
EPA oversight of per- and polyfluoroalkyl substances in the United States is accelerating reformulation timelines away from fluorinated soil-release chemistries, while REACH restrictions in Europe mandate full substance disclosure across textile auxiliary supply chains. China's MEE enforces wastewater discharge standards that favor biodegradable polymer architectures in Yangtze River basin manufacturing zones. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded formulation investments.
Market Dynamics
REACH compliance in Europe is forcing full substance disclosure across textile auxiliary supply chains, compelling reformulation investments that reshape competitive positioning among polymer suppliers serving performance apparel finishers.
Growth Catalysts
- EPA PFAS restrictions:Accelerated phase-out timelines for fluorinated soil-release chemistries in the United States are pulling demand toward silicone-based and polyester-based polymer alternatives.
- Technical sportswear expansion:Marathon and trail-running apparel brands are specifying soil-release finishes as standard for nylon-polyester blended base layers.
- Block copolymer innovation:Low-temperature wash effectiveness is unlocking adoption in cold-water detergent systems across Nordic household markets.
Market Restraints
- Petrochemical feedstock volatility:Ethylene oxide and propylene oxide price swings compress margin stability for polyester-based polymer producers.
- Specialized emulsion capacity concentration:Liquid concentrate formulation expertise clusters with a limited supplier base in Germany's Rhine-Ruhr chemical corridor.
- Biodegradability-performance tradeoff:MEE wastewater standards in China's Yangtze River basin constrain molecular architecture options for high-durability finishes.
Strategic Opportunities
- Military uniform technical specifications:NATO-member defense procurement standards are mandating soil-release performance for synthetic combat textiles.
- Dual-function finish convergence:Water-repellent and soil-release polymer combinations are capturing premium positioning in alpine outerwear.
- In-house finishing migration:Textile brands are bringing soil-release treatment captive rather than sourcing through detergent additive channels.
Industry Challenges
- Formulation-to-fabric compatibility testing:Each substrate blend requires validated polymer adhesion protocols, extending qualification timelines.
- Cross-jurisdiction substance notification:Divergent chemical inventory requirements between EPA TSCA and REACH create compliance fragmentation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soil-Release Functional Polymers for Performance Apparel Care Market |
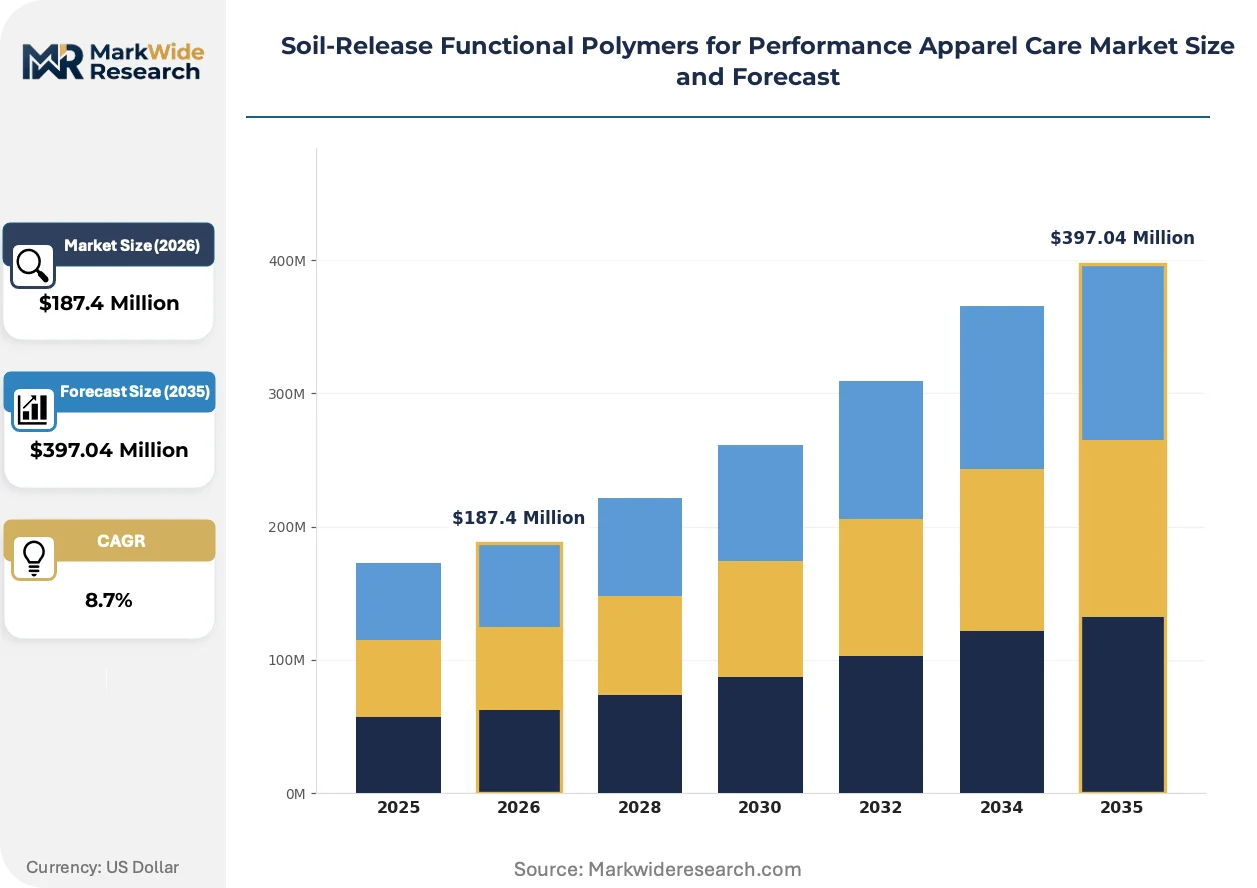
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Block Copolymers, Graft Copolymers, Polyester-Based, Polyether-Based, Silicone-Based Application: Laundry Detergents, Fabric Softeners, Textile Finishing, Stain Repellents, Water Repellents End User: Sportswear Manufacturers, Outdoor Gear Producers, Military Uniform Suppliers, Workwear Brands, Casual Wear Labels Form: Powder, Liquid Concentrate, Emulsion, Granules, Dispersion |
| Companies Covered | Dow, BASF, Lubrizol, Archroma, Clariant, Solvay, Evonik Industries, Wacker Chemie, Croda International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soil-Release Functional Polymers for Performance Apparel Care Market Trends and Innovations
Polymer architecture innovation is compressing wash-temperature requirements while regulatory chemistry bans are accelerating fluorinated compound substitution. These forces are reshaping supplier R&D allocation and buyer specification patterns simultaneously.
Block copolymer structures with segmented hydrophilic-hydrophobic domains are overtaking random copolymer architectures for soil-release efficacy. Marathon apparel brands in Japan and Germany are specifying these grades for cold-water wash compatibility. The technology is overtaking legacy polyester-polyether formulations in premium technical fabric finishing.
REACH restrictions on per- and polyfluoroalkyl substances are tightening substance disclosure thresholds for textile auxiliaries across European supply chains. Finishers must now document full polymer composition down to 0.1% weight concentration. Polyester-based and silicone-based alternatives are capturing specification share in outdoor gear and workwear segments.
Brand procurement teams are consolidating soil-release finish sourcing through direct mill relationships rather than detergent additive suppliers. This disintermediation is visible in China where domestic performance apparel brands are qualifying polymer suppliers directly. Technical textile mills are capturing margin previously held by consumer product channels.
Soil-Release Functional Polymers for Performance Apparel Care Market Segmentation
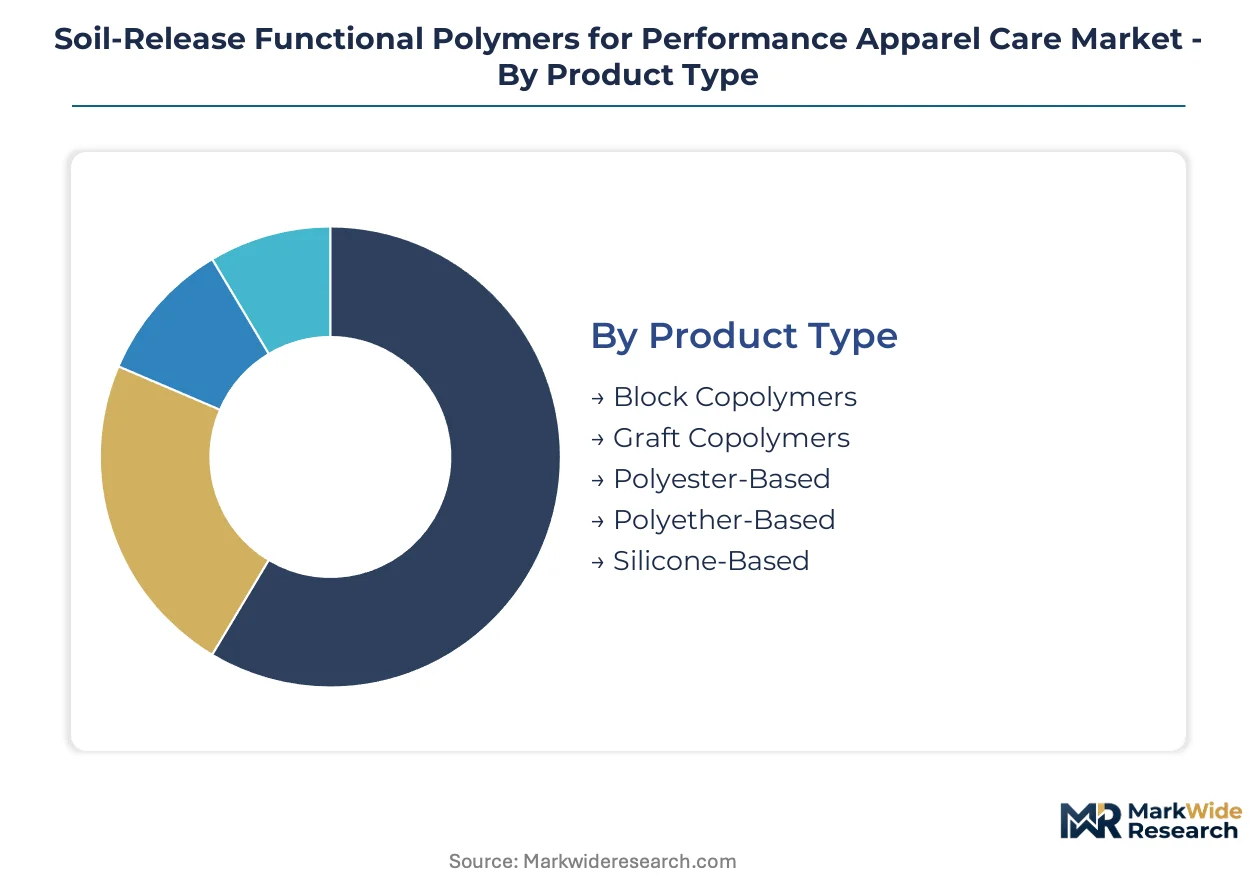
Polymer architecture, application method, and end-use specifications create distinct value pools in performance apparel care. Each segmentation axis carries specific technical requirements that reshape supplier R&D allocation and buyer qualification protocols.
Product Type:
Block copolymer structures with segmented hydrophilic-hydrophobic domains are overtaking legacy architectures for soil-release efficacy.
- Block Copolymers:Engineered with discrete hydrophilic and hydrophobic segments that enable particulate detachment at reduced wash temperatures. Marathon apparel brands in Japan and Germany specify these grades for cold-water compatibility, pulling specification share from polyester-polyether formulations in premium technical fabric finishing.
- Silicone-Based:Leverage polysiloxane backbones for dual-function water-repellent and soil-release performance. Outdoor gear producers in the United States and alpine markets capture premium positioning through these chemistries, though EPA PFAS oversight accelerates reformulation timelines for fluorinated alternatives.
- Graft Copolymers:Side-chain architectures grafted onto polyester or polyether backbones for substrate-specific adhesion.
- Polyester-Based:Dominant volume category compatible with PET and nylon substrates across standard wash cycles.
- Polyether-Based:Hydrophilic polyether segments enhance aqueous dispersibility in liquid concentrate formulations.
Polyester-based variants lead on manufacturing scale; silicone-based grades lead on margin expansion.
Application:
Channel selection determines polymer concentration requirements and qualification complexity for suppliers.
- Textile Finishing:Direct application to fabric during mill processing requires 15-40% active polymer content in finished formulations. Domestic performance apparel brands in China are bringing this capability captive, disintermediating detergent additive channels and reshaping margin distribution across the supply chain.
- Laundry Detergents:Consumer-facing formulations with lower active polymer loads delivered through wash-cycle dosing. Nordic household markets are specifying block copolymer grades for cold-water detergent systems, compressing wash-temperature requirements.
- Fabric Softeners:Combined softening and soil-release delivery through rinse-cycle deposition.
- Stain Repellents:Preventive surface treatments applied pre-soiling for hospitality and institutional textiles.
- Water Repellents:Dual-function finishes converging soil-release and hydrophobic performance in alpine outerwear.
Textile finishing expands most quickly as brands in-source treatment capacity; laundry detergents retain volume concentration through established consumer channels.
End User:
Procurement specifications vary sharply across durability requirements and regulatory exposure profiles.
- Sportswear Manufacturers:Technical base layer producers specify soil-release finishes as standard for nylon-polyester blends in marathon and trail-running apparel. REACH substance disclosure mandates are tightening qualification documentation across European supply relationships.
- Military Uniform Suppliers:NATO-member defense procurement standards now mandate soil-release performance for synthetic combat textiles, creating specification pull-through for high-durability polyester-based chemistries.
- Outdoor Gear Producers:Alpine and expedition equipment brands prioritize dual-function water-repellent and soil-release combinations.
- Workwear Brands:Industrial and service sector uniforms requiring frequent washing cycles with maintained performance.
- Casual Wear Labels:Mass-market apparel with soil-release as secondary feature to cost optimization.
Sportswear manufacturers lead on specification intensity; military uniform suppliers lead on contract durability.
Form:
Physical delivery state constrains formulation expertise and geographic supply concentration.
- Liquid Concentrate:Specialized emulsion formulations requiring technical expertise clustered in Germany's Rhine-Ruhr chemical corridor. Lubrizol competes through dedicated capacity serving textile mill direct channels with validated dispersion stability.
- Emulsion:Aqueous polymer dispersions for in-line textile finishing equipment with controlled particle size distribution.
- Powder:Dried formulations for detergent compounding and regional distribution efficiency.
- Granules:Free-flowing solid forms for automated dosing in industrial laundry operations.
- Dispersion:Stabilized polymer particles in continuous phase for specialized coating applications.
Liquid concentrate commands premium positioning through formulation complexity; powder leads on logistics scalability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr chemical corridor anchors polymer formulation expertise for soil-release functional polymers, with specialized emulsion capacity concentrating among German suppliers serving textile finishing channels across European performance apparel supply chains.
United States
EPA PFAS restrictions are accelerating reformulation timelines away from fluorinated soil-release chemistries toward silicone-based alternatives. Outdoor gear producers in the Pacific Northwest and alpine apparel brands specify dual-function water-repellent and soil-release finishes. Technical textile mills in North Carolina's manufacturing belt are bringing finishing capacity captive to disintermediate detergent additive channels.
Germany
REACH substance disclosure mandates now require full polymer composition documentation down to 0.1% weight concentration for textile auxiliaries. Marathon and trail-running apparel brands in Bavaria and Baden-Württemberg specify block copolymer grades for cold-water wash compatibility. The Rhine-Ruhr corridor maintains concentrated liquid concentrate formulation expertise serving mill-direct supply relationships.
China
Domestic performance apparel brands are expanding technical textile sourcing and qualifying polymer suppliers directly rather than through consumer product channels. MEE wastewater discharge standards in the Yangtze River basin favor biodegradable polymer architectures for high-durability finishes. Manufacturing zones in Jiangsu and Zhejiang provinces are capturing soil-release finish volume as brands in-source treatment capacity.
Japan
METI guidance on sustainable chemistry is shaping procurement specifications for sportswear manufacturers specifying soil-release performance. Marathon apparel brands in the Kanto region around Tokyo are adopting block copolymer structures for cold-water detergent system compatibility. Technical textile producers in Osaka's Kansai manufacturing cluster are validating polymer adhesion protocols for nylon-polyester blended base layers.
Soil-Release Functional Polymers for Performance Apparel Care Market Competitive Landscape
Reformulation investment dominates the current landscape as suppliers redirect R&D allocation away from fluorinated chemistries toward silicone-based and polyester-based alternatives. The supplier base concentrates among diversified chemical conglomerates with polymer architecture expertise and specialized emulsion formulators serving textile mill channels. Three archetypes define positioning: petrochemical majors leveraging feedstock integration, silicone specialists capturing premium dual-function finishes, and emulsion technology providers targeting liquid concentrate delivery. Portfolio diversification and geographic expansion represent the dominant competitive moves as suppliers qualify polymer compositions across divergent regulatory jurisdictions.
Among diversified chemical conglomerates, Dow, BASF, and Lubrizol occupy positions spanning silicone-based, polyester-based, and specialized emulsion formulation expertise respectively. These companies exemplify the tier of suppliers anchoring supply relationships with outdoor gear producers and technical sportswear manufacturers through validated polymer adhesion protocols and dispersion stability credentials. Their geographic footprints span the United States, Germany, and the specialized chemical corridor concentration serving mill-direct channels.
| Leading Market Players |
|---|
| Dow |
| BASF |
| Lubrizol |
| Archroma |
| Clariant |
| Solvay |
| Evonik Industries |
| Wacker Chemie |
| Croda International |
| Others |
Pricing and Supply Chain Analysis
EPA PFAS restrictions gate qualified supply for fluorinated soil-release chemistries and simultaneously compress premium-tier pricing access for legacy formulations. Buyers now face bifurcated sourcing economics where REACH-compliant silicone-based alternatives command sustained margin premiums while reformulation costs transmit downstream through textile finishing channels.
Pricing Analysis
Distributor margin layers in textile finishing channels absorb 15-25 point spreads between liquid concentrate formulators and mill-direct buyers. Pricing stratifies across premium, standard, and economy tiers based on polymer architecture complexity and REACH substance disclosure certification. Cost compression in polyester-based grades intensifies because ethylene oxide feedstock volatility transmits directly into formulation economics. Large-volume sportswear manufacturers exhibit lowest price sensitivity due to specification lock-in, while casual wear labels optimize aggressively on per-kilogram polymer costs.
Supply Chain Analysis
REACH substance disclosure certification gates supplier qualification for European textile finishing channels and fragments viable sourcing pools. Manufacturing concentration centers on Germany, China, and the United States, with specialized emulsion expertise clustering in the Rhine-Ruhr corridor. Feedstock supply draws from ethylene oxide and propylene oxide producers tethered to regional petrochemical complexes. Single-source vulnerability concentrates in liquid concentrate dispersion technology held by limited German formulators. Distribution runs through textile mill direct channels and detergent additive distributors serving consumer-facing brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Soil-release functional polymers constitute a stable compounder anchored by regulatory-mandated reformulation cycles that perpetually refresh demand for compliant chemistries. Technical sportswear expansion and military specification mandates provide durable volume foundations.
For Market Incumbents: Deploy backward integration into ethylene oxide feedstock to buffer margin compression from petrochemical volatility. BASF and Dow should accelerate block copolymer R&D allocation for cold-water wash specifications while defending European supply relationships through REACH documentation investments. EPA PFAS phase-out timelines threaten stranded capacity in fluorinated chemistries; incumbents must redirect technical service resources toward silicone-based qualification protocols. For New Entrants and Emerging Players: Enter via biodegradable polymer architectures targeting China's Yangtze River basin manufacturing zones where MEE wastewater standards create specification whitespace. Military uniform suppliers present the most penetrable end-use segment given NATO procurement standardization and limited incumbent focus on durability testing protocols. A direct mill qualification approach bypasses detergent additive channel concentration. For Investors and Strategic Acquirers: Roll-up economics work for specialized emulsion formulators because liquid concentrate expertise concentrates geographically and commands sustained premium multiples. The 5-10 year viability window favors suppliers with validated dispersion stability credentials and REACH-compliant polymer portfolios. Watch EPA enforcement intensity on PFAS import notifications as the inflection signal for accelerated silicone-based substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Oxide | Secures margin stability against Rhine-Ruhr feedstock price volatility for polyester-based polymer producers. |
| Block Copolymer Cold-Water Formulation | Captures Nordic detergent system specifications and Japanese marathon apparel brand procurement. |
| REACH Substance Disclosure Investment | Preserves European textile finishing channel access as ECHA tightens auxiliary documentation thresholds. |
| Biodegradable Polymer Architecture Development | Qualifies suppliers for China's Yangtze River basin manufacturing zones under MEE wastewater standards. |
| Direct Mill Relationship Consolidation | Disintermediates detergent additive distributors and captures margin from Chinese performance apparel brands. |
Research Methodology
Bottom-up textile finishing and laundry detergent modeling reconciled against top-down polymer supplier capacity tracking forms the analytical core of this study. Primary interviews with technical R&D directors at textile auxiliaries producers, procurement leads at sportswear manufacturers, plant managers at emulsion formulation facilities, and regulatory affairs specialists at chemical conglomerates were combined with secondary validation. Data sources include ECHA REACH registration dossiers, EPA TSCA chemical inventory filings, Chinese customs trade statistics for textile auxiliary imports, and SEC 10-K disclosures from diversified chemical majors. Triangulation between demand-side qualification timelines and supply-side capacity announcements ensures volume reconciliation.
Input-output matrices map polymer architecture types to end-use specifications across the projection horizon. Segmentation dimensions encompass product type, application method, end-user industry, and physical form state. CAGRs were derived from regression analysis of historical adoption curves adjusted for regulatory phase-out accelerants. Forecast inputs incorporate REACH substance disclosure compliance costs, EPA PFAS enforcement trajectory, and MEE wastewater standard implementation pace in Chinese manufacturing zones.
Inputs from ECHA registration databases and EPA enforcement announcements were available through the study window; gaps in real-time textile mill inventory data introduce uncertainty bands around quarterly volume estimates. Forecasts reflect documented assumptions regarding reformulation timeline adherence and military procurement specification adoption. A model refresh is warranted upon material change in EPA PFAS import notification enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polyolefin Compound Market
Polymers & Resins
Polyether Polyols Market
Polymers & Resins
Acrylic Styrene Acrylonitrile Resin Market
Polymers & Resins
Polyethylene Terephthalate (PET) Compounding Market
Polymers & Resins
Global VAE Emulsion Market
Polymers & Resins
Polymer Memory Market
Polymers & Resins
Ethylene Copolymer Market
Polymers & Resins
Polysorbate Market
Polymers & Resins
Polyacrylate Market
Polymers & Resins
Biobased Thermosetting Polymers Market
Polymers & Resins
Polysiloxane Market
Polymers & Resins
Polymer Foam Market
Polymers & Resins
North America Flame Retardant Thermoplastics Market
Polymers & Resins
Polyamide Resins Market
Polymers & Resins
Global Encapsulation Resins Market
Polymers & Resins
Polybenzoxazine Resins Market