
 Global Alkyd Resin Market | 2026-2036
Global Alkyd Resin Market Size, Share, and Industry Trends Forecast 2026-2036
Global Alkyd Resin Market Foresight
Capital-intensity divergence between integrated polyol producers and standalone resin compounders is rotating competitive advantage toward backward-linked operations. DSM leverages captive pentaerythritol supply to sustain margin stability across European coating accounts. Dow anchors North American volume through direct pipeline connections to phthalic anhydride and soybean oil feedstocks. Arkema SA differentiates via specialty modified alkyd grades targeting automotive OEM clearcoat specifications.
Alkyd resin denotes a polyester thermosetting resin produced through polycondensation of polyhydric alcohols with polybasic acids and fatty acid-modified drying oils, typically exhibiting oil lengths from 40% to 70% that govern air-dry characteristics and solvent resistance. These resins serve primarily as film-forming binders in protective and decorative coatings where gloss retention, adhesion, and weatherability prove critical. Long oil alkyds retain dominance in architectural trim and DIY applications where brushability and flow under ambient cure matter most, while high-performance and modified alkyds capture expanding share in industrial maintenance and transportation equipment where thermal and chemical resistance specifications tighten. Marine coatings represent the fastest-growing application vector as shipbuilders in South Korea and Japan specify alkyd-epoxy hybrid systems for ballast tank protection.
EPA VOC regulations under 40 CFR Part 59 and REACH Annex XVII restrictions on hazardous substance content are forcing reformulation investments across coating supply chains, with ECHA substance evaluations now extending to cobalt-based drier alternatives. China's MEE enforcement of GB standards on industrial coating emissions is redirecting domestic alkyd production toward water-reducible and high-solids architectures. Stakeholders must monitor drier chemistry substitution timelines and bio-based feedstock certification schemes to secure formulation flexibility ahead of tightening chemical hazard classifications.
Market Dynamics
Reformulation mandates across three major jurisdictions are compressing solvent-borne alkyd volumes while accelerating water-reducible and high-solids platform development. The shift is redistributing margin pools toward compounders with captive polyol assets and drier chemistry substitution capabilities.
Growth Catalysts
- China's MEE enforcement of GB coating emission standards:Industrial maintenance demand in Shanghai and Guangdong is redirecting toward compliant alkyd-epoxy hybrid systems for corrosion protection.
- Marine coating specifications from South Korean shipbuilders:Ballast tank protection protocols are specifying long-oil alkyd primers with enhanced salt-spray resistance for new vessel construction.
- REACH Annex XVII hazardous substance restrictions:Cobalt drier substitution timelines are creating first-mover advantage for manganese- and iron-based catalyst suppliers.
Market Restraints
- Feedstock concentration in phthalic anhydride:Chinese and South Korean purified terephthalic acid producers dominate aromatic acid supply, exposing European compounders to freight and duty volatility.
- EPA 40 CFR Part 59 VOC limits:Architectural coating reformulation costs are compressing margins for standalone resin producers without backward-linked alcohol supply.
- Acrylic and polyurethane substitution:Waterborne acrylic dispersions are capturing exterior wood coating share from long-oil alkyds in North American DIY channels.
Strategic Opportunities
- Underpenetrated Brazilian industrial maintenance sector:ANVISA-aligned coating registrations for petrochemical infrastructure are opening specification windows for medium-oil alkyd primers.
- EU Green Deal bio-based feedstock mandates:Tall oil fatty acid and soybean oil certification schemes are creating premium tier positioning for renewable-content alkyds.
- Water-reducible alkyd dispersion technology:Self-emulsifying resin architectures are enabling direct substitution in spray-applied automotive refinish segments.
Industry Challenges
- Specialized polymer chemist scarcity:Formulation expertise in oxidative cure kinetics and surfactant stabilization is concentrating at integrated producers, constraining independent compounder R&D velocity.
- Reactor asset intensity:Batch condensation equipment for 40-70% oil length precision requires capital deployment that mid-scale operators struggle to justify.
- ECHA substance evaluation timelines:Pending harmonized classification for residual monomers is extending product registration cycles and freezing formulation changes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Alkyd Resin Market |
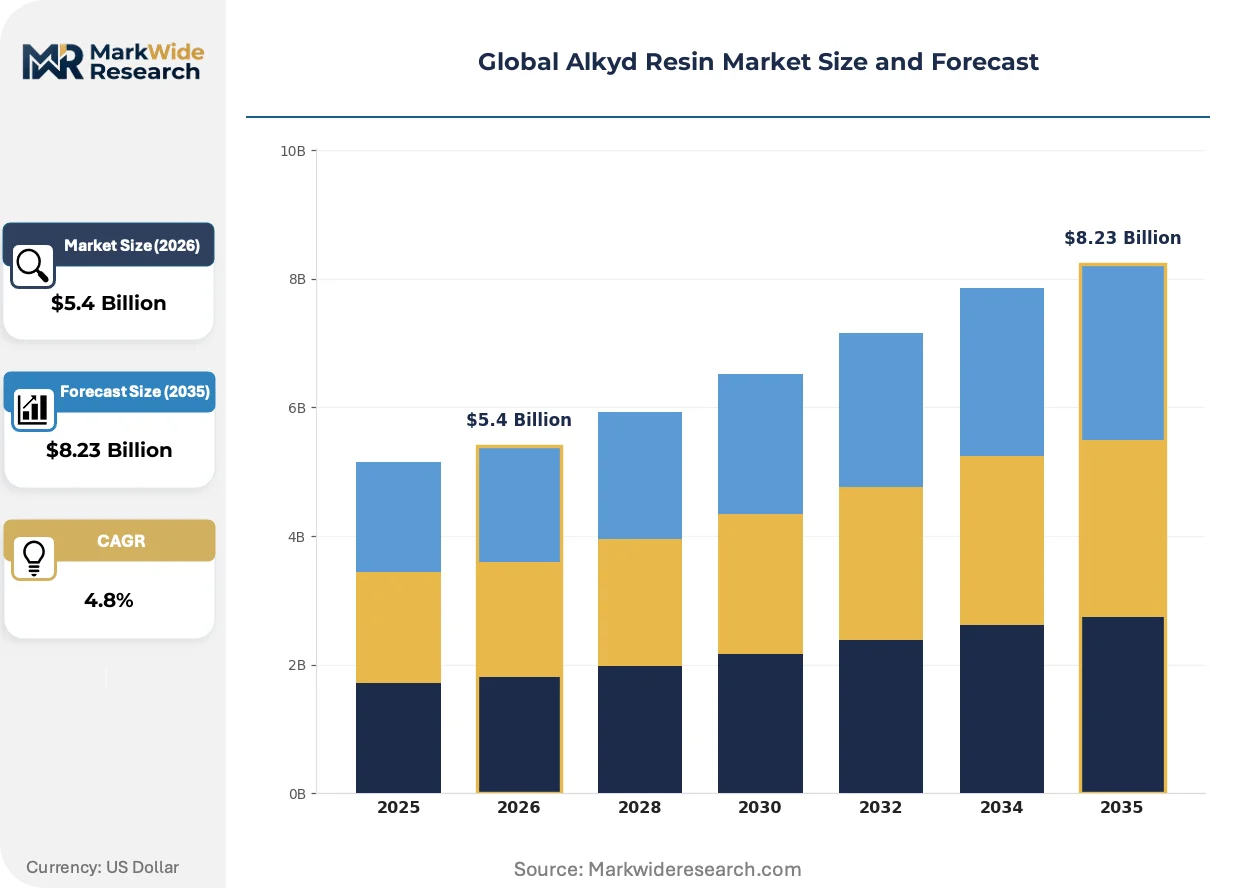
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $8.23 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
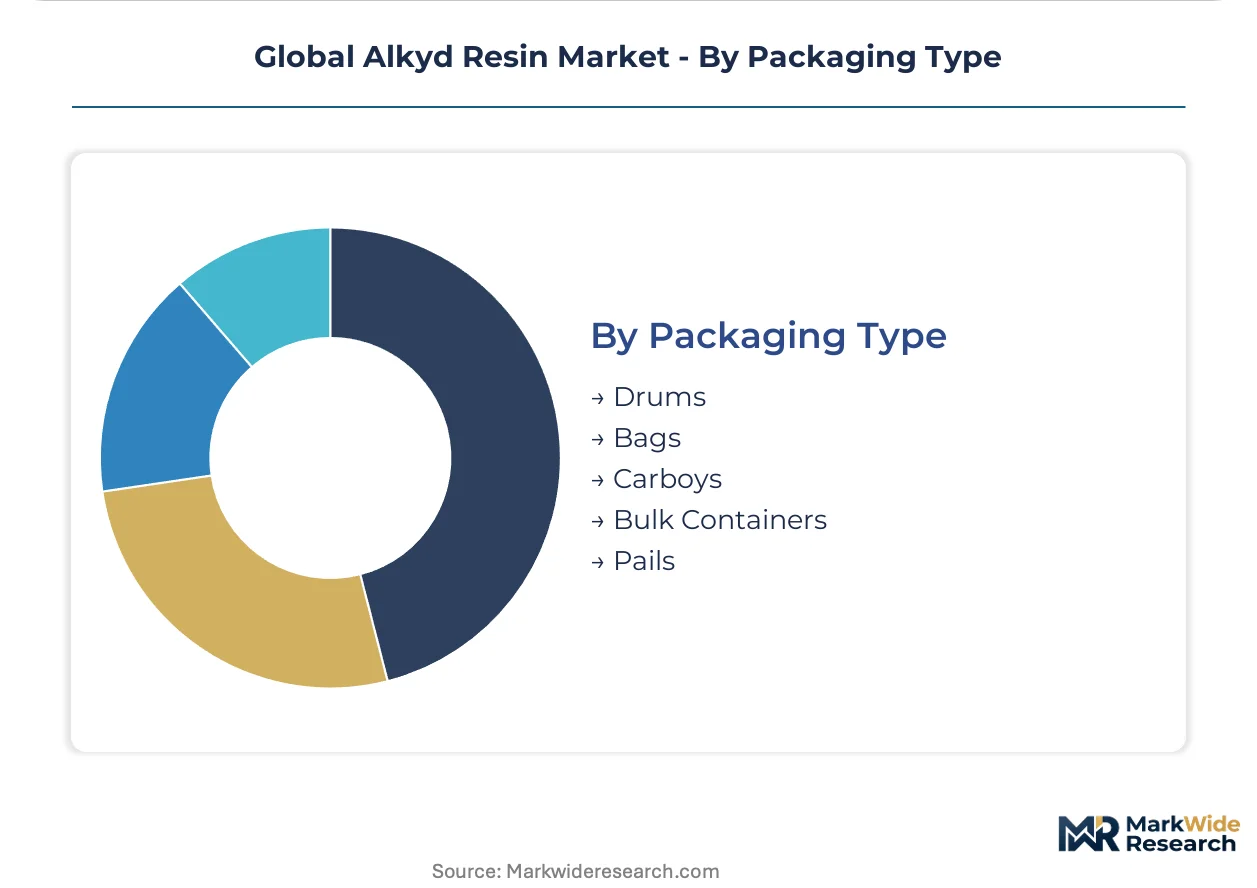
| Segmentation | Product Type: Short Oil Alkyd, Medium Oil Alkyd, Long Oil Alkyd, High-Performance Alkyd, Modified Alkyd Application: Architectural Coatings, Industrial Coatings, Automotive Coatings, Marine Coatings, Wood Finishings End User Industry: Manufacturing Plants, Shipbuilding, Furniture Production, Transportation Equipment, Construction Companies Packaging Type: Drums, Bags, Carboys, Bulk Containers, Pails |
| Companies Covered | Mancuso Chemicals Limited, DSM, Polynt Spa, Macro Polymers, Dow, Groupe Berkem, Cytech Solvay Group, Arkema SA, Nord Composites, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Alkyd Resin Market Shifts & Advancements
Alkyd resin technology is bifurcating between commodity architectural grades facing regulatory compression and specialty modified systems capturing industrial specification premiums. The innovation frontier centers on cure chemistry, bio-based feedstock integration, and application-method adaptation.
Water-reducible alkyd dispersion chemistry is decomposing the traditional solvent-borne application monopoly in industrial maintenance coatings. Japanese automotive refinish shops are adopting sprayable waterborne alkyds for primer-surfacer applications at accelerating rates. This technology is decomposing the volume advantage of conventional long-oil systems by enabling compliance with MEE and EPA emission limits without sacrificing film build.
REACH cobalt drier restrictions are forcing manganese complex and iron-based catalyst adoption across European coating supply chains. ECHA's 2023-2025 substance evaluation timeline is compressing reformulation windows for architectural and industrial maintenance producers. Decorative trim coating accounts in Germany and France are responding by qualifying calcium-zirconium drier blends with equivalent through-dry performance.
Shipyard procurement consolidation in South Korea and Japan is compressing supplier qualification cycles and unbundling technical service from resin supply contracts. Hyundai Heavy Industries and Imabari Shipbuilding are centralizing coating specification authority, displacing distributor-led technical consultation. This pattern is most visible in Ulsan and Marugame clusters where alkyd-epoxy hybrid system approvals now require direct compounder-shipbuilder technical agreements.
Global Alkyd Resin Market Segmentation
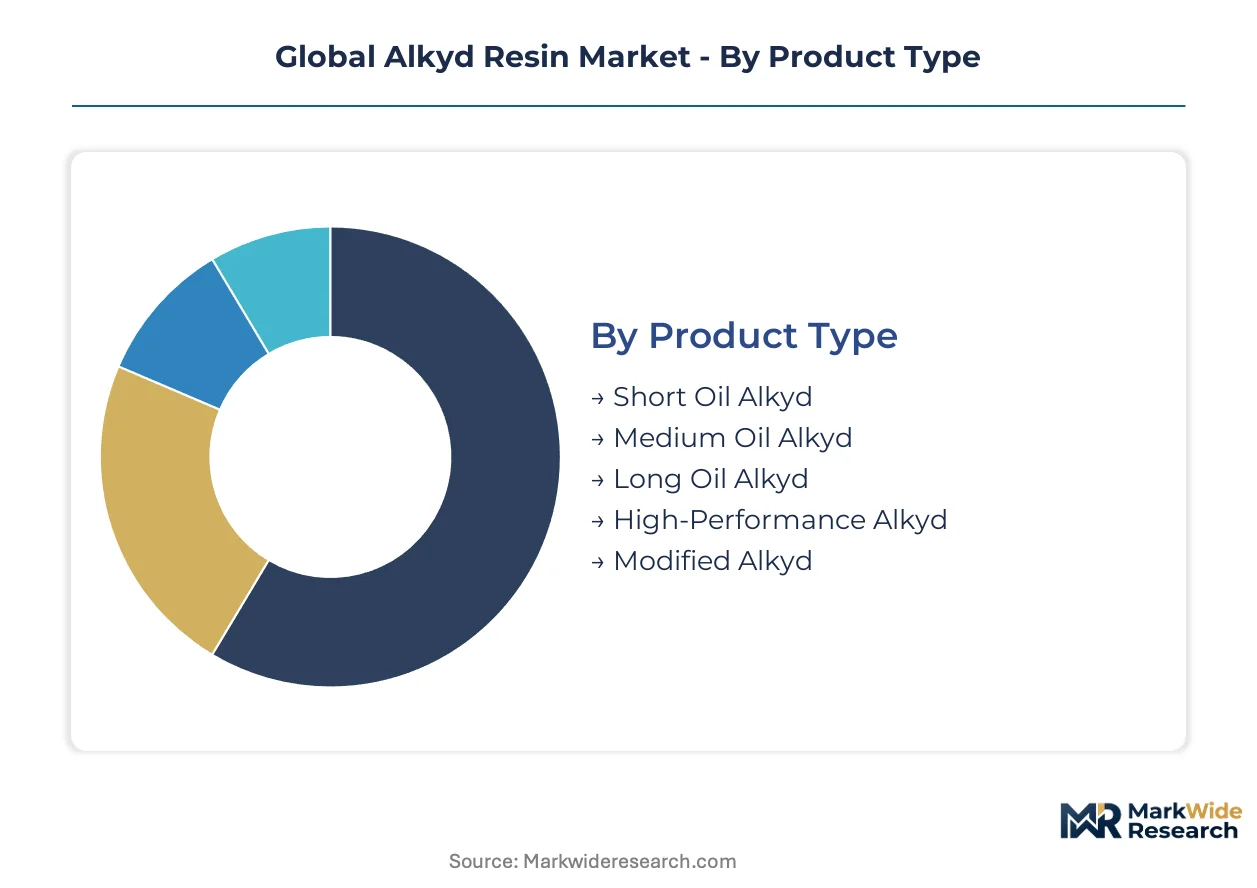
Alkyd resin segmentation reveals how formulation chemistry, application requirements, and supply chain economics intersect. Margin pools concentrate where regulatory compliance demands meet specialized performance specifications, particularly in industrial and marine coatings.
Product Type:
Margin stability clusters around oil length precision and modification chemistry, with premium capture in high-performance and specialty modified grades.
- Short Oil Alkyd:Formulated with 40% or less drying oil content, these resins deliver rapid hardness development and superior solvent resistance. Baking enamel demand from automotive OEM plants in Stuttgart and Detroit sustains volume, though thermal cure requirements limit ambient application flexibility.
- Long Oil Alkyd:Carrying 60-70% oil content, these systems dominate brush-applied architectural trim where flow and wet-edge retention matter. DIY channel concentration in North American home improvement retail chains absorbs the largest volume share, though waterborne acrylic substitution is compressing growth.
- Medium Oil Alkyd:Balanced 40-60% oil length serves industrial maintenance primers requiring compromise between dry speed and flexibility.
- High-Performance Alkyd:Silicone and fluorinated modifications target elevated temperature and chemical exposure specifications in petrochemical infrastructure.
- Modified Alkyd:Epoxy, polyurethane, and phenolic hybrids capture specification premiums where single-resin performance falls short.
Long Oil Alkyd holds installed capacity. High-Performance Alkyd is rotating up the share rankings.
Application:
Application segmentation tracks how cure environment and film performance requirements distribute volume across coating end-uses.
- Marine Coatings:Ballast tank protection specifications from Hyundai Heavy Industries and Imabari Shipbuilding are accelerating alkyd-epoxy hybrid adoption. Salt-spray resistance mandates in Ulsan and Marugame shipyards are expanding long-oil primer qualification cycles for direct compounder agreements.
- Industrial Coatings:Maintenance coatings for steel infrastructure in Shanghai and Rotterdam absorb medium-oil and high-solids formulations where MEE and REACH compliance tightens. Chemical resistance specifications in petrochemical clusters favor modified alkyd systems.
- Architectural Coatings:Decorative trim and exterior house paints retain solvent-borne long-oil dominance in price-sensitive segments.
- Automotive Coatings:Refinish primers and OEM baking enamels specify short-oil and high-performance grades for hardness and gloss retention.
- Wood Finishings:Exterior deck and furniture coatings face acrylic dispersion substitution in North American and European retail channels.
Industrial Coatings commands specification authority. Marine Coatings is gaining share fastest.
End User Industry:
Customer concentration patterns reveal where procurement consolidation and technical service bundling reshape supplier relationships.
- Shipbuilding:Centralized coating specification at South Korean and Japanese builders is displacing distributor-led technical consultation. Direct compounder-shipbuilder agreements in Ulsan and Nagasaki now govern alkyd-epoxy hybrid approvals for new vessel construction.
- Construction Companies:Infrastructure investment in Guangdong and Texas is scaling demand for compliant architectural and industrial maintenance systems.
- Manufacturing Plants:Steel fabrication and machinery production in the Ruhr and Michigan specify medium-oil primers for corrosion protection.
- Transportation Equipment:Railcar and commercial vehicle OEMs balance cost and performance with alkyd-urethane hybrid topcoats.
- Furniture Production:Mass-market wood coating in Vietnam and Poland faces waterborne system conversion pressure from retail sustainability mandates.
Construction Companies holds volume concentration. Shipbuilding is climbing the fastest.
Packaging Type:
Packaging economics reflect shipment scale, handling infrastructure, and customer formulation capabilities across the value chain.
- Bulk Containers:Integrated coating producers with captive alkyd production in Antwerp and Singapore receive multi-tonne tanker deliveries, minimizing packaging cost and handling labor.
- Drums:Standard 200-liter steel drums serve mid-scale compounders and independent coating manufacturers lacking bulk unloading infrastructure.
- Pails:Five-gallon and smaller pails target artisanal applicators and small-batch custom color matching in automotive refinish.
- Carboys:Glass and plastic carboys preserve moisture-sensitive modified alkyds for laboratory and specialty sampling quantities.
- Bags:Multi-layer paper and polymer bags contain solid resin flakes and pastilles for powder coating and hot-melt adhesive integration.
Bulk Containers holds throughput scale. Pails is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in alkyd resin trade reveal concentrated production in coastal chemical clusters and derivative demand in shipbuilding and construction hubs. China maintains net exporter status while European compounders absorb freight volatility on aromatic acid supply.
China
Domestic coating production expansion in Shanghai and Guangdong absorbs the largest volume share of alkyd resin output. MEE enforcement of GB industrial coating emission standards redirects formulation toward water-reducible architectures. The Yangtze River Delta cluster concentrates polyol production capacity serving both captive resin manufacturing and merchant market supply.
United States
Infrastructure investment in Texas and Gulf Coast petrochemical corridors sustains demand for industrial maintenance primers. EPA 40 CFR Part 59 VOC limits compress solvent-borne architectural coating margins and accelerate high-solids platform adoption. The Houston Ship Channel anchors phthalic anhydride supply integration with downstream alkyd compounding operations.
Germany
Automotive OEM baking enamel specifications from Stuttgart plants sustain short-oil alkyd demand for hardness-critical applications. REACH Annex XVII hazardous substance restrictions and ECHA cobalt drier evaluations compress reformulation timelines for decorative coating producers. The Ruhr industrial belt concentrates steel fabrication maintenance demand qualifying medium-oil primer systems.
South Korea
Hyundai Heavy Industries and DSME procurement consolidation in Ulsan drives alkyd-epoxy hybrid specification for ballast tank protection. KOSHA workplace chemical exposure guidelines align with MOL maritime safety mandates on coating hazard classification. The Busan-Ulsan shipbuilding corridor centralizes technical service relationships and displaces distributor-led consultation models.
Brazil
Petrochemical infrastructure expansion in São Paulo and Rio de Janeiro states opens specification windows for industrial maintenance coatings. ANVISA-aligned registration requirements for protective systems create compliance barriers favoring established compounders with regulatory affairs capability. The Santos port complex concentrates import logistics for aromatic acid feedstock supply to domestic resin producers.
Global Alkyd Resin Market Competitive Landscape
Concentration sits with integrated polyol producers possessing captive alcohol supply and backward-linked feedstock control. The vendor base separates into three strategic archetypes: petrochemical majors with aromatic acid integration, specialty chemical houses with modification chemistry expertise, and regional compounders serving price-sensitive architectural accounts. Competitive dynamics center on M&A activity consolidating reactor assets and strategic partnerships securing drier chemistry substitution capabilities ahead of regulatory deadlines.
Among European-based integrated producers, DSM and Arkema SA occupy positions reflecting distinct strategic postures. DSM exemplifies the backward-linked archetype through captive pentaerythritol supply sustaining margin stability across coating accounts. Arkema SA sits within the specialty modification tier targeting automotive OEM clearcoat specifications. Dow anchors North American volume through direct pipeline connections to phthalic anhydride and soybean oil feedstocks, representing the petrochemical major archetype with infrastructure-scale advantages.
| Leading Market Players |
|---|
| Mancuso Chemicals Limited |
| DSM |
| Polynt Spa |
| Macro Polymers |
| Dow |
| Groupe Berkem |
| Cytech Solvay Group |
| Arkema SA |
| Nord Composites |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between integrated polyol producers and shipbuilding clusters lock in both phthalic anhydride supply access and eighteen-month price visibility for alkyd resin compounders. These contracts insulate backward-linked producers from aromatic acid freight volatility while exposing standalone compounders to spot market swings.
Pricing Analysis
Industrial OEM buyers anchor contract structures around volume-commitment tiers with phthalic anhydride cost pass-through clauses. Three-tier pricing structure across premium, standard, and economy levels reflects oil length precision and modification chemistry, with silicone-modified grades commanding spreads over commodity architectural formulations. Cost compression in long-oil architectural segments is intensifying because waterborne acrylic substitution erodes volume leverage. DIY channel distributors exhibit highest price sensitivity, while marine coating procurement offices at Hyundai Heavy Industries and Imabari Shipbuilding prioritize salt-spray performance over unit cost.
Supply Chain Analysis
Just-in-time inventory preferences dominate among European automotive OEM coating plants, while Chinese MEE-compliant compounders maintain strategic stockpiles of pentaerythritol ahead of emission enforcement windows. Production gravity centers on China, South Korea, and Germany, with the Yangtze River Delta and Ulsan-Busan corridor hosting integrated polyol-to-resin operations. Feedstock supply draws from phthalic anhydride, soybean oil, and tall oil fatty acid streams. Single-source vulnerability concentrates in Chinese purified terephthalic acid supply to European compounders. Distribution runs through direct pipeline connections at integrated sites and drum-based merchant channels for independent formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Alkyd resin procurement is shifting toward platform-economy dynamics as shipbuilders centralize coating specification authority and unbundle technical service from resin supply. This interoperability inflection favors compounders capable of direct technical agreements with end-specifiers rather than distributor-mediated relationships.
For Market Incumbents: Consolidate reactor asset ownership in coastal chemical clusters to defend margin stability against waterborne acrylic substitution in architectural segments. Acquire manganese-based drier chemistry capabilities ahead of ECHA cobalt restriction enforcement. Prioritize captive pentaerythritol supply integration to offset phthalic anhydride freight volatility on European coating accounts.
For New Entrants and Emerging Players: Anchor in Brazilian industrial maintenance white space where ANVISA-aligned registration barriers favor agile compliance investment over capital scale. Target medium-oil alkyd primers for petrochemical infrastructure in São Paulo state. Pursue direct specification relationships with maintenance contractors rather than distributor channel penetration.
For Investors and Strategic Acquirers: Capital is best deployed toward specialty modification houses with silicone and fluorinated alkyd expertise serving automotive OEM clearcoat accounts. Long-term viability across the analysis window hinges on reformulation agility under tightening REACH and EPA VOC mandates. Watch ECHA substance evaluation timelines for residual monomer classification as the inflection signal triggering consolidation urgency.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyol Production | Captive pentaerythritol supply insulates DSM and Dow from aromatic acid freight swings. |
| Cobalt Drier Substitution R&D Partnership | Manganese-iron catalyst qualification with Arkema SA creates first-mover advantage under REACH. |
| Water-Reducible Alkyd Dispersion Launch | Self-emulsifying architectures enable EPA 40 CFR Part 59 compliance without film-build sacrifice. |
| Direct Shipbuilder Technical Agreement | Hyundai Heavy Industries procurement consolidation rewards compounders bypassing distributor channels. |
| Bio-Based Feedstock Certification Program | EU Green Deal tall oil fatty acid schemes unlock premium tier positioning for renewable-content alkyds. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC 10-K filings, Cefic industry reports, and ECHA substance evaluation databases. Plant managers at Antwerp and Singapore integrated sites, procurement leads at Stuttgart automotive OEM coating operations, distribution channel partners serving North American DIY retail, and technical R&D directors specializing in oxidative cure kinetics contributed operational perspective. Bottom-up resin volume modeling triangulates against top-down coating market consumption estimates.
Segmentation dimensions modeled span oil length tier, modification chemistry, end-use application, packaging format, and regional production hub across the projection horizon. CAGRs derive from elasticity-adjusted demand curves incorporating MEE enforcement intensity, REACH reformulation timelines, and shipbuilding orderbook trajectories. Forecast inputs include phthalic anhydride price indices and cobalt drier substitution adoption curves.
Decision-makers should treat outputs as directional under base assumptions of sustained infrastructure investment in Guangdong and Texas, stable ECHA evaluation timelines, and continued marine coating specification consolidation; material deviation would warrant model refresh. Revision becomes warranted when Chinese MEE enforcement intensity or cobalt alternative qualification rates cross thresholds altering reformulation cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Biobased Thermosetting Polymers Market
Polymers & Resins
Acrylic Monomers Market
Polymers & Resins
US Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Plastic Resins Market
Polymers & Resins
Styrene Acrylonitrile (SAN) Resins Market
Polymers & Resins
Epoxy Resin Market
Polymers & Resins
Europe Polymer Emulsion Market
Polymers & Resins
Lactic Acid and Polylactic Acid Market
Polymers & Resins
Medical Polymers Market
Polymers & Resins
Global Structural Foam Market
Polymers & Resins
Africa Polyethylene Terephthalate (PET) Market
Polymers & Resins
Europe Polyamide Market
Polymers & Resins
Polycarbonate Diols Market
Polymers & Resins
Bio Based Resin Market
Polymers & Resins
Europe Polyvinyl Chloride (PVC) Market
Polymers & Resins
Thermosetting Plastics Market