
 Asia-Pacific Polymer Emulsion Market | 2026-2036
Asia-Pacific Polymer Emulsion Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Polymer Emulsion Market Analysis
Technical service contracts for formulation customization is hardening as the primary revenue layer beyond base resin sales. Synthomer Plc leverages its regional compounding network to anchor long-term supply agreements with Southeast Asian coatings producers. DIC Corporation sustains competitive positioning through backward integration into specialty acrylic monomers. Arkema dominates high-performance polyurethane emulsion segments for automotive interior applications.
Polymer emulsion denotes a colloidal dispersion of polymer particles in a continuous aqueous phase, typically manufactured through batch or semi-continuous emulsion polymerization at 40-80% solids content, serving as a binder system that eliminates solvent-based volatile organic compound emissions. Acrylic formulations lead volume consumption across architectural coatings and waterproofing membranes, while polyurethane emulsions command premium positioning in automotive and textile finishing due to superior abrasion resistance and elasticity. Styrene-butadiene segments retain cost advantages in carpet backing and paper coating applications where performance specifications permit lower-tier chemistry.
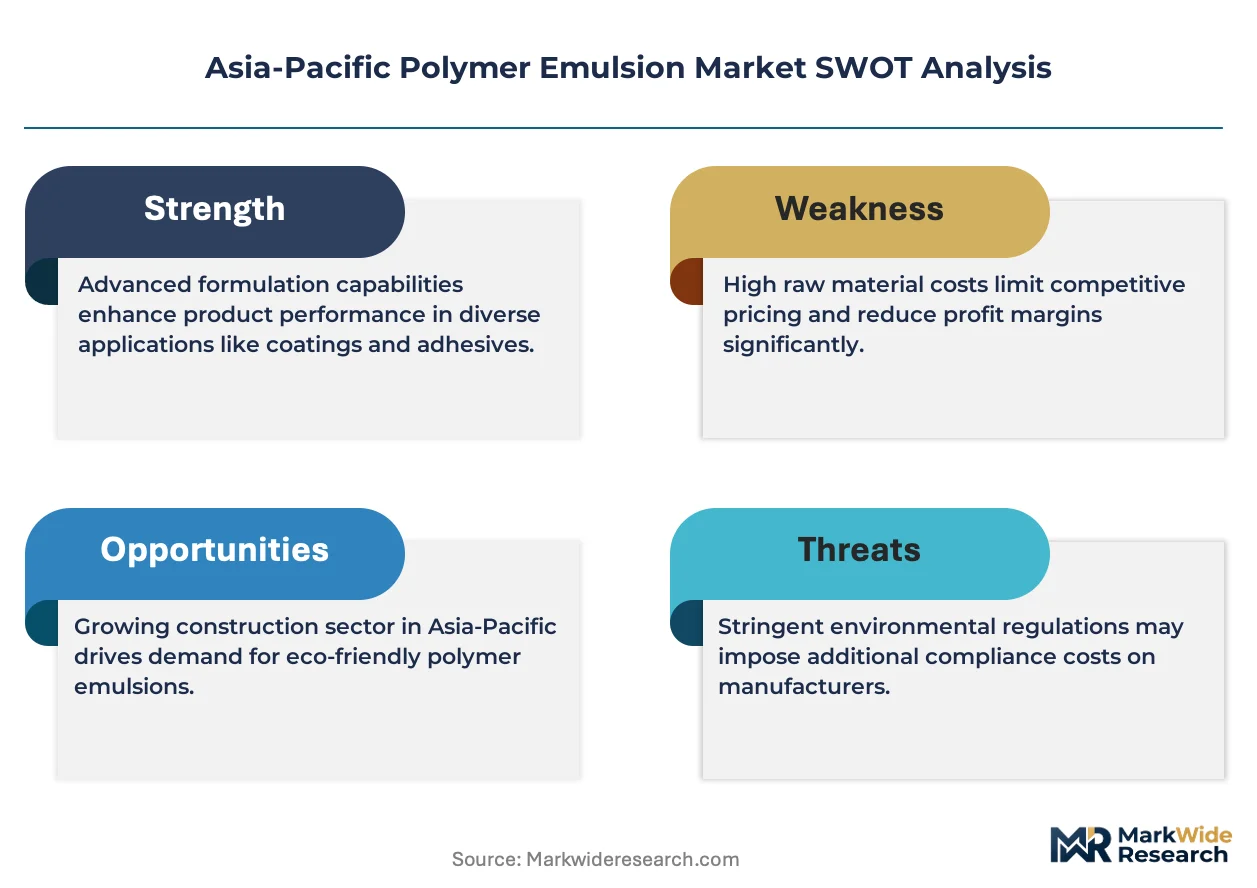
China's MEE enforces progressively stringent VOC limits under evolving GB standards, compelling reformulation investments from domestic producers and import-dependent end users. Japan's METI promotes low-carbon manufacturing incentives that favor water-based systems over solvent alternatives in industrial coating operations. India's BIS certification requirements for construction chemicals are tightening product quality thresholds, reshaping competitive access for regional suppliers. Stakeholders must monitor divergence between national emission standards and harmonized testing protocols when allocating R&D budgets across multi-country manufacturing footprints.
Market Dynamics
Water-based formulation mandates across Asia-Pacific construction and automotive sectors are compressing solvent-borne alternatives while concentrating procurement power among technical service-capable suppliers. China's MEE enforcement of GB VOC limits and India's BIS certification tightening are forcing simultaneous reformulation investments from domestic and multinational producers.
Growth Catalysts
- Southeast Asian Infrastructure Buildout:Vietnam, Indonesia, and Philippines are expanding waterproofing membrane specifications for commercial and residential developments. Water-based acrylic emulsions capture specification share from bituminous alternatives in tropical climate applications.
- China's Dual Carbon Policy Trajectory:MEE's progressive GB standards on architectural coatings are eliminating high-VOC solvent formulations from state-funded projects. Domestic manufacturers must reformulate or forfeit public procurement eligibility.
- Automotive Interior Material Transition:Polyurethane emulsions displace solvent-borne polyurethanes in seat upholstery and dashboard coatings. Japanese and South Korean OEMs are qualifying aqueous systems for premium vehicle segments.
Market Restraints
- Acrylic Monomer Price Volatility:Propylene and butyl acrylate feedstock costs fluctuate with naphtha cracking economics. Formulators lack pricing power to pass through raw material spikes in commoditized architectural coatings.
- Import Dependency for Specialty Additives:Southeast Asian producers rely on Chinese and Japanese suppliers for hydrophobic associative thickeners and defoamers. Concentrated additive sourcing creates formulation cost instability during supply disruptions.
- Performance Gap in Extreme Durability:Water-based polyurethane emulsions exhibit inferior hydrolytic stability versus solvent systems in tropical high-humidity environments. Automotive underhood and marine applications retain solvent-borne specifications.
Strategic Opportunities
- India's Western Industrial Corridor Expansion:Gujarat and Maharashtra automotive OEMs and textile finishers are building captive emulsion compounding capabilities. Technical service partnerships with these clusters secure long-term offtake agreements.
- Bio-based Acrylic Monomer Development:Fermentation-derived acrylic acid from agricultural waste streams is reaching pilot scale. Early adopters in Japanese coatings sector are qualifying bio-attributed emulsions for carbon accounting benefits.
- Japan's METI Low-Carbon Manufacturing Incentives:Subsidies for water-based system conversions in industrial coating operations are accelerating solvent displacement. Equipment retrofits and process requalification costs receive partial government coverage.
Industry Challenges
- Formulation Chemist Scarcity:Emulsion polymerization expertise concentrates among senior technical staff at established producers. Southeast Asian expansion plans face recruitment bottlenecks for rheology modification and particle size control specialists.
- Multi-Jurisdiction Certification Complexity:China's GB standards, India's BIS requirements, and Japan's JIS specifications employ divergent VOC testing protocols. Product registration costs multiply for suppliers serving cross-border automotive and construction supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Polymer Emulsion Market |
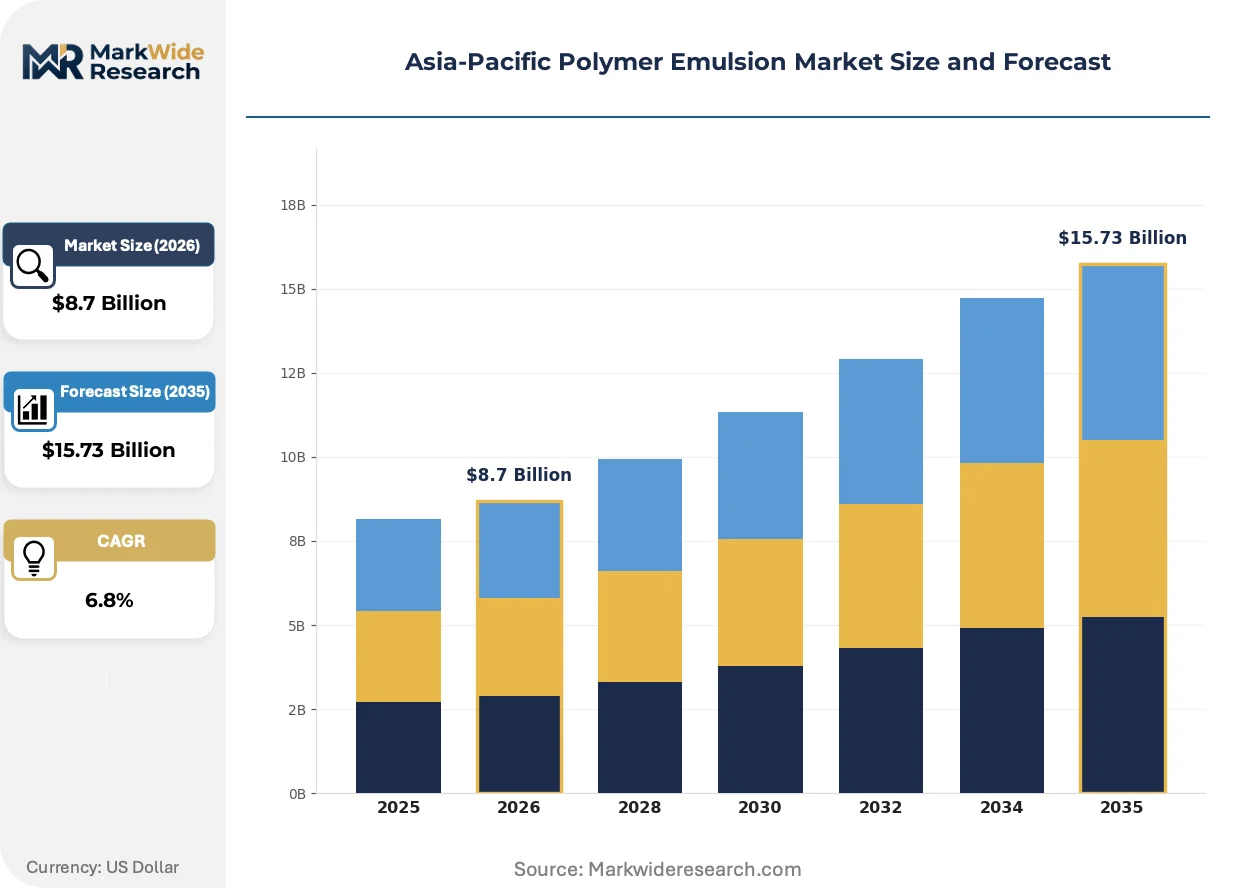
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adhesives, Coatings, Sealants, Inks End Use Industry: Construction, Automotive, Textiles, Consumer Goods Formulation Type: Acrylic, Styrene-Butadiene, Vinyl Acetate, Polyurethane Application: Waterproofing, Surface Protection, Bonding, Finishing |
| Companies Covered | OMNOVA Solutions, Synthomer Plc, Trinseo, DIC Corporation, Arkema, Asahi Kasei Corporation, JSR Corporation, Dairen Chemical Corporation, Nova Polychem, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Polymer Emulsion Market Emerging Trajectories
Core-shell particle architecture and hybrid polymer systems are displacing single-chemistry emulsions across performance-sensitive applications. Technical differentiation now centers on controlled morphology rather than solids content or price positioning.
Hybrid acrylic-polyurethane core-shell emulsions are electrifying premium architectural and automotive coating segments. Japanese and South Korean automotive OEMs are accelerating qualification timelines for these systems in metallic basecoats and clearcoats. The technology is compressing conventional two-component solvent polyurethane volumes in repair and refinish operations.
China's MEE is tightening GB 30982-2014 VOC limits for architectural coatings through progressive implementation schedules. Domestic manufacturers face capital-intensive reactor upgrades and formulation redevelopment to maintain market access. Import-dependent Southeast Asian coatings producers are absorbing compliance costs or sourcing from reformulated Chinese supply bases.
Specification-driven procurement is consolidating buyer power among technical service-capable formulators in Southeast Asian construction. Large infrastructure developers now require application support and warranty backing from emulsion suppliers, displacing spot-market commodity purchasing. Vietnam and Indonesia exhibit the most pronounced shift toward integrated supply agreements with performance guarantees.
Asia-Pacific Polymer Emulsion Market Segmentation
Segmentation in the Asia-Pacific polymer emulsion market reveals how formulation chemistry, application requirements, and end-use specifications create distinct competitive arenas. Procurement patterns diverge sharply between specification-driven construction coatings and cost-sensitive consumer goods adhesives.
Product Type:
Customization intensity varies from formulation-tolerant adhesives to specification-rigid sealants, creating tiered service requirements across supplier portfolios.
- Adhesives:Pressure-sensitive and laminating formulations dominate packaging and woodworking applications. Demand concentrates in Vietnam's furniture export clusters, where water-based systems displace solvent alternatives to meet EU import compliance.
- Coatings:Architectural and industrial formulations constitute the volume anchor, with acrylic emulsions serving tropical climate durability requirements. China's state-funded infrastructure projects mandate GB-compliant low-VOC systems, compressing solvent-borne alternatives.
- Sealants:Joint-filling and elastic recovery specifications for building envelopes.
- Inks:Flexographic and gravure printing applications for flexible packaging.
Most installed capacity flows through Coatings. Expansion is steepest in Adhesives.
End Use Industry:
Margin profiles separate project-based construction procurement from continuous automotive supply agreements, reshaping supplier relationship investments.
- Construction:Waterproofing membranes and decorative coatings absorb the majority of regional acrylic emulsion volume. Indonesia's commercial development pipeline and Philippines' residential buildout are specifying water-based systems for tropical humidity performance.
- Automotive:Interior trim coatings and adhesive applications command polyurethane emulsion premiums. Japanese and South Korean OEMs are qualifying aqueous systems for seat upholstery and dashboard finishes, displacing solvent-borne polyurethanes in premium segments.
- Textiles:Fabric finishing and nonwoven binders for apparel and technical applications.
- Consumer Goods:Packaging adhesives and product assembly for electronics and appliances.
Construction commands the dominant capacity share. Automotive delivers the steepest margin expansion trajectory.
Formulation Type:
Feedstock cost exposure and performance differentiation create distinct competitive moats across chemistry families.
- Acrylic:Methacrylate and acrylate copolymers deliver UV resistance and adhesion for architectural coatings. India's western industrial corridor is expanding captive compounding for construction chemicals, while Southeast Asian import dependency persists for specialty grades.
- Polyurethane:Aliphatic and aromatic dispersions provide abrasion resistance and elasticity for automotive and textile finishing. Japanese coatings producers are piloting bio-attributed versions for carbon accounting advantages.
- Styrene-Butadiene:Cost-optimized binders for carpet backing and paper coating.
- Vinyl Acetate:Homopolymer and copolymer systems for adhesives and construction additives.
Acrylic formulations absorb the majority of installed reactor capacity. Polyurethane is climbing the fastest on value terms.
Application:
Performance guarantees and warranty backing separate specification-driven waterproofing from commoditized bonding applications.
- Waterproofing:Membrane and coating systems for building envelopes and infrastructure. Vietnam and Indonesia are expanding commercial specifications that require supplier technical service and application support, displacing spot-market purchasing.
- Surface Protection:Clearcoats and primers for metal, wood, and concrete substrates.
- Bonding:Assembly adhesives for construction, packaging, and consumer products.
- Finishing:Topcoats and functional treatments for textiles, automotive interiors, and furniture.
Waterproofing concentrates the most installed formulation capacity. Surface Protection is gaining share fastest on specification upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's state-funded infrastructure pipeline absorbs more acrylic emulsion volume than India's western industrial corridor, yet Japanese automotive OEMs command the steepest polyurethane premiums across the region.
China
MEE enforcement of GB 30982-2014 VOC limits is eliminating high-solvent architectural coatings from public procurement. State-funded infrastructure projects now mandate water-based systems, compelling domestic manufacturers to reformulate or forfeit eligibility. Yangtze River Delta coatings clusters are absorbing compliance costs through reactor upgrades and captive monomer integration.
Japan
METI low-carbon manufacturing incentives favor water-based industrial coating conversions over solvent alternatives. Automotive OEMs in the Kanto region are accelerating qualification timelines for aqueous polyurethane systems in premium vehicle interiors. Bio-attributed emulsion development from fermentation-derived acrylic acid is reaching pilot scale among coatings producers.
India
BIS certification tightening for construction chemicals is reshaping competitive access for regional suppliers. Gujarat and Maharashtra automotive OEMs are building captive emulsion compounding capabilities to secure long-term supply chains. Western industrial corridor textile finishers are expanding consumption of polyurethane dispersions for technical fabric applications.
Vietnam
Commercial development pipelines are expanding waterproofing membrane specifications for tropical climate performance. Large infrastructure developers now require technical service and warranty backing from emulsion suppliers, displacing spot-market commodity purchasing. Ho Chi Minh City construction clusters are consolidating procurement power among specification-capable formulators.
Indonesia
Residential buildout and commercial development are specifying water-based acrylic systems over bituminous alternatives. Import dependency for specialty additives from Chinese and Japanese suppliers creates formulation cost instability during supply disruptions. Jakarta-Bandung industrial corridor coatings producers are negotiating integrated supply agreements with performance guarantees.
Asia-Pacific Polymer Emulsion Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with technical service capability determining specification access in construction while cost efficiency dominates consumer goods adhesives. The vendor base concentrates around three tiers: multinational chemical conglomerates with backward monomer integration, regional compounders with formulation customization expertise, and import-dependent distributors serving spot-market demand. M&A activity targets captive emulsion compounding assets in India's western corridor, while strategic partnerships anchor long-term supply agreements with Southeast Asian coatings producers.
Within the multinational tier, Synthomer Plc and DIC Corporation exemplify divergent integration strategies, with the former leveraging regional compounding networks and the latter sustaining positioning through specialty acrylic monomer control. Arkema occupies a position in high-performance polyurethane segments for automotive interior applications. These three entities represent distinct archetypes: technical service-led regional anchoring, backward-integrated specialty chemistry, and premium performance segment dominance.
| Leading Market Players |
|---|
| OMNOVA Solutions |
| Synthomer Plc |
| Trinseo |
| DIC Corporation |
| Arkema |
| Asahi Kasei Corporation |
| JSR Corporation |
| Dairen Chemical Corporation |
| Nova Polychem |
| Others |
Supply Flow & Price Mechanics
Propylene and butyl acrylate feedstock costs cascade through acrylic emulsion pricing tiers from Yangtze River Delta reactor complexes to Southeast Asian coatings formulators, with monomer volatility compressing margins at each formulation stage.
Pricing Analysis
Capacity additions in China are reshaping price floors for standard-grade acrylic emulsions across the Asia-Pacific region. Three-tier pricing structure across premium, standard, and economy levels separates specification-rigid automotive polyurethane systems from commoditized architectural binders. Cost compression in architectural coatings intensifies because formulators lack pricing power to pass through naphtha-derived feedstock spikes. Spot-market buyers in Vietnam and Indonesia exhibit the highest price sensitivity, while Japanese automotive OEMs accept polyurethane premiums for interior qualification programs.
Supply Chain Analysis
Return flows of off-specification emulsion batches and packaging materials from Southeast Asian construction sites create reverse-logistics complexity for regional distributors. Manufacturing concentrates in China, Japan, and South Korea, with specialty additive production anchored in Chinese and Japanese chemical parks. Formulation chemistry draws from acrylic monomer, polyurethane prepolymer, and hydrophobic associative thickener inputs. Single-source vulnerability for specialty additives from concentrated Japanese suppliers creates disruption risk during logistics chokepoints. Distribution runs through technical service-integrated direct supply agreements with large infrastructure developers, displacing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where China's MEE enforcement of progressive GB VOC limits creates sustained reformulation demand across state-funded construction procurement.
For Market Incumbents: To counter margin erosion from acrylic monomer price volatility, anchor long-term offtake agreements with India's western industrial corridor automotive OEMs and deepen captive monomer integration through Yangtze River Delta reactor upgrades. Certification investment for BIS-compliant construction chemical grades secures eligibility as India's quality thresholds tighten. For New Entrants and Emerging Players: Begin with technical service partnerships for Vietnam's waterproofing membrane specifications, where large developers now require application support and warranty backing. Indonesia's residential buildout offers the most penetrable volume opportunity for water-based acrylic systems displacing bituminous alternatives. A go-to-market angle centered on tropical climate durability testing and local compounding capabilities accelerates specification access. For Investors and Strategic Acquirers: Roll-up economics work for regional compounders with formulation customization expertise because procurement power is concentrating among technical service-capable suppliers serving Southeast Asian infrastructure. Long-term viability hinges on positioning for sustained regulatory-driven solvent displacement across the Asia-Pacific region. Acquisition targets should demonstrate captive emulsion compounding assets in India's western corridor with established automotive or textile finisher relationships. Practitioners should monitor divergence between national VOC testing protocols for early signals of compliance cost multiplication.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Acrylic Monomers | DIC Corporation's captive monomer production secures formulation cost stability against naphtha volatility. |
| Technical Service Network Expansion | Synthomer Plc's regional compounding anchors long-term supply agreements with Vietnamese coatings producers. |
| Joint Venture for Bio-Based Monomer Development | Fermentation-derived acrylic acid partnerships qualify Japanese coatings producers for METI carbon accounting incentives. |
| Capacity Expansion in India's Western Corridor | Gujarat and Maharashtra captive compounding assets capture automotive OEM demand for qualified polyurethane systems. |
| Long-term Supply Agreement with Infrastructure Developers | Integrated performance guarantees displace spot-market purchasing in Indonesia's Jakarta-Bandung industrial corridor. |
Methodological Framework
Direct dialogue with plant managers at emulsion polymerization facilities, procurement leads at Southeast Asian coatings producers, technical R&D directors at automotive OEMs, and distribution channel partners in Indonesia and Vietnam grounded qualitative assessments. Secondary validation drew from customs and trade data for acrylic monomer flows, China MEE regulatory filings on GB standard evolution, SEC 10-K disclosures from multinational chemical producers, and Japan METI low-carbon manufacturing incentive documentation. Bottom-up capacity assessments and top-down end-use consumption estimates were triangulated to constrain forecast variance.
Bottom-up modeling of reactor capacity utilization by formulation type and end-use industry was cross-checked against top-down construction spending and automotive production forecasts across the analysis window. Segmentation dimensions included product chemistry family, application performance tier, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to validated base-year consumption estimates. Industry-specific forecast inputs incorporated MEE implementation schedules for GB 30982-2014 and BIS certification rollout timelines for construction chemicals.
Several conditions sit outside the modeled scope, including abrupt feedstock price shocks from naphtha cracking economics disruptions, unilateral tariff impositions on specialty additive imports, and accelerated solvent-borne technology breakthroughs that close performance gaps in tropical humidity environments. Forecasts reflect documented assumptions about regulatory enforcement consistency and infrastructure spending continuity. Practitioners should monitor divergence between China's GB standards and India's BIS testing protocols for early signals of multi-jurisdiction compliance cost escalation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Ethylene Vinyl Acetate (EVA) Market
Polymers & Resins
Europe Geopolymer Market
Polymers & Resins
Middle East and Africa Hydroxyl-Terminated Polybutadiene (HTPB) Market
Polymers & Resins
Flame Retardant Polyester Resins Market
Polymers & Resins
Polymer Antioxidants Market
Polymers & Resins
Bio-Based and Synthetic Polyamide Market
Polymers & Resins
China Engineering Plastics Market
Polymers & Resins
Methacrylate Monomers Market
Polymers & Resins
Concrete Containing Polymer Market
Polymers & Resins
Plastic Compounding Market
Polymers & Resins
Polymer Modified Bitumen (PMB) Market
Polymers & Resins
Fluorine Polymer Films Market
Polymers & Resins
Polytetrafluoroethylene (PTFE) Market
Polymers & Resins
Global PEEK Market
Polymers & Resins
Global Medical Superabsorbent Polymers Market
Polymers & Resins
Global Linear Low Density Polyethylene Market