
 Temperature Calibration Equipment Market | 2026-2036
Temperature Calibration Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Temperature Calibration Equipment Market Analytics
The temperature calibration equipment sector is restructuring around a widening capability gap between laboratory-grade systems and portable field units. Fluke Corporation leverages its handheld instrument heritage to dominate on-site industrial calibration workflows. AMETEK Inc. sustains premium positioning through deep vertical integration into temperature sensor manufacturing. Beamex Oy Ab differentiates through software-integrated calibration management platforms that automate documentation chains.
Temperature calibration equipment encompasses instruments that verify and adjust the accuracy of temperature sensors, transmitters, and switches against traceable reference standards, typically achieving uncertainties from ±0.001°C in liquid bath systems to ±0.5°C in infrared field calibrators. These devices ensure measurement integrity across processes where thermal deviation risks product failure, regulatory non-compliance, or safety incidents. Dry block calibrators lead volume demand due to their portability and rapid heating-cooling cycles, while liquid bath systems retain margin concentration in metrology laboratories requiring sub-millikelvin stability. Smart and software-driven technologies represent the fastest-expanding technology segment as end users seek automated calibration interval tracking and digital certificate generation.
FDA 21 CFR Part 11 and EU Annex 11 mandate electronic records and signatures for pharmaceutical temperature monitoring, directly expanding demand for documented calibration traceability. EPA refrigerant management rules and ISO/IEC 17025 laboratory accreditation standards further shape equipment specifications and service provider qualifications. Stakeholders must evaluate how impending updates to the EU AI Act and FDA software-as-medical-device guidance will redefine validation requirements for automated calibration systems.
Market Dynamics
Calibration equipment manufacturers face a structural bifurcation between laboratory-grade precision systems and portable field units, with software-integrated documentation platforms emerging as the decisive competitive wedge separating premium positioning from commodity competition.
Growth Catalysts
- Pharmaceutical compliance mandates:FDA 21 CFR Part 11 and EU Annex 11 require electronic records and signatures for temperature monitoring, forcing documented calibration traceability across GMP facilities.
- Automotive EV battery testing:Thermal validation of lithium-ion cells and battery management systems demands expanded calibration capacity at cell gigafactories and vehicle assembly plants.
- ISO/IEC 17025 laboratory accreditation:Third-party testing laboratories in Germany and Switzerland pursue metrological traceability to maintain competitive certification status.
Market Restraints
- Platinum resistance thermometer element scarcity:Concentrated Russian and South African platinum group metal supply creates input cost volatility for high-precision reference sensors.
- Metrology-grade liquid bath manufacturing:Only three European suppliers produce thermal uniformity below ±0.005°C, creating supply concentration risk for sub-millikelvin applications.
- Infrared calibrator technical ceiling:Emissivity uncertainty and field-of-view limitations prevent infrared field units from displacing contact-based methods in pharmaceutical validation.
Strategic Opportunities
- India pharmaceutical manufacturing expansion:CDSCO's tightening data integrity requirements for export-oriented API producers creates demand for documented calibration management systems.
- Cloud-based calibration asset management:Integration of IoT sensor networks with predictive maintenance platforms enables automated interval optimization and digital certificate generation.
- South Korean semiconductor fabrication:MFDS-equivalent thermal process validation for advanced node chip manufacturing requires expanded on-site calibration infrastructure.
Industry Challenges
- Metrologist skill scarcity:Specialized expertise in uncertainty budget calculation and ISO 17025 quality system management commands wage premiums that compress service margins.
- Legacy SCADA integration complexity:Pharmaceutical facilities operating 1990s-era distributed control systems face protocol incompatibility with modern digital calibration recorders.
- UKAS/EIAC mutual recognition delays:Divergent national accreditation body interpretations of ILAC MRA requirements fragment cross-border calibration certificate acceptance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Temperature Calibration Equipment Market |
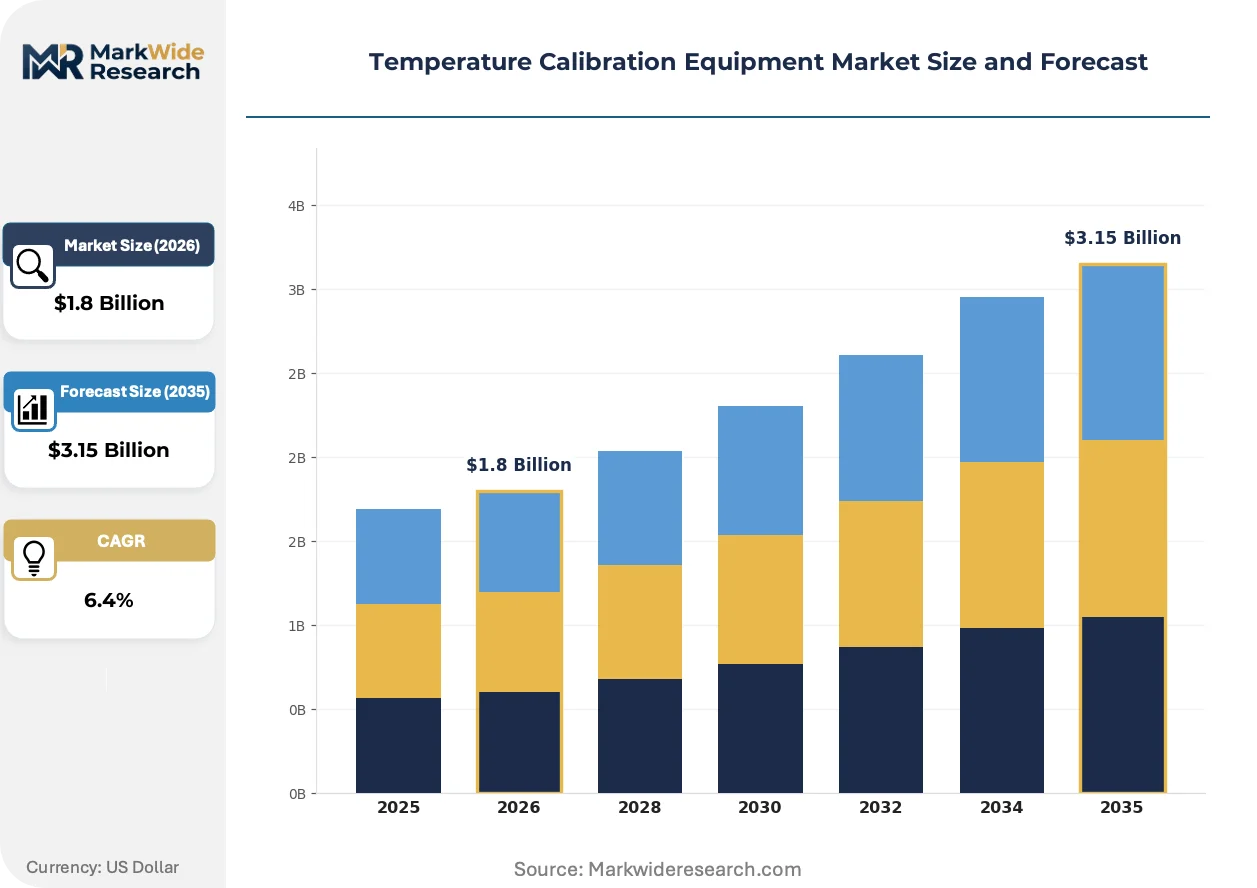
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Bath, Dry Block, Infrared Calibrators, Thermocouple Calibrators End User: Laboratories, Manufacturing Plants, Aerospace, Automotive Technology: Digital, Analog, Smart, Software-Driven Application: Food Safety, Pharmaceutical, Electronics Testing, HVAC |
| Companies Covered | Fluke Corporation, AMETEK Inc., WIKA Alexander Wiegand SE & Co. KG, Additel Corp., Beamex Oy Ab, Fortive Corp., Yokogawa Electric Corp., Omega Engineering, Spectris Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Temperature Calibration Equipment Market Evolving Landscape
Software-defined calibration workflows are displacing paper-based documentation chains across regulated industries, with automated data integrity and audit trail generation becoming baseline purchasing criteria rather than premium features.
Portable dry block calibrators with embedded IEEE 1588 precision time protocol synchronization are converging with distributed control system architectures, enabling pharmaceutical manufacturers to eliminate manual transcription errors in batch records while compressing calibration cycle times from hours to minutes.
The EU AI Act's risk classification framework for automated decision-making systems is reshaping validation requirements for machine-learning-enabled calibration interval prediction tools, forcing equipment vendors to document algorithmic transparency and training data provenance for pharmaceutical customers in Germany and France.
Asset-light calibration service contracting is displacing capital equipment ownership among mid-sized chemical processors, with third-party providers in the Netherlands and Belgium offering guaranteed uptime SLAs that bundle hardware, software, and metrological traceability into per-instrument subscription fees.
Temperature Calibration Equipment Market Segmentation
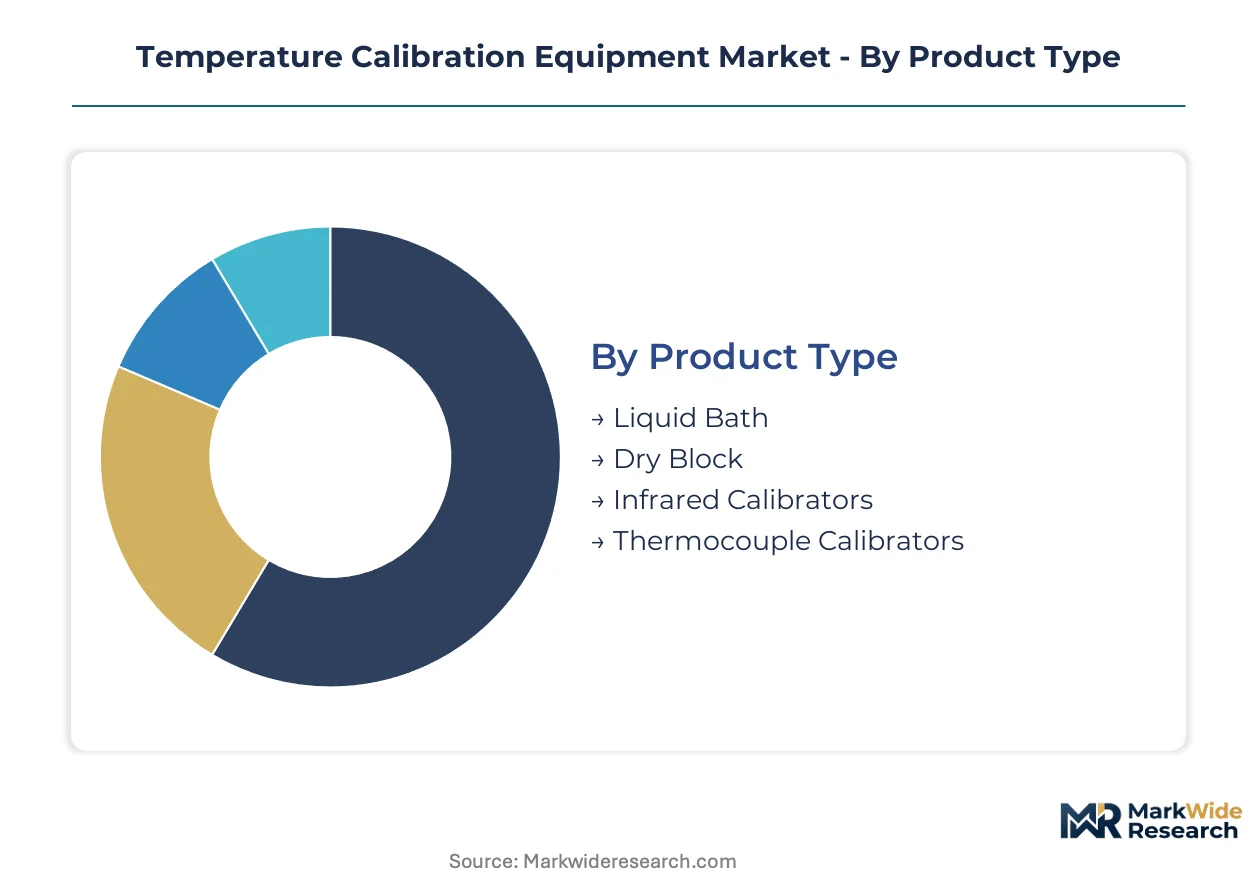
Temperature calibration equipment segments diverge sharply on certification burden. Pharmaceutical applications demand ISO/IEC 17025 traceability and FDA 21 CFR Part 11 documentation, while food safety and HVAC segments operate under lighter regulatory frameworks. Understanding these tiered compliance requirements shapes procurement strategies and margin structures across supplier portfolios.
Product Type:
Liquid bath systems carry the heaviest metrology-grade certification burden, requiring ILAC MRA-accredited laboratories for sub-millikelvin uncertainty claims. Dry block and infrared units face lighter documentation requirements in field calibration contexts.
- Liquid Bath:These systems achieve thermal uniformity below ±0.005°C through precision fluid temperature control, making them indispensable for national metrology institutes and pharmaceutical reference laboratories. German and Swiss calibration service providers concentrate demand here as ISO/IEC 17025 accreditation mandates deepen.
- Dry Block:Portable aluminum or brass insert calibrators enable rapid heating-cooling cycles for industrial fieldwork. Automotive EV battery testing facilities in Germany and South Korea drive expanding procurement as thermal validation protocols for lithium-ion cells tighten.
- Infrared Calibrators:Non-contact blackbody sources address emissivity-calibrated measurements where sensor contact is impractical.
- Thermocouple Calibrators:Millivolt-simulating instruments verify Type K, J, T, and N thermocouple accuracy across manufacturing plant floors.
Dry block calibrators sit at the top of the volume ranking, with smart-enabled portable units climbing the fastest.
End User:
Cost tier stratification separates end user segments. National laboratories and aerospace contractors absorb premium pricing for primary standards, while manufacturing plants prioritize total cost of ownership and calibration interval automation.
- Laboratories:Metrology institutes and third-party testing facilities require liquid bath systems with sub-millikelvin stability for platinum resistance thermometer calibration. German national standards laboratories anchor European demand as EURAMET key comparison programs expand.
- Manufacturing Plants:Chemical processors and pharmaceutical GMP facilities favor dry block calibrators with embedded documentation software. FDA 21 CFR Part 11 compliance costs drive preference for automated data integrity solutions over manual record-keeping.
- Aerospace:MRO providers and engine manufacturers demand portable multi-function calibrators for turbine temperature sensor validation.
- Automotive:EV battery gigafactories require expanded thermal validation capacity for cell formation and battery management system testing.
Manufacturing plants command the largest installed base, though aerospace qualification programs are expanding most quickly.
Technology:
Application maturity separates technology segments. Digital and analog platforms represent legacy installed bases, while smart and software-driven architectures capture new procurement as predictive maintenance platforms proliferate.
- Digital:Microprocessor-based instruments with stored calibration coefficients and linearization algorithms dominate mid-range industrial applications. Pharmaceutical facilities in France and Germany favor these units for their balance of accuracy and audit trail simplicity.
- Smart:IoT-enabled calibrators with embedded sensors and cloud connectivity enable automated interval optimization. EU AI Act risk classification requirements are reshaping validation protocols for machine-learning-enabled calibration prediction tools.
- Analog:Potentiometer and bridge-based instruments persist in legacy installations where electromagnetic interference resilience outweighs convenience.
- Software-Driven:Calibration management platforms automate documentation chains and digital certificate generation.
Digital platforms retain the broadest installed base, with software-driven solutions gaining share fastest.
Application:
Geographic concentration shapes application segment dynamics. Pharmaceutical and electronics testing cluster in Germany, Switzerland, and South Korea, while food safety and HVAC distribute more broadly across mid-tier manufacturing economies.
- Pharmaceutical:GMP facilities require documented calibration traceability for autoclave, lyophilizer, and cold chain validation. FDA 21 CFR Part 11 and EU Annex 11 mandates directly expand demand for software-integrated calibration management systems.
- Electronics Testing:Semiconductor fabrication facilities require thermal chuck calibration and environmental chamber validation. South Korean advanced node chip manufacturing drives on-site calibration infrastructure expansion.
- Food Safety:HACCP-compliant thermal process validation for pasteurization and sterilization operations.
- HVAC:Refrigerant management and building automation sensor calibration under EPA and F-Gas Regulation requirements.
Pharmaceutical applications lead revenue concentration, with electronics testing showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German metrology laboratories anchor European talent concentration for sub-millikelvin calibration expertise, while South Korean semiconductor fabrication clusters and Indian pharmaceutical export zones reshape procurement geography.
Germany
Automotive EV battery testing and chemical processing drive equipment demand as thermal validation protocols tighten. KBA and EURAMET accreditation requirements deepen documentation burdens for calibration service providers. Bavarian precision instrument clusters around Munich and Nuremberg expand metrology-grade liquid bath capacity for pharmaceutical reference laboratories.
United States
Pharmaceutical GMP facilities and aerospace MRO providers absorb premium calibration systems for FDA-regulated temperature monitoring. EPA refrigerant management rules and FAA turbine validation standards shape equipment specifications. Greater Boston and Research Triangle Park concentrate demand for software-integrated documentation platforms serving biotech manufacturing.
South Korea
Advanced node semiconductor fabrication requires expanded thermal chuck calibration infrastructure for sub-5nm chip manufacturing. MFDS-equivalent process validation mandates from the national pharmaceutical regulator tighten metrological traceability requirements. Seoul Capital Area and Busan-Ulsan industrial corridors anchor calibration service provider networks serving Samsung and SK Hynix supply chains.
India
CDSCO data integrity enforcement for export-oriented API producers accelerates documented calibration management adoption. PLI scheme incentives for pharmaceutical manufacturing deepen investment in automated calibration systems. Maharashtra and Gujarat pharmaceutical clusters in Mumbai-Pune and Ahmedabad-Vadodara corridors drive procurement of software-driven documentation platforms.
Switzerland
Swissmedic pharmaceutical oversight and precision instrument heritage sustain demand for laboratory-grade reference standards. ISO/IEC 17025 accreditation expansion among third-party testing laboratories tightens traceability requirements. Basel and Zurich metropolitan areas concentrate metrology expertise serving Novartis and Roche manufacturing quality systems.
Temperature Calibration Equipment Market Competitive Landscape
Top-tier vendors anchor premium positioning through software-integrated documentation platforms, while mid-tier specialists compete on portable field unit portability and rapid calibration cycle times. The vendor base stratifies across three archetypes: precision instrument conglomerates with captive sensor manufacturing, calibration management software specialists, and handheld field equipment heritage players. Consolidation pressures concentrate among documentation software providers as regulatory compliance automation becomes decisive. Strategic moves center on backward integration into platinum resistance thermometer element sourcing and cloud-based calibration asset management platform development.
Within the precision instrumentation tier, Fluke Corporation and AMETEK Inc. occupy positions reflecting handheld field heritage and sensor manufacturing integration respectively. Beamex Oy Ab exemplifies the software-integrated calibration management archetype, anchoring Finnish expertise in automated documentation chain platforms. WIKA Alexander Wiegand SE & Co. KG represents German precision instrument conglomerate positioning with deep upstream control over reference sensor production. These three companies illustrate competitive positioning vectors: field portability, vertical manufacturing integration, and compliance automation software.
| Leading Market Players |
|---|
| Fluke Corporation |
| AMETEK Inc. |
| WIKA Alexander Wiegand SE & Co. KG |
| Additel Corp. |
| Beamex Oy Ab |
| Fortive Corp. |
| Yokogawa Electric Corp. |
| Omega Engineering |
| Spectris Plc |
| Others |
Value Network & Pricing Analysis
Backward integration into platinum resistance thermometer element sourcing anchors premium pricing power for metrology-grade equipment manufacturers while exposing mid-tier players to Russian and South African supply volatility. This captive supply structure enables German and Swiss precision instrument conglomerates to defend margin positions in liquid bath systems even as portable dry block units face commoditization pressure from Asian contract manufacturers.
Pricing Analysis
Bundled calibration-as-a-service contracts with guaranteed uptime SLAs are displacing per-unit equipment transactions among mid-sized chemical processors in the Netherlands and Belgium. Three-tier pricing structure across premium, standard, and economy levels separates ISO/IEC 17025-accredited laboratory systems from field-portable units and non-certified maintenance tools. Cost compression in economy-tier infrared calibrators is intensifying because emissivity uncertainty limitations prevent technical differentiation. Pharmaceutical GMP facilities show least price sensitivity due to FDA 21 CFR Part 11 compliance mandates, while HVAC contractors absorb greatest pricing pressure.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from automotive EV battery gigafactories in Germany and South Korea, while distributor networks serve fragmented maintenance-repair-overhaul providers. Manufacturing concentrates in Germany, Finland, and Switzerland for precision instrument assembly, with sensor element sourcing drawn from Russian and South African platinum group metal suppliers. Supply chain risk centers on single-source vulnerability for sub-millikelvin liquid bath thermal uniformity components. Distribution runs through authorized service partners for documentation-integrated platforms and direct e-commerce for portable field units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as pharmaceutical and semiconductor end-users shift procurement toward software-integrated calibration management systems with automated audit trail generation.
For Market Incumbents: Hedge platinum group metal exposure through long-term offtake agreements with South African suppliers or accelerated transition to thin-film platinum resistance alternatives. Defend documentation software margins by embedding IEEE 1588 precision time protocol synchronization as a proprietary feature rather than open standard, creating switching costs for pharmaceutical customers facing FDA validation burdens. For New Entrants and Emerging Players: Capture white-space in Indian pharmaceutical export corridors where CDSCO data integrity enforcement outpaces local calibration service provider capacity. Target cloud-based calibration asset management platforms for mid-tier chemical processors in Belgium and the Netherlands seeking to avoid capital equipment ownership. Lead with subscription-based pricing that bundles hardware, software, and metrological traceability into per-instrument fees. For Investors and Strategic Acquirers: Roll-up economics work for calibration management software specialists because regulatory compliance automation requirements are consolidating buyer preference around documented platform solutions. Five-to-ten year viability hinges on EU AI Act algorithmic transparency mandates reshaping validation protocols for machine-learning-enabled interval prediction tools. Watch for inflection when national accreditation bodies harmonize ILAC MRA interpretation across UKAS and EIAC jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Elements | Captive platinum resistance thermometer supply insulates German manufacturers from Russian export volatility. |
| Cloud-Based Calibration Asset Management | Automated interval optimization aligns with EU AI Act risk classification for pharmaceutical customers. |
| Geographic Expansion into India | CDSCO enforcement creates documented calibration management demand among API export producers. |
| Software-Defined Documentation Platforms | FDA 21 CFR Part 11 compliance automation displaces paper-based audit trails in GMP facilities. |
| Strategic Partnership with EV Battery Gigafactories | Thermal validation protocols for lithium-ion cell formation require expanded on-site calibration infrastructure. |
Research Methodology
Coverage spans Germany, United States, South Korea, India, and Switzerland, with primary inputs from each market through structured interviews with calibration service provider technical directors, pharmaceutical GMP facility quality managers, automotive EV battery testing engineers, semiconductor fabrication metrologists, and precision instrument OEM procurement leads. Secondary validation draws from FDA 510(k) filings for calibration software, EPA refrigerant management rulemakings, ISO/IEC 17025 accreditation registries, and EURAMET key comparison program documentation. Bottom-up equipment shipment data triangulates against top-down pharmaceutical and semiconductor capital expenditure disclosures.
Rate-of-change decomposition separates volume expansion from mix-shift toward higher-value software-integrated platforms across the projection horizon. Segmentation dimensions modeled include product type, end user archetype, technology tier, and application vertical alongside regional regulatory cluster intensity. CAGRs derive from installed base growth, replacement cycle compression, and average selling price trajectory analysis. Industry-specific forecast inputs encompass platinum group metal price volatility scenarios and EU AI Act implementation timelines for automated calibration systems.
Underlying measurement precision varies by segment; pharmaceutical and metrology laboratory applications carry tighter precision than HVAC and general industrial maintenance. Forecasts reflect assumptions about regulatory enforcement continuity, accreditation body harmonization progress, and sensor element supply chain stability. Periodic stress-testing of base assumptions is recommended against platinum market disruption or accelerated EU AI Act risk reclassification.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Thin Wafer Processing and Dicing Equipment Market
Semiconductor Equipment
Lithography Systems Market
Semiconductor Equipment
Partition Inserter Machines Market
Semiconductor Equipment
Global Semiconductor Wafer Polishing and Grinding Equipment Market
Semiconductor Equipment
Semiconductor Wafer Fab Equipment (WFE) Market
Semiconductor Equipment
Global Photoresist Market
Semiconductor Equipment
Vacuum Chambers Market
Semiconductor Equipment
Global Semiconductor Thermal Evaporators Market
Semiconductor Equipment
Semiconductor Wafer Process Control Equipment Market
Semiconductor Equipment
OLED Vacuum Evaporation Machine Market
Semiconductor Equipment
Semiconductor Equipment Market
Semiconductor Equipment
Global Microelectronics Cleaning Equipment Market
Semiconductor Equipment
Global Semiconductor Front-End Equipment Market
Semiconductor Equipment
SMT Machine Market
Semiconductor Equipment
Wafer Processing Equipment Market
Semiconductor Equipment
North America Battery Manufacturing Equipment Market