
 Lithography Systems Market | 2026-2036
Lithography Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Lithography Systems Market Intelligence
Market Context
The direct sales channel between lithography equipment makers and leading-edge foundries is narrowing as ASML Holding N.V. controls EUV scanner allocation through long-term co-development agreements. Nikon Corporation competes in ArF immersion systems for mature nodes, while Canon Inc. leverages i-line and KrF tools to sustain exposure in power semiconductor and display panel applications. ZEISS Group anchors the optical supply chain with its exclusive EUV mirror production for ASML's most advanced systems.
Technical Definition and Segment Structure
Lithography systems project patterned images onto photosensitive substrates using electromagnetic radiation at wavelengths ranging from 436 nm (g-line) to 13.5 nm (EUV), enabling transistor feature sizes below 3 nanometers in semiconductor fabrication. Extreme Ultraviolet Lithography dominates capital allocation among technology segments due to its monopoly position at nodes below 7 nm, while Photolithography retains volume leadership across the broader installed base. Foundries represent the fastest-growing end user category as TSMC and Samsung expand EUV-intensive capacity, whereas Research Institutes occupy a stable but smaller margin pool focused on next-generation patterning methods.
Regulatory Environment
The EU F-Gas Regulation restricts hydrofluorocarbon use in immersion lithography cooling systems, pushing equipment redesign toward alternative chemistries, while REACH compliance governs photoresist monomer registration and supply chain transparency across European customer bases. Japan's METI coordinates export controls on advanced semiconductor manufacturing equipment through multilateral agreements with Dutch and US regulators. Stakeholders must monitor evolving dual-use technology restrictions and carbon border adjustments that could reshape equipment qualification timelines and geographic deployment strategies.
Market Dynamics
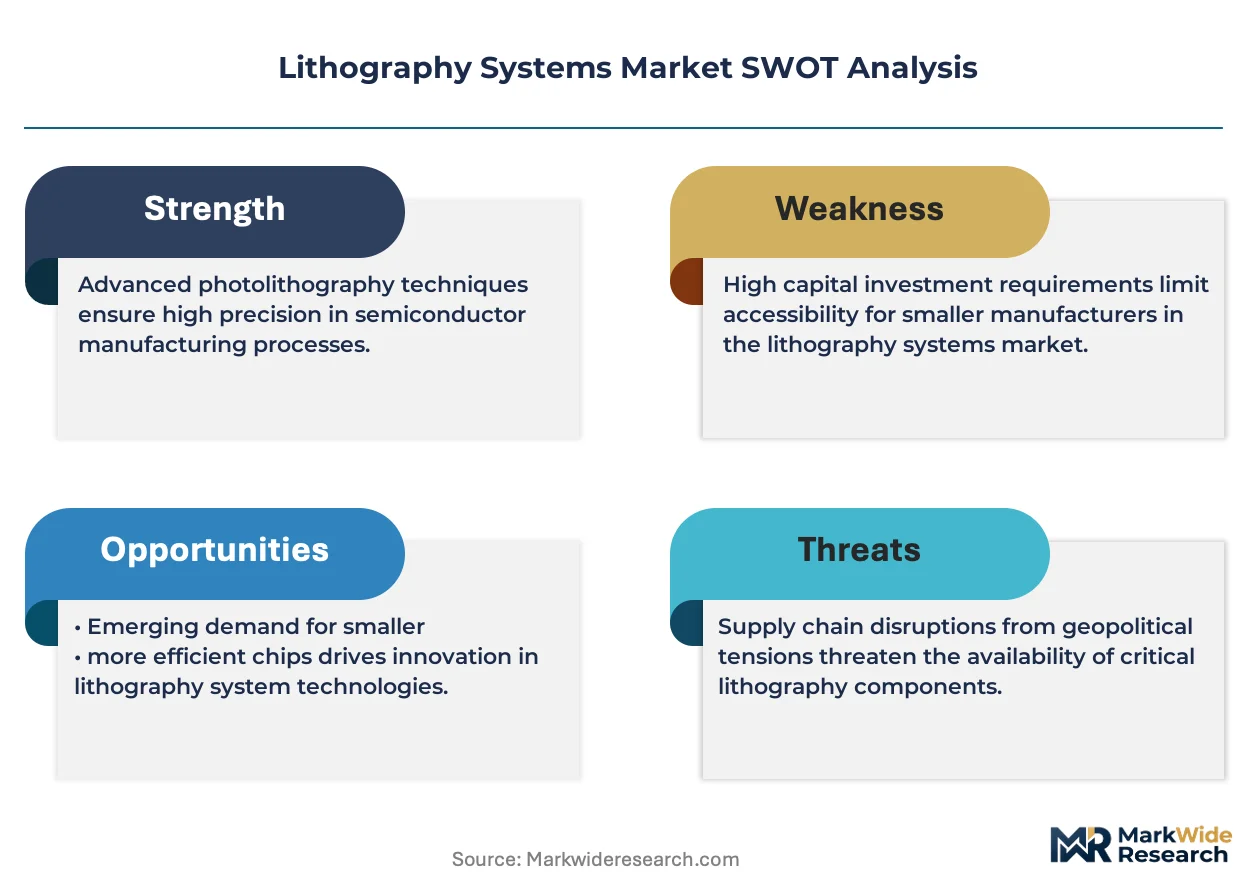
ASML's exclusive control over EUV scanner production has concentrated supply-side power, forcing foundries into multi-year co-development commitments and reshaping competitive access to sub-7nm manufacturing capability.
Growth Catalysts
- Foundry Node Migration:TSMC and Samsung are accelerating EUV layer counts for sub-3nm logic production, pulling equipment allocation toward Taiwan and South Korea.
- REACH Compliance:ECHA's tightened photoresist monomer registration is filtering out smaller chemical suppliers, consolidating qualified material streams for immersion systems.
- High-NA EUV Readiness:Semiconductor research institutes in the Netherlands and Japan are pre-qualifying next-generation optics, creating pull-through demand for metrology and mask infrastructure.
Market Restraints
- Optics Supply Concentration:ZEISS Group's exclusive mirror production for EUV systems creates single-point vulnerability for leading-edge scanner output.
- Fluorinated Compound Restrictions:The EU F-Gas Regulation is forcing cooling system redesigns, extending equipment qualification timelines by 12-18 months for immersion lithography platforms.
- ArF Immersion Saturation:Nikon Corporation's mature-node systems face demand compression as foundries freeze capital allocation at 28nm and above.
Strategic Opportunities
- Power Semiconductor Expansion:Canon Inc.'s i-line and KrF tools are capturing silicon carbide and gallium nitride substrate patterning demand from automotive electrification programs.
- Display Panel Recovery:OLED and micro-LED manufacturing in South Korea and China is reviving stepper demand for backplane patterning at Gen 6 and Gen 8.5 substrate sizes.
- Japan METI Export Control Coordination:Tokyo's alignment with Dutch and US dual-use restrictions is creating preferential equipment access channels for Japanese material and component suppliers.
Industry Challenges
- EUV Source Engineering Talent:The scarcity of plasma physics and laser-produced plasma specialists is constraining source power scaling and dose stability improvements.
- Mask Blank Defectivity:Sub-50nm multilayer defect detection requirements are outpacing metrology tool resolution, extending mask qualification cycles.
- Legacy Tool Obsolescence:Foundries are struggling to source spare parts for 200mm i-line steppers as original component vendors exit mature semiconductor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithography Systems Market |
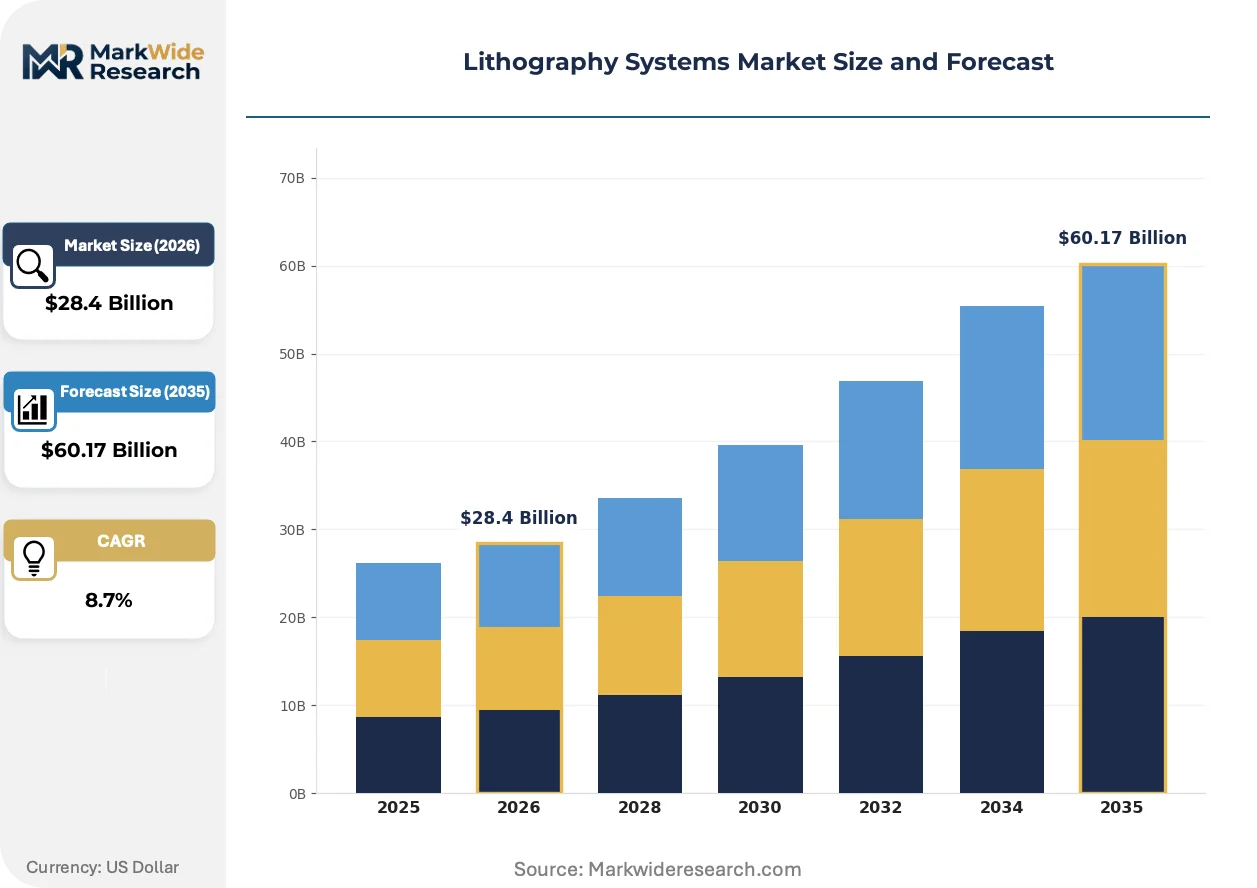
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $60.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photolithography, Electron Beam Lithography, X-Ray Lithography, Nanoimprint Lithography Technology: Optical Lithography, Extreme Ultraviolet Lithography, Maskless Lithography, 3D Lithography Application: Semiconductors, MEMS, Microfluidics, Displays End User: OEMs, Foundries, Research Institutes, Fabless Companies |
| Companies Covered | KLA Corporation, ZEISS Group, ASML Holding N.V., Veeco Instruments Inc., TRUMPF, Nikon Corporation, Applied Materials, Inc., SUSS MicroTec SE, Canon Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithography Systems Market Strategic Shifts & Innovations
Patterning technology is bifurcating between extreme ultraviolet dominance at leading nodes and directed energy diversification for power and photonics applications, while regulatory chemistry constraints are forcing optical system redesign.
High-NA EUV lithography is migrating from research-phase demonstration to pilot line installation at foundries preparing for sub-2nm transistor geometries. Intel and Samsung are committing early capacity slots for 0.55 numerical aperture systems despite unresolved mask infrastructure gaps. This technology compression is squeezing alternative multi-patterning approaches out of the leading-edge roadmap.
The EU F-Gas Regulation is prohibiting hydrofluorocarbon use in immersion lithography cooling loops from 2027, compelling equipment makers to qualify hydrofluoroolefin and natural refrigerant alternatives. Nikon Corporation's ArF systems face the steepest redesign burden given their dependence on precision thermal stability. European foundries with existing immersion fleets are accelerating replacement evaluations to avoid stranded asset risk.
After-sales service unbundling is fragmenting lithography equipment contracts as foundries negotiate source availability and preventive maintenance separately from core system warranties. TSMC and Samsung are driving this disaggregation to capture internal maintenance capabilities and reduce vendor lock-in. This shift is most pronounced in Taiwan, where captive service teams now handle 40-50% of non-critical module exchanges.
Lithography Systems Market Segmentation
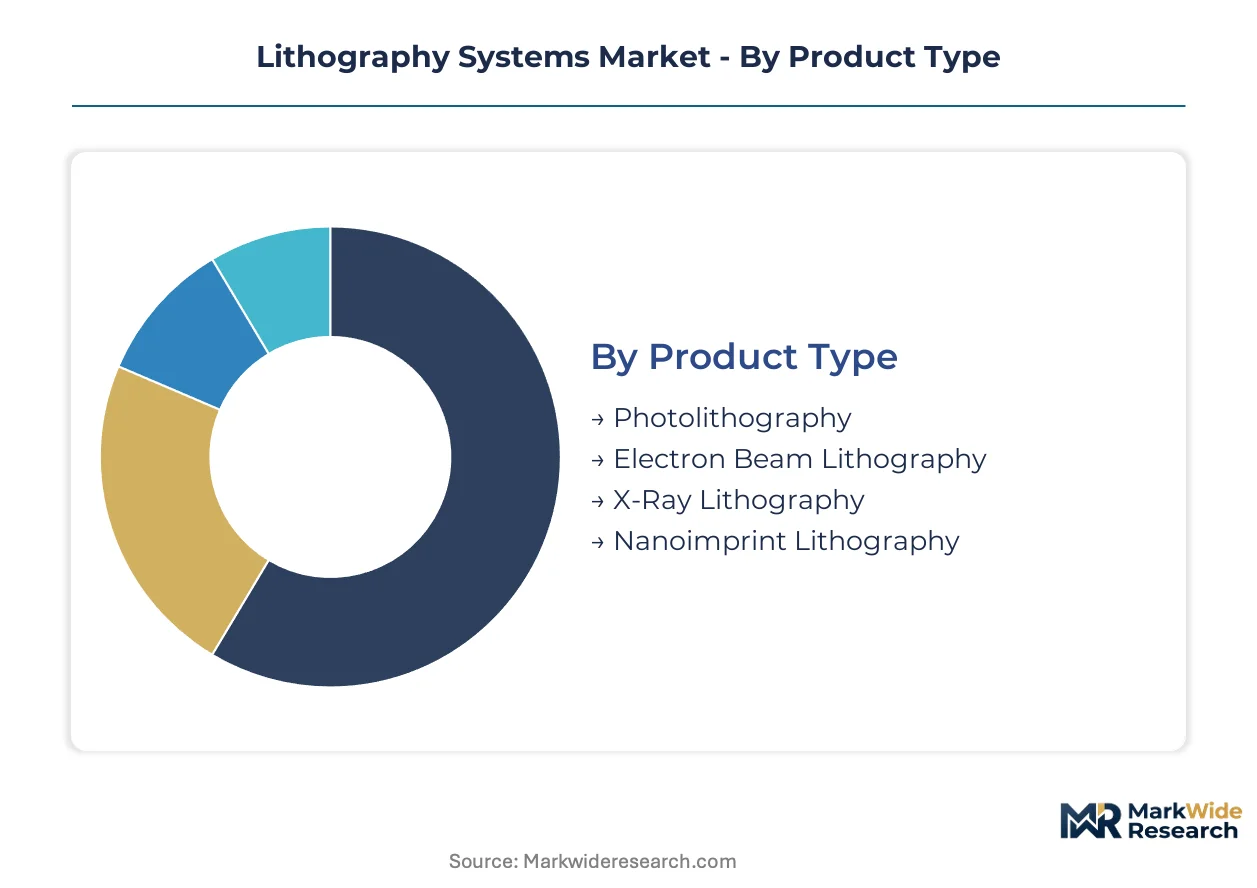
Segmentation in lithography systems reveals how capital allocation splits between leading-edge node production and mature technology servicing. Equipment specifications, wavelength requirements, and end-user integration complexity create distinct purchasing patterns across product categories.
Product Type:
Cost tier determines equipment accessibility and replacement cycles across fabrication facilities.
- Photolithography:Optical projection systems using 193 nm ArF or 248 nm KrF lasers dominate wafer throughput in high-volume manufacturing. Foundries in Taiwan and South Korea concentrate demand for immersion variants as they scale sub-3nm logic capacity.
- Electron Beam Lithography:Direct-write systems eliminate photomask dependency through focused electron beam scanning, enabling sub-10 nm resolution for prototyping. Research institutes in the Netherlands and Japan deploy these for photomask fabrication and advanced packaging development where volume economics favor flexibility over speed.
- X-Ray Lithography:Synchrotron-based proximity printing serves niche MEMS and sensor applications requiring high aspect ratio structures.
- Nanoimprint Lithography:Mechanical pattern transfer through template pressing targets LED and photonics manufacturing where cost sensitivity exceeds resolution requirements.
Photolithography holds installed capacity. Electron Beam Lithography is rotating up the share rankings.
Technology:
Application requirements split the market between resolution-driven leading nodes and throughput-driven mature manufacturing.
- Extreme Ultraviolet Lithography:13.5 nm wavelength systems using reflective optics enable single-exposure patterning at sub-7 nm nodes. ASML's exclusive production position forces foundries into multi-year co-development commitments, concentrating deployment in Taiwan and South Korea.
- Optical Lithography:Deep ultraviolet systems at 193 nm and 248 nm wavelengths sustain volume production at 28 nm and above. Nikon Corporation and Canon Inc. compete across immersion and dry variants for power semiconductor and display panel applications.
- Maskless Lithography:Programmable pattern generation without fixed reticles supports low-volume prototyping and security chip customization.
- 3D Lithography:Multi-layer stacking patterning addresses advanced packaging and memory cube architectures.
Optical Lithography retains volume leadership. Extreme Ultraviolet Lithography commands the steepest expansion trajectory in capital allocation.
Application:
Customer type shapes equipment specification priorities across semiconductor and adjacent industries.
- Semiconductors:Logic and memory fabrication demands the tightest overlay precision and lowest defectivity. EUV layer counts multiply as TSMC and Samsung advance sub-3nm process nodes, pulling scanner allocation toward East Asian manufacturing clusters.
- MEMS:Micro-electromechanical systems require thick resist processing and high aspect ratio etching compatibility. Automotive sensor programs in Germany and Japan drive stepper demand for accelerometer and gyroscope manufacturing.
- Microfluidics:Lab-on-chip devices prioritize substrate compatibility over resolution extremes.
- Displays:OLED and micro-LED backplane patterning at Gen 6 and Gen 8.5 substrate sizes revives large-field stepper demand in South Korea and China.
Semiconductors anchor revenue concentration. Displays is gaining share fastest as panel manufacturers refresh capacity.
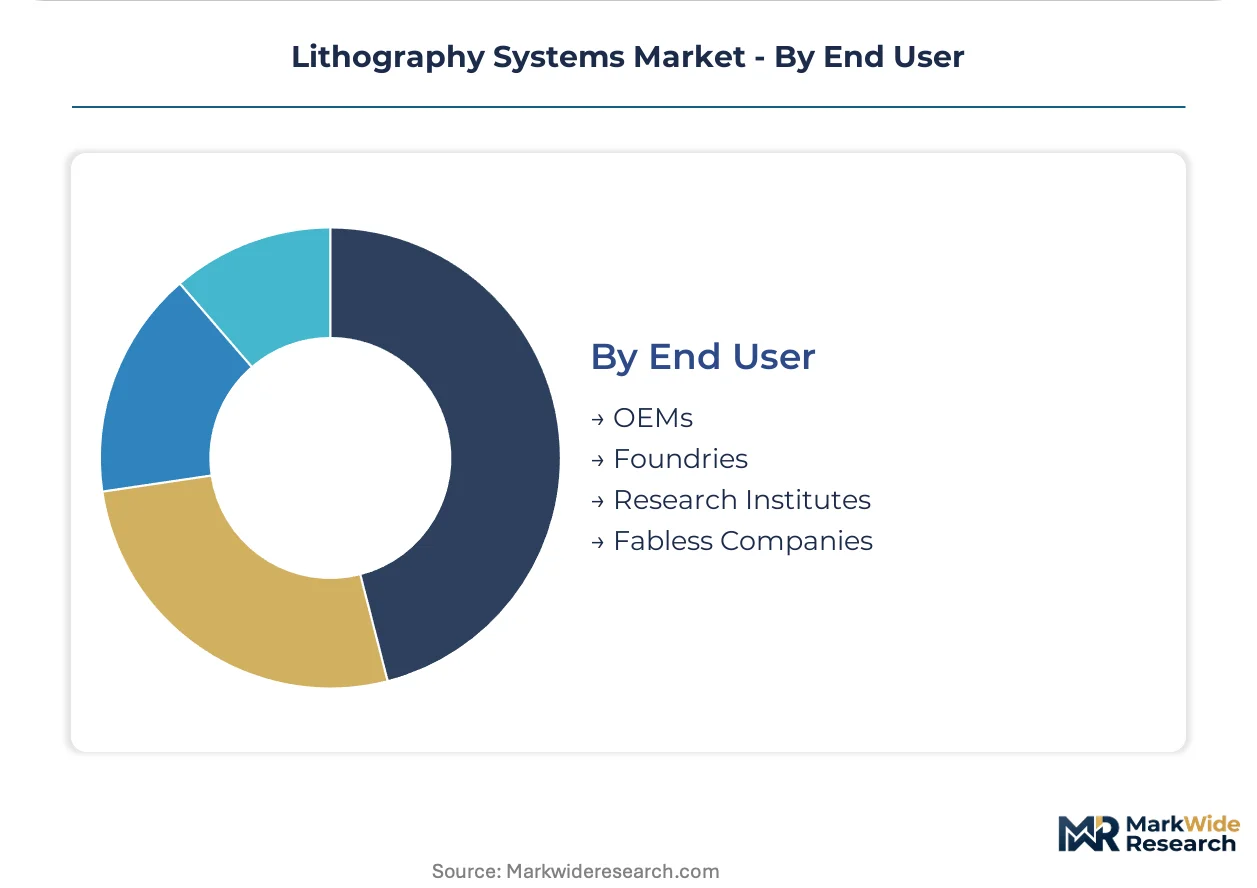
End User:
Volume scale and integration depth create distinct procurement patterns across the value chain.
- Foundries:Merchant manufacturing facilities consolidate the largest equipment budgets and most aggressive technology roadmaps. TSMC and Samsung's EUV-intensive expansion in Taiwan and South Korea is concentrating scanner allocation and reshaping vendor access to leading-edge capability.
- Research Institutes:Academic and government laboratories focus on next-generation patterning method development. IMEC in Belgium and imec's affiliates in Japan pre-qualify High-NA EUV optics, creating pull-through demand for metrology and mask infrastructure.
- OEMs:Integrated device manufacturers with captive fabrication maintain selective leading-edge investment.
- Fabless Companies:Design houses without manufacturing assets access lithography capacity through foundry partnerships rather than direct equipment procurement.
Foundries dominate capital deployment. Research Institutes is climbing the fastest in equipment sophistication requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI coordinates export controls with Dutch and US regulators, concentrating advanced equipment access in Japanese manufacturing corridors. Equipment allocation flows toward foundry clusters in Taiwan and South Korea, while European environmental regulations reshape cooling system designs.
Taiwan
TSMC expands EUV-intensive capacity for sub-3nm logic production, pulling scanner allocation toward Hsinchu and Tainan Science Parks. The island's environmental protection administration enforces fluorinated compound monitoring alongside industrial development. Taichung's precision machinery corridor supplies metrology and automation components for leading-edge fabs.
South Korea
Samsung accelerates EUV layer counts for advanced memory and logic processes, concentrating demand in Pyeongtaek and Hwaseong complexes. The Ministry of Trade, Industry and Energy administers semiconductor equipment import certifications under multilateral control frameworks. Yongin's cluster hosts mask blank suppliers qualifying next-generation optics.
Netherlands
ASML's Veldhoven headquarters anchors EUV scanner production, with IMEC pre-qualifying High-NA optics in Eindhoven's Brainport region. The F-Gas Regulation forces cooling system redesigns for immersion tools serving European foundries. Delft's technical university corridor feeds plasma physics and optical engineering talent into equipment supply chains.
Japan
Nikon and Canon sustain ArF immersion and i-line/KrF tool production for mature nodes and power semiconductors, with manufacturing concentrated in Kumagaya and Utsunomiya. METI's export control coordination with Dutch and US authorities shapes equipment access channels. Hiroshima's semiconductor materials cluster supplies photoresist and specialty chemicals under REACH-aligned registration protocols.
United States
Intel commits early High-NA EUV capacity slots for sub-2nm development in Hillsboro, Oregon and Chandler, Arizona. The Department of Commerce administers foreign direct product rules affecting equipment re-export to Chinese fabs. Albany's NY CREATES complex hosts lithography research partnerships bridging semiconductor research institutes and equipment makers.
Lithography Systems Market Key Industry Players
EUV monopoly holders and optical diversification specialists split the market into non-overlapping capability zones. ASML's exclusive production position forces foundries into multi-year co-development commitments, while Nikon and Canon compete for mature-node and specialty applications. Strategic archetypes include wavelength-dominant technology owners, precision optics integrators, and process-specific equipment diversifiers. Competitive moves center on long-term service contract unbundling and geographic access negotiations under export control frameworks.
Within the wavelength-dominant tier, ASML Holding N.V. and Nikon Corporation occupy positions reflecting their respective EUV and ArF immersion specializations. ZEISS Group anchors the precision optics archetype through its mirror production exclusivity. Canon Inc. exemplifies the diversification strategy, sustaining exposure across i-line, KrF, and display panel applications. These three named entities represent the structural concentration of equipment supply, with their geographic origins in the Netherlands, Japan, and Japan respectively shaping regional access patterns.
| Leading Market Players |
|---|
| KLA Corporation |
| ZEISS Group |
| ASML Holding N.V. |
| Veeco Instruments Inc. |
| TRUMPF |
| Nikon Corporation |
| Applied Materials, Inc. |
| SUSS MicroTec SE |
| Canon Inc. |
| Others |
Cost & Logistics Intelligence
ZEISS Group's exclusive mirror production for EUV systems creates single-source dependency that widens pricing spreads between configured-to-order leading-edge scanners and standard ArF immersion platforms while compressing procurement timelines for foundries locked into ASML co-development agreements. This concentration dynamic forces buyers to accept bundled long-term service contracts or face allocation penalties, reshaping how equipment makers structure tiered offerings across technology generations.
Pricing Analysis
Configured-to-order EUV systems command substantial premiums over standard ArF immersion configurations due to ASML's monopoly position and foundry co-development commitments. Price differentiation rests on customization depth and after-sales service bundling, with leading-edge nodes requiring dedicated field engineering support. Pricing pressure stems from foundry demands to unbundle preventive maintenance from core system warranties, particularly in Taiwan where captive service teams now handle substantial non-critical module exchanges. IDMs with captive fabrication show least price sensitivity given technology roadmap imperatives, while display panel manufacturers exhibit highest sensitivity as they evaluate stepper refresh cycles against OLED demand volatility.
Supply Chain Analysis
Tariff exposure between the Netherlands and China dominates supply chain risk calculations as METI-coordinated export controls reshape equipment access channels. Mirror substrates from Germany, laser-produced plasma sources from the United States, and precision motion stages from Japan constitute critical input dependencies. Distribution runs through direct sales channels anchored by long-term co-development agreements, with foundries in Taiwan and South Korea receiving preferential allocation. Single-source vulnerability at the EUV optics tier creates cascading qualification delays when mirror blank defectivity exceeds detection thresholds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where regulatory entrenchment through METI-Dutch-US export control coordination creates structural barriers that protect incumbent positions while constraining new entrant pathways.
For Market Incumbents: Insulate EUV allocation leverage by deepening captive service capabilities in Taiwan and South Korea, converting foundry maintenance disaggregation into recurring revenue streams. Secure alternative cooling chemistry qualifications ahead of EU F-Gas Regulation deadlines to avoid stranded asset exposure for immersion fleet customers. METI alignment on dual-use restrictions provides channel control advantages that should be reinforced through Japanese material supplier partnerships. For New Entrants and Emerging Players: Pursue electron beam lithography white space in photomask fabrication and advanced packaging prototyping where volume economics favor flexibility over throughput. Target research institutes in the Netherlands and Japan as beachhead accounts given their High-NA EUV pre-qualification activities creating pull-through demand for metrology infrastructure. Position around maskless patterning for security chip customization as a go-to-market angle distinct from volume manufacturing competition. For Investors and Strategic Acquirers: The market sits at a technology transition phase that favors precision optics specialists with EUV mirror production capabilities or electron beam direct-write innovators addressing mask infrastructure gaps. Long-term viability over the next decade hinges on exposure to sub-3nm foundry expansion or power semiconductor electrification tailwinds. Watch High-NA EUV pilot line announcements from Intel and Samsung as the signal indicating inflection timing for next-generation optics demand.| Strategic Initiative | Industry Significance |
|---|---|
| High-NA EUV Capacity Commitment | Intel and Samsung pilot line reservations signal sub-2nm manufacturing readiness. |
| Alternative Cooling Chemistry Qualification | Nikon Corporation's hydrofluoroolefin transition addresses EU F-Gas Regulation compliance. |
| Service Contract Unbundling | TSMC and Samsung captive maintenance teams reduce vendor lock-in across Taiwan fabs. |
| Power Semiconductor Stepper Deployment | Canon Inc. captures silicon carbide substrate patterning from automotive electrification. |
| Mask Blank Defectivity Reduction | Yongin cluster suppliers accelerate multilayer qualification cycles for next-generation optics. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with lithography equipment executives, foundry procurement directors, photoresist R&D leads, and metrology specialists; and secondary validation through SEC filings from ASML and Nikon, ECHA REACH registration databases, METI export control notices, and customs equipment trade records. Bottom-up triangulation against top-down market sizing ensured segmentation integrity across technology tiers.
Forecast inputs considered foundry node migration roadmaps, EU layer count expansion trajectories, and display panel capacity refresh cycles across the projection horizon. Segmentation dimensions modeled include wavelength technology, end-user integration depth, application requirements, and regional regulatory cluster. CAGRs were derived from equipment shipment patterns and capital expenditure disclosures by leading foundries, with High-NA EUV readiness timelines and F-Gas Regulation implementation schedules serving as industry-specific forecast modifiers.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles or multilateral export control tightening would shift the trajectory. Forecasts reflect assumptions about foundry co-development commitment durability and mirror blank yield improvement rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Global Semiconductor Thermal Evaporators Market
Semiconductor Equipment
Asia-Pacific Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Lithography Equipment Market
Semiconductor Equipment
APAC Die Attach Equipment Market
Semiconductor Equipment
Wafer Processing Equipment Market
Semiconductor Equipment
Cathode Stripping Machines Market
Semiconductor Equipment
Vacuum Chambers Market
Semiconductor Equipment
Sputtering Equipment Cathode Market
Semiconductor Equipment
Dry Reactor Market
Semiconductor Equipment
Automatic Flip Chip Bonders Market
Semiconductor Equipment
SMT Machine Market
Semiconductor Equipment
Wet Based Wafer Cleaning Equipment Market
Semiconductor Equipment
Solder Ball Mounter Market
Semiconductor Equipment
Ion Beam Etching System Market
Semiconductor Equipment
Global Semiconductor Stepper Systems Market
Semiconductor Equipment
North America Semiconductor Etch Equipment Market