
 Semiconductor Equipment Market | 2026-2036
Semiconductor Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Equipment Market Outlook
ISO 14644 cleanroom certification is unwinding the competitive field for sub-10nm equipment supply, forcing vendors to rebuild qualification protocols from the ground up. Applied Materials leverages its installed base in atomic layer deposition to sustain pricing power across logic foundry accounts. ASML dominates extreme ultraviolet lithography through captive optics supply chains that no competitor can replicate. Tokyo Electron anchors etch and deposition market presence with process modules qualified at every leading memory manufacturer.
Semiconductor equipment encompasses the precision machinery used to manufacture integrated circuits, including systems that handle wafer processing, metrology, and test functions with tolerances measured in angstroms. These tools perform photolithography, ion implantation, chemical vapor deposition, and plasma etching to pattern, dope, deposit, and remove materials on silicon substrates for electronic device fabrication. Wafer fabrication equipment captures the largest value pool as lithography and deposition systems command unit prices in the hundreds of millions of dollars. Test equipment represents a faster-growing segment as heterogeneous integration and chiplet architectures multiply the die-count per package requiring validation. Assembly equipment remains more fragmented, with margin pressure concentrated in legacy wire bonding as advanced packaging shifts toward thermocompression and hybrid bonding methods.
The EPA regulates perfluorinated compound emissions from semiconductor fabs through mandatory abatement requirements that shape etch equipment design specifications. REACH and RoHS constrain material inputs for equipment components sold into European fabs, while China's GB standards and MIIT directives govern local procurement eligibility for Naura Technology Group and AMEC. KLA Corporation navigates dual-use export control frameworks that restrict inspection tool sales to specified Chinese entities. Stakeholders must monitor how the EU AI Act and Chips Act intersect with equipment qualification timelines, since regulatory compliance now determines market access faster than technical performance differentiation alone.
Market Dynamics
Advanced node migration below 3nm is compressing equipment qualification cycles while simultaneously extending tool development timelines, creating a structural mismatch between foundry capex commitments and vendor delivery capacity.
Growth Catalysts
- EU Chips Act subsidies:European governments are redirecting public funds toward domestic fabrication capacity, creating dedicated procurement pipelines for lithography and deposition equipment suppliers.
- Heterogeneous integration:Chiplet architectures are multiplying die-count per package, expanding addressable demand for advanced packaging bonders and inspection systems.
- Memory technology transitions:High-bandwidth memory and 3D NAND stacking are forcing capacity expansions at Korean and Taiwanese manufacturers, pulling etch and deposition tool orders forward.
Market Restraints
- Optics supply concentration:Extreme ultraviolet lithography depends on single-source Zeiss mirror substrates, creating catastrophic failure risk for any fab scaling below 7nm.
- EPA abatement mandates:Perfluorinated compound emission rules are forcing costly scrubber retrofits on etch equipment, inflating total cost of ownership for legacy tool installations.
- Technical limitation at atomic scale:Deposition uniformity control breaks down below 5nm feature sizes, requiring entirely new chamber designs that extend development cycles by 18-24 months.
Strategic Opportunities
- India semiconductor mission:The country's PLI scheme for fabs is creating first-mover advantage for equipment vendors establishing local service infrastructure ahead of greenfield construction.
- Hybrid bonding adoption:Thermocompression and direct copper-to-copper bonding are displacing wire bonding in high-performance computing packages, opening equipment white space.
- Carbon border adjustments:EU Green Deal mechanisms are favoring equipment with verified low-emission manufacturing processes, creating premium positioning for certified suppliers.
Industry Challenges
- ISO 14644 cleanroom certification timelines:Sub-10nm qualification protocols require 12-18 month revalidation cycles that delay revenue recognition and strain field engineering resources.
- Atomic-scale metrology talent scarcity:Fewer than 200 engineers globally possess combined expertise in ellipsometry, scatterometry, and machine learning for defect classification at angstrom resolution.
- Legacy tool integration friction:300mm wafer platforms from the 2010s lack data interfaces required for AI-driven process control, forcing expensive middleware development or premature replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Equipment Market |
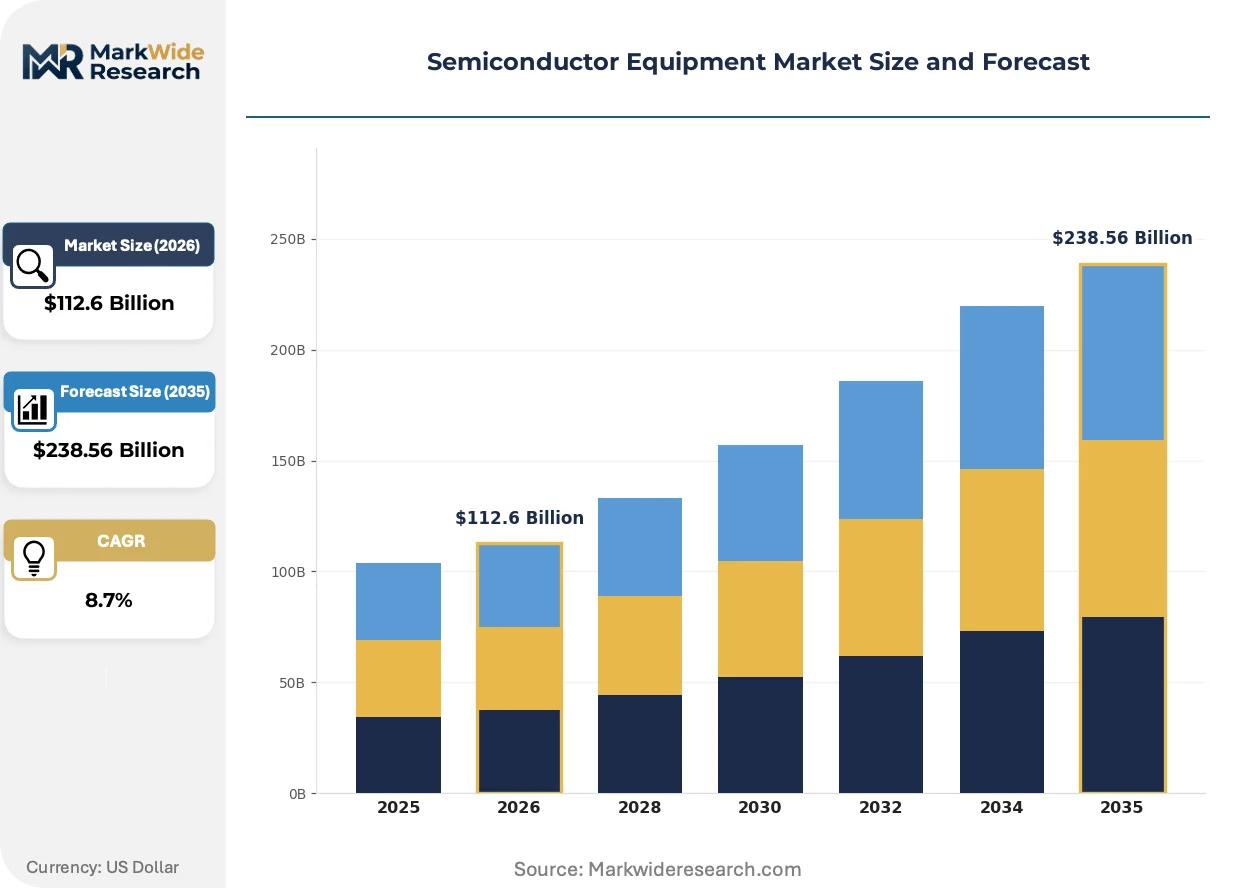
| Market Size in 2026 | $112.6 Billion |
| Market Size in 2035 | $238.56 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wafer Fabrication Equipment, Test Equipment, Assembly Equipment, Etching Equipment Technology: Photolithography, Ion Implantation, Chemical Vapor Deposition, Mask/Etch End User: Consumer Electronics, Automotive, Telecommunications, Aerospace Application: Memory Devices, Logic Devices, Power Devices, Sensors |
| Companies Covered | Tokyo Electron, Screen Holdings, ASML, Naura Technology Group, Teradyne, Applied Materials, KLA Corporation, AMEC, Lam Research, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Equipment Market Strategic Shifts
Equipment architecture is pivoting from standalone tools toward integrated process clusters where wafer handling robotics and real-time metrology merge into unified manufacturing cells.
Atomic layer etch is fragmenting process development workflows by enabling angstrom-level material removal control that thermal etch cannot achieve. Memory manufacturers are adopting it first for 3D NAND staircase profile tuning. The technology is fragmenting vendor specialization boundaries as etch suppliers must now master deposition chemistry to compete.
REACH substance restrictions are forcing material substitutions in chamber components sold into European fabs, particularly for fluoropolymer seals and electrostatic chuck ceramics. Equipment vendors are redesigning process kits to eliminate restricted perfluorinated substances before 2027 enforcement deadlines. This regulatory pressure is compressing qualification timelines for alternative material suppliers.
Foundry procurement teams are consolidating vendor relationships into multi-year framework agreements that bundle equipment, consumables, and predictive maintenance services. This contractual shift is displacing transactional spot purchasing for lithography and deposition tools. Taiwan and South Korea are furthest along in this transition, with framework coverage now exceeding 60% of leading-edge capex.
Semiconductor Equipment Market Segmentation
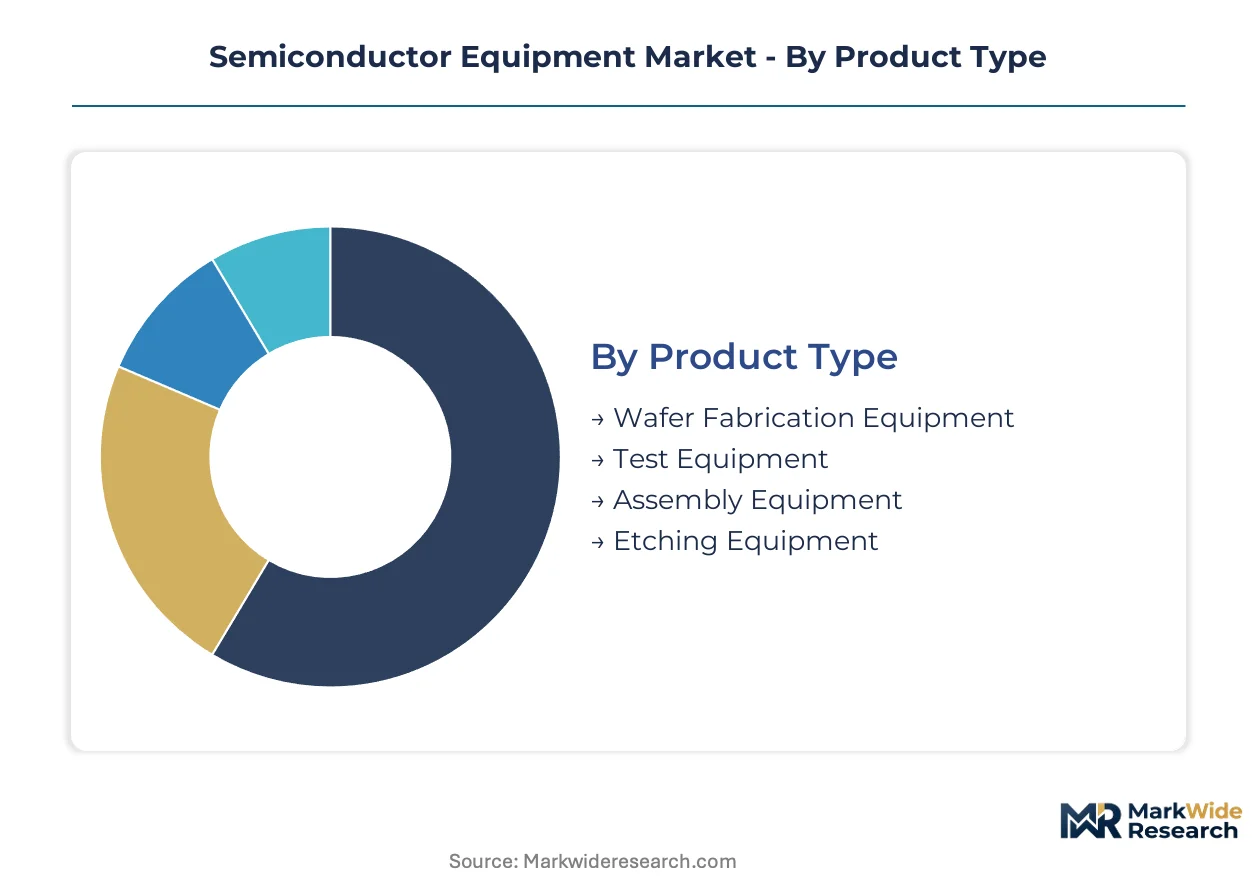
Segmentation in semiconductor equipment reveals how tool specifications cascade through procurement channels. Foundry operators in Taiwan and South Korea route lithography and deposition systems through multi-year framework agreements, while memory manufacturers in Korea favor spot purchasing for etch equipment upgrades.
Product Type:
Equipment flows through distinct channel architectures based on capital intensity and service attachment rates.
- Wafer Fabrication Equipment:Lithography and deposition systems dominate capital allocation with unit prices reaching hundreds of millions of dollars. TSMC and Samsung anchor procurement gravity in Hsinchu and Pyeongtaek, where multi-year service bundling now exceeds 60% of leading-edge capex.
- Test Equipment:Heterogeneous integration and chiplet architectures multiply die-count per package, expanding validation demand. Korean memory manufacturers pull inspection tool orders forward as high-bandwidth memory transitions accelerate.
- Assembly Equipment:Thermocompression and hybrid bonding methods displace legacy wire bonding in high-performance computing packages. The segment remains fragmented with margin pressure concentrated in older bonding technologies.
- Etching Equipment:Atomic layer etch enables angstrom-level material removal control that thermal processes cannot achieve. Tokyo Electron anchors market presence with process modules qualified at every leading memory manufacturer.
By volume, wafer fabrication equipment leads. By growth pace, test equipment is climbing the fastest.
Technology:
Cost tier stratification separates billion-dollar lithography platforms from sub-fifty-million-dollar implant systems.
- Photolithography:Extreme ultraviolet systems command the highest capital allocation with single-source Zeiss mirror substrates creating supply concentration. ASML dominates through captive optics supply chains that no competitor can replicate.
- Ion Implantation:Doping precision requirements tighten below 3nm nodes, extending qualification cycles. Applied Materials leverages its installed base to sustain pricing power across logic foundry accounts.
- Chemical Vapor Deposition:Deposition uniformity control breaks down below 5nm feature sizes, forcing entirely new chamber designs. Atomic layer deposition variants are gaining share in staircase profile tuning for 3D NAND.
- Mask/Etch:Atomic layer etch fragments vendor specialization boundaries as suppliers must master deposition chemistry to compete. Memory manufacturers adopt it first for 3D NAND staircase profile tuning.
By capital intensity, photolithography sits at the premium tier. By technical momentum, atomic layer variants within etch are expanding most quickly.
End User:
Application maturity varies sharply across end-use sectors, with automotive qualification timelines running 3-4x longer than consumer electronics.
- Consumer Electronics:Smartphone and PC demand cycles drive foundry capacity planning with the shortest procurement lead times. TSMC's N3 node ramp concentrates equipment orders in this channel.
- Automotive:Functional safety requirements under ISO 26262 extend equipment qualification by 18-24 months. Power device and sensor applications pull specialized etch and implant tool configurations.
- Telecommunications:Base station and optical networking chip demand concentrates in mature node equipment. European fab expansions under the EU Chips Act are redirecting subsidy flows toward this procurement pipeline.
- Aerospace:Radiation-hardened device requirements constrain supplier pools to qualified vendors with defense contracting history. Dual-use export controls restrict inspection tool sales to specified entities.
By equipment volume, consumer electronics leads. By qualification complexity, aerospace sets the standard.
Application:
Customer type concentration splits between integrated device manufacturers and pure-play foundries with divergent technology roadmaps.
- Memory Devices:High-bandwidth memory and 3D NAND stacking force capacity expansions at Korean manufacturers. Etch and deposition tool orders concentrate in Samsung and SK Hynix facilities.
- Logic Devices:Advanced node migration below 3nm compresses equipment qualification cycles while extending tool development timelines. A structural mismatch exists between foundry capex commitments and vendor delivery capacity.
- Power Devices:Silicon carbide and gallium nitride transitions pull specialized implant and anneal equipment. Automotive electrification drives demand concentration in this application.
- Sensors:MEMS and image sensor fabrication requires modified deposition and etch platforms with relaxed overlay requirements. The segment attracts second-tier equipment vendors with cost-optimized offerings.
By revenue concentration, logic devices lead. By expansion trajectory, power devices are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Subsidy programs and industrial policy are redrawing equipment procurement geography. Government incentives now determine fab location decisions faster than labor cost or infrastructure quality.
United States
CHIPS and Science Act disbursements are unlocking construction at greenfield sites in Arizona and Texas. EPA perfluorinated compound abatement rules shape etch equipment specifications for domestic fabs. Intel's Oregon and Arizona facilities anchor demand concentration for lithography and deposition systems.
South Korea
Samsung and SK Hynix are expanding Pyeongtaek and Yongin complexes for high-bandwidth memory production. MFDS equipment safety frameworks govern import qualification timelines for foreign vendors. Seoul Capital Area fabs pull etch and deposition tool orders forward as 3D NAND stacking accelerates.
Japan
Tokyo Electron and Screen Holdings anchor domestic supply chain gravity in etch and cleaning equipment. METI semiconductor revival subsidies redirect capital toward legacy node capacity preservation. Kyoto-Osaka industrial corridor hosts precision optics and ceramics suppliers feeding lithography tool manufacturers.
China
MIIT domestic procurement directives favor Naura Technology Group and AMEC for mature node equipment. GB standards constrain foreign vendor eligibility for subsidy-backed fab projects. Yangtze River Delta clusters in Shanghai and Hefei concentrate capacity expansion for 28nm and above processes.
Germany
EU Chips Act funds are flowing to Dresden and Magdeburg fab construction with Intel and TSMC commitments. REACH substance restrictions force chamber component redesigns for equipment sold into European fabs. Saxony's Silicon Saxony cluster anchors lithography and deposition demand as Infineon expands power semiconductor capacity.
Semiconductor Equipment Market Competitive Environment
Player mix skews toward integrated platform specialists with captive technology stacks. Lithography and deposition segments concentrate around vendors controlling irreplaceable subsystems. Three archetypes dominate: optics-captive lithography houses, process-module integrators spanning etch-through-deposition, and regional champions serving protected domestic markets. Competitive moves center on multi-year framework agreements bundling equipment with consumables and predictive maintenance, plus backward integration into critical component supply.
Within the optics-captive tier, ASML occupies a position no competitor can replicate through its Zeiss mirror supply exclusivity. Applied Materials and Lam Research exemplify the integrated platform model with process modules qualified across logic and memory accounts. Tokyo Electron anchors etch and deposition presence with tools installed at every leading memory manufacturer. Regional champions Naura Technology Group and AMEC sit within China's protected procurement ecosystem, capturing domestic mature-node demand.
| Leading Market Players |
|---|
| Tokyo Electron |
| Screen Holdings |
| ASML |
| Naura Technology Group |
| Teradyne |
| Applied Materials |
| KLA Corporation |
| AMEC |
| Lam Research |
| Others |
Value Chain & Pricing Dynamics
ISO 14644 cleanroom certification gates both supplier qualification and price stratification simultaneously, as sub-10nm equipment vendors must rebuild protocols from the ground up while foundry procurement teams extract premium positioning for certified suppliers.
Pricing Analysis
Certification level (ISO 14644-grade) creates the primary spread between qualified vendors and second-tier competitors. Equipment pricing stratifies across premium, standard, and economy tiers based on node qualification status and service bundling intensity. Cost compression in legacy deposition tools is intensifying because EPA abatement mandates inflate total cost of ownership for non-compliant installations. Memory manufacturers exhibit the highest price sensitivity due to cyclical capacity planning, while logic foundries prioritize qualification speed over unit cost.
Supply Chain Analysis
Inventory cycles for extreme ultraviolet optics extend 18-24 months, constraining fab construction schedules regardless of capital availability. Zeiss mirror substrates from Germany and fluoropolymer seals from Japan anchor irreplaceable input dependencies. Single-source vulnerability concentrates in the lithography optics tier where no qualified alternative exists for sub-7nm production. Distribution runs through direct vendor-fab relationships with multi-year framework agreements displacing spot purchasing for leading-edge tools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor equipment sits in early-cycle expansion as heterogeneous integration multiplies die-count per package and pulls advanced packaging tool orders forward.
For Market Incumbents: Shield installed base revenue by embedding predictive maintenance algorithms into process modules before emerging analytics vendors capture service attachment. Deepen backward integration into chamber ceramics and electrostatic chuck manufacturing to defend margin position against material cost volatility. Prioritize ISO 14644 revalidation acceleration to compress competitor qualification windows.
For New Entrants and Emerging Players: Lead with specialized metrology tools for atomic-scale defect classification, where fewer than 200 qualified engineers globally create acute capability scarcity. Target India's PLI-backed fab construction for first-mover service infrastructure establishment ahead of greenfield equipment procurement. Pursue joint development agreements with mature-node memory manufacturers seeking etch equipment alternatives.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision optics and ceramics suppliers feeding lithography tool manufacturers. Long-term viability hinges on captive technology stacks that survive node transition cycles. Watch hybrid bonding equipment qualification timelines at Korean memory manufacturers as the inflection signal for advanced packaging capital reallocation.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Framework Agreement | TSMC and Samsung now bundle lithography equipment with consumables and predictive maintenance services. |
| Backward Integration into Optics | ASML's Zeiss mirror exclusivity demonstrates how captive supply chains create unassailable pricing power. |
| Atomic Layer Etch Platform Launch | Tokyo Electron fragments vendor boundaries by merging etch and deposition chemistry expertise. |
| India Service Infrastructure Pre-Positioning | Applied Materials and Lam Research establish field engineering ahead of PLI-scheme fab construction. |
| Carbon Border Adjustment Certification | EU Green Deal mechanisms favor equipment vendors with verified low-emission manufacturing processes. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with fab operations directors, equipment procurement managers, process integration engineers, and field service technicians; and secondary validation through SEC 10-K filings, customs import records, SEMI equipment billings data, and foundry capex announcements. Bottom-up equipment unit forecasts triangulated against top-down wafer capacity expansion projections.
Across the projection horizon, the analytical framework modeled segmentation by equipment type, technology node, end-use application, and regional subsidy regime. CAGRs derived from equipment shipment trajectories weighted by average selling price evolution and service attachment rate expansion. Forecast inputs incorporated lithography tool delivery backlogs, etch chamber qualification timelines, and memory manufacturer capacity utilization cycles.
The analysis sits within stated boundaries; outcomes outside sustained foundry capex commitment, stable export control frameworks, or continued EU Chips Act disbursement would require recalibration. Forecasts reflect documented assumptions regarding node migration pace and vendor delivery capacity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Electrostatic Chucks Market
Semiconductor Equipment
Global Cleanroom Technologies Market
Semiconductor Equipment
Global Battery Manufacturing Equipment Market
Semiconductor Equipment
North America Semiconductor Etch Equipment Market
Semiconductor Equipment
Semiconductor Laser Equipment Market
Semiconductor Equipment
Semiconductor Assembly Equipment Market
Semiconductor Equipment
Electrolytic Etching Machine Market
Semiconductor Equipment
United States Chip Mounter Market
Semiconductor Equipment
Middle East Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
X-Ray Lithography Equipment Market
Semiconductor Equipment
PVD Coaters Market
Semiconductor Equipment
Thin Wafer Processing and Dicing Equipment Market
Semiconductor Equipment
Europe Semiconductor Manufacturing Equipment Market
Semiconductor Equipment
Wafer CMP Machine Market
Semiconductor Equipment
Global Photoresist Market
Semiconductor Equipment
Wet Bench Market