
 SMT Machine Market | 2026-2036
SMT Machine Market Size, Share, and Industry Trends Forecast 2026-2036
SMT Machine Market Insights
The direct-to-factory equipment channel is rewriting how SMT machinery reaches contract manufacturers across Asia. ASMPT Ltd. leverages its placement systems portfolio to sustain dominance in high-speed assembly lines. Yamaha Motor Co., Ltd. anchors its position through precision motion control technologies that serve automotive tier-one suppliers. Panasonic Corporation differentiates via integrated process solutions spanning printing through inspection.
Surface mount technology equipment automates the placement and soldering of electronic components onto printed circuit boards using precision pick-and-place heads, stencil printers, and controlled thermal reflow profiles achieving placement accuracies below 30 microns. Pick and place machines command the largest equipment spend as miniaturization trends drive multi-head gantry architectures. Inspection machines represent the fastest-growing product category as automotive electronics fault tolerances tighten under functional safety mandates. Contract manufacturers concentrate procurement volume for reflow ovens and solder paste printers as they absorb OEM outsourcing.
China's MIIT enforces GB standards for equipment energy efficiency that filter import eligibility for European and Japanese suppliers. Japan's METI coordinates JIS certification pathways that govern SMT equipment interoperability with domestic electronics factories. Korea's MFDS and industrial safety frameworks shape cleanroom-compatible machine designs for semiconductor-adjacent assembly. Stakeholders must track how carbon accounting rules and supply chain traceability requirements alter capital equipment depreciation cycles and factory upgrade timing.
Market Dynamics
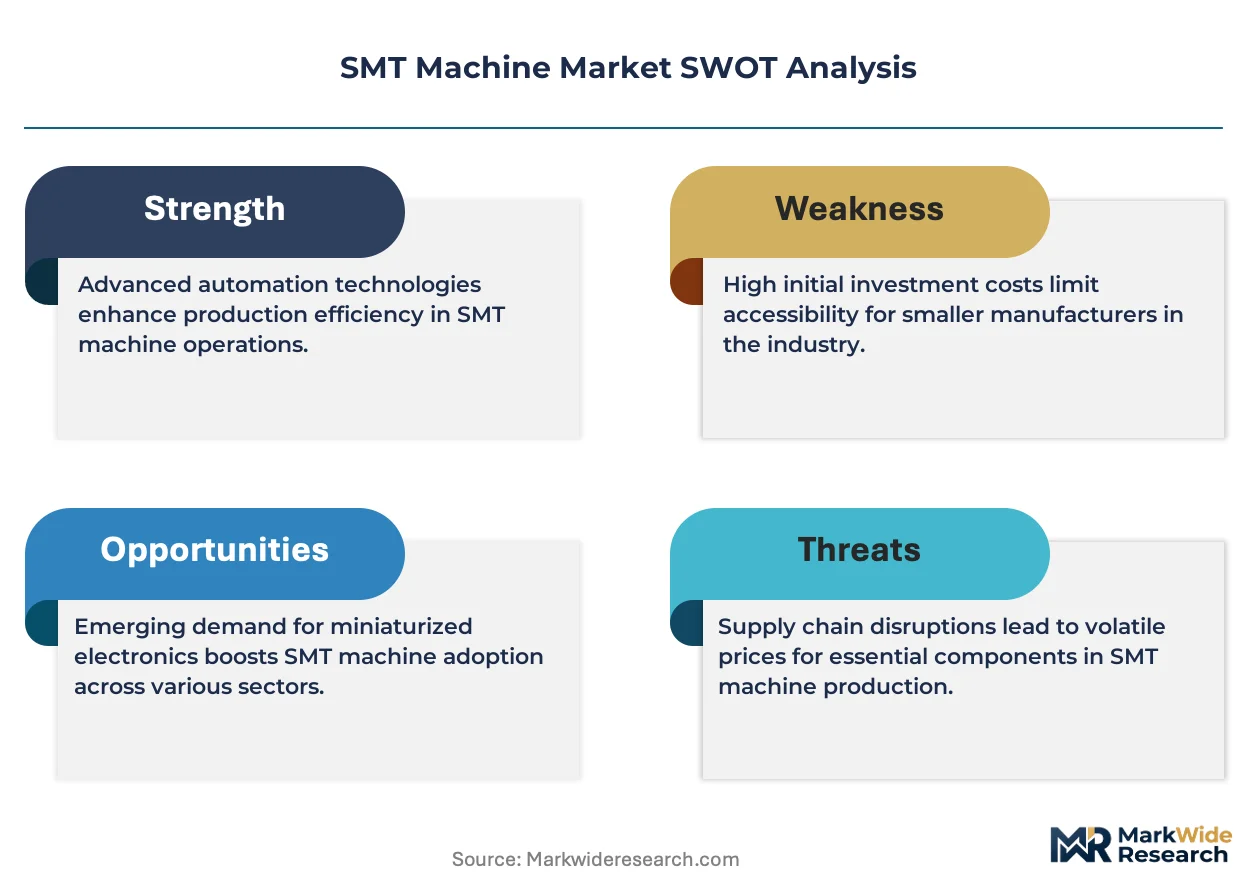
Electrification mandates across automotive OEMs are compressing SMT equipment refresh cycles as powertrain electronics demand higher-density PCB assembly with zero-defect tolerances.
Growth Catalysts
- Automotive functional safety mandates:ISO 26262 compliance requirements for ADAS modules are forcing tier-one suppliers to upgrade placement accuracy capabilities.
- China's dual carbon framework:GB standards for energy-efficient manufacturing equipment are redirecting procurement toward low-power reflow systems.
- Miniaturization in consumer wearables:0201 and 01005 component handling requirements are driving multi-head gantry replacements in Shenzhen contract manufacturers.
Market Restraints
- Specialized component supply concentration:High-precision linear motor drives for pick-and-place heads concentrate among Japanese and German suppliers.
- Technical throughput ceiling:Current gantry architectures face physical limits below 200,000 components per hour for micro-component placement.
- Import friction from GB certification:China's MIIT energy-efficiency testing protocols extend European equipment approval timelines by 8-14 months.
Strategic Opportunities
- India electronics manufacturing:PLI scheme incentives for mobile phone and component production are creating first-time SMT line demand in Noida and Sriperumbudur.
- AI-driven predictive maintenance:Machine learning integration with placement systems enables outcome-based service contracts for automotive tier-one suppliers.
- Semiconductor-adjacent assembly:Advanced packaging demand from Korea's MFDS-regulated facilities requires cleanroom-compatible equipment variants.
Industry Challenges
- Multi-disciplinary technician scarcity:SMT line operation now requires simultaneous expertise in precision mechanics, thermal profiling, and vision system calibration.
- Legacy MES integration complexity:Brownfield factories in Japan's industrial corridors struggle to connect new equipment to 1990s-era shop floor data architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | SMT Machine Market |
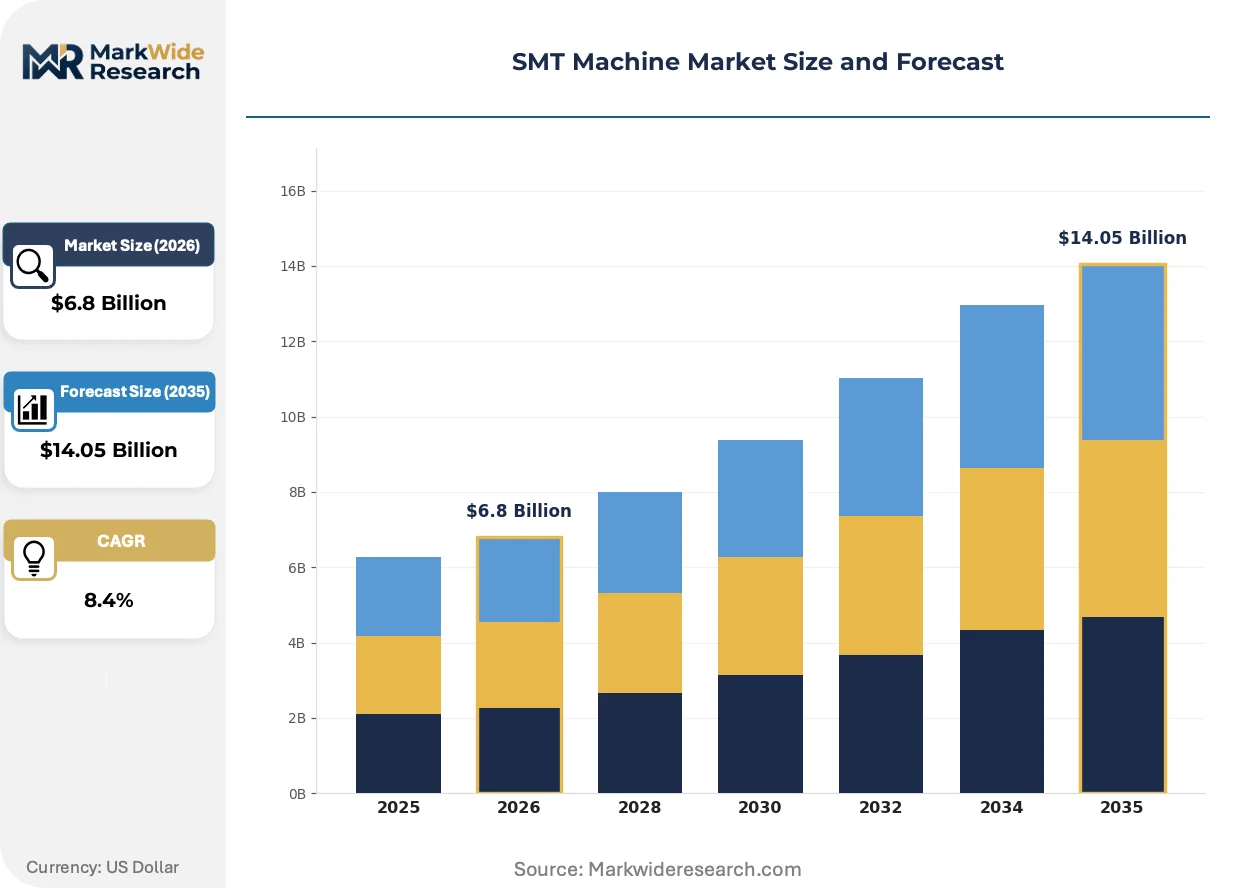
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pick and Place Machines, Solder Paste Printers, Reflow Ovens, Inspection Machines Technology: Surface Mount Technology, Through-Hole Technology, Hybrid Technology, Digital Printing Application: Consumer Electronics, Automotive Electronics, Telecommunications, Industrial Automation End User: OEMs, Contract Manufacturers, System Integrators, Aftermarket Providers |
| Companies Covered | ASMPT Ltd., Yamaha Motor Co., Ltd., JUKI Corporation, Panasonic Corporation, Fuji Corporation, Mycronic AB, Hanwha Precision Machinery, Europlacer, Koh Young Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
SMT Machine Market Trends and Innovations
Digital thread technologies are collapsing the traditional separation between SMT process steps, enabling real-time quality feedback loops that compress defect detection latency from hours to seconds.
Machine vision systems with sub-10-micron inspection resolution are digitizing quality assurance workflows across automotive electronics suppliers. Tier-one manufacturers in Germany and Japan are deploying these systems at line speed rather than as offline sampling stations. The shift is digitizing the traditional buffer between placement and reflow, eliminating separate inspection takt times.
EU CSRD disclosure requirements are mandating Scope 3 carbon accounting for capital equipment purchases, forcing European EMS providers to request energy-consumption documentation from SMT vendors. The regulation is reshaping RFP evaluation criteria toward lifecycle emissions rather than upfront capex. Automotive suppliers in Stuttgart and Munich are now weighting carbon intensity at 15-20% of total procurement scores.
Contract manufacturers are consolidating vendor relationships to secure priority allocation during equipment supply crunches. Foxconn and Jabil are reducing qualified machine suppliers from 5-6 to 2-3 per process step, trading price competition for delivery certainty. The behavior is most pronounced in Mexico and Vietnam, where greenfield factories lack established supplier networks and cannot absorb lead time volatility.
SMT Machine Market Segmentation
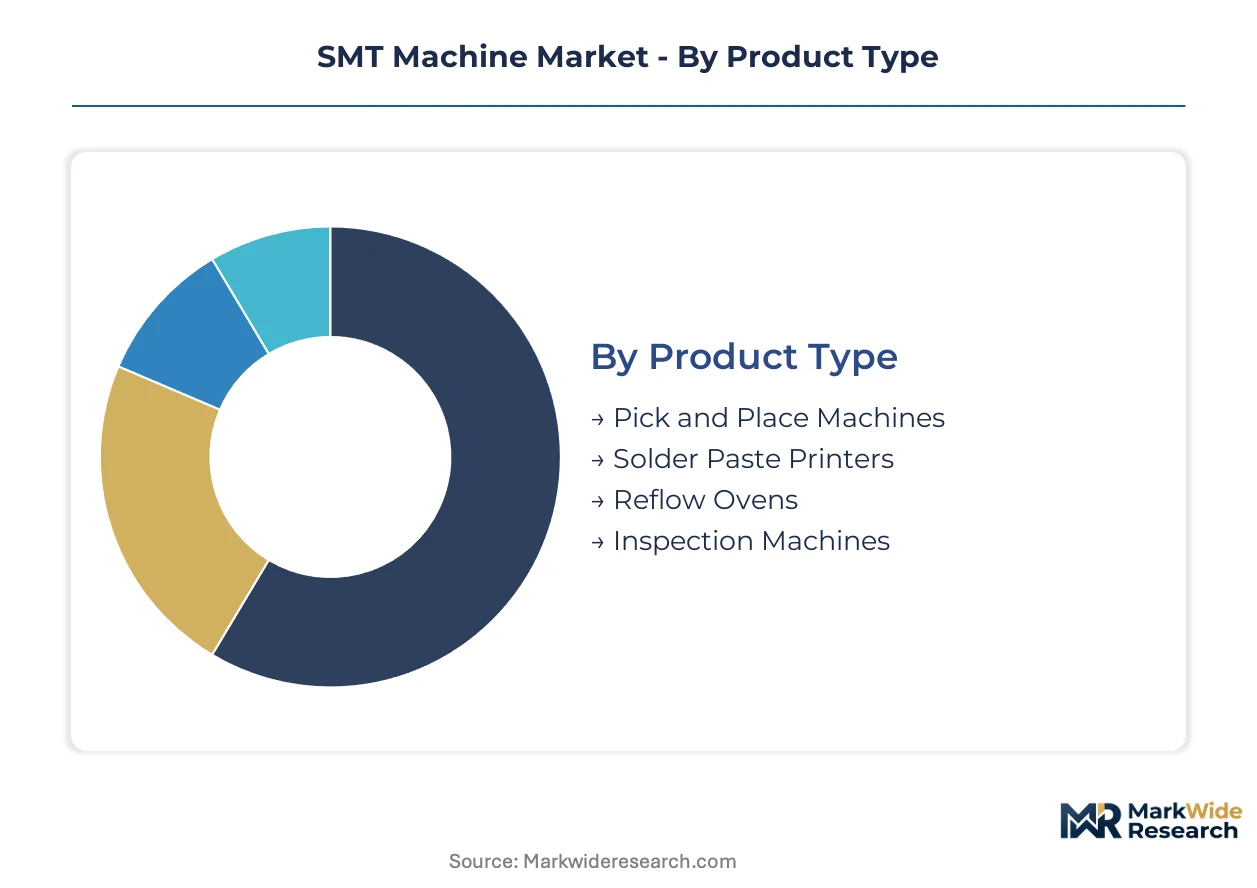
SMT machinery segmentation reveals how equipment specialization aligns with divergent manufacturing economics. Each dimension—product architecture, process technology, application intensity, and buyer structure—carries distinct procurement patterns and margin profiles that shape vendor strategy.
Product Type:
Equipment selection spans the full assembly workflow from solder deposition through final inspection, with capital allocation shifting toward quality assurance as defect costs escalate.
- Pick and Place Machines:Multi-head gantry systems execute component placement at sub-30-micron accuracy using linear motor drives and vision-guided heads. Shenzhen contract manufacturers and Seoul automotive tier-ones dominate procurement as 0201/01005 miniaturization forces gantry architecture refreshes.
- Inspection Machines:Machine vision systems with sub-10-micron resolution digitize quality assurance at line speed rather than offline sampling. Germany's automotive electronics suppliers and Japan's industrial automation OEMs are deploying these systems under ISO 26262 functional safety mandates.
- Solder Paste Printers:Stencil-based deposition systems control volume transfer efficiency for high-density PCB assemblies.
- Reflow Ovens:Controlled thermal profiling equipment manages solder joint formation across lead-free and low-temperature alloy chemistries.
Established volume favors pick and place systems; emerging adoption favors inspection machines.
Technology:
Process methodology selection reflects component packaging evolution and thermal reliability requirements across end-use applications.
- Surface Mount Technology:Dominant placement methodology for miniaturized passive and active components on high-density substrates. China's GB energy-efficiency standards and Japan's METI-coordinated JIS certification pathways govern equipment interoperability in East Asian electronics clusters.
- Through-Hole Technology:Axial and radial component insertion for high-reliability power electronics and industrial motor drives.
- Hybrid Technology:Mixed-format assembly combining SMT and through-hole processes on single substrates.
- Digital Printing:Direct-write solder paste deposition eliminating stencil tooling for prototype and low-volume production.
Hybrid configurations retain installed base dominance; digital printing gains share fastest in NPI environments.
Application:
End-use intensity varies dramatically across sectors, with automotive fault tolerance requirements compressing equipment refresh cycles versus consumer electronics volume economics.
- Automotive Electronics:ADAS modules, powertrain controllers, and battery management systems demand zero-defect placement under ISO 26262. Stuttgart and Munich OEMs now weight carbon intensity at 15-20% of procurement scores under EU CSRD disclosure mandates.
- Consumer Electronics:Smartphone, wearable, and tablet assembly drives the highest absolute equipment throughput requirements.
- Telecommunications:5G infrastructure and optical networking equipment assembly emphasizes signal integrity and thermal management.
- Industrial Automation:PLC, sensor, and drive electronics production prioritizes long-term reliability in harsh operating environments.
Consumer electronics maintains volume leadership; automotive electronics commands premium pricing tiers.
End User:
Buyer structure determines procurement centralization, technical specification authority, and service contract economics.
- Contract Manufacturers:Foxconn, Jabil, and Flex consolidate vendor relationships from 5-6 to 2-3 suppliers per process step, trading price competition for delivery certainty in Mexico and Vietnam greenfield sites.
- OEMs:Captive electronics manufacturing operations at automotive and industrial conglomerates specify equipment directly.
- System Integrators:Turnkey line builders configure multi-vendor equipment packages for brownfield upgrades.
- Aftermarket Providers:Spare parts, refurbishment, and legacy equipment support services extend depreciation cycles.
Contract manufacturers concentrate procurement volume; system integrators capture complexity premium in brownfield retrofits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shenzhen port complex and its feeder container terminals handle the densest concentration of electronics components globally, underwriting East Asia's dominance in SMT equipment procurement and factory investment cycles.
China
Domestic EV production and consumer electronics assembly drive equipment demand across Guangdong and Jiangsu provinces. MIIT enforces GB energy-efficiency standards that filter import eligibility and extend European equipment approval timelines. Shenzhen contract manufacturers absorb the highest absolute placement machine volumes as 0201/01005 miniaturization forces gantry refreshes.
Japan
Automotive tier-one suppliers and industrial automation OEMs anchor precision equipment requirements under ISO 26262 mandates. METI coordinates JIS certification pathways governing SMT equipment interoperability with domestic electronics factories. Nagoya's industrial corridor hosts concentrated brownfield upgrade demand where legacy MES integration complexity constrains procurement speed.
South Korea
Semiconductor-adjacent assembly and advanced packaging applications drive cleanroom-compatible machine specifications. MFDS and industrial safety frameworks shape equipment designs for regulated facilities. Seoul's Pangyo tech cluster concentrates procurement authority for high-accuracy placement systems serving memory module production.
Germany
Stuttgart and Munich automotive suppliers weight carbon intensity at 15-20% of procurement scores under EU CSRD disclosure mandates. ECHA REACH compliance and CE marking requirements govern equipment chemistry and safety documentation. Bavaria's industrial automation corridor generates premium-tier demand for zero-defect placement capabilities.
India
Mobile phone and component production incentives under the PLI scheme create first-time SMT line demand in Noida and Sriperumbudur. BIS certification requirements and DGFT import protocols shape equipment qualification timelines. Tamil Nadu's electronics manufacturing zones concentrate greenfield factory investment from contract manufacturers seeking supply chain diversification.
SMT Machine Market Competitive Landscape
On the supply side, the industry is tiered between integrated process solution providers and specialized equipment architects. Japanese and European vendors anchor premium positioning through precision motion control and inspection resolution capabilities. Korean and Chinese suppliers compete on throughput economics for high-volume contract manufacturing. Dominant competitive moves include geographic expansion into India and Vietnam greenfield sites, plus AI-driven predictive maintenance service contracts that shift revenue toward recurring models.
Within the integrated solutions tier, Panasonic Corporation and ASMPT Ltd. exemplify full-workflow coverage from printing through inspection. Yamaha Motor Co., Ltd. anchors precision motion control specialization for automotive tier-one supply chains. Fuji Corporation occupies a position among Japanese fabricators emphasizing high-speed gantry architectures for consumer electronics scale economics.
| Leading Market Players |
|---|
| ASMPT Ltd. |
| Yamaha Motor Co., Ltd. |
| JUKI Corporation |
| Panasonic Corporation |
| Fuji Corporation |
| Mycronic AB |
| Hanwha Precision Machinery |
| Europlacer |
| Koh Young Technology |
| Others |
Pricing and Supply Chain Analysis
GB certification bottlenecks under China's MIIT protocols determine both equipment pricing tier spreads and supply chain configuration, compressing margins for European vendors while forcing procurement consolidation among contract manufacturers seeking delivery certainty.
Pricing Analysis
Volume-discount tiering structures separate premium placement systems from standard gantry configurations and economy-grade reflow ovens. Price differentiation rests on ISO 26262 certification grade and after-sales service bundling rather than raw throughput specifications. Cost compression in the standard tier is intensifying because contract manufacturers are consolidating qualified suppliers from five or six to two or three per process step. Automotive tier-one suppliers exhibit the lowest price sensitivity, prioritizing zero-defect placement accuracy and carbon intensity documentation under EU CSRD mandates over upfront capex minimization.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Japanese and German component vendors anchor working capital structures for SMT equipment assemblers. Geographic supply concentration centers on Japan for high-precision linear motor drives, Germany for motion control systems, and China for reflow oven thermal assemblies. Raw material dependencies include rare-earth magnets for gantry actuators, specialized aluminum alloys for chassis frames, and high-purity copper for thermal profiling elements. Single-source vulnerability concentrates in sub-10-micron machine vision sensors sourced from Korean and Japanese optics specialists. Distribution runs through direct-to-factory channels for contract manufacturers and system integrator intermediaries for brownfield retrofit projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The scarcity of technicians combining precision mechanics, thermal profiling, and vision system calibration expertise constrains factory utilization rates and equipment refresh velocity across East Asian electronics clusters.
For Market Incumbents: Pre-empt technician scarcity by embedding AI-driven predictive maintenance modules that reduce multi-disciplinary staffing requirements at automotive tier-one customer sites. Capture backward integration into linear motor drive production to offset Japanese and German supplier concentration risks. Deepen JIS certification pathways with METI to maintain interoperability dominance in Japan's Nagoya industrial corridor against emerging Korean competitors. For New Entrants and Emerging Players: Establish a beachhead in India's Noida and Sriperumbudur electronics manufacturing zones where PLI scheme incentives create first-time SMT line demand without entrenched incumbent relationships. Target cleanroom-compatible equipment variants for Korea's MFDS-regulated semiconductor-adjacent assembly facilities. Deploy outcome-based service contracts as the primary go-to-market mechanism to bypass capital-intensive upfront equipment sales. For Investors and Strategic Acquirers: Precision motion control specialists with captive linear motor drive capabilities represent the highest-value acquisition archetype given supply concentration in Japanese and German vendor bases. Long-term viability hinges on carbon accounting integration capabilities as EU CSRD disclosure mandates expand Scope 3 reporting requirements for capital equipment purchases. Watch for BIS certification timeline compression in India as a signal that contract manufacturer procurement authority is shifting from system integrators to direct vendor relationships.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Predictive Maintenance Integration | Machine learning modules from ASMPT and Panasonic reduce automotive tier-one technician staffing requirements. |
| Backward Integration into Linear Motor Drives | Captive production of precision actuators mitigates single-source dependency on Japanese and German suppliers. |
| Cleanroom-Compatible Equipment Certification | MFDS-aligned designs unlock Korea's Pangyo tech cluster semiconductor-adjacent assembly demand. |
| Carbon Accounting Documentation Systems | Lifecycle emissions tracking satisfies EU CSRD procurement scoring at Stuttgart and Munich automotive suppliers. |
| India PLI Scheme Market Entry | Greenfield factory partnerships in Tamil Nadu electronics zones capture supply chain diversification momentum. |
Research Methodology
Cross-validation between primary interviews with SMT equipment procurement directors, plant engineers at contract manufacturers, and aftermarket service heads anchors the qualitative findings against secondary validation from MIIT GB standard filings, METI JIS certification databases, and SEC equipment vendor disclosures. Bottom-up aggregation of placement machine unit economics and top-down calibration against electronics manufacturing capex flows triangulate market sizing across the analysis window.
Calibration against historical equipment refresh cycles and automotive electronics content-per-vehicle trajectories shapes the analytical framework. Segmentation dimensions span product architecture, process technology, application intensity, and buyer structure throughout the forecast period. CAGRs derive from regression analysis of procurement volume against miniaturization trend acceleration and functional safety mandate implementation timelines. Industry-specific inputs include ISO 26262 compliance cost curves and GB energy-efficiency testing protocol duration estimates.
Stress conditions across MIIT certification timeline volatility, linear motor drive supply concentration, and technician training pipeline capacity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding electrification mandate pacing and dual carbon goal enforcement intensity. Macroeconomic contraction, regulatory acceleration, or breakthrough micro-component placement architectures would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Semiconductor Manufacturing Equipment Market
Semiconductor Equipment
Quantum Annealing Equipment Market
Semiconductor Equipment
Semiconductor CVD Equipment Market
Semiconductor Equipment
APAC Die Attach Equipment Market
Semiconductor Equipment
Analog and Digital IC Development Tools Market
Semiconductor Equipment
Global Semiconductor Stepper Systems Market
Semiconductor Equipment
Global Semiconductor Thermal Evaporators Market
Semiconductor Equipment
Cathode Stripping Machines Market
Semiconductor Equipment
Wet Station Market
Semiconductor Equipment
Plasma Etching Equipment Market
Semiconductor Equipment
Asia-Pacific Semiconductor Manufacturing Equipment Market
Semiconductor Equipment
Vapor Blasting Machine Market
Semiconductor Equipment
Automatic Dicing Saw Market
Semiconductor Equipment
Semiconductor Capital Equipment Market
Semiconductor Equipment
Semiconductor Wafer Cleaning Equipment Market
Semiconductor Equipment
Semiconductor POD Cleaner Market