
 Global Semiconductor Wafer Polishing and Grinding Equipment Market | 2026-2036
Global Semiconductor Wafer Polishing and Grinding Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Semiconductor Wafer Polishing and Grinding Equipment Market Intelligence
The push for sub-10 angstrom surface roughness on 300mm wafers is rotating the market toward advanced Chemical Mechanical Planarization (CMP) systems. Applied Materials leverages its integrated platform solutions to serve top-tier fab operators. DISCO Corporation sustains its leadership in grinding and dicing equipment for memory chip applications. EBARA Corporation competes directly in the CMP space, focusing on wafer foundries and contract manufacturers.
Semiconductor wafer polishing and grinding equipment encompasses machinery designed to thin, planarize, and remove defects from silicon or compound semiconductor wafers with nanometer-level precision. This process is critical for creating a pristine, uniform surface required for subsequent photolithography and thin-film deposition steps in chip manufacturing. Within equipment types, advanced CMP systems command the highest value due to their complexity. While logic devices remain the dominant application, demand for equipment tailored to power devices represents the fastest-growing segment.
Environmental regulations, including the EPA's rules on chemical disposal in the United States and the EU's REACH framework, govern the chemical slurries used in polishing. China's Ministry of Ecology and Environment (MEE) imposes strict standards on wastewater treatment from fabrication plants, influencing equipment design and consumables. Equipment vendors must therefore balance the push for novel abrasive materials with increasingly stringent global environmental compliance requirements.
Market Dynamics
The market's central dynamic is the technological imperative for atomic-level surface precision, driven by the semiconductor industry's transition to sub-5nm logic nodes and the adoption of compound semiconductors like SiC for high-power applications in electric vehicles.
Growth Catalysts
- Compound Semiconductors:The adoption of silicon carbide (SiC) and gallium nitride (GaN) substrates for power electronics and 5G radio frequency devices requires specialized grinding and polishing equipment capable of handling these harder, more brittle materials.
- Government Incentives:National industrial policies, including the US CHIPS Act and the European Chips Act, are stimulating new fabrication plant construction, directly pulling demand for wafer processing equipment to build out domestic supply chains.
- Automotive Electrification:Demand from electric vehicle manufacturers for high-efficiency power modules and sensors is a primary catalyst, increasing the volume of wafers, particularly 300mm, that require advanced polishing and thinning.
Market Restraints
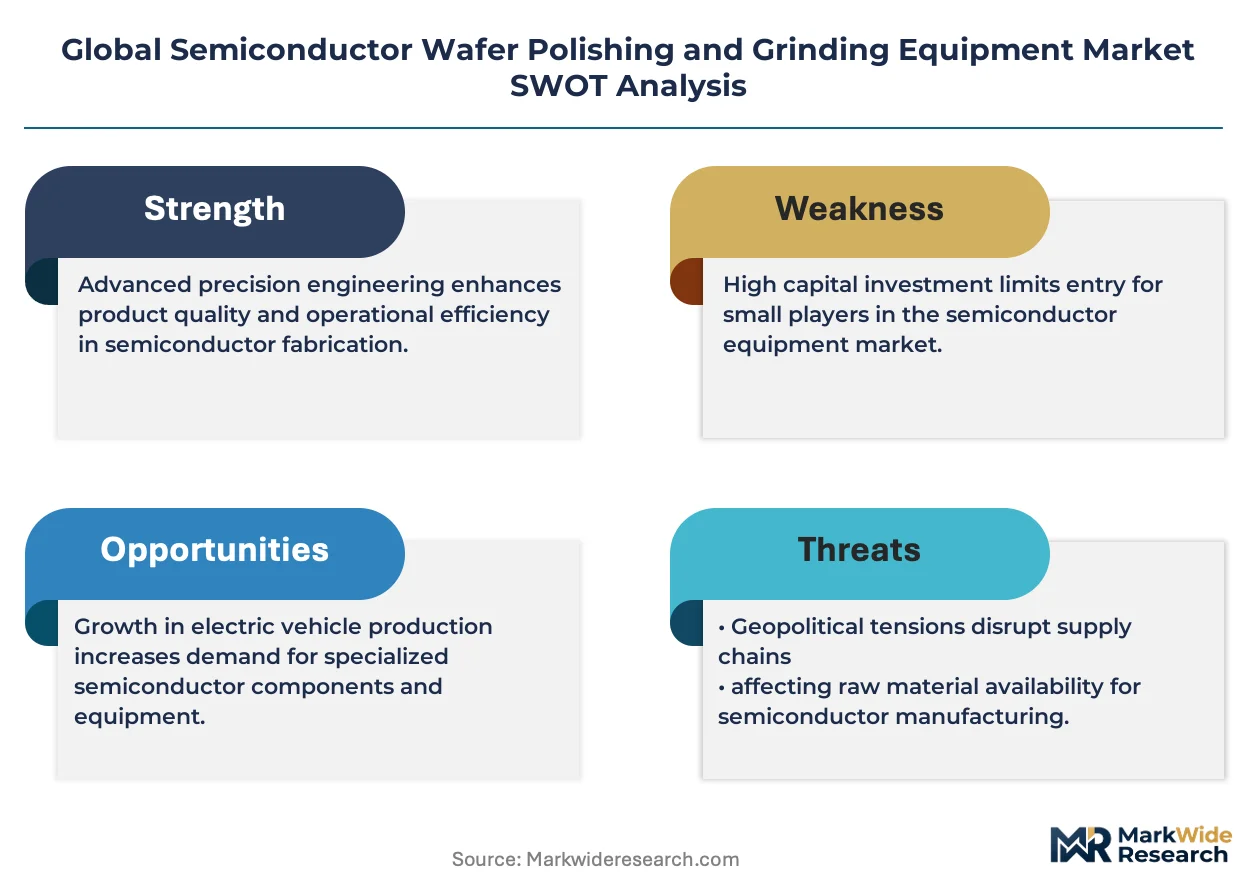
- High Capital Costs:The immense research and development expenditure required for next-generation CMP and grinding systems, coupled with their high acquisition cost, acts as a significant barrier for smaller fabs and new market entrants.
- Technical Limitations:Achieving uniform, defect-free surfaces below 10 angstroms of roughness on large-diameter wafers without inducing subsurface damage presents a fundamental materials science and engineering challenge that limits process yields.
- Supply Chain Concentration:Key sub-components for polishing and grinding equipment, such as precision motion stages and specialized optical sensors, are sourced from a limited number of suppliers, creating vulnerability to disruptions.
Strategic Opportunities
- Emerging Geographies:Initiatives like the India Semiconductor Mission create opportunities for equipment vendors to establish a foothold in new, government-supported semiconductor ecosystems beyond the established hubs in East Asia and North America.
- Advanced Packaging Substrates:The shift toward heterogeneous integration and chiplets opens a market for equipment designed to process non-silicon substrates, such as glass and advanced polymers, used for interposers and fan-out packaging.
- Process Control Software:Developing and marketing subscription-based software that integrates with CMP systems to provide real-time analytics on slurry life, pad wear, and wafer uniformity offers a high-margin, recurring revenue stream.
Industry Challenges
- Talent Scarcity:A persistent shortage of process engineers and equipment technicians with specialized skills in slurry chemistry, plasma physics, and advanced metrology constrains the operational capacity of both equipment vendors and their fab customers.
- Regulatory Divergence:Equipment manufacturers face complexity in designing systems that comply with disparate environmental rules, such as the EU's REACH framework and the EPA's chemical disposal regulations, increasing design and validation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Semiconductor Wafer Polishing and Grinding Equipment Market |
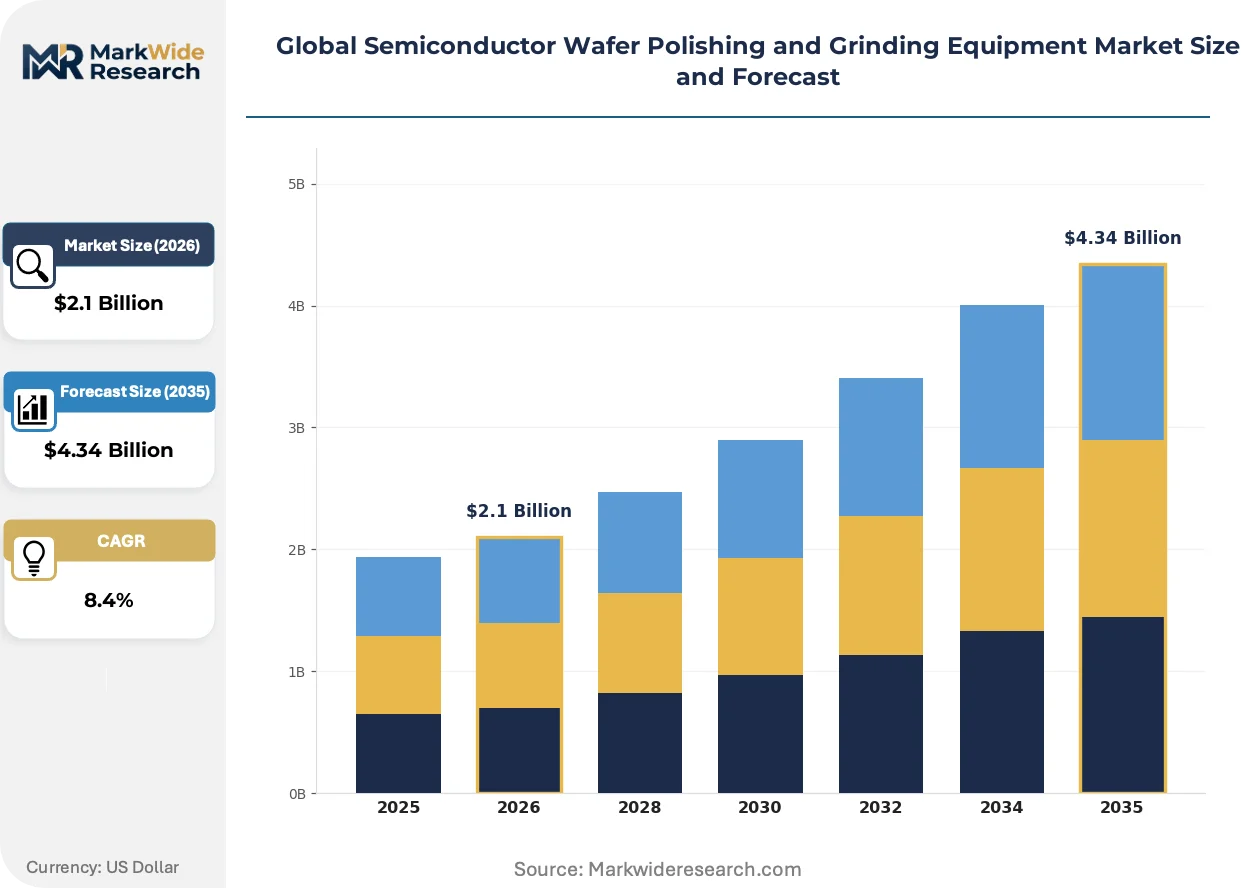
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Wafer Polisher, Grinding Machine, CMP System, Lapping Equipment Technology: Chemical Mechanical Planarization, Dry Grinding, Wet Grinding, Plasma Polishing Application: Memory Chips, Logic Devices, Power Devices, MEMS Fabrication End User: Fab Operators, Wafer Foundries, Contract Manufacturers, Research Labs |
| Companies Covered | Applied Materials, DISCO Corporation, EBARA Corporation, Tokyo Seimitsu (ACCRETECH), Revasum, Komatsu NTC, Okamoto Machine Tool Works, Lapmaster Wolters, Logitech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Semiconductor Wafer Polishing and Grinding Equipment Market Strategic Shifts & Innovations
A convergence of material science and data analytics is redefining wafer surface preparation. Innovations are focused on enabling new device structures and materials while simultaneously improving process control and meeting stricter environmental mandates from regulators like the MEE and EPA.
Hybrid polishing techniques, which combine CMP with electrochemical or plasma-assisted processes, are engineered to achieve ultra-smooth surfaces with minimal and highly controlled material removal. Top-tier logic and memory manufacturers are adopting these systems to create the pristine surfaces required for gate-all-around transistors and 3D NAND structures. This integrated method is displacing older, multi-step polishing sequences, thereby reducing process complexity and cycle time in advanced fabs.
The EU's REACH regulation, governing the registration and use of chemical substances, directly influences the composition of polishing slurries. The framework compels consumable suppliers and equipment vendors to phase out certain abrasive particles and chemical additives, pushing research toward more benign and recyclable alternatives. This shift most heavily impacts the high-volume logic and memory segments, which are now prioritizing slurry chemistries that balance performance with long-term regulatory compliance.
A significant change in customer behavior is the demand for fully integrated wafer preparation modules that combine grinding, polishing, cleaning, and metrology. This moves foundries away from purchasing discrete tools toward partnering with vendors who can deliver a qualified, end-to-end process solution. The trend is most visible in leading-edge foundries in Taiwan and South Korea, where maximizing yield and tool interoperability are critical competitive differentiators.
Global Semiconductor Wafer Polishing and Grinding Equipment Market Segmentation
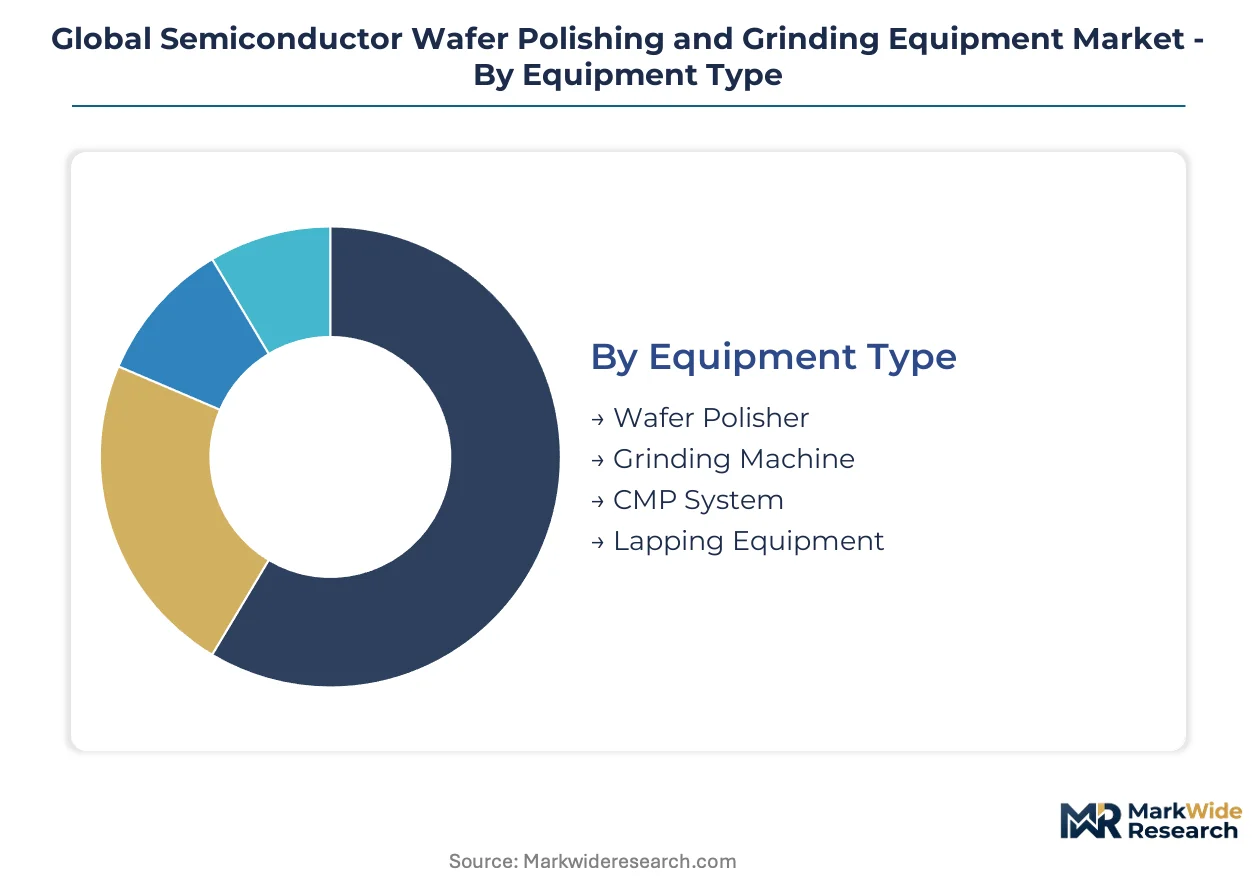
The global semiconductor wafer polishing and grinding equipment market exhibits distinct segments based on equipment type, technology, application, and end user. Understanding these divisions reveals critical insights into market dynamics and strategic focus areas. Each segment addresses specific manufacturing requirements within the complex semiconductor fabrication process.
Equipment Type:
The geographic distribution of equipment demand often reflects regional specialization, with certain equipment types seeing higher adoption in established Asian manufacturing hubs compared to nascent fabrication centers.
- CMP System:Chemical Mechanical Planarization systems are critical for achieving ultra-flat wafer surfaces with sub-10 angstrom roughness, essential for sub-5nm logic nodes. Demand for these high-precision tools concentrates among leading wafer foundries in Taiwan and South Korea, driven by the need for advanced device manufacturing.
- Grinding Machine:Grinding machines perform initial material removal and thinning of semiconductor wafers, preparing them for subsequent polishing steps. The need for specialized grinding equipment for harder materials like SiC and GaN in power device manufacturing is particularly strong in regions supporting electric vehicle production.
- Wafer Polisher:Wafer polishers refine surfaces after grinding, removing microscopic defects and achieving the required surface quality for photolithography.
- Lapping Equipment:Lapping equipment provides coarse material removal and initial planarization, primarily for thicker substrates or specific compound semiconductor applications.
Wafer polishers command the established base. The steepest expansion runs through CMP systems.
Technology:
The cost structure associated with each technology varies significantly, influencing adoption rates based on capital expenditure budgets and operational efficiencies.
- Chemical Mechanical Planarization:Chemical Mechanical Planarization employs abrasive slurries and mechanical force to achieve atomic-level surface flatness on wafers. This technology sees concentrated demand from advanced logic manufacturers in East Asia, where sub-5nm process nodes require extreme precision.
- Plasma Polishing:Plasma polishing utilizes reactive gases to remove material through chemical reactions, offering ultra-smooth, damage-free surfaces for sensitive device structures. This innovative technique is gaining traction among leading-edge foundries developing gate-all-around transistors and 3D NAND.
- Dry Grinding:Dry grinding performs material removal without liquid coolants, suitable for specific materials and applications where contamination is a concern.
- Wet Grinding:Wet grinding uses liquid coolants during material removal, offering better temperature control and debris removal for various wafer types.
Wet grinding remains a foundational technology for bulk material removal. Plasma polishing is emerging as a critical technique for advanced surface finishing.
Application:
The volume requirements for wafer processing vary substantially across different device applications, impacting equipment throughput and automation needs.
- Logic Devices:Logic devices, including CPUs and GPUs, demand the highest precision polishing and grinding due to their complex, multi-layered structures. Manufacturers of these advanced chips, particularly in Taiwan and South Korea, drive significant investment in cutting-edge CMP systems.
- Power Devices:Power devices, often built on SiC and GaN, require specialized equipment to handle harder, more brittle materials for electric vehicle applications. This segment represents the fastest-growing demand, particularly in regions with strong automotive manufacturing bases like Germany and China.
- Memory Chips:Memory chips, including DRAM and NAND, require high-volume, cost-effective planarization solutions for their stacked architectures.
- MEMS Fabrication:MEMS fabrication involves unique wafer thinning and surface preparation for sensors and actuators, often requiring customized equipment.
Logic devices account for the largest share of equipment demand. Power devices show dynamic expansion driven by new material adoption.
End User:
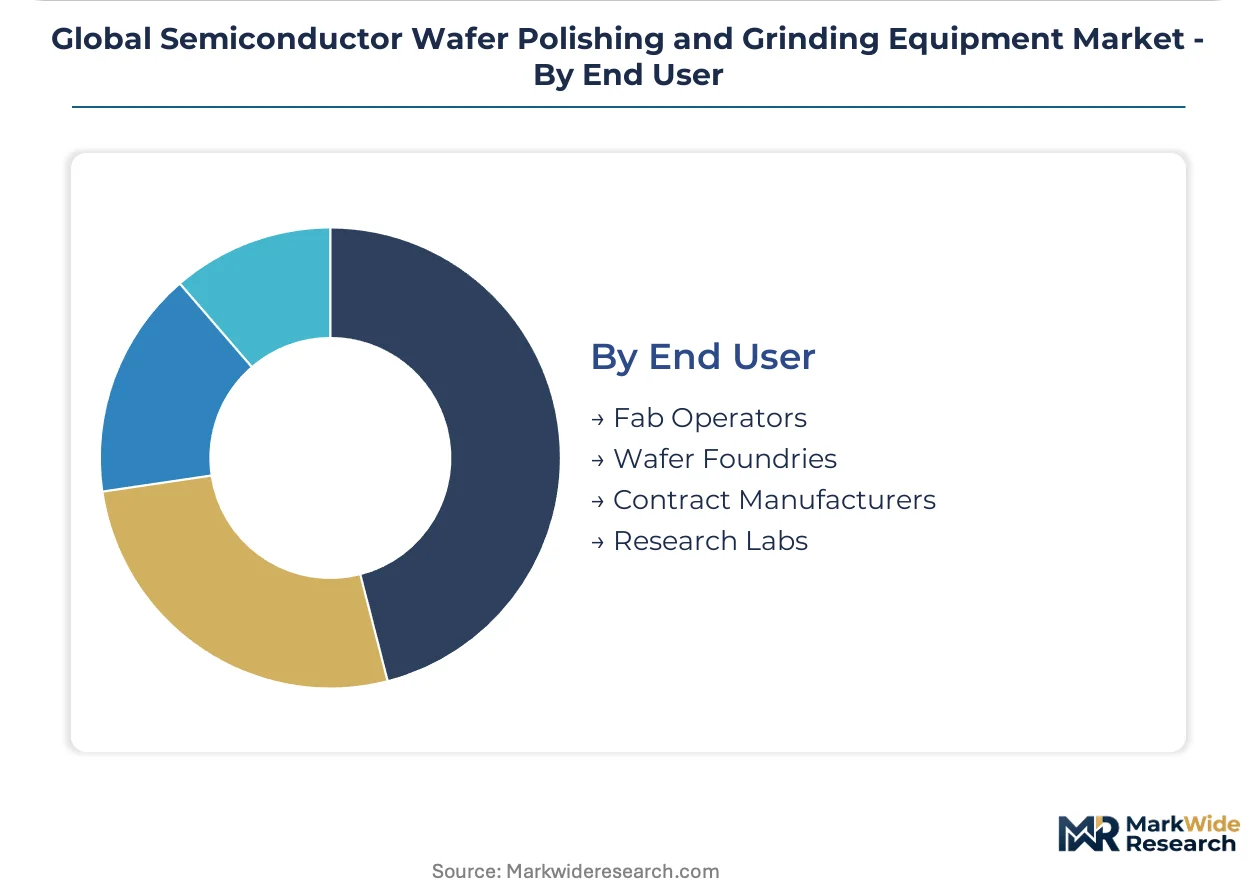
Each end-user type presents distinct purchasing behaviors and service requirements, influencing vendor sales strategies and support models.
- Wafer Foundries:Wafer foundries, such as TSMC and Samsung Foundry, are primary purchasers of advanced polishing and grinding equipment due to their high-volume, leading-edge production. These facilities, predominantly in Taiwan and South Korea, prioritize integrated process solutions and high yield.
- Fab Operators:Fab operators, including integrated device manufacturers, invest in equipment for their internal production lines, often customizing solutions for proprietary processes. Companies like Intel and Micron, with fabs globally, drive demand for both standard and specialized tools.
- Contract Manufacturers:Contract manufacturers offer specialized wafer processing services, requiring flexible and versatile equipment to serve diverse client needs.
- Research Labs:Research labs purchase equipment for process development, material science studies, and small-scale prototyping, focusing on flexibility and experimental capabilities.
Fab operators represent the core customer base for established equipment. Research labs influence future innovation and technology adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for semiconductor wafer polishing and grinding equipment exhibits varying price elasticity across regions. Leading-edge foundries in East Asia show lower price sensitivity for advanced CMP systems, prioritizing performance and yield for sub-5nm nodes. Conversely, nascent fabrication centers may prioritize cost-effective solutions for more mature technologies.
Taiwan
Taiwan's leading wafer foundries drive intense demand for advanced CMP systems, essential for sub-5nm logic node fabrication. The Taiwanese government actively supports domestic semiconductor manufacturing through strategic investments. Hsinchu Science Park, a global hub, concentrates R&D efforts and high-volume manufacturing.
South Korea
South Korea exhibits strong demand for polishing and grinding equipment, fueled by its dominant position in memory chip production and advanced logic. The national semiconductor strategy encourages investment in next-generation fabrication. The Gyeonggi-do region, home to major Samsung and SK Hynix fabs, upgrades equipment for 3D NAND and advanced transistors.
China
China's push for domestic chip manufacturing and EV power devices creates substantial demand for wafer processing equipment. The Ministry of Ecology and Environment (MEE) imposes strict wastewater treatment standards, influencing equipment design. New fab construction across the Yangtze River Delta and Beijing-Tianjin-Hebei regions pulls demand for advanced and foundational systems.
United States
United States demand is propelled by the CHIPS Act, stimulating new fabrication plant construction and advanced R&D. EPA regulations on chemical disposal directly impact polishing system design. States like Arizona and New York are seeing significant investment in new fabs and research centers, driving demand for cutting-edge wafer surface preparation tools.
Germany
Germany's strong automotive industry and focus on industrial semiconductors generate demand for specialized grinding and polishing equipment. The European Chips Act incentivizes domestic semiconductor production and R&D. The Dresden region, a prominent microelectronics cluster, focuses on power semiconductor manufacturing for electric vehicles.
Global Semiconductor Wafer Polishing and Grinding Equipment Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes in the semiconductor wafer polishing and grinding equipment market. The market structure is tiered, with highly specialized vendors focusing on cutting-edge solutions for advanced nodes. Other participants compete on efficiency and broader product portfolios for mature applications. Dominant competitive moves include strategic partnerships for integrated solutions and continuous R&D investment in novel surface preparation techniques. Capacity expansion also remains a key strategy for major equipment suppliers, alongside geographic market penetration.
Specialists in advanced wafer processing technology include Applied Materials, which leverages its integrated platform solutions for top-tier fab operators. DISCO Corporation, a Japan-based entity, sustains its leadership in grinding and dicing equipment, particularly for memory chip applications. EBARA Corporation, another Japan-based company, competes directly in the CMP space, focusing on wafer foundries and contract manufacturers. These entities collectively exemplify the market's drive toward precision and efficiency for critical semiconductor fabrication steps, reflecting distinct approaches to serving diverse customer needs.
| Leading Market Players |
|---|
| Applied Materials |
| DISCO Corporation |
| EBARA Corporation |
| Tokyo Seimitsu (ACCRETECH) |
| Revasum |
| Komatsu NTC |
| Okamoto Machine Tool Works |
| Lapmaster Wolters |
| Logitech |
| Others |
Cost & Logistics Intelligence
The shift from traditional silicon to compound semiconductors like SiC for power devices reshapes equipment supply geography and pricing economics. This substitution drives demand for specialized grinding and polishing tools, influencing regional manufacturing investments and equipment cost structures.
Pricing Analysis
After-sales service and software subscriptions drive significant lifetime value for equipment vendors. The dominant pricing model for advanced systems is project-based, encompassing equipment sales, installation, and ongoing support contracts. Price differentiation stems from the precision required for sub-5nm nodes and the customization for SiC/GaN material processing. Leading wafer foundries exhibit lower price sensitivity for cutting-edge CMP systems, while nascent fabrication centers prioritize cost-effective solutions.
Supply Chain Analysis
A limited number of suppliers for precision motion stages and specialized optical sensors creates a chokepoint in the equipment supply chain. Geographic supply concentration for these critical sub-components centers on Japan, Germany, and the United States. Single-source vulnerability for these highly engineered components poses a structural risk. Distribution runs through direct sales channels to major wafer foundries and integrated device manufacturers globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The semiconductor wafer polishing and grinding equipment market presents a defensive moat story, where high capital costs and immense technical complexity create substantial switching costs for major foundries.
For Market Incumbents:Compound investments in R&D for sub-5nm process nodes and compound semiconductor processing capabilities. Pursue strategic partnerships for integrated wafer preparation modules to counter fragmentation. Capacity addition in Taiwan and South Korea meets leading-edge foundry demand. Environmental regulations, such as EU's REACH framework, necessitate continuous material science innovation.
For New Entrants and Emerging Players:Differentiate on specialized solutions for compound semiconductors in electric vehicle applications. Target emerging geographies like India, where government incentives support new fab construction. Focus on process control software as a high-margin, recurring revenue stream. Offer flexible, versatile equipment for contract manufacturers to serve diverse client needs.
For Investors and Strategic Acquirers:Capital is best deployed toward vertically integrated equipment manufacturers with strong R&D pipelines for advanced CMP systems. Market viability rests on continuous demand for atomic-level surface precision in chip manufacturing. Companies expanding into advanced packaging substrates and process control software are attractive. A signal to watch is commercialization of hybrid polishing techniques for gate-all-around transistors.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand R&D for Hybrid Polishing | This initiative enables ultra-smooth surfaces for gate-all-around transistors, supporting advanced logic manufacturing. |
| Secure Supply of Precision Components | Mitigating single-source vulnerability for motion stages ensures stable production for equipment vendors like Applied Materials. |
| Develop Subscription-based Software | Offering real-time analytics for CMP systems creates recurring revenue for EBARA Corporation. |
| Geographic Penetration in India | Establishing a foothold in new semiconductor ecosystems leverages government incentives from India's Semiconductor Mission. |
| Focus on SiC/GaN Equipment | Specialized grinding and polishing tools address the fastest-growing power device segment for electric vehicles. |
Research Approach
Operator-level perspectives from process engineers, R&D directors, and procurement leads at leading foundries anchored the qualitative base for this study. This primary research was triangulated with extensive secondary data from industry association reports, patent databases, and company financial filings. A rigorous bottom-up and top-down approach validated market sizing and segmentation across all dimensions.
Sensitivity analysis informed the robustness of market forecasts across the analysis window. The analytical framework segmented the market by equipment type, technology, application, end user, and regional demand. Compound Annual Growth Rates were derived from historical data, market drivers, and expert projections. Key forecast inputs included wafer fab capacity expansion and electric vehicle production forecasts.
Decision-makers should treat outputs as directional under current geopolitical stability and technological development assumptions; material deviation would warrant model refresh. Forecasts reflect assumptions concerning trade policies and raw material availability. Practitioners should keep alternative scenarios live as global semiconductor investment evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Semiconductor Lithography Equipment Market
Semiconductor Equipment
India Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Wet Bench Market
Semiconductor Equipment
Photolithography Market
Semiconductor Equipment
Nanoimprint Lithography System Market
Semiconductor Equipment
300 Mm Front Opening Unified Pods (Foups) Market
Semiconductor Equipment
Semiconductor Wafer Cleaning Equipment Market
Semiconductor Equipment
Wafer Processing Equipment Market
Semiconductor Equipment
Vacuum Coating Equipment Market
Semiconductor Equipment
Automatic Dicing Saw Market
Semiconductor Equipment
Global Cleanroom Technologies Market
Semiconductor Equipment
Underfill Dispenser Market
Semiconductor Equipment
Africa Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Asia-Pacific Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Sample Preparation Equipment Market
Semiconductor Equipment
Wafer Grinding Machine Market