
 Thin Wafer Processing and Dicing Equipment Market | 2026-2036
Thin Wafer Processing and Dicing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Thin Wafer Processing and Dicing Equipment Market Analysis
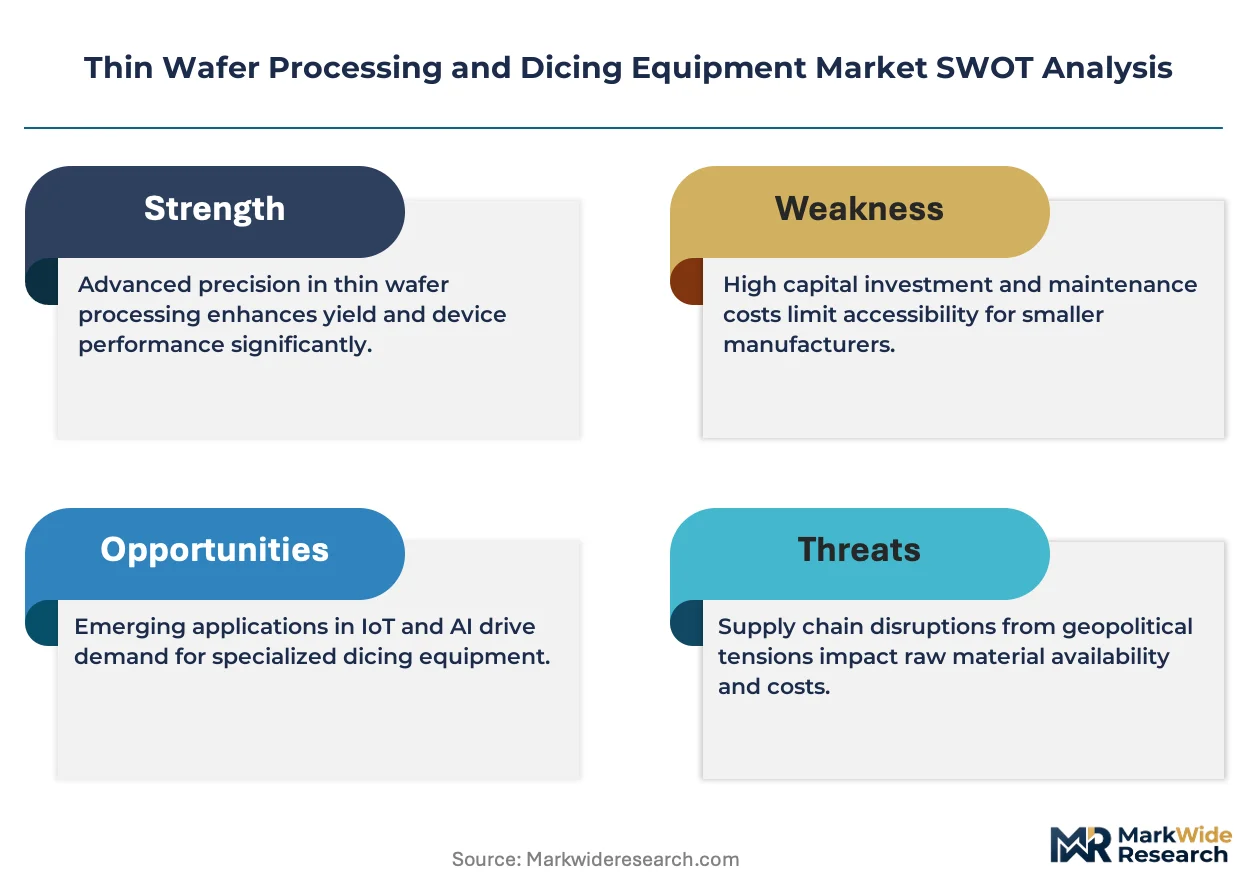
Modular equipment configurations is shifting buyer procurement patterns as semiconductor fabs seek flexible dicing lines that adapt to varying wafer thicknesses and substrate materials. TOKYO SEIMITSU leverages its precision grinding heritage to dominate high-accuracy thinning systems. DISCO Corporation anchors the dicing saw segment through proprietary blade technology and extensive installed base services. Lam Research Corporation competes by extending its plasma etch expertise into die singulation applications.
Thin wafer processing and dicing equipment encompasses machinery designed to reduce semiconductor substrate thickness below 100 micrometers and precisely separate individual dies without structural damage, employing diamond blade cutting, laser ablation, or plasma stealth dicing to achieve kerf widths under 20 micrometers for stacked die and fan-out packaging architectures. Laser dicing systems command premium positioning as silicon carbide and gallium nitride wafers drive demand for non-contact singulation that eliminates microcracking inherent to mechanical methods. Mechanical dicing tools sustain substantial volume across mature node production where cost-per-die economics favor established blade processes. Thin wafer handling systems represent the fastest-growing product category as temporary bonding and debonding workflows multiply process steps per wafer.
FDA scrutiny of MEMS-based medical implants shapes reliability requirements for dicing equipment serving medical device firms, while EPA and OSHA frameworks govern particulate emissions and worker exposure limits in US fabrication facilities. REACH and RoHS directives in Europe restrict hazardous substances in consumable dicing blades and cleaning chemistries, compelling equipment vendors to certify process compatibility. Stakeholders must monitor how evolving ISO cleanliness standards for sub-10 nanometer nodes intersect with national semiconductor subsidy programs to determine capital deployment timing and geographic manufacturing priorities.
Market Dynamics
Modular dicing line configurations are compressing equipment replacement cycles as semiconductor fabs seek flexible thinning systems that adapt to heterogeneous substrate materials without full line retooling.
Growth Catalysts
- China's dual carbon goals:GB standards for energy efficiency are mandating equipment upgrades across domestic fabrication facilities, creating replacement demand for low-power thinning systems.
- Silicon carbide wafer expansion:Power semiconductor manufacturers are adopting laser dicing for wide-bandgap materials that fracture under mechanical blade stress.
- East Asian manufacturing clusters:Concentrated packaging capacity across Japan, South Korea, and Taiwan is driving localized equipment procurement and service infrastructure investment.
Market Restraints
- Consumables cost volatility:Diamond blade and grinding wheel supply concentrates in Japanese specialty materials producers, exposing buyers to yen-denominated input price swings.
- Technical limitation in stealth dicing:Plasma etch singulation remains incompatible with opaque substrates including silicon carbide and gallium nitride, restricting addressable wafer types.
- REACH substance restrictions:ECHA frameworks on hazardous chemistries are constraining blade bonding agents and cleaning solvents, forcing process requalification cycles.
Strategic Opportunities
- India's semiconductor PLI scheme:Subsidized fab construction is creating first-mover equipment installation opportunities before domestic supply chains mature.
- Temporary bonding workflow proliferation:Multi-step handling processes for sub-50 micrometer wafers are expanding attachable equipment sales per fabrication line.
- EU AI Act compliance infrastructure:Traceability requirements for MEMS sensor production are driving demand for dicing equipment with integrated process data logging.
Industry Challenges
- Thin wafer handling expertise scarcity:Specialized technicians for temporary bonding and warpage compensation command premium compensation, constraining fab expansion timelines.
- ISO cleanliness certification delays:Sub-10 nanometer node qualification protocols are extending equipment acceptance testing, compressing vendor cash conversion cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thin Wafer Processing and Dicing Equipment Market |
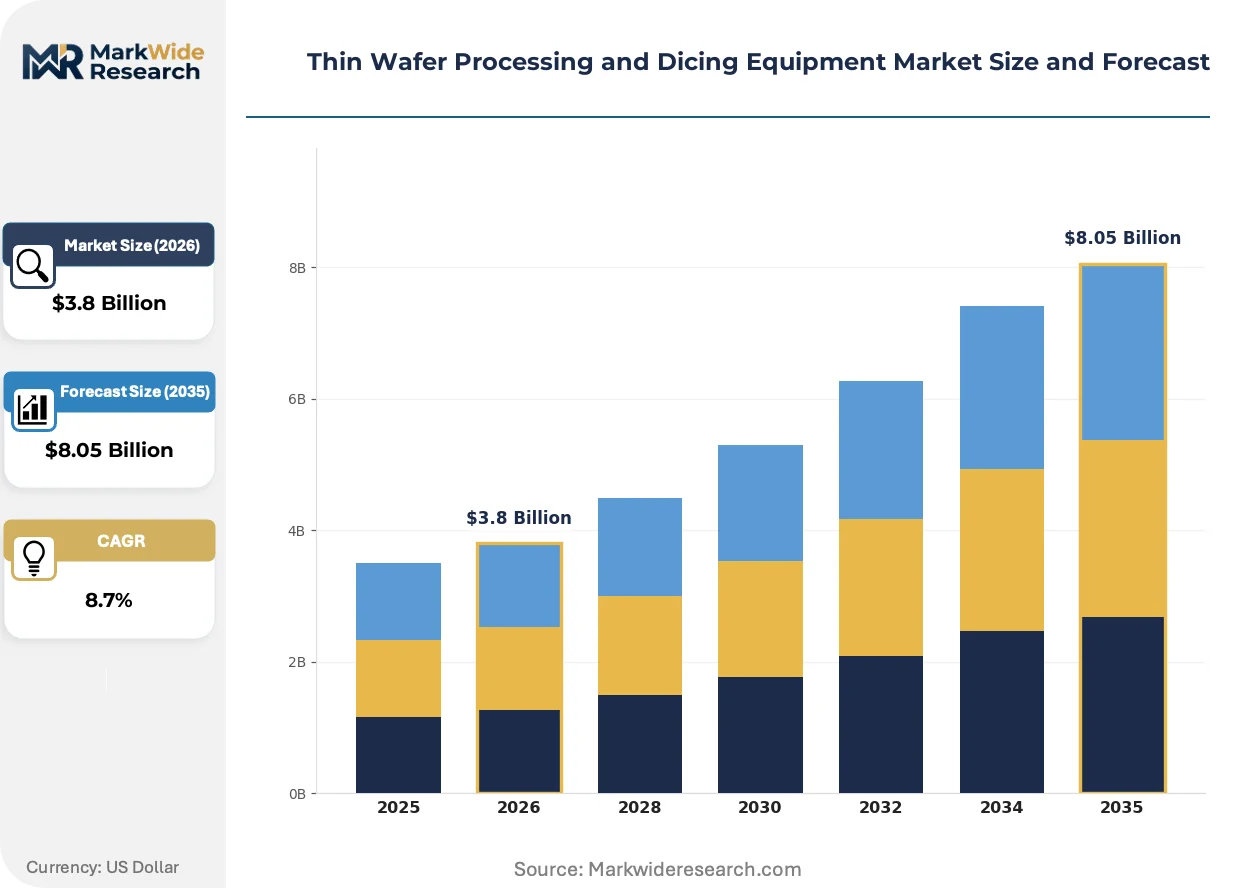
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dicing Saws, Laser Dicing Systems, Mechanical Dicing Tools, Thin Wafer Handling Systems Technology: Laser Technology, Mechanical Technology, Water Jet Technology, Plasma Technology End User: Semiconductor Manufacturers, Electronics Suppliers, Medical Device Firms, Research Institutions Application: Integrated Circuits, Sensors, MEMS Devices, Photovoltaics |
| Companies Covered | TOKYO SEIMITSU, Han's Laser Technology Industry Group Co., Ltd., DISCO Corporation, Lam Research Corporation, KLA Corporation, ASMPT, EV Group, Plasma-Therm LLC, Advanced Dicing Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thin Wafer Processing and Dicing Equipment Market Emerging Trajectories
Equipment architectures are fragmenting as process specialization outpaces general-purpose platform economics, with vendors diverging on whether to deepen grinding expertise or expand into adjacent singulation modalities.
Plasma stealth dicing is decentralizing process control from mechanical blade vendors to etch equipment specialists. Memory manufacturers are adopting this technology fastest for stacked die applications. The shift is compressing traditional dicing saw attach rates at advanced packaging facilities.
REACH authorization requirements are forcing blade chemistry reformulation across European-installed equipment bases. Manufacturers must now certify process compatibility with restricted bonding agents before consumable sales. Medical MEMS producers face the tightest substitution timelines due to FDA-EMA dual jurisdiction.
Equipment-as-a-service contracting is displacing outright purchase for mid-tier packaging houses. Leasing arrangements now bundle consumable supply with uptime guarantees, transferring operational risk to vendors. This restructuring is most visible among Taiwan-based OSATs managing volatile loading cycles.
Thin Wafer Processing and Dicing Equipment Market Segmentation
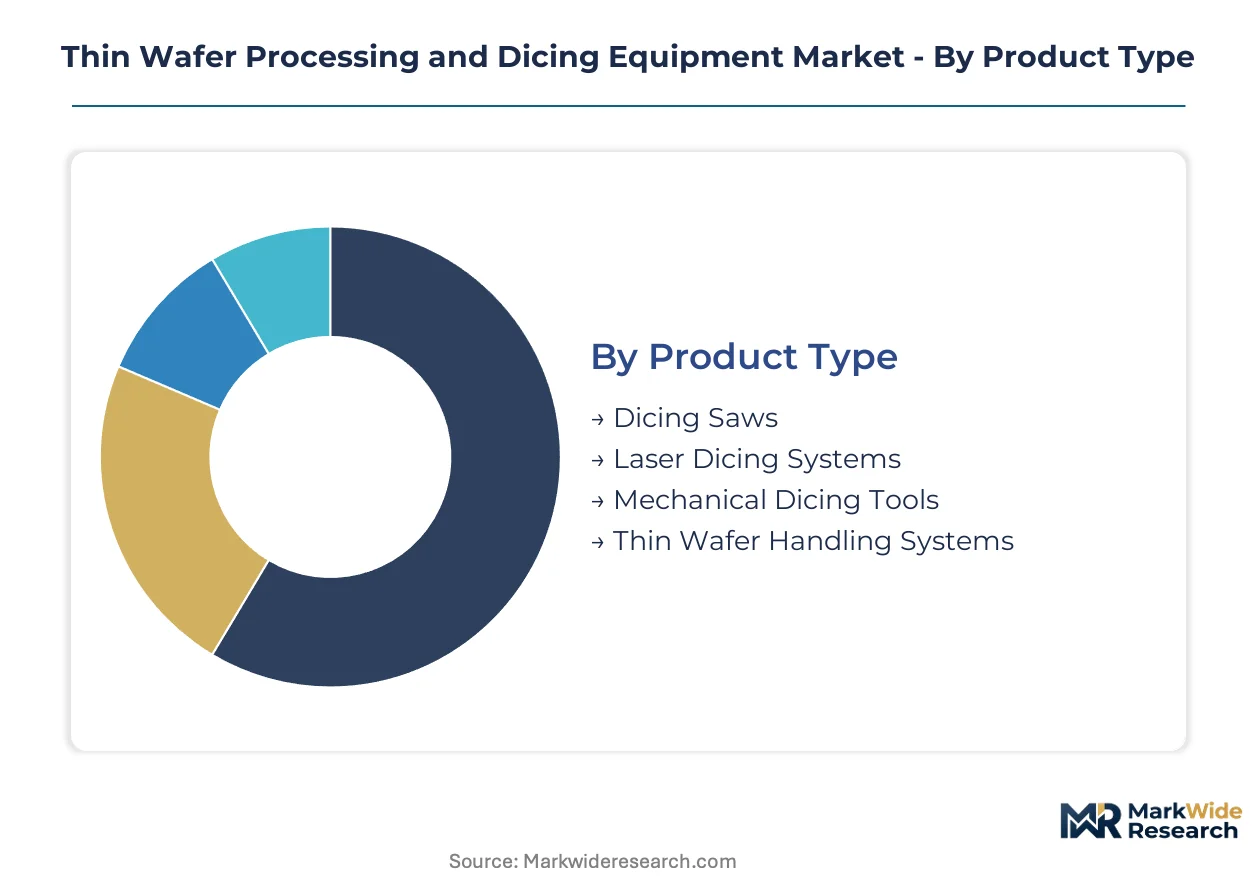
Equipment selection in thin wafer processing hinges on substrate material properties, die geometry requirements, and packaging architecture complexity. Procurement decisions cascade across technology generations, with each segment commanding distinct service infrastructure and consumable supply chains.
Product Type:
Laser dicing systems command premium positioning while mechanical tools anchor volume deployment across mature packaging lines.
- Dicing Saws:Diamond blade cutting platforms achieve kerf widths under 20 micrometers through precision spindle control and real-time blade wear compensation. Demand concentrates at OSAT facilities in Taiwan and Japan serving stacked die memory packaging, where blade process economics outweigh laser capital costs.
- Laser Dicing Systems:Non-contact ablation platforms eliminate mechanical stress on brittle wide-bandgap substrates. Silicon carbide power device manufacturers in Japan and South Korea are standardizing these systems as wafer diameters shift to 8-inch formats incompatible with blade fracture thresholds.
- Mechanical Dicing Tools:Established blade platforms dominate cost-sensitive mature node production.
- Thin Wafer Handling Systems:Temporary bonding and debonding equipment multiplies attach rates per fabrication line.
Mature deployment sits with mechanical dicing tools. Newer deployment is concentrated in laser dicing systems.
Technology:
Process modality selection tracks substrate opacity, die strength requirements, and acceptable kerf loss economics.
- Laser Technology:Solid-state and fiber laser platforms enable stealth dicing through internal material modification without surface debris generation. Memory manufacturers in South Korea deploy this for 3D NAND stack singulation where mechanical methods would generate fatal die cracks.
- Mechanical Technology:Diamond blade and grinding wheel systems rely on abrasive removal with continuous coolant delivery. Cost-per-die economics sustain dominance at analog and power discrete fabs in China serving automotive and industrial end-uses.
- Water Jet Technology:Abrasive fluid cutting addresses specialized substrate materials.
- Plasma Technology:Etch-based singulation extends Lam Research's installed etch expertise into die separation workflows.
Plasma technology is gaining share fastest at advanced packaging facilities. Mechanical technology retains the broadest installed base.
End User:
Regulatory exposure and volume scale differentiate procurement sophistication across buyer categories.
- Semiconductor Manufacturers:Integrated device fabs and foundries specify equipment with sub-10 nanometer node cleanliness certification and integrated process data logging. IDMs in Japan and South Korea drive specifications for temporary bonding workflows handling sub-50 micrometer wafers.
- Medical Device Firms:MEMS implant producers face FDA and EMA dual jurisdiction requiring traceability documentation and validated process windows. These buyers prioritize equipment with embedded statistical process control and audit-ready data architectures.
- Electronics Suppliers:OSATs and contract packagers balance flexibility against capital efficiency.
- Research Institutions:University and national laboratory buyers prioritize multi-material compatibility over throughput metrics.
Semiconductor manufacturers anchor equipment revenue. Medical device firms are expanding fastest as implantable MEMS volumes climb.
Application:
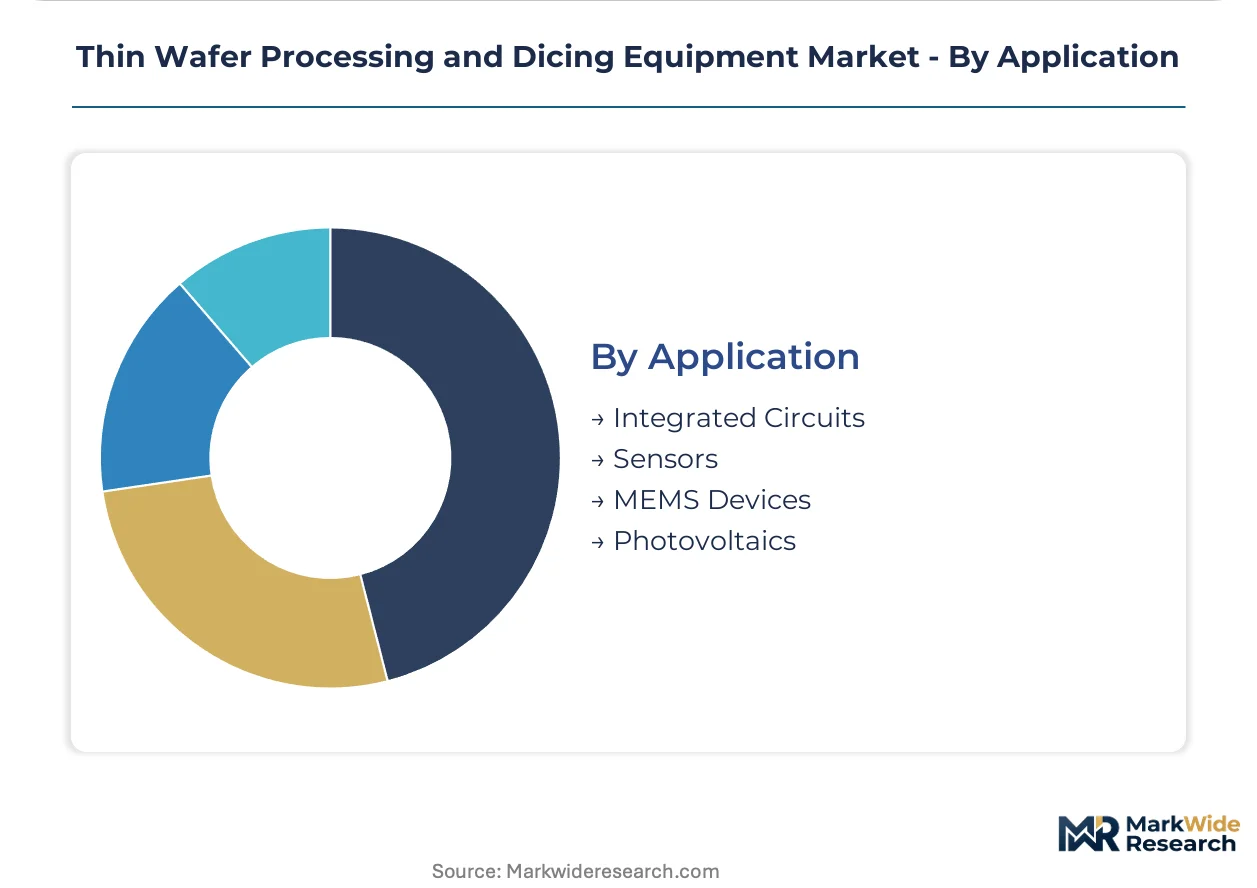
Die functionality dictates thinning depth, edge profile, and singulation damage tolerance thresholds.
- Integrated Circuits:Logic and memory dies require sub-100 micrometer thickness for 3D stacking and thermal management in high-performance computing packages. Taiwan-based advanced packaging houses concentrate demand for hybrid bonding-compatible surface finishes.
- MEMS Devices:Microelectromechanical structures impose strict constraints on die edge chipping and residual stress that would compromise mechanical resonator or pressure sensor calibration. FDA scrutiny of implantable applications elevates reliability requirements.
- Sensors:Image sensor and environmental detector dies prioritize edge quality for hermetic sealing.
- Photovoltaics:Solar cell dicing emphasizes throughput over kerf minimization.
Integrated circuits dominate capital deployment. MEMS devices are climbing fastest as automotive and medical sensor volumes expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment consumption concentrates in East Asian fabrication clusters while production capacity spreads across precision manufacturing bases in Japan, Germany, and the United States. This geographic split creates supply chain exposure to currency volatility and regional trade policy shifts.
China
Domestic fab construction under the dual carbon goals is driving replacement demand for energy-efficient thinning systems. GB standards for fabrication equipment energy consumption are tightening compliance windows through 2025. Yangtze River Delta clusters in Shanghai and Suzhou are absorbing the highest equipment installation rates for advanced packaging lines.
Japan
Silicon carbide power device manufacturers are standardizing laser dicing platforms as wafer formats scale to 200mm. METI industrial policy is subsidizing next-generation singulation technology development through regional technology centers. Kansai manufacturing corridors around Osaka and Kyoto remain the dominant precision equipment production base.
South Korea
Memory manufacturers are deploying plasma stealth dicing for 3D NAND stack singulation where mechanical methods risk fatal die cracking. MFDS medical device regulations are elevating traceability requirements for MEMS implant equipment procurement. Seoul Capital Area packaging houses are driving localized service infrastructure investment.
Taiwan
OSAT facilities are compressing equipment replacement cycles through modular dicing line configurations that adapt to heterogeneous substrates. Equipment-as-a-service contracting is displacing outright purchase among mid-tier packaging houses managing volatile loading cycles. Hsinchu Science Park and Tainan Technology Industrial Park anchor the highest equipment density per square kilometer.
United States
FDA scrutiny of MEMS-based medical implants is shaping reliability requirements for dicing equipment serving domestic device firms. EPA particulate emission frameworks and OSHA exposure limits govern fabrication facility equipment specifications. Arizona and Texas semiconductor manufacturing corridors are attracting capital deployment for thin wafer handling system installations.
Thin Wafer Processing and Dicing Equipment Market Vendor Landscape
The competitive structure tilts toward precision grinding specialists with installed base service networks. Japanese and American vendors dominate high-accuracy thinning platforms while Asian challengers compete on laser system cost efficiency. Three archetypes define positioning: heritage grinding equipment houses, plasma etch extension players, and laser platform specialists. Consolidation pressure is driving strategic partnerships between blade consumable producers and dicing system integrators.
Within the heritage precision equipment tier, TOKYO SEIMITSU and DISCO Corporation exemplify the grinding-to-dicing capability extension model. Lam Research Corporation occupies a distinct position by transferring plasma etch expertise into die singulation workflows. Among laser platform specialists, Han's Laser Technology Industry Group Co., Ltd. represents the Chinese cost-competitive archetype challenging established pricing structures.
| Leading Market Players |
|---|
| TOKYO SEIMITSU |
| Han's Laser Technology Industry Group Co., Ltd. |
| DISCO Corporation |
| Lam Research Corporation |
| KLA Corporation |
| ASMPT |
| EV Group |
| Plasma-Therm LLC |
| Advanced Dicing Technologies |
| Others |
Supply Flow & Price Mechanics
Specialized thin wafer handling technicians concentrated in Japan and Taiwan command premium compensation that compresses vendor margins and widens spreads between premium-certified and standard-tier equipment pricing across procurement contracts.
Pricing Analysis
Margin tightening in mid-tier laser dicing systems reflects equipment-as-a-service contracting proliferation among Taiwan-based OSATs seeking to transfer operational risk. Three-tier pricing structure across premium, standard, and economy levels separates ISO-certified sub-10 nanometer node equipment from mature-node mechanical tools. Cost-down pressure on standard-tier mechanical dicing tools accelerates because Chinese domestic fab construction under dual carbon goals prioritizes capital efficiency. Foundry buyers exhibit highest price sensitivity; medical device firms show least sensitivity due to FDA-EMA dual jurisdiction compliance requirements.
Supply Chain Analysis
Refurbishment flows for precision grinding spindles and blade wear compensation systems concentrate service revenue in Japanese vendors with captive remanufacturing facilities. Diamond blade and grinding wheel supply draws from Japanese specialty materials producers, exposing buyers to yen-denominated input volatility. Consumable chemistry feedstocks rest on German and American bonding agent suppliers constrained by REACH authorization timelines. Single-source vulnerability in stealth dicing etch chamber components creates procurement risk for memory manufacturers. Distribution runs through direct vendor sales teams serving concentrated East Asian fabrication clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thin wafer processing equipment markets are consolidating as plasma stealth dicing technology displaces mechanical blade vendors at advanced packaging facilities, forcing capability-deficient players toward exit or acquisition.
For Market Incumbents: Anchor service infrastructure investment in South Korea and Taiwan where memory manufacturers are standardizing plasma singulation workflows. Deepen backward integration into diamond blade consumable production to defend against yen-denominated input price swings. Prioritize temporary bonding equipment R&D to capture attach rate expansion from sub-50 micrometer wafer handling proliferation. For New Entrants and Emerging Players: Capture India's semiconductor PLI scheme installation window before domestic supply chain maturity closes first-mover pricing premiums. Target medical MEMS dicing equipment where FDA traceability requirements create compliance moats against established mechanical vendors. Deploy integrated process data logging architectures as primary go-to-market differentiator for EU AI Act compliance demand. For Investors and Strategic Acquirers: Re-rating potential sits with precision grinding specialists possessing installed base service networks given plasma stealth dicing technology shift compressing traditional dicing saw attach rates. Long-term viability favors vendors with temporary bonding workflow expertise as multi-step handling processes multiply equipment sales per fabrication line. Monitor Lam Research's die singulation attach rate trajectory as inflection indicator for plasma etch modality market share capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Consumable Production | Captures diamond blade margin and hedges yen-denominated input cost volatility. |
| Equipment-as-a-Service Contracting | Transfers operational risk to vendors serving Taiwan OSAT volatile loading cycles. |
| Temporary Bonding Workflow Expansion | Multiplies attachable equipment sales per line for sub-50 micrometer wafer handling. |
| Plasma Stealth Dicing Platform Development | Displaces mechanical blade vendors at South Korean 3D NAND memory facilities. |
| India PLI Scheme First-Mover Installation | Secures pricing premiums before domestic semiconductor supply chain maturity. |
Methodological Framework
Document review covered SEC 10-K filings, METI industrial policy white papers, and GB standards documentation, complemented by interviews with semiconductor fabrication equipment procurement directors, thin wafer process engineers, and OSAT operations managers. Primary fieldwork with temporary bonding workflow specialists and plasma etch equipment sales executives informed capability assessments. Secondary validation drew from customs trade data, ECHA REACH authorization databases, and ISO cleanliness certification registries. Bottom-up equipment shipment tracking and top-down fabrication capacity modeling enabled triangulation.
Historical attach rate trajectories cross-referenced against expert panel input on plasma stealth dicing adoption timelines shaped projection parameters. Segmentation modeling spanned product type, technology modality, end-user regulatory exposure, and application die functionality across the analysis window. CAGRs derived from equipment replacement cycle compression analysis and substrate material transition elasticity. Silicon carbide wafer diameter scaling and dual carbon equipment upgrade mandates served as industry-specific demand inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to plasma stealth dicing technical maturation and REACH substance restriction enforcement timelines. Forecasts reflect documented assumptions on temporary bonding workflow proliferation rates and East Asian manufacturing cluster concentration persistence. Material deviation in China's domestic fab construction pace or wide-bandgap substrate fracture threshold breakthroughs warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Global Cleanroom Technologies Market
Semiconductor Equipment
Vacuum Chambers Market
Semiconductor Equipment
Semiconductor Bonding Equipment Market
Semiconductor Equipment
Lithography Equipment Market
Semiconductor Equipment
Focused Ion Beam Market
Semiconductor Equipment
Semiconductor Assembly Equipment Market
Semiconductor Equipment
Pulse Tube and Gifford-Mcmahon Cryocoolers Market
Semiconductor Equipment
Plasma Etching Equipment Market
Semiconductor Equipment
China Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Chip Probing Market
Semiconductor Equipment
Middle East and Africa Semiconductor Manufacturing Equipment Market
Semiconductor Equipment
Vacuum Soldering System Market
Semiconductor Equipment
SMT Machine Market
Semiconductor Equipment
Global Battery Manufacturing Equipment Market
Semiconductor Equipment
Selective Soldering Equipment Market
Semiconductor Equipment
Automatic Dicing Saw Market