
 OLED Vacuum Evaporation Machine Market | 2026-2036
OLED Vacuum Evaporation Machine Market Size, Share, and Industry Trends Forecast 2026-2036
OLED Vacuum Evaporation Machine Market Insights
Automotive display integration is hardening as the dominant demand vector for OLED vacuum evaporation equipment. Canon Tokki Corporation anchors high-volume display manufacturing with its specialized inline deposition systems. ULVAC, Inc. competes through advanced multi-chamber architectures that sustain throughput advantages for Gen 8.5 substrate formats. Applied Materials Inc. leverages its broader semiconductor equipment platform to cross-sell deposition technologies into emerging flexible electronics lines.
OLED vacuum evaporation machines deposit organic electroluminescent materials onto glass or polymer substrates under ultra-high vacuum conditions, typically operating at pressures below 10^-6 Torr to prevent contamination and ensure uniform film formation. Thermal evaporation technology dominates current installed capacity, though organic vapor phase deposition systems are gaining traction for improved material utilization rates in large-area panels. Multi-chamber configurations command premium positioning due to their parallel processing architecture, while inline-type systems attract new capacity investments targeting automotive and flexible electronics applications where throughput scaling determines unit economics.
South Korea's Ministry of Trade, Industry and Energy (METI-equivalent industrial policy) and Japan's Ministry of Economy, Trade and Industry (METI) both shape equipment sourcing through domestic content requirements and strategic technology partnerships. China's SAMR enforces GB standards on display equipment safety and electromagnetic compatibility that foreign suppliers must satisfy for market access. Stakeholders must monitor how divergent regional certification regimes fragment equipment design standards and whether deposition technology licensors can maintain process uniformity across these compliance boundaries without duplicating development costs.
Market Dynamics
Automotive display integration is hardening equipment specifications as Tier 1 suppliers demand deposition systems capable of handling larger substrate formats and tighter uniformity tolerances for curved dashboard panels.
Growth Catalysts
- EU RoHS hazardous substance limits:Equipment manufacturers must redesign vacuum chamber materials and sealing technologies to eliminate restricted substances, creating replacement demand for legacy installed base.
- Flexible electronics manufacturing:Polymer substrate handling capabilities are pulling investment into next-generation inline deposition architectures that accommodate roll-to-roll processing.
- Gyeonggi Province cluster concentration:Samsung Display and LG Display anchor captive demand for high-throughput systems, with equipment vendors co-locating service infrastructure to capture lifecycle revenue.
Market Restraints
- High-purity organic material input costs:Precursor chemical prices fluctuate with rare earth supply constraints, compressing deposition equipment operating margins for system integrators.
- Japanese component supplier concentration:Critical vacuum pump and precision valve technologies source predominantly from domestic Japanese manufacturers, creating single-source vulnerability.
- Thermal evaporation throughput ceilings:Fundamental material utilization limits constrain cost scaling for Gen 10.5 substrate formats, favoring alternative deposition chemistries.
Strategic Opportunities
- India display manufacturing incentives:PLI scheme subsidies for semiconductor and display fabrication are attracting first-mover equipment vendors to establish local assembly and service presence.
- Micro-LED transfer equipment convergence:Vacuum evaporation expertise transfers to mass transfer tooling for next-generation emissive displays, opening adjacent revenue pools.
- China dual carbon goals:Energy efficiency mandates for industrial equipment are favoring low-power deposition architectures in new fab procurement specifications.
Industry Challenges
- Vacuum technology specialist scarcity:Ultra-high vacuum system engineering talent pools concentrate in Japan and Germany, constraining equipment vendor expansion timelines.
- Multi-jurisdiction certification complexity:China's SAMR GB standards, South Korea's KC marking, and EU CE requirements demand parallel testing protocols that extend product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | OLED Vacuum Evaporation Machine Market |
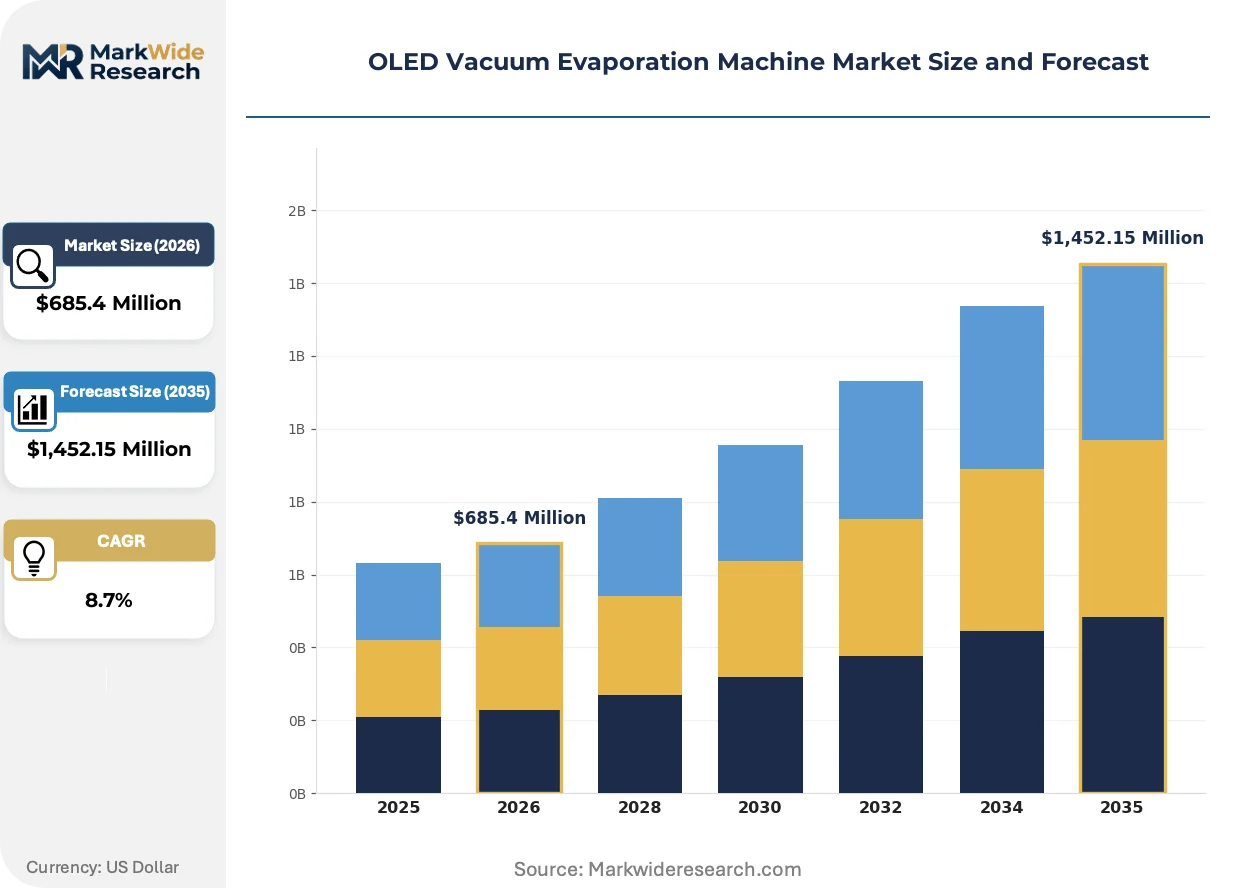
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Chamber, Multi Chamber, Batch Type, Inline Type Technology: Thermal Evaporation, E-beam Evaporation, Organic Vapor Phase Deposition, Sputtering End User: Display Manufacturers, Automotive Producers, Medical Device Firms, Aerospace Companies Application: Screen Manufacturing, Sensor Production, Lighting Solutions, Flexible Electronics |
| Companies Covered | Canon Tokki Corporation, ULVAC, Inc., Applied Materials Inc., Kurt J. Lesker Company, Sunic System, SNU Precision, SFA Engineering Corporation, Tokyo Electron, Veeco Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
OLED Vacuum Evaporation Machine Market Trends and Innovations
Deposition technology architectures are fragmenting as end-use requirements diverge between high-volume display manufacturing and emerging flexible electronics applications. Equipment vendors face strategic choices between scaling legacy thermal evaporation or betting on alternative chemistries.
Organic vapor phase deposition is decentralizing material distribution across substrate surfaces through carrier gas transport mechanisms rather than point-source evaporation. Automotive display manufacturers in South Korea are piloting these systems for improved thickness uniformity on curved panels. This technology is decentralizing the traditional supply relationship between equipment vendors and material suppliers by enabling broader precursor compatibility.
China's MIIT energy efficiency standards for industrial vacuum equipment are mandating power consumption disclosures and efficiency benchmarks for imported deposition systems. Foreign equipment manufacturers must redesign thermal management subsystems to qualify for state-backed fab procurement programs. Gen 8.5 substrate format systems face the steepest redesign requirements under these rules.
Buyers are unbundling after-sales service contracts from initial equipment purchases, negotiating separate multi-year maintenance agreements with third-party vacuum technology specialists. Display manufacturers in Taiwan and South Korea are driving this shift to reduce total cost of ownership and accelerate response times for chamber refurbishment. This pattern is most visible in high-volume fabs where downtime costs exceed service contract premiums.
OLED Vacuum Evaporation Machine Market Segmentation
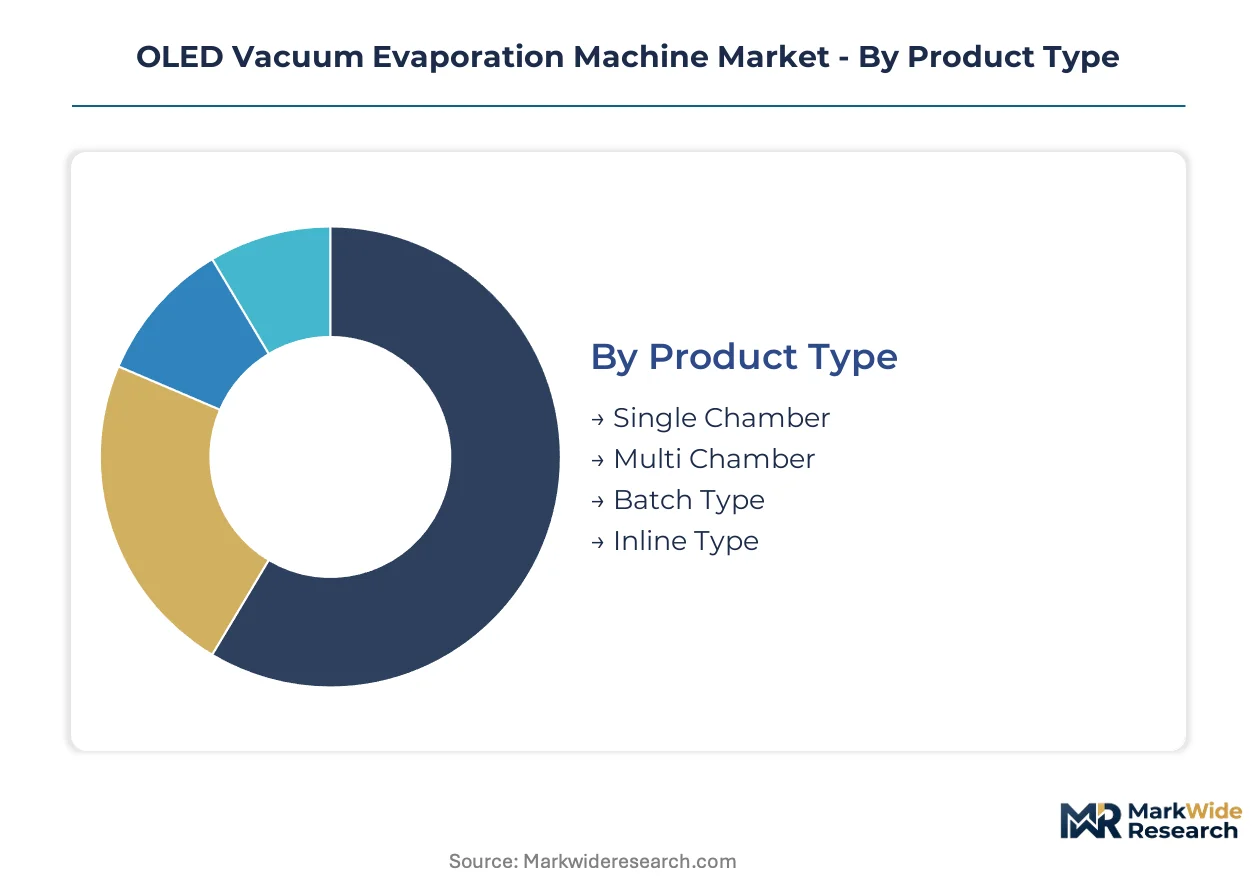
Segmentation in OLED vacuum evaporation equipment reveals how deposition architectures align with distinct certification burdens and substrate handling requirements. Equipment buyers segment procurement by the interplay of vacuum integrity standards, throughput demands, and end-use regulatory exposure.
Product Type:
Certification requirements fragment sharply across chamber architectures, with multi-chamber and inline systems facing the most complex multi-jurisdiction approval pathways for vacuum safety and electromagnetic compatibility.
- Multi Chamber:Parallel processing architectures enable simultaneous deposition of multiple organic layers without breaking vacuum. Samsung Display and LG Display in South Korea's Gyeonggi Province anchor demand for these systems where throughput scaling determines fab economics. EU CE marking and South Korea KC certification impose the steepest testing protocols on these configurations.
- Inline Type:Continuous substrate transport through sequentially connected deposition zones suits roll-to-roll flexible electronics manufacturing. Automotive display producers pilot these systems for curved dashboard panels where uniformity tolerances tighten. China's SAMR GB standards on equipment safety and electromagnetic compatibility create redesign requirements for imported inline systems.
- Single Chamber:Compact footprint suits research facilities and pilot production lines with lower throughput requirements.
- Batch Type:Stationary substrate handling enables precise thickness control for small-format medical and aerospace applications.
Leading the category by volume: Multi Chamber. Growing fastest: Inline Type.
Technology:
Technology selection maps directly to material utilization rates and the energy efficiency benchmarks now embedded in China's MIIT procurement specifications for industrial vacuum equipment.
- Thermal Evaporation:Point-source heating of organic materials under ultra-high vacuum below 10^-6 Torr dominates current installed capacity. Display manufacturers in Taiwan and South Korea favor this proven approach for Gen 8.5 substrate formats where process maturity reduces qualification risk. Fundamental material utilization limits constrain cost scaling for Gen 10.5 formats.
- Organic Vapor Phase Deposition:Carrier gas transport mechanisms decentralize material distribution across substrate surfaces, improving thickness uniformity on curved automotive panels. This chemistry enables broader precursor compatibility, loosening traditional equipment-material supplier relationships. Energy consumption profiles favor this approach under China's dual carbon goals for industrial equipment.
- E-beam Evaporation:Electron beam heating achieves higher deposition rates for inorganic encapsulation layers in flexible electronics.
- Sputtering:Ion bombardment of targets deposits metal electrode materials with excellent adhesion characteristics.
Dominant by installed base: Thermal Evaporation. Expanding most quickly: Organic Vapor Phase Deposition.
End User:
End-user concentration determines service contract structures, with display manufacturers unbundling maintenance agreements to third-party vacuum specialists while automotive producers demand captive service infrastructure.
- Display Manufacturers:Samsung Display and LG Display anchor captive demand for high-throughput systems in South Korea's Gyeonggi Province cluster. These buyers negotiate separate multi-year maintenance agreements to reduce total cost of ownership and accelerate chamber refurbishment response times. Procurement specifications emphasize uptime guarantees and spare parts availability.
- Automotive Producers:Tier 1 suppliers demand deposition systems handling larger substrate formats and tighter uniformity tolerances for curved dashboard panels. Integration timelines align with vehicle platform development cycles extending equipment qualification periods. NHTSA and EU automotive safety regulations indirectly shape display quality requirements.
- Medical Device Firms:FDA and EMA biocompatibility requirements constrain organic material selection for diagnostic display integration.
- Aerospace Companies:MIL-STD environmental testing and FAA certification burdens limit supplier qualification to established vacuum equipment vendors.
Commanding procurement volume: Display Manufacturers. Steepest growth trajectory: Automotive Producers.
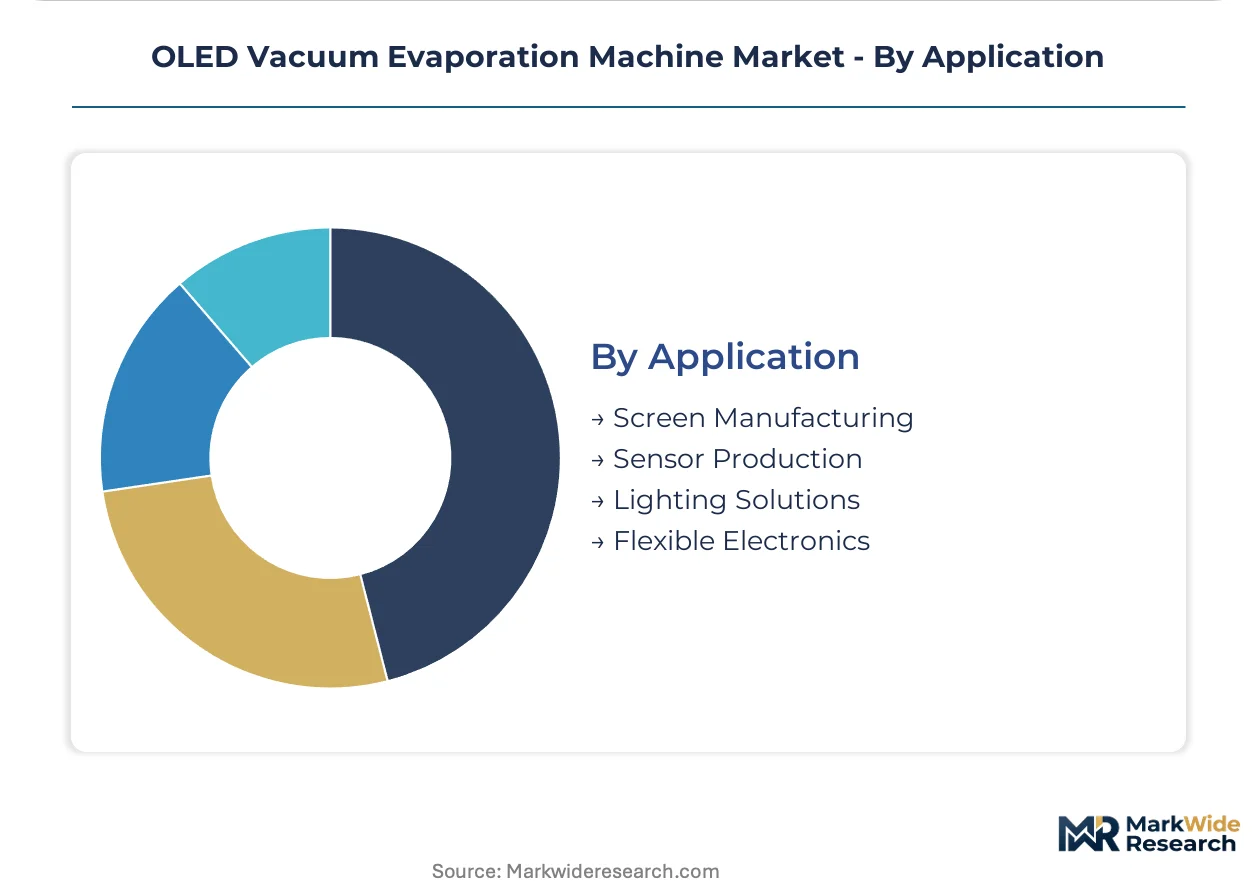
Application:
Application segmentation reveals diverging substrate handling requirements between rigid glass-based production and emerging polymer substrate formats.
- Screen Manufacturing:Smartphone, tablet, and television panel production consumes the majority of evaporation equipment capacity. Gen 8.5 and emerging Gen 10.5 substrate formats drive chamber scaling requirements. China's MIIT energy efficiency standards mandate power consumption disclosures for imported systems in this application.
- Flexible Electronics:Roll-to-roll processing of polymer substrates demands inline deposition architectures with tension control and thermal management adaptations. Equipment vendors face strategic choices between scaling legacy thermal evaporation or betting on alternative chemistries for this application. India's PLI scheme subsidies attract first-mover vendors to establish local assembly presence.
- Sensor Production:Uniform organic semiconductor deposition enables photodetector and gas sensor fabrication.
- Lighting Solutions:OLED panel architectures for general illumination require distinct optical outcoupling layer deposition sequences.
Capturing dominant equipment deployment: Screen Manufacturing. Gaining share fastest: Flexible Electronics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gyeonggi Province's display manufacturing corridor concentrates equipment demand through Samsung Display and LG Display captive procurement. Tax incentives for advanced manufacturing equipment accelerate depreciation schedules for deposition system investments.
South Korea
Samsung Display and LG Display anchor multi-chamber system procurement in the Gyeonggi Province cluster. MFDS equipment safety standards and KC electromagnetic compatibility marking create dual certification burdens for imported inline systems. Suwon and Paju host the densest concentration of deposition equipment service infrastructure outside Japan.
Japan
METI strategic technology partnerships steer domestic content requirements toward Japanese vacuum component suppliers. JIS standards on ultra-high vacuum chamber materials restrict foreign alloy sourcing for critical sealing surfaces. Nagoya and Osaka prefectures concentrate precision valve and vacuum pump manufacturing capabilities.
China
MIIT energy efficiency mandates for industrial vacuum equipment reshape Gen 8.5 system procurement specifications toward lower-power thermal management. SAMR GB standards on electromagnetic compatibility extend testing timelines for inline deposition architectures. Yangtze River Delta fabs pilot organic vapor phase deposition for improved material utilization compliance.
United States
NHTSA automotive safety regulations indirectly tighten display uniformity requirements for Tier 1 dashboard panel suppliers. EPA hazardous substance reporting constrains organic precursor chemical handling protocols in deposition facilities. Arizona and Texas semiconductor corridors attract equipment vendors establishing North American service presence.
India
PLI scheme subsidies for semiconductor and display fabrication attract first-mover equipment vendors to establish local assembly operations. BIS certification requirements for imported industrial vacuum equipment create pre-market testing obligations. Gujarat and Maharashtra states compete for fab investments with dedicated electronics manufacturing zone incentives.
OLED Vacuum Evaporation Machine Market Competitive Landscape
Top-tier vendors anchor high-throughput display manufacturing, while mid-tier specialists occupy flexible electronics and research equipment niches. Japanese and South Korean manufacturers concentrate around captive domestic demand from anchor display producers. Three archetypes dominate: integrated semiconductor equipment platforms, dedicated vacuum technology specialists, and display-industry captive engineering divisions. Capacity co-location with Gyeonggi Province cluster customers and technology licensing for organic vapor phase deposition represent the dominant competitive moves.
Among Japanese vacuum technology specialists, Canon Tokki Corporation and ULVAC, Inc. exemplify the dedicated equipment archetype through their concentrated exposure to display manufacturing cycles. Applied Materials Inc. represents the diversified semiconductor platform model, leveraging cross-segment deposition expertise. These three anchors illustrate how vendor strategies diverge between captive display-industry relationships and broader electronics manufacturing diversification.
| Leading Market Players |
|---|
| Canon Tokki Corporation |
| ULVAC, Inc. |
| Applied Materials Inc. |
| Kurt J. Lesker Company |
| Sunic System |
| SNU Precision |
| SFA Engineering Corporation |
| Tokyo Electron |
| Veeco Instruments |
| Others |
Pricing and Supply Chain Analysis
Organic vapor phase deposition adoption is simultaneously compressing material input costs and redistributing supply leverage toward equipment vendors with captive gas handling capabilities. This technology transition tightens procurement specifications for thermal evaporation legacy systems while amplifying price premiums for inline architectures qualifying under China's MIIT energy efficiency mandates.
Pricing Analysis
Lead-time premiums command substantial markups for multi-chamber systems delivering under standard fabrication cycles, while spot inventory of refurbished vacuum pumps trades at discounts. A three-tier pricing structure across premium, standard, and economy levels separates Gen 8.5 qualification-ready systems from pilot-line configurations and research-scale units. Price differentiation hinges on KC electromagnetic compatibility certification tier and after-sales service bundling depth. Pricing pressure stems from South Korean display manufacturers unbundling maintenance contracts to third-party vacuum specialists. Automotive producers exhibit lowest price sensitivity due to captive qualification timelines, while Indian PLI scheme beneficiaries negotiate aggressively on total cost of ownership.
Supply Chain Analysis
Freight costs for ultra-high vacuum chamber components from Japan to South Korea's Gyeonggi Province cluster absorb 8-12% of landed equipment value, with Nagoya-Osaka manufacturing corridors feeding precision valve and cryopump subassemblies. Supply concentration rests on Japanese vacuum component specialists, German sealing technology providers, and South Korean substrate handling integrators. Raw material dependencies span high-purity aluminum alloys for chamber fabrication, rare earth magnetic materials for ion pumps, and fluoropolymer seals for ultra-high vacuum integrity. Single-source vulnerability concentrates in Japanese turbo molecular pump manufacturing. Distribution runs through direct OEM procurement for anchor display manufacturers, with regional service subsidiaries capturing aftermarket parts and refurbishment demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a supply-constrained environment where Japanese vacuum component specialist scarcity props pricing power for integrated equipment vendors. Capacity bottlenecks in precision valve and cryopump manufacturing sustain margin premiums despite downstream display fab cyclicality.
For Market Incumbents: Deepen captive relationships with Gyeonggi Province display manufacturers through co-located service infrastructure and multi-year uptime guarantee contracts. Expand backward integration into vacuum pump refurbishment capabilities to capture lifecycle revenue streams unbundled by procurement teams. Organic vapor phase deposition licensing from Japanese technology holders represents a critical defensive move against thermal evaporation displacement. For New Entrants and Emerging Players: Automotive Tier 1 suppliers represent the most penetrable buyer archetype, with curved dashboard panel qualification cycles creating windows for alternative equipment vendors. Target India's PLI scheme subsidy window through local assembly partnerships in Gujarat electronics manufacturing zones. A service-first go-to-market angle—unbundled chamber refurbishment and spare parts logistics—sidesteps the capital intensity barrier of competing for initial equipment procurement. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified semiconductor equipment platforms seeking display manufacturing exposure. Long-term viability favors vendors with organic vapor phase deposition intellectual property and established service infrastructure in South Korea. The signal to watch is Samsung Display and LG Display procurement specifications shifting from thermal evaporation throughput metrics to carrier gas uniformity benchmarks.| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing for OVPD Systems | Canon Tokki's carrier gas expertise transfers to automotive panel uniformity requirements. |
| Local Assembly Operations in India | Gujarat PLI subsidies reduce landed cost for Gen 8.5 inline systems serving emerging fabs. |
| Service Infrastructure Co-location | Paju and Suwon facilities capture unbundled maintenance contracts from display manufacturers. |
| Backward Integration into Vacuum Components | In-house cryopump production mitigates Japanese single-source supply risk. |
| Energy Efficiency Certification Investment | MIIT compliance unlocks state-backed procurement in Yangtze River Delta fab expansions. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with vacuum equipment engineering directors, display manufacturer procurement leads, fab operations managers, and aftermarket service specialists. SEC 10-K disclosures from listed equipment vendors, Japan Vacuum Industry Association shipment statistics, and South Korean Ministry of Trade import records provided demand-side validation. Bottom-up equipment shipment tallies triangulated against top-down display fab capex announcements.
Data-stream reconciliation across shipment volumes, fab qualification timelines, and technology transition announcements generated segmentation-level projections. The analytical framework modeled chamber architecture, deposition technology, end-user concentration, and application substrate format across the projection horizon. CAGRs derived from equipment replacement cycles, capacity expansion announcements, and technology substitution elasticity parameters. Forecast inputs incorporated MIIT energy efficiency mandate compliance rates and automotive display integration timelines.
Revisions become necessary when Japanese vacuum component export restrictions materialize, organic vapor phase deposition adoption accelerates beyond pilot thresholds, or India's PLI scheme disbursement delays alter fab construction schedules. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Semiconductor POD Cleaner Market
Semiconductor Equipment
Global Semiconductor Machinery Market
Semiconductor Equipment
Asia-Pacific Semiconductor Manufacturing Equipment Market
Semiconductor Equipment
Wafer Back-Grinding Machine Market
Semiconductor Equipment
Europe Semiconductor Manufacturing Equipment Market
Semiconductor Equipment
FOUP Cleaning System Market
Semiconductor Equipment
Solar Texturing Equipment Market
Semiconductor Equipment
UV-Based Nanoimprint Lithography (UV-NIL) System Market
Semiconductor Equipment
Semiconductor Lithography Equipment Market
Semiconductor Equipment
Global Photoresist Market
Semiconductor Equipment
Die Attach Equipment Market
Semiconductor Equipment
Partition Inserter Machines Market
Semiconductor Equipment
Dicing Equipment Market
Semiconductor Equipment
Global Semiconductor Thermal Evaporators Market
Semiconductor Equipment
APAC Die Attach Equipment Market
Semiconductor Equipment
Global Cleanroom Technologies Market