
 Battery Testing Equipment Market | 2026-2036
Battery Testing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Testing Equipment Market Analysis
Automotive OEMs is bifurcating from consumer electronics as the dominant buyer archetype in battery testing equipment procurement. Keysight Technologies leverages its precision instrumentation heritage to dominate high-frequency impedance spectroscopy for next-generation cell validation. Chroma Systems Solutions anchors its position through integrated power conversion test platforms that span module-to-pack verification workflows. Arbin Instruments specializes in multichannel cycler architectures that sustain R&D intensity across university and national laboratory channels.
Battery testing equipment encompasses electrochemical characterization instruments that apply controlled current, voltage, and thermal loads to evaluate energy storage device performance, safety margins, and degradation trajectories under standardized protocols. These systems typically operate across microamp-to-kiloamp ranges with millisecond sampling resolution to capture transient behaviors during formation cycling, abuse testing, and state-of-health estimation. Charge/discharge testers command the largest installed base due to their ubiquity in formation and grading operations, while electrochemical impedance spectroscopy (EIS) platforms represent the fastest-expanding technology segment as manufacturers embed diagnostic capabilities directly into production lines. Cell testers concentrate margin pools at the premium tier where sub-ppm failure detection justifies capital intensity for solid-state and silicon-anode chemistries.
The EPA and NHTSA in the United States enforce battery safety and lifecycle transparency standards that compel OEMs to maintain traceable test records across cell suppliers. Europe's ECHA REACH framework and EU Green Deal battery passport regulations mandate disclosure of recycled content thresholds and carbon intensity footprints, forcing equipment vendors to embed data lineage features. China's NMPA and GB standards impose mandatory abuse testing protocols that drive demand for multi-physics coupled test chambers. Stakeholders must calibrate capital allocation between modular upgrade paths and full platform replacements as chemistry transitions outpace equipment depreciation cycles.
Market Dynamics
Solid-state battery chemistry transitions are forcing equipment manufacturers to recalibrate validation protocols as silicon-anode and lithium-metal architectures demand sub-ppm failure detection thresholds that legacy testers cannot achieve.
Growth Catalysts
- EU Green Deal battery passport:Mandates for carbon intensity disclosure and recycled content traceability compel OEMs to install data lineage features in formation and grading lines.
- China's GB standards abuse testing:NMPA protocols for nail penetration and thermal runaway propagation drive procurement of multi-physics coupled test chambers.
- Semiconductor-battery integration:South Korea's packaging corridors require cell-to-pack verification workflows that compress validation cycles.
Market Restraints
- Precision instrumentation cost structure:High-frequency impedance spectroscopy platforms require rare earth magnetics and cryogenic sensors that concentrate supply risk.
- Metrology talent scarcity:Electrochemical characterization expertise pools concentrate in Germany's automotive testing corridors and constrain equipment vendor scaling.
- Depreciation cycle compression:Chemistry transitions outpace five-year equipment amortization schedules, stranding capital in obsolete formation cycling architectures.
Strategic Opportunities
- India's PLI scheme for battery manufacturing:Incentive-linked capacity buildouts create first-mover advantage for localized test system deployment.
- Second-life battery diagnostics:State-of-health estimation algorithms embedded in charge/discharge testers open aftermarket revenue streams.
- Cloud-native data architectures:Distributed ledger integration for test record immutability addresses ECHA REACH audit requirements.
Industry Challenges
- Multiphysics simulation integration:Coupling electrochemical-thermal-mechanical models with hardware-in-the-loop testing demands cross-functional teams that equipment vendors struggle to field.
- ISO 17025 calibration drift:Maintaining millisecond sampling resolution certification across microamp-to-kiloamp ranges requires continuous metrology investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Testing Equipment Market |
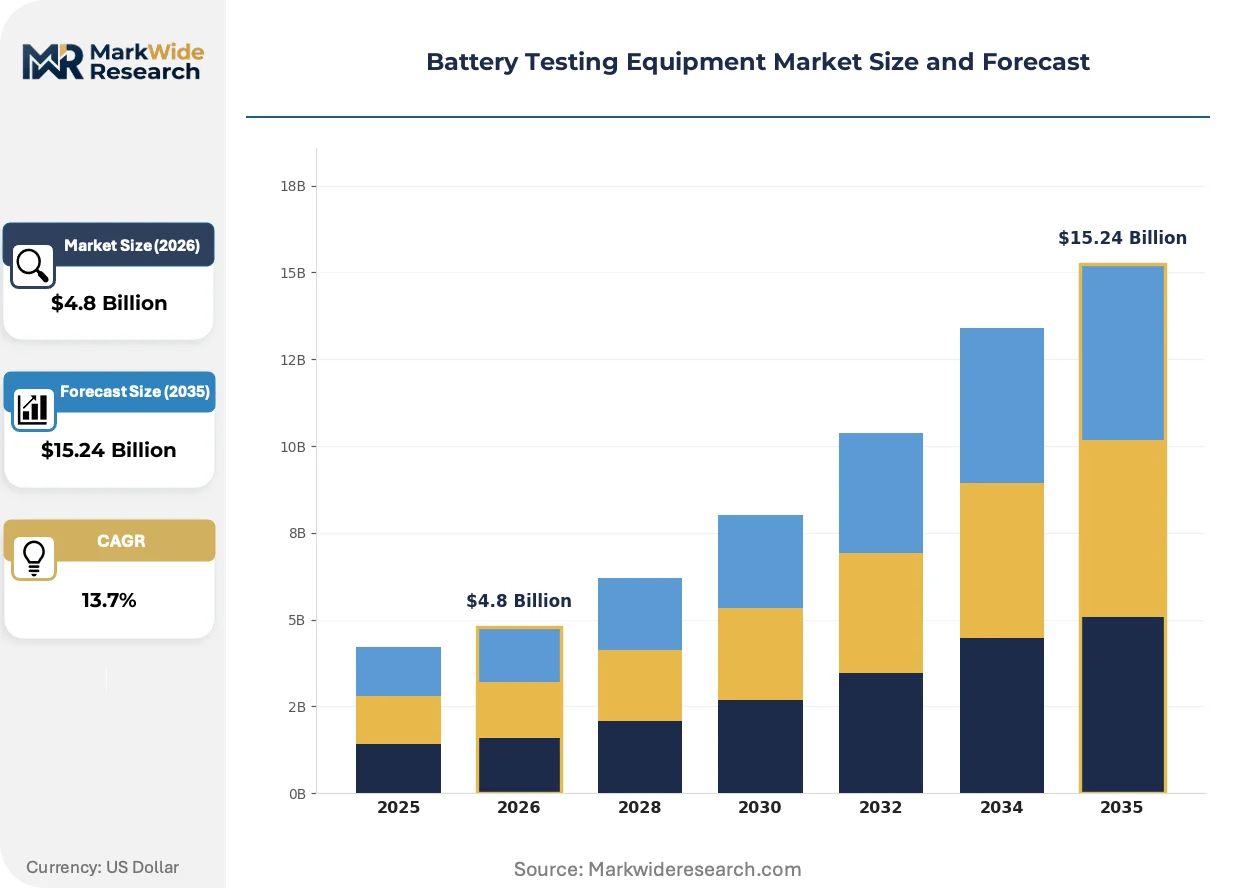
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery Analyzers, Cell Testers, Charge/Discharge Testers, Cycle Life Testers End User: Aerospace, Automotive OEMs, Consumer Electronics, Research Laboratories Technology: Conductive Testing, EIS, Load Testing, Thermal Imaging Application: Electric Vehicles, Renewable Energy Storage, Smartphone Batteries, Industrial Backup Systems |
| Companies Covered | Arbin Instruments, Chroma Systems Solutions, Keysight Technologies, Hioki, Maccor, Bitrode Corporation, Neware, BioLogic, Ametek Scientific Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Testing Equipment Market Emerging Trajectories
Diagnostic capabilities are migrating from laboratory benches into production line equipment as manufacturers embed real-time degradation tracking directly within formation cycling operations.
Electrochemical impedance spectroscopy is decomposing traditional charge/discharge testing workflows by enabling non-destructive state-of-health monitoring during formation cycling. Automotive OEMs in Germany and South Korea are adopting EIS-integrated testers at pilot scale. This convergence is decomposing the boundary between R&D characterization and production validation, compressing equipment procurement cycles.
REACH framework amendments on substance restriction are forcing equipment vendors to redesign thermal chamber insulation and coolant chemistries. Industrial consequence includes accelerated obsolescence of legacy abuse testing infrastructure. Cell tester manufacturers serving European automotive OEMs are responding with fluorinated gas-free thermal management architectures.
Buyer concentration among tier-one automotive OEMs is consolidating procurement authority away from cell suppliers and into vehicle platform engineering divisions. Equipment vendors now face direct specification by Volkswagen, BMW, and Hyundai Motor Group rather than indirect influence through battery maker channels. This shift is most visible in Germany's testing corridor where OEMs operate captive validation facilities.
Battery Testing Equipment Market Segmentation
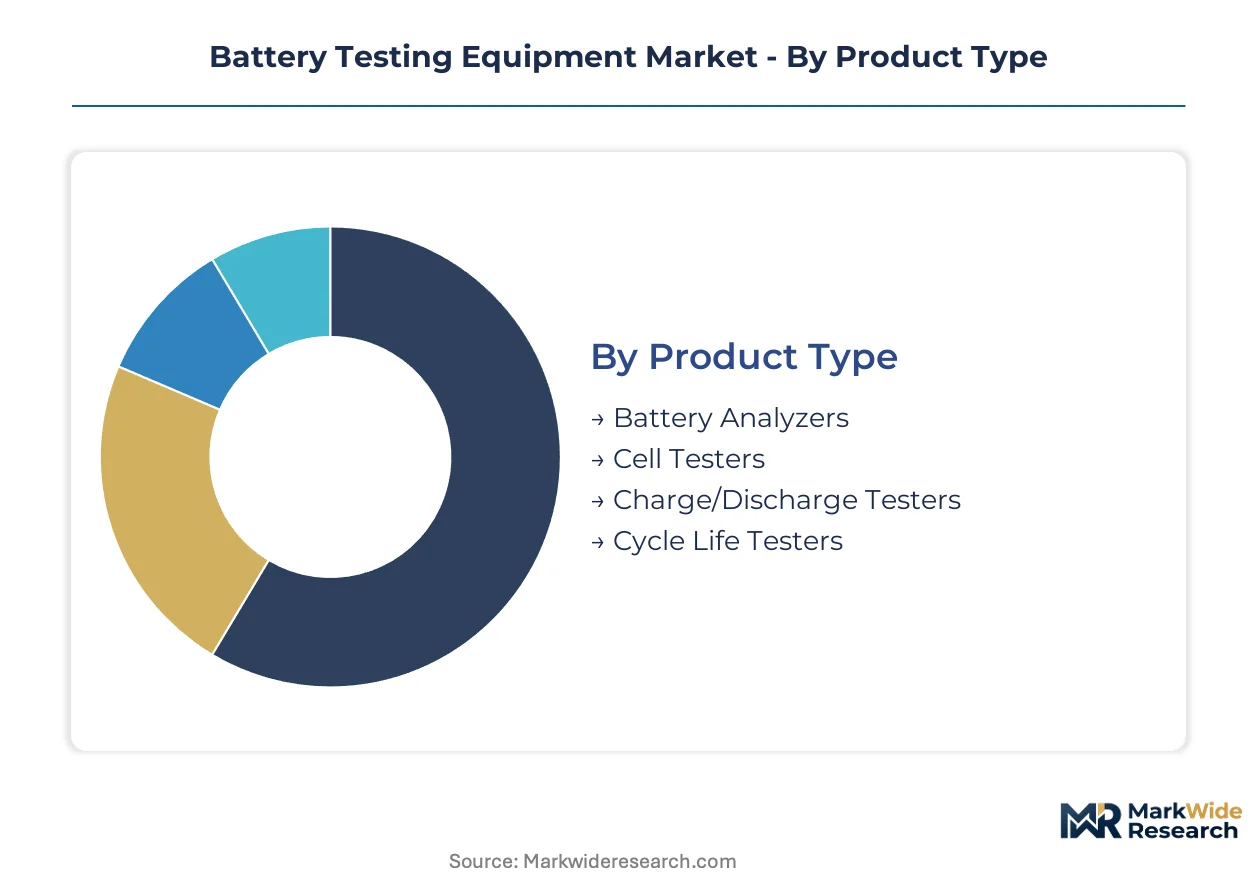
Segmentation in battery testing equipment reveals divergent technical requirements across chemistry transitions and end-use validation protocols. Equipment specifications vary dramatically between formation cycling for solid-state cells versus degradation tracking for second-life battery deployments.
Product Type:
Substitution pressure concentrates in charge/discharge testers as electrochemical impedance spectroscopy platforms displace traditional cycling architectures for inline diagnostic applications.
- Charge/Discharge Testers:These systems apply controlled current and voltage profiles across microamp-to-kiloamp ranges with millisecond sampling resolution. Demand concentrates in China's NMPA-mandated formation lines where GB standards abuse testing protocols require synchronized thermal-electrical loading. Legacy architectures face obsolescence as silicon-anode chemistries demand sub-ppm failure detection.
- Cell Testers:Precision instrumentation for individual cell validation captures transient behaviors during formation cycling and state-of-health estimation. Procurement clusters in Germany's automotive testing corridors where Volkswagen and BMW operate captive validation facilities for solid-state battery qualification.
- Cycle Life Testers:Accelerated degradation assessment platforms simulate multi-year operational stress in compressed test windows.
- Battery Analyzers:Portable diagnostic units for field-deployed state-of-health estimation in second-life battery applications.
Charge/Discharge Testers retain volume leadership; Cell Testers hold the steepest expansion curve.
End User:
Cost tier stratification separates capital-intensive automotive OEM captive facilities from modular research laboratory procurement patterns.
- Automotive OEMs:Vehicle platform engineering divisions now specify equipment directly rather than through battery maker channels. Germany's testing corridor concentrates specification authority at Volkswagen, BMW, and Porsche engineering centers. EU Green Deal battery passport mandates compel embedded data lineage features in formation and grading lines.
- Research Laboratories:University and national laboratory channels sustain R&D intensity through multichannel cycler architectures with flexible protocol programming. South Korea's KAIST and Seoul National University battery institutes anchor demand for high-frequency impedance spectroscopy.
- Consumer Electronics:Smartphone and laptop manufacturers prioritize compact, high-throughput grading systems for cylindrical and pouch cell formats.
- Aerospace:Satellite and electric aviation applications demand extreme temperature range validation from cryogenic to elevated thermal profiles.
Automotive OEMs dominate capital deployment; Research Laboratories show the most rapid equipment refresh cycles.
Technology:
Application maturity divides established load testing methodologies from emerging diagnostic platforms gaining production line integration.
- EIS:Electrochemical Impedance Spectroscopy enables non-destructive state-of-health monitoring during formation cycling without interrupting standard charge/discharge workflows. Hyundai Motor Group and SK Innovation pilot lines in South Korea represent early production integration. The technology decomposes boundaries between R&D characterization and inline validation.
- Load Testing:Constant current and power discharge protocols remain ubiquitous in abuse testing and capacity verification. China's NMPA nail penetration and thermal runaway propagation mandates sustain installed base demand for high-power load banks.
- Thermal Imaging:Infrared-based hotspot detection during cycling identifies cell-level defects before catastrophic failure.
- Conductive Testing:Electrical continuity and isolation verification for pack-level assembly quality assurance.
Load Testing maintains the broadest installed base; EIS claims the most aggressive adoption trajectory among new procurement.
Application:
Customer type concentration separates high-volume electric vehicle formation cycling from specialized industrial backup system validation requirements.
- Electric Vehicles:Cell-to-pack verification workflows compress validation cycles as automotive OEMs internalize testing authority. Solid-state and silicon-anode chemistry transitions demand recalibrated protocols that legacy testers cannot achieve. Procurement concentrates in Germany, South Korea, and China.
- Renewable Energy Storage:Grid-scale battery installations require extended cycle life validation under variable temperature and humidity profiles. Utility procurement emphasizes second-life battery diagnostics and state-of-health estimation for warranty risk management.
- Smartphone Batteries:High-throughput grading lines for cylindrical and pouch cell formats prioritize speed over diagnostic depth.
- Industrial Backup Systems:Uninterruptible power supply and telecom backup applications emphasize reliability certification over energy density optimization.
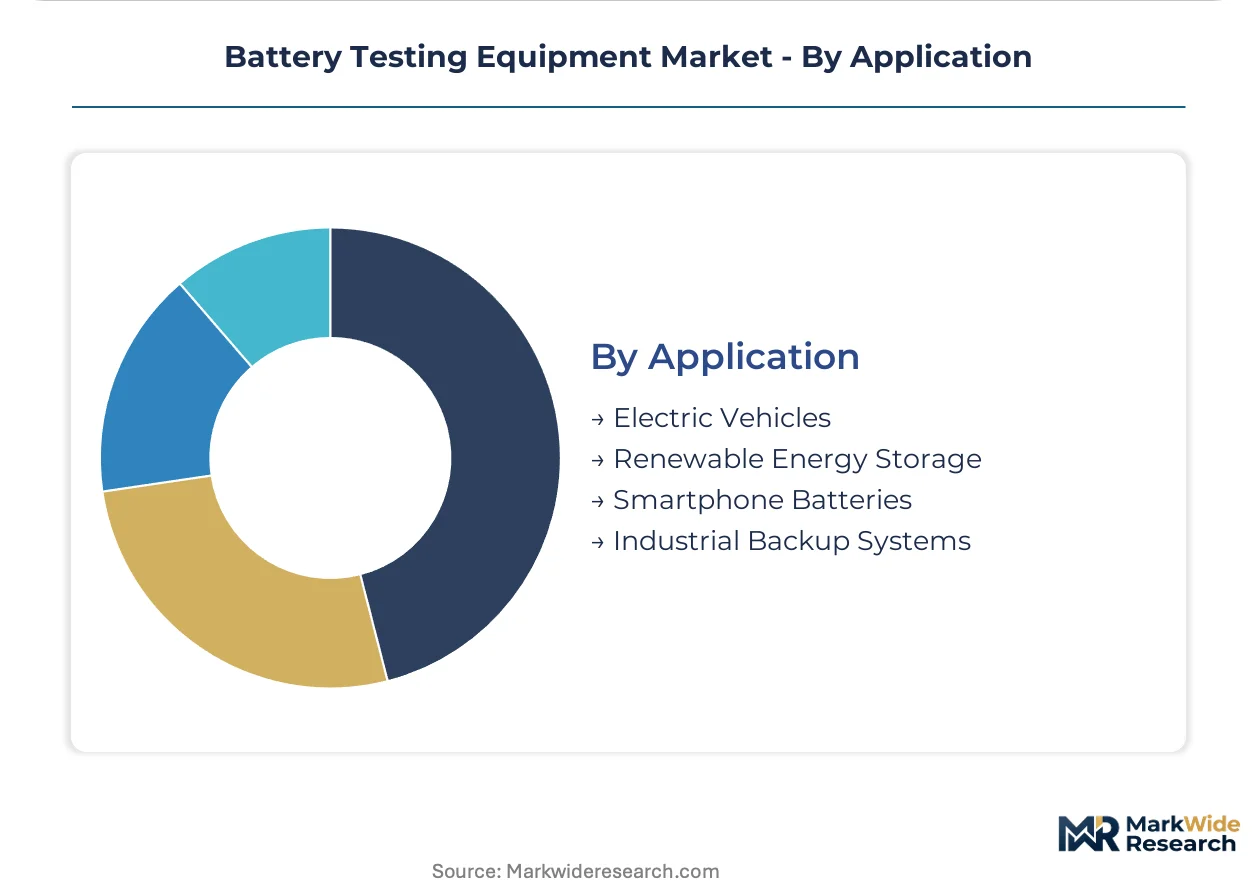
Electric Vehicles command the largest equipment capital allocation; Renewable Energy Storage demonstrates the fastest climb in tester specification complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German testing equipment exports flow into South Korean battery packaging corridors and Chinese formation line expansions, creating a triangular trade pattern that concentrates validation technology procurement in three dominant manufacturing geographies.
United States
NHTSA battery safety mandates and EPA lifecycle transparency standards compel OEMs to maintain traceable test records across cell suppliers. The Detroit automotive engineering corridor concentrates captive validation facility investment as Ford and General Motors internalize solid-state qualification workflows. Equipment procurement emphasizes data lineage features for audit compliance.
Germany
Volkswagen, BMW, and Porsche engineering centers in Bavaria and Baden-Württemberg now specify equipment directly rather than through battery maker channels. ECHA REACH framework amendments on substance restriction force redesign of thermal chamber insulation and coolant chemistries. The Stuttgart-Munich testing corridor anchors European demand for high-frequency impedance spectroscopy platforms.
China
NMPA battery safety mandates and GB standards impose mandatory abuse testing protocols that drive demand for multi-physics coupled test chambers. Yangtze River Delta formation line operators accelerate procurement of cell testers and charge/discharge systems as solid-state chemistry transitions reshape validation protocols. Shanghai and Suzhou concentrate equipment deployment for export-oriented cell manufacturing.
South Korea
Hyundai Motor Group and SK Innovation pilot lines adopt electrochemical impedance spectroscopy-integrated testers for production line diagnostic migration. Semiconductor-battery integration in Busan-Ulsan packaging corridors compresses cell-to-pack verification cycles. Seoul Capital Area research institutes sustain R&D intensity through multichannel cycler architectures.
India
PLI scheme incentive-linked capacity buildouts create first-mover advantage for localized test system deployment in Gujarat and Tamil Nadu battery manufacturing zones. Central Electricity Authority grid-scale storage mandates drive extended cycle life validation requirements. Maharashtra and Karnataka concentrate emerging formation line investments.
Battery Testing Equipment Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and R&D velocity dimensions, producing a tiered structure where scale advantages concentrate in precision instrumentation while agility favors application-specific architectures. Three strategic archetypes dominate: precision heritage players leveraging metrology credibility, integrated platform vendors spanning module-to-pack workflows, and multichannel specialists sustaining academic and national laboratory channels. Competitive moves center on chemistry transition responsiveness and cloud-native data architecture integration.
Within the precision instrumentation tier, Keysight Technologies exemplifies heritage positioning in high-frequency impedance spectroscopy. Chroma Systems Solutions anchors integrated power conversion test platforms. Arbin Instruments occupies the multichannel cycler specialist position serving research laboratory channels.
| Leading Market Players |
|---|
| Arbin Instruments |
| Chroma Systems Solutions |
| Keysight Technologies |
| Hioki |
| Maccor |
| Bitrode Corporation |
| Neware |
| BioLogic |
| Ametek Scientific Instruments |
| Others |
Supply Flow & Price Mechanics
Fourteen-to-eighteen-week lead times for cryogenic sensors and rare earth magnetics concentrate procurement power among German and South Korean equipment vendors, compressing margin pools for mid-tier suppliers while amplifying pricing leverage for precision instrumentation specialists serving solid-state battery qualification workflows.
Pricing Analysis
Next-generation EIS-integrated testers command substantial premiums over legacy charge/discharge architectures, while prior-generation formation cycling equipment faces accelerated depreciation. Three-tier pricing structure across premium, standard, and economy levels separates sub-ppm failure detection systems from modular research-grade units and refurbished legacy platforms. Pricing pressure stems from chemistry transition velocity outpacing equipment amortization schedules. Automotive OEM captive facilities demonstrate lowest price sensitivity; research laboratories and emerging market operators exhibit highest elasticity.
Supply Chain Analysis
Shanghai port congestion and transpacific container availability constraints inflate inbound logistics costs for cryogenic sensor imports feeding German test equipment assembly. Component sourcing draws from China for precision machining, Japan for high-frequency electronics, and the United States for specialized software modules. Single-source vulnerability concentrates in rare earth magnetics supply. Distribution runs through direct OEM specification channels rather than battery maker intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment vendors face substitution defense imperatives as electrochemical impedance spectroscopy platforms displace traditional charge/discharge architectures in production line integration.
For Market Incumbents: Secure backward integration into cryogenic sensor supply chains to mitigate rare earth magnetics concentration risk. Anchor certification investment in ISO 17025 calibration protocols for millisecond sampling resolution maintenance across microamp-to-kiloamp ranges. Defend against modular research-grade entrants by embedding cloud-native data lineage features addressing ECHA REACH audit requirements. For New Entrants and Emerging Players: Lead with second-life battery diagnostics as the most penetrable white-space segment, targeting utility procurement channels in India and renewable energy storage operators requiring state-of-health estimation algorithms. Pursue localized test system deployment in Gujarat and Tamil Nadu manufacturing zones under India's PLI scheme incentives. Position through subscription-based SaaS pricing models for cloud-native data architectures. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across EIS-integrated production line equipment as semiconductor-battery integration compresses validation cycles. Long-term viability favors precision instrumentation specialists with metrology heritage and captive validation facility relationships over modular platform vendors. Target acquisition archetypes include multichannel cycler specialists serving national laboratory channels. Watch for inflection signals in South Korean pilot line EIS adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cryogenic Sensors | Mitigates rare earth magnetics supply concentration risk for Keysight and Chroma precision platforms. |
| Cloud-Native Data Architecture Deployment | Addresses ECHA REACH audit requirements for Volkswagen and BMW captive validation facilities. |
| Second-Life Diagnostics Algorithm Development | Opens utility procurement channels for state-of-health estimation in grid-scale storage applications. |
| Localized Test System Manufacturing | Captures PLI scheme incentives in Gujarat and Tamil Nadu battery manufacturing zones. |
| EIS-Integrated Production Line Pilot | Validates non-destructive monitoring for Hyundai Motor Group and SK Innovation cell-to-pack workflows. |
Methodological Framework
A spread of perspectives from equipment vendor sales directors, automotive OEM platform engineers, national laboratory principal investigators, and semiconductor packaging specialists converged on the working assumptions underlying chemistry transition timelines and validation protocol evolution. Primary interview intelligence combined with secondary validation from NHTSA safety filings, ECHA REACH substance restriction amendments, NMPA GB standards documentation, and SEC equipment manufacturer disclosures. Bottom-up equipment unit economics triangulated against top-down automotive battery capacity buildout projections.
Segmentation dimensions modeled span product type, end user archetype, technology maturity, and application vertical across the analysis window. CAGRs derived from equipment procurement cycle compression rates and replacement demand elasticity under chemistry transition scenarios. Industry-specific forecast inputs incorporated solid-state battery pilot line deployment schedules and EU Green Deal battery passport implementation timelines.
The analysis sits within stated boundaries; outcomes outside sustained solid-state chemistry transition momentum or accelerated regulatory mandate enforcement would require recalibration. Forecasts reflect assumptions on equipment depreciation cycle compression and metrology talent concentration persistence. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Sound Level Measurement Meter Market
Test and Measurement
Photometer and Calorimeter Market
Test and Measurement
VXI Testing Equipment Market
Test and Measurement
Circuit Tracer Market
Test and Measurement
Miniature Atomic Clock Market
Test and Measurement
VXI Test Equipment Market
Test and Measurement
Environmental Test Chambers Market
Test and Measurement
Height Measurement Devices Market
Test and Measurement
Hearing Aid and True Wireless Earbud Acoustic Performance Test Systems Market
Test and Measurement
Quantum Key Distribution System Performance and Security Test Equipment Market
Test and Measurement
Handheld Digital Multimeter Market
Test and Measurement
Data Acquisition Equipment Market
Test and Measurement
Calibration Solutions Market
Test and Measurement
E-Beam Wafer Inspection System Market
Test and Measurement
Water Leakage Tester Market
Test and Measurement
EMC Shielding and Test Equipment Market