
 Calibration Management Software Market | 2026-2036
Calibration Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Calibration Management Software Market Analysis
Pharmaceutical manufacturing is realigning calibration workflows around electronic records and automated scheduling to satisfy FDA 21 CFR Part 11 validation mandates. Beamex Oy Ab leverages its native integration with distributed control systems to anchor position in process industries. Fluke Corporation sustains brand strength through hardware-software bundling across industrial maintenance channels. CyberMetrics Corporation specializes in multi-site compliance tracking for heavily regulated facilities.
Calibration management software governs the scheduling, execution, documentation, and traceability of instrument calibration events across laboratory and production environments, typically supporting tolerance thresholds of 0.1% to 0.01% of full scale depending on instrument criticality. Cloud-based deployment leads product type adoption as manufacturers prioritize remote access and reduced IT overhead for distributed operations. Compliance tracking within the solution segment commands premium pricing due to audit-readiness requirements in pharmaceutical and aerospace end users. On-premises installations retain share in defense and nuclear applications where air-gapped security protocols prevail.
FDA enforces instrument calibration as a predicate for current Good Manufacturing Practice compliance, while ISO/IEC 17025 accreditation standards shape laboratory software procurement in testing facilities across Germany, Japan, and the United States. The EU AI Act and MDR frameworks in Europe are extending traceability requirements into automated calibration decision systems. Stakeholders must monitor convergence between calibration data and enterprise quality management platforms to anticipate platform consolidation decisions.
Market Dynamics
Pharmaceutical manufacturers are compressing calibration cycles to satisfy intensifying FDA validation scrutiny, forcing software vendors to embed automated audit trails and electronic signature workflows as standard features rather than premium add-ons.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records mandates in pharmaceutical manufacturing are mandating software with automated calibration scheduling and tamper-proof documentation, pulling demand from paper-based systems.
- Cloud-native architectures:Life sciences firms are prioritizing browser-based platforms to reduce IT overhead across distributed manufacturing sites and contract research organizations.
- ISO/IEC 17025 accreditation:Testing laboratories in Germany, Japan, and the United States are procuring integrated calibration-quality management modules to satisfy auditor traceability requirements.
Market Restraints
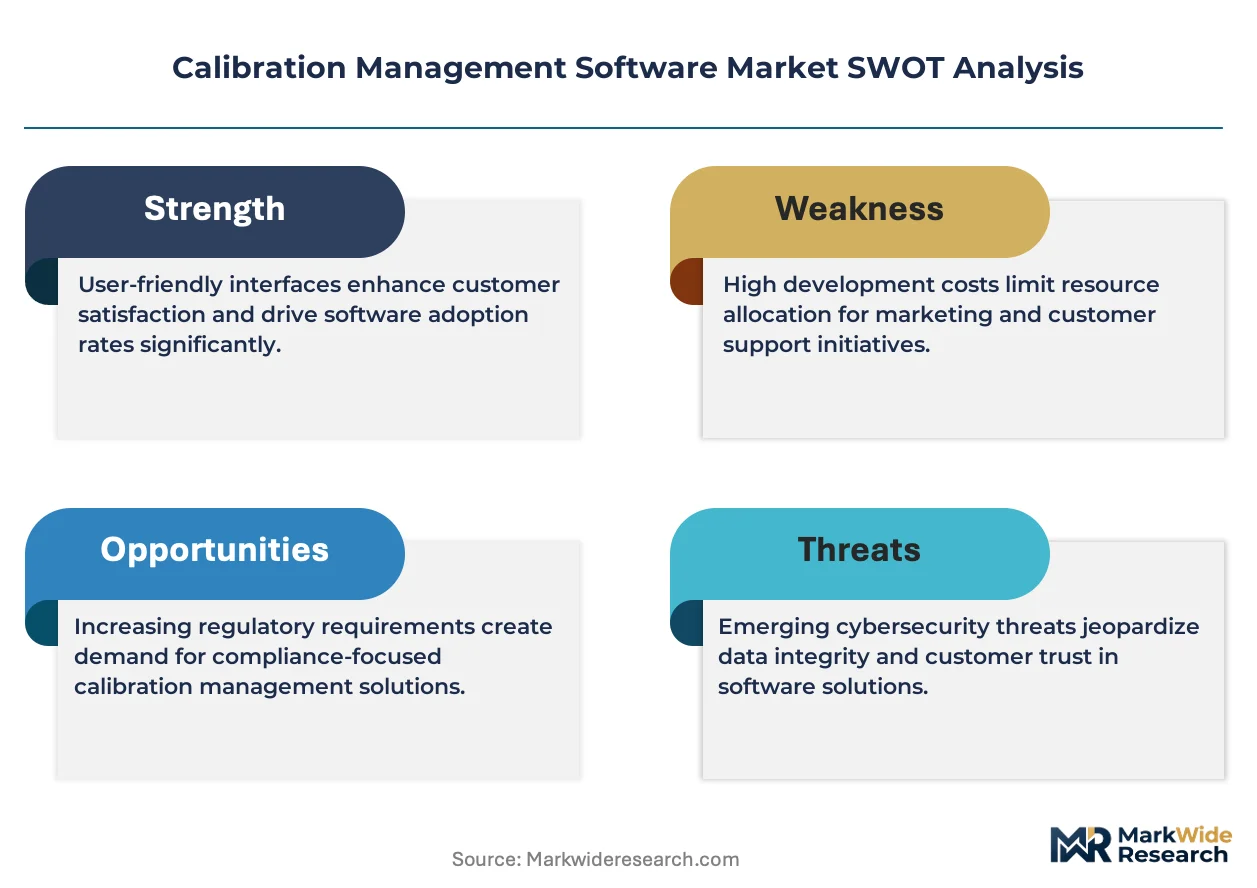
- Air-gapped security protocols:Defense and nuclear facilities in the United States mandate on-premises installations, blocking cloud revenue streams from high-budget segments.
- Legacy instrument incompatibility:Decades-old field devices in process industries lack digital interfaces, requiring costly middleware or manual data entry that erodes automation ROI.
- Specialized talent scarcity:Metrology engineers capable of configuring tolerance thresholds at 0.01% full scale precision command premium salaries that inflate implementation costs.
Strategic Opportunities
- EU AI Act traceability extensions:Automated calibration decision systems in Europe face new algorithmic audit requirements, creating demand for AI-governed validation modules.
- Medical device manufacturing:EU MDR framework expansion is forcing small-batch producers to adopt electronic calibration records for the first time.
- Edge computing convergence:Integration of calibration software with IoT sensor networks enables real-time drift detection in semiconductor fabrication facilities.
Industry Challenges
- Enterprise quality platform integration:Calibration data must map to SAP, Oracle, and Veeva systems without custom API development, stretching vendor engineering resources.
- Multi-site harmonization:Global pharmaceutical firms struggle to standardize calibration intervals across FDA, EMA, and PMDA jurisdictions with conflicting tolerance interpretations.
- Cybersecurity certification timelines:FedRAMP and ISO 27001 accreditation for cloud deployments delay market entry by 12-18 months for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calibration Management Software Market |
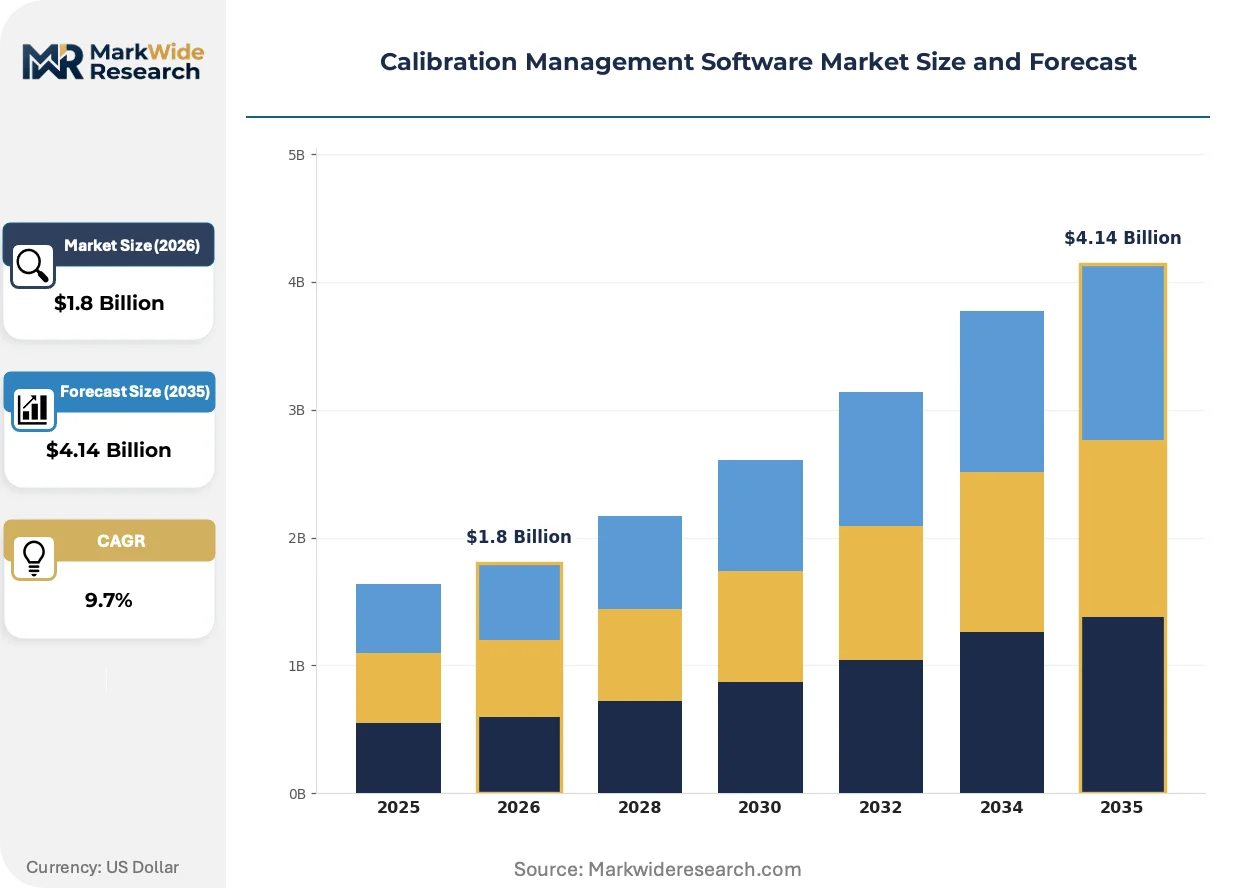
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premises, Mobile, Hybrid End User: Aerospace, Pharmaceutical, Manufacturing, Automotive Deployment: Public Cloud, Private Cloud, On-Site, Multi-Tenant Solution: Quality Assurance, Compliance Tracking, Inventory Management, Scheduling |
| Companies Covered | Fluke Corporation, Beamex Oy Ab, CyberMetrics Corporation, Prime Technologies, CompuCal Calibration Solutions, MasterControl, Ape Software Inc., AcTouch.com, ETQ LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calibration Management Software Market Emerging Trajectories
Artificial intelligence is penetrating calibration decision workflows, compressing the interval between instrument drift detection and corrective action while regulators scramble to define acceptable algorithmic evidence standards.
Machine learning-based predictive calibration is consolidating maintenance schedules across pharmaceutical production lines. Merck and Pfizer manufacturing sites are deploying neural networks that analyze historical drift patterns to dynamically adjust calibration frequencies. This capability is consolidating vendor competitive position around data science expertise rather than traditional metrology credentials.
The EU AI Act is extending algorithmic traceability requirements into automated calibration systems used for critical quality decisions. Medical device manufacturers in Ireland and the Netherlands must now document training data provenance and model validation protocols. Compliance tracking modules command 40-60% pricing premiums as audit-readiness becomes a procurement gate.
Buyer concentration among contract manufacturing organizations is forcing software vendors to unbundle implementation services from perpetual licenses. Large CMOs in the United States now demand API-first architectures that enable self-service integration with existing quality infrastructure. This shift is most visible in the Boston-Cambridge biotech cluster where procurement teams prioritize interoperability over feature depth.
Calibration Management Software Market Segmentation
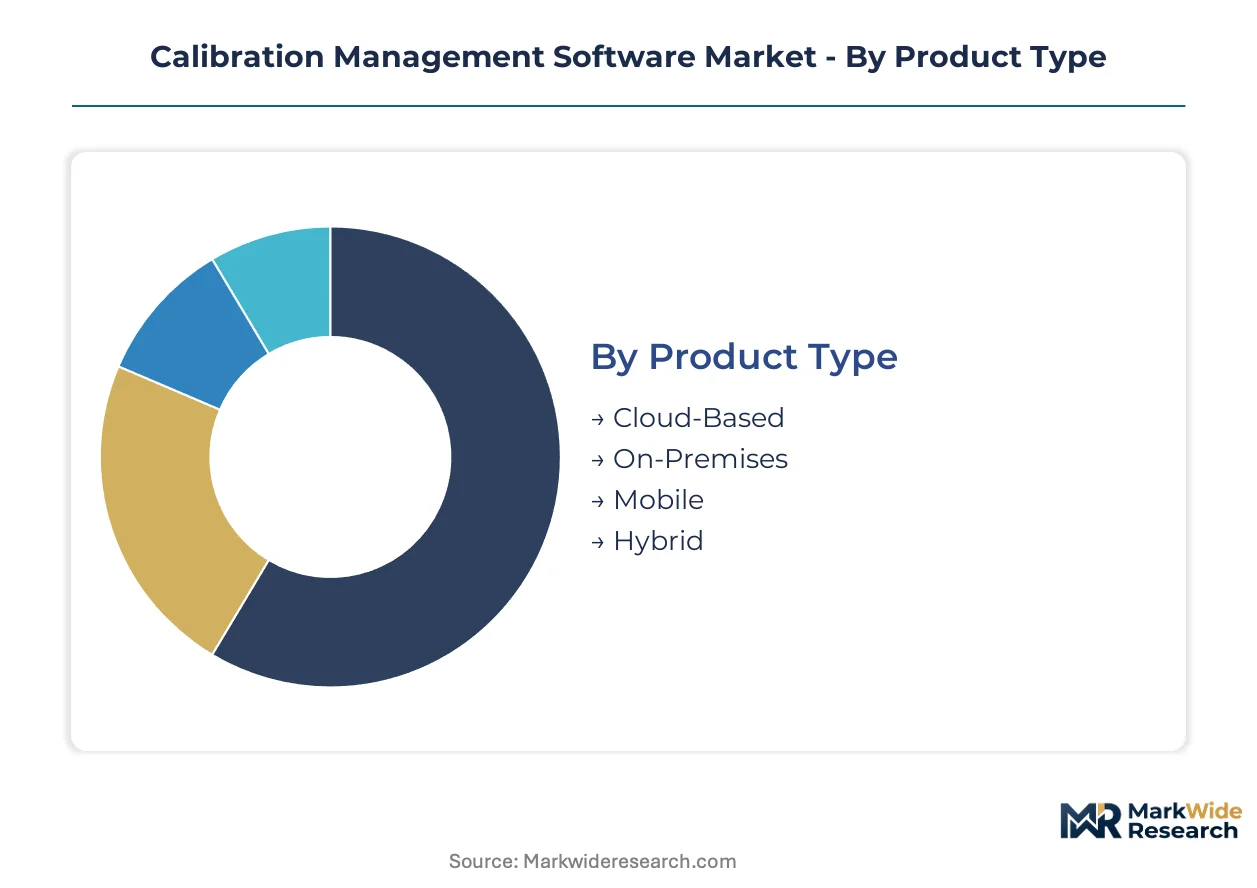
Calibration management software procurement diverges sharply across deployment architectures and regulatory exposure levels. Buyers prioritize audit-readiness capabilities in pharmaceutical applications while manufacturing segments weigh total cost of ownership against integration complexity.
Product Type:
Deployment economics and IT resource constraints drive buyer selection between cloud-native and legacy architectures.
- Cloud-Based:Browser-accessible platforms eliminate server maintenance burdens and enable real-time collaboration across distributed manufacturing sites. Life sciences firms in the United States concentrate procurement here to satisfy FDA remote inspection capabilities while reducing capital expenditure.
- On-Premises:Air-gapped installations run entirely within facility firewalls, supporting defense and nuclear applications where data sovereignty mandates block external connectivity. These deployments command premium service contracts due to specialized hardening requirements.
- Mobile:Native iOS and Android applications extend calibration execution to field technicians without workstation dependency.
- Hybrid:Architectures synchronize on-premises instrument databases with cloud analytics layers for centralized reporting.
Volume sits with Cloud-Based; growth tilts toward Hybrid.
End User:
Regulatory stringency and instrument density determine software sophistication requirements across verticals.
- Pharmaceutical:FDA 21 CFR Part 11 mandates electronic signatures, audit trails, and tamper-proof records for every calibration event. Batch release processes in New Jersey and Massachusetts facilities require real-time compliance dashboards that integrate with quality management systems.
- Aerospace:AS9100 standards and FAA airworthiness directives impose traceability chains from calibration standards through flight-critical measurements. Defense contractors in California and Texas maintain on-premises installations to satisfy ITAR data handling protocols.
- Manufacturing:Process industries prioritize tolerance threshold automation over documentation depth, accepting lighter compliance modules.
- Automotive:IATF 16949 requirements drive calibration integration with statistical process control systems on production lines.
Compliance spending concentrates in Pharmaceutical; Manufacturing delivers the steepest expansion trajectory.
Deployment:
Infrastructure control preferences segment buyers between shared and isolated computing environments.
- Public Cloud:Shared infrastructure delivers lowest per-seat pricing and automatic security patching, attracting mid-market pharmaceutical contract manufacturers.
- Private Cloud:Dedicated single-tenant instances isolate data from co-tenancy risks while retaining cloud operational benefits.
- On-Site:Physical servers within facility boundaries satisfy nuclear regulatory commission cybersecurity mandates.
- Multi-Tenant:Architectures enable parent companies to partition calibration data across subsidiary operations with unified administrative oversight.
Private Cloud captures premium budgets; Public Cloud scales fastest.
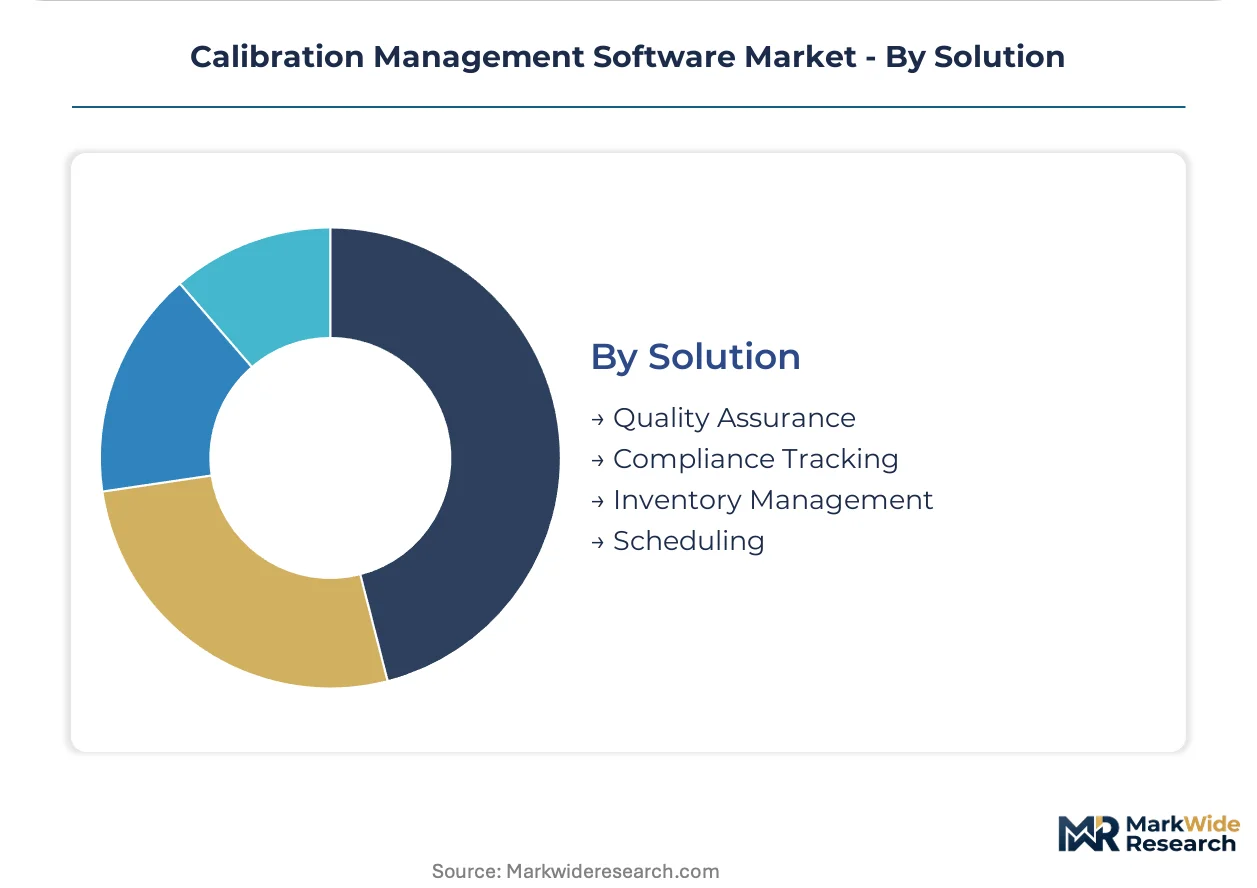
Solution:
Functional module selection reflects organizational maturity in quality system digitization.
- Compliance Tracking:Automated audit preparation, regulator-ready documentation packages, and deviation workflow management command 40-60% pricing premiums. Medical device manufacturers in Ireland and the Netherlands procure these modules first to satisfy EU MDR technical documentation requirements.
- Scheduling:Predictive algorithms analyze historical drift patterns to optimize calibration intervals, reducing instrument downtime in continuous pharmaceutical production. Neural network capabilities differentiate vendor positioning in this segment.
- Quality Assurance:Modules map calibration data to statistical process control charts and corrective action systems.
- Inventory Management:Functions track calibration standard provenance, recall status, and inter-laboratory comparison schedules.
Compliance Tracking dominates revenue; Scheduling gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Ireland and the Netherlands concentrate pharmaceutical calibration software procurement as EU MDR technical documentation requirements reshape vendor selection criteria across European manufacturing clusters.
United States
FDA 21 CFR Part 11 enforcement compresses calibration cycles at pharmaceutical contract manufacturers. Life sciences firms in the Boston-Cambridge corridor prioritize browser-based platforms with real-time compliance dashboards for remote inspection readiness. New Jersey and Massachusetts facilities drive cloud-native adoption as batch release processes demand tamper-proof electronic records.
Germany
ISO/IEC 17025 accreditation standards govern laboratory software procurement in testing facilities across Bavaria and North Rhine-Westphalia. Industrial metrology clusters in Stuttgart and Munich anchor demand for automated tolerance threshold configuration at 0.01% full scale precision. German automotive suppliers integrate calibration modules with statistical process control systems under IATF 16949 mandates.
Japan
PMDA quality system regulations extend traceability requirements into pharmaceutical manufacturing sites in Kanto and Kansai regions. Tokyo and Osaka facilities deploy predictive calibration algorithms to optimize instrument downtime in continuous production. Japanese semiconductor fabricators in Kyushu pioneer edge computing convergence for real-time drift detection.
Ireland
EU MDR framework expansion forces medical device manufacturers in Dublin and Cork to adopt electronic calibration records for the first time. IDA Ireland tax incentives attract pharmaceutical multinationals requiring automated audit trail documentation. Galway and Limerick clusters concentrate compliance tracking module procurement at 40-60% pricing premiums.
Netherlands
Algorithmic traceability requirements under EU AI Act reshape automated calibration decision systems in Eindhoven and Rotterdam manufacturing zones. ASML supplier networks demand AI-governed validation modules for semiconductor fabrication calibration. Dutch life sciences firms in Leiden and Amsterdam prioritize API-first architectures for self-service quality infrastructure integration.
Calibration Management Software Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with calibration software vendors fragmenting between hardware-integrated platforms and pure-play SaaS providers. Market structure tilts toward tiered competition where native distributed control system integration anchors premium positioning. Three archetypes dominate: instrumentation conglomerates bundling software with sensor hardware, compliance-focused specialists targeting FDA-regulated facilities, and cloud-native entrants unbundling implementation services. Consolidation pressure intensifies through strategic partnerships with enterprise quality management platforms and vertical integration into predictive maintenance analytics.
Within the instrumentation-integrated tier, Fluke Corporation and Beamex Oy Ab exemplify hardware-software bundling strategies that sustain industrial maintenance channel presence. CyberMetrics Corporation occupies a distinct position among compliance specialists, anchoring multi-site tracking capabilities for heavily regulated pharmaceutical and aerospace facilities. These three companies represent divergent competitive vectors: sensor ecosystem leverage, process industry control system integration, and audit-readiness module specialization.
| Leading Market Players |
|---|
| Fluke Corporation |
| Beamex Oy Ab |
| CyberMetrics Corporation |
| Prime Technologies |
| CompuCal Calibration Solutions |
| MasterControl |
| Ape Software Inc. |
| AcTouch.com |
| ETQ LLC |
| Others |
Supply Flow & Price Mechanics
Cloud infrastructure pricing indices from AWS, Azure, and Google Cloud Platform cascade through SaaS vendor cost structures, compressing margins for calibration management software providers while forcing tiered service packaging around compliance module depth.
Pricing Analysis
Short lead-time premiums for FedRAMP-accredited cloud deployments command 25-40% markups over standard SaaS tiers, while spot inventory of on-premises licenses trades at distressed multiples. Pricing stratifies across premium compliance-tracking bundles, standard scheduling modules, and economy-tier calibration logs based on audit-readiness certification and API integration depth. Cost compression in the mid-market stems from contract manufacturing organizations consolidating vendor relationships. Pharmaceutical quality directors show lowest price sensitivity; small-batch medical device producers exhibit highest.
Supply Chain Analysis
Metrology engineer scarcity in Germany, Japan, and the United States constrains implementation capacity for precision-tolerance configurations. Software development draws from Indian and Polish engineering hubs, while cloud infrastructure rests on hyperscaler data centers in Virginia, Frankfurt, and Singapore. Single-source vulnerability concentrates in FDA validation consulting networks. Distribution runs through direct enterprise sales teams and quality management system channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise quality platform consolidation pressures standalone calibration vendors, forcing acquisition or partnership decisions as SAP, Oracle, and Veeva absorb workflow functionality.
For Market Incumbents: Extend predictive analytics capabilities through native machine learning modules to defend against cloud-native entrants. Beamex and Fluke should deepen distributed control system integration as hardware-software bundling faces API-first disintermediation from Boston-Cambridge procurement teams. Certification investment in EU AI Act algorithmic traceability creates switching costs.
For New Entrants and Emerging Players: The premium-economy price gap in compliance tracking modules opens mid-market entry for browser-native platforms with self-service configuration. Target pharmaceutical contract manufacturing organizations in New Jersey and Massachusetts with lightweight FDA 21 CFR Part 11 templates. Go-to-market through GPO contracts with hospital system quality infrastructure.
For Investors and Strategic Acquirers: Distressed-cycle entries favor compliance-specialist SaaS vendors with sticky pharmaceutical customer bases in Ireland and the Netherlands. Long-term viability hinges on data science talent retention against instrumentation conglomerates. Watch EU MDR enforcement velocity as inflection signal for compliance module demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native SAP and Oracle connectors reduce implementation friction for pharmaceutical quality directors. |
| Acquisition of Specialist Firm | Machine learning calibration startups add predictive drift detection to legacy vendor portfolios. |
| Regulatory Certification Program | FedRAMP and ISO 27001 accreditation unlocks defense and nuclear facility procurement pipelines. |
| Geographic Expansion | Irish and Dutch medical device clusters demand EU MDR-compliant electronic calibration records. |
| Strategic Partnership | Hyperscaler alliances reduce cloud infrastructure costs for mid-market SaaS pricing competitiveness. |
Methodological Framework
SEC filings, FDA 483 inspection databases, and ISO/IEC 17025 accreditation registries formed the secondary backbone, cross-referenced against primary interviews with pharmaceutical quality directors, metrology engineers, calibration software product managers, and GPO contracts managers. Bottom-up and top-down triangulation validated deployment model splits and end-user segment sizing across the analysis window.
Bottom-up modeling aggregated individual customer account profiles by deployment architecture, solution module penetration, and vertical regulatory exposure, while top-down checks applied software-as-a-service spending ratios to life sciences IT budgets. CAGRs derived from logistic adoption curves calibrated to FDA enforcement intensity and cloud migration velocity. Segmentation dimensions spanned deployment model, organization size, vertical compliance stringency, integration complexity, and regional regulatory cluster.
Inputs from hyperscaler pricing disclosures and pharmaceutical quality spending surveys were available through the study window; gaps in small-batch medical device manufacturer procurement data introduce uncertainty bands around EU MDR adoption trajectories. Forecasts reflect assumptions about regulatory enforcement continuity and cloud security accreditation timelines. Material deviation in FDA inspection frequency or EU AI Act implementation pace warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Continuous Friction Tester Market
Test and Measurement
Electronic Test Instrument Market
Test and Measurement
Solid-State Battery Fast-Charge Degradation Test Systems Market
Test and Measurement
Digital Weighing Terminal Market
Test and Measurement
Next-Generation Industrial Metrology and Inspection Market
Test and Measurement
United States Signal Generator Market
Test and Measurement
Brightness Meter Market
Test and Measurement
Semiconductor Chip Test Probes Market
Test and Measurement
Portable Appliance Tester (PAT) Market
Test and Measurement
Protective Earth Resistance Meter Market
Test and Measurement
Network Tester Market
Test and Measurement
RFID Tester Market
Test and Measurement
Volte Testing Market
Test and Measurement
Shock Testing System Market
Test and Measurement
Bit Error Rate Tester Market
Test and Measurement
Digital Weighing Machine Market