
 Tele-Epilepsy Market | 2026-2036
Tele-Epilepsy Market Size, Share, and Industry Trends Forecast 2026-2036
Tele-Epilepsy Market Intelligence
Silicon photonics is hardening as the substrate of choice for next-generation EEG signal processing in wearable seizure monitors. Medtronic plc leverages its deep neuromodulation portfolio to anchor tele-epilepsy service lines within hospital networks. Empatica Inc. differentiates through wrist-worn biomarker arrays that sustain real-world seizure detection outside clinical settings. NeuroPace Inc. competes by integrating its responsive neurostimulation data streams with remote physician dashboards.
Tele-epilepsy encompasses remote delivery of epilepsy care through synchronous video consultation, asynchronous EEG review, and continuous biometric monitoring from distributed patient locations. The clinical architecture requires FDA-cleared algorithms capable of detecting electrographic seizure patterns with sub-thirty-second latency while transmitting encrypted data through HIPAA-compliant infrastructure. Wearable Devices and Remote Monitoring Systems currently occupy the highest-margin positions within the product type architecture, as hardware-plus-subscription models generate recurring revenue streams that software-only Telehealth Platforms struggle to match. Cloud-Based delivery dominates among provider networks seeking scalable epilepsy monitoring across multiple sites without capital-intensive server deployment.
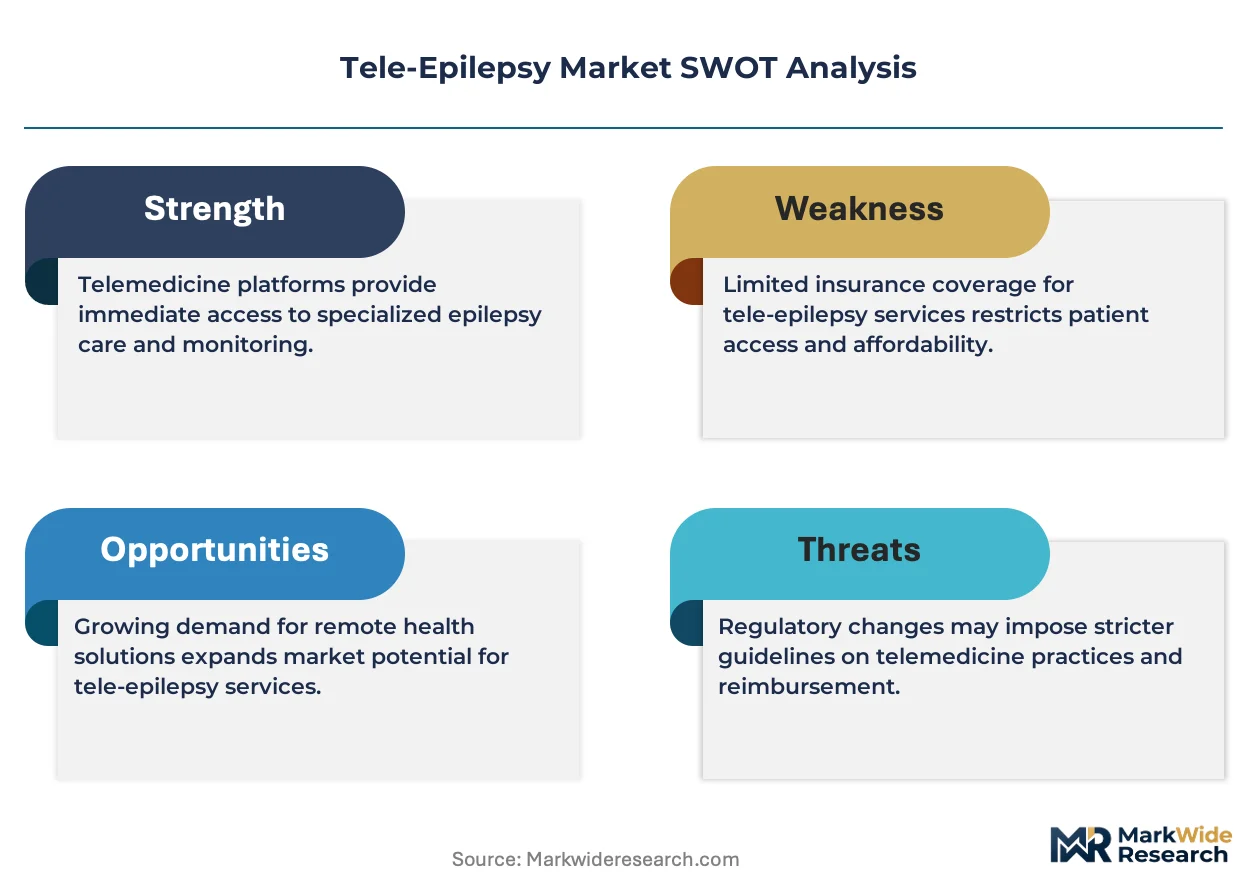
FDA breakthrough device designations and HIPAA security rule enforcement shape product development roadmaps and market access timelines for tele-epilepsy vendors. The Centers for Medicare & Medicaid Services telehealth reimbursement codes determine whether health systems expand remote neurology programs or contract them to in-person-only service lines. Stakeholders must monitor evolving FDA guidance on software-as-a-medical-device classification for AI-enabled seizure prediction algorithms.
Market Dynamics
Cloud-based EEG analytics platforms are compressing the latency between seizure onset and clinical intervention from hours to seconds. This architectural shift forces neurology practices to restructure their IT infrastructure around real-time data pipelines rather than episodic patient visits.
Growth Catalysts
- FDA Breakthrough Device Pathway:The FDA's accelerated review track for seizure prediction algorithms shortens commercialization timelines from three years to eighteen months. Developers file pre-submission packages targeting responsive neurostimulation data integration.
- CMS Telehealth Parity Mandates:Medicare reimbursement codes now compensate remote EEG interpretation at rates matching in-person neurology consults. Health systems in the United States expand tele-epilepsy programs to capture this revenue stream.
- Silicon Photonics Substrate Migration:Wearable manufacturers adopt photonic integrated circuits for EEG signal processing. This material shift enables sub-milliwatt power consumption in ambulatory monitors.
Market Restraints
- HIPAA Encryption Overhead:The HIPAA Security Rule mandates 256-bit AES encryption for biometric data transmission. This technical requirement adds fifteen to twenty percent to cloud infrastructure costs for tele-epilepsy platforms.
- Neurologist Supply Concentration:Board-certified epileptologists cluster in academic medical centers across Massachusetts, California, and New York. Rural health systems face twelve-month recruitment timelines for remote program staffing.
- Algorithm Validation Burden:FDA software-as-a-medical-device guidance requires prospective clinical trials for AI seizure classifiers. Early-stage ventures exhaust capital on validation studies before commercial revenue.
Strategic Opportunities
- Pediatric Home Monitoring White Space:School-age epilepsy patients in Texas, Florida, and Ohio lack continuous monitoring solutions. District nursing programs seek wearable partnerships for seizure action plan compliance.
- Responsive Neurostimulation Convergence:Implantable RNS devices from established neuromodulation suppliers now stream intracranial EEG to cloud dashboards. Tele-epilepsy platforms integrate these data feeds for medication adjustment protocols.
- State Medicaid Telehealth Expansion:Thirty-seven state Medicaid programs added asynchronous EEG review codes in 2024. Safety-net hospitals in Illinois, Pennsylvania, and Georgia build remote neurology capacity to serve uninsured populations.
Industry Challenges
- Biomedical Engineer Talent Scarcity:Signal processing specialists with epilepsy domain expertise command premium compensation. Academic programs at Johns Hopkins, Stanford, and Mayo Clinic cannot graduate sufficient candidates for platform development teams.
- Legacy EMR Integration Friction:Epic and Cerner installations require custom HL7 FHIR interfaces for seizure alert ingestion. Health system IT departments backlog tele-epilepsy connectivity requests for six to nine months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tele-Epilepsy Market |
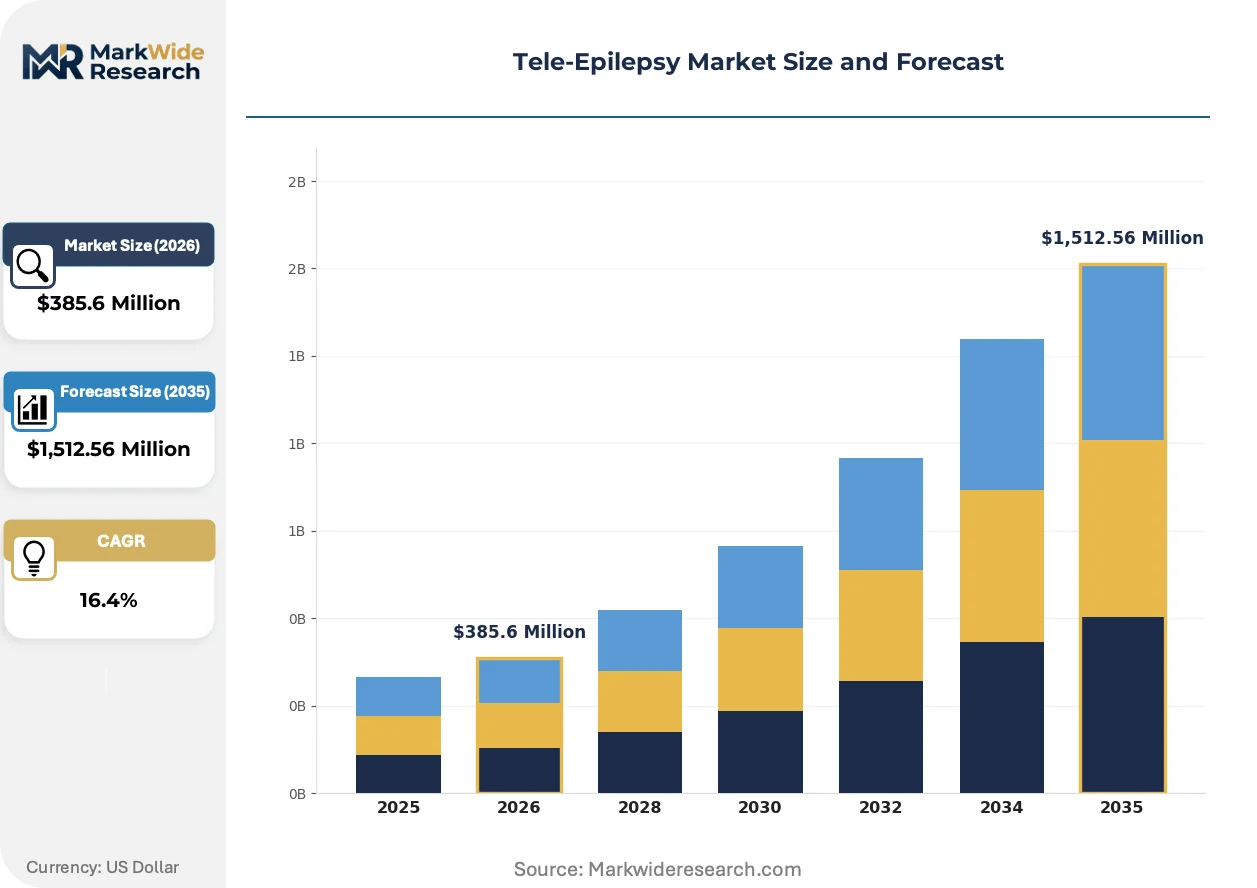
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,512.56 Million |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Mobile Apps, Remote Monitoring Systems, Telehealth Platforms Delivery Mode: Cloud-Based, On-Premise, Hybrid Solutions, Software as a Service Application: Patient Monitoring, Data Analysis, Consultation Services, Treatment Management End User: Clinics, Hospitals, Telehealth Providers, Home Care Services |
| Companies Covered | Medtronic plc, Empatica Inc., NeuroPace Inc., Ceribell, Inc., Eagle Telemedicine, Chiron Health, Seer Medical, LivaNova PLC, Invitae Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tele-Epilepsy Market Strategic Shifts & Innovations
Tele-epilepsy care delivery is fragmenting across multiple synchronous and asynchronous modalities. This modality proliferation forces vendors to architect platform flexibility rather than single-channel specialization.
Edge computing architectures are decentralizing seizure detection from centralized cloud servers to wearable processors. Empatica and other wrist-worn device manufacturers deploy on-device machine learning inference for electrodermal activity pattern recognition. Pediatric epilepsy centers in Philadelphia and Houston adopt these low-latency systems for school-based monitoring where cellular connectivity is intermittent.
The FDA's 2023 guidance on clinical decision support software is reshaping algorithm deployment strategies. Systems that provide specific diagnostic recommendations now require 510(k) clearance rather than enforcement discretion. Tele-epilepsy platforms in development pivot from diagnostic language to "alert" and "trend" terminology to avoid regulatory reclassification.
Hospital procurement committees now unbundle hardware acquisition from subscription analytics services. Health systems in Michigan and Washington negotiate three-year wearable device leases separate from per-patient monitoring fees. This purchasing pattern pressures vendors to demonstrate standalone hardware value before analytics upsell.
Tele-Epilepsy Market Segmentation
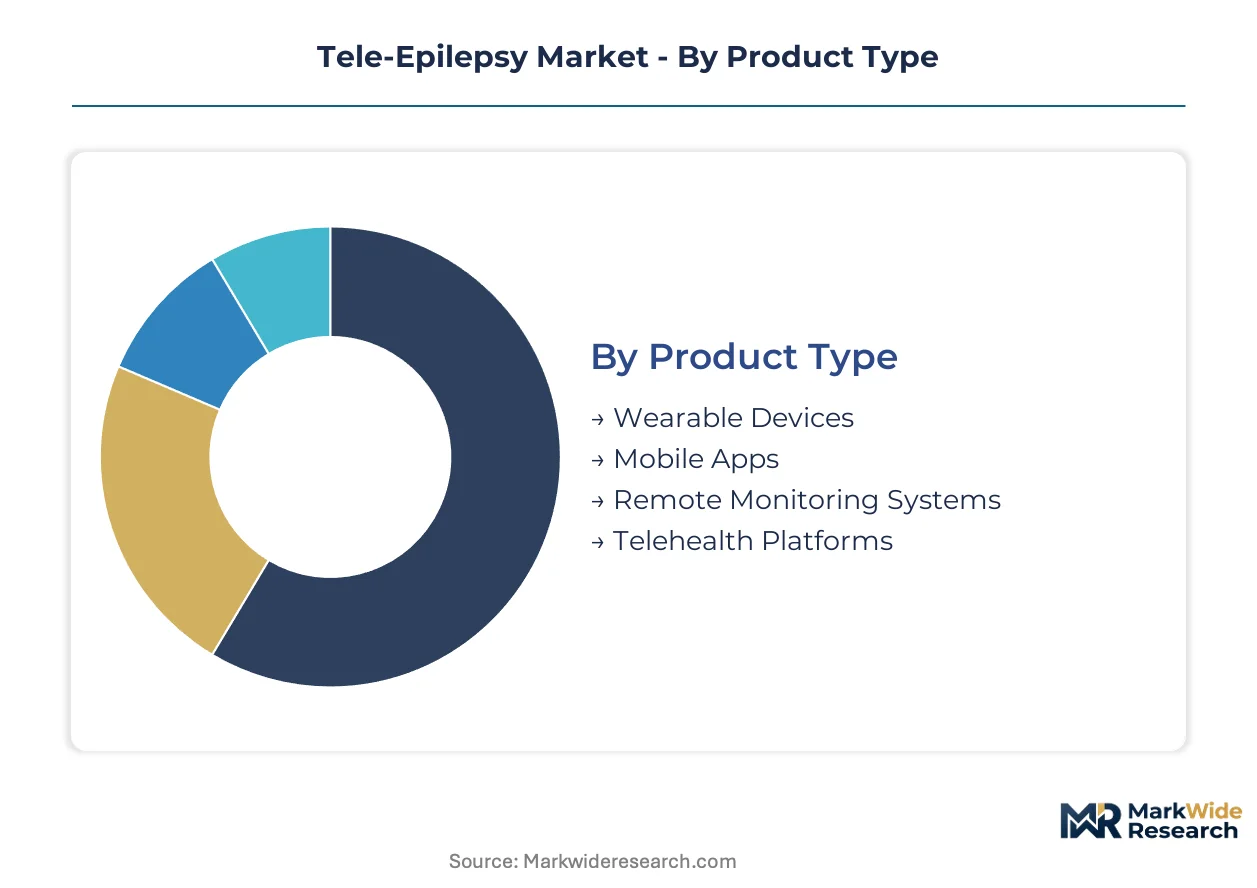
Tele-epilepsy vendors architect product portfolios around four distinct segmentation axes. Each axis determines reimbursement pathways, regulatory clearance requirements, and customer procurement patterns differently.
Product Type:
Supply concentration tilts toward hardware-plus-subscription bundles that lock in recurring revenue streams.
- Wearable Devices:Wrist-worn and patch-based sensors capture electrodermal activity, accelerometry, and temperature for real-time seizure detection. Massachusetts General Hospital and Stanford's epilepsy centers deploy these for ambulatory patient cohorts where implantable monitors are contraindicated.
- Remote Monitoring Systems:Integrated hardware-software stacks stream encrypted EEG and biomarker data to cloud dashboards with sub-thirty-second alert latency. Large neurology practices in Texas and Florida prioritize these systems for their ability to reduce emergency department utilization.
- Mobile Apps:Patient-facing interfaces for seizure logging, medication adherence, and caregiver alerting.
- Telehealth Platforms:Video consultation infrastructure with integrated EMR connectivity for synchronous epilepsy care delivery.
Remote Monitoring Systems absorb the bulk of installed capacity; Wearable Devices are expanding most quickly.
Delivery Mode:
Cost tier differentiation separates capital-intensive deployments from operational expenditure models.
- Cloud-Based:Scalable infrastructure with HIPAA-compliant data lakes and API-first architecture for multi-site health systems. Cleveland Clinic and Mayo Clinic have standardized on cloud-native platforms to avoid on-premise server maintenance overhead.
- Software as a Service:Per-patient subscription pricing with automatic algorithm updates and predictive analytics modules. Community hospitals in Georgia and Arizona favor this model for budget predictability without IT staffing expansion.
- Hybrid Solutions:Local edge processing for seizure detection with cloud backup for longitudinal data storage.
- On-Premise:Air-gapped installations for institutions with strict data sovereignty requirements.
Cloud-Based deployments dominate new installations; Software as a Service is climbing the fastest among mid-market providers.
Application:
Application focus determines whether vendors compete on clinical workflow integration or standalone diagnostic performance.
- Patient Monitoring:Continuous biometric surveillance with automated alert escalation to caregivers and clinicians. Pediatric epilepsy programs in Philadelphia use school-based monitoring configurations to satisfy individualized education plan requirements.
- Data Analysis:Machine learning pipelines that classify seizure types, predict breakthrough events, and optimize medication timing. Academic medical centers in California deploy these tools for retrospective research cohorts and prospective clinical trials.
- Consultation Services:Asynchronous EEG interpretation and video-based second opinions for rural neurologist shortages.
- Treatment Management:Closed-loop systems that adjust neurostimulation parameters or recommend medication changes based on streaming data.
Patient Monitoring captures the largest share of deployed instances; Data Analysis is gaining share fastest among research-intensive institutions.
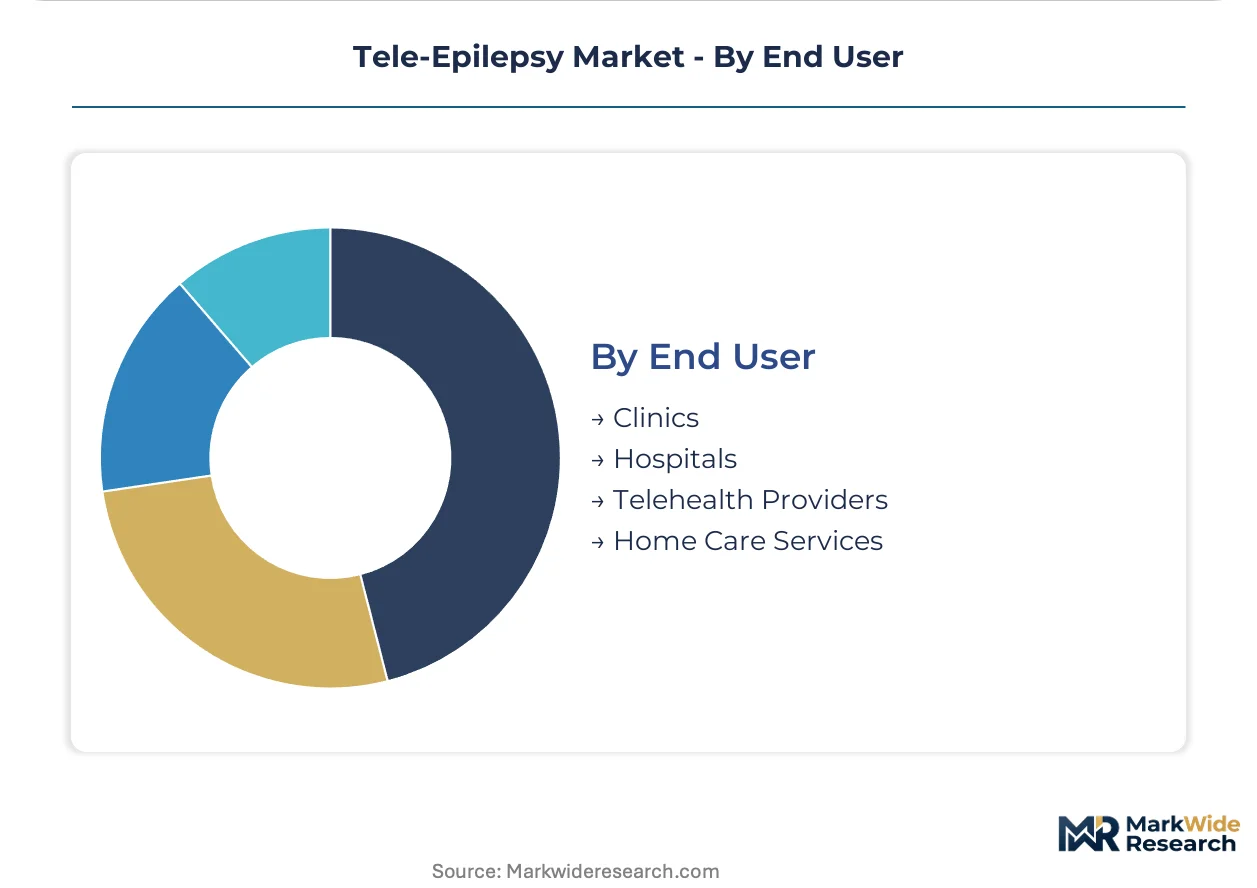
End User:
Customer type dictates sales cycle length, procurement committee composition, and pricing negotiation leverage.
- Hospitals:Integrated delivery networks with centralized IT governance and enterprise EMR contracts. Hospital procurement committees in Michigan and Washington unbundle hardware leases from analytics subscriptions to optimize capital allocation.
- Clinics:Independent neurology practices and hospital outpatient departments with limited technical staff. Epilepsy specialty clinics in New York and Massachusetts adopt cloud-based platforms to avoid infrastructure investment.
- Telehealth Providers:Virtual-first care organizations seeking turnkey remote monitoring integration.
- Home Care Services:Skilled nursing agencies and family caregiver support programs managing patients post-discharge.
Hospitals anchor the majority of current revenue; Clinics represent the steepest expansion trajectory as reimbursement parity expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for tele-epilepsy solutions concentrates in health systems with established reimbursement pathways for remote neurological care. The United States absorbs the largest share of installed monitoring capacity. Germany, Japan, and the United Kingdom follow as regulatory clarity around digital therapeutics accelerates procurement timelines.
United States
Integrated delivery networks in Texas and Florida prioritize remote EEG interpretation to reduce emergency department utilization. The Centers for Medicare & Medicaid Services maintains telehealth parity codes that match in-person neurology consult reimbursement rates. Massachusetts General Hospital and Stanford's epilepsy centers anchor clinical validation studies for wearable seizure detection systems.
Germany
University hospitals in Bavaria and Baden-Württemberg deploy cloud-native platforms for multi-site epilepsy monitoring across rural catchment areas. The EU Medical Device Regulation (MDR) harmonizes clearance requirements for AI-enabled seizure classifiers across member states. The Munich and Heidelberg medical technology clusters host development teams for photonic integrated circuit substrates in ambulatory monitors.
Japan
Metropolitan epilepsy centers in Tokyo and Osaka adopt hybrid edge-cloud architectures to address intermittent cellular connectivity in mountainous regions. The Ministry of Economy, Trade and Industry (METI) funds digital health pilot programs that include remote neurological monitoring. The Nagoya medical device manufacturing corridor supplies precision sensors for wrist-worn biomarker arrays.
United Kingdom
NHS Trusts in Greater London and Manchester expand asynchronous EEG review services to address neurologist supply shortages in northern England. The Medicines and Healthcare products Regulatory Agency (MHRA) operates an accelerated access pathway for breakthrough device designations. The Cambridge life sciences cluster houses signal processing specialists developing on-device machine learning inference engines.
Australia
Pediatric epilepsy programs in Sydney and Melbourne deploy school-based monitoring configurations to satisfy individualized education plan requirements. The Therapeutic Goods Administration (TGA) aligns software-as-a-medical-device guidance with FDA precedent for seizure prediction algorithms. The Melbourne biomedical precinct hosts clinical trials for responsive neurostimulation data integration with remote physician dashboards.
Tele-Epilepsy Market Key Industry Players
Strategic partnerships dominate the current landscape as device manufacturers align with cloud platform vendors to deliver integrated hardware-software stacks. The vendor base organizes around three tiers: established neuromodulation suppliers with deep hospital network relationships, wearable technology specialists with direct-to-consumer channels, and telehealth infrastructure providers with enterprise EMR connectivity. Two archetypes define competitive positioning: hardware-plus-subscription bundlers capturing recurring revenue streams, and software-only platforms competing on algorithm sophistication. Capacity expansion in silicon photonics fabrication and geographic extension into state Medicaid programs represent the dominant competitive moves.
Among established neuromodulation suppliers, Medtronic plc anchors the hardware-integrated tier through its responsive neurostimulation data streams. Empatica Inc. and NeuroPace Inc. occupy distinct positions within the wearable and implantable monitoring segments respectively, each representing alternative pathways for real-world seizure detection outside clinical settings. These three companies exemplify the divergence between ambient biomarker sensing and intracranial electrographic monitoring as competing technical architectures.
| Leading Market Players |
|---|
| Medtronic plc |
| Empatica Inc. |
| NeuroPace Inc. |
| Ceribell, Inc. |
| Eagle Telemedicine |
| Chiron Health |
| Seer Medical |
| LivaNova PLC |
| Invitae Corp. |
| Others |
Cost & Logistics Intelligence
Silicon photonics substrate migration simultaneously compresses unit manufacturing costs and concentrates wafer fabrication capacity among specialized foundries in Taiwan, Germany, and the United States. This dual effect reshapes procurement economics for wearable seizure monitor producers while amplifying pricing leverage for photonic integrated circuit suppliers serving the tele-epilepsy device ecosystem.
Pricing Analysis
Volume-versus-margin splits separate hardware-plus-subscription bundlers from software-only platform vendors. Three-tier pricing structure across premium, standard, and economy levels differentiates by FDA clearance tier and algorithm latency performance. Cost compression in standard-tier wearable devices intensifies as Chinese sensor manufacturers enter the electrodermal activity monitoring segment. Pediatric epilepsy programs and rural health systems exhibit highest price sensitivity; academic medical centers with research funding tolerate premium positioning for investigational algorithm access.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based photonic foundries supplying sub-milliwatt EEG processing chips for ambulatory monitors. Raw material dependencies include indium phosphide wafers, precision accelerometers from Japan, and medical-grade lithium polymer cells from South Korea. Tariff exposure on Chinese-manufactured electrodermal sensors generates supply chain risk for cost-optimized device tiers. Distribution runs through hospital procurement committees and GPO contracts for institutional buyers, with direct-to-consumer channels emerging for unregulated wellness-adjacent seizure logging applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-based EEG analytics platforms are displacing fragmented paper-based seizure logging systems across neurology practices. This technology-transition phase rewards vendors who architect real-time data pipelines ahead of episodic care models.
For Market Incumbents: Anchor defensive positioning through backward integration into silicon photonics fabrication capacity and captive cloud infrastructure deployment. Consolidate hospital network relationships by integrating responsive neurostimulation data streams with remote physician dashboards. Counter emerging wearable specialists by locking in multi-year enterprise EMR connectivity contracts.
For New Entrants and Emerging Players: On-device machine learning inference for electrodermal activity pattern recognition offers technology-first wedge into school-based pediatric monitoring white space. Target Texas, Florida, and Ohio district nursing programs seeking seizure action plan compliance partnerships. Pursue FDA breakthrough device designation pathway to compress commercialization timelines against established algorithm portfolios.
For Investors and Strategic Acquirers: Re-rating potential sits with hybrid edge-cloud architecture developers given CMS telehealth parity mandate expansion across state Medicaid programs. Five-to-ten year viability favors platforms with HIPAA-compliant infrastructure and multi-site health system deployments. Monitor FDA software-as-a-medical-device guidance evolution as inflection indicator for AI seizure classifier valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerates commercialization timelines for AI-enabled seizure prediction algorithms from thirty-six to eighteen months. |
| Silicon Photonics Foundry Partnership | Secures sub-milliwatt power consumption advantage for ambulatory EEG monitors against legacy CMOS competitors. |
| Hospital System EMR Integration | Locks in six-to-nine month IT procurement cycles through Epic and Cerner HL7 FHIR interface certification. |
| State Medicaid Reimbursement Strategy | Captures asynchronous EEG review revenue streams in Illinois, Pennsylvania, and Georgia safety-net expansions. |
| Pediatric Home Monitoring Partnership | Addresses individualized education plan compliance demand in Philadelphia and Houston school-based deployments. |
Research Approach
FDA 510(k) clearance databases, CMS Medicare reimbursement code filings, and hospital procurement contract records formed the secondary backbone for market sizing validation. Primary interviews with epileptologists, biomedical engineers, health system IT directors, and GPO contracts managers supplemented secondary triangulation. Bottom-up installed base estimates for wearable seizure monitors and remote monitoring systems were cross-checked against top-down neurology practice telehealth adoption surveys.
Historical trendline analysis across wearable device shipment volumes, cloud platform subscription renewals, and telehealth reimbursement claim volumes established baseline growth trajectories. The analytical framework modeled product type, delivery mode, application focus, and end-user archetype segmentation throughout the forecast period. CAGRs were derived from algorithm penetration curves in academic medical centers and community hospital expansion patterns. Forecast inputs incorporated FDA software-as-a-medical-device guidance evolution and state Medicaid telehealth code adoption timelines.
Several conditions sit outside the modeled scope, including responsive neurostimulation implant surgical volumes and pharmaceutical medication adherence intervention revenues. Forecasts reflect assumptions regarding HIPAA Security Rule enforcement consistency and neurologist supply concentration in coastal academic centers. Deviation in FDA AI-enabled diagnostic classification policy would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telemedicine
Telemedicine Equipment Market
Telemedicine
Asia-Pacific Telemedicine Market
Telemedicine
Telemedicine Diagnostic Services Market
Telemedicine
Telemedicine Cart Market
Telemedicine
North America and Europe Ehealth Market
Telemedicine
In-Flight Telemedicine System Market
Telemedicine
Global Virtual Care Market
Telemedicine
US Telemedicine Market
Telemedicine
Video Telemedicine Market
Telemedicine
US Virtual Care Market
Telemedicine
Telemedicine Workstations Market
Telemedicine
US Virtual Visits Market
Telemedicine
Telemedicine EMR Software Market
Telemedicine
Telemedicine Service Market
Telemedicine
India Telemedicine Market
Telemedicine
Europe Telehealth Service Market