
 Telemedicine EMR Software Market | 2026-2036
Telemedicine EMR Software Market Size, Share, and Industry Trends Forecast 2026-2036
Telemedicine EMR Software Market Insights
Direct-to-clinic SaaS distribution is rewriting how telemedicine EMR vendors reach end users, bypassing traditional health IT procurement cycles. Epic Systems Corporation anchors hospital system deployments through its deeply integrated EHR-to-telehealth workflow. Oracle Health competes by leveraging its Cerner acquisition to extend cloud infrastructure across federal and large integrated delivery networks. Teladoc Health specializes in white-label platform delivery, enabling payers and employers to embed EMR-connected virtual care without building proprietary stacks.
Telemedicine EMR software constitutes a digital health information system that synchronizes electronic medical records with real-time virtual consultation interfaces, typically requiring HL7 FHIR interoperability, end-to-end encryption, and sub-200-millisecond latency for synchronous video encounters. Its primary purpose is to unify clinical documentation, prescribing, and billing within a single patient encounter regardless of physical care setting. Cloud-based deployment leads volume due to lower capital barriers and automatic regulatory patching, while artificial intelligence integration represents the fastest-expanding technology layer as ambient clinical documentation and predictive triage modules mature. Hybrid architectures retain relevance among mid-size clinic groups balancing data sovereignty with remote accessibility.
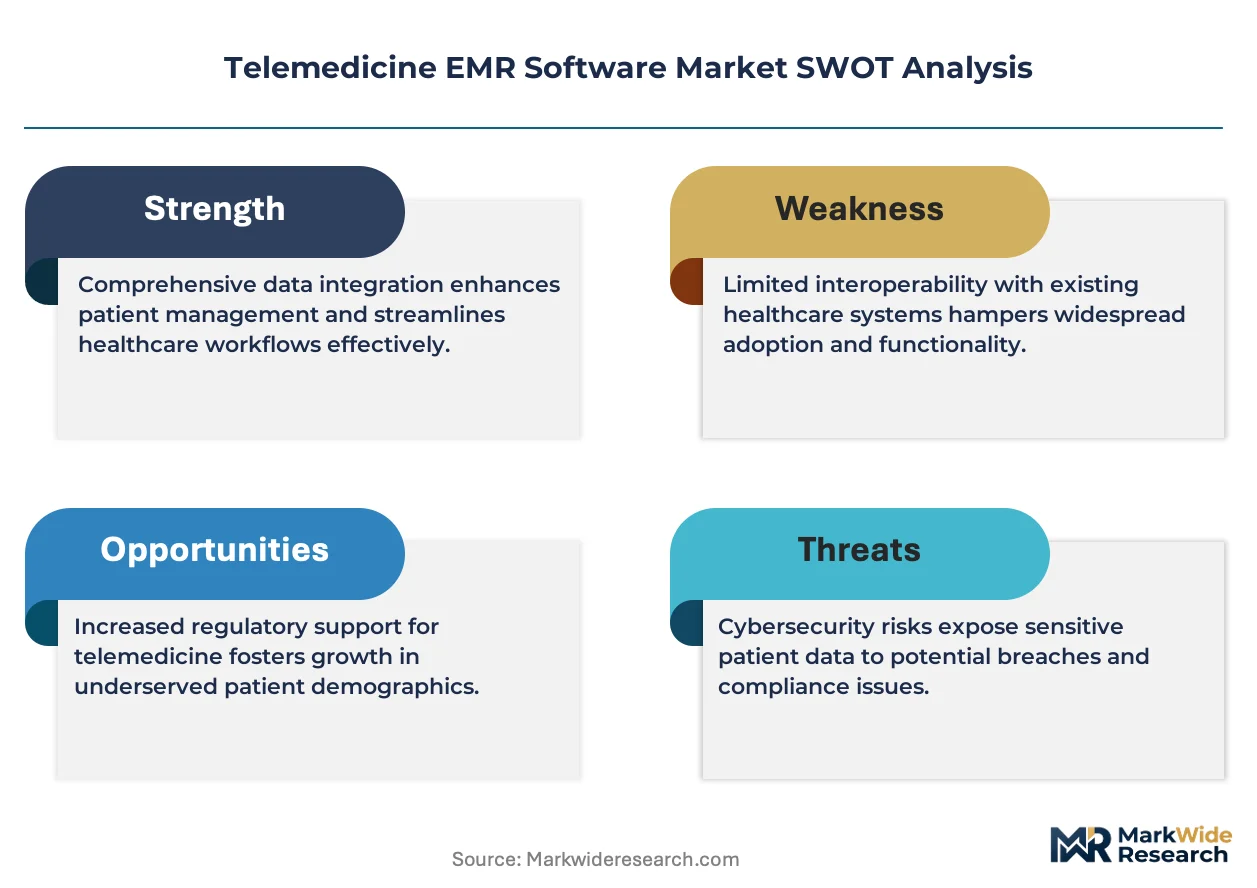
FDA Software as a Medical Device oversight, HIPAA security rule enforcement, and ONC Cures Act information blocking provisions collectively shape product roadmaps, certification requirements, and data exchange obligations for vendors operating in the United States. The FDA's evolving stance on AI-enabled diagnostic support within EMR workflows is forcing developers to maintain rigorous algorithmic transparency and clinical validation documentation. Stakeholders must monitor how interoperability mandates and emerging state-level telehealth prescribing regulations will reshape competitive differentiation between integrated suite providers and best-of-breed point solutions.
Market Dynamics
The FDA's Software as a Medical Device framework is compressing validation timelines for clinical decision support modules embedded within telemedicine EMR platforms, forcing vendors to restructure quality assurance workflows around algorithmic transparency documentation.
Growth Catalysts
- Interoperability mandates:The ONC Cures Act information blocking provisions in the United States compel vendors to deploy HL7 FHIR APIs, accelerating data liquidity between disparate health systems and virtual care networks.
- India's digitization push:The Ayushman Bharat Digital Mission and eSanjeevani platform create institutional demand for cloud-native EMR architectures capable of supporting 500,000+ daily remote consultations.
- Ambient clinical documentation:Natural language processing engines integrated into telemedicine workflows automate encounter note generation, reducing physician administrative burden by capturing synchronous video dialogue in structured formats.
Market Restraints
- Input cost volatility:Specialized healthcare cloud infrastructure pricing from hyperscale providers fluctuates with energy markets, squeezing margins for SaaS vendors serving mid-size clinic groups.
- Supply concentration risk:Video codec licensing and encryption certificate authorities concentrate among a handful of US and European technology holders, creating dependency vulnerabilities.
- Technical limitation:Sub-200-millisecond latency requirements for synchronous telehealth encounters exclude rural broadband infrastructure in underserved US territories and developing economies.
Strategic Opportunities
- Underpenetrated geographies:Brazil's SUS digital transformation and ANVISA telehealth guidelines open pathways for EMR-integrated virtual care platforms in Latin America's largest public health system.
- Regulatory tailwind:The EU AI Act's risk-based classification for medical device software creates compliance clarity that favors established vendors capable of clinical validation documentation.
- Technology convergence:Edge computing architectures paired with 5G network slicing enable real-time diagnostic imaging transmission from ambulatory settings, expanding reimbursable telemedicine service categories.
Industry Challenges
- Specialized talent scarcity:Health informaticists capable of bridging clinical workflow design with FHIR implementation and AI model governance command premium compensation, constraining vendor scaling velocity.
- Certification timeline compression:FDA 510(k) clearance pathways for AI-enabled diagnostic support within EMR workflows now require prospective clinical validation studies, extending time-to-market by 12-18 months.
- Integration complexity:Legacy on-premise EHR systems at hospital systems demand custom middleware development for telemedicine module connectivity, fragmenting implementation resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telemedicine EMR Software Market |
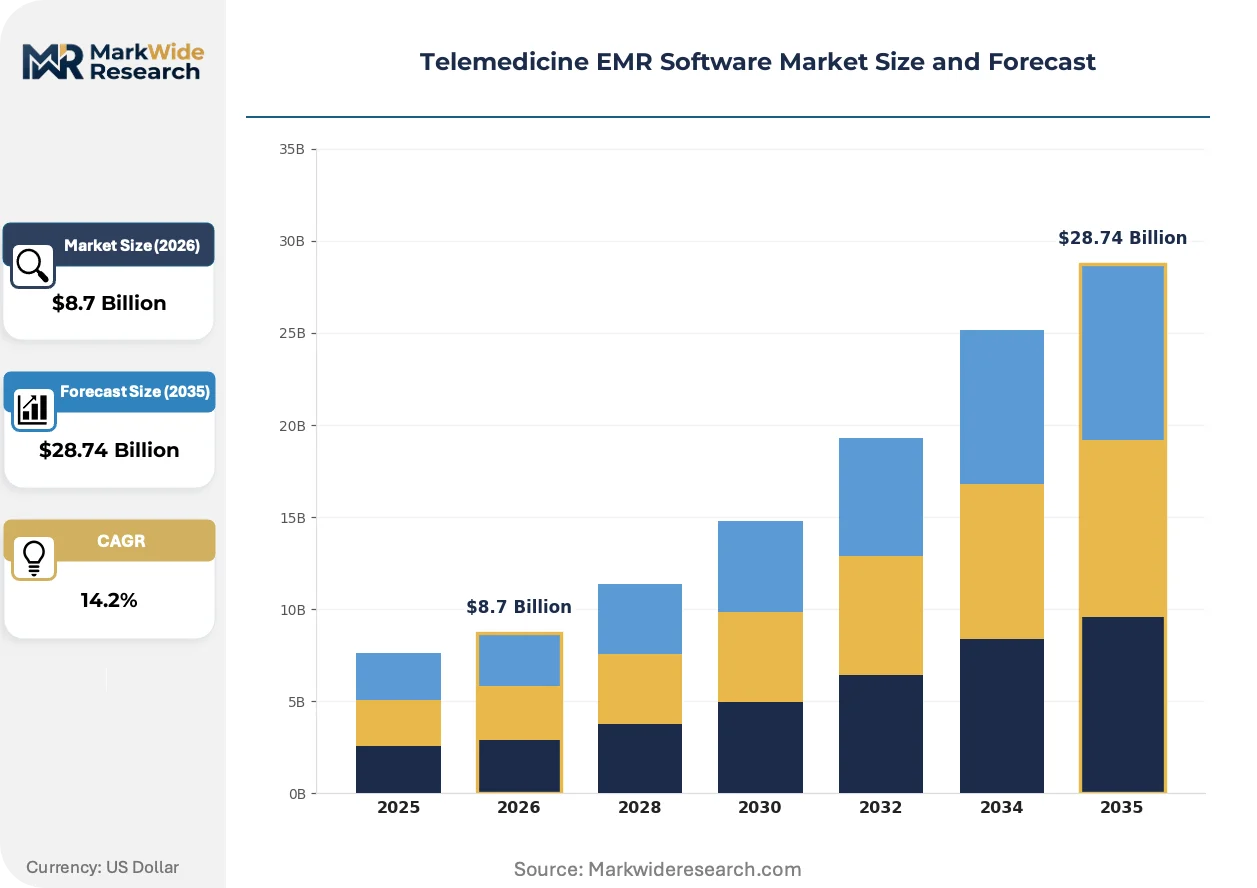
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-based, On-premise, Hybrid, Mobile Applications End User: Hospitals, Clinics, Telehealth Providers, Patient Care Organizations Technology: Artificial Intelligence, Blockchain, Data Analytics, Secure Messaging Deployment Model: Public Cloud, Private Cloud, Dedicated Servers, SaaS |
| Companies Covered | Teladoc Health, Amwell, Epic Systems Corporation, Oracle Health, Doxy.me, Kareo, DrCare247, Updox, PrognoCIS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telemedicine EMR Software Market Trends and Innovations
Artificial intelligence layers are penetrating telemedicine EMR architectures faster than any previous technology wave, restructuring how clinical documentation, triage, and decision support converge within virtual care encounters.
Generative AI models trained on structured and unstructured clinical data are digitizing encounter documentation by converting real-time provider-patient dialogue into codified diagnosis and procedure records. Rural health networks in the United States are piloting these ambient scribing tools to address physician burnout and documentation backlogs. This capability is digitizing the traditional medical transcription vendor market while compressing reimbursement cycle timelines.
The FDA's evolving enforcement discretion for clinical decision support software is reshaping how algorithmic risk stratification tools receive market authorization. Developers must now maintain prospective performance monitoring systems and algorithmic change control protocols. Multi-hospital systems are responding by consolidating vendor relationships around platforms with established FDA quality system documentation.
Direct-to-clinic SaaS distribution is displacing traditional health IT procurement cycles that previously routed through group purchasing organizations and extended sales cycles. Payers and self-insured employers now procure white-label telemedicine EMR platforms through annual subscription contracts. This pattern is most visible in employer-sponsored virtual primary care programs across the United States and United Kingdom.
Telemedicine EMR Software Market Segmentation
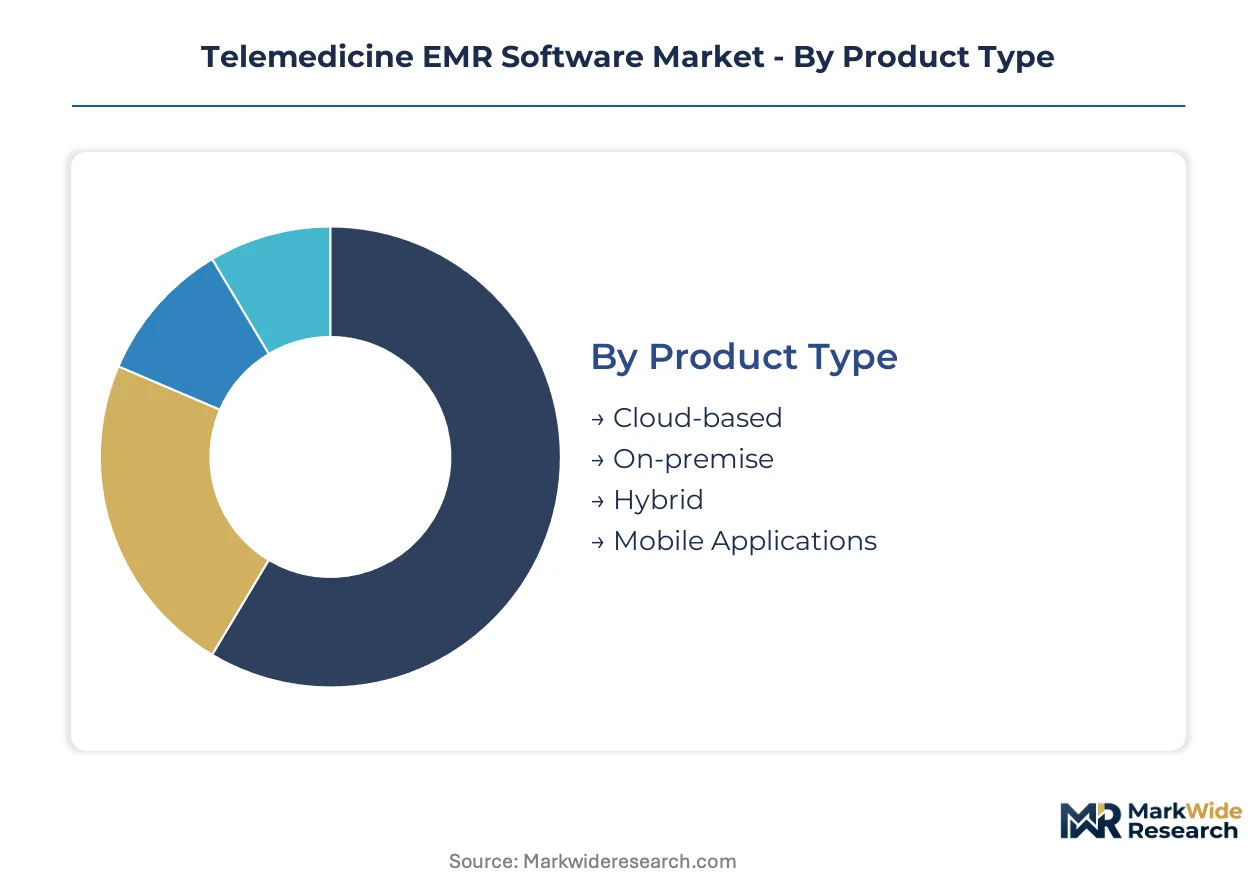
Segmentation in telemedicine EMR software reveals how procurement cycles, technical requirements, and regulatory exposure vary across deployment modes and user types. Vendors must align product roadmaps with distinct velocity profiles: cloud-native solutions refresh quarterly while on-premise installations cycle across multi-year capital planning horizons.
Product Type:
Cloud-based platforms turn over fastest with continuous deployment pipelines, while on-premise installations exhibit the longest replacement cycles tied to hospital capital expenditure calendars.
- Cloud-based:Multi-tenant architectures with automatic regulatory patching eliminate version fragmentation across health system networks. India's eSanjeevani platform and US rural health networks concentrate procurement here, driven by zero-capital onboarding and instant scalability for surge consultation volumes.
- On-premise:Single-tenant installations behind hospital firewall perimeters satisfy data sovereignty requirements for sensitive patient populations. Large integrated delivery networks in Germany and Japan maintain these deployments due to strict local data residency statutes and legacy infrastructure amortization schedules.
- Hybrid:Split architectures keep protected health information on-site while routing video traffic through cloud edge nodes. Mid-size clinic groups in Brazil and Mexico favor this model for balancing HIPAA-equivalent compliance with remote accessibility.
- Mobile Applications:Native iOS and Android clients with offline synchronization capabilities extend EMR access to home health and emergency response workflows.
Cloud-based deployments anchor the volume base while mobile applications gain share at the steepest rate.
End User:
Cost tier stratification separates enterprise hospital systems from budget-constrained independent practices, reshaping how vendors package feature modules and support services.
- Hospitals:Enterprise-grade implementations demand deep EHR integration, 99.99% uptime SLAs, and dedicated implementation teams. Academic medical centers in the United States and NHS Trusts in the United Kingdom drive procurement here, compelled by ONC Cures Act interoperability mandates and NHS Long Term Plan digitization targets.
- Clinics:Smaller-footprint deployments prioritize rapid onboarding and pre-configured specialty templates. Federally qualified health centers across US states and primary care networks in Spain concentrate demand, seeking reimbursement optimization for virtual visit billing codes.
- Telehealth Providers:Pure-play virtual care platforms require white-label customization and payer-specific workflow configurations.
- Patient Care Organizations:Home health agencies and long-term care facilities need asynchronous documentation tools and caregiver-facing mobile interfaces.
Hospitals dominate current revenue concentration while telehealth providers expand most quickly as direct-to-employer virtual care contracts proliferate.
Technology:
Application maturity varies sharply: ambient documentation AI deploys in weeks while blockchain credentialing networks require multi-stakeholder governance establishment.
- Artificial Intelligence:Natural language processing engines convert synchronous video dialogue into structured encounter notes and diagnostic suggestions. US health systems and United Kingdom GP networks pilot these tools most aggressively, responding to physician burnout metrics and NHS workforce retention targets.
- Blockchain:Distributed ledger architectures for provider credentialing and prescription integrity create immutable audit trails. Dubai's MOHAP and Estonia's e-Health Authority drive experimental deployments, attracted by cross-border patient mobility use cases.
- Data Analytics:Population health dashboards and predictive triage algorithms stratify virtual queue priority.
- Secure Messaging:End-to-end encrypted asynchronous channels extend care team coordination beyond video encounters.
Artificial Intelligence anchors the volume base while blockchain gains share at the steepest rate despite longer implementation timelines.
Deployment Model:
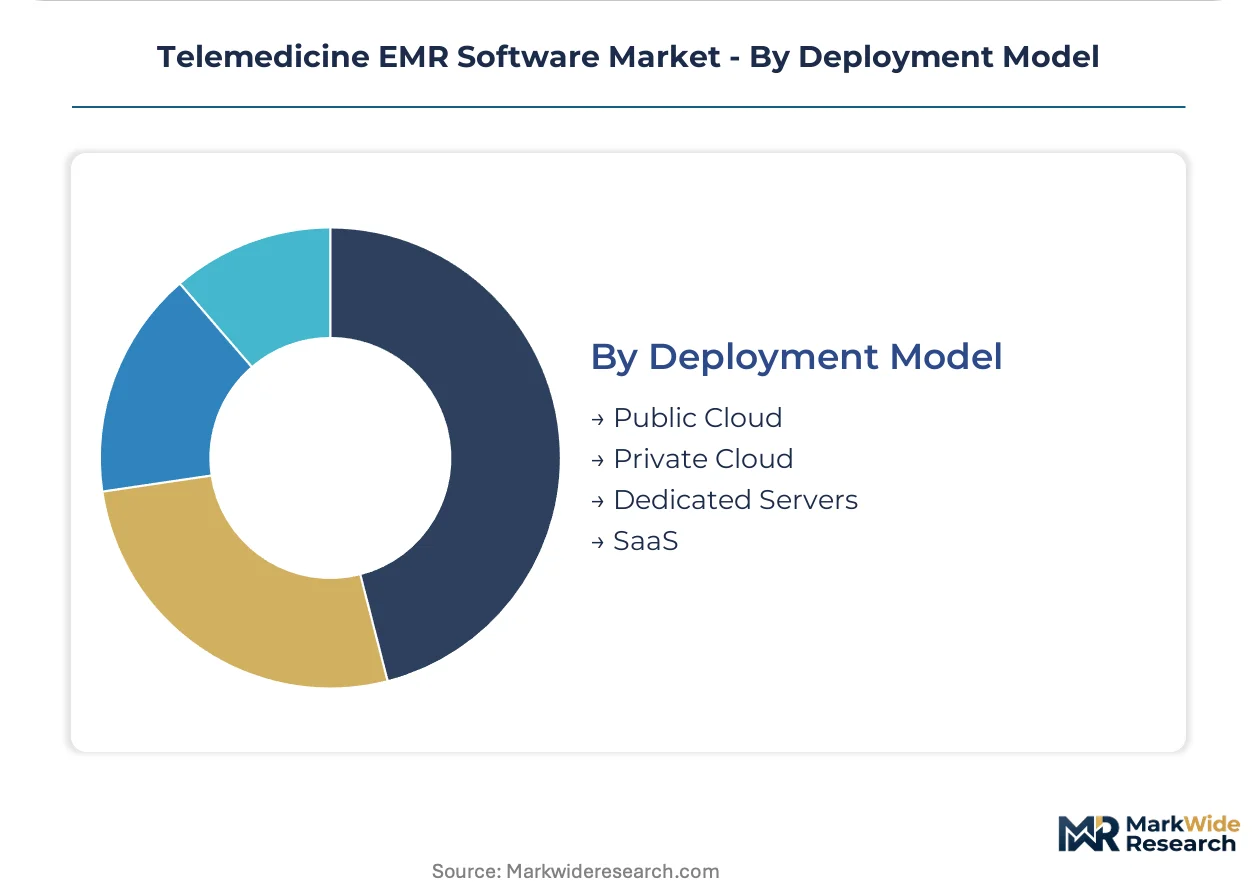
Supply concentration among hyperscale infrastructure providers concentrates margin pressure differently across public versus private cloud configurations.
- Public Cloud:Shared infrastructure from AWS, Azure, and Google Cloud delivers elastic compute for variable consultation volumes. India's Ayushman Bharat Digital Mission and US community health centers standardize here, prioritizing cost efficiency over physical infrastructure control.
- Private Cloud:Single-tenant virtualized environments within hospital-owned data centers satisfy stringent security frameworks. Defense Health Agency facilities and Swiss university hospitals mandate these deployments under FedRAMP and Swissmedic data protection requirements.
- Dedicated Servers:Bare-metal colocation arrangements for maximum performance isolation in high-throughput diagnostic imaging workflows.
- SaaS:Fully managed software subscriptions with vendor-operated infrastructure and automatic feature updates.
Public cloud anchors the volume base while SaaS gains share at the steepest rate as direct-to-clinic procurement displaces traditional health IT sales cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where HIPAA-compliant cloud infrastructure commands subscription premiums, while India's government-subsidized eSanjeevani platform compresses margins through volume-based procurement at national scale.
United States
Federally qualified health centers and rural health networks drive procurement of integrated telemedicine EMR platforms. The ONC Cures Act information blocking provisions and FDA Software as a Medical Device framework reshape vendor certification requirements. The Mayo Clinic and Cleveland Clinic anchor enterprise deployments in the Upper Midwest, while Texas Medical Center clusters pilot ambient clinical documentation AI.
India
The Ayushman Bharat Digital Mission and eSanjeevani platform institutionalize demand for cloud-native architectures supporting 500,000+ daily remote consultations. CDSCO oversight and the Ministry of Health's interoperability standards guide product roadmaps. Bangalore's HealthTech corridor and Hyderabad's pharmaceutical IT clusters concentrate startup development for FHIR-compliant patient record systems.
Germany
University hospitals and large integrated delivery networks maintain on-premise deployments under strict data residency statutes. The EU AI Act's risk-based classification and BfArM medical device guidance create compliance clarity for algorithmic diagnostic tools. Berlin-Brandenburg and Munich anchor health IT vendor development, while Baden-Württemberg's automotive-to-healthcare technology transfer accelerates edge computing pilot programs.
Brazil
SUS digital transformation and ANVISA telehealth guidelines open pathways for EMR-integrated virtual care in Latin America's largest public health system. The Ministry of Health's national telemedicine program subsidizes platform adoption in underserved municipalities. São Paulo's hospital networks and Rio de Janeiro's research institutions pilot hybrid cloud architectures balancing data sovereignty with remote accessibility.
United Kingdom
NHS Trusts drive procurement under Long Term Plan digitization targets and NHSX interoperability standards. The MHRA's software medical device guidance and NICE technology appraisals shape clinical validation requirements. London's digital health cluster and Manchester's health innovation district concentrate vendor development for GP network virtual consultation workflows.
Telemedicine EMR Software Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying discrete modules for video infrastructure, encryption, or FHIR middleware. The vendor base organizes around three strategic archetypes: EHR incumbents extending into virtual care workflows, pure-play telehealth platforms white-labeling to payers, and cloud-native challengers targeting mid-size clinic groups. Dominant competitive moves include strategic partnerships with hyperscale infrastructure providers and portfolio diversification into ambient clinical documentation AI.
Within the EHR-integrated tier, Epic Systems Corporation and Oracle Health represent established platform architectures, while Teladoc Health exemplifies the white-label virtual care model. Epic Systems Corporation occupies a position anchoring hospital system deployments through deeply integrated workflow design. Oracle Health sits within the cloud infrastructure extension archetype following its Cerner acquisition. Teladoc Health exemplifies payer-facing platform delivery, enabling employers to embed EMR-connected virtual care without proprietary development.
| Leading Market Players |
|---|
| Teladoc Health |
| Amwell |
| Epic Systems Corporation |
| Oracle Health |
| Doxy.me |
| Kareo |
| DrCare247 |
| Updox |
| PrognoCIS |
| Others |
Pricing and Supply Chain Analysis
Hyderabad's pharmaceutical IT corridor anchors cloud infrastructure capacity for Indian telemedicine EMR deployments, compressing subscription pricing for SaaS vendors serving mid-size clinic groups while US-based hyperscale providers maintain premium positioning for HIPAA-compliant enterprise implementations.
Pricing Analysis
The customization-premium spread separates white-label platform configurations from standard SaaS tiers. Subscription-based pricing stratifies across premium, standard, and economy tiers, with differentiation anchored in FDA 510(k) certification status and HL7 FHIR integration depth. Pricing pressure stems from India's government-subsidized eSanjeevani procurement, which forces margin compression through volume-based national contracts. Federally qualified health centers in the United States exhibit highest price sensitivity, while academic medical centers prioritize uptime SLAs over cost.
Supply Chain Analysis
Contract manufacturing concentration rests with AWS, Azure, and Google Cloud for hyperscale infrastructure, with Tata Communications and NTT Data holding regional edge capacity. Supply draws from the United States, India, and Germany for encryption certificate authorities, video codec licensing, and FHIR middleware development. Single-source vulnerability concentrates in US-controlled encryption standards and European certificate authorities. Distribution runs through direct-to-clinic SaaS channels, displacing traditional health IT procurement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telemedicine EMR software sits in early-cycle expansion as ambient clinical documentation AI penetrates virtual care workflows, with India's nationwide digitization and US rural health network subsidies creating durable adoption tailwinds.
For Market Incumbents: Pre-empt margin erosion from pure-play AI documentation vendors by embedding ambient scribing modules directly into core EMR workflows. Acquire FHIR middleware specialists to lock in interoperability positioning ahead of ONC Cures Act enforcement expansion. Defensive consolidation around algorithmic transparency documentation will satisfy FDA Software as a Medical Device scrutiny. For New Entrants and Emerging Players: Brazil's SUS digital transformation represents the most penetrable geographic white-space, with ANVISA telehealth guidelines creating regulatory clarity for cloud-native platform entry. Target mid-size clinic groups in São Paulo and Rio de Janeiro with hybrid deployment models balancing data sovereignty with remote accessibility. Pursue payer white-label partnerships to bypass capital-intensive direct sales cycles. For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because EHR-to-telehealth workflow integration creates sticky enterprise relationships with 99.99% uptime requirements. Acquisition targets should cluster around ambient AI documentation engines with FDA quality system documentation already established. Monitor CDSCO and FDA enforcement discretion shifts as the primary inflection signal for algorithmic diagnostic support valuations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Accelerates market authorization for AI-enabled diagnostic support modules within EMR workflows. |
| HL7 FHIR API Integration | Satisfies ONC Cures Act mandates while enabling data liquidity between disparate health systems. |
| Hospital System Partnership | Locks in enterprise revenue through deeply integrated EHR-to-telehealth workflow design. |
| Ambient AI Documentation Acquisition | Addresses physician burnout metrics while compressing reimbursement cycle timelines. |
| Geographic Expansion into Brazil | Captures SUS digital transformation subsidies in Latin America's largest public health system. |
Research Methodology
A spread of perspectives from hospital CIOs, telehealth platform engineers, GPO contracts managers, and health informaticists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement data, hospital procurement databases, and hyperscaler capex disclosures. Bottom-up segmentation modeling triangulated against top-down market sizing across deployment modes and end-user archetypes.
Demand-supply-balance framing anchored the forecast framework throughout the projection horizon. Segmentation dimensions modeled include deployment architecture, organization size tier, integration complexity level, and regional regulatory cluster. CAGRs derived from historical penetration curves adjusted for policy inflection points. Forecast inputs incorporated India's eSanjeevani consultation volume trajectories and US rural health network subsidy allocation patterns.
Practitioners should monitor FDA enforcement discretion shifts, CDSCO telehealth guideline revisions, and EU AI Act implementation timelines for early signals requiring forecast adjustment. Quarterly review of hospital system procurement pipeline data and ambient AI documentation pilot outcomes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telemedicine
AI in Telemedicine Market
Telemedicine
Healthcare IoT Telemedicine Market
Telemedicine
Europe Telehealth Service Market
Telemedicine
Oceania Telemedicine Market
Telemedicine
Global Healthcare Virtual Assistants Market
Telemedicine
Telemedicine Technologies Market
Telemedicine
US Telehealth Market
Telemedicine
In-Flight Telemedicine System Market
Telemedicine
Tele-ICU Services Market
Telemedicine
Pediatric Telemedicine Market
Telemedicine
Global Tele Intensive Care Unit Market
Telemedicine
Online Doctor Consultation Market
Telemedicine
United States Telehealth Postpartum Services Market
Telemedicine
Tele-Care Market
Telemedicine
Telemedicine Equipment Market
Telemedicine
Global Virtual Care Market