
 Alzheimer's Therapeutics Market | 2026-2036
Alzheimer's Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Alzheimer's Therapeutics Market Intelligence
Buyer concentration among Alzheimer's therapeutics purchasers is broadening as hospital systems consolidate specialty pharmacy operations while home care providers fragment into regional networks. Biogen Inc. leverages its neurology infrastructure to sustain infusion center partnerships across major metropolitan markets. Eli Lilly and Company anchors its position through manufacturing scale for antibody-based therapies. Eisai Co., Ltd. competes via joint development structures that extend its reach into North American and Asian markets simultaneously.
Alzheimer's therapeutics comprise pharmacological agents designed to modify disease pathology or manage cognitive and behavioral symptoms, with monoclonal antibodies requiring cold-chain distribution at two to eight degrees Celsius and parenteral administration in certified infusion centers. These treatments serve patients across mild cognitive impairment through severe dementia stages, with clinical endpoints measured by cognitive assessment scales and biomarker clearance. Cholinesterase inhibitors occupy the mature oral therapy segment with generic erosion compressing margins, while monoclonal antibodies represent the fastest-expanding value pool despite restricted prescriber networks and risk evaluation strategies. The injectable administration route commands premium pricing tied to site-of-care requirements, whereas oral formulations sustain volume leadership in symptomatic management.
The FDA governs accelerated approval through surrogate biomarker endpoints, while the EMA applies conditional marketing authorization frameworks that demand post-approval confirmatory trials. The Centers for Medicare and Medicaid Services shapes demand through national coverage determinations that restrict reimbursement to registry-enrolled patients with confirmed amyloid pathology. Stakeholders must monitor evolving FDA confirmatory trial requirements and CMS coverage restrictions to align pipeline investments with accessible patient populations.
Market Dynamics
FDA's accelerated approval pathway for amyloid-targeting therapies has compressed development timelines while fragmenting prescriber eligibility through restricted distribution networks. Medicare coverage determinations now gate patient access to disease-modifying treatments, forcing manufacturers to integrate registry enrollment into commercial infrastructure.
Growth Catalysts
- Biomarker-Guided Patient Selection:PET imaging and cerebrospinal fluid testing protocols enable precise amyloid confirmation, expanding treatable populations within mild cognitive impairment stages. Neurology clinics in the United States are embedding these diagnostics into standard workups.
- CMS National Coverage Determinations:Medicare reimbursement for anti-amyloid monoclonal antibodies creates predictable payment pathways for infusion centers. This policy framework anchors demand concentration among registry-enrolled patients with confirmed pathology.
- Specialized Infusion Infrastructure:Hospital systems are certifying neurological infusion suites with MRI monitoring capabilities and specialized nursing staff. These capital investments reduce site-of-care bottlenecks for parenteral antibody administration.
Market Restraints
- Confirmatory Trial Risk:FDA's requirement for post-approval verification of clinical benefit creates regulatory overhang for accelerated approvals. Withdrawal mechanisms threaten revenue stability if surrogate endpoints fail to translate into cognitive outcomes.
- Cold-Chain Distribution Costs:Monoclonal antibodies require two-to-eight-degree Celsius handling through certified logistics networks. Temperature excursion liability concentrates supply risk among limited specialty pharmacy distributors.
- Generic Erosion of Symptomatic Agents:Donepezil and memantine face patent cliff compression in oral cholinesterase markets. Price erosion in mature therapeutic classes constrains portfolio margin contribution.
Strategic Opportunities
- Early-Stage Patient Identification:Primary care networks in Germany and France present underpenetrated screening opportunities for mild cognitive impairment. Memory clinic partnerships with general practitioners expand diagnostic reach before specialist referral.
- Combination Therapy Protocols:Anti-amyloid antibodies paired with tau-targeting agents or neuroinflammation modulators represent emerging therapeutic architectures. Clinical trial designs are exploring sequential or concurrent mechanism stacking.
- Digital Biomarker Integration:Smartphone-based cognitive assessments and passive monitoring through wearable sensors enable decentralized trial endpoints. These technologies compress patient burden while expanding geographic recruitment.
Industry Challenges
- Specialized Neurology Workforce Scarcity:Certified prescribers for risk evaluation and mitigation strategy programs remain concentrated in academic medical centers. Community neurology practices lack training infrastructure for complex antibody monitoring protocols.
- ARIA Detection and Management:Amyloid-related imaging abnormalities require radiological expertise and clinical decision frameworks that vary across imaging centers. Standardized severity grading and treatment interruption protocols remain institution-specific.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alzheimer's Therapeutics Market |
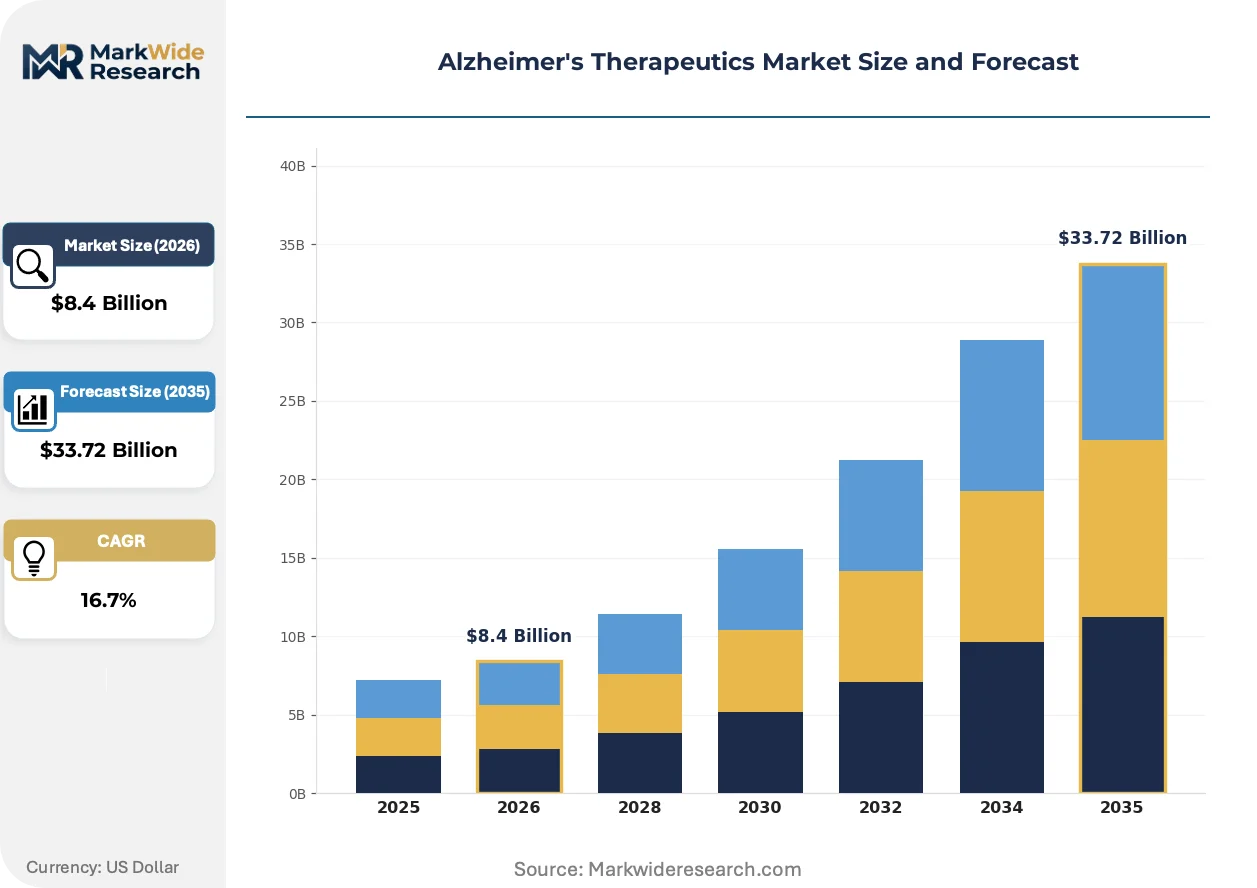
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $33.72 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cholinesterase Inhibitors, Antipsychotics, NMDA Receptor Antagonists, Monoclonal Antibodies Administration Route: Oral, Injectable, Transdermal, Inhalation Stage of Development: Preclinical, Phase I, Phase II, Phase III End User: Hospitals, Nursing Homes, Home Care, Outpatient Clinics |
| Companies Covered | Biogen Inc., Eisai Co., Ltd., Eli Lilly and Company, AbbVie Inc., Novartis AG, Johnson & Johnson Services Inc., Pfizer Inc., Merck & Co., Inc., H. Lundbeck A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alzheimer's Therapeutics Market Strategic Shifts & Innovations
Digital health infrastructure is reshaping how Alzheimer's therapies move from trial enrollment through long-term patient monitoring, compressing traditional site-based research models. Remote assessment tools and decentralized data capture are enabling geographic expansion of treatable populations.
Subcutaneous administration technologies are decentralizing site-of-care requirements for monoclonal antibody delivery. Home health nursing networks and patient self-administration training programs are piloting alternatives to certified infusion centers. This shift reduces facility overhead burdens while expanding rural and suburban patient access where neurological infrastructure remains sparse.
EMA's conditional marketing authorization framework is tightening evidentiary standards for surrogate endpoint approvals, demanding earlier initiation of confirmatory trials than FDA pathways. European manufacturers face compressed timelines between accelerated launch and placebo-controlled completion studies. Germany's Federal Joint Committee (G-BA) is responding with provisional reimbursement tied to demonstrated outcome milestones.
Hospital systems are consolidating specialty pharmacy operations under centralized oncology and neurology service lines, displacing fragmented outpatient infusion models. Academic medical centers in the United States are acquiring community neurology practices to capture patient flow earlier in disease progression. This concentration shifts negotiating leverage toward integrated delivery networks and away from standalone infusion operators.
Alzheimer's Therapeutics Market Segmentation
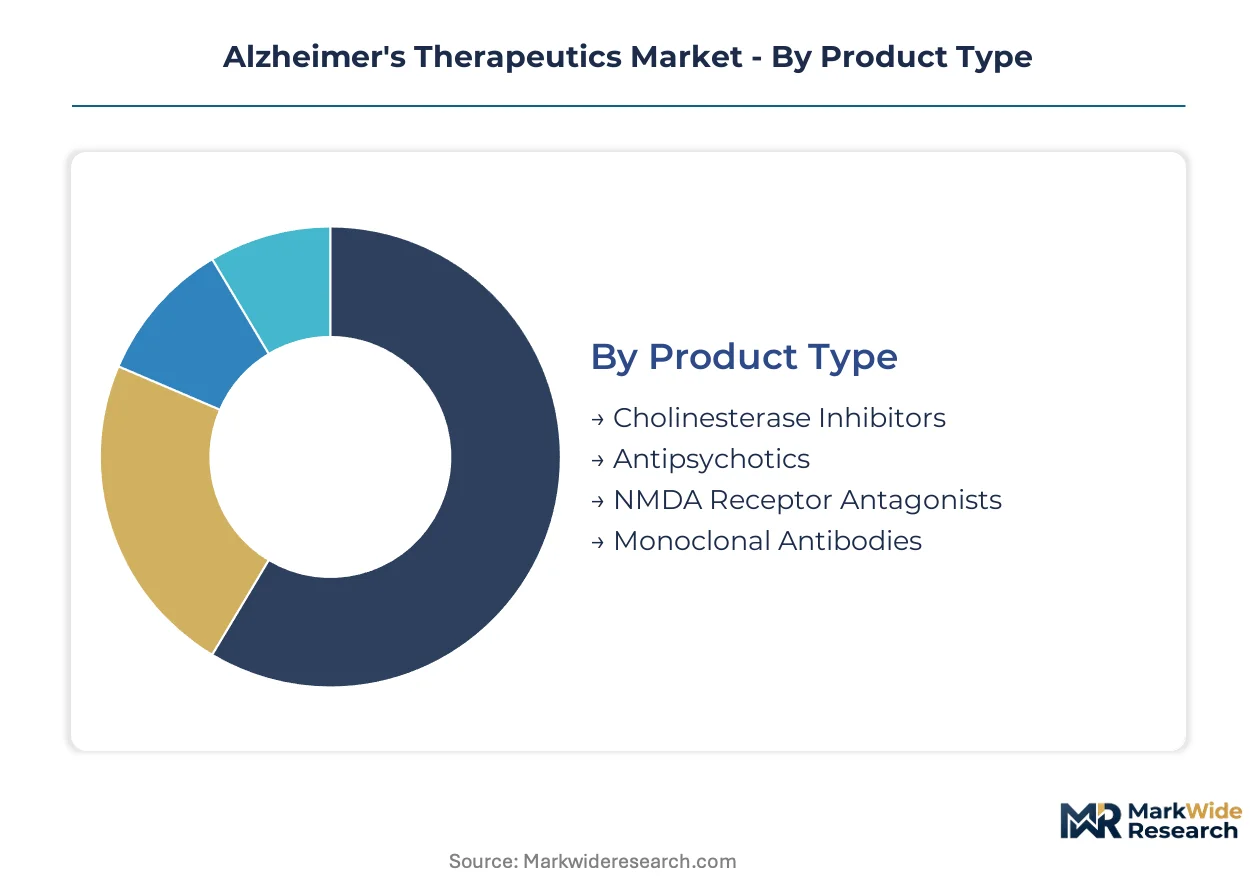
Alzheimer's therapeutics segmentation reflects divergent capital requirements across manufacturing modalities. Cold-chain antibody production demands bioreactor infrastructure and sterile fill-finish capacity that oral small-molecule facilities cannot accommodate. Understanding these investment profiles guides portfolio allocation between mature symptomatic agents and disease-modifying platforms.
Product Type:
Monoclonal antibodies command the steepest upfront capital commitment, requiring single-use bioreactor suites and dedicated viral clearance validation. Cholinesterase inhibitors and NMDA antagonists leverage existing small-molecule infrastructure with lower barrier to entry.
- Monoclonal Antibodies:Recombinant protein therapeutics targeting amyloid-beta or tau pathology require mammalian cell culture systems and continuous cold-chain integrity from manufacturing through patient administration. Demand concentrates in United States academic medical centers with certified infusion suites and MRI monitoring capabilities, constrained by FDA risk evaluation and mitigation strategy prescriber certification requirements.
- Cholinesterase Inhibitors:Small-molecule acetylcholinesterase inhibitors including donepezil, rivastigmine, and galantamine operate through established oral solid dose manufacturing. Generic erosion has compressed pricing power, though volume leadership persists in primary care prescribing across Germany and France where diagnostic infrastructure reaches mild cognitive impairment populations earlier.
- NMDA Receptor Antagonists:Memantine and combination formulations address moderate-to-severe disease stages through glutamatergic modulation.
- Antipsychotics:Atypical antipsychotic agents manage behavioral and psychological symptoms of dementia under restricted labeling.
Most installed capacity flows through Cholinesterase Inhibitors. Expansion is steepest in Monoclonal Antibodies.
Administration Route:
Route selection determines site-of-care economics and patient access geography. Injectable formats concentrate treatment in urban corridors with neurological infrastructure, while oral and transdermal options extend reach into rural and home-based settings.
- Injectable:Intravenous monoclonal antibody delivery requires certified infusion centers with emergency response protocols for amyloid-related imaging abnormalities. United States hospital systems are consolidating these services under neurology service lines, displacing standalone outpatient operators.
- Oral:Tablet and capsule formulations dominate symptomatic management with pharmacy distribution through retail and mail-order channels. Medicare Part D coverage structures anchor demand concentration among community-dwelling patients in early-to-moderate disease stages.
- Transdermal:Rivastigmine patches provide continuous drug delivery with reduced caregiver burden for medication adherence.
- Inhalation:Investigational dry powder and nebulized formulations target rapid CNS penetration for acute agitation episodes.
Oral administration retains the broadest patient reach. Injectable formats are gaining share fastest among disease-modifying candidates.
Stage of Development:
Clinical phase distribution shapes capital deployment timelines and regulatory risk profiles. Late-stage assets demand commercial manufacturing investment before approval certainty, while early-phase programs require flexible platform technologies.
- Phase III:Registrational trials for anti-amyloid and anti-tau antibodies command the largest development expenditures, with global site networks spanning North America, Western Europe, and Japan. Confirmatory endpoint requirements under FDA accelerated approval pathways extend observation periods and inflate per-patient costs.
- Phase II:Proof-of-concept studies for novel mechanisms including neuroinflammation modulators and synaptic plasticity agents concentrate in academic medical center partnerships. Biomarker-enriched designs reduce sample sizes but require PET imaging and CSF collection infrastructure.
- Phase I:First-in-human safety assessments for small-molecule and biologic candidates.
- Preclinical:Discovery-stage programs leveraging human iPSC-derived neuron models and transgenic animal systems.
Most development capital is tied up in Phase III programs. Preclinical investment is expanding most quickly for combination therapy platforms.
End User:
Care setting fragmentation creates divergent procurement and reimbursement pathways. Hospital systems negotiate centralized contracts for infused therapies, while home care operators manage oral medication adherence through nursing networks.
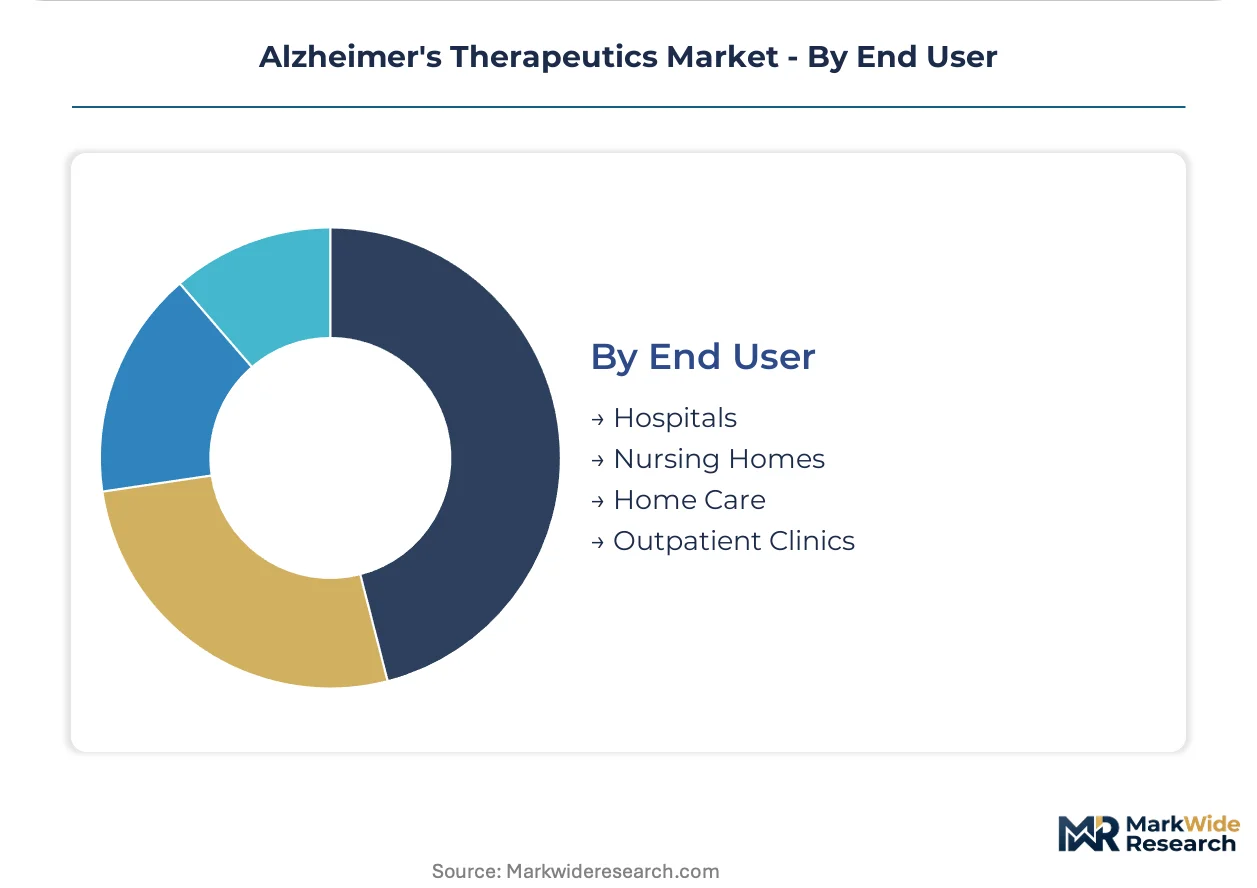
- Hospitals:Academic and community hospital neurology departments anchor infusion-based monoclonal antibody delivery, with CMS national coverage determinations restricting reimbursement to registry-enrolled patients. United States health systems are acquiring community practices to capture patient flow earlier in disease progression.
- Nursing Homes:Long-term care facilities manage behavioral symptom control through psychotropic protocols, facing regulatory scrutiny from CMS on antipsychotic prescribing rates. Medication administration by licensed nursing staff dominates procurement decisions.
- Home Care:Home health agencies and informal caregiver networks manage oral cholinesterase inhibitor adherence.
- Outpatient Clinics:Memory care centers and neurology private practices conduct diagnostic workups and treatment initiation.
Most treated patients flow through Outpatient Clinics for diagnosis. Capacity expansion is steepest in Hospitals for infusion-based disease modification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized neurology workforces concentrate in academic medical centers across the United States, Germany, and Japan, anchoring regional capacity for amyloid-targeting therapy administration. These talent clusters determine where infusion infrastructure expands and where clinical trial networks achieve recruitment density.
United States
Cleveland Clinic and Mayo Clinic anchor infusion center certification programs that train nursing staff for monoclonal antibody administration. Medicare national coverage determinations restrict reimbursement to registry-enrolled patients with confirmed amyloid pathology. Massachusetts General Hospital and Johns Hopkins Hospital operate the densest networks of neurological infusion suites with MRI monitoring capabilities.
Germany
Memory clinic partnerships with general practitioners in Bavaria and North Rhine-Westphalia expand diagnostic reach before specialist referral. The Federal Joint Committee (G-BA) applies provisional reimbursement tied to demonstrated outcome milestones for accelerated approvals. Heidelberg University Hospital and Charité Berlin anchor the country's clinical trial site network for anti-amyloid therapies.
Japan
PMDA's Sakigake designation system compresses review timelines for disease-modifying candidates targeting unmet neurological need. Tokyo University Hospital and Osaka University Hospital concentrate the nation's certified prescriber workforce for risk evaluation protocols. Domestic pharmaceutical manufacturers leverage joint development structures to extend reach into North American markets simultaneously.
United Kingdom
NHS England's specialized commissioning frameworks concentrate disease-modifying therapy access in designated neuroscience centers. The Medicines and Healthcare products Regulatory Agency (MHRA) applies conditional approval pathways demanding post-authorization evidence generation. London's National Hospital for Neurology and Neurosurgery and Manchester's Salford Royal Hospital anchor infusion capacity.
Switzerland
Swissmedic's accelerated assessment procedures align with EMA conditional marketing authorization timelines for surrogate endpoint approvals. Basel and Zurich host dense clusters of neurology specialists serving cross-border patient flows from France and Germany. University Hospital Zurich operates specialized infusion infrastructure with integrated PET imaging capabilities for patient selection.
Alzheimer's Therapeutics Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the Alzheimer's therapeutics landscape, creating a tiered competitive structure. Large-cap pharmaceutical companies leverage manufacturing scale and global distribution networks to dominate monoclonal antibody segments. Mid-sized neurology specialists concentrate on targeted mechanisms and regional market access. Competitive moves center on joint development structures for risk sharing and manufacturing partnerships for cold-chain capacity.
Within the large-cap diversified tier, Biogen Inc., Eli Lilly and Company, and Eisai Co., Ltd. exemplify contrasting strategic archetypes. Biogen represents the neurology-focused incumbent leveraging established infusion center partnerships. Eli Lilly occupies the manufacturing scale position for antibody-based therapies. Eisai exemplifies the joint-venture specialist extending geographic reach through co-development structures rather than standalone infrastructure.
| Leading Market Players |
|---|
| Biogen Inc. |
| Eisai Co., Ltd. |
| Eli Lilly and Company |
| AbbVie Inc. |
| Novartis AG |
| Johnson & Johnson Services Inc. |
| Pfizer Inc. |
| Merck & Co., Inc. |
| H. Lundbeck A/S |
| Others |
Cost & Logistics Intelligence
Certified prescriber workforce concentration in United States academic medical centers anchors labor-cost differentials that widen pricing-tier spreads between infusion-based monoclonal antibodies and oral symptomatic agents. Neurology nursing specialists command premium compensation in certified infusion suites, forcing manufacturers to absorb site-of-care overhead into therapy pricing while generic cholinesterase inhibitors compete on pharmacy margin alone.
Pricing Analysis
Bundled service contracts dominate monoclonal antibody pricing, packaging drug acquisition with infusion administration and MRI monitoring protocols, while unbundled oral therapies compete through pharmacy benefit manager rebates. Price differentiation rests on prescriber certification tier and amyloid confirmation requirements, with registry-enrolled academic centers commanding premium reimbursement versus community neurology practices. Cost compression in the symptomatic segment intensifies as donepezil and memantine face multi-source generic erosion. Medicare Part D enrollees exhibit highest price sensitivity for daily oral regimens, whereas hospital systems negotiating national coverage determination contracts absorb infusion-based premiums through bundled case rates.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and Japan operate hub-and-spoke cold-chain networks that feed certified infusion suites with two-to-eight-degree Celsius integrity requirements. Mammalian cell culture bioreactors in the United States, Ireland, and Switzerland anchor monoclonal antibody production, drawing from single-use bag assemblies and proprietary protein A resin chromatography media. Single-source vulnerability concentrates in specialty pharmacy distributors with REMS certification. Distribution runs through hospital-system consolidated service lines rather than fragmented outpatient operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Alzheimer's therapeutics market functions as a stable compounder, with Medicare national coverage determinations anchoring predictable reimbursement pathways that sustain manufacturer revenue visibility across regulatory cycles.
For Market Incumbents: Cement prescriber certification monopolies by acquiring community neurology practices before diagnostic referral, converting fragmented patient flow into captive infusion volume. Deepen backward integration into cold-chain logistics to offset specialty pharmacy distributor concentration risk. For New Entrants and Emerging Players: Enter via primary care screening networks in Germany and France, where memory clinic partnerships with general practitioners remain underpenetrated for mild cognitive impairment detection. Target diagnostic infrastructure buildout ahead of therapeutic launch, securing patient identification capacity before antibody approval. For Investors and Strategic Acquirers: Large-cap pharmaceutical companies with neurology service line integration are the most active acquirers in this space, seeking Phase II tau-targeting assets to stack against existing amyloid platforms. Watch FDA confirmatory trial readouts as the inflection signal for accelerated approval withdrawal risk versus full conversion.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase III biomarker-enriched designs reduce sample sizes through PET imaging patient selection at academic medical centers. |
| Regulatory Approval Pathway | FDA accelerated approval via surrogate endpoints compresses timelines while demanding confirmatory cognitive outcome studies. |
| Manufacturing Scale-Up | Single-use bioreactor capacity expansion in Ireland and Switzerland addresses cold-chain antibody production bottlenecks. |
| Hospital System Partnership | Academic medical center infusion suite certification programs anchor monoclonal antibody administration capacity. |
| Pipeline Diversification | Tau-targeting agents and neuroinflammation modulators extend mechanism portfolios beyond amyloid-beta clearance. |
Research Approach
Coverage spans North America, Western Europe, and Asia-Pacific, with primary inputs from each region triangulated against secondary validation. Drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers provided operational perspective on infusion infrastructure constraints and payer access dynamics. FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS national coverage determination documents anchored secondary data architecture. Bottom-up patient-flow modeling and top-down manufacturer revenue reconciliation cross-validated market sizing.
Granularity-level modeling deployed treatment line, administration route, and regional regulatory cluster as core segmentation dimensions across the projection horizon. CAGRs were derived from epidemiology-adjusted patient penetration curves and pricing trajectory assumptions. Biomarker confirmation rates and prescriber certification expansion timelines served as key forecast inputs for monoclonal antibody adoption.
Inputs from clinical trial registries and payer policy databases were available through the study window; gaps in real-world evidence generation timelines introduce uncertainty bands around confirmatory trial success assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmacology
Aldosterone Receptor Antagonists Market
Pharmacology
Medication Adherence Market
Pharmacology
Global Asthma Therapeutics Market
Pharmacology
Ketoprofen API Market
Pharmacology
Prescription Narcotic Cough Preparations and Expectorants Market
Pharmacology
Global Geriatric Medicines Market
Pharmacology
Immunotherapy Drugs Market
Pharmacology
Drug Eruptions Treatment Market
Pharmacology
Global Migraine Therapeutics Market
Pharmacology
Aspirin API Market
Pharmacology
Antitussive Drugs Market
Pharmacology
Huoxiang Zhengqi Drug Market
Pharmacology
Alexipharmic Drugs Market
Pharmacology
Pegylated Drugs Market
Pharmacology
Antihyperlipidemic Drugs Market
Pharmacology
Autacoids and Related Drugs Market