
 In-Flight Telemedicine System Market | 2026-2036
In-Flight Telemedicine System Market Size, Share, and Industry Trends Forecast 2026-2036
In-Flight Telemedicine System Market Insights
Class II medical device certification is reorganizing competitive positioning in airborne telemedicine. Teladoc Health Inc sustains technology leadership through its virtual care platform architecture optimized for low-bandwidth satellite links. Philips dominates diagnostic hardware integration, leveraging its patient monitoring ecosystems for cabin deployment. American Well anchors the software layer, specializing in clinician network orchestration for aviation contracts.
An in-flight telemedicine system constitutes a networked diagnostic and communication platform that transmits patient physiological data and video to ground-based clinicians during aircraft operations, typically operating at latency thresholds below 500 milliseconds for cardiac event triage. Real-time consultation systems command premium deployment as airlines prioritize immediate physician access for critical incidents, while remote monitoring segments expand fastest through wearable integration for crew health programs. Satellite-based deployment retains structural importance over oceanic routes where air-to-ground cellular handoffs fail, though hybrid communication architectures now capture investment as carriers seek seamless coverage transitions.
FAA Part 25 airworthiness standards, EASA CS-25 certification requirements, and FDA 510(k) clearance pathways collectively govern device approval timelines and cabin installation protocols, extending product development cycles by months. The EU AI Act introduces additional algorithmic transparency obligations for diagnostic assistance modules employing machine learning. Stakeholders must monitor evolving cybersecurity mandates for airborne medical data transmission as regulators harmonize aviation safety with healthcare privacy frameworks.
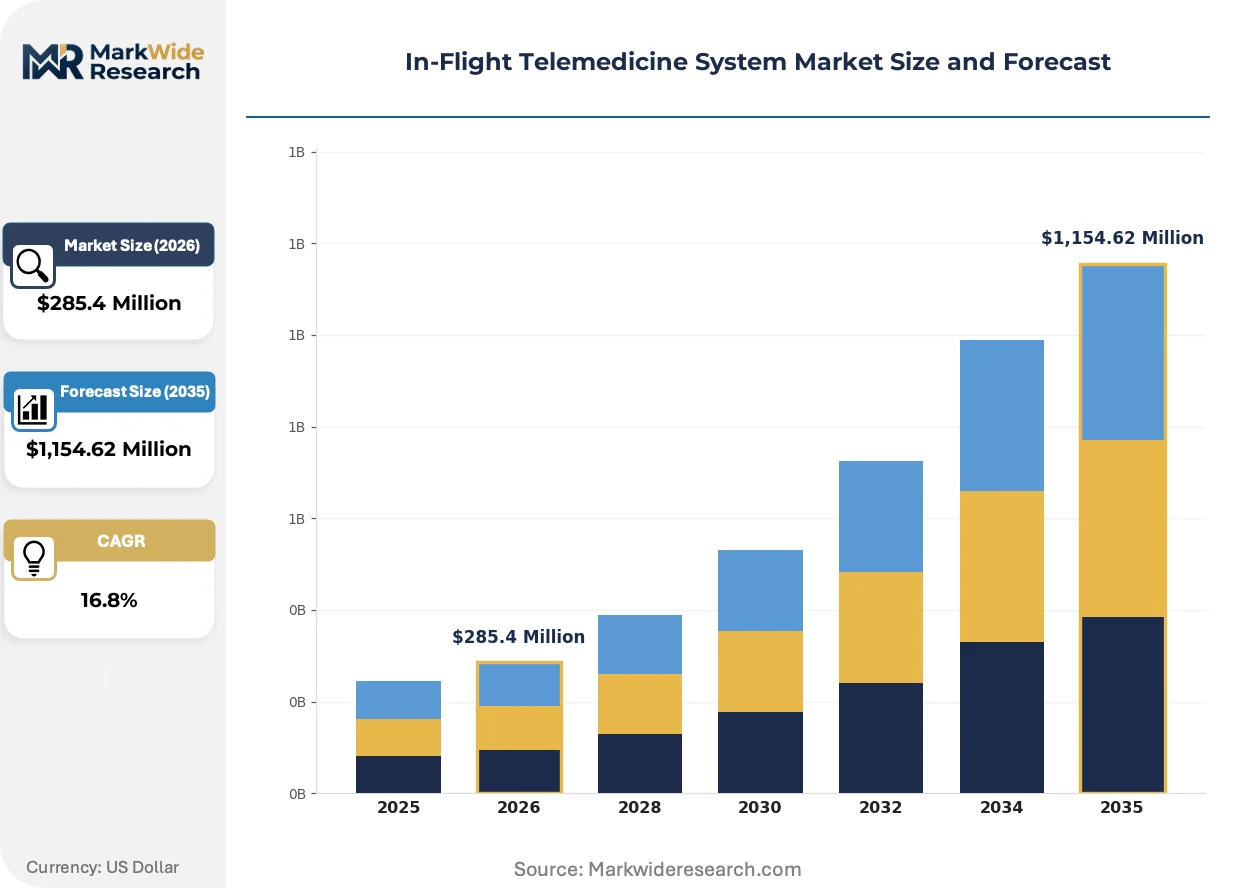
Market Dynamics
Class II medical device certification timelines are compressing vendor margins while hybrid satellite-cellular communication architectures recalibrate deployment economics across fleet modernization programs.
Growth Catalysts
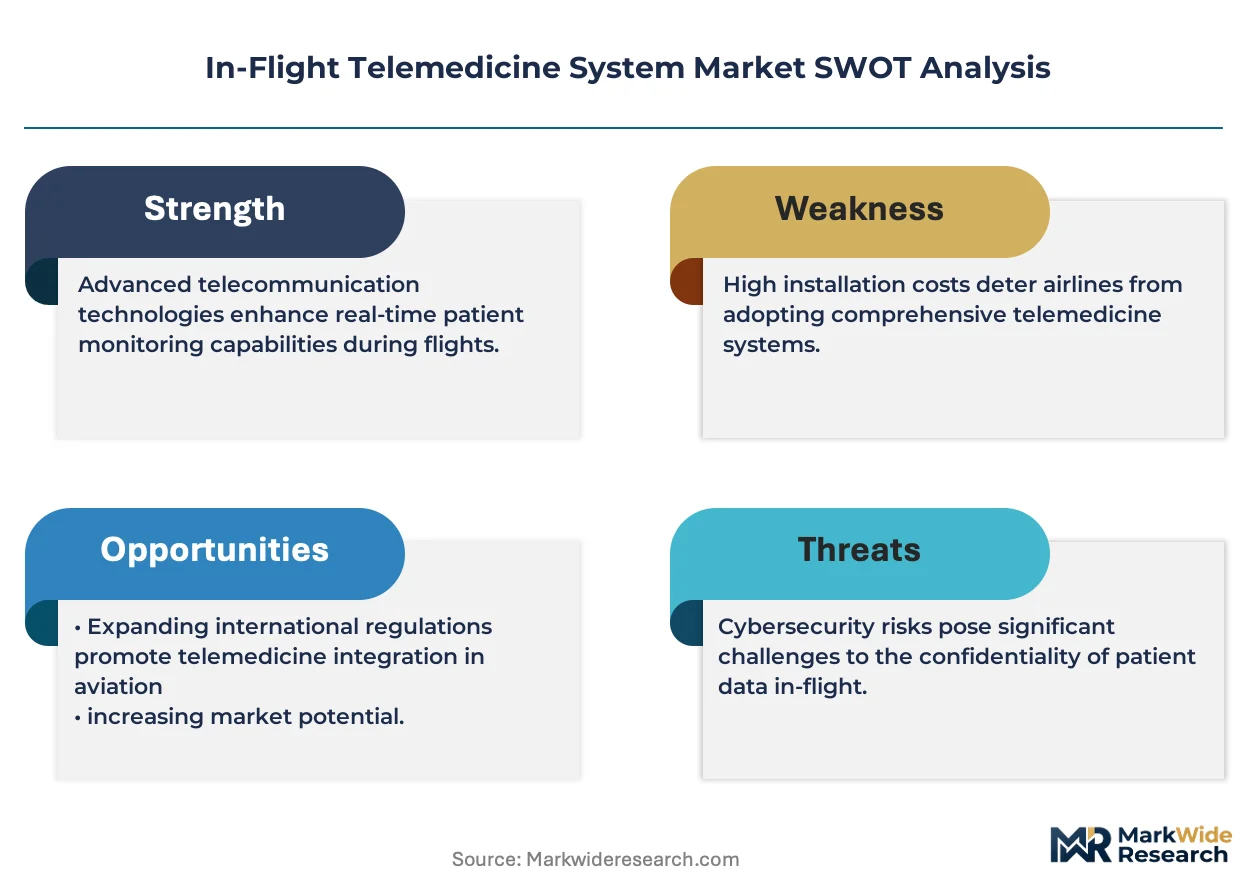
- FAA Part 25 airworthiness mandates:Airlines retrofitting wide-body fleets for real-time cardiac monitoring capabilities must install certified diagnostic hardware, creating pull-through demand for integrated telemedicine platforms.
- Wearable biosensor convergence:Crew health monitoring programs are expanding from reactive emergency response to continuous physiological tracking, embedding telemedicine infrastructure into standard operating procedures.
- China fleet expansion:Domestic carriers adding long-haul routes over Pacific corridors require satellite-based consultation systems where cellular handoffs fail, prioritizing redundant medical communication layers.
Market Restraints
- Certification cost structure:FDA 510(k) clearance pathways combined with EASA CS-25 validation extend product development cycles by months, locking smaller vendors out of commercial aviation contracts.
- Bandwidth supply concentration:Satellite communication providers operating geostationary fleets over oceanic routes command premium pricing for guaranteed low-latency medical data transmission.
- Legacy aircraft retrofit limitations:Narrow-body fleets without factory-installed diagnostic harnesses face structural wiring constraints that prevent seamless telemedicine integration.
Strategic Opportunities
- India domestic aviation expansion:Low-cost carriers building regional networks present greenfield deployment potential for lightweight, portable telemedicine kits without heavy certification baggage.
- EU AI Act diagnostic transparency:Algorithmic explainability requirements for machine learning triage modules create first-mover advantage for vendors with pre-validated clinical decision support architectures.
- Crew fatigue management convergence:Integration of sleep monitoring wearables with telemedicine backends is opening subscription-based preventive health revenue streams distinct from emergency response pricing.
Industry Challenges
- Aerospace-medical hybrid talent scarcity:Engineers capable of bridging avionics certification protocols with clinical workflow design command compensation premiums that strain vendor operating models.
- Cybersecurity compliance fragmentation:Harmonizing FAA airborne data transmission standards with HIPAA privacy frameworks requires dedicated legal-technical liaison functions most vendors lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In-Flight Telemedicine System Market |
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $1,154.62 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Real-time Consultation, Store-and-Forward, Remote Monitoring, Emergency Response, Diagnostic Assistance Deployment Mode: Satellite-Based, Air-to-Ground, Hybrid Communication, Cloud-Integrated, Offline Capability Use Case: Medical Emergencies, Routine Health Monitoring, Mental Health Support, Chronic Condition Management, Preventive Care End User: Commercial Airlines, Charter Services, Military Aviation, Air Ambulance Operators, Private Aviation |
| Companies Covered | Teladoc Health Inc, Avizia, MIME Technologies, MDLive, Doctor On Demand, Remote Diagnostic Technologies, Philips, Polycom, American Well, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In-Flight Telemedicine System Market Trends and Innovations
Edge computing architectures are redistributing diagnostic processing from ground stations to aircraft systems, compressing triage latency while complicating certification scopes. This shift is forcing vendors to rethink hardware-software boundaries.
Modular patient monitoring hardware is decomposing traditional integrated diagnostic suites into swappable, independently certifiable components. Regional carriers operating mixed fleets are adopting these building-block configurations to reduce spare parts inventory overhead. The approach is decomposing vendor lock-in patterns that previously tied airlines to single-source ecosystem providers.
The EU AI Act's algorithmic transparency obligations are tightening documentation requirements for machine learning modules embedded in cardiac event detection systems. Vendors must now submit training data provenance and bias audit trails alongside traditional safety validation. Long-haul European operators are prioritizing suppliers with pre-established regulatory documentation libraries to compress deployment timelines.
Airline procurement departments are unbundling hardware acquisition from clinical service subscriptions, treating ground-based physician networks as separately negotiable contracts. This purchasing pattern is fragmenting vendor relationships that previously bundled device and service under single-source agreements. North American legacy carriers are driving this separation most aggressively, using competitive bidding for clinician network access to pressure integrated providers.
In-Flight Telemedicine System Market Segmentation
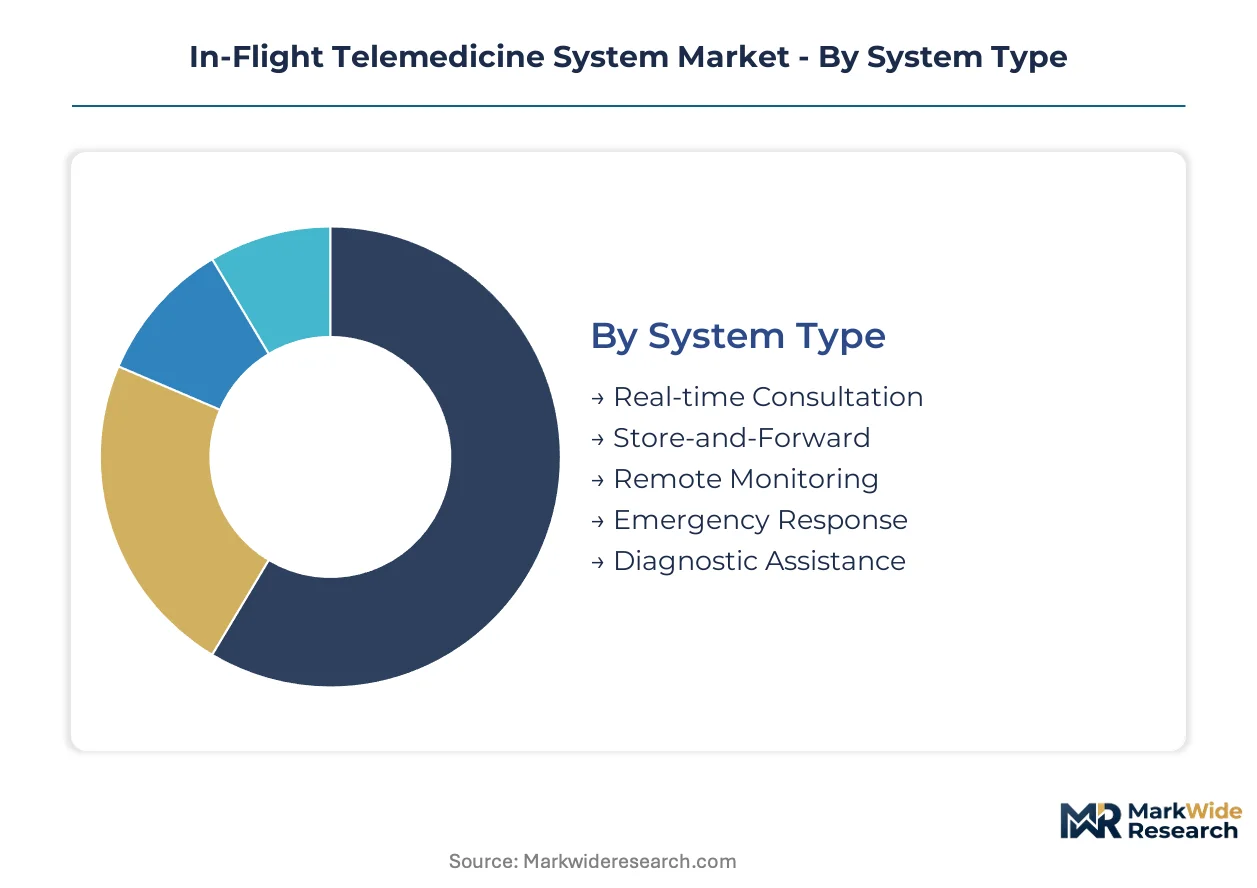
Telemedicine system architectures must reconcile aviation certification constraints with clinical workflow requirements. Segment boundaries determine vendor specialization, procurement bundling, and regulatory pathway selection across fleet modernization programs.
System Type:
Real-time consultation platforms dominate transoceanic routes where satellite redundancy matters, while store-and-forward systems concentrate in regional short-haul markets with intermittent connectivity.
- Real-time Consultation:Synchronous video-physician links operating below 500-millisecond latency thresholds for cardiac event triage. Demand clusters with United States-based legacy carriers retrofitting wide-body fleets under FAA Part 25 mandates for immediate physician access during critical incidents.
- Remote Monitoring:Continuous physiological data streams from wearable biosensors enabling crew fatigue tracking and preventive health protocols. German and Chinese carriers are embedding this infrastructure into standard operating procedures as fleet health programs expand beyond reactive emergency response.
- Store-and-Forward:Asynchronous transmission of diagnostic imagery and patient records for delayed specialist review.
- Emergency Response:Protocol-driven automated guidance systems for cabin crew intervention before ground contact.
- Diagnostic Assistance:Algorithm-supported clinical decision tools requiring EU AI Act transparency documentation for European deployment.
Real-time consultation commands the established base. The steepest expansion runs through remote monitoring.
Deployment Mode:
Cost tiers separate premium guaranteed-bandwidth contracts from economized hybrid architectures that blend satellite redundancy with cellular handoffs where terrain permits.
- Satellite-Based:Geostationary fleet connectivity ensuring coverage over Pacific and Atlantic corridors where terrestrial infrastructure fails. China domestic carriers adding long-haul routes require these redundant layers, accepting premium pricing from concentrated bandwidth suppliers.
- Hybrid Communication:Seamless satellite-cellular handoff architectures capturing investment as carriers seek coverage continuity across flight phases. United States regional operators prioritize these configurations to optimize transmission economics on mixed-route networks.
- Air-to-Ground:Cellular tower handoff systems limited to continental airspace with dense ground infrastructure.
- Cloud-Integrated:Centralized data architectures enabling fleet-wide analytics and predictive maintenance of medical equipment.
- Offline Capability:Localized diagnostic processing for initial triage when connectivity drops, requiring edge computing hardware certification.
Satellite-based deployment retains the revenue concentration. Hybrid architectures are climbing the fastest as procurement seeks cost optimization without coverage gaps.
Use Case:
Application maturity spans from legally mandated emergency response to emerging subscription models for crew wellness programs.
- Medical Emergencies:Acute event triage for cardiac arrest, anaphylaxis, and trauma during flight operations. Regulatory pressure from FAA and EASA certification requirements drives baseline installation across commercial fleets operating in United States and European airspace.
- Chronic Condition Management:Pre-flight passenger health screening and in-flight medication adherence support for diabetic and hypertensive travelers. German carriers are piloting these services on long-haul routes to differentiate premium cabin offerings.
- Routine Health Monitoring:Basic vital sign tracking for general passenger wellness without acute intervention protocols.
- Mental Health Support:Crisis intervention and anxiety management resources delivered through encrypted communication channels.
- Preventive Care:Subscription-based crew wellness programs integrating sleep monitoring with telemedicine backends.
Medical emergencies command the established base. Preventive care is gaining share fastest as airlines seek recurring revenue streams distinct from emergency response pricing.
End User:
Customer type determines certification burden, with commercial airlines accepting full regulatory rigor while private aviation seeks portable lightweight alternatives.
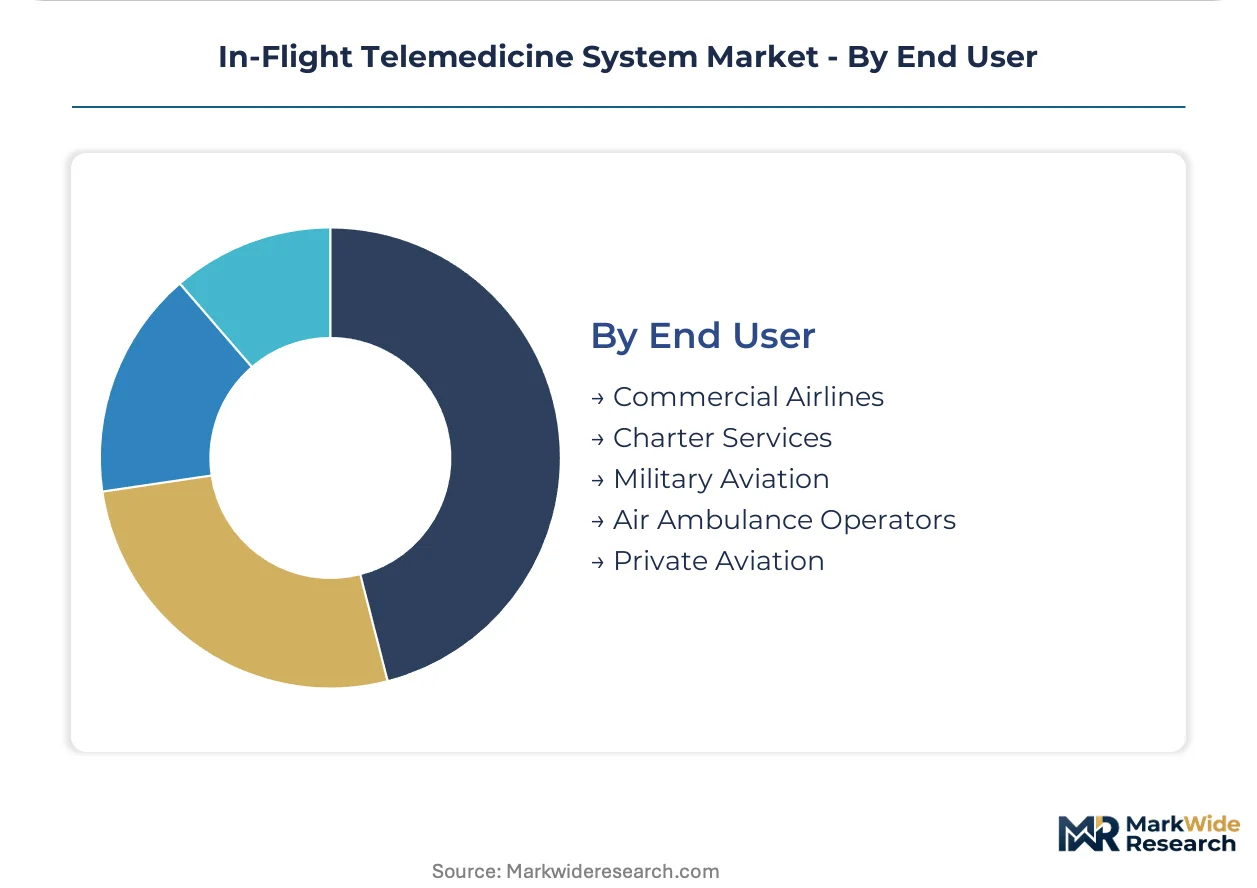
- Commercial Airlines:Scheduled carriers operating under FAA Part 121 and EASA Part-CAT with fleet-wide standardization requirements. United States legacy carriers are unbundling hardware acquisition from clinical service subscriptions, fragmenting vendor relationships through competitive bidding.
- Air Ambulance Operators:Medical transport services requiring intensive care-grade monitoring during patient transfer. These operators in Germany and Switzerland demand the highest diagnostic hardware specifications, driving premium segment margins.
- Charter Services:On-demand operators with variable fleet composition seeking modular, transferable telemedicine kits.
- Military Aviation:Defense departments with classified transmission requirements and hardened cybersecurity specifications.
- Private Aviation:Individual aircraft owners and fractional ownership programs prioritizing portable, minimally certified solutions.
Commercial airlines command the established base. Air ambulance operators are expanding most quickly as specialized medical transport networks professionalize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a substantial trade surplus in airborne medical equipment, exporting diagnostic hardware to European and Asian carriers while importing specialized telemedicine software modules from Israeli and Indian developers. Germany and China maintain near-balanced flows, with China accelerating domestic production of satellite communication terminals to reduce import dependency on North American suppliers.
United States
Legacy carriers retrofitting wide-body fleets under FAA Part 25 mandates drive demand for certified diagnostic hardware. The FDA 510(k) clearance pathway governs device approval timelines, extending product development cycles. Dallas-Fort Worth anchors the domestic aerospace-medical cluster, where avionics specialists collaborate with clinical workflow designers on integrated cabin systems.
Germany
Lufthansa Group's fleet health programs embed continuous crew monitoring into standard operating procedures, expanding wearable integration contracts. EASA CS-25 certification requirements tighten device standards alongside MDR compliance for diagnostic hardware. Hamburg's aviation technology corridor concentrates vendors specializing in modular patient monitoring components for mixed-fleet operators.
China
Domestic carriers adding Pacific long-haul routes require redundant satellite-based consultation systems where cellular handoffs fail. NMPA medical device registration and MIIT telecommunications licensing create dual regulatory tracks for system deployment. Shanghai's Yangtze River Delta hosts the primary manufacturing base for cabin-integrated diagnostic terminals serving Asia-Pacific carriers.
Switzerland
Air ambulance operators in Zurich and Geneva demand intensive care-grade monitoring specifications, driving premium segment margins for specialized hardware. Swissmedic medical device oversight aligns with EASA airborne certification, streamlining approval for alpine rescue aviation applications. The Basel region concentrates precision sensor manufacturers supplying cardiac event detection modules to European telemedicine platforms.
India
Low-cost carriers building regional networks present greenfield deployment potential for lightweight telemedicine kits without heavy certification baggage. CDSCO medical device rules and DGFT import licensing shape procurement pathways for foreign suppliers. Bangalore's aerospace engineering hub incubates domestic vendors developing portable diagnostic hardware for narrow-body retrofit limitations.
In-Flight Telemedicine System Market Competitive Landscape
Concentration sits with integrated platform providers bundling hardware certification with clinical service orchestration. The vendor base spans three tiers: established telemedicine networks leveraging aviation contracts, diagnostic hardware specialists extending patient monitoring ecosystems into cabin environments, and emerging portable kit developers targeting regional carrier price sensitivity. Strategic moves center on unbundling hardware acquisition from physician network subscriptions, and hybrid communication architecture partnerships compressing satellite bandwidth costs.
Within the integrated platform tier, Teladoc Health Inc and American Well exemplify contrasting approaches to aviation market penetration. Teladoc's virtual care architecture optimizes for low-bandwidth satellite links, while American Well anchors clinician network orchestration for carrier contracts. Philips occupies a distinct position as diagnostic hardware incumbent, leveraging patient monitoring ecosystems for cabin deployment without direct competition in the service layer. MDLive represents the mid-tier specialist archetype, focusing on modular software integration rather than full-stack platform ownership.
| Leading Market Players |
|---|
| Teladoc Health Inc |
| Avizia |
| MIME Technologies |
| MDLive |
| Doctor On Demand |
| Remote Diagnostic Technologies |
| Philips |
| Polycom |
| American Well |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation contracts with satellite bandwidth providers lock in both supply access and price visibility for telemedicine platform vendors, insulating procurement teams from spot-market volatility on Pacific and Atlantic routes where geostationary fleet coverage concentrates. These arrangements tether hardware manufacturers to guaranteed transmission economics while compressing margin flexibility for smaller entrants lacking volume scale.
Pricing Analysis
Commercial airline procurement teams anchor three-tier pricing structure across premium, standard, and economy levels based on certification grade and after-sales service bundling. Price differentiation hinges on FDA 510(k) clearance tier and geographic delivery cost to fleet maintenance hubs. Cost compression in standard-tier hardware is intensifying because Chinese domestic carriers are consolidating purchase volumes. Low-cost regional operators exhibit highest price sensitivity, while air ambulance operators in Switzerland accept premium positioning for intensive care-grade specifications.
Supply Chain Analysis
Strategic stockpiling of satellite communication terminals dominates inventory strategy, reflecting long lead times for EASA CS-25 certified hardware and MIIT licensing requirements in China. Manufacturing concentrates in the United States, Germany, and China, with precision sensor modules sourcing from Switzerland and avionics harnesses from Mexico. Raw material dependencies include gallium arsenide semiconductors, medical-grade lithium batteries, and aerospace aluminum alloys. Single-source vulnerability runs through geostationary bandwidth providers operating over oceanic corridors. Distribution runs through OEM direct sales for wide-body retrofits and specialized aviation distributors for regional carrier segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in airborne telemedicine are shifting toward unbundled procurement architectures, with hardware certification and clinical service subscriptions decoupling as distinct contract layers. Interoperability between modular diagnostic components and multiple physician network backends is reshaping vendor lock-in dynamics.
For Market Incumbents: Shield installed base relationships by deepening backward integration into satellite bandwidth partnerships that secure transmission cost advantages over emerging hybrid communication entrants. Invest in pre-validated EU AI Act documentation libraries to compress deployment timelines for European carriers facing algorithmic transparency mandates. Certification investment in edge computing hardware represents the critical defensive lever against modular component disruptors.
For New Entrants and Emerging Players: Differentiate on lightweight portable kit architectures that bypass structural wiring constraints plaguing narrow-body retrofits, targeting India's low-cost carrier expansion with minimal certification baggage. The most penetrable segment sits in regional short-haul markets where store-and-forward systems suffice and incumbent platform bundling holds weakest grip. A direct-to-airline procurement channel, bypassing traditional avionics distributors, offers viable go-to-market positioning.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated platform owners with established regulatory documentation libraries and captive clinician networks. Long-term viability over the next decade hinges on hybrid communication architecture control and AI-enabled diagnostic module validation. Acquisition targets should display pre-established FAA-EASA dual certification pathways and existing airline service contracts. The signal to watch is unbundling velocity in North American legacy carrier procurement, where competitive bidding for physician network access accelerates vendor fragmentation.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Communication Partnership | Satellite-cellular handoff architectures reduce bandwidth costs for United States regional operators. |
| EU AI Act Documentation Library | Pre-validated algorithmic transparency compresses deployment timelines for European long-haul carriers. |
| Edge Computing Hardware Certification | Localized diagnostic processing meets EASA CS-25 standards while reducing ground-station dependency. |
| Crew Wellness Subscription Model | Preventive care revenue streams diversify beyond emergency response pricing for German fleet health programs. |
| Modular Component Standardization | Swappable independently certifiable hardware reduces spare parts inventory for mixed-fleet regional operators. |
Research Methodology
Desk research of FAA certification databases, EASA CS-25 technical documentation, and NMPA medical device registries preceded structured interviews with avionics procurement directors, biomedical engineers, airline fleet health managers, and satellite bandwidth contract negotiators. Primary fieldwork with telemedicine platform vendors and diagnostic hardware manufacturers was cross-referenced against customs trade data and hospital procurement databases. Bottom-up installation forecasts by aircraft type were triangulated with top-down airline fleet modernization expenditure projections.
Variance decomposition across system type, deployment mode, use case, and end user segments shaped the analytical framework over the projection horizon. CAGRs were derived from installation run-rate modeling and average system value by certification tier. Forecast inputs included fleet retirement schedules from United States and Chinese carriers, EASA regulatory amendment timelines, and wearable biosensor adoption curves in crew health programs.
The analysis sits within stated boundaries; outcomes outside sustained FAA Part 25 enforcement, stable geostationary satellite capacity, or continued airline fleet expansion assumptions would require recalibration. Forecasts reflect documented assumptions regarding certification timeline compression and hybrid communication technology maturation. Revision becomes warranted when bandwidth supply concentration or cybersecurity compliance fragmentation crosses thresholds that alter vendor economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telemedicine
United States Telehealth Pre-Natal Services Market
Telemedicine
Real-Time E-Healthcare System Market
Telemedicine
Telepathology Service Market
Telemedicine
AI in Telemedicine Market
Telemedicine
US Telemedicine Market
Telemedicine
Telehealth Software Market
Telemedicine
Video Telemedicine Market
Telemedicine
Telehealth and Telemedicine Market
Telemedicine
Global Virtual Care Market
Telemedicine
Asia-Pacific Telemedicine Market
Telemedicine
Online Doctor Consultation Market
Telemedicine
Telestroke Services Market
Telemedicine
Global Telemedicine Market
Telemedicine
Global Tele Intensive Care Unit Market
Telemedicine
Global Healthcare Virtual Assistants Market
Telemedicine
Next Generation Telehealth Market