
 Asia-Pacific Telemedicine Market | 2026-2036
Asia-Pacific Telemedicine Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Telemedicine Market Analysis
Multi-source platform sourcing is restructuring procurement patterns across the Asia-Pacific Telemedicine Market. Ping An Good Doctor leverages its insurer-backed ecosystem to dominate chronic disease management in China. Apollo Hospitals anchors specialist consultation networks across South Asian markets. Philips Healthcare competes on integrated diagnostic hardware and software stacks.
Telemedicine encompasses the remote delivery of clinical services through synchronous video, asynchronous data transmission, and connected biometric devices operating over secure broadband or cellular networks. Its primary commercial purpose is to extend specialist reach while reducing per-encounter infrastructure costs. Video conferencing and remote patient monitoring command the deepest margin pools as health systems prioritize real-time intervention over store-and-forward models. Mobile apps are displacing browser-based portals among younger demographics. Homecare and hospital end users are splitting investment between scheduled chronic management and emergency on-demand deployment.
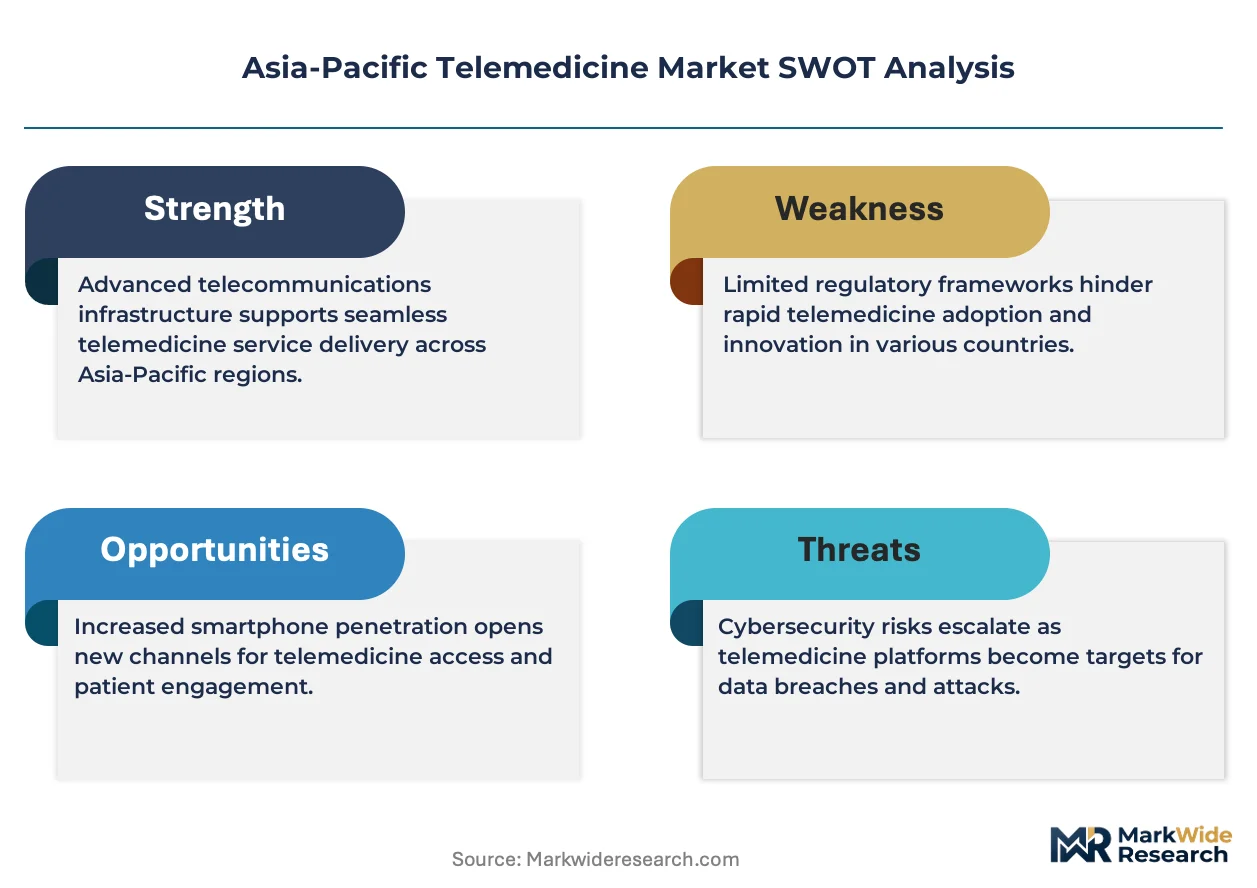
India's CDSCO, China's NMPA, and Australia's TGA enforce divergent software-as-medical-device standards that fragment platform certification costs. Japan's PMDA and South Korea's MFDS are tightening data localization requirements for cross-border patient records. Stakeholders must decide whether to absorb multi-jurisdiction compliance overhead or retreat to single-country specialization.
Market Dynamics
Multi-jurisdiction software-as-medical-device certification is fragmenting platform economics across the Asia-Pacific Telemedicine Market, forcing vendors to absorb compliance overhead or retreat to single-country specialization.
Growth Catalysts
- India's PLI scheme:Domestic medical device manufacturing incentives are accelerating infrastructure deployment for remote diagnostic hardware.
- Rural hospital networks:Indonesia and Vietnam are expanding adoption of remote diagnostic platforms to address specialist physician shortages.
- Cellular network densification:5G rollout in China's tier-2 and tier-3 cities is enabling real-time video consultation where physician density lags metropolitan benchmarks.
Market Restraints
- Data localization mandates:Japan's PMDA and South Korea's MFDS are tightening cross-border patient record restrictions, raising operational complexity.
- Silicon component concentration:Telemedicine hardware supply chains remain dependent on concentrated semiconductor fabrication outside the region.
- Reimbursement fragmentation:Divergent national health insurance protocols create pricing inconsistency across Australia, India, and Southeast Asian markets.
Strategic Opportunities
- Vietnam's underserved provinces:Northern and central rural districts present white space for asynchronous store-and-forward diagnostic services.
- Chronic disease convergence:Integration of continuous glucose monitors with AI triage algorithms is opening new service revenue pools.
- Australia's TGA fast-track:Streamlined software-as-medical-device pathways are reducing time-to-market for validated remote monitoring platforms.
Industry Challenges
- Interoperability standards:Legacy hospital information systems in China and India resist seamless API integration with third-party telemedicine platforms.
- Clinical workflow reconfiguration:Physician training and compensation restructuring demands sustained organizational change management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Telemedicine Market |
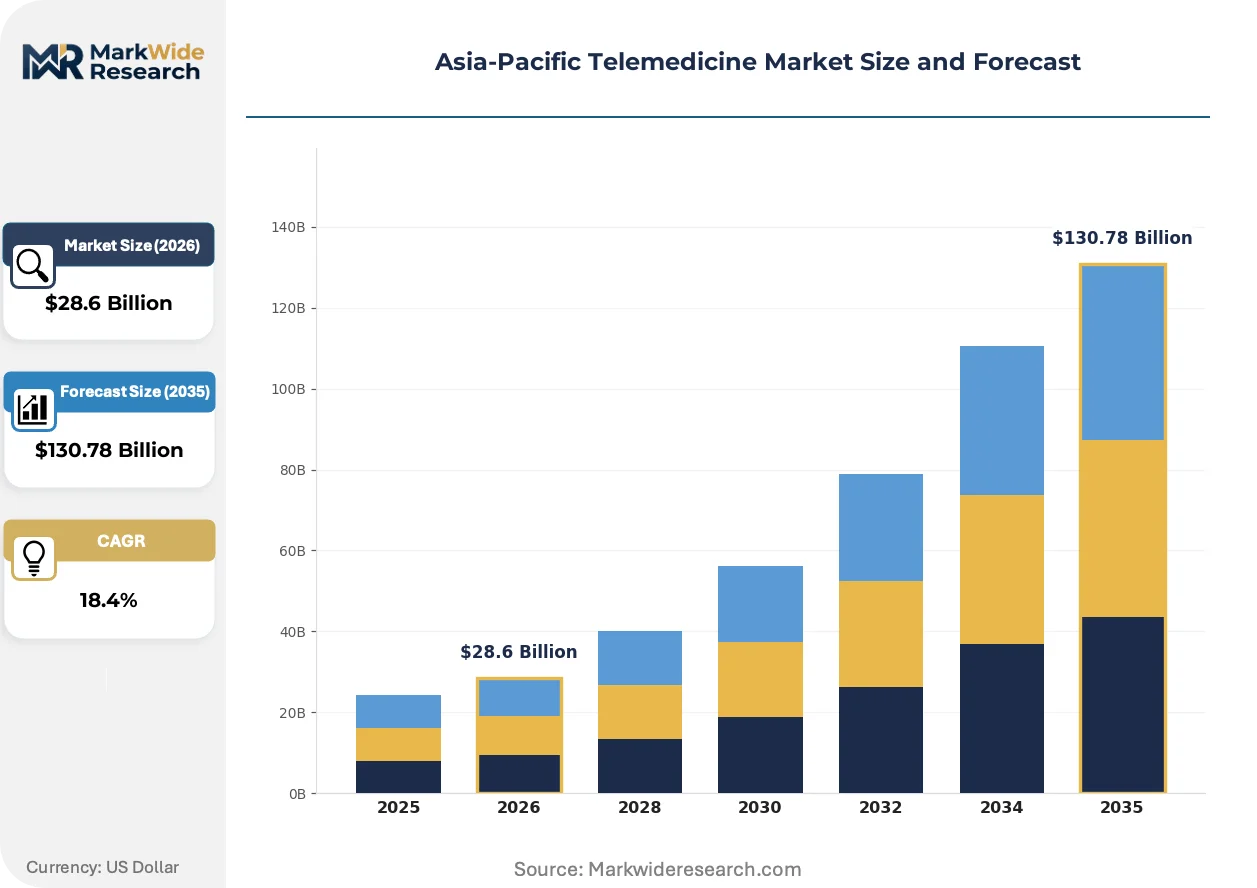
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $130.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Video Conferencing, Mobile Apps, Remote Patient Monitoring, Store-and-Forward Delivery Model: On-Demand, Scheduled, Hybrid, Emergency Services End User: Clinics, Hospitals, Homecare, Pharmacies Service Type: Consultation, Diagnosis, Treatment, Follow-Up Care |
| Companies Covered | GE Healthcare, Ping An Good Doctor, AMD Global Telemedicine, Cisco Systems, Teladoc Health, Philips Healthcare, Apollo Hospitals, Aerotel Medical Systems, Medtronic, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Telemedicine Market Emerging Trajectories
Artificial intelligence triage algorithms, evolving software-as-medical-device frameworks, and shifting patient channel preferences are restructuring how telemedicine platforms capture value across the Asia-Pacific region.
AI-powered symptom classification is automating front-line patient routing in Chinese and Indian hospital networks. Tier-2 city health systems are deploying these tools to reduce specialist consultation bottlenecks. The technology is automating clinical decision support that previously required physician oversight, compressing per-encounter labor costs.
China's NMPA is tightening algorithm transparency requirements for diagnostic software, mandating clinical validation datasets for AI-enabled platforms. This regulatory shift is elevating compliance costs for vendors deploying machine learning models. Domestic Chinese platforms with established regulatory affairs capabilities are capturing market share from foreign competitors.
Mobile-first patient engagement is displacing browser-based portals among younger demographics across Indonesia, Vietnam, and the Philippines. Telemedicine providers are unbundling service packages into app-based subscription tiers. Urban millennial and Gen Z patient segments in Southeast Asian capitals are driving this channel migration fastest.
Asia-Pacific Telemedicine Market Segmentation
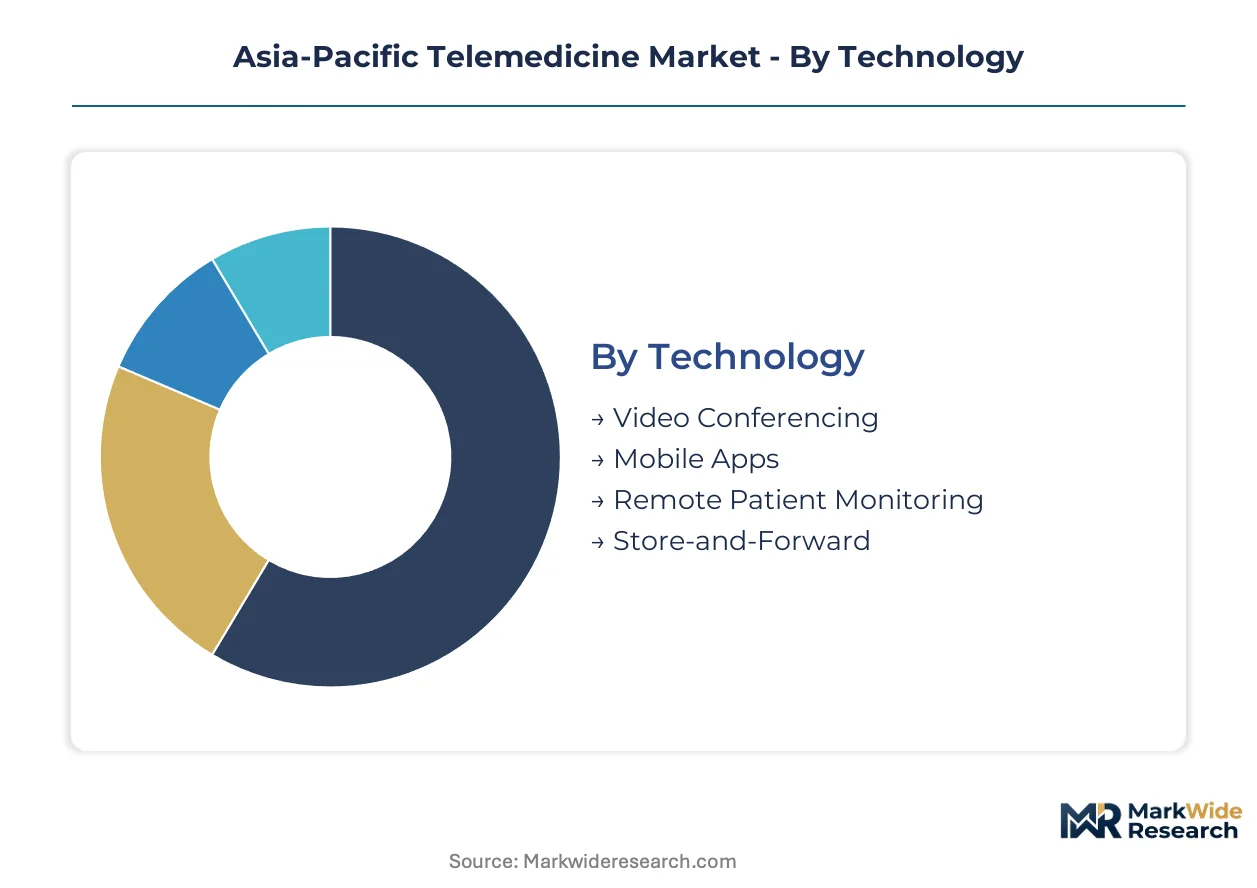
Telemedicine platforms in the Asia-Pacific region configure their technology stacks and service architectures around distinct integration depths. Standalone applications serve intermittent demand, while embedded systems weave into hospital information networks and insurer workflows.
Technology:
Integration depth varies sharply across modalities, with some technologies operating as bolt-on solutions while others demand full-stack hospital system redesign.
- Video Conferencing:Real-time audiovisual platforms with encrypted transmission protocols and low-latency optimization for clinical consultation. China's tier-2 and tier-3 cities deploy these systems most intensively where specialist physician density falls below metropolitan benchmarks.
- Remote Patient Monitoring:Continuous biometric data collection through connected devices with cloud-based analytics dashboards. Homecare providers across India and Indonesia favor this modality for chronic disease management, though reimbursement protocols remain fragmented across national insurance schemes.
- Mobile Apps:Native smartphone applications with offline symptom logging and asynchronous provider messaging. Urban millennial demographics in Jakarta, Manila, and Ho Chi Minh City drive adoption.
- Store-and-Forward:Asynchronous transmission of medical images and clinical data for delayed specialist review. Vietnam's northern rural districts present white space deployment opportunities.
Volume placements concentrate in Video Conferencing; the faster expansion belongs to Remote Patient Monitoring.
Delivery Model:
Cost tier stratification separates episodic, low-touch engagements from comprehensive, subscription-based care relationships.
- On-Demand:Immediate-access consultations triggered by acute symptom onset without prior provider relationship. Southeast Asian capitals show strongest uptake among digitally native patient segments seeking convenience over continuity.
- Scheduled:Pre-booked appointments with designated specialists through platform-managed calendars. Apollo Hospitals anchors this model across South Asian specialist consultation networks.
- Hybrid:Blended synchronous and asynchronous touchpoints combining real-time video with continuous data monitoring. Ping An Good Doctor leverages its insurer-backed ecosystem to dominate chronic disease management deployments.
- Emergency Services:24/7 triage and stabilization support with ambulance dispatch integration. Australia's TGA fast-track pathways accelerate software-as-medical-device certification for these platforms.
Scheduled consultations claim the deepest revenue pools; Emergency Services are climbing the fastest as health systems prioritize real-time intervention.
End User:
Application context determines whether platforms serve institutional workflows or direct-to-consumer channels.
- Hospitals:Enterprise-grade deployments with electronic health record integration and multi-department specialist access. Legacy hospital information systems in China and India resist seamless API integration, elevating implementation complexity.
- Homecare:Patient-directed monitoring and consultation services delivered outside clinical facilities. Japan's PMDA data localization mandates raise operational complexity for cross-border platform operators.
- Clinics:Smaller-scale primary care and specialist practice implementations with lighter IT infrastructure requirements. Rural hospital networks across Indonesia expand adoption to address physician shortages.
- Pharmacies:Medication adherence and minor ailment consultation services with prescription fulfillment integration. India's CDSCO software-as-medical-device standards fragment certification costs.
Hospital deployments absorb the largest capital commitments; Homecare is gaining share fastest as cellular network densification enables reliable connectivity.
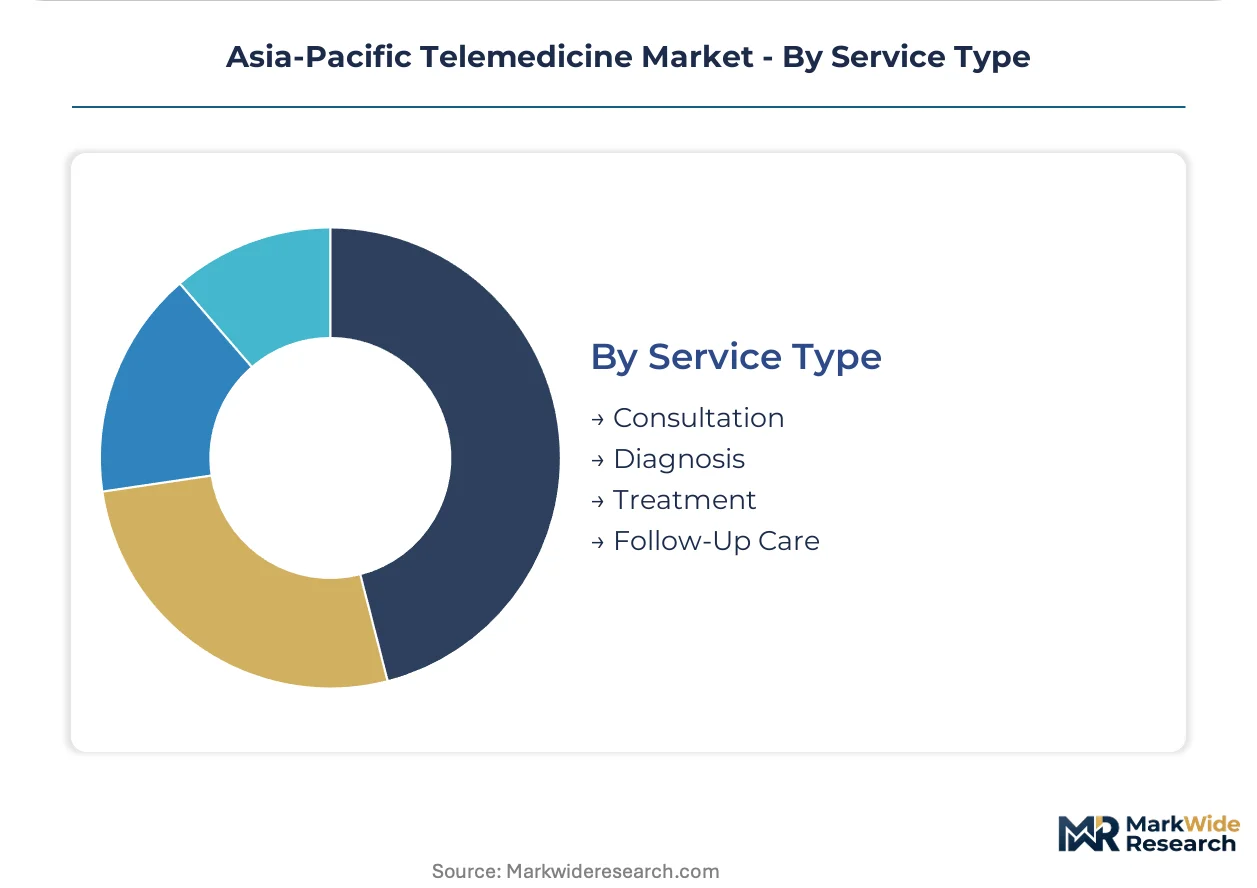
Service Type:
Margin structure separates high-labor diagnostic and treatment services from automated, scalable follow-up workflows.
- Diagnosis:Clinical assessment and differential diagnosis through remote examination and AI-assisted symptom classification. China's NMPA tightening algorithm transparency requirements elevates compliance costs for machine learning platforms.
- Treatment:Therapeutic intervention planning, prescription management, and procedure coordination. Philips Healthcare competes on integrated diagnostic hardware and software stacks.
- Consultation:Initial patient-provider encounters for symptom evaluation and care pathway routing. AI-powered triage algorithms automate front-line patient routing in Chinese and Indian hospital networks.
- Follow-Up Care:Post-treatment monitoring, medication adjustment, and recovery tracking. Mobile-first engagement is displacing browser-based portals among younger demographics.
Diagnosis commands premium pricing; Follow-Up Care shows the steepest expansion trajectory as platforms unbundle services into subscription tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Semiconductor fabrication clusters in Taiwan and South Korea supply the sensor hardware anchoring telemedicine infrastructure across the Asia-Pacific region. Domestic cloud infrastructure investments in China and India are reshaping data sovereignty patterns for health platform operators.
China
Tier-2 and tier-3 cities drive hardware deployment where physician density falls below metropolitan benchmarks. The NMPA tightens algorithm transparency requirements for AI-enabled diagnostic software, elevating compliance costs for machine learning platforms. Yangtze River Delta health systems deploy video conferencing infrastructure most intensively.
India
Rural hospital networks expand adoption to address specialist physician shortages in underserved districts. The CDSCO enforces divergent software-as-medical-device standards that fragment platform certification costs. Maharashtra and Karnataka anchor domestic medical device manufacturing under the PLI scheme.
Japan
Aging demographics accelerate homecare monitoring demand outside traditional clinical facilities. The PMDA tightens data localization requirements for cross-border patient records, raising operational complexity for foreign platform operators. Tokyo-Osaka metropolitan corridors concentrate telemedicine R&D investment.
Australia
Remote and rural communities drive demand for asynchronous diagnostic services bridging specialist access gaps. The TGA operates streamlined software-as-medical-device pathways reducing time-to-market for validated remote monitoring platforms. New South Wales and Victoria anchor enterprise hospital deployments.
Vietnam
Northern and central rural districts present white space for store-and-forward diagnostic services in underserved provinces. The Ministry of Health expands reimbursement frameworks for remote consultation platforms. Ho Chi Minh City anchors private telemedicine startup formation.
Asia-Pacific Telemedicine Market Vendor Landscape
Global majors compete with regional champions across technology integration depth and insurer-backed ecosystem reach. Market structure fragments between hardware-integrated platforms, insurer-affiliated service networks, and standalone software vendors. Three archetypes dominate: diagnostic hardware suppliers with software stacks, insurer-backed chronic disease management platforms, and hospital-anchored specialist consultation networks. Capacity expansion and strategic partnerships represent the dominant competitive moves reshaping vendor positioning.
Among hardware-integrated specialists, GE Healthcare exemplifies the diagnostic equipment-to-software convergence archetype. Ping An Good Doctor occupies a position within the insurer-backed ecosystem tier, leveraging captive patient pools for chronic disease management reach. Apollo Hospitals represents the hospital-anchored consultation network model across South Asian markets.
| Leading Market Players |
|---|
| GE Healthcare |
| Ping An Good Doctor |
| AMD Global Telemedicine |
| Cisco Systems |
| Teladoc Health |
| Philips Healthcare |
| Apollo Hospitals |
| Aerotel Medical Systems |
| Medtronic |
| Others |
Supply Flow & Price Mechanics
Rural hospital procurement clusters across Indonesia and Vietnam anchor volume contracting for remote diagnostic platforms, locking in subscription-tier pricing with hardware bundling that compresses margins for standalone software vendors.
Pricing Analysis
Warranty and multi-year service contracts separate premium platform tiers from unbundled economy offerings. Three-tier pricing structure across premium, standard, and economy levels reflects NMPA certification grade and AI algorithm validation depth. Cost compression in the economy tier is intensifying because India's CDSCO fragments certification costs for foreign entrants. Tier-2 city health systems in China show the highest price sensitivity; insurer-backed ecosystems like Ping An Good Doctor demonstrate the lowest.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for semiconductor fabrication of biometric sensors and video processing chipsets. Telemedicine hardware draws from concentrated silicon supply outside the region, with cloud infrastructure components sourcing from domestic Chinese and Indian data center investments. Tariff exposure on imported diagnostic modules threatens margin stability for hardware-integrated platforms. Distribution runs through hospital procurement committees and insurer channel partnerships rather than direct-to-clinic sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-jurisdiction software-as-medical-device certification overhead is forcing consolidation as smaller vendors retreat from cross-border expansion or absorb unsustainable compliance costs.
For Market Incumbents: Extend regulatory affairs capabilities across NMPA, CDSCO, and TGA pathways to defend against emerging domestic champions with established certification workflows. Deepen vertical integration into semiconductor procurement through long-term offtake agreements with Taiwanese foundries to offset silicon concentration risk. For New Entrants and Emerging Players: The price-point gap between premium insurer-backed platforms and economy browser-based portals opens white space in Vietnam's northern rural districts and Indonesia's outer island provinces. Target asynchronous store-and-forward diagnostic services with lightweight mobile-first deployment to bypass legacy hospital information system integration barriers. For Investors and Strategic Acquirers: The window for entry favors mid-cap platforms with established single-country regulatory moats and proven hospital system partnerships. Monitor NMPA algorithm transparency enforcement as the signal indicating when domestic Chinese platforms will consolidate foreign market share.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Algorithm Transparency Compliance | Elevates barriers for foreign AI-enabled diagnostic platforms entering Chinese tier-2 cities. |
| CDSCO Software-as-Medical-Device Certification | Unlocks hospital procurement eligibility for remote monitoring platforms across Maharashtra and Karnataka. |
| 5G Network Infrastructure Partnership | Enables real-time video consultation deployment where physician density lags metropolitan benchmarks. |
| Insurer Ecosystem Integration | Captures chronic disease management revenue pools through captive patient routing and reimbursement control. |
| Semiconductor Supply Agreement | Secures sensor hardware allocation for remote patient monitoring device manufacturing under India's PLI scheme. |
Methodological Framework
Independent corroboration across hospital procurement databases, GPO contracts, and CMS Medicare data underwrites the qualitative findings in this study. Primary interviews with clinicians, hospital purchasing committees, biomedical engineers, and GPO contracts managers combined with secondary validation from NMPA filings, CDSCO submissions, TGA approval pathways, and hyperscaler capex disclosures. Bottom-up platform deployment estimates and top-down health system budget allocations were triangulated to cross-check segment sizing.
Rate-of-change decomposition across technology modality, delivery model, end-user vertical, and geographic adoption pattern structured the analytical framework. CAGRs were derived from modeled annual platform deployment trajectories and per-encounter revenue capture across the projection horizon. Forecast inputs incorporated 5G rollout timelines in Chinese tier-2 cities and PLI scheme infrastructure acceleration in India.
Inputs from hospital procurement databases and GPO contracts were available through the study window; gaps in real-time reimbursement rate adjustments introduce uncertainty bands around revenue projections. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telemedicine
Telemedicine Workstations Market
Telemedicine
Global Telehealth Market
Telemedicine
Telemedicine EMR Software Market
Telemedicine
North America Telemedicine Market
Telemedicine
GCC Telemedicine Market
Telemedicine
5G Telemedicine Platform Market
Telemedicine
Real-Time E-Healthcare System Market
Telemedicine
Stroke Telemedicine Services Market
Telemedicine
AI in Telemedicine Market
Telemedicine
Telemedicine Cart Market
Telemedicine
Next Generation Telehealth Market
Telemedicine
Online Doctor Consultation Market
Telemedicine
Telehealth Software Market
Telemedicine
Tele-Epilepsy Market
Telemedicine
Remote Healthcare Market
Telemedicine
Tele-Care Market