
 Acute Viral Rhinosinusitis Treatment Market | 2026-2036
Acute Viral Rhinosinusitis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Acute Viral Rhinosinusitis Treatment Market Analysis
India's active pharmaceutical ingredient manufacturing corridor is reconfiguring cost structures for generic decongestant and antihistamine supply. Pfizer Inc. leverages its respiratory franchise infrastructure to sustain formulation leadership across North American and European channels. GlaxoSmithKline plc anchors consumer health distribution through pharmacy-centric networks that dominate over-the-counter rhinosinusitis segments. Bayer AG differentiates via topical delivery platforms that occupy a distinct position between prescription and self-care boundaries.
Acute viral rhinosinusitis treatment encompasses pharmacological and non-pharmacological interventions targeting symptomatic relief of viral-induced nasal and paranasal sinus inflammation, typically involving intranasal corticosteroids formulated at microgram-per-spray precision, antihistamines with H1-receptor selectivity, and isotonic saline irrigation systems designed to restore mucociliary clearance. Intranasal corticosteroids command the deepest margin pools due to prescription-tier pricing and chronic-recurrence dispensing patterns, while nasal saline irrigation competes on volume through pharmacy and homecare channels that bypass clinical gatekeeping. The inhalation delivery mode remains the fastest-growing structural segment as device manufacturers improve lung-nose deposition efficiency and patient compliance metrics.
The FDA's OTC monograph reform and EMA's centralized assessment of combination cold therapies create divergent approval economics that shape multinational launch sequencing. India's CDSCO and the WHO prequalification programme collectively determine which generic manufacturers gain tender access across emerging procurement systems. Stakeholders must monitor how regulatory divergence between FDA OTC pathways and EMA prescription maintenance requirements reallocates investment toward either consumer-health autonomy or clinician-mediated therapy models.
Market Dynamics
OTC switch pathways for intranasal corticosteroids are fragmenting prescription gatekeeping, forcing incumbents to defend margin pools through formulation differentiation while generic manufacturers exploit abbreviated approval routes.
Growth Catalysts
- Hospital outpatient volume expansion:United States ambulatory surgical centers are deepening formulary coverage for symptomatic viral upper respiratory therapies, creating pull-through demand for combination antihistamine-decongestant portfolios.
- EMA centralized assessment harmonization:The European Medicines Agency's streamlined combination cold therapy reviews are compressing multi-national launch timelines from sequential to parallel market entries.
- Microgram-precision spray technology:Device manufacturers achieving sub-50-micron droplet deposition consistency are unlocking pediatric and geriatric segments previously blocked by compliance failures.
Market Restraints
- API supply concentration:Pseudoephedrine and phenylephrine precursor manufacturing clusters in Gujarat and Hyderabad create single-point vulnerability for generic decongestant supply chains.
- FDA OTC monograph reform friction:The agency's ongoing reclassification of GRASE ingredients is forcing reformulation investments without guaranteed grandfathering of existing SKUs.
- Saline irrigation commoditization:Unbranded isotonic solution manufacturers are compressing pharmacy channel margins to single-digit percentages, eroding R&D recovery capacity.
Strategic Opportunities
- Underpenetrated Japanese self-care:METI's 2023 regulatory clarification on intranasal corticosteroid OTC eligibility is opening pharmacy-front shelf space previously reserved for prescription tiers.
- Digital therapeutics convergence:Smartphone-connected irrigation devices with compliance tracking are creating subscription revenue streams adjacent to consumable saline sales.
- PLI scheme API backward integration:India's production-linked incentive program for bulk drugs is enabling domestic manufacturers to bypass Chinese intermediate dependence for antihistamine actives.
Industry Challenges
- Spray device bioequivalence validation:Demonstrating therapeutic equivalence for generic intranasal corticosteroids requires expensive clinical endpoint studies that smaller manufacturers cannot fund.
- Multinational labeling harmonization:Divergent pediatric age cutoffs between FDA, EMA, and PMDA submissions are forcing territory-specific packaging runs that fragment production economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acute Viral Rhinosinusitis Treatment Market |
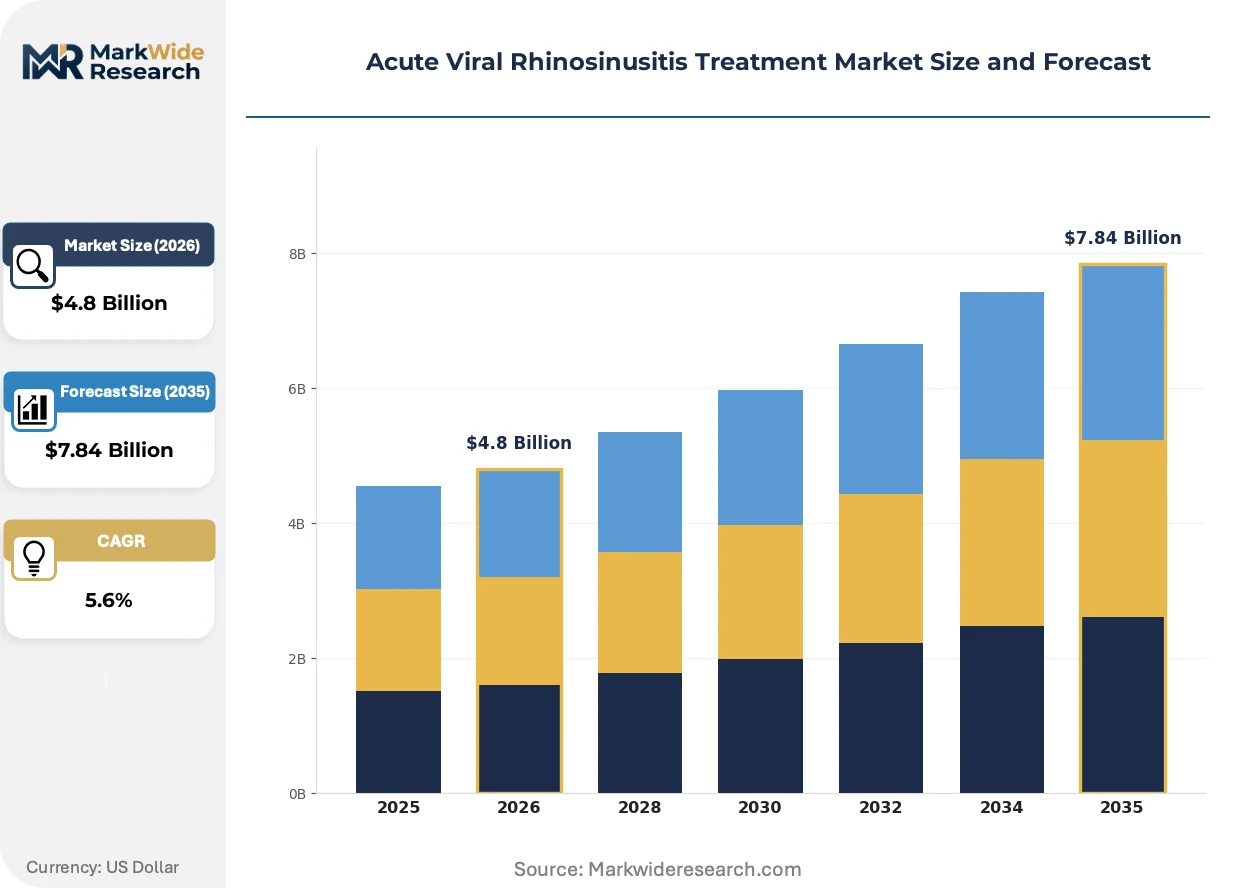
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intranasal Corticosteroids, Antihistamines, Decongestants, Nasal Saline Irrigation Delivery Mode: Topical, Oral, Injectable, Inhalation End User: Hospitals, Clinics, Homecare, Pharmacies Treatment Duration: Acute, Short-term, Long-term, Follow-up |
| Companies Covered | Pfizer Inc., GlaxoSmithKline plc, Bayer AG, AstraZeneca plc, Novartis AG, Merck & Co., Inc., Abbott Laboratories, Johnson & Johnson, Sanofi S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acute Viral Rhinosinusitis Treatment Market Emerging Trajectories
Device-drug convergence is collapsing the traditional separation between formulation and delivery mechanics, with deposition efficiency becoming the primary competitive variable rather than active ingredient concentration alone.
Soft-mist inhaler technology adapted from asthma therapy is collapsing the efficacy gap between pressurized metered-dose devices and pump sprays for intranasal corticosteroid delivery. German and Japanese respiratory device specialists are licensing these platforms to pharmaceutical partners seeking pediatric compliance advantages. The structural consequence is collapsing R&D timelines for next-generation nasal sprays as deposition physics replaces chemistry as the innovation frontier.
REACH authorization requirements for preservative excipients are forcing reformulation of multi-dose nasal sprays across European markets. ECHA's 2024 updated safety assessments for benzalkonium chloride are disqualifying several legacy preservatives from continued use. Manufacturers are responding with single-use vial formats or novel antimicrobial peptides that bypass the regulatory scrutiny entirely.
Direct-to-consumer pharmacy subscription models are compressing repurchase cycles for chronic rhinosinusitis sufferers from episodic to automated replenishment. United States telehealth platforms are integrating nasal spray prescriptions into bundled upper respiratory consults that bypass traditional primary care gatekeeping. This channel shift is most visible in metropolitan markets where same-day delivery logistics have achieved pharmacy-network density.
Acute Viral Rhinosinusitis Treatment Market Segmentation
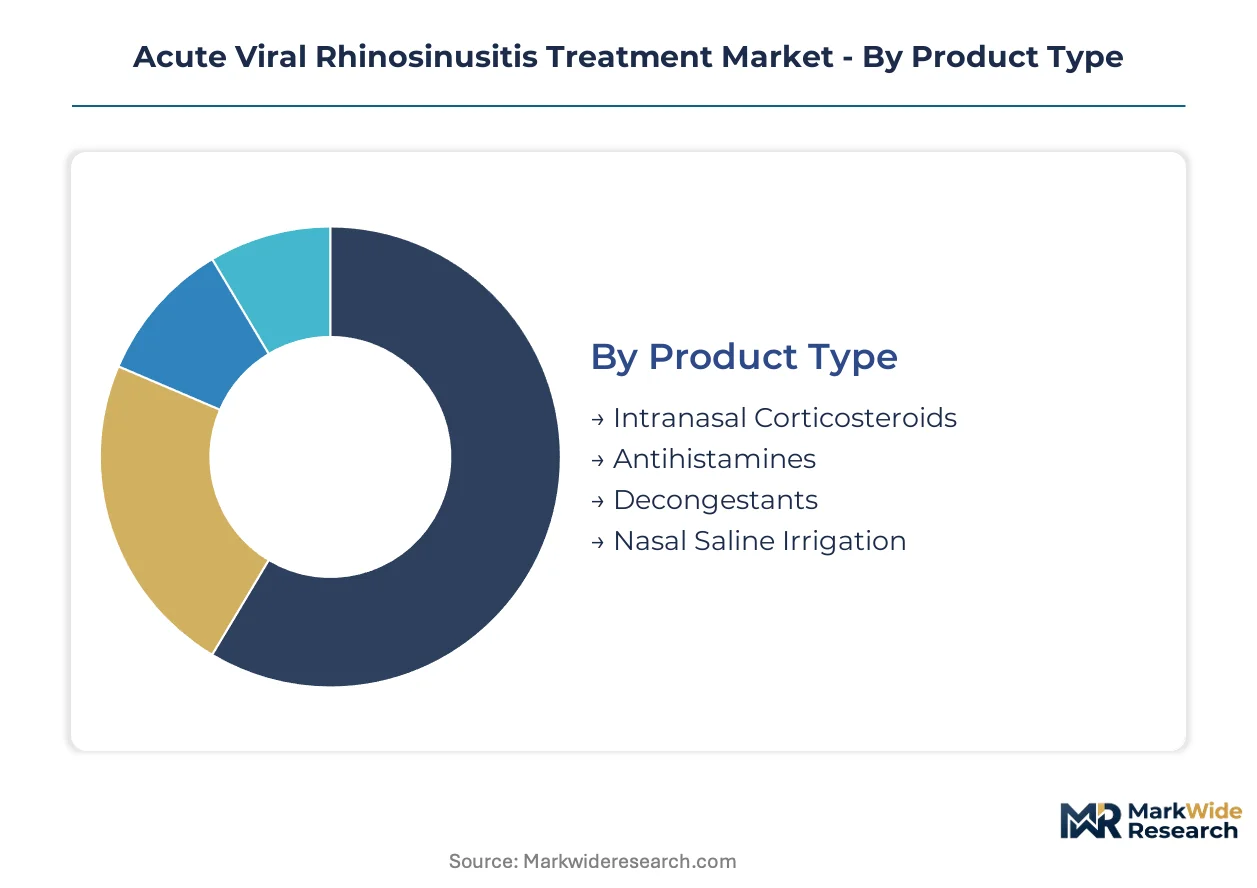
Segmentation in acute viral rhinosinusitis treatment reveals how formulation precision, delivery mechanics, and care setting economics allocate margin pools across the value chain. Device-drug convergence and OTC switch dynamics create divergent investment returns depending on which segment boundaries manufacturers choose to defend.
Product Type:
After-sales service intensity varies sharply across product categories, with device-dependent segments requiring technical support infrastructure that pure chemical formulations bypass entirely.
- Intranasal Corticosteroids:Microgram-per-spray precision formulations command prescription-tier pricing through chronic-recurrence dispensing patterns. Demand concentrates in United States hospital outpatient departments deepening formulary coverage for symptomatic viral upper respiratory therapies, though EMA centralized assessment timelines compress multinational launch sequencing for combination portfolios.
- Antihistamines:H1-receptor selective compounds compete through pharmacy-centric distribution networks with established consumer health penetration. Japanese self-care channels are expanding following METI regulatory clarification on intranasal corticosteroid OTC eligibility, opening pharmacy-front shelf space previously reserved for prescription tiers.
- Decongestants:Pseudoephedrine and phenylephrine formulations face API supply concentration risks in Gujarat and Hyderabad manufacturing clusters.
- Nasal Saline Irrigation:Isotonic solution systems compete on volume through pharmacy and homecare channels that bypass clinical gatekeeping, with unbranded manufacturers compressing margins to single-digit percentages.
By volume, nasal saline irrigation leads. By growth pace, intranasal corticosteroids are expanding most quickly.
Delivery Mode:
Cost tier differentiation separates premium deposition-optimized devices from commodity delivery formats, with reimbursement pathways determining which tier captures patient switching economics.
- Topical:Direct nasal mucosa application through sprays and drops dominates symptomatic relief with immediate local action. German and Japanese respiratory device specialists are licensing soft-mist inhaler platforms to pharmaceutical partners seeking pediatric compliance advantages.
- Oral:Systemic absorption routes serve patients with concurrent symptoms beyond nasal passages, though first-pass metabolism reduces local efficacy.
- Injectable:Parenteral administration reserves for severe complications or hospitalized cases requiring rapid systemic intervention.
- Inhalation:Lung-nose deposition efficiency improvements are accelerating device manufacturer R&D timelines as deposition physics replaces chemistry as the innovation frontier.
By patient reach, topical formulations dominate. By technology investment intensity, inhalation delivery is climbing the fastest.
End User:
Customer type determines whether procurement flows through centralized tender systems or fragmented retail transactions, reshaping margin recovery timelines and working capital requirements.
- Hospitals:Inpatient and outpatient formulary committees gate access through centralized procurement with volume-based contracting. United States ambulatory surgical centers are deepening coverage for combination antihistamine-decongestant portfolios, creating pull-through demand.
- Clinics:Physician office dispensing maintains prescription control with limited inventory carrying compared to hospital systems.
- Homecare:Direct patient management bypasses clinical gatekeeping through telehealth-integrated subscription models compressing repurchase cycles from episodic to automated replenishment.
- Pharmacies:Front-of-store and behind-counter placement splits between OTC autonomy and pharmacist-mediated recommendation.
By transaction volume, pharmacies lead. By value per episode, hospitals are gaining share fastest.
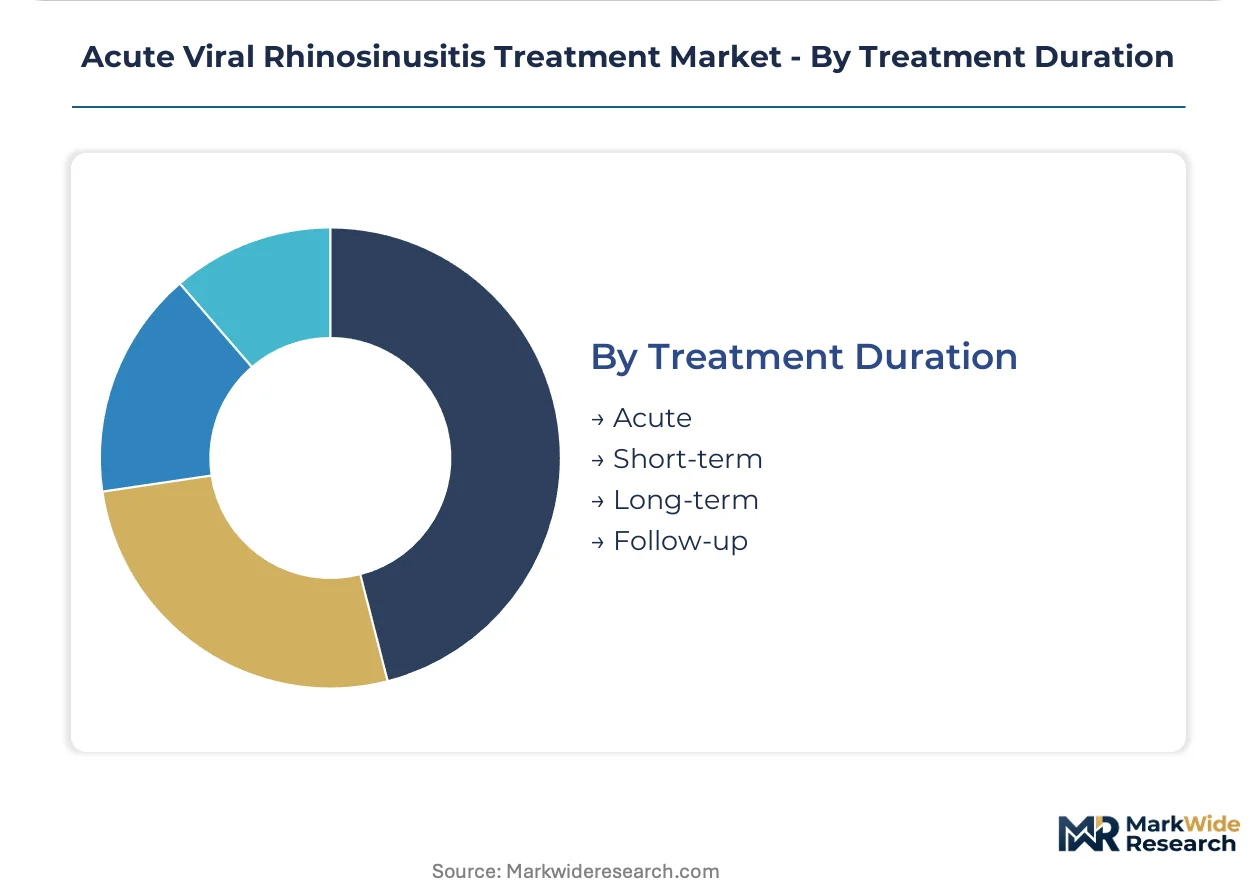
Treatment Duration:
Supply concentration for acute versus chronic indications determines whether manufacturers optimize for single-SKU scale or portfolio breadth across recurrence patterns.
- Acute:Single-course therapy for initial viral episodes emphasizes rapid symptom resolution with limited follow-up. FDA OTC monograph reform is forcing reformulation investments without guaranteed grandfathering of existing SKUs.
- Short-term:Limited-duration regimens bridge acute presentation and sustained resolution, often involving tapering dose protocols.
- Long-term:Chronic or recurrent rhinosinusitis maintenance requires sustained adherence monitoring with deposition efficiency becoming the primary competitive variable rather than active ingredient concentration alone.
- Follow-up:Post-acute surveillance and prevention-focused interventions target recurrence reduction through mucociliary clearance restoration.
By prescription frequency, acute treatments lead. By lifetime value per patient, long-term regimens show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold chain infrastructure underwrites Europe's distribution dominance for temperature-sensitive intranasal formulations, while Mumbai's JNPT container terminal anchors Indian API export flows to North American and European formulation sites.
United States
Hospital outpatient departments at Cleveland Clinic and Mayo Clinic systems are deepening formulary coverage for combination antihistamine-decongestant portfolios. FDA OTC monograph reform is forcing reformulation investments for legacy intranasal corticosteroid SKUs without guaranteed grandfathering. New Jersey's pharmaceutical corridor houses device manufacturers achieving sub-50-micron droplet deposition consistency for pediatric segments.
Germany
Ambulatory surgical centers in Bavaria and North Rhine-Westphalia are expanding procurement volumes for symptomatic viral upper respiratory therapies. EMA centralized assessment harmonization is compressing multi-national launch timelines from sequential to parallel market entries. Heidelberg and Munich respiratory device specialists are licensing soft-mist inhaler platforms to pharmaceutical partners seeking compliance advantages.
Japan
Pharmacy-front shelf space in Tokyo and Osaka is expanding following METI's 2023 regulatory clarification on intranasal corticosteroid OTC eligibility. PMDA pediatric age cutoff requirements are forcing territory-specific packaging runs that fragment production economics. Kansai region device manufacturers are improving lung-nose deposition efficiency metrics for next-generation nasal spray platforms.
India
CDSCO regulatory pathways are determining which generic manufacturers gain tender access across emerging procurement systems. The PLI scheme for bulk drugs is enabling domestic manufacturers to bypass Chinese intermediate dependence for antihistamine actives. Gujarat and Hyderabad manufacturing clusters concentrate pseudoephedrine and phenylephrine precursor production, creating single-point vulnerability for generic decongestant supply chains.
Acute Viral Rhinosinusitis Treatment Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in deposition physics and preservative excipient niches. The vendor base stratifies between multinational consumer health portfolios with pharmacy-centric distribution and generic manufacturers exploiting abbreviated FDA approval routes. Three archetypes dominate: formulation leaders with respiratory franchise infrastructure, device-drug convergence specialists licensing delivery platforms, and API backward integrators leveraging India's PLI scheme. Competitive moves concentrate on M&A for spray device bioequivalence capabilities and strategic partnerships for pediatric compliance technology.
Within the multinational platform tier, Pfizer Inc. and GlaxoSmithKline plc occupy positions anchored by respiratory franchise infrastructure and consumer health distribution networks respectively. Bayer AG exemplifies the device-drug convergence specialist archetype through topical delivery platform differentiation. These three entities represent the dominant competitive anchors spanning prescription-tier pricing and OTC autonomy boundaries.
| Leading Market Players |
|---|
| Pfizer Inc. |
| GlaxoSmithKline plc |
| Bayer AG |
| AstraZeneca plc |
| Novartis AG |
| Merck & Co., Inc. |
| Abbott Laboratories |
| Johnson & Johnson |
| Sanofi S.A. |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Gujarat's pseudoephedrine precursor corridor is compressing API contract rates and forcing decongestant manufacturers toward volume-based pricing postures that sacrifice margin recovery for shelf-position security.
Pricing Analysis
FDA OTC monograph reform dictates the pricing tier structure across intranasal corticosteroid portfolios, separating grandfathered prescription-tier SKUs from reformulated consumer-health entrants facing abbreviated approval economics. Three-tier pricing structure across premium microgram-precision sprays, standard pump-dose formats, and economy saline irrigation systems reflects deposition technology differentiation and clinical gatekeeping intensity. Pricing pressure stems from unbranded saline manufacturers compressing pharmacy channel margins to single-digit percentages. Hospital outpatient procurement committees demonstrate lowest price sensitivity due to formulary-driven volume contracting, while pharmacy front-store consumers exhibit highest elasticity to promotional discounting.
Supply Chain Analysis
Contract manufacturing concentration rests with respiratory device specialists in Heidelberg, Munich, and the Kansai region holding soft-mist inhaler platform capacity for pharmaceutical licensing partnerships. API production draws from Gujarat and Hyderabad clusters for decongestant precursors, with domestic Indian manufacturers leveraging PLI scheme incentives to bypass Chinese intermediate dependence for antihistamine actives. Single-source vulnerability concentrates in benzalkonium chloride preservative supply following ECHA's REACH authorization restrictions. Distribution runs through Rotterdam's pharmaceutical cold chain infrastructure for temperature-sensitive intranasal formulations, with Mumbai's JNPT terminal anchoring generic API export flows to North American formulation sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Device-drug convergence is fragmenting competitive boundaries between formulation chemistry and deposition physics, creating specialized niches for platform licensors and pediatric compliance technology developers.
For Market Incumbents: Entrench respiratory franchise infrastructure through exclusive soft-mist inhaler licensing agreements with German and Japanese device specialists, while accelerating backward integration into antihistamine API production under India's PLI scheme to offset Chinese intermediate exposure. Defend prescription-tier margin pools by differentiating microgram-per-spray precision formulations ahead of generic bioequivalence validation requirements. For New Entrants and Emerging Players: Japanese pharmacy-front shelf space offers the most penetrable white-space target following METI's regulatory clarification on intranasal corticosteroid OTC eligibility, with METI's framework enabling direct-to-consumer positioning previously blocked by prescription gatekeeping. Target smartphone-connected irrigation device segments with subscription revenue models adjacent to consumable saline sales, leveraging telehealth platform integration to bypass traditional primary care channels. For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because device-drug convergence specialists with proven pediatric deposition technology command scarcity premia as multinational incumbents seek compliance advantages. Target acquisition archetypes include respiratory device manufacturers with sub-50-micron droplet validation capabilities and Indian API backward integrators with CDSCO tender access. Monitor FDA OTC monograph reform implementation velocity as the critical inflection signal for prescription-to-consumer-health margin reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| Soft-Mist Inhaler Licensing | Heidelberg and Munich specialists unlock pediatric compliance advantages for pharmaceutical partners seeking deposition efficiency leadership. |
| API Backward Integration | India's PLI scheme enables domestic manufacturers to bypass Chinese intermediate dependence for antihistamine active production. |
| Digital Therapeutics Convergence | Smartphone-connected irrigation devices with compliance tracking create subscription revenue streams adjacent to consumable saline sales. |
| Preservative Excipient Reformulation | ECHA's REACH authorization requirements force multi-dose nasal spray redesigns using novel antimicrobial peptides or single-use vial formats. |
| Telehealth Platform Integration | United States telehealth platforms bundle nasal spray prescriptions into upper respiratory consults bypassing traditional primary care gatekeeping. |
Methodological Framework
Cross-validation between regulatory filing analysis and channel inventory data anchors the qualitative findings across the acute viral rhinosinusitis treatment landscape. Primary interviews with formulary directors at United States hospital outpatient systems, regulatory affairs leads at intranasal corticosteroid manufacturers, pharmacy procurement managers at German and Japanese retail chains, and biomedical engineers at respiratory device specialists were synthesized with secondary validation from FDA OTC monograph dockets, EMA centralized assessment documentation, CDSCO tender databases, and WHO prequalification records. Bottom-up demand modeling and top-down regulatory pathway analysis were triangulated to reconcile volume estimates with approval timeline constraints.
Calibration against historical switch patterns from prescription to OTC status informs the projection framework across the analysis window. Segmentation dimensions modeled include product type precision tiers, delivery mode deposition efficiency categories, end-user procurement channel structures, and regional regulatory cluster divergence. CAGRs were derived from elasticity-adjusted volume trajectories incorporating hospital outpatient expansion rates, pharmacy subscription model penetration, and device technology replacement cycles. Industry-specific forecast inputs include METI regulatory implementation velocity and ECHA preservative authorization timelines.
Practitioners should monitor FDA GRASE ingredient reclassification decisions and EMA combination therapy assessment harmonization progress for early signals of margin pool reallocation between prescription and consumer-health tiers. Forecasts reflect assumptions regarding OTC switch pathway continuity, API supply cluster stability, and deposition technology adoption curves. Quarterly review of CDSCO tender award patterns and telehealth platform integration metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
Chronic Hepatitis B (CHB) Market
Infectious Disease
Brucellosis Market
Infectious Disease
Japanese Encephalitis Market
Infectious Disease
Measles Market
Infectious Disease
Global Veterinary Infectious Disease Diagnostics Market
Infectious Disease
Actinomycosis Market
Infectious Disease
Veterinary Infectious Disease Therapeutics Market
Infectious Disease
Efavirenz Market
Infectious Disease
IVD Infectious Disease Market
Infectious Disease
Viral Hemorrhagic Fever Market
Infectious Disease
Mycobacterium Infections Treatment Market
Infectious Disease
Ceftriaxone Injection Market
Infectious Disease
Typhoid Fever Vaccine Market
Infectious Disease
Global Infectious Disease Therapeutics Market
Infectious Disease
Infectious Disease Molecular Diagnostics Market
Infectious Disease
Communicable Diseases Treatment Market