
 Global Sinusitis Treatment Market | 2026-2036
Global Sinusitis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sinusitis Treatment Market Foresight
Modular treatment kits that pair corticosteroid sprays with irrigation devices is broadening patient choice in chronic sinusitis management. Pfizer Inc. leverages its manufacturing scale to supply broad-spectrum antibiotics across hospital networks. Sanofi anchors its position through antihistamine portfolios that serve allergic rhinosinusitis populations. OptiNose US, Inc. differentiates via specialized nasal delivery mechanisms that target drug deposition in the ostiomeatal complex.
Sinusitis treatment encompasses pharmacological and procedural interventions designed to reduce mucosal inflammation, restore sinus ventilation, and eradicate infectious pathogens from the paranasal sinuses. Standard formulations include fluticasone propionate at 50 mcg per spray, amoxicillin-clavulanate at 875/125 mg oral tablets, and hypertonic saline solutions at 3% concentration for irrigation. Nasal corticosteroids command substantial margin pools due to their chronic use profile and favorable reimbursement in outpatient settings. Antibiotics face structural pressure from antimicrobial stewardship programs, while saline nasal sprays occupy a commoditized tier with limited pricing power. The therapy area dimension reveals chronic sinusitis as the most resource-intensive segment, driving sustained investment in sustained-release formulations.
The FDA regulates nasal drug-device combinations under its combination product pathway, requiring human factors validation for spray pumps. The EMA's MDR framework imposes clinical evidence requirements on sinus balloon dilation systems marketed in Europe. Japan's PMDA evaluates intranasal corticosteroids through its Sakigake designation pathway for expedited review. Stakeholders must monitor how divergent evidentiary standards across these agencies reshape regional launch sequencing and portfolio prioritization.
Market Dynamics
Antimicrobial stewardship programs are compressing antibiotic utilization across ENT clinics and hospital networks, forcing manufacturers to recalibrate revenue models around chronic maintenance therapies rather than acute infection courses.
Growth Catalysts
- Japan's Sakigake Pathway:Expedited regulatory review for intranasal corticosteroids accelerates product launches in the world's second-largest ENT device market.
- Balloon Sinus Dilation:Office-based procedural adoption reduces hospital dependency and expands addressable patient pools in ambulatory settings.
- Germany's Ambulatory Surgical Infrastructure:Federal reimbursement reforms incentivize same-day sinus procedures, driving capital deployment into ENT clinic networks.
Market Restraints
- API Supply Concentration:Fluticasone propionate active pharmaceutical ingredient production clusters in Indian and Chinese contract manufacturers, creating single-source vulnerability.
- EMA MDR Compliance Burden:Sinus balloon dilation systems face elevated clinical evidence requirements that extend European commercialization timelines by 18-24 months.
- Saline Commoditization:Hypertonic irrigation solutions command minimal pricing power as pharmacy chains and direct-to-consumer channels erode brand premiums.
Strategic Opportunities
- Brazil's Underpenetrated Chronic Sinusitis Population:ANVISA's streamlined medical device pathway enables first-mover positioning in Latin America's largest healthcare market.
- Drug-Device Convergence:Corticosteroid-eluting stents paired with bioresorbable delivery platforms create premium positioning beyond standalone pharmaceutical or mechanical offerings.
- Telehealth-Enabled Refill Channels:Direct nasal spray subscription models bypass traditional pharmacy distribution and capture recurring revenue streams.
Industry Challenges
- Human Factors Engineering Talent Scarcity:FDA combination product pathway demands specialized expertise in spray pump ergonomics and patient-use validation studies.
- Legacy EHR Integration Friction:Sinusitis diagnostic algorithms and treatment outcome tracking systems require costly adaptation to hospital information architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sinusitis Treatment Market |
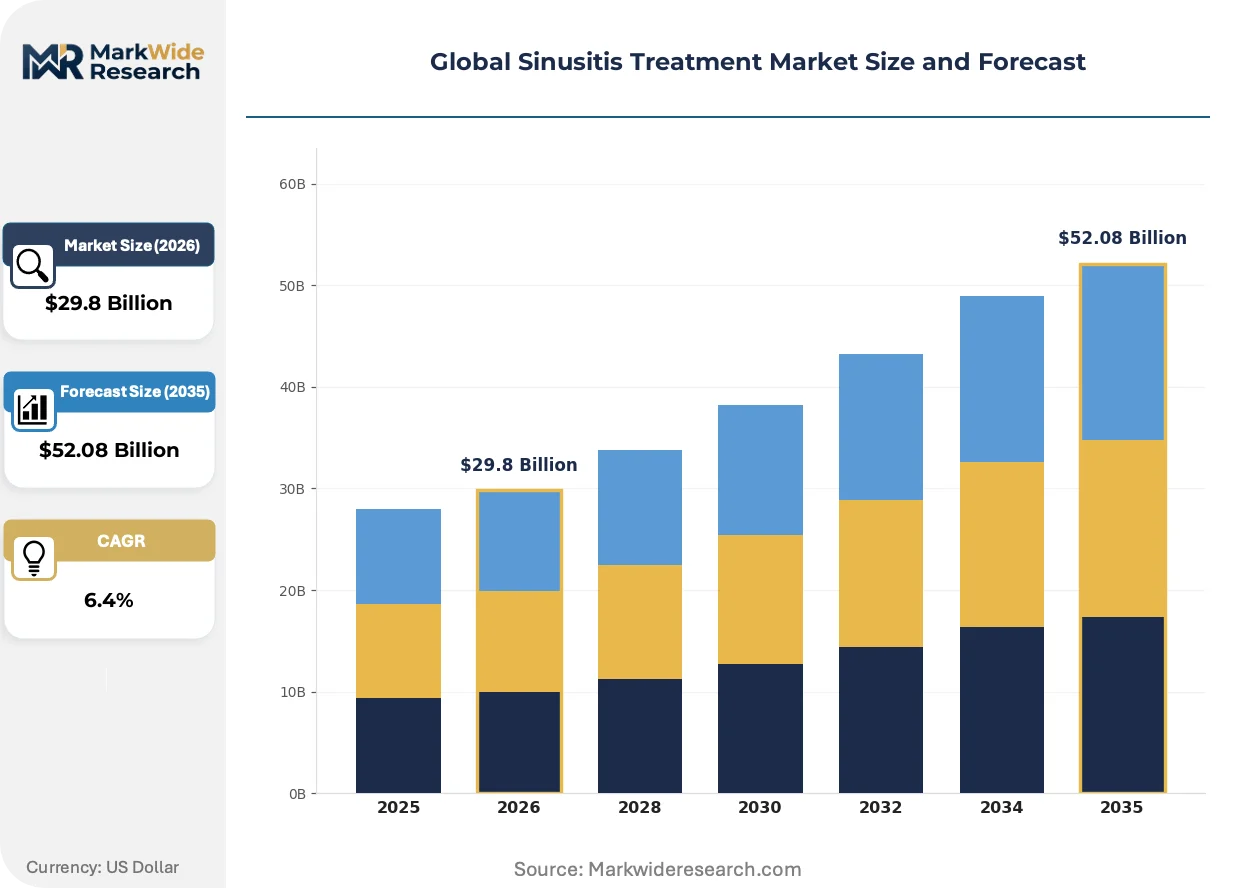
| Market Size in 2026 | $29.8 Billion |
| Market Size in 2035 | $52.08 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Decongestants, Nasal Corticosteroids, Antihistamines, Antibiotics, Saline Nasal Sprays Therapy Area: Acute Sinusitis, Chronic Sinusitis, Recurrent Sinusitis, Allergic Rhinosinusitis, Fungal Sinusitis End User: ENT Clinics, Diagnostic Centers, Specialty Hospitals, Pharmacies, Outpatient Care Centers Delivery Mode: Oral, Nasal Spray, Injection, Topical, Inhalation |
| Companies Covered | Medtronic plc, Stryker Corporation, Cipla Inc., Dr. Reddy’s Laboratories Ltd., Pfizer Inc., Sanofi, Bayer AG, GSK plc, OptiNose US, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sinusitis Treatment Market Shifts & Advancements
Digital health integration and precision delivery mechanisms are redefining therapeutic endpoints in sinusitis management, shifting competitive advantage from formulation chemistry to deposition physics and patient adherence monitoring.
Exhalation-powered nasal delivery technology is unifying drug administration with patient breathing mechanics to achieve targeted deposition in the ostiomeatal complex. ENT specialists in tertiary referral centers are adopting these systems for recalcitrant chronic sinusitis cases. This convergence of respiratory physiology with device engineering is compressing the efficacy gap between topical and systemic corticosteroid exposure.
REACH chemical registration requirements are compelling reformulation of propellant and preservative systems in European nasal spray products. Manufacturers face substitution mandates for chlorofluorocarbon alternatives that alter spray plume characteristics and patient sensory profiles. German and French regulators are enforcing post-market surveillance obligations that extend pharmacovigilance obligations beyond traditional adverse event reporting.
Hospital purchasing consortia are consolidating procurement authority for sinusitis therapeutics into centralized pharmacy committees. Independent ENT practices and ambulatory surgery centers are losing direct vendor relationships as integrated delivery networks capture formulary control. This concentration is most pronounced in the United States, where health system mergers have reduced the number of distinct contracting entities by over one-third since 2019.
Global Sinusitis Treatment Market Segmentation
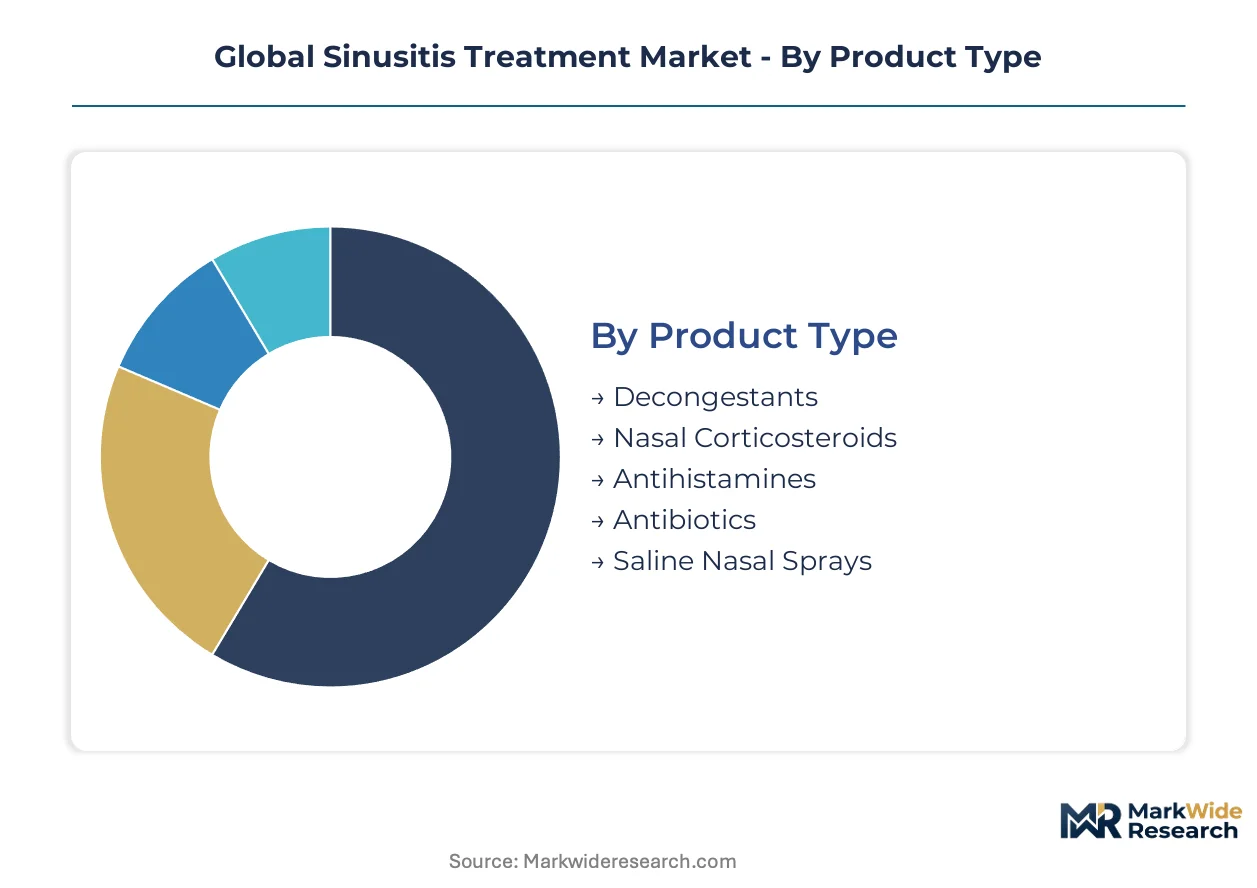
Sinusitis treatment segmentation reveals divergent margin profiles across pharmacological and procedural modalities. Chronic maintenance therapies generate recurring revenue streams distinct from acute intervention economics. Delivery mechanism sophistication increasingly determines reimbursement tier placement and patient adherence outcomes.
Product Type:
Buyers in this category differentiate primarily by treatment duration economics and reimbursement pathway access.
- Nasal Corticosteroids:Synthetic glucocorticoid formulations at 50-200 mcg per spray deliver sustained mucosal anti-inflammatory action. Demand concentrates in United States outpatient settings where Medicare Part B covers prescription intranasal therapies for chronic rhinosinusitis. Favorable prior authorization protocols reinforce physician prescribing preference over systemic alternatives.
- Antibiotics:Amoxicillin-clavulanate and respiratory fluoroquinolones target acute bacterial sinusitis with 7-14 day course durations. German hospital networks are compressing utilization through antimicrobial stewardship mandates, redirecting procurement budgets toward culture-guided narrow-spectrum alternatives.
- Decongestants:Sympathomimetic agents provide short-term nasal patency restoration.
- Antihistamines:H1-receptor antagonists address allergic rhinosinusitis overlap populations.
- Saline Nasal Sprays:Isotonic and hypertonic irrigation solutions occupy commoditized retail pharmacy tiers.
Volume sits with nasal corticosteroids; growth tilts toward saline-based maintenance regimens as stewardship programs restrict antibiotic expansion.
Therapy Area:
Therapy selection hinges on disease chronicity and surgical candidacy rather than acute symptom severity alone.
- Chronic Sinusitis:Persistent inflammation exceeding 12 weeks drives sustained-release formulation development and balloon dilation procedural volume. Japan's tertiary ENT centers are expanding functional endoscopic sinus surgery capacity for refractory cases, with PMDA Sakigake designation accelerating biologic adjunct therapies.
- Acute Sinusitis:Self-limiting viral or bacterial episodes dominate total case incidence but generate lower per-patient revenue. United Kingdom primary care networks are restricting antibiotic prescribing through NICE guideline implementation, compressing pharmaceutical capture in this segment.
- Recurrent Sinusitis:Multiple annual episodes prompt immunological workup and prophylactic intervention.
- Allergic Rhinosinusitis:IgE-mediated inflammation overlaps substantially with chronic presentations.
- Fungal Sinusitis:Invasive and non-invasive subtypes require distinct antifungal and surgical protocols.
Procedure volume clusters with chronic presentations; biologic-eligible refractory populations are expanding most quickly.
End User:
Site-of-care economics and capital equipment requirements fragment procurement authority across delivery settings.
- ENT Clinics:Office-based balloon sinus dilation and diagnostic endoscopy concentrate procedural revenue. Germany's federal reimbursement reforms incentivize same-day interventions, driving capital deployment into ambulatory ENT networks independent of hospital ownership.
- Specialty Hospitals:Tertiary centers manage complex revision surgeries and fungal sinusitis cases requiring extended intravenous therapy. United States integrated delivery networks are consolidating purchasing authority for biologics and drug-device combinations into centralized pharmacy committees.
- Diagnostic Centers:CT and nasal endoscopy services support referral pathway triage.
- Pharmacies:Retail and specialty channels dispense maintenance therapies with varying prior authorization burden.
- Outpatient Care Centers:Urgent care and community health settings handle acute presentation triage.
Revenue concentration favors ENT clinics; specialty hospitals retain complex case premium capture.
Delivery Mode:
Deposition physics and patient ergonomics determine efficacy variance and regulatory pathway complexity.
- Nasal Spray:Metered-dose pump systems achieve anterior nasal cavity distribution with particle sizing optimized for turbinate deposition. FDA combination product pathway demands human factors validation for spray plume characterization, extending development timelines for novel device architectures.
- Inhalation:Exhalation-powered delivery systems target ostiomeatal complex deposition through synchronized breathing mechanics. Japanese otolaryngology specialists are adopting these platforms for recalcitrant chronic sinusitis, narrowing topical-systemic efficacy gaps.
- Oral:Systemic bioavailability exposes patients to corticosteroid and antibiotic adverse effect profiles.
- Topical:Irrigation and nebulized solutions provide high-volume sinus lavage.
- Injection:Depot corticosteroid and biologic subcutaneous administration serve refractory populations.
Prescription volume dominates nasal spray; device-enabled inhalation platforms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of active pharmaceutical ingredients clusters in Indian and Chinese contract facilities while consumption concentrates in United States, German, and Japanese ambulatory care networks. This divergence shapes regulatory submission strategies and supply chain contingency planning across the forecast period.
United States
Medicare Part B reimbursement for intranasal corticosteroids drives outpatient prescribing volume in chronic rhinosinusitis management. The FDA's combination product pathway demands human factors validation for novel spray pump architectures, extending development timelines for device innovators. Integrated delivery networks in Texas and the Northeast Corridor are consolidating formulary authority, reducing direct vendor access for independent ENT practices.
Germany
Federal reimbursement reforms incentivize same-day sinus procedures, accelerating capital deployment into ambulatory ENT clinic networks. The EMA's MDR framework imposes elevated clinical evidence requirements on balloon dilation systems, extending commercialization timelines by 18-24 months. Bavaria and North Rhine-Westphalia host the densest concentrations of office-based procedural capacity.
Japan
PMDA's Sakigake designation pathway expedites review for intranasal corticosteroids, accelerating launch timelines in the world's second-largest ENT device market. METI reimbursement policies favor chronic maintenance therapies over acute antibiotic courses. Tertiary referral centers in Tokyo and Osaka are expanding functional endoscopic sinus surgery capacity for refractory populations.
India
Domestic API production for fluticasone propionate and amoxicillin-clavulanate supplies global generic formulation networks. CDSCO regulatory harmonization efforts are streamlining medical device registration pathways for nasal delivery systems. Contract manufacturing clusters in Maharashtra and Gujarat face REACH chemical registration pressures for European export compliance.
Brazil
ANVISA's streamlined medical device pathway enables first-mover positioning in Latin America's largest chronic sinusitis population. Private health insurance expansion in São Paulo and Rio de Janeiro is deepening ambulatory surgical infrastructure. Local distribution partnerships remain essential for navigating federal procurement complexity in public hospital networks.
Global Sinusitis Treatment Market Competitive Landscape
The competitive structure tilts toward diversified pharmaceutical conglomerates with manufacturing scale advantages. Nasal corticosteroid and antibiotic supply contracts concentrate procurement authority within hospital purchasing consortia. Three archetypes dominate: API-integrated generic manufacturers, device-enabled delivery specialists, and broad-spectrum respiratory portfolio holders. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms seek backward integration into active pharmaceutical ingredient supply.
Among diversified pharmaceutical conglomerates, Pfizer Inc. and Sanofi occupy positions reflecting manufacturing scale and chronic therapy portfolio breadth. OptiNose US, Inc. exemplifies the device-enabled delivery specialist archetype, representing convergence of respiratory physiology with targeted deposition engineering. These three anchors illustrate the strategic divergence between formulation chemistry and mechanical delivery innovation in competitive positioning.
| Leading Market Players |
|---|
| Medtronic plc |
| Stryker Corporation |
| Cipla Inc. |
| Dr. Reddy's Laboratories Ltd. |
| Pfizer Inc. |
| Sanofi |
| Bayer AG |
| GSK plc |
| OptiNose US, Inc. |
| Others |
Supply & Pricing Matrix
Hospital purchasing consortia in the United States and Germany concentrate procurement authority for sinusitis therapeutics, forcing manufacturers toward contract-based long-term offtake agreements with volume-tiered rebates that compress margins for non-integrated suppliers.
Pricing Analysis
Cost-down pressure on nasal corticosteroids accelerates because hospital formulary committees leverage consolidated purchasing scale against fragmented generic manufacturers. Three-tier pricing structure across premium device-enabled delivery, standard metered-dose sprays, and economy saline irrigation separates reimbursement tiers by clinical evidence depth. Price differentiation hinges on FDA combination product certification and ambulatory surgery center contract access. Antibiotic segments face the steepest price erosion as antimicrobial stewardship programs restrict utilization, while device-enabled inhalation platforms retain pricing power through deposition physics patents.
Supply Chain Analysis
Freight cost volatility from Indian and Chinese API manufacturing clusters to European and North American formulation facilities is reshaping inventory strategies toward regional buffer stocks. Fluticasone propionate and amoxicillin-clavulanate active pharmaceutical ingredients draw from contract manufacturers in Maharashtra and Gujarat, with spray pump mechanical components sourced from precision molding specialists in Germany and Japan. Single-source vulnerability in corticosteroid API supply creates exposure to REACH chemical registration disruptions. Distribution runs through health system central pharmacy committees rather than direct ENT clinic relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressures are intensifying as EMA MDR compliance burdens and FDA combination product validation requirements force sub-scale device manufacturers toward acquisition or exit.
For Market Incumbents: Lock in corticosteroid API supply through backward integration into Indian contract manufacturing or captive production of fluticasone propionate. Secure hospital system formulary placement through outcomes-based contracting that demonstrates reduced revision surgery rates against balloon dilation competitors. For New Entrants and Emerging Players: Enter via Brazil's ANVISA-streamlined device pathway to capture first-mover positioning in Latin America's underpenetrated chronic sinusitis population. Target office-based balloon dilation adoption in German ambulatory ENT networks where federal reimbursement reforms concentrate procedural demand. For Investors and Strategic Acquirers: The window for entry favors device-enabled delivery specialists with validated human factors engineering capabilities and PMDA Sakigake pathway progress. Monitor FDA guidance publication timing on nasal drug-device combination requirements as the inflection signal for portfolio revaluation.| Strategic Initiative | Industry Significance |
|---|---|
| API Manufacturing Scale-Up | Captive fluticasone propionate production insulates against Indian supply concentration risks. |
| MDR Clinical Evidence Investment | European balloon dilation commercialization accelerates with preemptive EMA submission data packages. |
| Hospital System Partnership | Integrated delivery network formulary access secures recurring corticosteroid revenue streams. |
| Exhalation-Powered Device Launch | PMDA Sakigake designation in Japan narrows topical-systemic efficacy gaps for refractory cases. |
| Telehealth Refill Channel Development | Direct nasal spray subscriptions bypass pharmacy distribution and capture patient adherence data. |
Research Methodology
Multi-period observation of FDA combination product approval timelines, EMA MDR certification progressions, and PMDA Sakigake designations anchored the trend analysis, supplemented by interviews with ENT clinic medical directors, hospital pharmacy committee chairs, nasal device engineering leads, and API procurement managers at generic manufacturers. Secondary validation drew from FDA 510(k) filings, EMA MDR technical documentation, ClinicalTrials.gov intervention records, and CMS Medicare Part B reimbursement data. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation cross-checked segment estimates.
Segment-weighting across therapy area chronicity, delivery mode sophistication, and end-user site-of-care economics structured the analytical framework. CAGRs were derived from procedure volume trajectories in ambulatory settings and maintenance therapy persistence rates. Modeled inputs included antimicrobial stewardship program penetration by hospital network, balloon dilation capital equipment deployment in German ENT clinics, and intranasal corticosteroid prior authorization burden by United States payer type.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden API supply disruptions or accelerated FDA guidance revisions on human factors validation. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
ENT
Nasal Sampling Lines Market
ENT
Interventional ENT Devices Market
ENT
Global Audiological Devices Market
ENT
Audiology Devices Market
ENT
Global Acute Otitis Media Treatment Market
ENT
US Hearing Aids Market
ENT
Global ENT Workstations Market
ENT
Hearing Loss Disease Treatment Market
ENT
Global Pediatric Hearing Aids Market
ENT
Surgical ENT Devices Market
ENT
Ear Health Market
ENT
ENT Disorder Treatment Market
ENT
Europe Hearing Aids Market
ENT
Head and Neck Squamous Cell Carcinoma Market
ENT
ENT Laser Devices Market
ENT
ENT Devices Market