
 Laryngeal Papillomatosis Treatment Market | 2026-2036
Laryngeal Papillomatosis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Laryngeal Papillomatosis Treatment Market Analytics
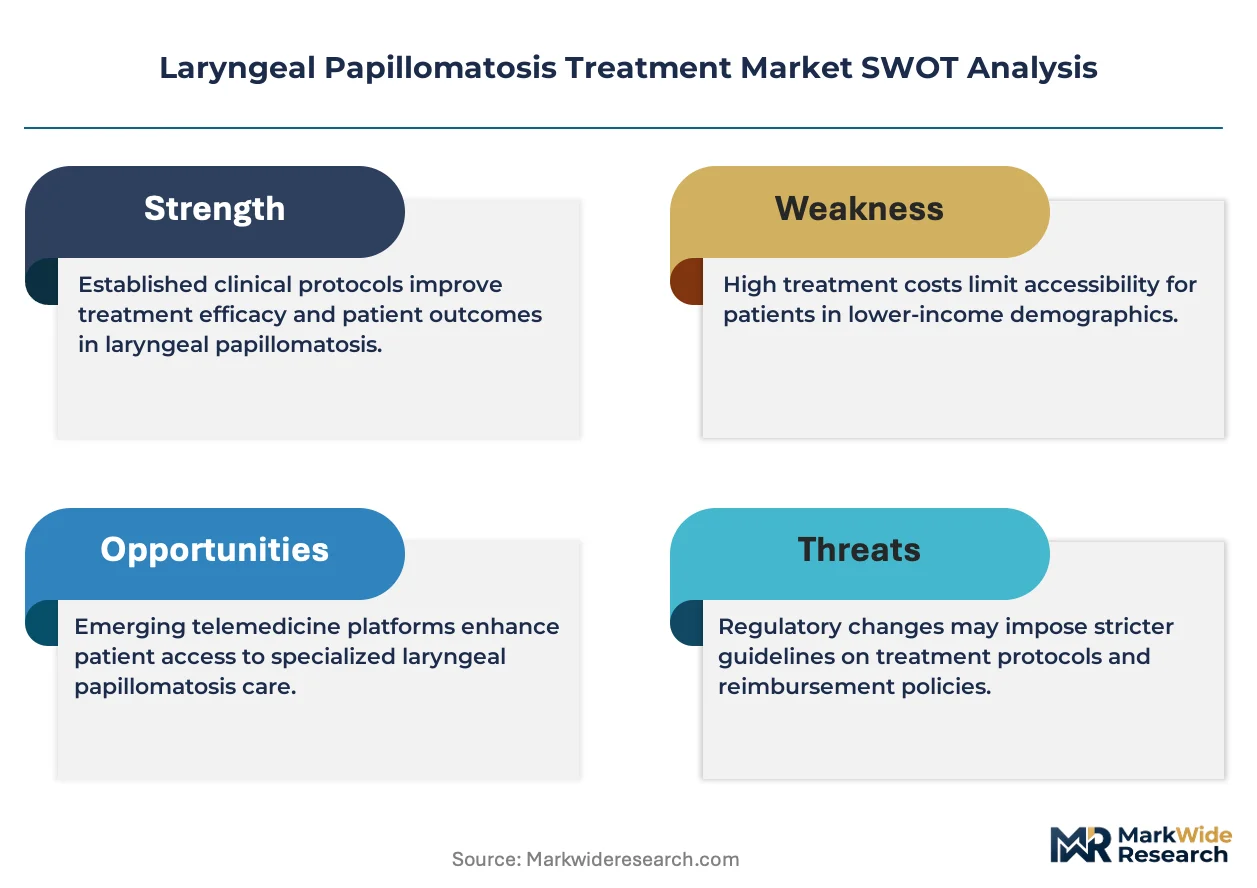
FDA orphan drug designation is realigning the cost-of-entry calculus for developers targeting recurrent respiratory papillomatosis. Inovio Pharmaceuticals leverages its DNA medicine platform to sustain clinical momentum in immunotherapy candidates. Merck & Co. anchors its position through established antiviral portfolios, while Bristol-Myers Squibb competes via oncology-derived immunotherapy expertise applied to benign proliferative conditions.
Laryngeal papillomatosis treatment encompasses surgical, pharmacological, and immunological interventions designed to debulk or eradicate human papillomavirus-driven benign epithelial tumors of the upper aerodigestive tract, with carbon dioxide laser systems operating at 10,600 nm wavelength serving as the historical gold standard for precise mucosal resection. The primary purpose is restoration of airway patency and voice preservation in patients experiencing recurrent disease burden. Laser surgery occupies the dominant procedural share due to decades of otolaryngology training infrastructure and instrument familiarity, while immunotherapy represents the fastest-expanding category as intralesional cidofovir and investigational therapeutic vaccines redirect treatment from repeated debulking toward durable viral suppression. Antiviral therapy maintains stable utilization in adjuvant settings where surgical access remains incomplete.
FDA oversight of biologics and orphan indications shapes trial design requirements and exclusivity incentives for developers, while the European Medicines Agency's pediatric investigation plans influence adolescent patient study commitments across transatlantic programs. Health Canada and the Therapeutic Goods Administration in Australia impose parallel manufacturing standards that determine multi-jurisdictional product registration feasibility. Stakeholders must monitor regulatory divergence between accelerated approval pathways and traditional efficacy benchmarks as immunotherapy candidates advance through clinical development.
Market Dynamics
Hospital procurement of advanced surgical systems is accelerating as ENT departments modernize intervention capabilities, while FDA orphan drug incentives are compressing therapeutic development timelines and redirecting R&D investment toward immunotherapy platforms.
Growth Catalysts
- FDA Orphan Drug Designation:The incentive framework reduces regulatory cost-of-entry for developers targeting recurrent respiratory papillomatosis, accelerating clinical trial initiation and exclusivity timelines.
- Carbon Dioxide Laser Systems:Otolaryngology training infrastructure and decades of instrument familiarity sustain procedural dominance in mucosal resection, reinforcing hospital capital expenditure cycles.
- United States:Specialized laryngeal surgery volumes concentrate demand for advanced debulking technologies and adjuvant antiviral protocols.
Market Restraints
- Input Cost Volatility:Precision laser optics and specialized surgical consumables expose procurement budgets to supply chain fluctuations in rare-earth mineral markets.
- Technical Limitation:Repeated debulking procedures fail to eradicate underlying HPV infection, trapping patients in cyclical intervention without durable viral suppression.
- EMA Pediatric Investigation Plans:Transatlantic study commitments for adolescent patient populations extend development timelines and inflate trial complexity for immunotherapy candidates.
Strategic Opportunities
- Therapeutic Vaccines:DNA medicine platforms redirect treatment paradigms from mechanical debulking toward durable immune-mediated viral clearance, opening adjuvant and monotherapy positioning.
- Intralesional Cidofovir:Off-label antiviral application in incomplete surgical access cases creates pharmacological white space between laser resection and systemic therapy.
- Health Canada Parallel Registration:Harmonized manufacturing standards with FDA and TGA enable multi-jurisdictional product launches without redundant facility certification.
Industry Challenges
- Microsurgical Skill Concentration:Laryngeal laser surgery demands specialized fellowship training that concentrates capable practitioners in tertiary academic medical centers.
- Biologics Manufacturing Scale-Up:Immunotherapy candidates require GMP-compliant viral vector or DNA plasmid production capacity that exceeds current contract manufacturing availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laryngeal Papillomatosis Treatment Market |
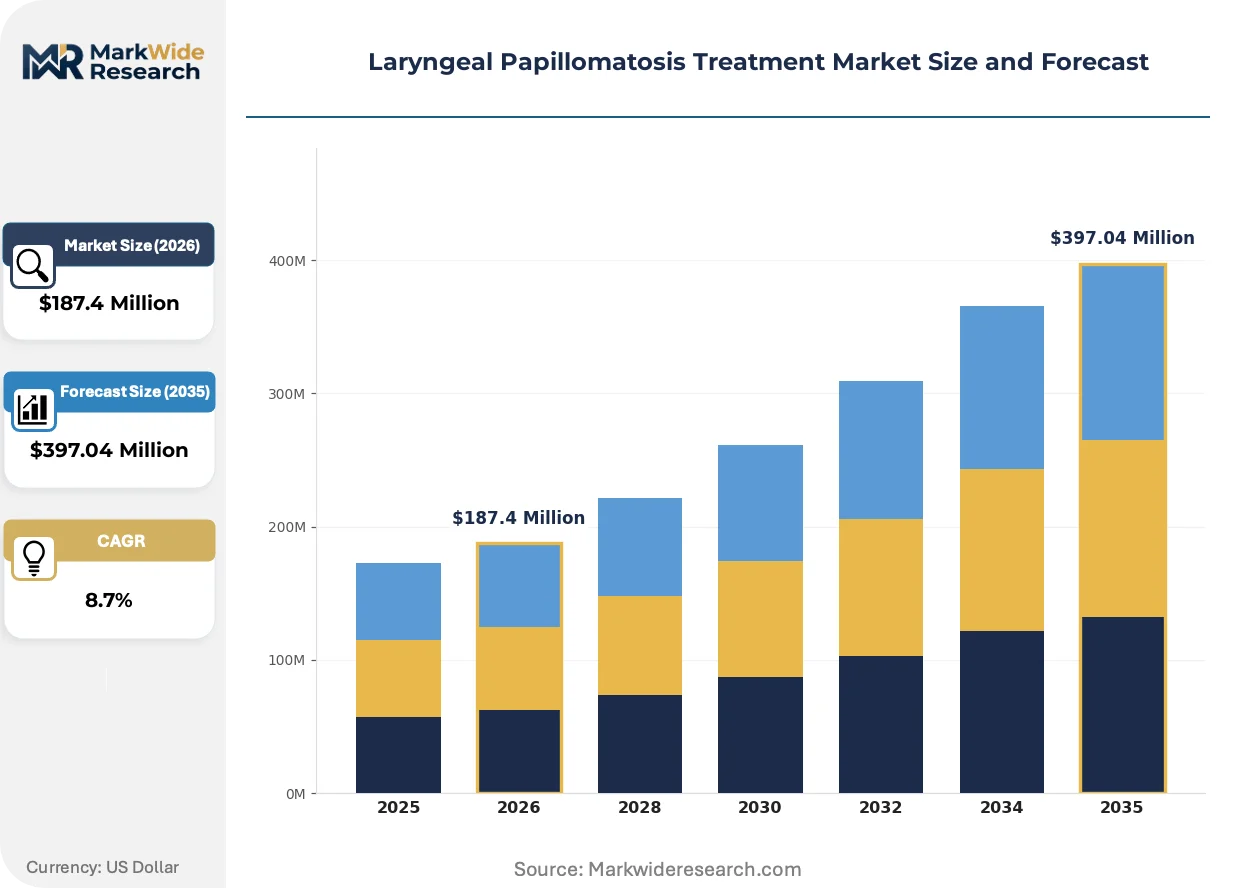
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Surgery, Cryotherapy, Antiviral Therapy, Immunotherapy End User: Hospitals, ENT Clinics, Ambulatory Surgical Centers, Rehabilitation Facilities Delivery Mode: Intralesional Injection, Oral Administration, Topical Application, Surgical Procedure Technology: Radiofrequency Ablation, Microdebrider, Photodynamic Therapy, Electrocautery |
| Companies Covered | Inovio Pharmaceuticals, Precigen Inc., Merck & Co., Inc., Bristol-Myers Squibb Company, F. Hoffmann-La Roche AG, Eli Lilly and Company, GlaxoSmithKline plc, Johnson & Johnson Services Inc., Hologic, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laryngeal Papillomatosis Treatment Market Evolving Landscape
Immunotherapy platforms are compressing the historical dominance of mechanical debulking, while regulatory acceleration pathways and procurement centralization reshape how treatments reach patients.
Pulsed dye laser technology at 585 nm wavelength is absorbing select mucosal resection cases from carbon dioxide systems by reducing thermal collateral damage in pediatric airways. Pediatric otolaryngology departments in academic medical centers are adopting this modality for recurrent disease in juvenile-onset patients. The technology is absorbing market share in precision-demanding applications where voice preservation outcomes drive referral patterns.
FDA breakthrough therapy designation for recurrent respiratory papillomatosis candidates compresses Phase II-to-approval timelines through rolling review and real-time data submission. The industrial consequence accelerates capital deployment into immunotherapy pipelines previously deprioritized for benign tumor indications. Developers with existing antiviral portfolios are responding by repurposing oncology-derived immunotherapy expertise toward this orphan indication.
Hospital procurement committees now bundle surgical system acquisitions with multi-year service contracts and training commitments, displacing standalone instrument purchases. Integrated delivery networks in the United States are consolidating vendor relationships to extract volume discounts on laser platforms and consumables. This concentration is most visible in metropolitan hospital systems where ENT department modernization budgets exceed rural facility capabilities by an order of magnitude.
Laryngeal Papillomatosis Treatment Market Segmentation
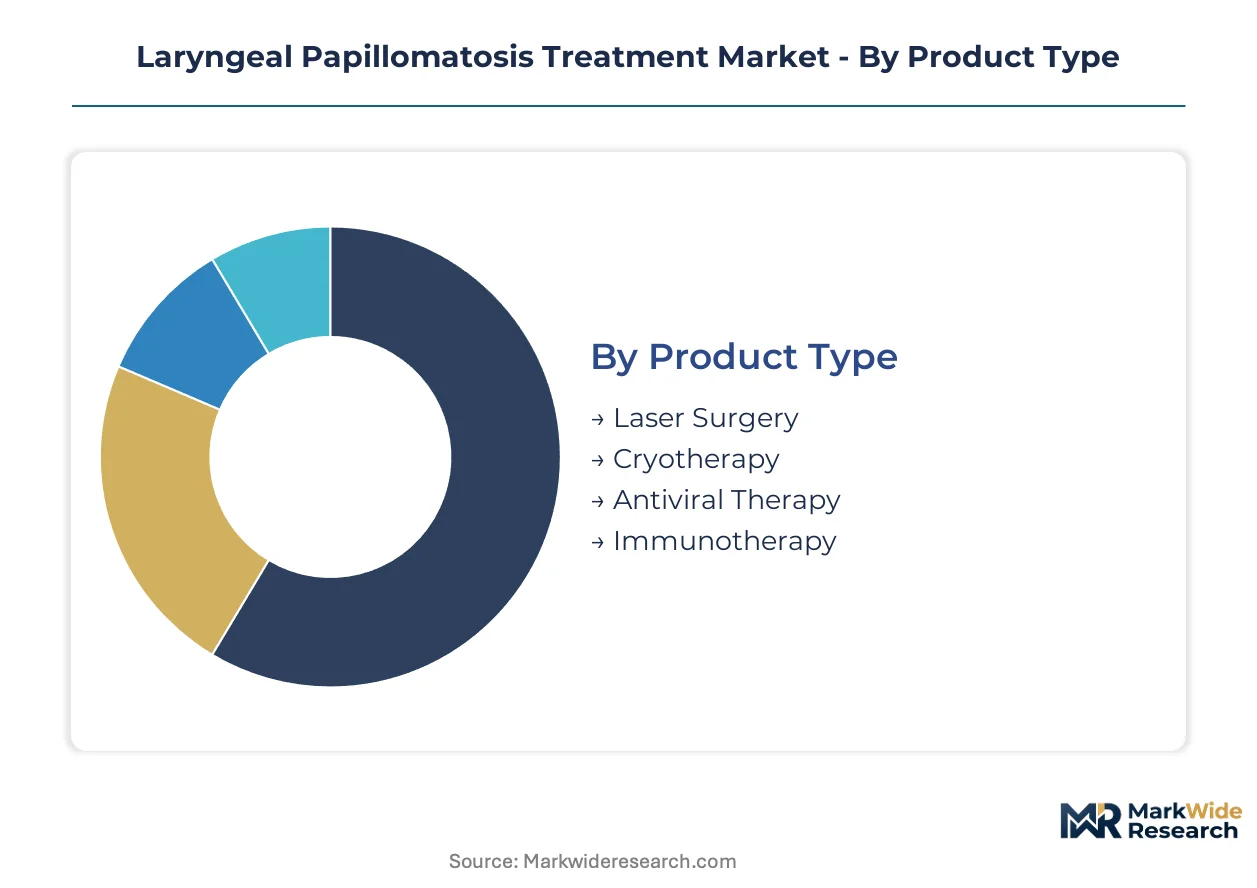
Treatment selection in laryngeal papillomatosis hinges on disease severity, patient age, and recurrence history. Segmentation reveals how surgical, pharmacological, and immunological modalities partition across care settings and administration routes.
Product Type:
Customization dominates at the severe-recurrence end, where combination protocols blend modalities; standardization prevails in first-line surgical management across high-volume centers.
- Laser Surgery:Carbon dioxide systems at 10,600 nm wavelength enable precise mucosal resection with minimal thermal spread. Demand clusters in United States tertiary academic centers where fellowship-trained otolaryngologists concentrate and voice preservation outcomes drive referral patterns.
- Immunotherapy:DNA medicine platforms and intralesional cidofovir redirect treatment from mechanical debulking toward durable viral suppression. Pediatric populations in specialized airway centers are expanding off-label adjuvant use as repeated surgery fails to eradicate underlying HPV infection.
- Cryotherapy:Nitrous oxide-based tissue destruction offers lower capital cost than laser systems for resource-constrained settings.
- Antiviral Therapy:Systemic and intralesional cidofovir protocols stabilize disease burden in incomplete surgical access cases.
Leading the category by volume: Laser Surgery. Growing fastest: Immunotherapy.
End User:
Capital intensity and reimbursement scale separate institutional tiers, with integrated delivery networks capturing procurement advantages unavailable to standalone facilities.
- Hospitals:Tertiary academic medical centers anchor complex recurrent case management through bundled surgical system acquisitions and multi-year service contracts. United States metropolitan hospital systems with ENT department modernization budgets exceeding rural capabilities by an order of magnitude concentrate advanced debulking technology deployment.
- ENT Clinics:Outpatient-based laryngoscopy suites handle stable disease surveillance and minor debulking procedures.
- Ambulatory Surgical Centers:CMS reimbursement shifts and payer preference for lower-cost settings are expanding same-day laser procedure volumes.
- Rehabilitation Facilities:Voice therapy integration supports post-surgical functional recovery.
Procurement scale favors: Hospitals. Fastest volume expansion: Ambulatory Surgical Centers.
Delivery Mode:
Route selection tracks anatomical access limitations and pharmacokinetic requirements, with invasive administration correlating to disease refractoriness.
- Surgical Procedure:Direct visualization under suspension laryngoscopy remains the historical standard for tumor debulking. United States otolaryngology training infrastructure sustains procedural dominance despite inability to eradicate underlying viral infection.
- Intralesional Injection:Cidofovir and investigational therapeutic vaccines target residual disease at surgical margins.
- Oral Administration:Systemic antiviral bioavailability constraints limit efficacy in laryngeal tissue.
- Topical Application:Mucosal penetration barriers restrict use to adjuvant settings.
Volume concentration: Surgical Procedure. Steepest expansion trajectory: Intralesional Injection.
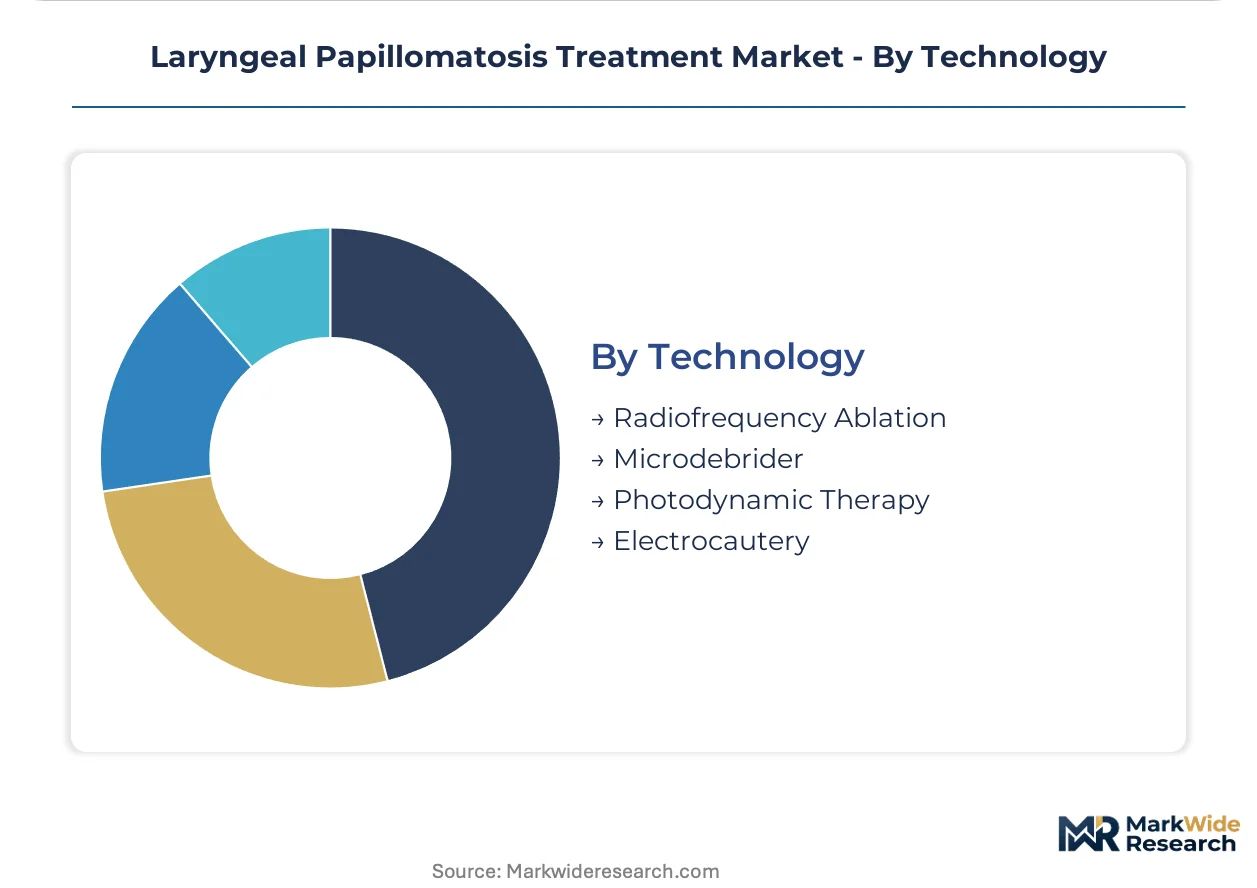
Technology:
Maturity gradients separate decades-old electrosurgical platforms from emerging energy modalities competing on collateral damage profiles.
- Microdebrider:Rotary suction-assisted resection systems offer tactile feedback advantages in bulky pediatric airway disease. Academic medical centers with specialized pediatric otolaryngology fellowship programs are adopting this technology for juvenile-onset recurrent respiratory papillomatosis where tissue preservation priorities exceed laser precision requirements.
- Radiofrequency Ablation:Controlled thermal energy delivery competes with laser systems in select mucosal applications.
- Photodynamic Therapy:Photosensitizer activation requires specialized infrastructure limiting deployment to research centers.
- Electrocautery:Lowest-cost thermal modality retains utility in resource-limited settings despite thermal spread limitations.
Installed base leader: Microdebrider. Technology gaining share fastest: Radiofrequency Ablation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized economic zones for biomedical innovation in Massachusetts and North Carolina concentrate laryngeal papillomatosis treatment development, while hospital procurement centralization across metropolitan health systems reshapes geographic demand distribution.
United States
Tertiary academic medical centers in Boston and New York anchor specialized laryngeal surgery volumes, with ENT department modernization budgets exceeding rural facilities by an order of magnitude. FDA orphan drug designation accelerates therapeutic development timelines through exclusivity incentives and compressed review pathways. The Research Triangle Park corridor in North Carolina clusters DNA medicine platform development for immunotherapy candidates targeting recurrent respiratory papillomatosis.
Germany
University hospitals in Munich and Heidelberg concentrate pediatric otolaryngology fellowship programs that drive adoption of precision surgical modalities. EMA pediatric investigation plans mandate adolescent patient study commitments that extend development timelines for transatlantic immunotherapy programs. The Baden-Württemberg medical technology cluster around Stuttgart sustains carbon dioxide laser system manufacturing and surgical instrument innovation.
Japan
PMDA streamlined review pathways for orphan indications align with global regulatory harmonization efforts, reducing entry barriers for immunotherapy developers. METI funding programs for rare disease therapeutic development redirect domestic pharmaceutical investment toward viral-driven benign tumor indications. The Kanto region around Tokyo concentrates specialized airway surgery centers with fellowship-trained practitioners managing complex recurrent cases.
United Kingdom
NHS England specialized commissioning frameworks concentrate laryngeal papillomatosis care in designated tertiary centers across London and Manchester. MHRA parallel recognition agreements with FDA and EMA enable accelerated market access for immunotherapy candidates receiving breakthrough designation elsewhere. The Cambridge biomedical cluster supports therapeutic vaccine platform development through university-industry partnership structures.
Canada
Health Canada orphan drug regulatory pathways mirror FDA incentive structures, attracting multi-jurisdictional trial participation from academic medical centers in Toronto and Vancouver. Provincial health technology assessment processes in Ontario and British Columbia evaluate laser surgical system procurement through centralized hospital group purchasing organizations. The MaRS Discovery District in Toronto clusters emerging biologics manufacturers addressing rare otolaryngology indications.
Laryngeal Papillomatosis Treatment Market Competitive Landscape
United States-based pharmaceutical developers anchor the immunotherapy tier; European and Japanese specialists hold established positions in antiviral and surgical device segments. Market structure concentrates around three strategic archetypes: DNA medicine platform developers, diversified antiviral portfolio holders, and precision surgical system manufacturers. Competitive dynamics favor strategic partnerships between biologics developers and contract manufacturing organizations, alongside geographic expansion through multi-jurisdictional regulatory registrations.
Within the DNA medicine platform tier, Inovio Pharmaceuticals and Precigen Inc. represent archetypal positions in therapeutic vaccine development for viral-driven proliferative conditions. Among established antiviral and immunotherapy developers, Merck & Co., Inc. and Bristol-Myers Squibb Company exemplify diversified pharmaceutical portfolios repurposing oncology-derived expertise toward orphan benign tumor indications. These four entities occupy positions spanning clinical-stage innovation through commercialized adjuvant protocols, reflecting the market's bifurcation between mechanical debulking incumbents and immune-mediated viral suppression challengers.
| Leading Market Players |
|---|
| Inovio Pharmaceuticals |
| Precigen Inc. |
| Merck & Co., Inc. |
| Bristol-Myers Squibb Company |
| F. Hoffmann-La Roche AG |
| Eli Lilly and Company |
| GlaxoSmithKline plc |
| Johnson & Johnson Services Inc. |
| Hologic, Inc. |
| Others |
Value Network & Pricing Analysis
Integrated delivery network procurement centralization in United States metropolitan hospital systems is compressing vendor margins and forcing surgical system manufacturers toward bundled service contracts that embed multi-year training commitments and consumable lock-ins.
Pricing Analysis
Short lead-time premiums for carbon dioxide laser optics and replacement consumables command 15-25 percent markups over standard contract pricing in United States tertiary centers. Three-tier pricing structure across premium, standard, and economy levels separates academic medical center bundled acquisitions from standalone clinic spot purchases and ambulatory surgical center group purchasing organization arrangements. Pricing pressure stems from Health Canada and TGA parallel registration requirements that inflate compliance costs for multi-jurisdictional product launches. Ambulatory surgical centers exhibit highest price sensitivity due to CMS reimbursement compression, while academic medical centers prioritize outcome guarantees over unit economics.
Supply Chain Analysis
Direct-to-hospital channels handle high-volume laser system deployments, while specialized distributors manage consumable replenishment for outpatient ENT clinics. Precision laser optics manufacturing concentrates in Germany, the United States, and Japan, with rare-earth mineral processing for specialized coatings drawing from Chinese and Australian feedstocks. Supply chain vulnerability rests on single-source dependence for 10,600 nm wavelength optical components and precision-machined surgical handpieces. Distribution runs through integrated delivery network procurement committees that consolidate vendor relationships across metropolitan hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as immunotherapy developers pursue backward integration into GMP-compliant viral vector manufacturing to escape contract manufacturing capacity constraints.
For Market Incumbents: Cement dominance by acquiring specialized pediatric otolaryngology fellowship programs to lock in referral patterns for recurrent respiratory papillomatosis cases. Expand captive production of precision laser optics to offset rare-earth mineral price volatility and neutralize emerging radiofrequency ablation challengers. For New Entrants and Emerging Players: Digital health platform partnerships with integrated delivery networks offer the lowest-friction route to embed therapeutic vaccine candidates into existing care pathways. Target ambulatory surgical center expansion corridors in United States Sun Belt metropolitan areas where ENT department modernization budgets are accelerating fastest. For Investors and Strategic Acquirers: The window for entry favors DNA medicine platform developers with Phase II-ready recurrent respiratory papillomatosis candidates and established FDA breakthrough therapy designation. Monitor PMDA orphan indication review pathway harmonization as the inflection signal for Japanese market entry viability.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | FDA breakthrough therapy designation compresses Phase II-to-approval timelines for immunotherapy candidates. |
| Manufacturing Scale-Up | GMP-compliant viral vector production capacity expansion addresses contract manufacturing bottlenecks for DNA medicine platforms. |
| Hospital System Partnership | Bundled surgical system acquisitions with multi-year service contracts lock in tertiary academic center procurement committees. |
| Regulatory Approval Pathway | Health Canada parallel registration enables multi-jurisdictional launches without redundant facility certification. |
| Pipeline Diversification | Intralesional cidofovir adjuvant positioning creates pharmacological white space between laser resection and systemic therapy. |
Research Methodology
Independent corroboration across otolaryngology department heads, hospital procurement managers, and regulatory affairs specialists at DNA medicine platform developers underwrites the qualitative findings. Secondary validation draws from FDA orphan drug designation filings, EMA pediatric investigation plans, ClinicalTrials.gov entries for recurrent respiratory papillomatosis candidates, and integrated delivery network capital expenditure disclosures. Bottom-up procedure volume estimates triangulate against top-down pharmaceutical pipeline valuations across the analysis window.
Comparable-period anchoring to historical laser surgery adoption curves and immunotherapy clinical trial progression rates structures the forecast framework. Segmentation dimensions span treatment modality, end-user facility type, delivery mode, and patient age stratification. CAGRs derive from procedure volume elasticity models and therapeutic pricing trajectory assumptions, with pediatric population prevalence and HPV vaccination coverage rates serving as key demand-side inputs.
The model holds under stable FDA orphan drug incentive structures and continued hospital capital expenditure growth; deviation in EMA pediatric investigation plan enforcement stringency or rare-earth mineral supply disruptions would shift immunotherapy penetration timelines. Periodic stress-testing of base assumptions against regulatory filing velocity and contract manufacturing capacity expansion is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
ENT
Ear Health Market
ENT
Over-The-Counter (OTC) Hearing Aids Market
ENT
Europe Hearing Aids Market
ENT
Custom Hearing Aids Market
ENT
Hearing Amplifiers Market
ENT
Electrolarynx Market
ENT
Head and Neck Squamous Cell Carcinoma Market
ENT
Nasal Polyps Treatment Market
ENT
Acute Sinusitis Market
ENT
Surgical ENT Devices Market
ENT
Interventional ENT Devices Market
ENT
Global Pediatric Hearing Aids Market
ENT
ENT Examination Chair Market
ENT
Global ENT Workstations Market
ENT
US Hearing Aids Market
ENT
North America Hearing Aid Market