
 Denmark Hearing Aids Market | 2026-2036
Denmark Hearing Aids Market Size, Share, and Industry Trends Forecast 2026-2036
Denmark Hearing Aids Market Insights
Bluetooth-enabled connectivity is tilting hearing aid architecture toward smartphone-integrated ecosystems. WS Audiology A/S leverages its dual-brand structure to sustain broad channel coverage across retail and clinical segments. Demant A/S anchors its position through deep R&D investment in signal processing algorithms. GN Group competes aggressively on rechargeable battery platforms that reduce user maintenance burdens.
Hearing aids are electroacoustic wearable devices that amplify sound for individuals with sensorineural or conductive hearing loss, typically incorporating digital signal processors with 16-24 bit resolution and multi-channel compression to restore speech intelligibility across frequency bands. Behind-the-Ear and Receiver-in-Canal designs dominate unit volume due to their acoustic flexibility and cosmetic acceptability, while Bluetooth connectivity commands premium positioning as users expect seamless integration with mobile devices and televisions. Digital technology has fully displaced analog architectures in Denmark, leaving rechargeable power systems as the primary hardware differentiation frontier where margin pools concentrate.
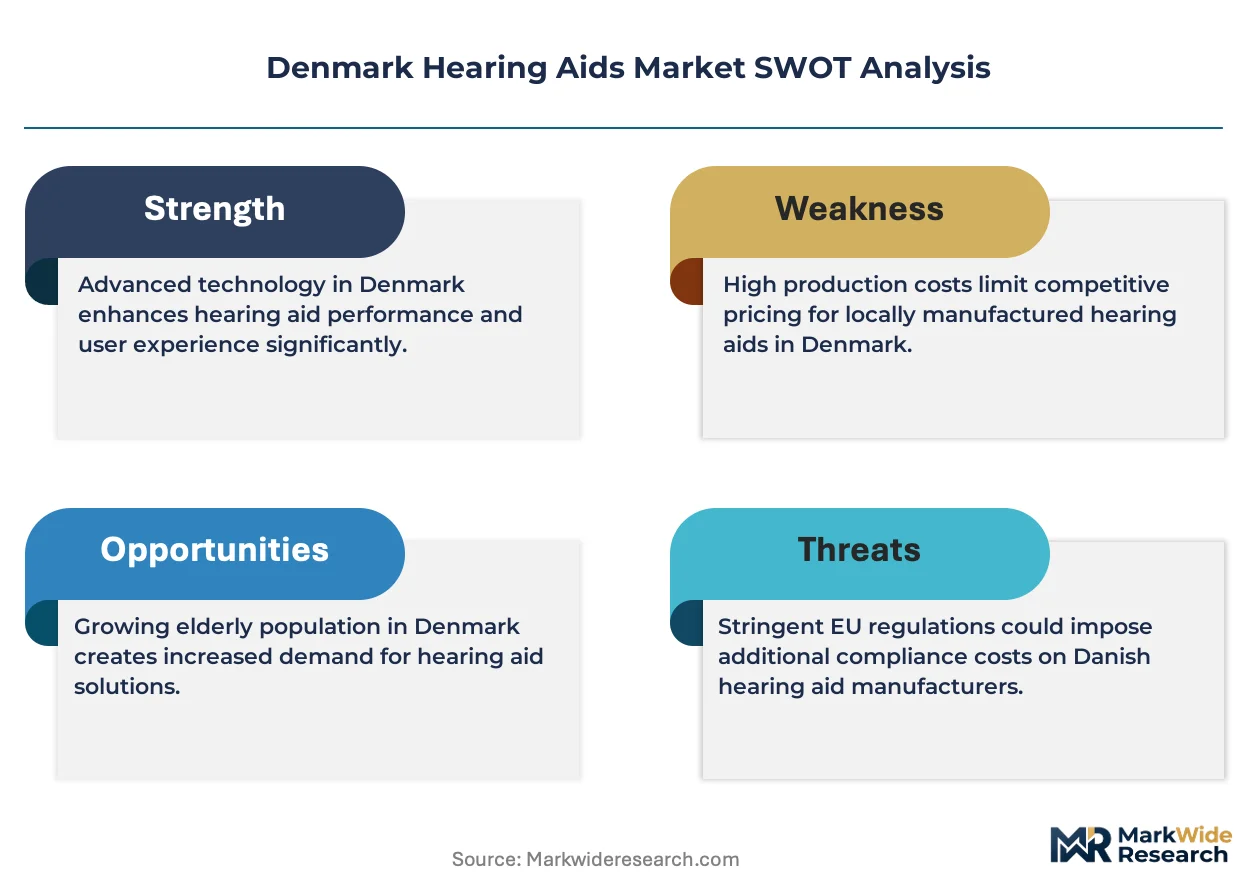
The Danish Medicines Agency oversees medical device registration under EU MDR-aligned frameworks, while the Danish Health Authority governs subsidy eligibility and reimbursement thresholds that directly shape patient access patterns. BIS-relevant standards and CE marking requirements ensure product safety but also create compliance cost barriers for smaller manufacturers. Stakeholders must monitor whether Denmark tightens subsidy criteria or shifts toward outcome-based procurement models that would favor vendors with robust clinical validation data.
Market Dynamics
Bluetooth Low Energy audio protocols are collapsing the traditional boundary between hearing aids and consumer earbuds, forcing vendors to compete on smartphone ecosystem integration rather than acoustic performance alone. This shift compresses replacement cycles and redirects R&D budgets toward software platforms.
Growth Catalysts
- EU MDR alignment:The Danish Medicines Agency's streamlined registration pathway accelerates product clearance for manufacturers already holding CE marking, reducing time-to-market for updated device generations.
- Rechargeable lithium-ion systems:Battery chemistry improvements eliminate zinc-air cell replacement burdens, expanding addressable demand among dexterity-limited seniors who previously abandoned hearing aid use.
- Copenhagen audiology cluster:Capital-region clinic density concentrates diagnostic capacity and creates referral network effects that pull patients from peripheral Jutland and Funen municipalities.
Market Restraints
- Zinc-air battery supply:Raw material concentration in East Asian processing facilities exposes Danish distributors to freight cost volatility and customs clearance delays.
- Danish Health Authority subsidy thresholds:Strict audiometric criteria exclude mild-to-moderate hearing loss cases from full reimbursement, pushing price-sensitive patients toward unregulated personal sound amplification devices.
- Acoustic fitting complexity:Individual ear canal geometry variation requires professional calibration, preventing true self-fitting and maintaining labor cost structures that resist automation.
Strategic Opportunities
- North Jutland penetration gap:Aalborg and surrounding rural districts maintain lower hearing aid adoption rates than national averages, presenting whitespace for mobile audiology service models.
- Teleaudiology protocols:Remote fitting software validated under Danish clinical standards enables post-purchase adjustments without clinic visits, unlocking subscription-based service revenue streams.
- AI-driven noise reduction:Machine learning classification of acoustic environments converges with edge computing capabilities to differentiate premium tier positioning from standard signal processing.
Industry Challenges
- Audiologist workforce constraints:Specialized training programs at University of Copenhagen and Aarhus University produce insufficient graduates to match clinic expansion plans across Zealand.
- EU MDR technical documentation:Clinical evidence requirements for software-as-a-medical-device updates extend recertification timelines, complicating agile firmware release cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Denmark Hearing Aids Market |
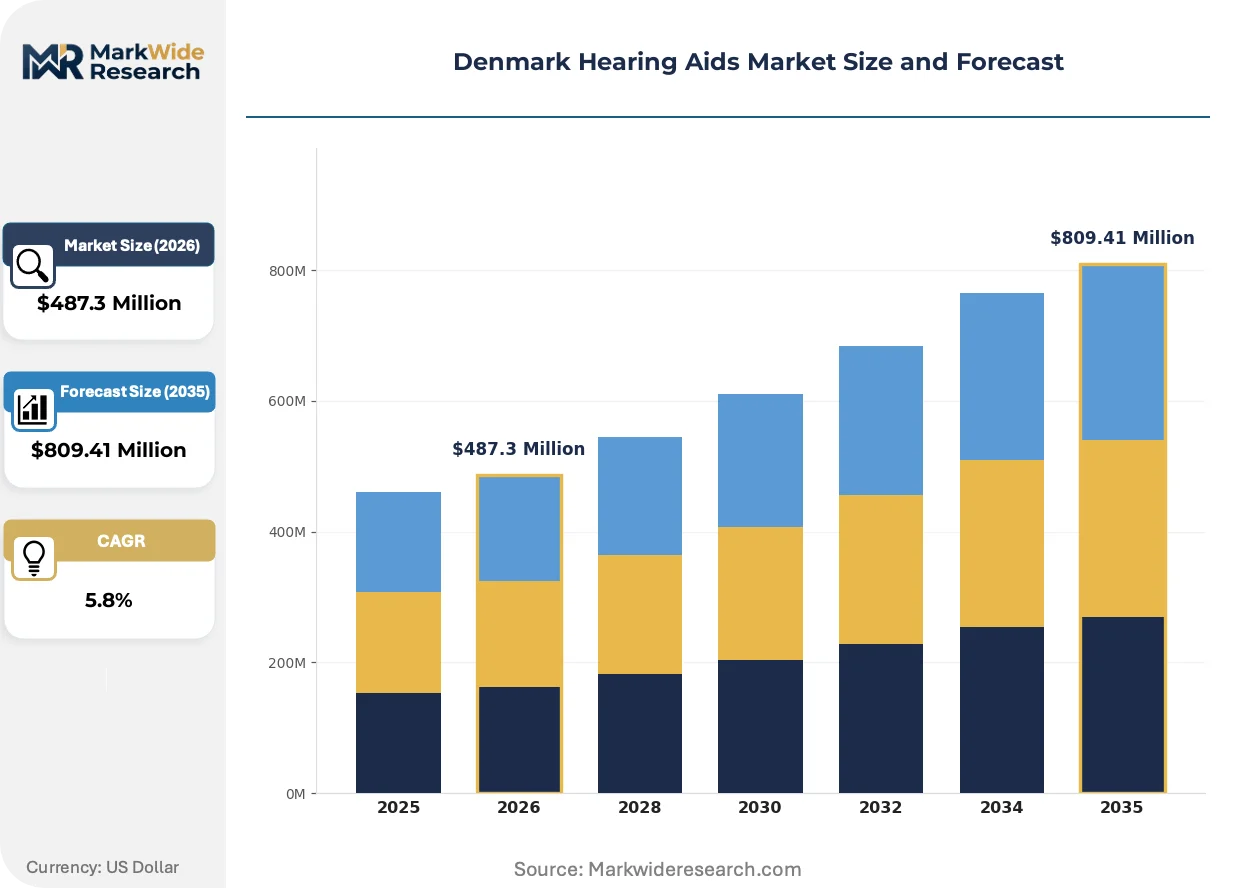
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Behind-the-Ear, In-the-Ear, Receiver-in-Canal, Completely-in-Canal Technology: Analog, Digital, Bluetooth, Rechargeable End User: Seniors, Adults, Pediatrics, Veterans Distribution Channel: Online, Retail, Hospitals, Audiology Clinics |
| Companies Covered | WS Audiology A/S, Demant A/S, GN Group, Oticon Medical, Sonova, Widex Hearing Technology A/S, ReSound, Bernafon, AudioNova, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Denmark Hearing Aids Market Trends and Innovations
Software-defined functionality is overtaking hardware as the primary value creation mechanism in Danish hearing aid distribution. Vendors now compete on algorithm update frequency and smartphone app integration depth rather than acoustic component specifications alone.
Deep neural network-based sound scene classification is migrating from research laboratories to commercial firmware releases. Private audiology chains in Copenhagen and Odense deploy these systems for patients with complex social communication needs. The technology is compressing differentiation timelines as algorithm improvements distribute via over-the-air updates rather than hardware replacement cycles.
Danish Health Authority subsidy frameworks are tightening outcome documentation requirements for reimbursed devices. Clinicians must now submit standardized speech-in-noise test results to justify premium-tier approvals. This policy shift redirects manufacturer clinical trial investment toward real-world effectiveness studies in Danish-speaking populations rather than laboratory threshold measurements.
Direct-to-consumer online channels are capturing younger first-time users who research Bluetooth connectivity specifications before seeking professional fitting. Traditional retail audiology practices in Aarhus and Esbjerg respond by unbundling diagnostic services from device sales, creating transparent fee-for-test structures that compete with internet-based hearing screeners. This channel friction is most visible among tech-sector employees aged 45-55 in Greater Copenhagen who prioritize smartphone integration over clinical hand-holding.
Denmark Hearing Aids Market Segmentation
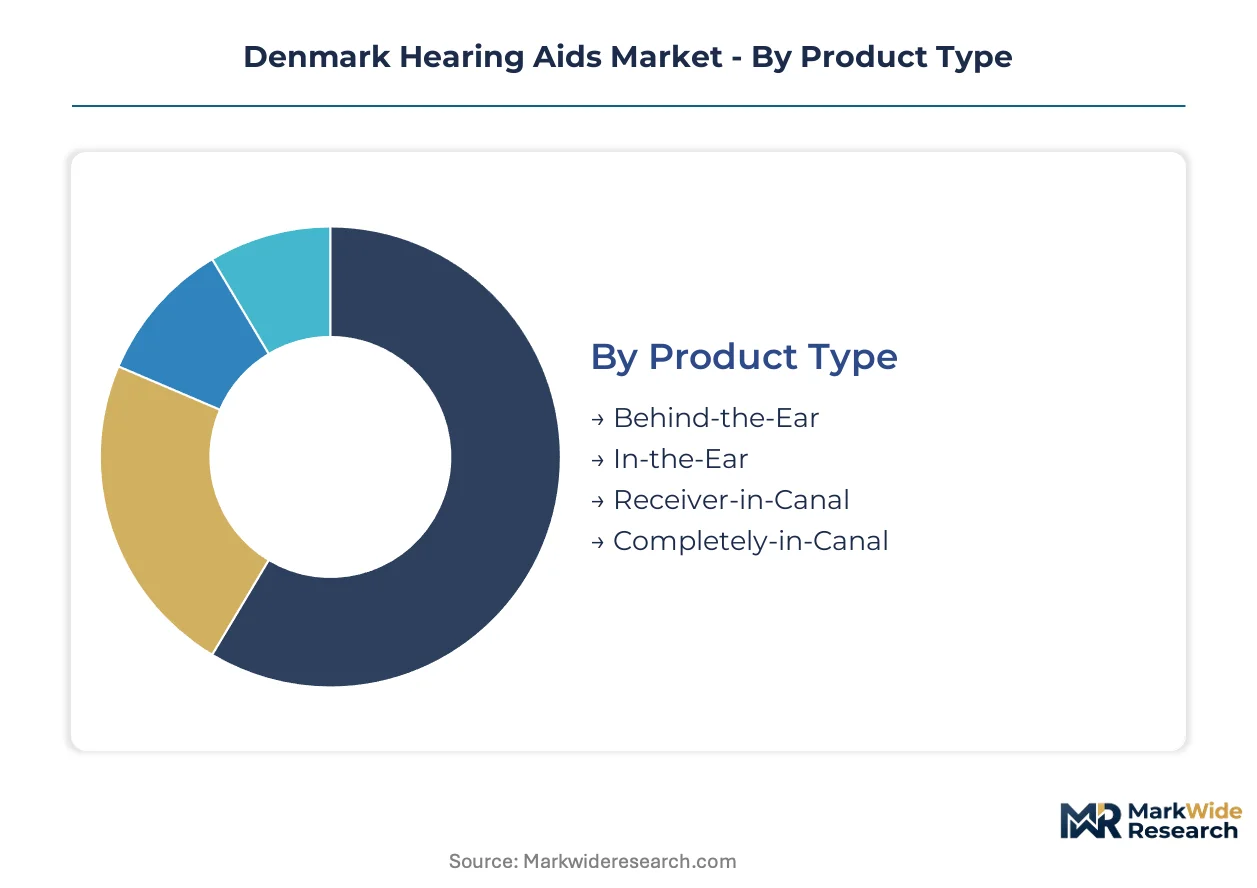
Segmentation in Denmark's hearing aid market reveals how technology adoption, reimbursement pathways, and patient demographics intersect. Each dimension carries distinct regulatory implications under Danish Health Authority frameworks and shapes vendor go-to-market priorities across Copenhagen's clinical cluster and peripheral regions.
Product Type:
Cost tier stratification in Denmark's hearing aid market maps directly to acoustic performance capabilities and cosmetic discretion trade-offs. Reimbursement thresholds favor certain form factors over others.
- Behind-the-Ear:These units house microphones, amplifiers, and processors in a casing resting behind the auricle, connected via tubing to custom ear molds. Demand concentrates among seniors in Zealand and Funen municipalities where Danish Health Authority subsidies cover moderate-to-severe hearing loss cases requiring maximum amplification power.
- Receiver-in-Canal:A miniature receiver sits directly in the ear canal while the main body rests behind the ear, reducing occlusion and improving high-frequency response. Copenhagen's private audiology chains push this format toward working-age adults who prioritize Bluetooth streaming and smartphone integration.
- In-the-Ear:Custom-molded shells fill the concha and ear canal for discreet placement. The Danish Medicines Agency's CE marking requirements for custom impressions create longer fulfillment timelines.
- Completely-in-Canal:These micro-devices sit deep within the ear canal with extraction cords visible. Limited battery size restricts amplification power and wireless connectivity options.
Behind-the-Ear commands the established base. The steepest expansion runs through Receiver-in-Canal.
Technology:
Maturity gradients across Denmark's hearing aid technology stack show analog architectures fully displaced while rechargeable power systems emerge as the primary hardware differentiation frontier.
- Analog:Simple amplification circuits without digital signal processing persist only in legacy inventory and personal sound amplification devices falling outside Danish Health Authority reimbursement.
- Digital:16-24 bit resolution processors with multi-channel compression and feedback cancellation dominate unit volume. North Jutland's lower audiology clinic density drives preference for reliable, service-light digital platforms.
- Bluetooth:Low Energy audio protocols enable direct streaming from smartphones, televisions, and remote microphones. Copenhagen's tech-sector employees aged 45-55 prioritize this capability.
- Rechargeable:Lithium-ion battery systems eliminate zinc-air cell replacement burdens. Demand from dexterity-limited seniors in Aarhus and Odense accelerates fastest.
Digital technology anchors current installed base. Rechargeable systems are gaining share fastest among first-time users.
End User:
Customer type segmentation in Denmark reflects distinct clinical pathways, subsidy eligibility criteria, and device feature requirements across age and service history cohorts.
- Seniors:Adults aged 65+ represent the dominant addressable population given Denmark's aging demographic structure. Copenhagen's hospital audiology departments and municipal hearing centers concentrate diagnostic capacity for this cohort.
- Adults:Working-age users aged 18-64 typically present with noise-induced or early-onset sensorineural loss. Private audiology chains in Aarhus and Esbjerg capture this segment through unbundled diagnostic and fitting services.
- Pediatrics:Congenital and early childhood hearing loss cases require specialized fitting protocols and frequent device replacement as ear canals grow. The Danish Health Authority mandates binaural provision for children.
- Veterans:Military service-related hearing loss claims flow through separate administrative channels with distinct reimbursement schedules.
Seniors command the established base. The steepest expansion runs through Adults seeking Bluetooth-enabled devices.
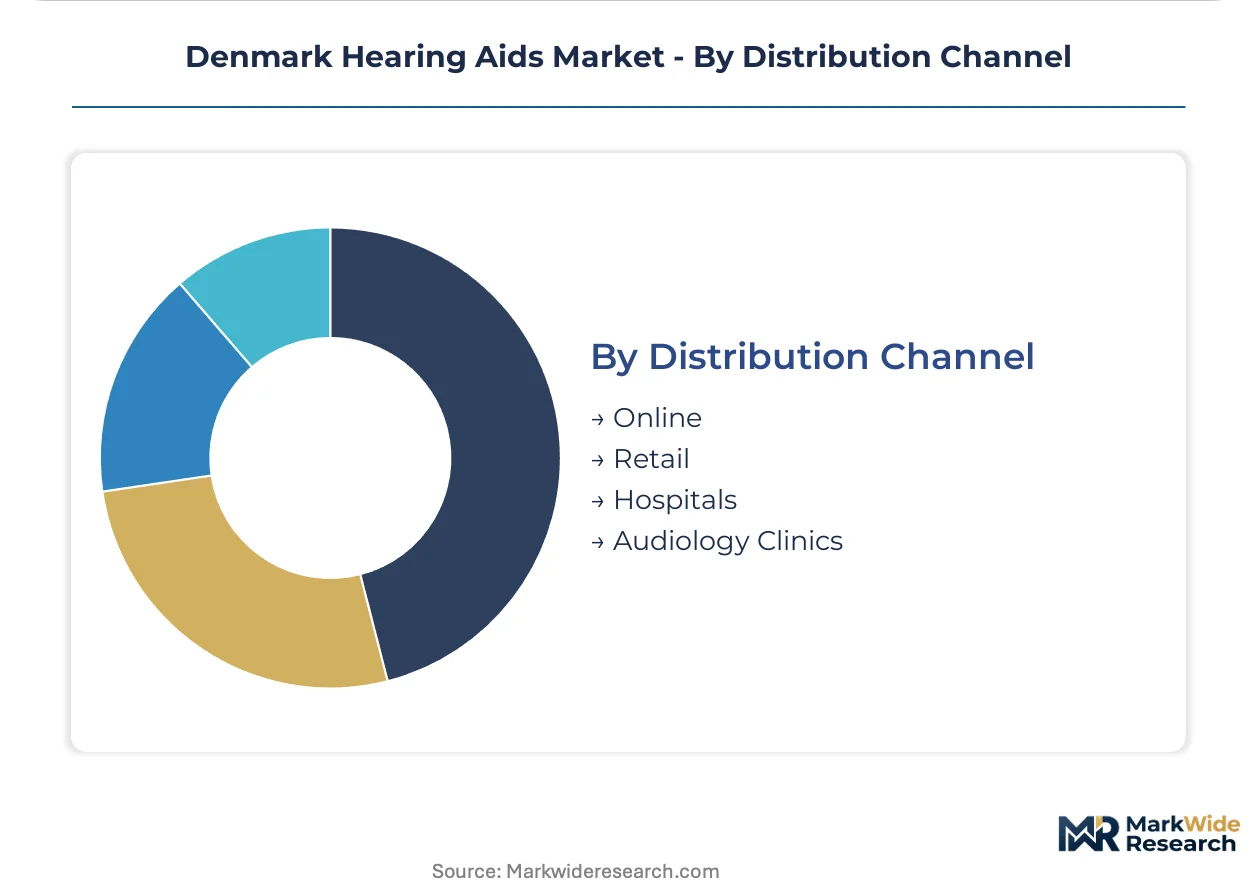
Distribution Channel:
Supply concentration across Denmark's hearing aid distribution landscape shows channel friction intensifying as direct-to-consumer models challenge traditional clinical gatekeeping.
- Online:Direct-to-consumer platforms capture younger first-time users who research specifications independently. Greater Copenhagen's tech-literate population aged 45-55 drives this channel's expansion.
- Retail:Consumer electronics and pharmacy chains stock personal sound amplification devices and basic hearing aids. Danish Health Authority reimbursement restrictions limit penetration of clinically validated products.
- Hospitals:Public hospital audiology departments handle complex cases, pediatric fittings, and cochlear implant candidacy assessments. Copenhagen University Hospital and Aarhus University Hospital anchor this channel.
- Audiology Clinics:Independent and chain-affiliated practices dominate premium-tier device dispensing. Clinic density concentrates in Copenhagen, Odense, and Aarhus with whitespace in rural Jutland districts.
Audiology Clinics command the established base. The steepest expansion runs through Online channels among digitally native patient cohorts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German hearing aid manufacturers export precision-engineered devices to Denmark's clinical networks, establishing the bilateral trade corridor that shapes Nordic market supply dynamics.
Zealand
Copenhagen's hospital audiology departments and municipal hearing centers concentrate diagnostic capacity for seniors aged 65+. Danish Health Authority subsidy frameworks govern reimbursement eligibility for devices dispensed through this channel. The capital region's clinic density pulls patients from peripheral municipalities seeking specialized fitting services.
North Jutland
Aalborg and surrounding rural districts maintain lower hearing aid adoption rates than national averages, creating whitespace for mobile audiology service models. University of Copenhagen audiology training programs supply insufficient graduates to match clinic expansion plans here. Aarhus University Hospital anchors tertiary referral capacity for complex cases from this region.
Central Denmark
Aarhus hosts independent and chain-affiliated audiology practices dominating premium-tier device dispensing. Private audiology chains capture working-age users aged 18-64 through unbundled diagnostic and fitting services. The city's tech-sector employees aged 45-55 prioritize Bluetooth streaming and smartphone integration.
Southern Denmark
Odense's audiology clinics deploy deep neural network-based sound scene classification systems for patients with complex social communication needs. Danish Medicines Agency CE marking requirements for custom impressions create longer fulfillment timelines for In-the-Ear devices. Private chains here respond to direct-to-consumer online channels by unbundling services.
Denmark Hearing Aids Market Competitive Landscape
On the supply side, the industry is consolidated around vertically integrated hearing specialists and diversified audio-technology conglomerates. Three strategic archetypes dominate: full-stack manufacturers with captive R&D pipelines, platform-agnostic component suppliers, and retail-channel integrators. Competitive intensity concentrates on algorithm update frequency and rechargeable battery platform differentiation rather than acoustic hardware specifications alone.
Within the integrated manufacturer tier, WS Audiology A/S and Demant A/S exemplify archetypes combining device production with clinical service networks. GN Group occupies a position bridging hearing aid and consumer audio domains through rechargeable platform development. These Danish-anchored entities represent the supply-side concentration that shapes procurement patterns across Zealand and Jutland clinic networks.
| Leading Market Players |
|---|
| WS Audiology A/S |
| Demant A/S |
| GN Group |
| Oticon Medical |
| Sonova |
| Widex Hearing Technology A/S |
| ReSound |
| Bernafon |
| AudioNova |
| Others |
Pricing and Supply Chain Analysis
Zinc-air battery supply concentration in East Asian processing facilities exposes Danish distributors to freight cost volatility and customs clearance delays, compressing margin structures at the economy tier while amplifying pricing power for vendors with captive lithium-ion rechargeable platforms. This raw material chokepoint simultaneously widens the premium-to-standard tier spread and accelerates backward integration incentives among integrated manufacturers.
Pricing Analysis
The technology-generation pricing gap separates current-generation Bluetooth-enabled devices from prior-generation basic digital units and emerging next-generation AI-driven platforms. Three-tier pricing structure across premium, standard, and economy levels dominates, with Bluetooth connectivity and rechargeable battery systems driving differentiation. Cost compression in the economy tier is intensifying because personal sound amplification devices capture price-sensitive mild-to-moderate hearing loss cases excluded from Danish Health Authority subsidies. Seniors with dexterity limitations show least price sensitivity due to reimbursement coverage, while working-age first-time users in Greater Copenhagen exhibit highest elasticity.
Supply Chain Analysis
Upstream feedstock for lithium-ion cells draws from China, South Korea, and Japan, while precision acoustic components and digital signal processors source from Germany, Taiwan, and the USA. Critical dependencies include rare earth magnets for miniature receivers, medical-grade silicones for custom molds, and 16-24 bit resolution DSP chips. Single-source vulnerability concentrates in advanced battery management systems from East Asian semiconductor foundries. Distribution runs through audiology clinic networks anchored in Copenhagen, Aarhus, and Odense, with direct-to-consumer online channels capturing growing share among tech-literate demographics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bluetooth Low Energy audio protocols are collapsing the traditional boundary between hearing aids and consumer earbuds, creating a high-growth disruption window as software-defined functionality overtakes hardware specifications as the primary value creation mechanism.
For Market Incumbents: Pre-empt platform commoditization by accelerating over-the-air algorithm update frequency and deepening smartphone ecosystem integration partnerships. Consolidate channel control through exclusive audiology clinic network agreements in Copenhagen and Aarhus to defend against direct-to-consumer entrants. Invest captive R&D in edge-computing noise reduction to maintain premium tier separation. For New Entrants and Emerging Players: Pursue the North Jutland whitespace where mobile audiology service models can bypass fixed clinic infrastructure constraints. Target working-age adults aged 45-55 in peripheral municipalities with subscription-based teleaudiology protocols that unbundle diagnostic services from device sales. Position through transparent fee-for-test structures competing with internet-based hearing screeners. For Investors and Strategic Acquirers: EU MDR software-as-a-medical-device recertification timelines reshape the acquisition landscape toward targets with robust clinical validation data and agile firmware release capabilities. Five-to-ten year viability hinges on outcome-based procurement model readiness. Signal to watch: Danish Health Authority tightening of speech-in-noise test documentation requirements for premium-tier approvals.| Strategic Initiative | Industry Significance |
|---|---|
| Teleaudiology Platform Development | Remote fitting software validated under Danish clinical standards unlocks subscription revenue streams without clinic infrastructure. |
| Rechargeable Battery Platform Expansion | Lithium-ion systems eliminate zinc-air supply dependencies while capturing dexterity-limited senior demand in Aarhus and Odense. |
| AI-Driven Noise Reduction Investment | Machine learning classification of acoustic environments differentiates premium positioning from standard signal processing tiers. |
| Audiology Clinic Network Consolidation | Exclusive agreements in Copenhagen and Aarhus create referral moats against direct-to-consumer channel erosion. |
| Danish-Specific Clinical Validation Studies | Real-world effectiveness data in Danish-speaking populations satisfies tightening Danish Health Authority subsidy documentation requirements. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with audiology clinic directors, biomedical engineers at Copenhagen University Hospital, procurement managers at Danish Health Authority regional offices, and hearing aid manufacturer product strategy leads. Secondary validation drew from Danish Medicines Agency medical device registration databases, Danish Health Authority reimbursement schedule documentation, EU MDR technical documentation requirements, and hospital procurement contract disclosures. Bottom-up unit volume estimates from clinic-level dispensing data were triangulated against top-down manufacturer shipment figures reported in regulatory filings.
Calibration against historical adoption curves and technology substitution patterns shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology tier, end-user age cohort, and distribution channel structure. CAGRs were derived from fitted growth curves incorporating rechargeable battery penetration rates, Bluetooth adoption trajectories among working-age users, and teleaudiology service expansion assumptions. Industry-specific inputs encompassed audiologist workforce graduation rates from University of Copenhagen and Aarhus University training programs.
Macroeconomic conditions sit as an overlay; deviation in Danish krone exchange rates against euro-denominated component sourcing, or shifts in public health expenditure allocation toward hearing care, would shift the trajectory. Forecasts reflect documented assumptions regarding EU MDR implementation timelines and Danish Health Authority subsidy stability. Cross-checking against hospital audiology department waitlist data and municipal hearing center capacity utilization is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
ENT
Custom Hearing Aids Market
ENT
Nasal Sampling Lines Market
ENT
Hearing Implants Market
ENT
Global ENT Workstations Market
ENT
US Hearing Aids Market
ENT
Nasal Polyps Treatment Market
ENT
Global Audiological Devices Market
ENT
Audiology Devices Market
ENT
Electrolarynx Market
ENT
ENT Disorder Treatment Market
ENT
Over-The-Counter (OTC) Hearing Aids Market
ENT
North America Hearing Aid Market
ENT
Hearing Amplifiers Market
ENT
Laryngeal Papillomatosis Treatment Market
ENT
ENT Examination Chair Market
ENT
Europe Hearing Aids Market