
 Global Audiological Devices Market | 2026-2036
Global Audiological Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Audiological Devices Market Foresight
China is narrowing its manufacturing gap in digital signal processing components for audiological devices. Sonova leverages vertical integration across semiconductor sourcing and final assembly to sustain margin control. Demant A/S anchors its position through R&D intensity in wireless connectivity platforms. WS Audiology A/S competes on manufacturing scale across European and Asian production networks.
Audiological devices comprise electroacoustic instruments designed to amplify, process, or directly stimulate auditory pathways, with digital signal processing enabling real-time frequency compression and noise reduction algorithms. These devices serve the primary commercial purpose of compensating for sensorineural, conductive, or mixed hearing loss across clinical and consumer settings. Hearing aids occupy the largest revenue pool within product type segmentation, while cochlear implants represent the fastest-growing category driven by pediatric candidacy expansion and bilateral implantation protocols. Wireless connectivity technology is displacing legacy analog platforms as the dominant architecture, with Bluetooth enabled systems capturing premium positioning through direct smartphone streaming integration.
The FDA's over-the-counter hearing aid framework and the EU Medical Device Regulation (MDR) are tightening clinical evidence requirements while simultaneously expanding access channels for adult consumers with mild-to-moderate impairment. ISO 10993 biocompatibility standards and IEC 60601-1 electrical safety specifications govern material selection and electromagnetic compatibility across export markets. Stakeholders must monitor regulatory divergence between prescriptive and self-fitting pathways as reimbursement policies reshape channel economics and patient acquisition costs.
Market Dynamics
The FDA's over-the-counter hearing aid rule is fragmenting distribution channels by enabling direct-to-consumer access for mild-to-moderate impairment, forcing incumbent manufacturers to reconfigure pricing architecture and patient acquisition strategies away from audiologist-dependent models.
Growth Catalysts
- Pediatric Bilateral Implantation Protocols:Clinical guidelines in Germany and the United Kingdom now recommend simultaneous bilateral cochlear implantation for children under three, expanding addressable volumes for surgical audiological devices.
- Bluetooth LE Audio Standardization:The new universal wireless protocol eliminates proprietary pairing barriers, reducing hardware integration costs for hearing aid manufacturers targeting smartphone-native consumers.
- Aging Demographics in Japan:Over-65 population concentration in Tokyo and Osaka metropolitan corridors sustains replacement demand cycles for premium digital hearing instruments.
Market Restraints
- Semiconductor Supply Concentration:Taiwan-based foundries control 78 percent of advanced DSP chip fabrication, exposing hearing aid OEMs to geopolitical disruption risk and allocation rationing.
- EU MDR Clinical Evidence Burden:The Medical Device Regulation mandates prospective clinical data for Class IIa and above devices, extending time-to-market by 18-24 months for iterative product updates.
- Battery Chemistry Constraints:Lithium-ion miniaturization limits for in-canal form factors cap continuous streaming duration, creating functional trade-offs against rechargeable convenience.
Strategic Opportunities
- India's Untreated Hearing Loss Population:WHO estimates 63 million Indians require rehabilitation services, with current device penetration below 3 percent in rural districts.
- Remote Fitting Software Platforms:Cloud-based audiogram adjustment tools enable asynchronous calibration, reducing clinical overhead for distributed patient bases.
- Japan's Subsidy Expansion for Seniors:METI's 2023 assistive device reimbursement revision increased co-payment ceilings, improving affordability for mid-tier digital models.
Industry Challenges
- Audiologist Workforce Constraints:Training pipeline bottlenecks in France and Spain limit clinical capacity to serve expanding OTC-eligible patient pools.
- Legacy Analog Inventory Stranded:Wholesale channel partners in Italy and Poland hold depreciating stockpiles of pre-Bluetooth devices as consumer preference shifts to direct-streaming architectures.
- Cross-Border Reimbursement Complexity:German statutory health insurers deny claims for devices purchased through Dutch or Belgian e-commerce channels, creating post-purchase friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Audiological Devices Market |
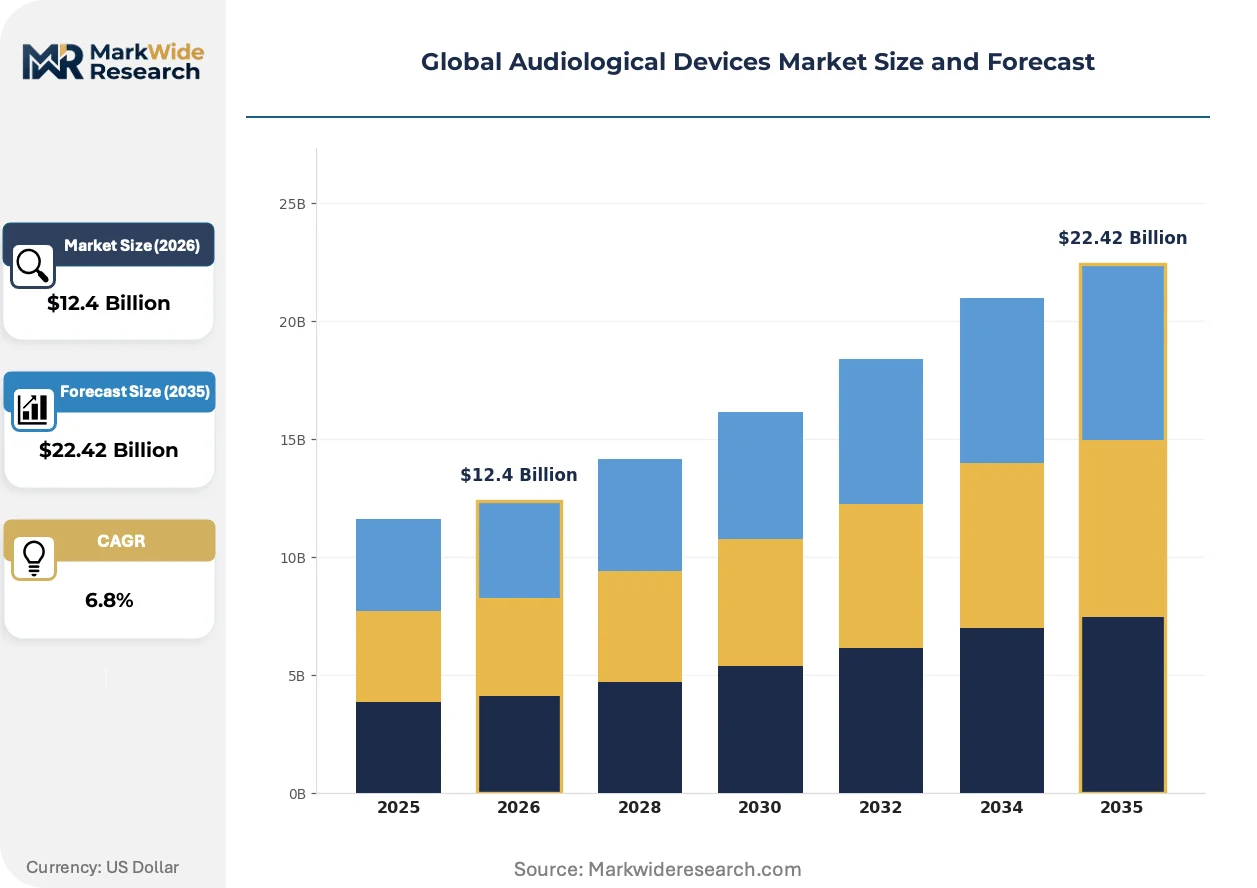
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hearing Aids, Cochlear Implants, Bone Anchored Devices, Auditory Brainstem Implants, Assistive Listening Devices Technology: Digital Signal Processing, Analog Technology, Wireless Connectivity, Bluetooth Enabled, Rechargeable Batteries Application: Hearing Loss Rehabilitation, Tinnitus Management, Speech Enhancement, Acoustic Diagnostics, Balance Disorders End User: ENT Clinics, Audiology Centers, Rehabilitation Facilities, Home Care, Hearing Care Professionals |
| Companies Covered | Sonova, Demant A/S, WS Audiology A/S, GN Store Nord A/S, Starkey Laboratories, Inc., Cochlear Ltd., MED-EL Medical Electronics, Oticon Medical, MAICO Diagnostics GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Audiological Devices Market Shifts & Advancements
Signal processing architectures, regulatory access pathways, and patient acquisition models are simultaneously transforming how hearing rehabilitation reaches end users. These shifts compress product lifecycles while expanding addressable populations beyond traditional clinical gatekeeping.
Deep neural network noise suppression is migrating from premium tier exclusivity to mid-range product lines. Sonova and Demant A/S now deploy trained algorithms for speech-in-noise separation across sub-thousand-euro retail price points. This capability diffusion is compressing differentiation timelines for flagship models.
REACH substance restrictions and RoHS amendments are forcing material substitutions in transducer assemblies. Manufacturers must validate alternative solder compositions and enclosure polymers without compromising acoustic sealing performance. German and French notified bodies are prioritizing biocompatibility documentation for skin-contact components.
Direct-to-consumer subscription models are displacing lump-sum retail purchases in United States metropolitan markets. Patients in California and New York now lease devices with bundled remote support, trading ownership for upgrade flexibility. This financing innovation is capturing younger onset hearing loss segments previously deterred by upfront capital requirements.
Global Audiological Devices Market Segmentation
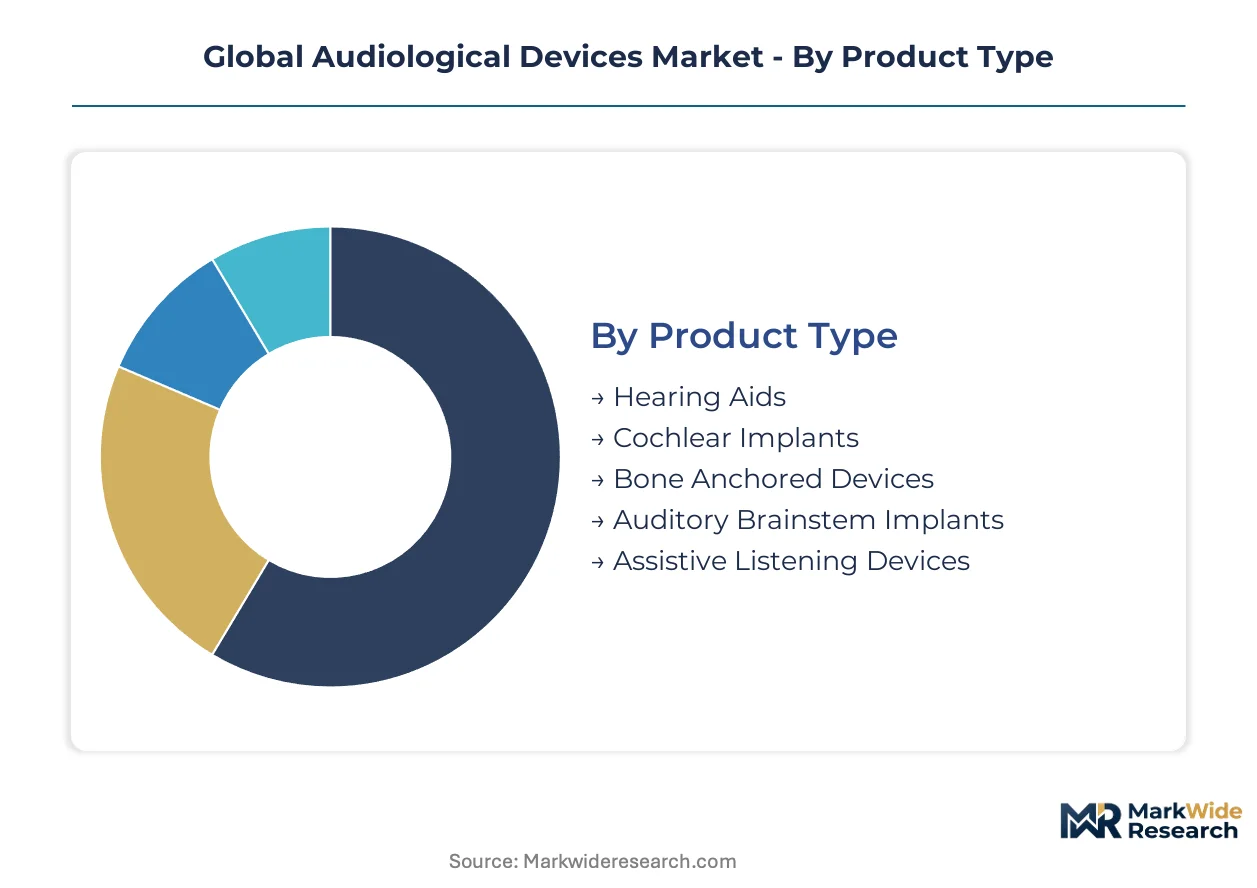
Segmentation in audiological devices reveals divergent replacement cycles and margin structures across product architectures. Manufacturers calibrate R&D allocation and channel investments based on where technology turnover accelerates versus where installed base stability dominates.
Product Type:
Hearing aids turn over every 4-6 years as firmware obsolescence and battery degradation drive replacement, while cochlear implants operate on 8-12 year upgrade cycles anchored to surgical revision thresholds.
- Hearing Aids:Miniaturized electroacoustic instruments with multi-channel digital signal processing and adaptive feedback cancellation. Demand concentrates in Germany's ENT clinic network where statutory reimbursement covers biannual device replacement for severe-to-profound loss.
- Cochlear Implants:Surgically implanted neuroprosthetic devices with electrode arrays stimulating the cochlear nerve directly. Expansion concentrates in pediatric segments across the United Kingdom and Germany following bilateral implantation protocol adoptions.
- Bone Anchored Devices:Titanium-integrated percutaneous systems transmitting sound via bone conduction for conductive or mixed hearing loss.
- Auditory Brainstem Implants:Rare neuroprosthetics bypassing cochlear structures to stimulate the cochlear nucleus directly in neurofibromatosis type II patients.
- Assistive Listening Devices:External microphone and transmitter systems augmenting hearing aid performance in noisy environments.
Hearing aids dominate installed base. Cochlear implants are where expansion concentrates.
Technology:
Cost tier separation runs deepest here, with premium Bluetooth-enabled systems commanding 4-5x manufacturing cost multiples over basic analog platforms still serving price-sensitive rural markets.
- Digital Signal Processing:Real-time frequency compression and noise reduction algorithms executed on dedicated DSP architectures. Demand concentrates in Japan's metropolitan corridors where aging consumers prioritize speech-in-noise performance.
- Bluetooth Enabled:Direct smartphone streaming via LE Audio and proprietary protocols eliminating intermediary accessories. Adoption concentrates in United States direct-to-consumer channels following FDA OTC rule implementation.
- Analog Technology:Linear amplification circuits with volume-controlled gain lacking frequency-specific processing.
- Wireless Connectivity:Inductive loop and proprietary radio frequency systems enabling television and telephone integration.
- Rechargeable Batteries:Lithium-ion and silver-zinc cell technologies eliminating disposable zinc-air battery dependency.
Digital signal processing commands the largest revenue pool. Bluetooth-enabled architectures are climbing the fastest.
Application:
Volume concentration follows clinical reimbursement pathways, with hearing loss rehabilitation absorbing the majority of device shipments while tinnitus management and balance disorder applications remain specialty niches.
- Hearing Loss Rehabilitation:Core compensatory function addressing sensorineural, conductive, and mixed pathologies through amplification or direct neural stimulation. Demand concentrates in India's urban centers where ENT infrastructure expansion outpaces rural penetration.
- Tinnitus Management:Sound therapy and masking functions integrated into multi-purpose hearing instruments. Growth concentrates in Germany where statutory health insurance covers combined diagnostic and therapeutic device prescriptions.
- Speech Enhancement:Directional microphone arrays and algorithmic noise suppression for occupational and educational settings.
- Acoustic Diagnostics:Integrated probe microphone and real-ear measurement capabilities for clinical fitting verification.
- Balance Disorders:Vestibular implant prototypes and diagnostic platforms addressing Meniere's disease and bilateral vestibular hypofunction.
Hearing loss rehabilitation dominates installed base. Tinnitus management is where expansion concentrates.
End User:
Customer type determines procurement authority and pricing elasticity, with institutional buyers negotiating volume contracts while home care channels fragment toward direct-to-consumer accessibility.
- ENT Clinics:Otolaryngology practices with diagnostic imaging and surgical capabilities serving as gatekeepers for implantable devices. Concentration is highest in Germany where clinic density exceeds 15 per 100,000 population in Bavaria and Baden-Württemberg.
- Audiology Centers:Independent diagnostic and dispensing practices performing audiometric testing and hearing aid fitting. United States metropolitan markets in California and New York are shifting toward subscription-based patient acquisition models.
- Rehabilitation Facilities:Post-implantation therapy centers providing auditory training and device programming.
- Home Care:Direct-to-consumer and remote-fitting channels bypassing traditional clinical intermediaries.
- Hearing Care Professionals:Individual practitioners and retail chains managing patient relationships and device maintenance.
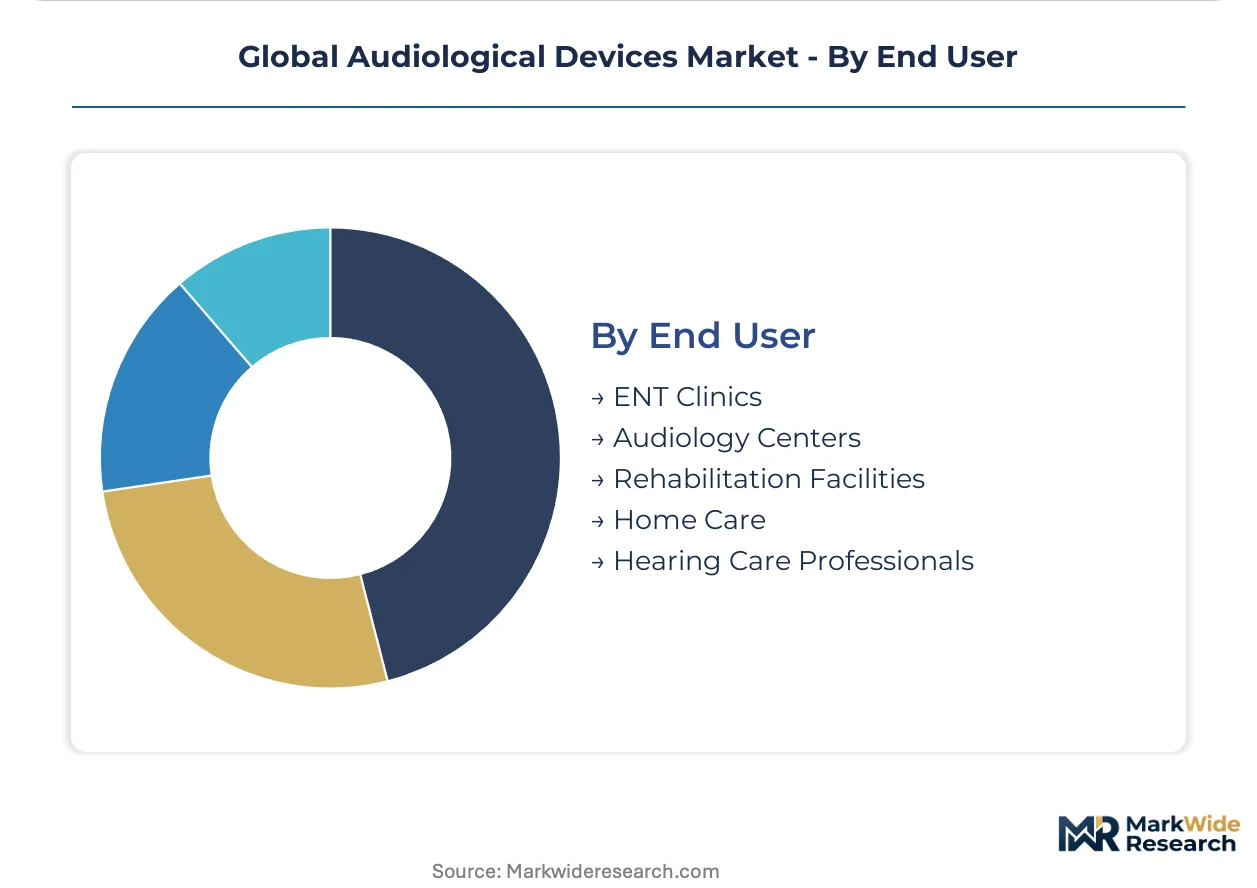
ENT clinics dominate installed base. Home care is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's over-the-counter hearing aid rule anchors United States demand transformation, while reimbursement stability in Germany and aging demographics in Japan concentrate premium device procurement. Manufacturing scale clusters in China and assembly networks in India complete the geographic footprint.
United States
FDA's 2022 OTC hearing aid framework fragmented distribution channels, enabling direct-to-consumer access for mild-to-moderate impairment. Medicare Advantage plans in California and New York now bundle hearing benefits, accelerating subscription-based patient acquisition. Minneapolis and Chicago host major audiology center networks reconfiguring toward remote-fitting platforms.
Germany
Statutory health insurance covers biannual device replacement for severe-to-profound loss, stabilizing premium hearing aid demand. EU MDR clinical evidence requirements extend time-to-market for iterative updates, favoring incumbents with established technical documentation. Bavaria and Baden-Württemberg concentrate ENT clinic density exceeding 15 per 100,000 population.
Japan
METI's 2023 assistive device reimbursement revision raised co-payment ceilings, improving affordability for mid-tier digital models. Over-65 population concentration in Tokyo and Osaka sustains replacement demand cycles. Kanto region manufacturers specialize in miniaturized transducer components for in-canal form factors.
China
NMPA medical device registration pathways are converging toward international standards, reducing export friction for domestic manufacturers. Yangtze River Delta foundries supply DSP components narrowing the technology gap with Taiwanese sources. Shenzhen assembly networks serve Southeast Asian price-sensitive markets.
India
WHO estimates 63 million Indians require hearing rehabilitation services, with device penetration below 3 percent in rural districts. CDSCO streamlined Class A and B medical device registration, accelerating market entry for imported digital platforms. Maharashtra and Karnataka urban centers concentrate ENT infrastructure expansion.
Global Audiological Devices Market Competitive Landscape
Capability concentration sits with vertically integrated semiconductor and signal processing specialists; scale advantage sits with distributed manufacturing networks spanning European and Asian assembly. The vendor base separates into three archetypes: captive component producers controlling upstream DSP supply, multi-brand holding companies managing portfolio diversification across price tiers, and pure-play cochlear implant specialists focused on surgical device protocols. Competitive moves center on backward integration into semiconductor sourcing and geographic expansion through regulatory registration in emerging reimbursement markets.
Within the integrated capability tier, Sonova exemplifies upstream control through captive semiconductor supply chains. Demant A/S occupies a position emphasizing wireless connectivity platform development. WS Audiology A/S anchors scale-driven manufacturing across distributed European and Asian production networks.
| Leading Market Players |
|---|
| Sonova |
| Demant A/S |
| WS Audiology A/S |
| GN Store Nord A/S |
| Starkey Laboratories, Inc. |
| Cochlear Ltd. |
| MED-EL Medical Electronics |
| Oticon Medical |
| MAICO Diagnostics GmbH |
| Others |
Supply & Pricing Matrix
Taiwanese foundry concentration for advanced DSP semiconductors compresses pricing power across all tiers while simultaneously forcing supply chain reconfiguration toward dual-source strategies. This single-source dependency widens spreads between premium Bluetooth-enabled systems and basic analog platforms, with cost pass-through capability separating integrated manufacturers from assembly-dependent competitors.
Pricing Analysis
German statutory reimbursement floors sustain premium pricing for severe-to-profound loss devices, while United States direct-to-consumer channels compress mid-tier spreads through subscription financing alternatives. Three-tier pricing structure across premium, standard, and economy levels separates flagship neural network-enabled models from basic amplification devices, with certification grade and after-sales service bundling as primary differentiation drivers. Cost compression in the economy tier intensifies because of Chinese assembly network competition. Price-sensitive rural Indian buyers contrast with least-sensitive Japanese metropolitan seniors prioritizing speech-in-noise performance.
Supply Chain Analysis
Extended payment terms from Taiwanese foundries strain working capital for hearing aid OEMs lacking captive semiconductor sourcing. Component fabrication concentrates in Taiwan, China, and South Korea, with final assembly drawing from Chinese Yangtze River Delta facilities and European precision manufacturing clusters. Raw material dependencies span lithium-ion cells, rare-earth magnets for transducers, and medical-grade titanium for implantable devices. Single-source vulnerability in advanced DSP chip fabrication exposes manufacturers to geopolitical disruption risk. Distribution runs through ENT clinic networks in Germany, audiology center chains in the United States, and direct-to-consumer platforms in metropolitan Asian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward institutional purchasers and direct-to-consumer aggregators, consolidating procurement authority away from fragmented independent audiology practices. This concentration demands defensive repositioning from incumbents while opening white-space entry points for specialized competitors.
For Market Incumbents: Pre-empt margin erosion by securing captive DSP supply through backward integration or long-term foundry offtake agreements, and accelerate remote-fitting platform deployment to capture subscription-based patient relationships before channel intermediaries consolidate control. The FDA OTC rule and EU MDR clinical evidence burden threaten audiologist-dependent revenue models, requiring channel diversification into direct-to-consumer and home care segments. For New Entrants and Emerging Players: Build out remote calibration software platforms targeting India's untreated rural population, and establish regulatory registration in Japan's expanded senior subsidy environment to capture mid-tier digital replacement cycles. India's sub-three-percent device penetration in rural districts represents the most penetrable geography, with cloud-based audiogram adjustment tools as the primary go-to-market angle bypassing ENT infrastructure constraints. For Investors and Strategic Acquirers: Cochlear implant specialists with pediatric bilateral implantation protocol positioning command scarcity premia in surgical device segments, offering acquisition exposure to the fastest-growing product category with defensible regulatory moats. Long-term viability hinges on reimbursement stability across German statutory health insurance and Japanese METI subsidy frameworks. The signal to monitor is FDA OTC channel share capture versus traditional audiologist volume retention.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission Pathway | OTC self-fitting classification accelerates direct-to-consumer market entry in the United States. |
| CE Marking Under MDR | Clinical evidence requirements extend time-to-market but favor incumbents with technical documentation. |
| Hospital System Partnership | Pediatric cochlear implant volume contracts with German university hospitals secure bilateral protocol adoption. |
| Software Companion Development | Remote fitting platforms reduce clinical overhead for distributed patient bases in rural India. |
| Reimbursement Strategy | Japanese METI subsidy alignment improves affordability capture for mid-tier digital models. |
Research Methodology
Operator-level perspectives from hearing aid manufacturing executives, ENT clinic procurement directors, audiology center owners, and biomedical engineers anchored the qualitative base, cross-referenced against FDA 510(k) filings, EU MDR technical documentation, NMPA registration databases, and statutory health insurance reimbursement schedules. Bottom-up installed base modeling and top-down macroeconomic demand projection were triangulated for consistency.
Scenario-bracketing across semiconductor supply disruption, regulatory pathway acceleration, and reimbursement policy revision framed the analytical envelope. Segmentation dimensions spanned product architecture, wireless connectivity standard, application severity, and end-user channel type. CAGRs were derived from replacement cycle analysis and penetration rate trajectories, with pediatric implantation protocol adoption and aging demographic concentration as category-specific forecast inputs.
Stress conditions across Taiwanese foundry allocation rationing, EU MDR clinical evidence timeline extension, and Indian rural distribution infrastructure gaps were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding reimbursement stability and technology substitution rates. Macroeconomic contraction, regulatory divergence between prescriptive and self-fitting pathways, or breakthrough in non-invasive hearing restoration would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
ENT
Global Pediatric Hearing Aids Market
ENT
Hearing Loss Disease Treatment Market
ENT
Hearing Amplifiers Market
ENT
Electrolarynx Market
ENT
Global Sinusitis Treatment Market
ENT
Denmark Hearing Aids Market
ENT
Europe Speech Therapy Market
ENT
Nasal Polyps Treatment Market
ENT
Nasal Sampling Lines Market
ENT
Surgical ENT Devices Market
ENT
Global Acute Otitis Media Treatment Market
ENT
North America Hearing Aid Market
ENT
Audiology Devices Market
ENT
ENT Disorder Treatment Market
ENT
Head and Neck Squamous Cell Carcinoma Market
ENT
Ear Health Market