
 Nasal Sampling Lines Market | 2026-2036
Nasal Sampling Lines Market Size, Share, and Industry Trends Forecast 2026-2036
Nasal Sampling Lines Market Foresight
ISO 13485 certification is bifurcating the competitive landscape into qualified suppliers and marginal participants. Medtronic leverages its vertical integration across respiratory care portfolios to sustain manufacturing scale. Fisher & Paykel Healthcare anchors its position through specialized product lines for high-flow nasal cannula applications. Smiths Medical differentiates via stringent quality systems that satisfy multiple regulatory jurisdictions.
Nasal sampling lines are flexible, single-use or reusable conduits, typically manufactured from medical-grade silicone or polyurethane, designed to transport exhaled gas from a patient's nares to monitoring equipment for capnography or gas analysis. The clinical testing application dominates current procurement volumes, while the home healthcare segment represents the fastest-growing demand pool as remote patient monitoring expands. Silicone-based lines command premium positioning due to biocompatibility and extended wear comfort, whereas plastic variants occupy high-volume, cost-sensitive contracts in emergency services.
FDA clearance requirements and EU MDR technical documentation obligations shape product development timelines and market access costs for all manufacturers. The country's national pharmaceutical regulator in Japan and Health Canada impose additional testing protocols that filter out undercapitalized entrants. Stakeholders must weigh certification investment against segment-specific margin profiles when allocating R&D resources.
Market Dynamics
Home healthcare expansion is restructuring procurement patterns across the nasal sampling lines market. Patients managing chronic respiratory conditions at home now demand comfortable, extended-wear designs that differ materially from acute-care specifications.
Growth Catalysts
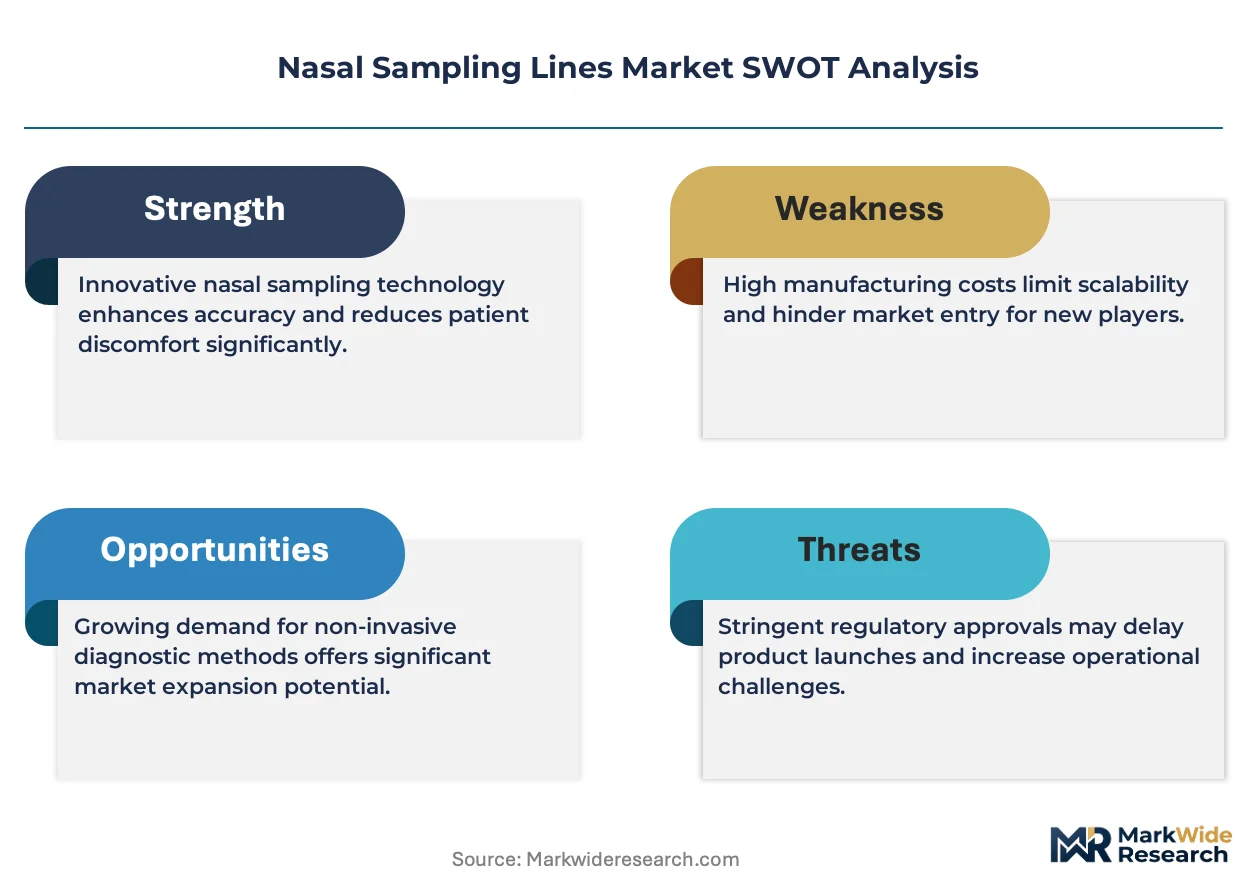
- EU MDR Compliance Deadlines:European regulatory pressure is filtering out marginal suppliers and concentrating procurement among ISO 13485-certified manufacturers with established technical documentation capabilities.
- High-Flow Nasal Cannula Adoption:Critical care units in the United States are upgrading gas delivery infrastructure, creating pull-through demand for compatible sampling interfaces.
- Remote Patient Monitoring:Telehealth platforms are integrating capnography into home-based respiratory management protocols, expanding the addressable patient population beyond hospital walls.
Market Restraints
- Medical-Grade Silicone Price Volatility:Petrochemical feedstock fluctuations and specialized polymer supply concentration in Germany and Japan compress margin stability for premium product lines.
- FDA 510(k) Timeline Extension:Enhanced scrutiny of respiratory device submissions has lengthened market access cycles, freezing capital deployment for development-stage entrants.
- Disposable Plastic Substitution Pressure:Single-use polymer lines face sustainability-driven procurement restrictions from hospital systems with carbon reduction mandates.
Strategic Opportunities
- Japan's Aging Demographic:METI-supported home medical device subsidies are creating reimbursement pathways for wearable respiratory monitors requiring specialized nasal interfaces.
- Capnography-Pulse Oximetry Convergence:Multi-parameter monitoring platforms are driving demand for integrated sampling lines that combine gas analysis with SpO2 sensing in single-patient-use configurations.
- Direct-to-Patient Distribution:Durable medical equipment suppliers are building e-commerce fulfillment capabilities that bypass traditional hospital procurement intermediaries.
Industry Challenges
- Biocompatibility Testing Bottlenecks:ISO 10993 cytotoxicity and sensitization studies require 8-14 month completion timelines, compressing product launch windows against regulatory deadlines.
- Legacy Anesthesia Monitor Integration:Hospital capital equipment refresh cycles lag behind sampling line innovation, forcing backward compatibility engineering that adds cost without differentiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nasal Sampling Lines Market |
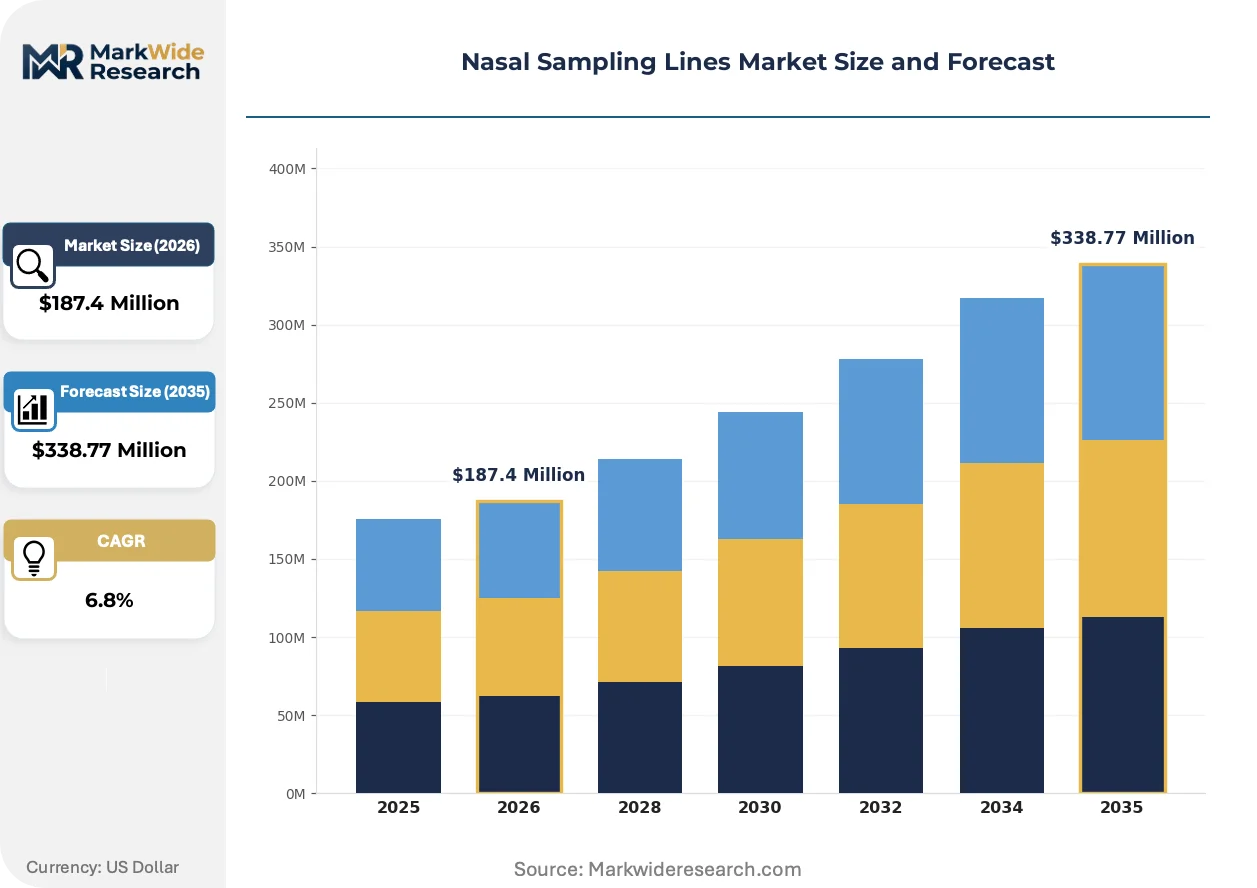
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Reusable, Multi-channel, Single-channel Application: Clinical Testing, Home Healthcare, Research Laboratories, Diagnostics End User: Hospitals, Laboratories, Clinics, Emergency Services Material: Plastic, Silicone, Polyurethane, Others |
| Companies Covered | Medtronic, Smiths Medical, Masimo, Teleflex, Vapotherm, Fisher & Paykel Healthcare, ResMed, Becton Dickinson, Salter Labs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nasal Sampling Lines Market Shifts & Advancements
Material science advances and regulatory harmonization efforts are simultaneously elevating performance standards and consolidating supplier bases. Three developments warrant particular attention from market participants.
Silicone-polyurethane hybrid formulations are bifurcating the product landscape between premium extended-wear lines and standard acute-care disposables. Home healthcare providers in the United States are specifying 72-hour wear durations for sleep apnea monitoring applications. This material transition is compressing margins for pure-play plastic extruders while rewarding compounders with in-house polymer science capabilities.
EU MDR Annex I general safety and performance requirements are mandating clinical evidence for all Class IIa respiratory accessories. Manufacturers must now generate post-market surveillance data that was previously exempt under the Medical Devices Directive. German notified bodies are experiencing 18-month backlog queues, forcing European market entrants to sequence regulatory submissions strategically.
Hospital procurement departments are consolidating respiratory consumables into multi-year enterprise agreements with price-volume mechanisms. Group purchasing organizations are absorbing regional distributor relationships that previously managed product selection at the facility level. This concentration is most visible in the southeastern United States, where health system mergers have reduced independent buying entities by 40 percent since 2020.
Nasal Sampling Lines Market Segmentation
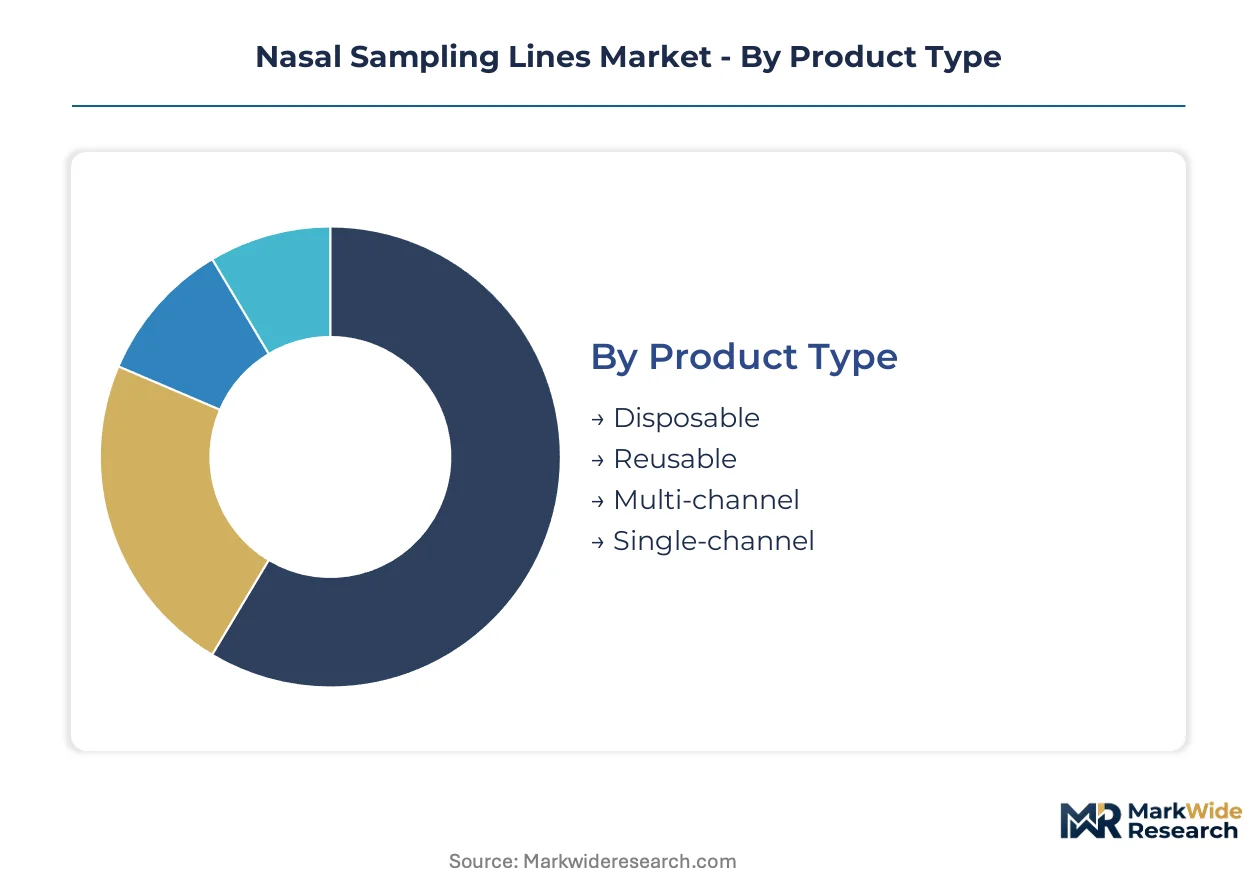
Segmentation in nasal sampling lines determines regulatory pathways, margin architecture, and channel access. Product durability, application setting, and material specification each create distinct procurement workflows and certification requirements.
Product Type:
Hospital procurement channels favor disposables for infection control, while home healthcare distributors stock reusables for cost-conscious chronic patients. Multi-channel configurations flow through critical care device suppliers integrating with anesthesia platforms.
- Disposable:Single-use polymer lines dominate emergency services and operating theater procurement. United States hospital systems with carbon reduction mandates are beginning to restrict pure-plastic variants, redirecting volume toward silicone-blend alternatives.
- Reusable:Medical-grade silicone construction supports 72-hour wear durations for sleep apnea monitoring. Home healthcare providers in Japan specify these for METI-subsidized wearable respiratory programs.
- Multi-channel:Integrated gas analysis and SpO2 sensing configurations serve high-flow nasal cannula upgrades in United States critical care units.
- Single-channel:Standard capnography interfaces occupy high-volume, cost-sensitive contracts through emergency medical services distributors.
Disposable lines dominate installed base. Reusable configurations are where expansion concentrates for remote patient monitoring.
Application:
Cost tiers separate acute-care specifications from extended-wear designs. Clinical testing commands premium pricing for ISO 13485-certified supply, while research laboratories accept non-medical-grade alternatives.
- Clinical Testing:Capnography during procedural sedation requires FDA-cleared interfaces with documented biocompatibility. United States hospital procurement networks concentrate volume here.
- Home Healthcare:Comfortable, extended-wear designs differ materially from acute-care specifications. Telehealth platforms integrating respiratory management are climbing the fastest in this segment.
- Research Laboratories:Non-patient-contact validation studies use non-certified variants, bypassing ISO 10993 testing timelines.
- Diagnostics:Pulmonary function testing equipment manufacturers specify custom connector geometries that fragment supplier bases.
Clinical testing commands revenue concentration. Home healthcare is where volume expansion accelerates.
End User:
Customer type determines technical documentation burden and purchasing centralization. Hospitals demand full regulatory packages; emergency services prioritize logistics reliability over certification depth.
- Hospitals:Enterprise agreements with group purchasing organizations absorb regional distributor relationships. Southeastern United States health system mergers have reduced independent buying entities substantially.
- Laboratories:Reference labs specify traceable calibration standards for gas analysis accuracy validation.
- Clinics:Outpatient procedural settings balance infection control against capital constraints.
- Emergency Services:Ambulance fleet procurement prioritizes packaging durability and rapid restocking logistics.
Hospitals dominate procurement value. Emergency services represent the most price-elastic demand pool.
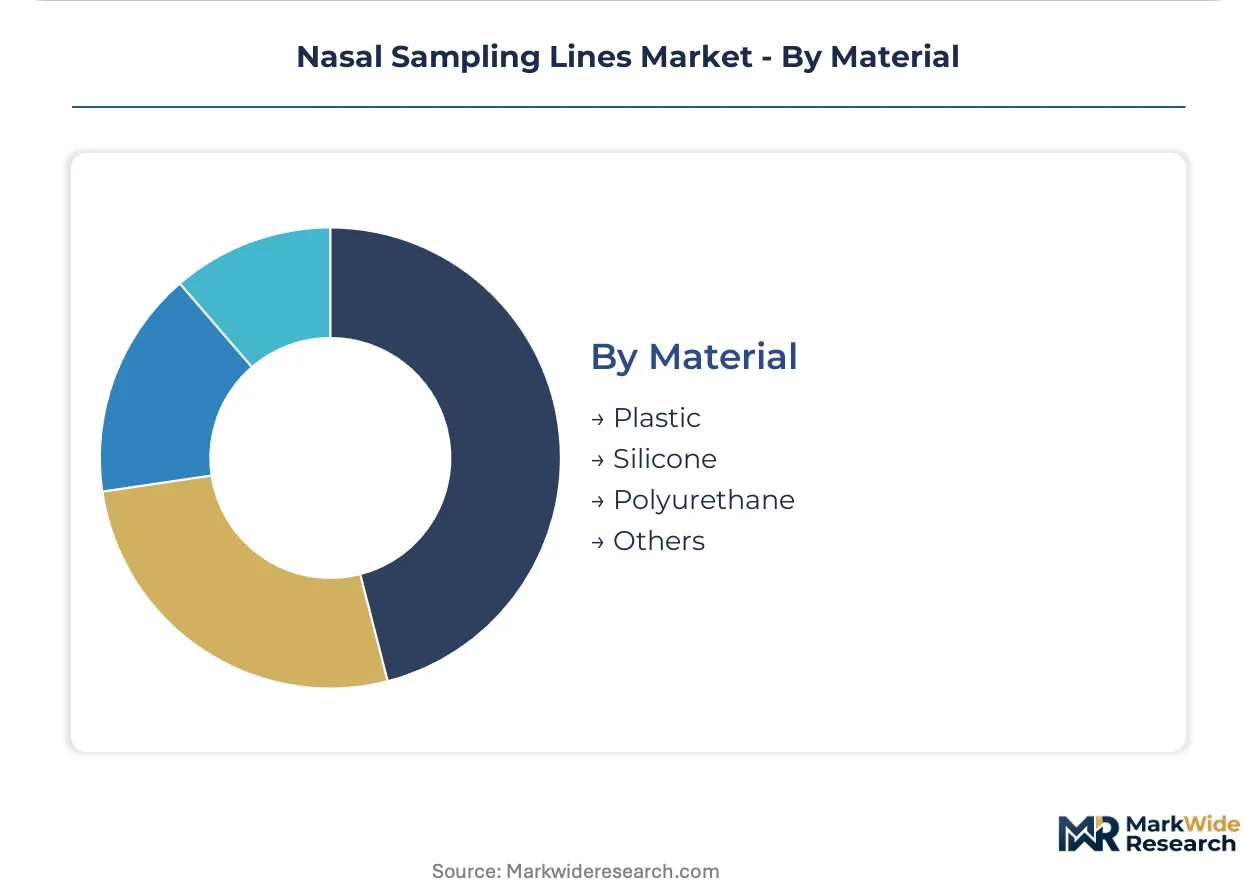
Material:
Supply concentration in Germany and Japan for specialized polymers creates margin volatility that stratifies pricing tiers. Material selection directly determines wear duration specifications and regulatory testing scope.
- Plastic:Polymer extruders face sustainability-driven procurement restrictions from hospital systems with carbon reduction mandates.
- Silicone:Biocompatibility and extended wear comfort command premium positioning. Petrochemical feedstock fluctuations compress margin stability.
- Polyurethane:Hybrid formulations with silicone are displacing pure-play plastic in sleep apnea monitoring applications.
- Others:Experimental biodegradable polymers remain confined to research procurement pending ISO 10993 completion.
Silicone dominates premium positioning. Polyurethane hybrids are where formulation investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's METI subsidies for home medical devices and Germany's notified body backlog under EU MDR are redirecting procurement flows across major markets. Hospital consolidation in the United States and aging demographics in East Asia are restructuring demand geography.
United States
Group purchasing organizations have absorbed 40 percent of independent hospital buying entities in the Southeast since 2020. FDA 510(k) scrutiny of respiratory device submissions has lengthened market access cycles. The Boston diagnostic device cluster anchors high-flow nasal cannula infrastructure upgrades.
Germany
Specialized polymer supply concentration creates margin volatility for silicone-dependent manufacturers. EMDR Annex I clinical evidence requirements and 18-month notified body queues filter out undercapitalized entrants. The Rhine-Ruhr industrial corridor hosts compounders with in-house polymer science capabilities.
Japan
METI-supported subsidies for wearable respiratory monitors are creating reimbursement pathways for extended-wear nasal interfaces. PMDA testing protocols impose additional qualification barriers beyond ISO 13485. The Kanto region around Tokyo concentrates home healthcare distributor networks.
China
NMPA regulatory harmonization with international standards is elevating documentation burdens for imported accessories. Domestic manufacturers are capturing emergency services procurement with cost-sensitive polymer lines. The Yangtze River Delta clusters medical-grade silicone extrusion capacity.
Canada
Health Canada testing protocols filter entrants lacking capital for parallel regulatory submissions. Remote patient monitoring adoption in Ontario and British Columbia is pulling through home healthcare-compatible designs. The Toronto-Waterloo corridor anchors telehealth platform integration.
Nasal Sampling Lines Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and manufacturing scale. The vendor base stratifies into ISO 13485-certified incumbents with technical documentation capabilities and marginal participants facing EU MDR exclusion. Three archetypes dominate: diversified respiratory portfolios, specialized high-flow interface developers, and quality-systems-focused contract manufacturers. M&A activity concentrates among hospital procurement networks, while capacity expansion targets silicone-polyurethane hybrid formulations.
Within the diversified portfolio tier, Medtronic exemplifies backward integration across respiratory care segments. Fisher & Paykel Healthcare occupies a position among specialized developers of high-flow nasal cannula applications. Smiths Medical anchors the quality-systems-focused archetype with multi-jurisdictional compliance capabilities.
| Leading Market Players |
|---|
| Medtronic |
| Smiths Medical |
| Masimo |
| Teleflex |
| Vapotherm |
| Fisher & Paykel Healthcare |
| ResMed |
| Becton Dickinson |
| Salter Labs |
| Others |
Supply & Pricing Matrix
Eighteen-month notified body queues for EU MDR certification concentrate procurement leverage among ISO 13485-qualified manufacturers with established technical documentation, compressing margin stability for silicone-dependent product lines while elevating pricing power for compounders with in-house polymer science capabilities.
Pricing Analysis
Certification level creates the primary spread between premium silicone-based lines and standard plastic variants, with FDA-cleared and CE-marked products commanding substantial premiums over non-certified alternatives. Three-tier pricing structure separates extended-wear silicone configurations from acute-care disposables and emergency services economy lines. Cost compression in plastic extrusion tiers is intensifying because hospital sustainability mandates restrict pure-polymer procurement. Emergency services distributors represent the most price-elastic demand pool, while home healthcare providers with METI-subsidized reimbursement show least sensitivity.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes and container availability constraints elevate inbound logistics costs for German and Japanese polymer suppliers feeding medical-grade silicone extrusion. Manufacturing concentrates in Germany, Japan, and the United States, with specialized polymer compounding anchored in the Rhine-Ruhr corridor. Raw material flows draw from petrochemical feedstocks, medical-grade silicone resins, and polyurethane precursors. Single-source vulnerability runs through German notified body concentration for EU MDR certification. Distribution runs through group purchasing organizations absorbing regional hospital distributor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Remote patient monitoring integration represents a high-growth disruption as telehealth platforms embed capnography into home-based respiratory management, with EU MDR compliance deadlines filtering out undercapitalized competitors and concentrating procurement among qualified suppliers.
For Market Incumbents: Secure ISO 13485 certification depth across multiple regulatory jurisdictions to defend against emerging contract manufacturers with streamlined quality systems. Backward integration into silicone-polyurethane hybrid formulation capabilities protects margin stability against petrochemical feedstock volatility. Hospital procurement network consolidation in the southeastern United States demands enterprise agreement positioning with price-volume mechanisms.
For New Entrants and Emerging Players: Anchor in Japan's METI-subsidized home medical device segment, where reimbursement pathways for wearable respiratory monitors create the most penetrable entry point for extended-wear nasal interfaces. Direct-to-patient e-commerce fulfillment bypassing traditional hospital procurement intermediaries offers a specific go-to-market angle. Research laboratory non-certified variants provide near-term revenue while ISO 10993 testing timelines progress.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical device parents with underoptimized respiratory consumables portfolios. Five-to-ten-year viability hinges on home healthcare volume expansion and capnography-pulse oximetry convergence adoption. Acquisition candidates with established German notified body relationships and silicone compounding capabilities warrant priority attention. Watch FDA 510(k) timeline extensions as an inflection indicator for capital deployment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Investment | Eighteen-month notified body queues in Germany filter out undercapitalized competitors concentrating procurement leverage. |
| Silicone-Polyurethane Hybrid Development | Seventy-two-hour wear specifications for sleep apnea monitoring displace pure-play plastic extruders from premium tiers. |
| Direct-to-Patient Distribution Buildout | E-commerce fulfillment capabilities bypass GPO intermediaries capturing margin from hospital procurement consolidation. |
| Hospital System Partnership | Enterprise agreements with southeastern United States health systems lock in volume through price-volume mechanisms. |
| Reimbursement Strategy | METI subsidy alignment in Japan creates sustainable demand pathways for wearable respiratory monitor interfaces. |
Research Methodology
A standing panel of hospital purchasing committee members, biomedical engineers, GPO contracts managers, and home healthcare distributors provided ongoing calibration across primary fieldwork and secondary validation. FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement contract registries, and medical device trade flow records supplied foundational triangulation. Bottom-up volume modeling across product type, application setting, material specification, and end-user category converged with top-down market sizing.
Consistency checks against external benchmarks validated analytical outputs across the projection horizon. Segmentation dimensions modeled include product durability tier, clinical versus home healthcare application, silicone-polyurethane-plastic material grade, and hospital-emergency services-laboratory end-user archetype. CAGRs derived from fitted growth curves incorporating high-flow nasal cannula adoption rates, remote patient monitoring penetration, and regulatory compliance timeline impacts.
Decision-makers should treat outputs as directional under sustained EU MDR implementation and home healthcare reimbursement stability assumptions; material deviation would warrant model refresh. Specific risk factors include FDA submission scrutiny intensification, medical-grade silicone supply disruption from German or Japanese polymer concentration, and hospital carbon mandate acceleration affecting plastic line procurement. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
ENT
North America Hearing Aid Market
ENT
Interventional ENT Devices Market
ENT
US Hearing Aids Market
ENT
Head and Neck Squamous Cell Carcinoma Market
ENT
Denmark Hearing Aids Market
ENT
Acute Sinusitis Market
ENT
ENT Laser Devices Market
ENT
Hearing Loss Disease Treatment Market
ENT
ENT Devices Market
ENT
ENT Disorder Treatment Market
ENT
Ear Health Market
ENT
Laryngeal Papillomatosis Treatment Market
ENT
Global Pediatric Hearing Aids Market
ENT
Nasal Polyps Treatment Market
ENT
Hearing Implants Market
ENT
ENT Examination Chair Market