
 ENT Examination Chair Market | 2026-2036
ENT Examination Chair Market Size, Share, and Industry Trends Forecast 2026-2036
ENT Examination Chair Market Analytics
Hospital procurement is tilting toward bundled equipment contracts that pair examination chairs with integrated diagnostic systems. ATMOS MedizinTechnik leverages its acoustic and visualization technology heritage to anchor premium positioning in European hospital networks. Global Surgical Corporation competes through geographic dominance in North American outpatient surgery centers, while Heinemann Medizintechnik specializes in ergonomic configurations for prolonged diagnostic procedures.
An ENT examination chair constitutes a purpose-built patient positioning device featuring motorized or manual height adjustment, backrest articulation, and headrest fixation mechanisms designed to enable direct visualization of the ear canal, nasal cavity, and oropharynx during otolaryngologic assessment. Electric chairs command the widest installed base among product types due to reimbursement alignment and staff ergonomic mandates, while pediatric chairs represent a concentrated margin pool where specialized sizing and safety interlocks justify premium positioning. Hydraulic technology persists in cost-sensitive installations, though electric adjustment systems are displacing legacy pneumatic mechanisms in new hospital construction.
The FDA enforces 510(k) clearance pathways for powered examination tables, while the EU Medical Device Regulation requires notified body certification and post-market surveillance for electric chairs sold in member states. ISO 13485 quality management standards shape supplier qualification criteria for public tenders across OECD markets. Stakeholders must monitor evolving electrical safety harmonization between IEC 60601-1 third edition requirements and national deviations as procurement specifications tighten.
Market Dynamics
Electric adjustment systems are displacing hydraulic mechanisms across hospital procurement specifications, driven by staff ergonomic mandates and reimbursement alignment for powered positioning equipment. This technological transition concentrates vendor qualification around ISO 13485 certification and IEC 60601-1 electrical safety compliance.
Growth Catalysts
- EU Medical Device Regulation:MDR certification requirements for electric chairs are filtering out uncertified competitors, consolidating procurement toward established manufacturers with notified body relationships.
- Outpatient clinic expansion:Rising patient volumes in ambulatory settings are accelerating replacement cycles for adjustable examination chairs with integrated headrest fixation.
- Ergonomic mandates:Hospital occupational safety frameworks in Germany and France are requiring powered height adjustment to reduce staff musculoskeletal injury claims.
Market Restraints
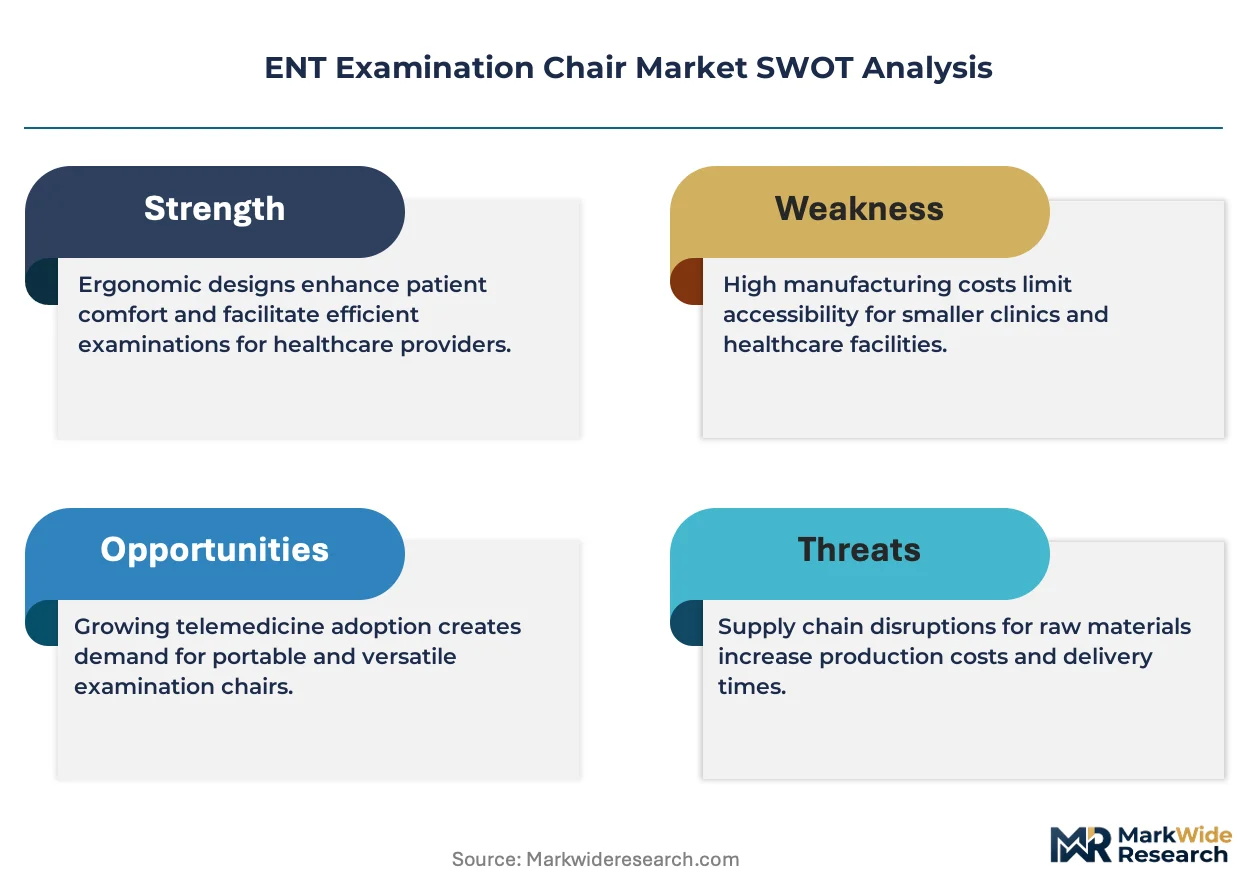
- Stainless steel and linear actuator costs:Input price volatility for motorized positioning components compresses margins on mid-range electric chair configurations.
- Notified body capacity constraints:Limited EU MDR certification bandwidth creates 12-18 month approval backlogs for new market entrants.
- Refurbished equipment channels:Secondary markets for reconditioned hydraulic chairs extend replacement cycles in cost-sensitive municipal hospital systems.
Strategic Opportunities
- Pediatric specialization:Underserved sizing configurations with safety interlocks for otolaryngologic assessment of children present premium positioning potential.
- Telemedicine integration:Chairs with embedded camera mounts and data connectivity are capturing specification share in hybrid care delivery models.
- Indian outpatient infrastructure:PLI scheme incentives for medical device manufacturing are lowering import barriers for European and North American suppliers.
Industry Challenges
- IEC 60601-1 third edition harmonization:Divergent national electrical safety deviations require redundant testing protocols for multi-country product registrations.
- Biomedical technician shortages:Hospital maintenance departments lack trained staff for troubleshooting programmable positioning controllers, extending service response times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ENT Examination Chair Market |
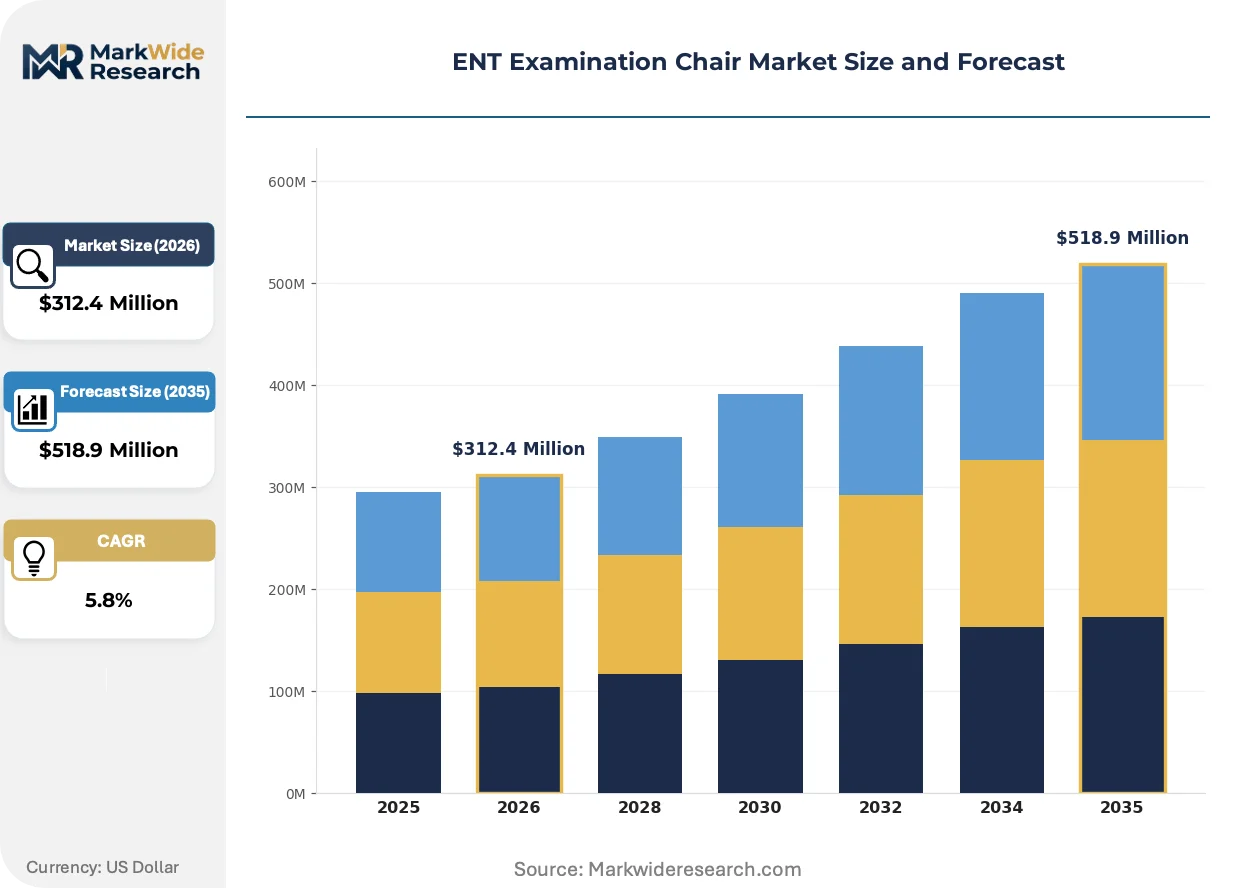
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Chairs, Electric Chairs, Adjustable Chairs, Pediatric Chairs End User: Hospitals, Outpatient Clinics, Diagnostic Labs, ENT Specialty Clinics Technology: Hydraulic, Pneumatic, Electric, Manual Adjustment Material: Steel, Aluminum, Plastic, Upholstery |
| Companies Covered | Medical Experts Group, Medstar, Xuzhou Pengkang Electrical Equipment, TEYCO Med, SPOMC, OPTOMIC, ATMOS MedizinTechnik, Global Surgical Corporation, Heinemann Medizintechnik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ENT Examination Chair Market Evolving Landscape
Diagnostic visualization technology is converging with patient positioning equipment, creating specification demand for chairs that accommodate integrated endoscopic and microscopic systems. This integration pressure favors vendors with heritage in acoustic and optical equipment over pure-play furniture manufacturers.
Remote technical assistance platforms are virtualizing service delivery for electric chair maintenance, enabling real-time diagnostic support without on-site technician dispatch. Large hospital networks in Germany are piloting these systems to reduce equipment downtime in high-volume ENT departments. The technology is virtualizing traditional aftermarket service revenue models toward subscription-based remote monitoring.
FDA 510(k) clearance pathways for powered examination tables are tightening predicate device requirements, extending pre-market notification preparation timelines. Device manufacturers are responding by consolidating 510(k) submissions into portfolio-wide clearances rather than individual product approvals. Electric chair categories with novel positioning algorithms face heightened scrutiny compared to incremental mechanical improvements.
Group purchasing organizations are consolidating equipment specification authority, displacing individual hospital procurement autonomy with standardized vendor lists. Outpatient surgery centers in the United States are experiencing this concentration most acutely, as regional GPO contracts bundle examination chairs with diagnostic system purchases. The shift compresses price negotiation leverage for standalone chair buyers while favoring suppliers with broad equipment portfolios.
ENT Examination Chair Market Segmentation
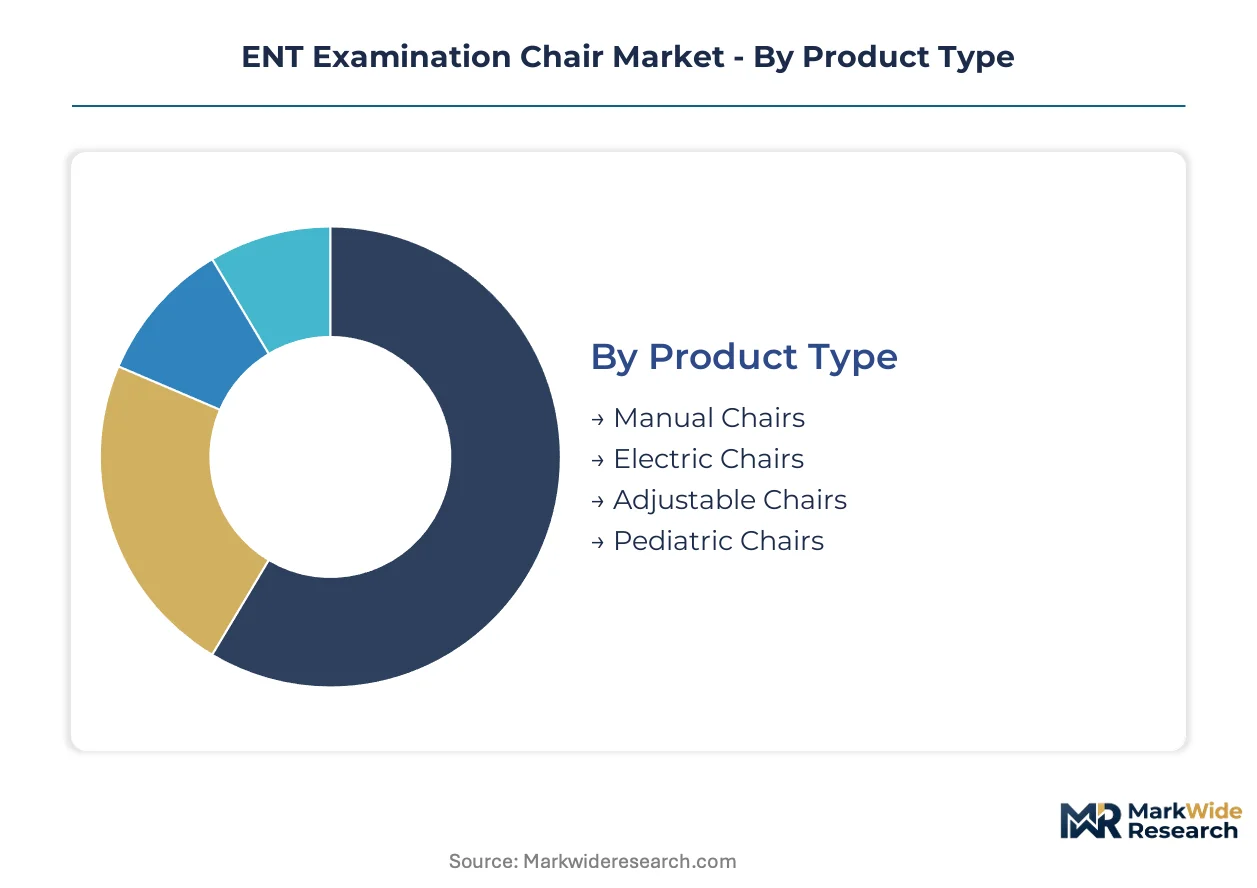
Procurement specifications for ENT examination chairs diverge sharply across care settings, with electric positioning systems commanding hospital tenders while manual configurations persist in cost-constrained installations. Understanding these segment boundaries clarifies where technology premiums justify investment versus where durability and basic functionality dominate purchasing criteria.
Product Type:
Use cases span from high-throughput hospital departments requiring programmable positioning to specialized pediatric configurations demanding safety interlocks and anatomical sizing adaptations.
- Electric Chairs:Motorized height adjustment, backrest articulation, and programmable memory positions define this category. Hospital procurement in Germany and France concentrates here, driven by occupational safety mandates for powered positioning equipment that reduces staff musculoskeletal injury claims.
- Pediatric Chairs:Downsized dimensions with integrated safety restraints and child-appropriate headrest fixation mechanisms characterize these specialized units. ENT specialty clinics in North America and Europe generate concentrated demand, where specialized sizing justifies premium positioning and margin capture.
- Manual Chairs:Mechanical crank or lever adjustment systems without powered components serve cost-sensitive installations.
- Adjustable Chairs:Modular configurations allowing component-level customization for varying diagnostic procedures.
Established volume favors electric chairs; emerging adoption favors pediatric specialization.
End User:
Customer types range from capital-rich hospital networks pursuing bundled equipment contracts to independent diagnostic labs prioritizing single-unit durability over integrated system compatibility.
- Hospitals:Large-scale procurement departments with standardized specifications for powered positioning, infection control surfaces, and diagnostic system integration. Group purchasing organization consolidation in the United States increasingly bundles examination chairs with endoscopic equipment.
- Outpatient Clinics:Ambulatory settings experiencing rapid patient volume expansion drive replacement cycles for adjustable chairs with rapid patient turnover features. These facilities in Germany and the United States represent the steepest expansion trajectory for electric adjustment systems.
- Diagnostic Labs:Standalone imaging and testing facilities with limited otolaryngologic specialization.
- ENT Specialty Clinics:Concentrated demand for procedure-specific configurations including microscope integration mounts.
Procurement concentration tilts toward hospitals; volume growth accelerates fastest in outpatient clinics.
Technology:
Technology selection reflects a transition trajectory from legacy pneumatic and hydraulic systems toward electric actuation, constrained by installed base longevity and maintenance technician training gaps.
- Electric:Linear actuator-driven positioning with programmable controllers and memory functions. New hospital construction specifications in OECD markets increasingly mandate this technology, displacing legacy alternatives through IEC 60601-1 electrical safety compliance requirements.
- Hydraulic:Fluid-pressure adjustment mechanisms with manual pump activation. Municipal hospital systems in Southern Europe and secondary markets extend replacement cycles through refurbished equipment channels.
- Pneumatic:Compressed gas-powered positioning, now largely obsolete outside legacy installed bases.
- Manual Adjustment:Purely mechanical systems without powered assistance, persisting in lowest-cost procurement tiers.
Technology transition favors electric systems; installed base inertia preserves hydraulic presence.
Material:
Material specifications balance infection control imperatives, structural load requirements, and surface durability against procurement cost constraints and upholstery replacement cycle economics.
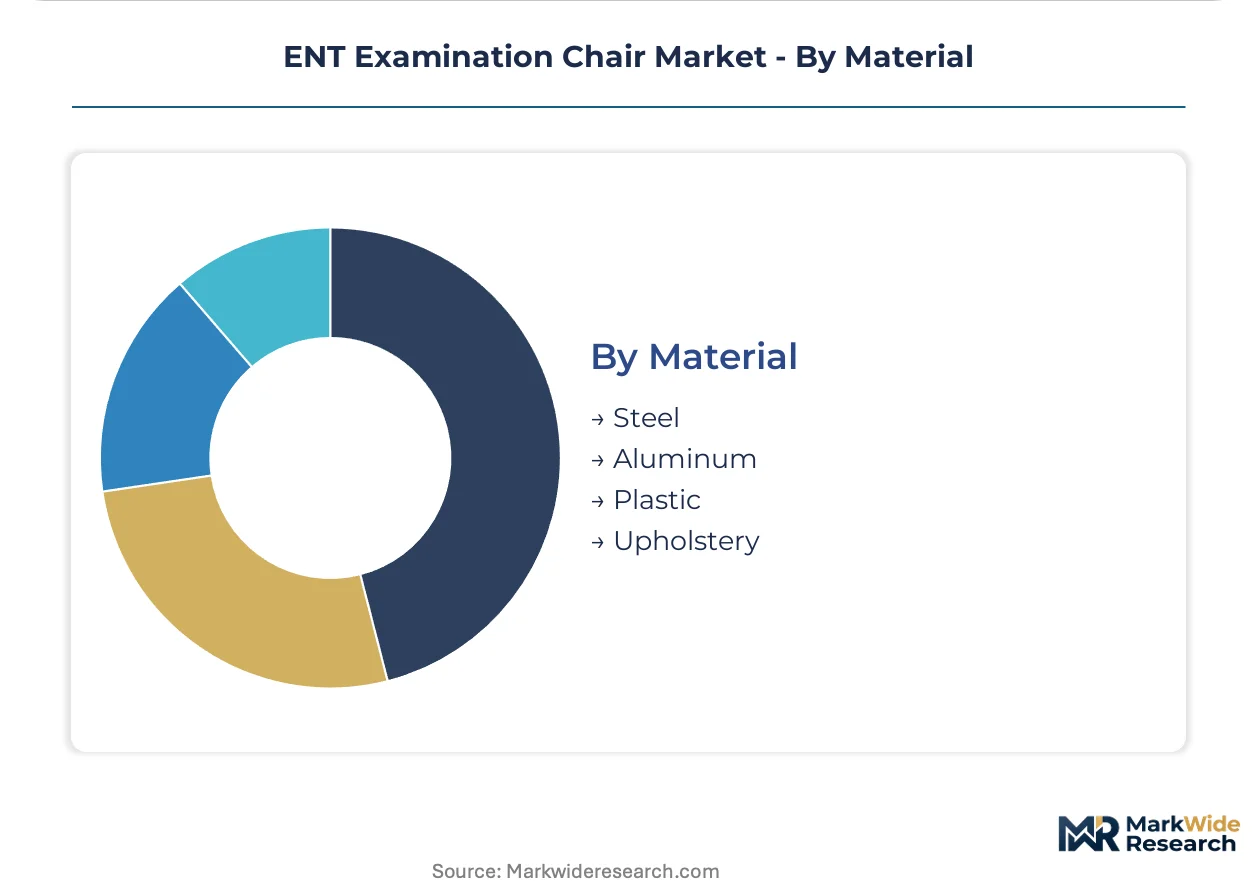
- Steel:Primary structural framing material with powder-coated or stainless finishes for corrosion resistance. Input price volatility for specialty steel grades compresses margins on mid-range electric chair configurations.
- Upholstery:Medical-grade vinyl and antimicrobial fabric surfaces requiring frequent replacement in high-utilization settings. Outpatient clinics in Germany specify extended-warranty upholstery packages to manage lifecycle costs.
- Aluminum:Lightweight alternative for portable or mobile chair configurations.
- Plastic:Component-level applications for non-structural elements and pediatric safety features.
Structural integrity depends on steel; surface economics hinge on upholstery durability specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors Germany's central role in European medical device distribution, channeling precision-engineered components from Mittelstand fabricators to hospital procurement networks across the continent.
United States
Outpatient surgery centers in Texas and Florida drive specification demand for powered positioning systems with integrated diagnostic mounts. FDA 510(k) clearance pathways for powered examination tables tighten predicate requirements, extending pre-market timelines for novel positioning algorithms. The Dallas-Fort Worth metroplex concentrates GPO contract administration, bundling examination chairs with endoscopic equipment purchases.
Germany
Hospital outpatient departments in Bavaria and North Rhine-Westphalia accelerate replacement cycles for electric adjustment systems. EU Medical Device Regulation notified body certification filters procurement toward established manufacturers with technical documentation capabilities. The Tuttlingen surgical instrument cluster supplies precision actuators and fixation mechanisms to chair assemblers throughout the region.
France
ENT specialty clinics in the Île-de-France region specify ergonomic configurations for prolonged diagnostic procedures. Hospital occupational safety frameworks mandate powered height adjustment to reduce staff musculoskeletal injury claims. The Paris-Saclay medical technology corridor anchors service delivery networks for high-volume hospital departments.
India
PLI scheme incentives for medical device manufacturing lower import barriers for European and North American suppliers entering outpatient infrastructure expansion. Maharashtra and Karnataka state health procurement tenders specify electric chairs for new district hospital constructions. The Mumbai-Pune pharmaceutical and medical device belt channels distribution to secondary cities.
Japan
Metropolitan hospital networks in Tokyo and Osaka prioritize infection control surfaces and programmable memory positions for high-throughput departments. METI medical device quality standards shape supplier qualification criteria for public tenders. The Kansai region's precision manufacturing base supplies linear actuator components to domestic and regional assemblers.
ENT Examination Chair Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: heritage acoustic equipment vendors with positioning integration capabilities, geographic-focused distributors serving outpatient surgery networks, and ergonomic specialists targeting prolonged diagnostic workflows. Dominant competitive moves include portfolio diversification into bundled diagnostic system contracts and strategic partnerships with group purchasing organizations to secure specification authority in consolidated procurement channels.
Within the heritage equipment tier, ATMOS MedizinTechnik GmbH and Global Surgical Corporation exemplify divergent geographic anchoring strategies. Heinemann Medizintechnik GmbH occupies a specialized position in ergonomic configuration development. Xuzhou Pengkang Electrical Equipment represents the Chinese fabrication base serving cost-sensitive procurement tiers. Medstar and TEYCO Med sit within regional distribution-focused archetypes.
| Leading Market Players |
|---|
| Medical Experts Group |
| Medstar |
| Xuzhou Pengkang Electrical Equipment |
| TEYCO Med |
| SPOMC |
| OPTOMIC |
| ATMOS MedizinTechnik |
| Global Surgical Corporation |
| Heinemann Medizintechnik |
| Others |
Value Network & Pricing Analysis
EU MDR notified body capacity constraints function as a regulatory chokepoint that simultaneously widens pricing spreads between certified and uncertified tiers while compressing supply chain options toward established manufacturers with technical documentation capabilities. This bottleneck forces procurement departments into longer lead times and premium positioning for compliant equipment.
Pricing Analysis
Volume-discount tiering structures dominate hospital procurement, with group purchasing organizations extracting graduated concessions based on annual unit commitments. Pricing stratifies across premium electric configurations with full diagnostic integration, standard powered chairs meeting basic IEC 60601-1 compliance, and economy hydraulic alternatives for cost-constrained municipal systems. Cost compression in mid-range electric tiers is intensifying because stainless steel and linear actuator input volatility erodes assembler margins. Outpatient surgery centers exhibit the highest price sensitivity due to capital constraints, while integrated hospital networks prioritize total cost of ownership over acquisition price.
Supply Chain Analysis
Upstream feedstock for precision actuators and medical-grade steel draws from Germany's Tuttlingen surgical instrument cluster, China's component fabrication base, and Japan's Kansai precision manufacturing region. Critical inputs include specialty stainless steel grades, linear actuator assemblies, and programmable positioning controllers. Single-source vulnerability concentrates in European notified body certification bandwidth, where limited auditor availability creates approval backlogs. Distribution runs through regional medical device distributors serving hospital procurement networks, with direct manufacturer relationships dominating large GPO contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric adjustment systems are displacing hydraulic mechanisms across OECD hospital construction specifications, creating a high-growth disruption window as regulatory mandates for powered positioning equipment accelerate replacement cycles. This technological inflection concentrates competitive advantage around ISO 13485 certification and IEC 60601-1 electrical safety compliance capabilities.
For Market Incumbents: Pre-empt margin erosion in mid-range electric tiers by securing captive supply of linear actuators through backward integration into precision component manufacturing. Consolidate specification authority with group purchasing organizations before emerging entrants establish notified body relationships, as EU MDR certification requirements filter procurement toward established technical documentation capabilities. For New Entrants and Emerging Players: Pursue pediatric specialization as the most penetrable white-space segment, where undersized configurations with safety interlocks command premium positioning and limited incumbent focus. Target Indian outpatient infrastructure expansion under PLI scheme incentives, leveraging lowered import barriers to establish distribution partnerships with Maharashtra and Karnataka state health procurement systems. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors manufacturers with heritage acoustic and optical equipment integration capabilities over pure-play furniture assemblers. Acquisition targets should demonstrate established notified body relationships and ISO 13485 certification infrastructure. Watch FDA 510(k) clearance pathway tightening as the inflection signal indicating regulatory barrier elevation and consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Certification Investment | EU MDR technical documentation capabilities filter procurement toward compliant manufacturers with established auditor relationships. |
| Diagnostic System Integration Partnership | ATMOS MedizinTechnik leverages acoustic heritage to anchor bundled contracts with European hospital networks. |
| Pediatric Configuration Development | Specialized sizing with safety interlocks captures concentrated margin pools in ENT specialty clinics. |
| Remote Technical Assistance Platform | German hospital networks pilot virtualized service delivery to reduce equipment downtime in high-volume departments. |
| PLI Scheme Market Entry | European suppliers exploit Indian manufacturing incentives to access Maharashtra and Karnataka state procurement tenders. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across hospital purchasing committees, biomedical engineering departments, GPO contracts managers, and ENT clinic administrators. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body certification records, hospital procurement tender documents, and group purchasing organization contract disclosures. Bottom-up unit demand estimates triangulated against top-down market sizing from equipment manufacturer revenue disclosures.
Calibration against historical replacement cycle data and regulatory implementation timelines anchored the analytical framework across the projection horizon. Segmentation modeling spanned product type, end-user setting, technology platform, and geographic regulatory cluster. CAGRs were derived from installed base turnover rates and new construction specification trends. Forecast inputs incorporated EU MDR transition timelines and outpatient clinic expansion trajectories in target markets.
Macroeconomic conditions sit as an overlay; deviation in healthcare capital expenditure budgets and medical device input commodity prices would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory implementation pace and reimbursement alignment for powered positioning equipment. Cross-checking against hospital construction pipeline data and GPO contract renewal schedules is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
ENT
Laryngeal Papillomatosis Treatment Market
ENT
Audiology Devices Market
ENT
Head and Neck Squamous Cell Carcinoma Market
ENT
Europe Hearing Aids Market
ENT
ENT Devices Market
ENT
Nasal Sampling Lines Market
ENT
ENT Laser Devices Market
ENT
Europe Speech Therapy Market
ENT
Hearing Amplifiers Market
ENT
North America Hearing Aid Market
ENT
Acute Sinusitis Market
ENT
Denmark Hearing Aids Market
ENT
Global Audiological Devices Market
ENT
Surgical ENT Devices Market
ENT
Nasal Polyps Treatment Market
ENT
Interventional ENT Devices Market