
 Arrow LED Displays Market | 2026-2036
Arrow LED Displays Market Size, Share, and Industry Trends Forecast 2026-2036
Arrow LED Displays Market Analytics
Aftermarket service revenue is narrowing as manufacturers embed predictive diagnostics into arrow LED display systems. Daktronics leverages its North American sports venue dominance to sustain recurring calibration contracts. Leyard Opto-Electronic anchors its position through captive LED chip sourcing from affiliated foundries. Absen competes aggressively on outdoor display modularity for rapid-deployment transportation projects.
An arrow LED display is a directional electronic signage system composed of light-emitting diode matrices arranged in arrow configurations, typically operating at pixel pitches between 1.5mm and 16mm depending on viewing distance requirements. These displays serve critical wayfinding, traffic management, and commercial guidance functions where instantaneous visual direction transmission supersedes static signage. Outdoor displays command durable margin pools due to IP65 enclosure requirements and thermal management complexity, while transparent displays represent the fastest-growing product category as retailers integrate glass-facade digital layering. COB technology leads in high-reliability transportation applications where solder-joint failure rates must approach zero, whereas SMD retains cost advantages in budget-sensitive corporate office deployments.
The US Federal Highway Administration shapes product standards through Manual on Uniform Traffic Control Devices compliance requirements for roadway arrow displays, while the EU Ecodesign Directive and CE marking govern energy consumption and electromagnetic compatibility across European installations. China's GB standards and MIIT certification protocols create divergent testing burdens for manufacturers seeking cross-border market access. Stakeholders must monitor regulatory fragmentation between NHTSA roadway specifications and emerging EU right-to-repair mandates affecting display module replaceability.
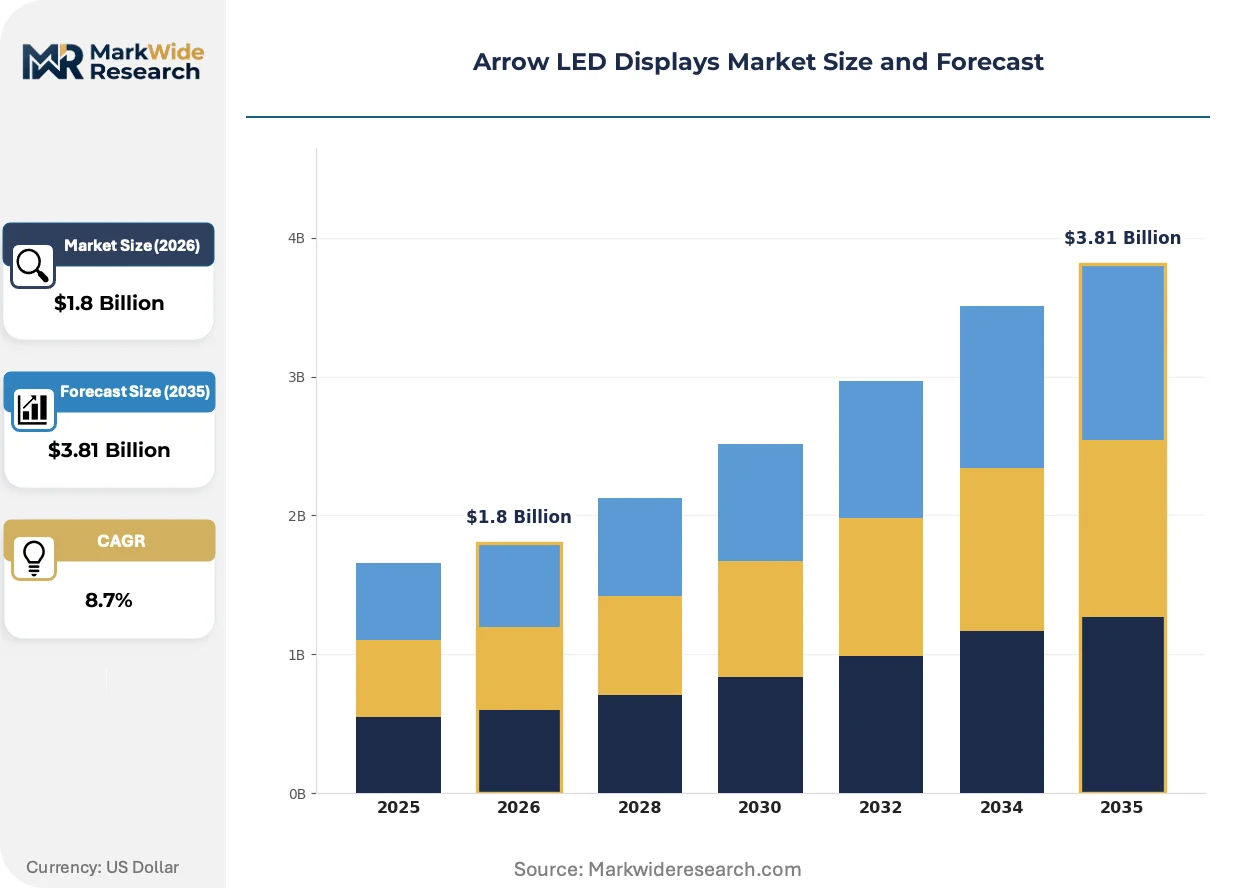
Market Dynamics
COB and Mini-LED architectures are collapsing the historical cost-reliability tradeoff in arrow LED displays, forcing manufacturers to abandon legacy SMD production lines or absorb margin compression from stranded capacity.
Growth Catalysts
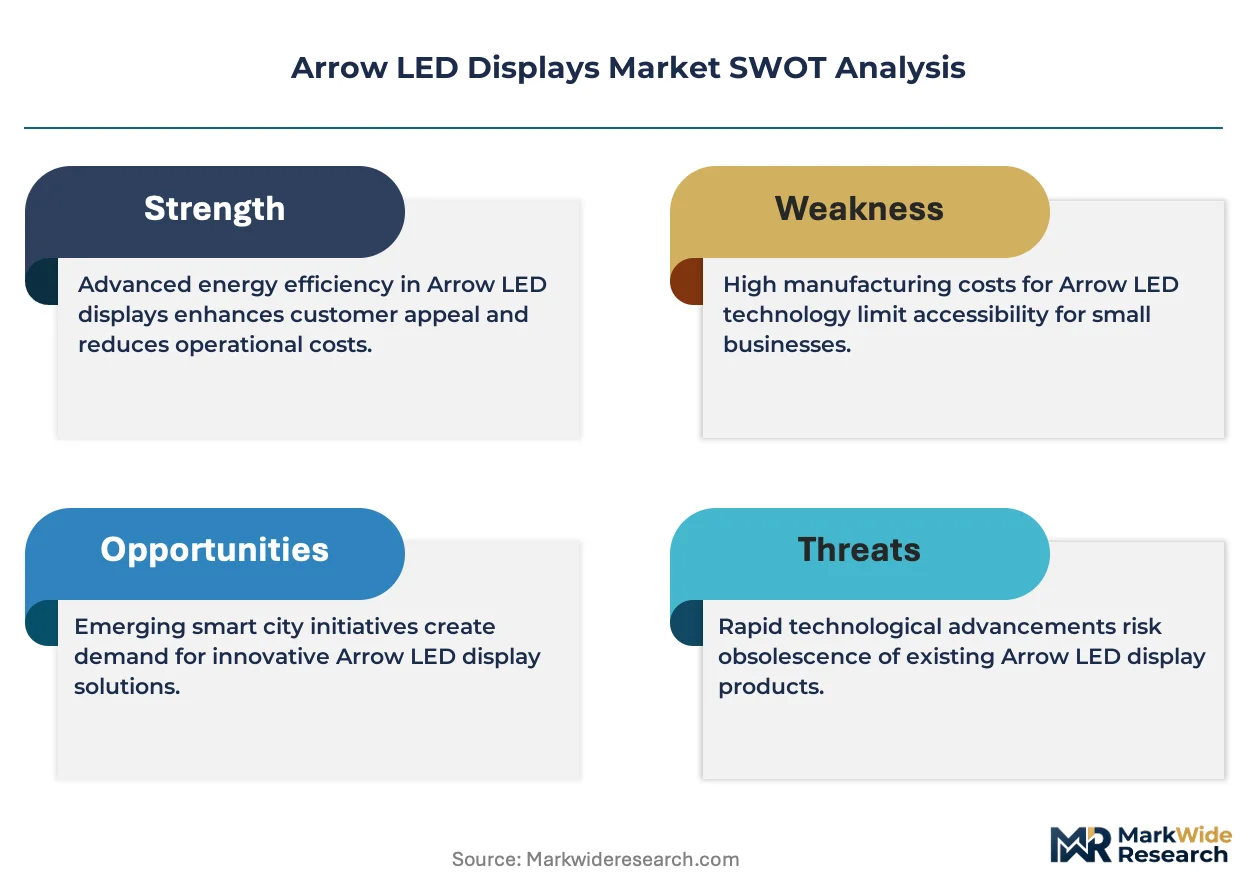
- EU Ecodesign Directive:Energy-efficiency mandates in Germany and France are accelerating digital signage replacement cycles across transportation authorities, creating pull-through demand for low-power arrow configurations.
- COB packaging technology:Chip-on-board modules eliminate solder-joint failure modes entirely, satisfying zero-fault requirements in tunnel and highway deployments where maintenance access is severely restricted.
- Shenzhen manufacturing cluster:Concentrated LED die and driver IC production in China's Pearl River Delta compresses component lead times from weeks to days for global display integrators.
Market Restraints
- Indium phosphide substrate volatility:Red LED epitaxy depends on constrained III-V semiconductor supply chains concentrated in Japanese and Taiwanese foundries, exposing margins to raw material price swings.
- IP65 enclosure cost structure:Outdoor arrow displays require gasket-sealed aluminum housings and conformal-coated PCBs that add 40-60% BOM cost premium versus indoor equivalents.
- CE marking electromagnetic compatibility:European EMC testing protocols for roadway signage impose 12-16 week certification timelines that delay project revenue recognition.
Strategic Opportunities
- Transparent LED glass integration:Retail facade applications in South Korea and UAE are adopting see-through arrow overlays that preserve natural lighting while embedding dynamic wayfinding.
- Right-to-repair regulatory tailwind:Emerging EU mandates for modular component replaceability favor arrow display architectures with field-swappable driver boards and LED tile matrices.
- Edge computing convergence:Integration of NVIDIA Jetson and Qualcomm Vision Intelligence platforms enables real-time content adaptation based on pedestrian flow analytics.
Industry Challenges
- Thermal engineering talent scarcity:Mini-LED density increases heat flux requirements beyond traditional signage engineering competencies, forcing recruitment from automotive lighting and data center cooling sectors.
- Legacy DMX512 protocol integration:Transportation authorities in Japan and North America maintain decades-old control infrastructure, requiring costly protocol bridge development for smart display connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Arrow LED Displays Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor Displays, Outdoor Displays, Transparent Displays, Digital Billboards Technology: SMD, COB, Mini-LED, Micro-LED Application: Advertising, Sports Events, Retail Signage, Transportation End User: Retailers, Event Organizers, Transportation Authorities, Corporate Offices |
| Companies Covered | Daktronics, Leyard Opto-Electronic, Absen, Unilumin, Barco, Samsung Electronics, LG Electronics, Asian Electronics, Kingbright, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Arrow LED Displays Market Evolving Landscape
Arrow LED display evolution centers on three vectors: physical form factor disruption, regulatory-driven energy performance floors, and procurement model compression that unbundles hardware from service obligations.
Chip-on-board (COB) LED technology is collapsing the pixel pitch barrier between indoor and outdoor applications. Transportation departments in Germany and Japan now specify 2.5mm pitch modules for covered highway gantries previously limited to 10mm SMD products. The structural consequence is a single product platform spanning both environments, eliminating SKU proliferation but demanding universal IP ratings.
EU F-Gas Regulation phase-down schedules are mandating refrigerant-free thermal management in large-format outdoor displays. Manufacturers are responding with graphene-enhanced heat spreaders and passive chimney ventilation that eliminate compressor-based cooling systems. This regulatory pressure most affects southern European deployments where ambient temperatures exceed 40°C seasonally.
Buying committees at municipal transportation authorities are unbundling decade-long service contracts from initial hardware procurement. Daktronics and Leyard now compete on modular field-replaceability metrics rather than total-cost-of-ownership bundling. This pattern is most visible in US state DOT RFPs where separate maintenance awards now follow hardware selection by 6-12 months.
Arrow LED Displays Market Segmentation
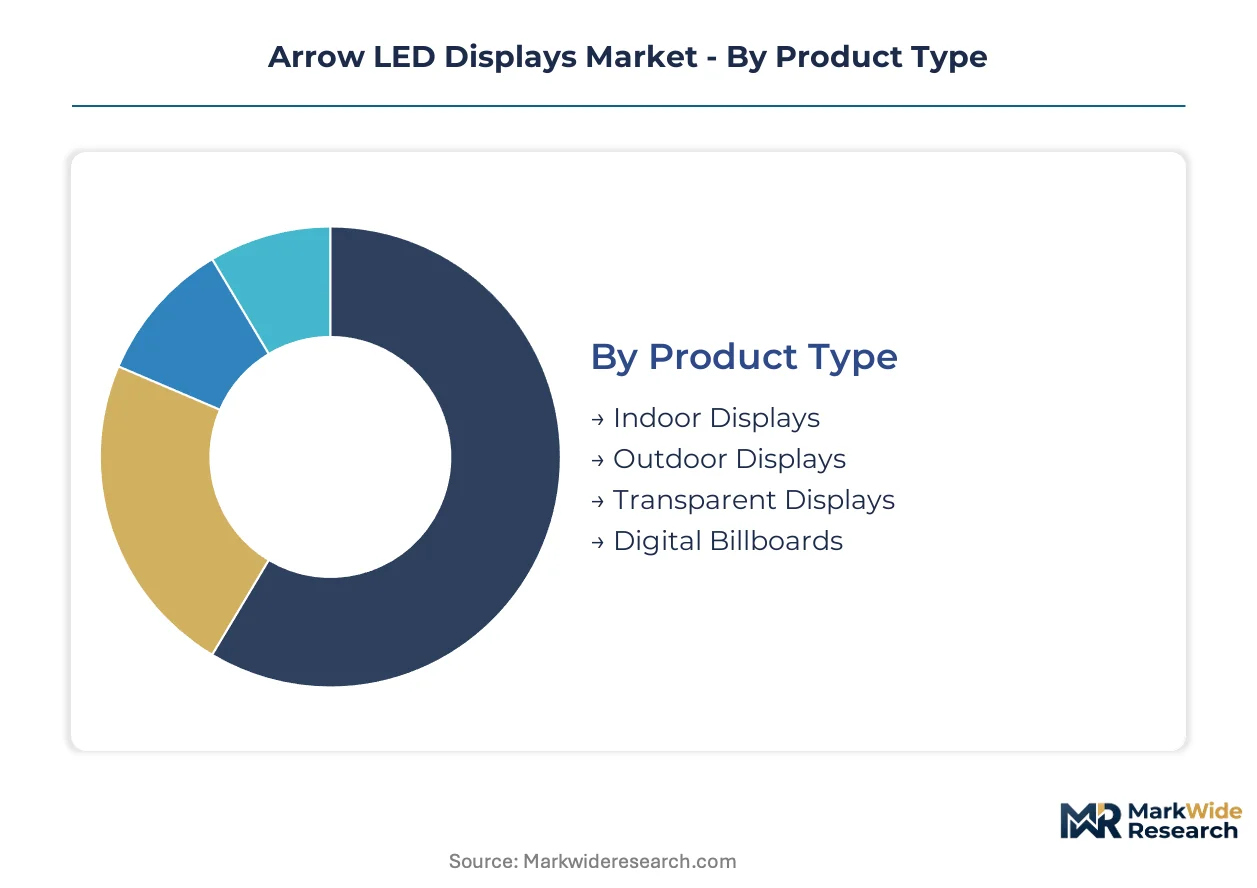
Arrow LED display procurement patterns diverge sharply across environmental exposure requirements, packaging architectures, and regulatory compliance burdens. Understanding these fault lines reveals where margin pools concentrate and which technology transitions reshape competitive positioning.
Product Type:
Environmental exposure requirements determine enclosure specifications, thermal management complexity, and IP rating investments across the four product categories.
- Indoor Displays:Operating at 1.5mm to 4mm pixel pitch with standard aluminum housings and passive cooling, these units serve corporate lobbies and retail interiors where ambient conditions remain controlled. Demand clusters in South Korean department store renovations and German automotive showroom deployments driven by CE marking energy-efficiency mandates.
- Outdoor Displays:IP65-rated enclosures with conformal-coated PCBs and gasket-sealed aluminum housings withstand temperature extremes from -40°C to 60°C. Transportation authorities in Japan and the US Federal Highway Administration specify these for highway gantries and tunnel installations where maintenance access is severely restricted.
- Transparent Displays:See-through LED matrices mounted on glass substrates preserve natural lighting while embedding dynamic wayfinding. Retail facade applications in the UAE and South Korea are adopting these for premium storefront integration.
- Digital Billboards:Large-format installations exceeding 100 square meters require structural engineering certification and local permitting compliance. These command extended procurement cycles due to municipal zoning review processes.
Outdoor Displays hold installed capacity. Transparent Displays are rotating up the share rankings.
Technology:
Packaging architecture selection determines solder-joint reliability, pixel density ceilings, and thermal flux management requirements.
- SMD:Surface-mount devices with discrete LED packages on PCB substrates retain cost advantages in budget-sensitive indoor corporate deployments. German office fit-out contractors specify these for meeting room wayfinding where fault tolerance exceeds maintenance access constraints.
- COB:Chip-on-board modules eliminate wire bonds and solder joints entirely by mounting bare LED dies directly on substrate. Japan's transportation authorities mandate COB for tunnel installations where zero-failure specifications override procurement cost sensitivity.
- Mini-LED:Sub-200-micron LED dies enable 0.9mm to 1.5mm pixel pitches with localized dimming zones. South Korean broadcast studios and premium retail flagships in the UAE are driving adoption where visual performance differentiation commands price premiums.
- Micro-LED:Sub-50-micron self-emitting dies promise theoretical lifetime advantages but remain constrained by mass transfer yield challenges and indium phosphide substrate costs.
SMD maintains volume leadership. Mini-LED is climbing the fastest as premium specifications displace legacy architectures.
Application:
Use-case requirements determine brightness specifications, content refresh rates, and integration complexity with external control systems.
- Advertising:High-brightness configurations exceeding 5,000 nits compete for visibility in direct sunlight. Digital out-of-home networks in the US and France require FCC and CE marking compliance for electromagnetic emissions in dense urban environments.
- Sports Events:Perimeter displays and scoreboard integration demand real-time data feeds and DMX512 protocol compatibility with legacy arena infrastructure. North American stadium operators prioritize field-replaceable driver boards to minimize game-day failure recovery times.
- Retail Signage:Wayfinding and promotional content systems integrate with POS analytics for dynamic message targeting. South Korean luxury retail chains are specifying transparent overlay configurations for facade preservation.
- Transportation:Highway gantries, tunnel guidance, and transit platform displays must satisfy Manual on Uniform Traffic Control Devices or equivalent national standards for color accuracy and viewing angle consistency.
Transportation holds installed capacity. Retail Signage is rotating up the share rankings.
End User:
Procurement authority structures and budget cycles determine contract terms, service bundling preferences, and vendor qualification requirements.
- Retailers:Brand-conscious buyers prioritize aesthetic integration and content management system flexibility over hardware durability specifications. South Korean department store chains and UAE mall operators drive transparent display adoption for facade differentiation.
- Event Organizers:Temporary deployment requirements favor rapid-assembly modular systems with rental-friendly packaging. These buyers prioritize weight reduction and tool-free assembly over long-term reliability metrics.
- Transportation Authorities:Municipal and national agencies in Germany, Japan, and the US specify multi-year total-cost-of-ownership evaluations with stringent mean-time-between-failure requirements. EU Ecodesign Directive compliance is accelerating replacement cycles for legacy high-power installations.
- Corporate Offices:Facility managers balance procurement cost sensitivity against IT integration requirements for building management system connectivity. These buyers favor standard pixel pitches and generic control protocols to minimize vendor lock-in.
Transportation Authorities hold installed capacity. Retailers are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Transportation authorities in Germany and Japan deploy arrow LED displays for highway wayfinding with zero-failure specifications, while retailers in South Korea and the UAE prioritize transparent facade integration for aesthetic differentiation. This consumption-mix differential splits procurement logic between reliability-engineered infrastructure and visually-driven commercial installations.
United States
The Federal Highway Administration mandates Manual on Uniform Traffic Control Devices compliance for roadway arrow displays, driving standardization across state DOT procurement. NHTSA specifications govern color accuracy and viewing angle consistency for tunnel and gantry installations. Daktronics anchors its position through recurring calibration contracts with North American sports venues and transportation authorities.
Germany
KBA certification requirements and EU Ecodesign Directive energy-efficiency mandates accelerate digital signage replacement cycles across municipal transportation networks. The country's automotive showroom segment drives premium indoor display specifications with strict CE marking compliance. Manufacturing clusters in Bavaria concentrate LED driver IC and control system production for European integrators.
Japan
METI procurement guidelines and JIS standards enforce stringent mean-time-between-failure requirements for tunnel and highway arrow displays where maintenance access is restricted. COB technology dominates specifications due to zero solder-joint failure tolerance. The Kansai corridor around Osaka hosts specialized thermal engineering firms serving transportation infrastructure projects.
South Korea
MFDS-equivalent display quality standards and aggressive smart city investments propel transparent LED adoption across retail facades and transit hubs. Seoul Capital Area department store chains specify see-through arrow overlays preserving natural lighting. Samsung Electronics and LG Electronics anchor domestic R&D corridors pushing Mini-LED pixel density boundaries.
China
MIIT certification protocols and GB standards create divergent testing burdens for manufacturers seeking cross-border market access. The Pearl River Delta manufacturing cluster compresses component lead times from weeks to days through concentrated LED die and driver IC production. Shenzhen-based integrators supply rapid-deployment modular systems for global transportation projects.
Arrow LED Displays Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another, fragmenting competitive dynamics across the arrow LED display market. Premium-tier vendors command transportation authority contracts through zero-failure engineering credentials, while volume-tier competitors capture corporate office and retail segments on cost efficiency. Three archetypes dominate: integrated display manufacturers with captive LED sourcing, modular system specialists optimized for rapid-deployment infrastructure, and diversified electronics conglomerates leveraging consumer display R&D spillover. M&A activity concentrates on thermal engineering talent acquisition from adjacent sectors, while strategic partnerships cluster around edge computing platform integration for real-time content adaptation.
Among North American infrastructure specialists, Daktronics exemplifies the calibration-contract model sustaining recurring revenue beyond hardware installation. Chinese modular system providers Absen and Unilumin occupy positions on the rapid-deployment vector, competing aggressively for transportation project modularity metrics. South Korean diversified electronics manufacturers Samsung Electronics and LG Electronics represent the R&D-spillover archetype, translating consumer display innovations into commercial arrow LED configurations.
| Leading Market Players |
|---|
| Daktronics |
| Leyard Opto-Electronic |
| Absen |
| Unilumin |
| Barco |
| Samsung Electronics |
| LG Electronics |
| Asian Electronics |
| Kingbright |
| Others |
Value Network & Pricing Analysis
The Shenzhen-to-Rotterdam maritime corridor compresses logistics costs for arrow LED display manufacturers while simultaneously amplifying pricing power for concentrated LED die suppliers in China's Pearl River Delta. This freight dynamic reinforces a supply structure where downstream integrators absorb input volatility while transportation authorities and retailers face divergent price tiers based on certification burdens and thermal management complexity.
Pricing Analysis
Long-term offtake agreements dominate procurement between display integrators and LED foundries, though spot purchasing persists for driver IC components subject to foundry allocation cycles. Three-tier pricing structure across premium, standard, and economy levels separates COB tunnel-certified modules from SMD office configurations and bare-bones indoor units. Pricing pressure stems from stranded SMD capacity as manufacturers accelerate COB line conversions. Transportation authorities exhibit lowest price sensitivity due to zero-failure specifications, while corporate facility managers drive hardest bargain on per-unit costs.
Supply Chain Analysis
Tariff exposure between China and the United States dominates risk calculations for North American project deliveries, forcing contingency planning through Mexican assembly nodes. LED epitaxy draws from concentrated III-V semiconductor supply chains anchored in Japan and Taiwan, while driver IC production centers on China's Pearl River Delta. Single-source vulnerability persists for indium phosphide substrates essential to red LED die production. Distribution runs through systems integrators who bundle installation and commissioning services for municipal transportation authorities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among municipal transportation authorities unbundling hardware procurement from decade-long service contracts, fragmenting vendor revenue streams and forcing margin compression on pure-play display manufacturers.
For Market Incumbents: Entrench position through captive LED chip sourcing from affiliated foundries, mirroring Leyard Opto-Electronic's backward integration model that insulates margins from indium phosphide substrate volatility. Accelerate thermal engineering recruitment from automotive lighting sectors to address Mini-LED heat flux requirements. Defend against modular system specialists by embedding predictive diagnostics that sustain recurring calibration revenue streams despite unbundling trends. For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point, where CE marking requirements remain less stringent than EU mandates and local integrators lack COB packaging expertise. Transparent LED glass retrofit projects for aging retail facades in secondary South Korean cities offer second white-space target with shorter sales cycles than transportation infrastructure. Lead with edge computing integration capabilities as differentiation against legacy DMX512-dependent incumbents. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified electronics conglomerates seeking to monetize non-core commercial display divisions amid consumer OLED margin pressure. Long-term viability hinges on thermal engineering talent scarcity resolution and successful COB yield ramp. Watch for inflection when EU right-to-repair mandates force modular architecture redesigns that favor field-replaceable specialists over sealed-unit legacy players.| Strategic Initiative | Industry Significance |
|---|---|
| COB Packaging Yield Improvement | Eliminates solder-joint failure modes for Japan's tunnel zero-fault specifications. |
| Predictive Diagnostics Integration | Embeds NVIDIA Jetson platforms for real-time pedestrian flow content adaptation. |
| Graphene Heat Spreader Adoption | Satisfies EU F-Gas Regulation phase-down for refrigerant-free thermal management. |
| Modular Field-Replaceability Design | Aligns with emerging EU right-to-repair mandates for component swapability. |
| Edge Computing Platform Partnership | Enables Qualcomm Vision Intelligence integration for smart city transit hubs. |
Research Methodology
Desk research of customs trade databases, MIIT certification registries, and SEC 10-K filings preceded structured interviews with transportation authority procurement officers, LED foundry operations managers, systems integrators, and thermal engineering specialists. Primary fieldwork combined with secondary validation across Manual on Uniform Traffic Control Devices compliance documentation, EU Ecodesign Directive implementation reports, and Japanese JIS standard revision records. Bottom-up unit economics triangulated against top-down market sizing from component shipment data.
Assumptions held fixed include current EU regulatory enforcement intensity and existing III-V semiconductor supply chain geography, while variables included COB yield improvement trajectories and right-to-repair mandate adoption timing across member states. Segmentation modeling spanned environmental exposure requirements, packaging architectures, application use cases, and end-user procurement authority structures. CAGRs derived from regression analysis of historical replacement cycle data and projected mandate-driven upgrade schedules. Forecast inputs incorporated LED die cost curves and thermal management technology substitution elasticities.
Macroeconomic conditions sit as an overlay; deviation in infrastructure spending commitments or cross-border tariff regimes would shift the trajectory. Forecasts reflect documented assumptions regarding technology transition speeds and regulatory implementation timelines. Material shifts in indium phosphide substrate supply concentration or F-Gas Regulation enforcement severity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Brazil LED Market
LED
North America Indoor LED Lighting Market
LED
Gan Micro LED Market
LED
Smart LED Indoor Signage Market
LED
Europe Outdoor LED Lighting Market
LED
UK LED Lighting Market
LED
Small Pitch LED Display Market
LED
India LED Outdoor Lighting Market
LED
LED Light Market
LED
LED Encapsulation Market
LED
US LED Downlight Market
LED
High-Brightness LED Market
LED
Global LED Phosphor Market
LED
Pixel Pitch LED Market
LED
United States Micro LED Market
LED
LED Tester Market