
 India Indoor LED Lighting Market | 2026-2036
India Indoor LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
India Indoor LED Lighting Market Insights
Market Context
The dealer-distributor network is fragmenting as e-commerce platforms and direct contractor procurement gain share. Havells India Limited leverages its captive manufacturing base in Haridwar and Baddi to sustain pricing flexibility across tier-2 and tier-3 cities. Crompton Greaves Consumer Electricals Limited anchors its position through deep electrical wholesale relationships in western India. Signify N.V. competes by positioning its Philips-branded portfolio toward premium smart-home segments in metro markets.
Technical Definition and Segments
India indoor LED lighting encompasses solid-state luminaires engineered with gallium nitride chipsets, aluminum heat sinks, and polycarbonate diffusers to deliver efficacy above 100 lumens per watt for enclosed commercial and residential environments. Panel lights and downlights dominate volume flows into new commercial construction, while tunable white and smart lighting systems capture expanding margin pools from architect-specified hospitality and corporate retrofit projects. RGB LED and dimmable LED categories grow fastest among technology segments as BEE star-labeling pushes buyers beyond basic replacement bulbs toward controllable, networked systems.
Regulatory Outlook
Bureau of Energy Efficiency star ratings, BIS certification under IS 16102, and E-Waste Management Rules compliance shape product design cycles and import barriers for unbranded Asian suppliers. State-level electricity distribution companies in Maharashtra and Karnataka increasingly mandate LED adoption in government buildings, tightening specification standards. Stakeholders must monitor how BEE's evolving minimum energy performance standards and state smart-city tenders redefine qualification thresholds for vendor participation.
Market Dynamics
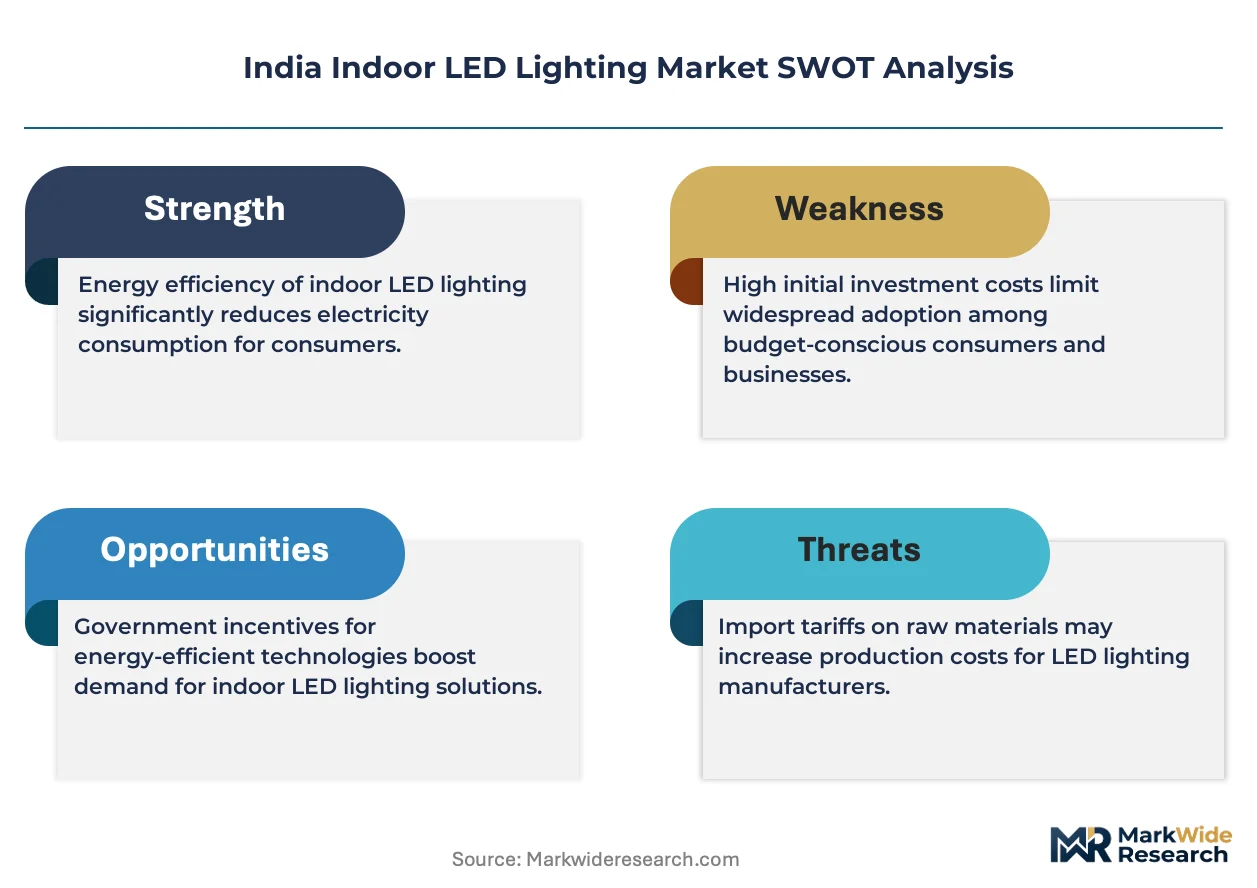
Bureau of Energy Efficiency star-labeling mandates are compressing replacement cycles and forcing manufacturers to redesign thermal management systems and driver electronics around gallium nitride chipsets.
Growth Catalysts
- Perform Achieve and Trade scheme:Energy-intensive industries in Gujarat's industrial corridor face carbon credit obligations that accelerate LED retrofits in factory floors and warehousing facilities.
- Smart-city infrastructure tenders:Municipal corporations in Maharashtra and Karnataka specify networked lighting controls, creating bundled procurement opportunities for systems integrators.
- Aluminum heat sink localization:Domestic fabrication of thermal management components reduces import dependency and shortens lead times for fixture assemblers in Tamil Nadu's manufacturing zones.
Market Restraints
- Driver IC supply concentration:Taiwan and China-based semiconductor foundries control gallium nitride driver production, exposing Indian assemblers to geopolitical logistics disruptions and currency volatility.
- E-Waste Management Rules compliance costs:Extended producer responsibility mandates force fixture manufacturers to establish reverse logistics networks for mercury-free lamp collection and rare earth recovery.
- Incumbent fluorescent infrastructure:Legacy ballast-compatible T8 troffers in government buildings and educational institutions delay full LED conversions due to rewiring cost thresholds.
Strategic Opportunities
- Human-centric lighting in healthcare:Circadian rhythm-tunable white systems address patient recovery protocols in tertiary hospitals across Delhi-NCR and Chennai's medical corridor.
- Kirana store digitization:Electrical wholesale cooperatives in tier-3 towns adopt B2B platforms for inventory pooling, reducing working capital burdens for regional distributors.
- PLI scheme for semiconductor packaging:Domestic chip-on-board LED module assembly incentives attract component manufacturers to set up surface-mount technology lines in Telangana and Karnataka.
Industry Challenges
- Optical design engineering scarcity:Few Indian institutes train photometric simulation specialists capable of ray-tracing analysis for glare-controlled hospitality luminaires.
- BIS certification timeline compression:IS 16102 testing queue backlogs at NABL-accredited laboratories delay product launches by four to six months during peak tender seasons.
- Legacy DALI protocol integration:Existing building automation systems in Mumbai's commercial towers require protocol bridge hardware that complicates smart fixture commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Indoor LED Lighting Market |
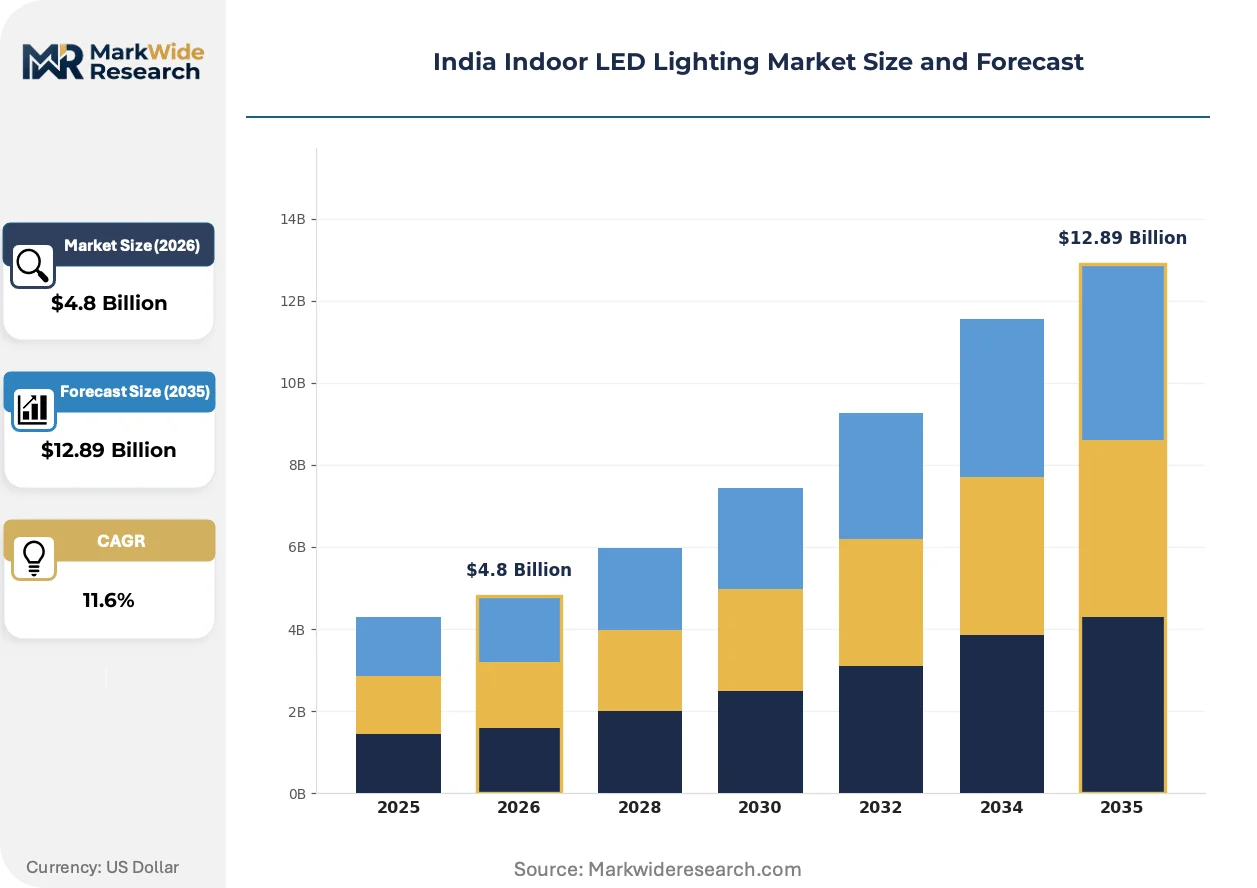
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.89 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Residential, Commercial, Industrial, Hospitality Form Factor: Panel Lights, Downlights, Decorative Fixtures, Tubes Technology: Smart Lighting, Dimmable LED, RGB LED, Tunable White End User: Homeowners, Business Owners, Contractors, Architects |
| Companies Covered | Signify N.V., Havells India Limited, Crompton Greaves Consumer Electricals Limited, Bajaj Electricals Limited, Surya Roshni Limited, Orient Electric Limited, Wipro Lighting, Eveready Industries India Limited, Polycab India Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Indoor LED Lighting Market Trends and Innovations
Fixture architecture is converging around chip-on-board LED engines and intelligent driver platforms that enable granular energy monitoring and predictive maintenance contracts.
Chip-on-board LED technology eliminates individual SMD packaging by depositing phosphor directly onto multi-die arrays, improving lumen density and thermal uniformity. Hospitality specifiers in Bengaluru and Goa adopt these engines for compact cove lighting profiles. The technology is migrating from high-end architectural projects toward mid-market commercial retrofits as domestic phosphor deposition capabilities mature.
Bureau of Energy Efficiency's proposed revision to minimum energy performance standards will tighten luminous efficacy thresholds for panel lights and downlights by fifteen percentage points. Fixture manufacturers must redesign optical systems and driver efficiencies to maintain star ratings. Western India's electrical wholesale channels are pre-positioning inventory clearance strategies ahead of implementation deadlines.
Contractor-direct procurement through project-tender platforms is disintermediating traditional distributor markups in large commercial developments. Mumbai and Delhi-based MEP contractors now source specified brands through volume aggregation sites that bypass regional electrical bazaars. This pattern concentrates most acutely in IT park and co-working space fit-outs where project timelines compress specification-to-delivery windows.
India Indoor LED Lighting Market Segmentation
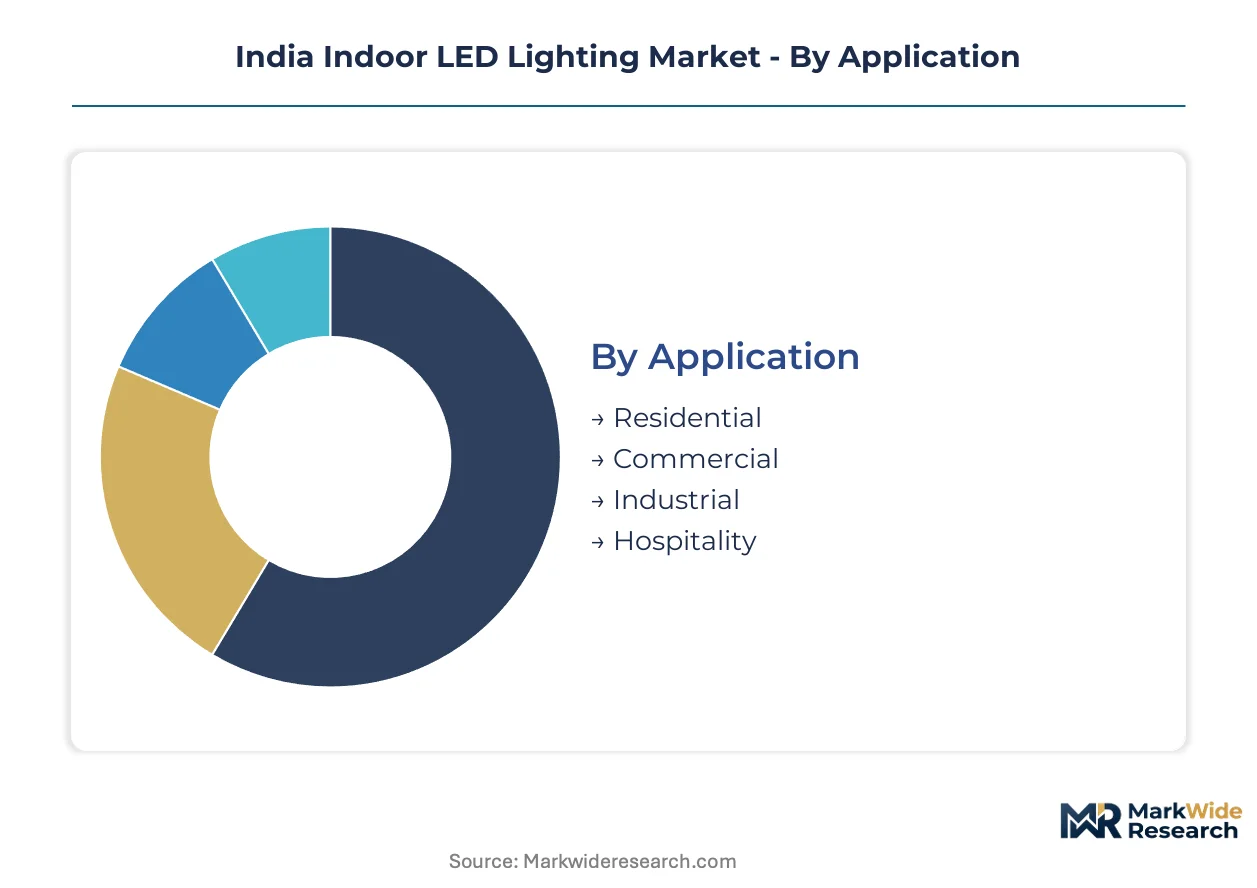
Segmentation in the India indoor LED lighting market reveals distinct procurement rhythms and margin structures. Replacement cycles vary dramatically across application types, with some segments turning over every 18 months while others extend beyond seven years.
Application:
Replacement velocity separates commercial retrofit demand from residential new-build installations by a factor of three.
- Residential:Homeowners prioritize fixture aesthetics and BEE star ratings over advanced controls. Demand clusters in Gujarat's apartment construction corridors and Delhi-NCR's builder-floor developments where developer-specified bulk procurement dominates.
- Commercial:Office retrofits in Mumbai's Bandra-Kurla Complex and Bengaluru's Whitefield tech parks compress replacement cycles to 24-36 months as landlords chase green building certifications and electricity distribution company rebate programs.
- Industrial:Factory floor lighting in Tamil Nadu's Sriperumbudur automotive cluster and Pune's Chakan belt emphasizes IP65 ingress protection and vibration-resistant housings.
- Hospitality:Goa resorts and Jaipur heritage hotels specify tunable white and RGB systems for guest experience differentiation, though project timelines stretch 12-18 months from specification to commissioning.
Commercial retrofits anchor the volume base while hospitality specifications gain share at the steepest rate.
Form Factor:
Margin concentration follows thermal management complexity rather than unit volume.
- Panel Lights:Edge-lit and back-lit variants with aluminum die-cast frames dominate BPO and IT park fit-outs. Maharashtra state government tenders for municipal buildings specify 2x2 and 2x4 foot configurations with integrated emergency battery backup.
- Downlights:COB and SMD variants with deep baffle designs address glare control requirements in Delhi's luxury retail developments and Chennai's hospital atriums.
- Decorative Fixtures:Pendant and chandelier-style LED luminaires serve architect-driven projects in Hyderabad's HITEC City commercial towers.
- Tubes:T5 and T8 retrofits with integrated drivers target educational institution upgrades where BEE mandates accelerate fluorescent phase-out.
Panel lights generate the highest absolute shipment volumes while downlights command the widest specification spreads.
Technology:
Control granularity determines pricing tiers and installation complexity.
- Smart Lighting:Zigbee and Bluetooth mesh-enabled systems with cloud-based energy dashboards penetrate Mumbai's co-working space developments and Bengaluru's smart-city pilot zones.
- Dimmable LED:Phase-cut and 0-10V analog dimming circuits satisfy basic code compliance in commercial buildings without full building automation integration.
- RGB LED:Addressable pixel strips and wall-washers serve experiential retail in Delhi's Select Citywalk and Bangalore's Phoenix Marketcity malls.
- Tunable White:Circadian rhythm systems with 2700K-6500K CCT adjustment address healthcare protocols in Chennai's Apollo Hospitals and Delhi's AIIMS expansion wings.
Dimmable LED maintains the broadest installed base while smart lighting climbs the fastest on systems integration contracts.
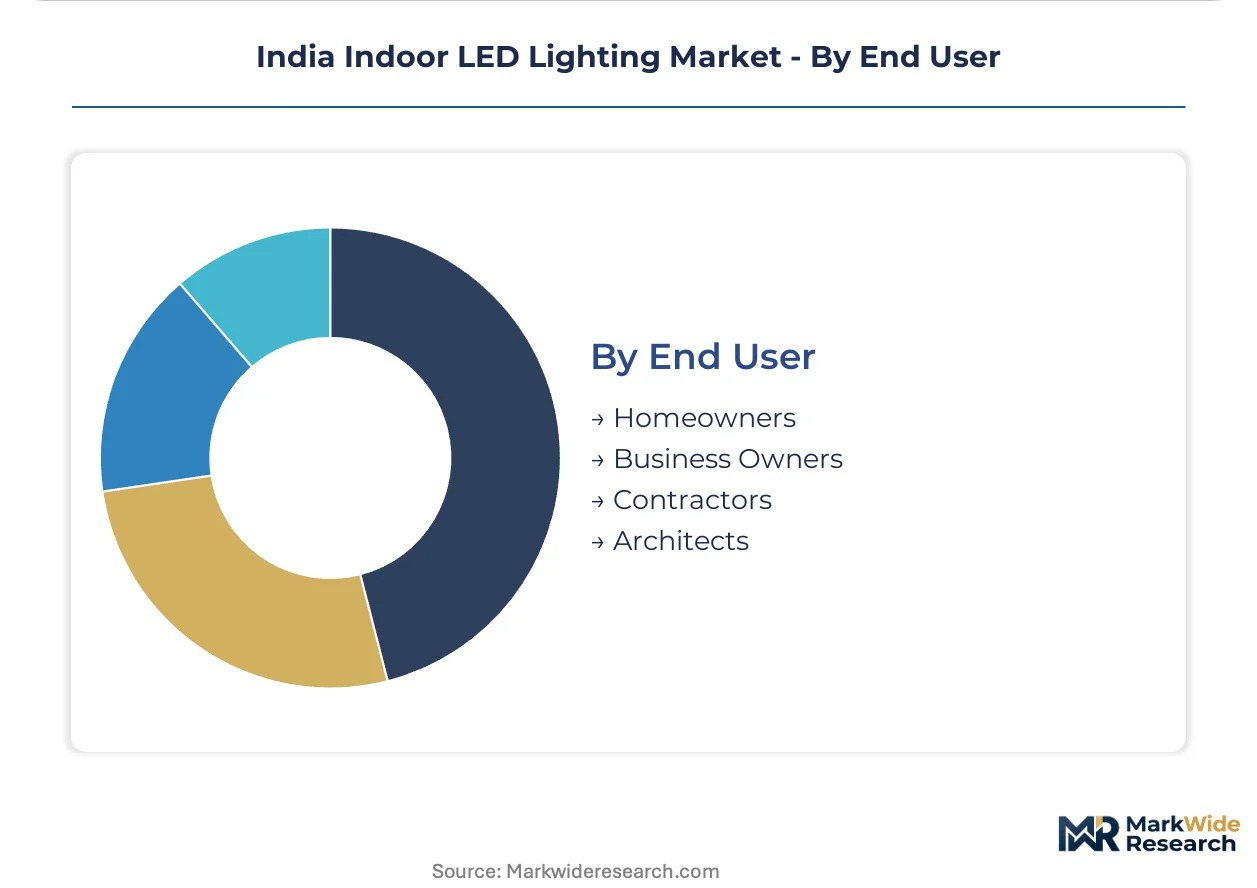
End User:
Specification authority and procurement scale diverge sharply across buyer types.
- Homeowners:E-commerce platform purchases through Flipkart and Amazon India dominate replacement bulb and basic fixture transactions, with delivery expectations compressing to 24-48 hours in tier-1 cities.
- Business Owners:MSME factory proprietors in Rajkot's machine tool cluster and Coimbatore's pump manufacturing belt prioritize payback periods under 18 months for warehouse lighting upgrades.
- Contractors:MEP firms in Hyderabad and Ahmedabad aggregate volumes across multiple sites, bypassing traditional electrical wholesale markups through direct manufacturer negotiations.
- Architects:Specifiers on premium hospitality and corporate headquarters projects in Mumbai's Lower Parel and Delhi's Aerocity demand photometric data packages and IES file libraries for lighting simulation workflows.
Contractors drive the largest transaction sizes while architects dictate the steepest premium capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Bureau of Energy Efficiency anchors Maharashtra's regulatory environment, driving specification standards that cascade through western India's electrical wholesale networks and municipal procurement frameworks.
Maharashtra
State electricity distribution companies mandate LED adoption across government buildings and smart-city pilot zones. Mumbai's municipal corporation specifies networked lighting controls in Bandra-Kurla Complex retrofits. The state's Perform Achieve and Trade obligations compress replacement cycles for energy-intensive industries in Pune's Chakan manufacturing belt.
Gujarat
Industrial corridor demand concentrates in factory floor and warehousing retrofits seeking carbon credit compliance. The state's electrical wholesale cooperatives aggregate volumes for Rajkot's machine tool cluster and Surat's textile processing units. Gujarat Urja Vikas Nigam Limited rebate programs accelerate fluorescent phase-out in SME facilities.
Karnataka
Bengaluru's Whitefield tech parks and co-working developments specify smart lighting systems with cloud-based energy dashboards. State-level electricity distribution companies tighten efficacy thresholds for municipal building tenders. Mysuru's heritage hotel retrofit pipeline demands tunable white systems for guest experience differentiation.
Tamil Nadu
Sriperumbudur's automotive cluster drives IP65-rated industrial fixture demand with vibration-resistant housing specifications. Chennai's Apollo Hospitals and medical corridor facilities specify circadian rhythm-tunable white systems for patient recovery protocols. Domestic aluminum heat sink fabrication shortens lead times for fixture assemblers in Coimbatore's pump manufacturing belt.
Delhi-NCR
Builder-floor developments and Aerocity commercial towers drive architect-specified premium fixture demand. Delhi's AIIMS expansion wings and tertiary hospitals adopt human-centric lighting protocols. The National Capital Region's electrical wholesale channels face disintermediation pressure from contractor-direct procurement platforms.
India Indoor LED Lighting Market Competitive Landscape
Diversified electrical conglomerates and captive manufacturing specialists split the market along vertical integration fault lines. The vendor base organizes around three strategic archetypes: integrated electrical majors with captive component production, brand licensors leveraging offshore manufacturing partnerships, and component-focused assemblers serving price-sensitive replacement demand. Competitive moves concentrate on backward integration into driver electronics and thermal management components, alongside direct contractor procurement platform development that bypasses traditional distribution markups.
Among integrated electrical conglomerates, Havells India Limited and Crompton Greaves Consumer Electricals Limited exemplify the captive manufacturing archetype with in-house production capabilities. Signify N.V. occupies a distinct position as a technology licensor and brand steward. These three entities anchor the competitive structure, with diversified industrials like Bajaj Electricals and Surya Roshni representing the mid-tier assembly-focused segment that competes through electrical wholesale relationship depth rather than component-level vertical control.
| Leading Market Players |
|---|
| Signify N.V. |
| Havells India Limited |
| Crompton Greaves Consumer Electricals Limited |
| Bajaj Electricals Limited |
| Surya Roshni Limited |
| Orient Electric Limited |
| Wipro Lighting |
| Eveready Industries India Limited |
| Polycab India Limited |
| Others |
Pricing and Supply Chain Analysis
Haridwar's captive manufacturing corridors anchor domestic fixture assembly capacity, translating aluminum heat sink localization into pricing leverage against import-dependent competitors in Tamil Nadu's coastal zones. BEE star-labeling mandates compress product lifecycles, forcing manufacturers to absorb thermal management redesign costs or surrender margin at the wholesale tier.
Pricing Analysis
Western India's electrical wholesale channels command fifteen to twenty percent premiums over eastern markets due to Maharashtra's concentrated commercial retrofit demand and faster inventory turns. Three-tier pricing structure across premium, standard, and economy levels separates architect-specified hospitality systems from BEE-compliant bulk procurement for government buildings. Cost compression in the economy tier intensifies because unbranded Asian suppliers bypass BIS certification queues through gray-market channels. MSME factory proprietors in Rajkot's machine tool cluster exhibit the highest price sensitivity, while Mumbai's MEP contractors prioritize specification compliance over unit economics.
Supply Chain Analysis
Tariff exposure between Taiwan and mainland China dominates supply chain risk planning for gallium nitride driver IC procurement. Indian fixture assemblers draw from semiconductor foundries in Taiwan, China, and South Korea for critical chip-on-board modules, with domestic phosphor deposition capabilities still maturing in Telangana's emerging packaging zones. Single-source vulnerability concentrates in gallium nitride epitaxy equipment, where German and Japanese toolmakers control deposition system supply. Distribution runs through electrical wholesale cooperatives in tier-2 cities, though contractor-direct platforms are disintermediating traditional markups in Mumbai and Delhi metro corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Optical design engineering scarcity constrains premium hospitality specification capture, with few Indian institutes producing photometric simulation specialists capable of ray-tracing analysis for glare-controlled luminaires.
For Market Incumbents: Entrench control over thermal management component supply through captive aluminum heat sink fabrication in Haridwar and Baddi facilities, insulating margin structures from Taiwan semiconductor foundry volatility. Deepen electrical wholesale relationships in western India to defend against contractor-direct procurement platforms disintermediating traditional distribution. Prioritize BIS certification pipeline investment to compress IS 16102 testing queue delays that handicap product launch timing against unbranded competitors. For New Entrants and Emerging Players: Mid-market commercial retrofits in Karnataka's tier-2 cities represent the most penetrable entry point, where BEE compliance mandates outpace local manufacturer response capacity. Human-centric lighting protocols for Delhi-NCR's tertiary hospital expansion pipeline offer specification-driven margin pools with lower competitive density than saturated metro commercial segments. Pursue systems integration partnerships with Bengaluru-based building automation contractors to bypass wholesale channel establishment costs. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because regulatory compliance burdens and certification backlogs favor scaled incumbents with established NABL laboratory relationships and reverse logistics networks for E-Waste Management Rules adherence. Acquisition targets should surface among component-focused assemblers in Tamil Nadu's manufacturing zones with latent surface-mount technology capacity and underutilized phosphor deposition lines. Monitor BEE minimum energy performance standard revision implementation timelines as the signal for inventory clearance-driven distress opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Driver Electronics | Captive gallium nitride chipset sourcing insulates margin from Taiwan foundry volatility and currency fluctuation. |
| Direct Contractor Procurement Platform | Bypassing electrical wholesale markups captures volume aggregation from Mumbai's MEP contractor consolidation. |
| Human-Centric Lighting Certification | Circadian rhythm protocol validation opens Delhi-NCR hospital specification channels with premium pricing. |
| Aluminum Heat Sink Localization | Domestic thermal management fabrication shortens lead times for Tamil Nadu fixture assemblers. |
| BIS Certification Pipeline Expansion | Accelerated IS 16102 testing queue access compresses product launch windows against unbranded competitors. |
Research Methodology
A spread of perspectives from MEP contractors, electrical wholesale distributors, BIS certification laboratory directors, and hospitality lighting specifiers converged on the working assumptions for demand segmentation and pricing tier boundaries. Primary fieldwork combined structured interviews with procurement officers at Mumbai's Bandra-Kurla Complex developments and Bengaluru's Whitefield tech parks with secondary validation through BEE star-labeling databases, state electricity distribution company tender records, and customs import data for LED component trade flows. Bottom-up fixture shipment estimates from Tamil Nadu and Gujarat manufacturing clusters were triangulated against top-down electricity savings projections from Perform Achieve and Trade scheme filings.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning application type, form factor, technology tier, and end-user procurement authority. Modeled variables included replacement cycle velocity by building stock vintage, BEE efficacy threshold compliance costs, and smart-city infrastructure tender bundling patterns. CAGRs were derived from installed base turnover rates and new construction pipeline tracking rather than extrapolated trend fitting.
Practitioners should monitor BEE minimum energy performance standard revision implementation schedules and gallium nitride semiconductor foundry capacity announcements for early signals of margin compression or supply disruption. Forecasts reflect assumptions about regulatory enforcement consistency, state electricity distribution company rebate program continuity, and domestic phosphor deposition capability maturation timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Thailand LED Market
LED
Europe Outdoor LED Lighting Market
LED
Architectural LED Products Market
LED
Germany Outdoor LED Lighting Market
LED
North America Commercial LED Lighting Market
LED
Japan LED Lighting Market
LED
Linear LED Strip Fixture Market
LED
Philippines LED Market
LED
High-Intensity LED Logo and Livery Lighting Systems Market
LED
Asia Pacific LED Lighting Market
LED
UK Indoor LED Lighting Market
LED
Surface Mount PLCC Leds Market
LED
North America Outdoor LED Lighting Market
LED
LED Panel Market
LED
Brazil LED Market
LED
LED Mask Market