
 East Africa LED Lighting Market | 2026-2036
East Africa LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
East Africa LED Lighting Market Intelligence
The customer base for LED lighting across East Africa is broadening as municipal procurement authorities in Kenya, Ethiopia, and Tanzania fragment into decentralized purchasing units. Signify N.V. (Philips Lighting) leverages its established East African distribution network to sustain volume leadership in commercial and street lighting segments. OSRAM GmbH anchors its position through specialized industrial and high-bay applications serving manufacturing zones near Nairobi and Addis Ababa. Syska LED competes aggressively on price-point positioning for residential retrofits in urban Kenyan households.
East Africa LED lighting comprises solid-state luminaires utilizing semiconductor diodes with typical efficacy ratings exceeding 100 lumens per watt, designed for grid-tied and off-grid deployment across tropical climates with ambient temperatures ranging 25-40°C. The technology serves primary purposes of reducing energy consumption in power-constrained economies and extending operational hours for commercial and public infrastructure. Solar LED technology leads structural growth due to alignment with rural electrification gaps and declining photovoltaic module costs, while smart lighting remains nascent pending broadband infrastructure maturation. Street lighting dominates application-level demand as multilateral development finance flows into urban infrastructure across the region.
Kenya's Energy Regulatory Authority and Tanzania's Energy and Water Utilities Regulatory Authority enforce minimum energy performance standards that shape product compliance requirements and filter lower-tier imports from regional markets. Ethiopia's Ethiopian Energy Authority and the East African Community's harmonized standards framework further consolidate technical specifications across cross-border trade corridors. Stakeholders must monitor regulatory convergence between national bodies and the emerging African Continental Free Trade Area technical committees to anticipate certificate reciprocity and localized assembly incentives.
Market Dynamics
Municipal procurement fragmentation across Kenya, Ethiopia, and Tanzania is redrawing competitive access routes as centralized energy utilities devolve purchasing authority to city-level infrastructure departments.
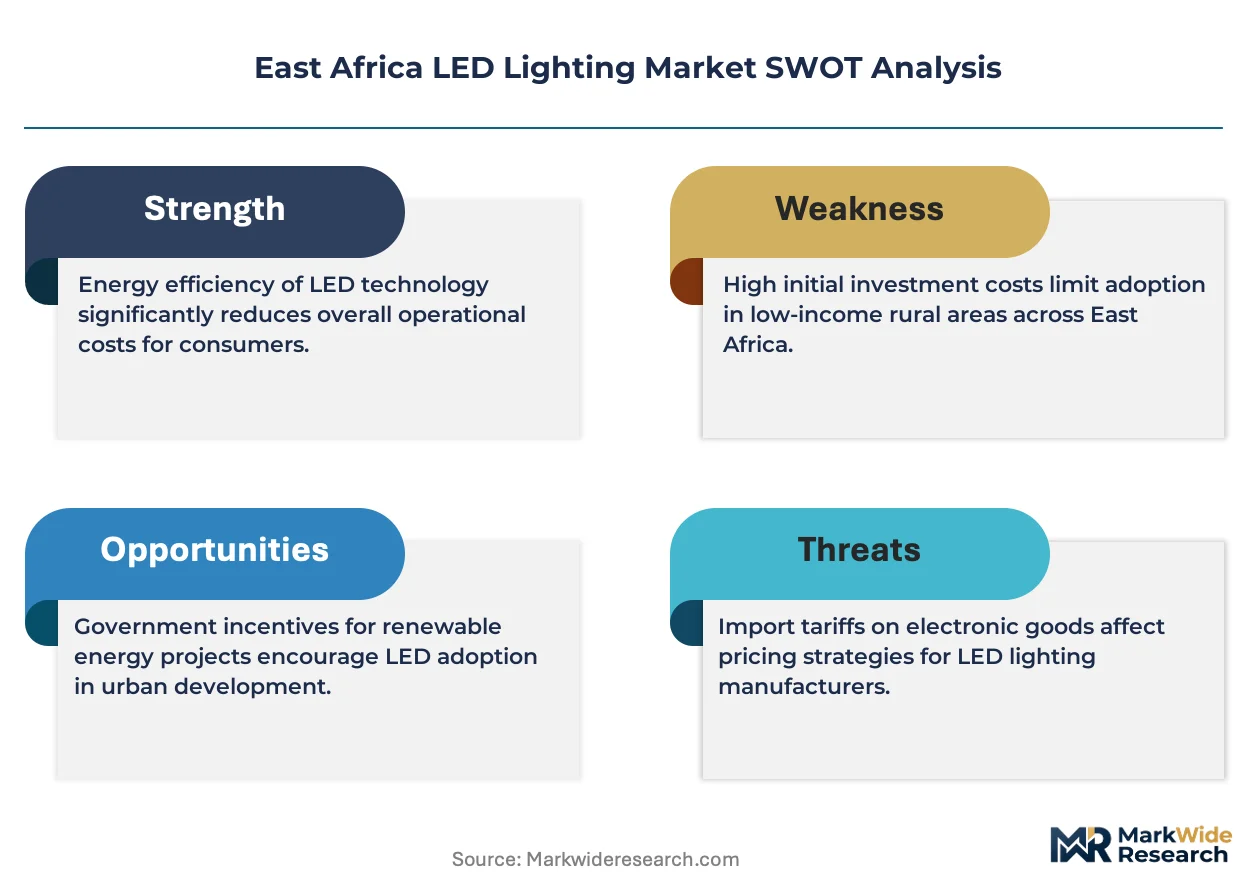
Growth Catalysts
- Kenya's Energy Regulatory Authority efficacy mandates:Minimum lumen-per-watt thresholds accelerate replacement cycles for legacy street luminaires in Nairobi and Mombasa.
- Solar photovoltaic cost compression:Declining module prices enable off-grid LED deployment in rural Tanzanian settlements beyond grid extension timelines.
- Dar es Salaam port corridor:Container throughput capacity supports rapid project logistics for commercial lighting installations across the northern Tanzania industrial zone.
Market Restraints
- Import tariff layering:East African Community customs protocols impose cumulative duties on semiconductor drivers sourced from non-member states.
- Foreign exchange volatility:Ethiopian Birr and Kenyan Shilling depreciation inflates landed costs for chip-on-board LED components.
- Technical service infrastructure:Sparse certified technician networks in secondary Ethiopian cities extend warranty claim resolution timelines.
Strategic Opportunities
- Ugandan market underpenetration:Kampala's nascent municipal LED retrofit program offers first-mover positioning before competitive saturation.
- Smart lighting convergence:Narrowband IoT integration with existing cellular towers enables remote dimming pilots in Kenyan commercial estates.
- Pay-as-you-go solar LED:Mobile money-enabled financing models unlock household segments excluded from upfront capital requirements.
Industry Challenges
- Harmonized standard delays:Divergent testing protocols between Kenya's Energy Regulatory Authority and Tanzania's Energy and Water Utilities Regulatory Authority complicate cross-border product certification.
- Skills scarcity in thermal management design:Local engineering capacity for high-ambient-temperature luminaire specification remains concentrated in Nairobi and Addis Ababa.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | East Africa LED Lighting Market |
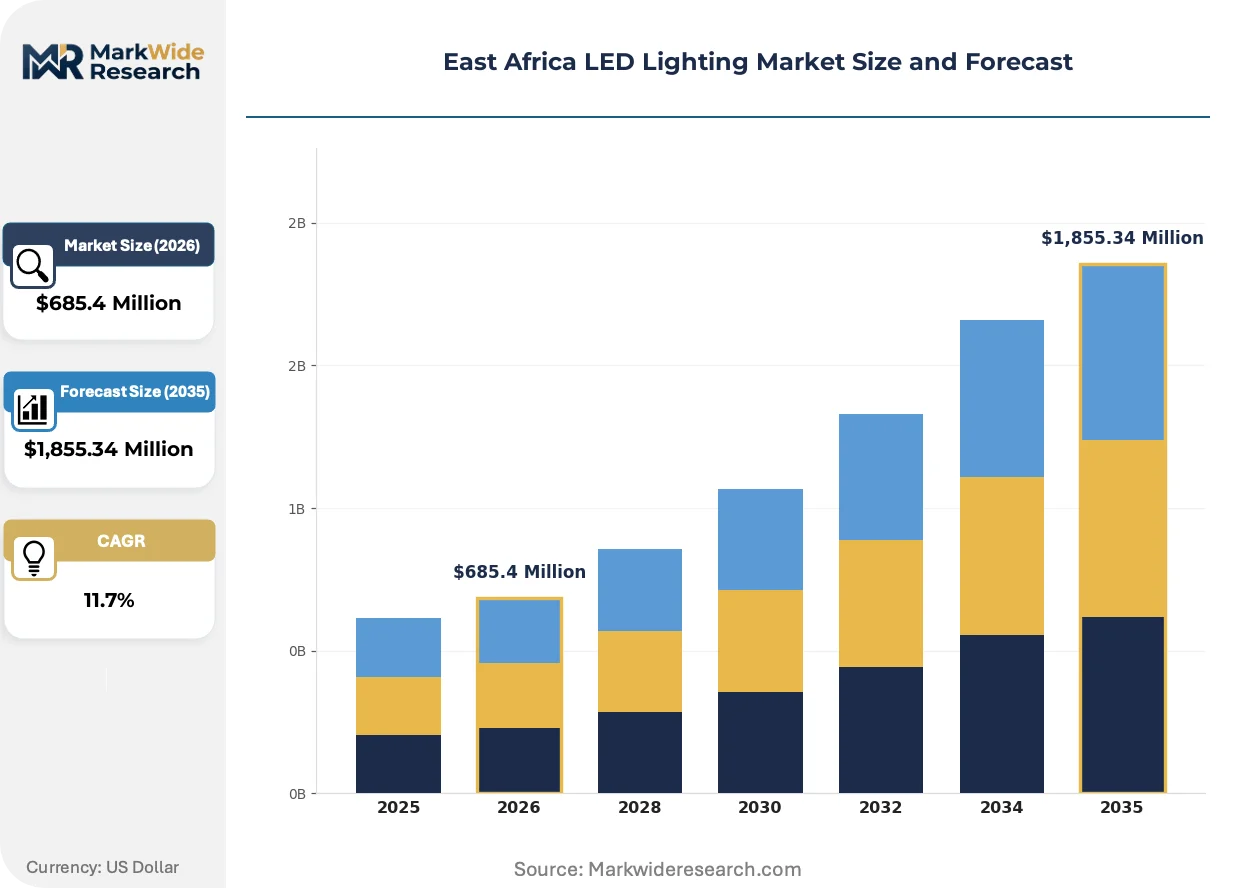
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,855.34 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Residential, Commercial, Industrial, Outdoor Technology: Smart Lighting, Solar LED, Energy-efficient, Driverless Application: Street Lighting, Decorative Lighting, Task Lighting, Emergency Lighting End User: Governments, Corporates, Households, Non-profits |
| Companies Covered | Acuity Brands Lighting Inc., Zumtobel Group, Signify N.V. (Philips Lighting), Syska LED, Hubbell Incorporated, OSRAM GmbH, Opple Lighting Co., Ltd., Samsung Electronics, Cree Lighting, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
East Africa LED Lighting Market Strategic Shifts & Innovations
Technology trajectories in East African LED markets center on climate-adapted hardware design, regulatory harmonization pressures, and procurement model experimentation that bypasses traditional distributor hierarchies.
Thermal management engineering is rewriting product specifications for tropical deployment. Manufacturers now specify junction temperature tolerances exceeding 125°C for luminaires destined for Ethiopian highland and Kenyan coastal installations. Municipal buyers in Dar es Salaam and Nairobi increasingly require accelerated life-test documentation before tender qualification. This specification elevation compresses viable supplier pools to firms with captive thermal simulation capabilities.
Kenya's Energy Regulatory Authority and Tanzania's Energy and Water Utilities Regulatory Authority are converging minimum efficacy thresholds under East African Community harmonization protocols. The regulatory alignment reduces duplicate testing burdens for luminaires crossing the Namanga border corridor. Industrial facility managers in the Nairobi-Addis Ababa manufacturing belt now specify dual-certified products to simplify multi-country estate standardization.
Direct manufacturer engagement with municipal engineering departments is displacing traditional electrical distributor intermediaries. Kenyan county governments in Nakuru and Kisumu now issue tenders through centralized electronic procurement portals that bypass legacy wholesaler relationships. This channel compression squeezes margin layers for importer-distributors while rewarding manufacturers with localized assembly presence. The pattern is most visible in Kenyan street lighting segments where multilateral development bank financing requires direct contractor accountability.
East Africa LED Lighting Market Segmentation
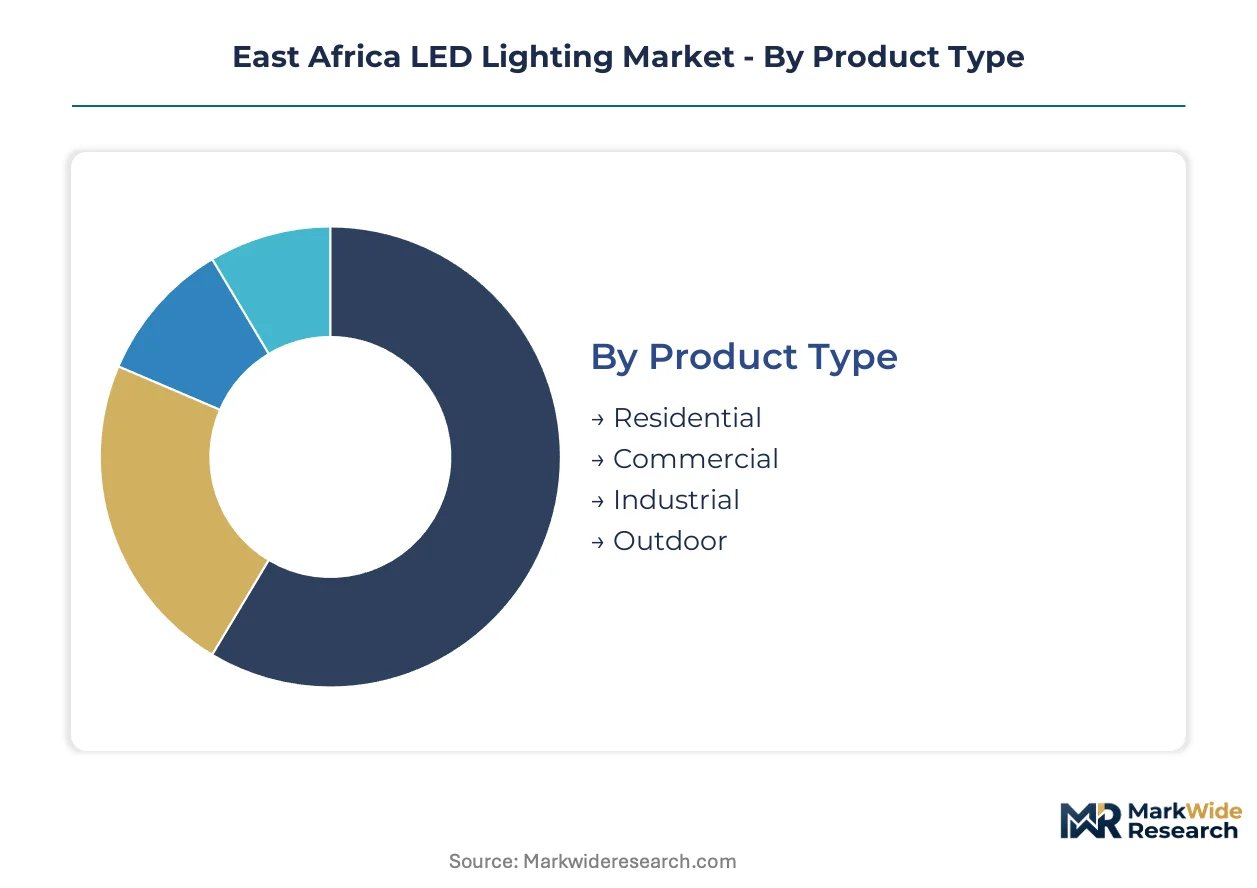
Segmentation in East African LED markets reveals how procurement fragmentation and infrastructure gaps reshape demand patterns. Upgrade cycles vary sharply across product categories, with municipal street lighting operating on compressed replacement timelines driven by regulatory mandates while residential retrofits follow household income cycles.
Product Type:
Replacement urgency differs materially across installation environments, with outdoor infrastructure facing the shortest upgrade windows due to public accountability pressures.
- Outdoor:Luminaires engineered for street, highway, and public space illumination with IP65+ ingress protection and surge suppression for tropical storm exposure. Nairobi County's street lighting division and Dar es Salaam's municipal engineering department drive volume through development-bank financed retrofit programs.
- Commercial:Troffers, downlights, and linear fixtures specified for retail, hospitality, and office environments with 50,000-hour rated lifespans. Kenya's Energy Regulatory Authority efficacy mandates accelerate turnover in Nairobi's commercial estates as landlords face penalty exposure for non-compliant installations.
- Industrial:High-bay and floodlighting systems for manufacturing floors and warehousing with enhanced thermal management for ambient temperatures exceeding 35°C.
- Residential:Bulb-form retrofits and integrated ceiling fixtures targeting urban Kenyan and Ethiopian households through distributor and mobile-money channels.
Outdoor sits at the top of the volume ranking, with Commercial climbing the fastest.
Technology:
Cost tier stratification separates premium smart systems from mass-market solar solutions, with financing accessibility determining adoption velocity more than technical capability.
- Solar LED:Off-grid luminaires integrating photovoltaic modules, lithium battery storage, and dusk-to-dawn controllers for rural Tanzanian settlements beyond grid extension timelines. Declining module costs expand addressable households.
- Energy-efficient:Conventional grid-tied LED systems meeting minimum lumen-per-watt thresholds enforced by Kenya's Energy Regulatory Authority and Tanzania's Energy and Water Utilities Regulatory Authority.
- Smart Lighting:Connected systems with dimming, occupancy sensing, and remote management capability. Narrowband IoT pilots in Kenyan commercial estates remain constrained by broadband infrastructure gaps.
- Driverless:Simplified luminaire architectures eliminating separate driver components to reduce failure points and cost in price-sensitive segments.
Solar LED commands the largest installed base, while Smart Lighting shows the steepest expansion trajectory pending connectivity maturation.
Application:
Geographic concentration of development finance flows determines where specific lighting functions deploy most intensively across the region.
- Street Lighting:Cobra-head and decorative pole-mounted luminaires for roadway and pedestrian illumination. Multilateral development bank financing concentrates deployment in Nairobi, Addis Ababa, and Dar es Salaam corridor municipalities.
- Task Lighting:Focused illumination systems for workstations, surgical suites, and precision manufacturing. Ethiopian industrial parks near Addis Ababa and Kenyan EPZ facilities specify high-CRI variants.
- Decorative Lighting:Architectural accent and landscape illumination for hospitality and public realm enhancement.
- Emergency Lighting:Battery-backed exit and egress systems for commercial and institutional compliance.
Street Lighting dominates procurement volumes, with Task Lighting gaining share fastest in industrializing secondary cities.
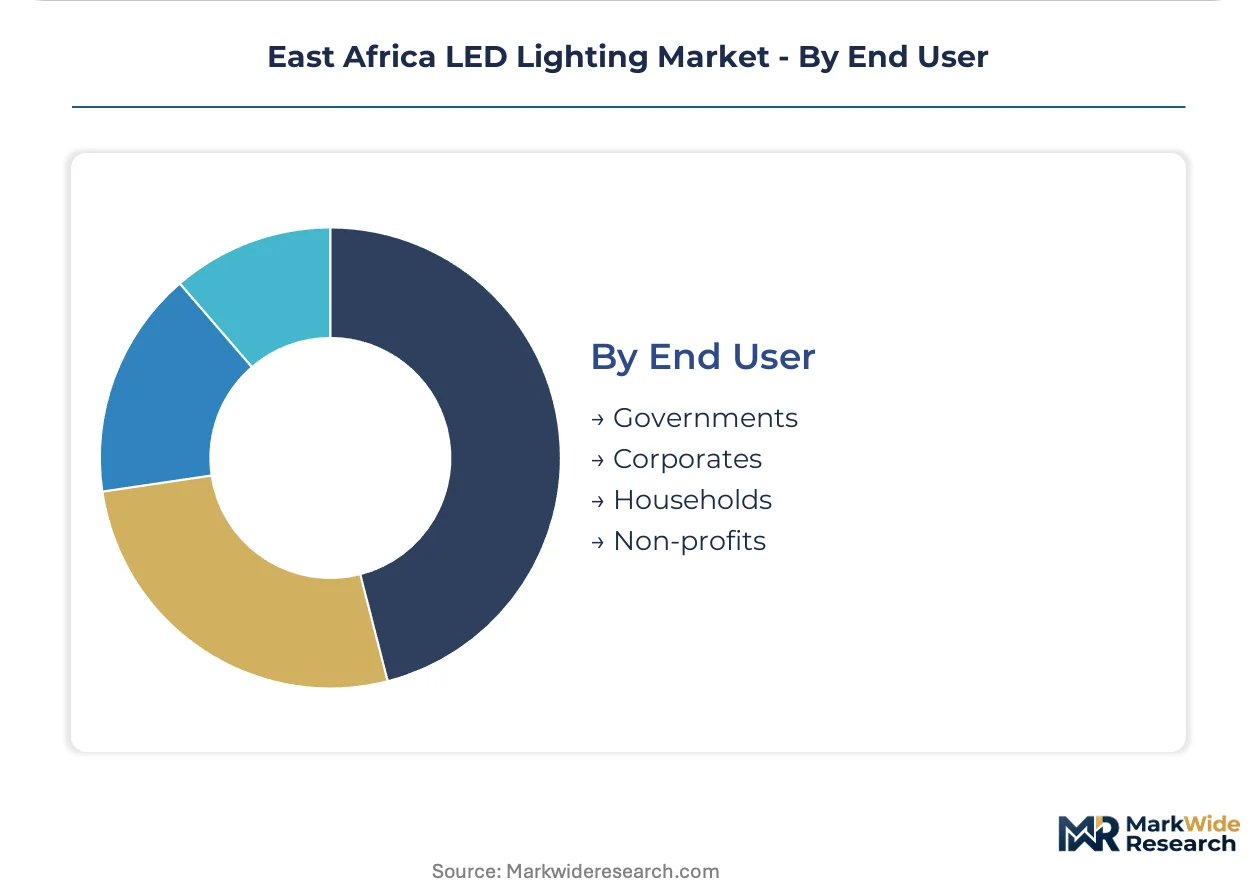
End User:
Customer type dictates payment modality and decision velocity, with public procurement cycles running 18-24 months against household purchase spontaneity.
- Governments:National ministries, county administrations, and municipal engineering departments procuring through tender processes with efficacy compliance requirements. Kenya's county governments in Nakuru and Kisumu utilize centralized electronic procurement portals.
- Corporates:Industrial facility managers and commercial property operators seeking energy cost reduction and regulatory compliance across multi-country estates.
- Households:Urban residential consumers in Kenyan and Ethiopian cities accessing products through electrical retailers and pay-as-you-go solar distributors.
- Non-profits:Development organizations and NGOs deploying solar LED in rural electrification programs.
Governments anchor procurement volume, with Households expanding most quickly through mobile-money financing enablement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kenya's regulatory stringency contrasts with Tanzania's port-driven logistics advantage, while Ethiopia's industrial corridor expansion creates divergent procurement rhythms across the region.
Kenya
Nairobi's street lighting retrofit program and Mombasa port modernization drive concentrated demand for high-efficacy luminaires. Kenya's Energy Regulatory Authority enforces minimum lumen-per-watt thresholds that filter non-compliant imports. The Nairobi-Kisumu corridor anchors commercial estate development where landlords face penalty exposure for outdated installations.
Tanzania
Dar es Salaam's container throughput capacity enables rapid project logistics for northern Tanzania industrial zone deployments. The country's Energy and Water Utilities Regulatory Authority maintains efficacy standards that shape cross-border product flows. Secondary cities in the Lake Victoria zone are emerging as solar LED penetration points beyond grid extension timelines.
Ethiopia
Addis Ababa's industrial park expansion and manufacturing zone electrification sustain demand for high-bay and task lighting systems. The Ethiopian Energy Authority consolidates technical specifications that align with emerging East African Community harmonization protocols. Industrial clusters near the capital specify thermal-tolerant luminaires for ambient temperatures exceeding 35°C.
Uganda
Kampala's nascent municipal LED retrofit program offers positioning ahead of competitive saturation in East Africa's underpenetrated market. The country's national energy regulator is developing efficacy standards that mirror Kenyan and Tanzanian frameworks. Jinja's manufacturing corridor and Entebbe's logistics hub concentrate early commercial deployment.
Rwanda
Kigali's smart city infrastructure investments pilot connected lighting systems alongside narrowband IoT integration. The Rwanda Utilities Regulatory Authority enforces energy performance standards that accelerate technology turnover in public infrastructure. The capital's commercial district serves as a testbed for remote-managed luminaires pending regional broadband maturation.
East Africa LED Lighting Market Key Industry Players
European producers anchor the premium tier through established distribution networks; Asian specialists hold cost-competitive positions in volume segments. The vendor base stratifies across three tiers: multinationals with captive thermal engineering capabilities, regional assemblers leveraging localized compliance advantages, and price-point competitors serving residential retrofits. Strategic moves center on direct municipal engagement and backward integration into driver component sourcing.
Among the established multinationals, Signify N.V. and OSRAM GmbH occupy positions exemplifying divergent specialization vectors. Signify leverages its East African distribution infrastructure to sustain volume leadership across commercial and municipal segments. OSRAM anchors its presence through industrial and high-bay applications serving manufacturing zones near Nairobi and Addis Ababa. Syska LED represents the aggressive price-point tier targeting urban Kenyan households through distributor and mobile-money channels.
| Leading Market Players |
|---|
| Acuity Brands Lighting Inc. |
| Zumtobel Group |
| Signify N.V. (Philips Lighting) |
| Syska LED |
| Hubbell Incorporated |
| OSRAM GmbH |
| Opple Lighting Co., Ltd. |
| Samsung Electronics |
| Cree Lighting |
| Others |
Cost & Logistics Intelligence
LED driver semiconductor costs originating from East Asian foundries cascade through three distinct pricing tiers before reaching East African municipal procurement departments, with tariff layering at each border crossing amplifying differentials between premium thermal-engineered luminaires and economy bulb retrofits.
Pricing Analysis
Capacity additions in Chinese and Vietnamese LED component manufacturing are reshaping price floors for standard-efficiency luminaires bound for Dar es Salaam and Nairobi distributor channels. Pricing stratifies across premium, standard, and economy tiers based on thermal management certification grade and after-sales service bundling. Cost compression in the residential retrofit segment is intensifying because Syska LED and Opple Lighting are aggressively expanding mobile-money-enabled distribution networks. Households in urban Kenyan corridors exhibit the highest price sensitivity, while Ethiopian industrial park facility managers prioritize thermal tolerance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with semiconductor driver components fabricated in China, Taiwan, and South Korea before consolidation in Shenzhen and Guangzhou export hubs. Luminaire assembly draws from aluminum heat sink extrusions, lithium battery cells for solar-integrated units, and chip-on-board LED packages. Tariff exposure accumulates through East African Community customs protocols when drivers transit from non-member states. Distribution runs through Dar es Salaam port logistics corridors for northern Tanzania industrial zones, with Nairobi-based distributors serving Kenyan county procurement portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
East Africa LED lighting functions as a geographic-arbitrage play where Kenyan regulatory stringency creates premium pricing headroom against Tanzanian port-accessible cost baselines.
For Market Incumbents: Deploy captive thermal simulation capabilities to defend municipal tender qualification requirements as Kenya's Energy Regulatory Authority and Tanzania's Energy and Water Utilities Regulatory Authority converge efficacy thresholds. Anchor position through backward integration into driver component sourcing to offset foreign exchange volatility in Ethiopian Birr and Kenyan Shilling corridors. Counter price-point competitors by bundling accelerated life-test documentation with commercial estate contracts. For New Entrants and Emerging Players: Capture underpenetrated positioning in Kampala's nascent municipal retrofit program before competitive saturation reaches Kenyan and Tanzanian levels. Penetrate Ugandan household segments through pay-as-you-go solar LED financing models enabled by mobile money infrastructure. Establish direct engagement with county-level electronic procurement portals that bypass legacy electrical distributor hierarchies. For Investors and Strategic Acquirers: Consolidation pressure builds where local assembly capabilities intersect with East African Community harmonized standards compliance. Target regional assemblers with captive thermal management engineering and established certificate reciprocity across Kenya-Tanzania-Uganda trade corridors. Monitor regulatory convergence between national energy regulators and African Continental Free Trade Area technical committees as the inflection signal for localized manufacturing incentives.| Strategic Initiative | Industry Significance |
|---|---|
| Localized Assembly Investment | Captures East African Community tariff advantages and shortens warranty response timelines for Ethiopian industrial zones. |
| Direct Municipal Engagement | Bypasses distributor margin layers in Kenyan county procurement portals requiring direct contractor accountability. |
| Thermal Engineering Certification | Qualifies for Nairobi and Dar es Salaam tenders specifying junction temperature tolerances exceeding 125°C. |
| Mobile Money Financing Integration | Unlocks household segments excluded from upfront capital requirements in urban Kenyan and Tanzanian settlements. |
| Narrowband IoT Platform Development | Positions for smart lighting pilots in Kenyan commercial estates as broadband infrastructure matures. |
Research Approach
Multiple input streams — regulatory filing analysis, customs trade data, and procurement portal monitoring — were reconciled with primary interviews involving municipal engineering directors, electrical distributor procurement leads, thermal management R&D specialists, and solar LED program officers at development organizations. Secondary validation incorporated Kenya Energy Regulatory Authority efficacy standard documents, Tanzania Energy and Water Utilities Regulatory Authority compliance bulletins, East African Community harmonization protocols, and multilateral development bank project disclosure databases. Bottom-up luminaire shipment estimates and top-down infrastructure investment flows were triangulated to anchor volume assumptions.
Data-stream reconciliation across product type, technology tier, application function, and end-user category dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth trajectory modeling incorporating solar photovoltaic cost compression curves, regulatory mandate implementation schedules, and municipal procurement fragmentation patterns. Forecast inputs included grid extension timelines for rural Tanzanian settlements and county-level budget allocation transparency indices for Kenyan retrofit programs.
Foreign exchange volatility, regulatory harmonization delays, and development finance disbursement interruptions are the dominant revision risks that could reshape trajectory assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Middle East and Africa Indoor LED Lighting Market
LED
LED Encapsulation Market
LED
High-Brightness Light-Emitting Diodes (LED) Headlamps Market
LED
LED Mask Market
LED
LED Flip Chip Market
LED
India LED Outdoor Lighting Market
LED
Vietnam LED Lighting Market
LED
Linear LED Strip Fixture Market
LED
Middle East and Africa Outdoor LED Lighting Market
LED
US and Europe LED Lighting Market
LED
Japan LED Market
LED
LED Work Light Market
LED
North America Micro-LED Display Market
LED
Smart LED Indoor Signage Market
LED
LED Phosphor Materials Market
LED
LED Light Market