
 Four-Digit 7 Segment LED Displays Market | 2026-2036
Four-Digit 7 Segment LED Displays Market Size, Share, and Industry Trends Forecast 2026-2036
Four-Digit 7 Segment LED Displays Market Analytics
Modular display configurations bundled with driver ICs and interface boards is broadening buyer choice across industrial and automotive procurement teams. Texas Instruments leverages its analog semiconductor heritage to sustain leadership in integrated driver solutions for multi-digit LED modules. STMicroelectronics anchors its position through specialized automotive-grade display controllers that meet stringent reliability requirements. Infineon Technologies competes by extending its power management expertise into efficient LED driver architectures for high-ambient industrial environments.
Four-digit 7 segment LED displays are electro-optical numeric indicators constructed from four independent seven-segment digit blocks, each containing eight or more individual gallium arsenide phosphide or indium gallium nitride emitters arranged to form numerals zero through nine plus decimal points, typically operating at forward currents between five and twenty milliamperes per segment with dominant wavelengths spanning red, green, blue, and amber spectra. These devices serve primarily as human-machine interface elements where immediate numeric readability, wide viewing angles, and immunity to ambient light interference outweigh graphical complexity requirements. Common cathode configurations dominate unit shipments due to simpler single-resistor current limiting and compatibility with standard logic families, while bi-color variants capture expanding margin pools in status-indication applications where dual-state visual feedback replaces separate indicator lamps. The analog technology segment retains substantial installed-base presence in legacy industrial equipment, though digital control interfaces with pulse-width modulation dimming are displacing purely resistive drive methods in new designs.
RoHS substance restrictions and REACH candidate list obligations enforced by ECHA constrain lead-frame plating chemistries and epoxy molding compound formulations across European supply chains. The EPA oversees hazardous substance reporting for display manufacturing facilities operating within the United States, while China's GB standards administered by SAMR mandate electromagnetic compatibility testing for electronic display modules sold domestically. Stakeholders must monitor evolving energy efficiency labeling requirements and substance disclosure mandates that increasingly differentiate market access conditions across major economies.
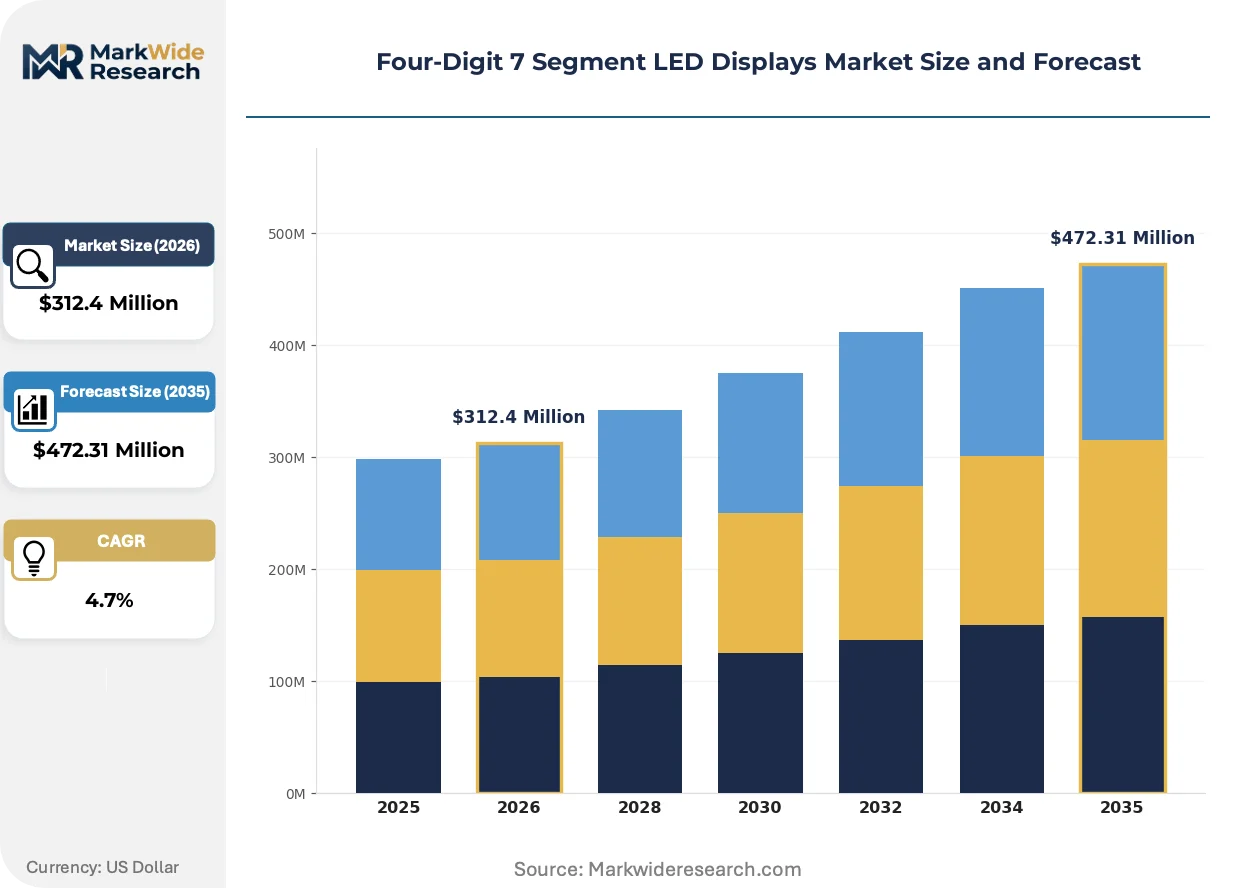
Market Dynamics
Industrial automation retrofits are pulling four-digit 7 segment LED displays into legacy control systems, creating a dual-track market where analog interfaces coexist with digitally addressable modules. Pulse-width modulation dimming protocols are compressing the design cycle for equipment OEMs seeking seamless integration with programmable logic controllers.
Growth Catalysts
- EU RoHS substance restrictions:Lead-free solder mandates are forcing component redesigns that favor surface-mount LED packages over through-hole alternatives. Display manufacturers in Shenzhen and Dongguan are retooling plating lines to maintain European market access.
- Automotive instrument clusters:Commercial vehicle dashboards are adopting four-digit modules for odometer and hour-meter readouts. Heavy-duty truck OEMs specify automotive-grade temperature ranges from -40°C to 85°C.
- Indium gallium nitride emitters:Blue and green spectrum dominance wavelengths are expanding into outdoor signage applications. Municipal traffic control systems specify these emitters for daylight-visible countdown timers.
Market Restraints
- Epoxy resin supply concentration:High-reflectivity potting compounds rely on bisphenol-A feedstocks concentrated in East Asian chemical parks. Price volatility in benzene derivatives squeezes gross margins for mid-tier display assemblers.
- LCD and OLED substitution:Graphical display modules are capturing price-insensitive segments requiring alphanumeric flexibility. Industrial HMI panels increasingly specify thin-film transistor LCDs for multi-parameter visualization.
- REACH candidate list expansion:ECHA's annual substance reviews threaten cadmium-based quantum dot phosphors used in some high-brightness variants. Formulation changes trigger six-month requalification cycles.
Strategic Opportunities
- India's PLI scheme for electronics:Domestic display module assembly incentives are attracting component distributors to establish kitting operations near Noida and Sri City. Local value-addition requirements favor common-cathode configurations with Indian-sourced resistors.
- Bi-color status indication:Dual-state emitters are displacing separate indicator lamps in elevator control panels and medical device interfaces. Red-green transitions communicate fault conditions without additional wiring.
- ISO 15031 diagnostic protocols:Automotive OBD-II compliance mandates standardized numeric readouts for emission-related fault codes. Aftermarket scan tool manufacturers specify four-digit formats for direct code display.
Industry Challenges
- Legacy PLC integration:24V industrial logic levels require level-shifting circuitry incompatible with standard TTL driver ICs. System integrators face software reconfiguration costs when retrofitting displays into 1990s-era equipment.
- Automotive AEC-Q101 qualification:The six-month stress-test protocol for discrete optoelectronics delays new product introductions. Thermal cycling and humidity bias testing consume significant engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Four-Digit 7 Segment LED Displays Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Common Cathode, Common Anode, Bi-Color, Multi-Color Technology: Analog, Digital, LCD, OLED Application: Consumer Electronics, Automotive Displays, Industrial Controls, Medical Equipment End User: Retailers, OEMs, Manufacturers, End Consumers |
| Companies Covered | NXP Semiconductors, STMicroelectronics, Texas Instruments, Toshiba, Infineon Technologies, Broadcom, Microchip Technology, Renesas Electronics, ON Semiconductor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Four-Digit 7 Segment LED Displays Market Evolving Landscape
Interface standardization is collapsing the distinction between standalone displays and subsystem modules, with I2C and SPI protocols displacing parallel bus architectures. Equipment designers now expect driver ICs with integrated brightness control and diagnostic feedback.
Integrated driver architectures are unifying current regulation, dimming, and fault detection within single-package solutions. Industrial control panel builders specify these modules to reduce bill-of-material complexity and assembly labor. The unification of analog and digital control paths is compressing procurement decisions toward qualified subsystem suppliers rather than discrete component sourcing.
China's GB standards administered by SAMR now mandate electromagnetic compatibility testing for all electronic display modules sold domestically. The surge immunity and electrostatic discharge requirements are filtering out uncertified imports from smaller Taiwanese and Korean suppliers. Domestic Chinese manufacturers with in-house testing laboratories are capturing share from foreign competitors facing six-week certification delays.
Equipment-as-a-service contracts are restructuring how display modules are specified and replaced. Packaging machinery OEMs in Germany now bundle display subsystems into total cost-of-ownership agreements with predictive maintenance clauses. The KBA's type-approval requirements for commercial vehicle instrumentation reinforce long-term supplier relationships over spot purchasing.
Four-Digit 7 Segment LED Displays Market Segmentation
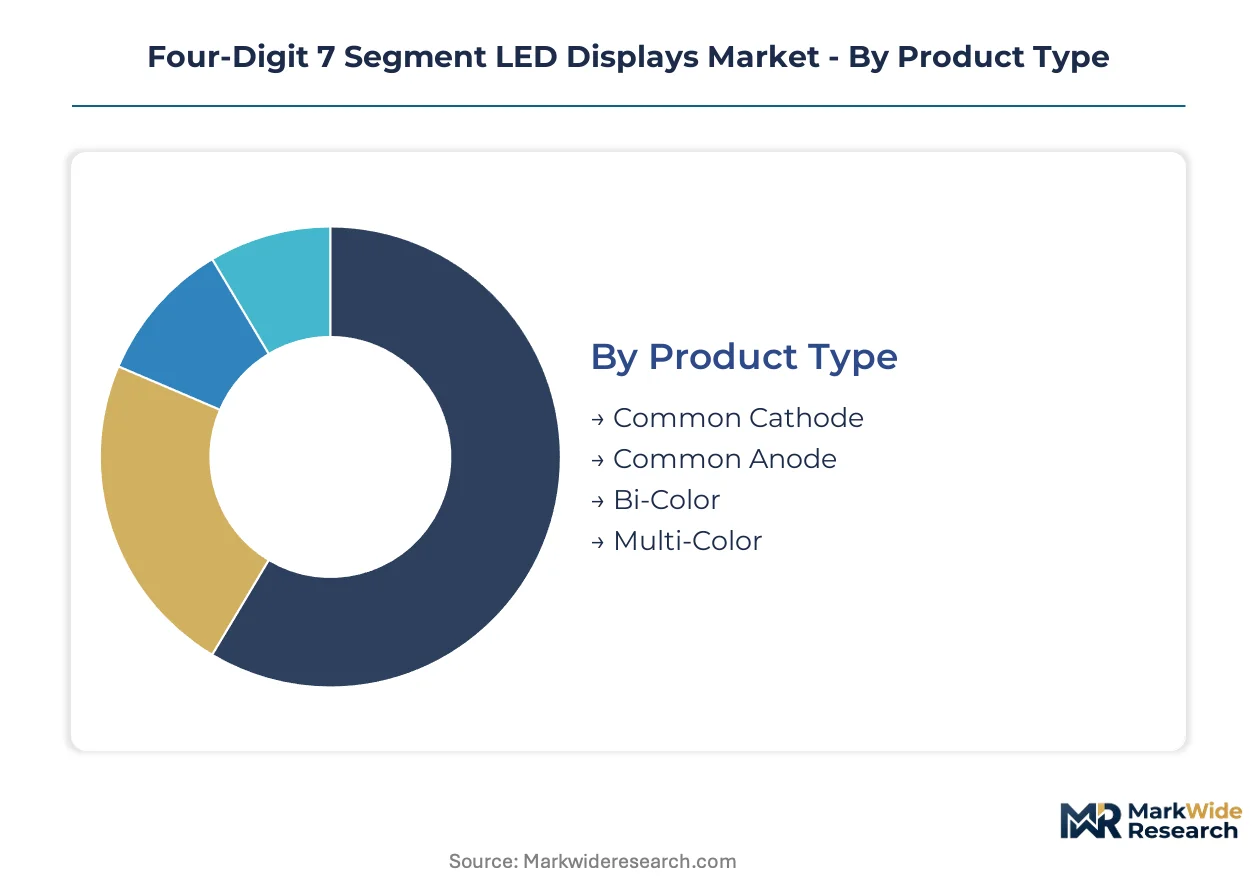
Four-digit 7 segment LED displays fragment across electrical architecture, control methodology, and buyer procurement patterns. Equipment designers select configurations based on legacy system compatibility, ambient operating conditions, and total subsystem integration costs.
Product Type:
Procurement teams prioritize driver circuit simplicity and thermal management when selecting electrical configurations for multi-digit modules.
- Common Cathode:All segment cathodes connect to a shared ground rail, enabling single-resistor current limiting per digit. Manufacturing facilities in China specify these modules for industrial timers and process counters where straightforward TTL logic interfacing reduces firmware overhead.
- Common Anode:Shared positive voltage rail requires active-low driver logic, complicating microcontroller interfacing but simplifying high-side switching in automotive 12V systems. German commercial vehicle OEMs specify common anode architectures for dashboard hour-meters to leverage existing wiring harness designs.
- Bi-Color:Dual-emitter segments switch between red and green states without additional discrete indicators. Elevator control panels and medical device interfaces specify these variants for fault-condition visualization.
- Multi-Color:RGB-capable segments enable programmable hue adjustment across the full spectrum. Architectural countdown timers and premium appliance displays specify these for brand-customizable aesthetics.
Volume sits with Common Cathode; growth tilts toward Bi-Color.
Technology:
Control interface selection determines integration labor and subsystem qualification requirements across equipment categories.
- Analog:Resistive current limiting with fixed brightness operates without microcontroller intervention. Legacy industrial equipment in the United States retains substantial installed base of purely analog drive circuits.
- Digital:Pulse-width modulation dimming and I2C/SPI bus architectures enable software-defined brightness and diagnostic feedback. New industrial control panel designs specify digital interfaces to reduce bill-of-material complexity.
- LCD:Liquid crystal alternatives capture applications requiring alphanumeric flexibility beyond numeric-only readouts.
- OLED:Organic emitter technology penetrates price-insensitive segments demanding high contrast and wide viewing angles.
Installed base concentrates in Analog; new design activity favors Digital.
Application:
End-use environmental specifications drive emitter chemistry and package sealing requirements.
- Consumer Electronics:Cost-optimized modules with standard temperature ranges serve appliance timers and fitness equipment displays.
- Automotive Displays:AEC-Q101-qualified packages with -40°C to 85°C ratings serve odometers and diagnostic code readouts in commercial vehicles.
- Industrial Controls:High-brightness indium gallium nitride emitters with conformal coating withstand factory floor vibration and chemical exposure.
- Medical Equipment:Isolation-rated drivers and EMI-shielded enclosures serve patient-monitoring systems requiring IEC 60601 compliance.
Shipment volume concentrates in Industrial Controls; qualification complexity peaks in Medical Equipment.
End User:
Channel structure determines technical support expectations and volume pricing tiers.
- Retailers:Distributors stocking standard configurations for maintenance replacement and small-batch projects.
- OEMs:Original equipment manufacturers specifying qualified subsystems for multi-year production contracts.
- Manufacturers:Display module assemblers sourcing bare LED matrices and driver ICs for captive integration.
- End Consumers:Hobbyist and educational markets purchasing through electronics component retailers.
Revenue concentrates with OEMs; margin expansion targets Manufacturers pursuing backward integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Chinese electronics clusters while consumption spreads across industrial automation hubs in Germany, the United States, and Japan. Component sourcing follows divergent regulatory pathways as RoHS compliance in Europe, GB standards in China, and EPA reporting in the United States reshape supply chain configurations.
China
Shenzhen and Dongguan manufacturers dominate module assembly for industrial timers and process counters. SAMR-administered GB standards mandate electromagnetic compatibility testing that filters uncertified imports. Domestic firms with in-house laboratories capture share from Taiwanese competitors facing six-week certification delays in Shanghai and Beijing testing centers.
Germany
Commercial vehicle OEMs in Stuttgart and Munich specify common anode architectures for dashboard hour-meters leveraging existing wiring harness designs. KBA type-approval requirements reinforce long-term supplier relationships over spot purchasing. Bavarian packaging machinery builders bundle display subsystems into equipment-as-a-service contracts with predictive maintenance clauses.
United States
Legacy industrial equipment in Midwest manufacturing belts retains substantial installed base of analog drive circuits. EPA hazardous substance reporting constrains plating chemistries for display manufacturing facilities operating in Texas and Ohio. System integrators face software reconfiguration costs when retrofitting displays into 1990s-era programmable logic controllers.
Japan
Automotive instrument cluster suppliers in Nagoya and Tokyo specify AEC-Q101-qualified packages for odometer readouts. METI industrial policy supports domestic semiconductor initiatives that accelerate local procurement of display modules. Kyushu-based electronics assemblers specialize in medical equipment interfaces requiring IEC 60601 compliance.
India
Domestic display module assembly incentives under the PLI scheme attract component distributors to Noida and Sri City kitting operations. DGFT import substitution mandates favor common-cathode configurations with Indian-sourced resistors. Tamil Nadu and Karnataka electronics parks host backward integration efforts by appliance timer manufacturers.
Four-Digit 7 Segment LED Displays Market Competitive Landscape
The competitive structure tilts toward integrated semiconductor suppliers with analog heritage and specialized automotive-grade portfolios. Tier-one positions concentrate among diversified chipmakers bundling driver ICs with power management expertise. Three archetypes dominate: analog semiconductor incumbents extending into LED drivers, automotive-qualified specialists commanding premium positioning, and industrial-focused subsystem integrators compressing bill-of-material complexity. Capacity expansion in East Asian packaging facilities and strategic partnerships between driver IC suppliers and display assemblers represent the dominant competitive moves.
Among diversified semiconductor suppliers, Texas Instruments exemplifies the analog heritage archetype through integrated driver solutions, while STMicroelectronics anchors the automotive-grade specialization tier with reliability-focused controllers. Infineon Technologies occupies a position extending power management expertise into efficient LED driver architectures. These three firms represent distinct strategic postures rather than direct substitutes, with each anchoring procurement decisions across different buyer segments based on application requirements and qualification standards.
| Leading Market Players |
|---|
| NXP Semiconductors |
| STMicroelectronics |
| Texas Instruments |
| Toshiba |
| Infineon Technologies |
| Broadcom |
| Microchip Technology |
| Renesas Electronics |
| ON Semiconductor |
| Others |
Value Network & Pricing Analysis
Automotive OEM procurement teams mandating AEC-Q101 qualification for dashboard hour-meters are compressing supplier margins and forcing display assemblers toward captive driver IC production. This specification-driven consolidation is reshaping tier relationships across Shenzhen and Dongguan manufacturing clusters.
Pricing Analysis
Margin tightening in economy-tier common-cathode modules reflects benzene derivative volatility in epoxy resin feedstocks. Three-tier pricing structure across AEC-Q101 automotive, industrial-grade, and consumer-tier segments separates qualified subsystem suppliers from commodity assemblers. Pricing pressure stems from LCD substitution in multi-parameter HMI panels. OEM procurement teams exhibit lowest price sensitivity; aftermarket maintenance buyers drive hardest bargain.
Supply Chain Analysis
Refurbishment flows for legacy 24V industrial timers create secondary component channels alongside primary module distribution. Supply concentrates in China, Taiwan, and South Korea for LED epitaxy and driver IC fabrication. High-reflectivity potting compounds draw from concentrated East Asian chemical parks. Single-source vulnerability sits with indium gallium nitride wafer supply. Distribution runs through specialized electronics distributors serving industrial automation and automotive Tier 1 suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as driver IC suppliers acquire display assembly capabilities to capture subsystem margins and compress OEM procurement cycles.
For Market Incumbents: Anticipate LCD and OLED substitution threats in price-insensitive industrial HMI segments by deepening backward integration into indium gallium nitride epitaxy. Secure AEC-Q101 qualification pipelines through captive stress-testing laboratories. Channel control via long-term supply agreements with German commercial vehicle OEMs reinforces position against emerging subsystem integrators. For New Entrants and Emerging Players: Enter via India's PLI scheme electronics parks, where domestic value-addition requirements favor kitting operations with Indian-sourced resistors. Bi-color status indication in elevator and medical device interfaces offers lowest qualification barrier. Direct sales to appliance timer manufacturers in Tamil Nadu bypass established distributor relationships. For Investors and Strategic Acquirers: The window for entry favors automotive-qualified subsystem integrators with in-house EMC testing capabilities. Long-term viability hinges on equipment-as-a-service contract penetration in German packaging machinery. Watch for KBA type-approval consolidation signals indicating preferred supplier list narrowing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Driver IC Design | Captures margin pools from Texas Instruments and STMicroelectronics in automotive subsystem sales. |
| AEC-Q101 Qualification Investment | Unlocks KBA type-approval pathways for Stuttgart and Munich commercial vehicle OEMs. |
| GB Standards EMC Certification | Mandatory SAMR compliance filters Taiwanese competitors from China domestic procurement. |
| Bi-Color Product Line Expansion | Displaces separate indicator lamps in elevator control panels requiring IEC 60601 compliance. |
| Equipment-as-a-Service Partnership | Bavarian packaging machinery OEMs bundle predictive maintenance clauses with display subsystem supply. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs alongside primary interviews with industrial control panel procurement managers, automotive Tier 1 supplier engineers, display module manufacturing directors, and aftermarket electronics distributors. SEC 10-K disclosures, SAMR certification databases, and ECHA REACH substance notifications provided cross-validation. Bottom-up shipment estimates from Shenzhen and Dongguan assemblers reconciled with top-down OEM demand aggregation.
Data-stream reconciliation across analog and digital control interface segments, common-cathode versus common-anode architectures, and automotive-industrial-consumer application tiers informed the analytical framework. CAGRs derived from segment-level volume projections and average selling price trajectories across the projection horizon. Indium gallium nitride emitter adoption curves and RoHS compliance transition timelines served as industry-specific forecast inputs.
Revisions become necessary when REACH candidate list expansions trigger six-month requalification cycles or when India's PLI scheme subsidy structures shift domestic assembly economics. Forecasts reflect assumptions about epoxy resin feedstock stability and AEC-Q101 testing capacity availability. Practitioners should monitor ECHA substance reviews and KBA type-approval backlog indicators for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Superluminescent Diodes Market
LED
Organic Light Emitting Diode (OLED) Market
LED
LED and OLED Display Market
LED
North America Outdoor LED Lighting Market
LED
Global LED Phosphor Market
LED
India Indoor LED Lighting Market
LED
Bluetooth LED Bulb Market
LED
UK LED Lighting Market
LED
North America LED Lighting Market
LED
Asia Pacific Indoor LED Lighting Market
LED
Middle East and Africa Outdoor LED Lighting Market
LED
LED Chip Market
LED
North America Commercial LED Lighting Market
LED
Europe LED Packaging Market
LED
OLED Blue Emitter Market
LED
China Outdoor LED Lighting Market