
 Philippines LED Market | 2026-2036
Philippines LED Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines LED Market Intelligence
Buyer concentration across Philippine municipalities is restructuring procurement patterns for street and roadway illumination. Omniphil, Inc. leverages its distribution network across provincial government units to secure bulk lighting contracts. Signify Philippines anchors its position through energy-service-company partnerships that finance retrofit projects without upfront capital from local governments. Firefly Electric & Lighting Corporation differentiates through domestic manufacturing of entry-level fixtures priced for barangay-level budgets.
Light-emitting diode technology converts electrical current into visible light through a semiconductor chip doped with gallium nitride or indium gallium nitride, achieving luminous efficacy exceeding 150 lumens per watt in premium architectures while operating at junction temperatures below 85 degrees Celsius. The technology serves commercial and industrial end users seeking to reduce cooling loads and extend maintenance intervals in tropical climates. Indoor product types occupy the largest installed base, while Mini LED technology represents the fastest-growing segment as display manufacturers in Clark Freeport Zone adopt finer pixel pitches for digital signage. Specialty applications command the highest margin pools, particularly horticultural fixtures for Cavite greenhouse operations and UV-C sterilization units for hospital procurement.
The Department of Energy enforces the Philippine Energy Labeling Program, which grades LED lamps on luminous efficacy and color rendering index, directly filtering products eligible for government tenders. BIS-equivalent testing protocols administered by the Department of Trade and Industry's Bureau of Product Standards require photometric and electrical safety certification before market entry, creating compliance barriers for unverified imports. Stakeholders must monitor pending amendments to the Renewable Energy Act that could extend tax incentives to energy-efficient lighting retrofits in manufacturing zones.
Market Dynamics
Municipal streetlight retrofit programs across Luzon and Visayas are compressing replacement cycles from fifteen years to seven, forcing fixture manufacturers to reconfigure warranty structures and service networks around accelerated depreciation schedules.
Growth Catalysts
- Philippine Energy Efficiency Roadmap:The Department of Energy's minimum luminous efficacy standards for public procurement filter inferior imports from government tenders, elevating certified domestic suppliers.
- Metro Manila commercial real estate:Green building certification requirements under BERDE and LEED drive specification of high-efficacy LED systems in new tower developments.
- Gallium nitride chip architectures:Premium semiconductor materials achieve junction temperatures below 85 degrees Celsius, reducing cooling loads in tropical installations and extending maintenance intervals.
Market Restraints
- Import dependency for semiconductor substrates:Philippine manufacturers lack captive gallium nitride wafer production, exposing margins to Taiwan and China supply concentration.
- Bureau of Product Standards certification timeline:BIS-equivalent photometric and electrical safety testing creates six-to-nine month market entry barriers for unverified imports.
- Fluorescent and halogen residual stock:Barangay-level budgets and informal electrical contractors sustain demand for legacy technologies in price-sensitive rural installations.
Strategic Opportunities
- Mindanao agricultural zones:Horticultural LED fixtures for Cavite-style greenhouse replication in Davao del Norte and Bukidnon remain underpenetrated relative to Luzon deployment density.
- Energy-service-company financing:Zero-upfront-capital retrofit structures for provincial government units expand addressable municipal budgets beyond traditional procurement limits.
- UV-C sterilization convergence:Hospital procurement protocols integrating antimicrobial lighting with HVAC systems create specification pull for multi-function fixtures.
Industry Challenges
- Photometric engineering talent scarcity:Domestic universities produce insufficient lighting designers familiar with IESNA standards and DIALux simulation, forcing reliance on foreign consultants.
- Legacy electrical contractor training:Informal installation networks lack certification for smart lighting control integration, creating commissioning failures that damage brand reputation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines LED Market |
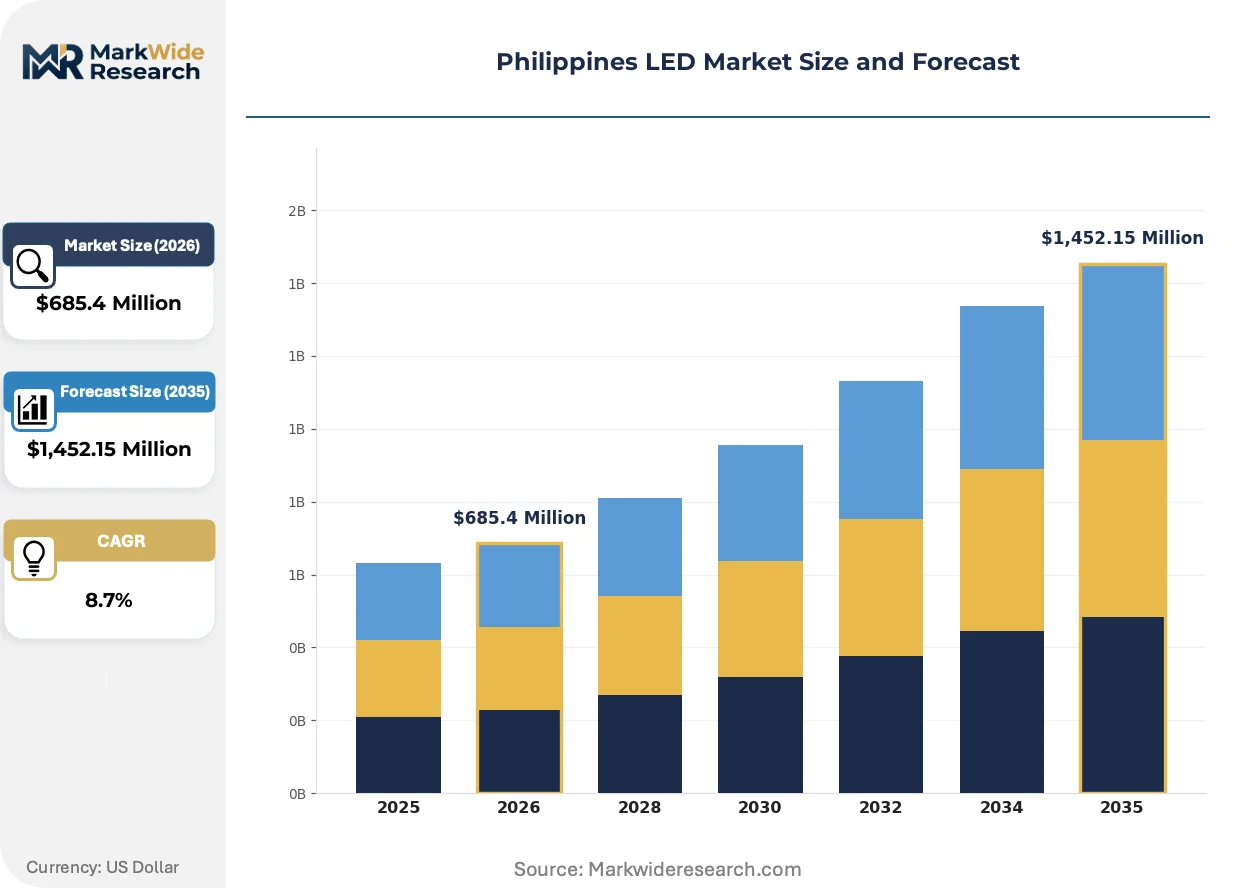
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor, Outdoor, Automotive, Specialty Technology: SMD, COB, OLED, Mini LED Application: Advertising, Residential, Commercial, Industrial End User: Retailers, Hotels, Manufacturers, Municipalities |
| Companies Covered | Panasonic Manufacturing Philippines Corporation, Omniphil, Inc., Signify Philippines (Philips Lighting), Osram Philippines, Inc., GE Philippines, Inc., Firefly Electric & Lighting Corporation (FELCO), Samsung Electronics Philippines Corporation, Toshiba Philippines, Inc., Akari Lighting & Technology Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines LED Market Strategic Shifts & Innovations
Mini LED pixel architecture is compressing display manufacturing into the Clark Freeport Zone, while regulatory enforcement tightens around efficacy labeling and safety certification protocols.
Smart lighting control systems is integrating wireless mesh protocols with daylight harvesting sensors, enabling granular zone-level dimming in BPO office towers. Ayala Land and SM Prime specifications now mandate DALI-2 compatibility for new commercial developments. This convergence is integrating facility management software with lighting infrastructure, compressing the traditional divide between MEP contractors and IT systems integrators.
The Department of Energy's Philippine Energy Labeling Program now grades LED lamps on luminous efficacy and color rendering index, filtering products eligible for government tenders. Industrial consequence includes accelerated phase-out of sub-100 lumens-per-watt imports from procurement pipelines. Local distributors are responding by pre-certifying inventory through Bureau of Product Standards testing to maintain eligibility for Department of Public Works and Highways streetlight contracts.
Barangay-level procurement is consolidating through provincial government unit bulk purchasing agreements, displacing fragmented municipal tender processes. Omniphil and similar distributors capture volume through aggregated demand rather than individual municipal sales. This concentration is most visible in Central Luzon and Western Visayas, where regional development councils coordinate lighting retrofits across multiple local government units simultaneously.
Philippines LED Market Segmentation
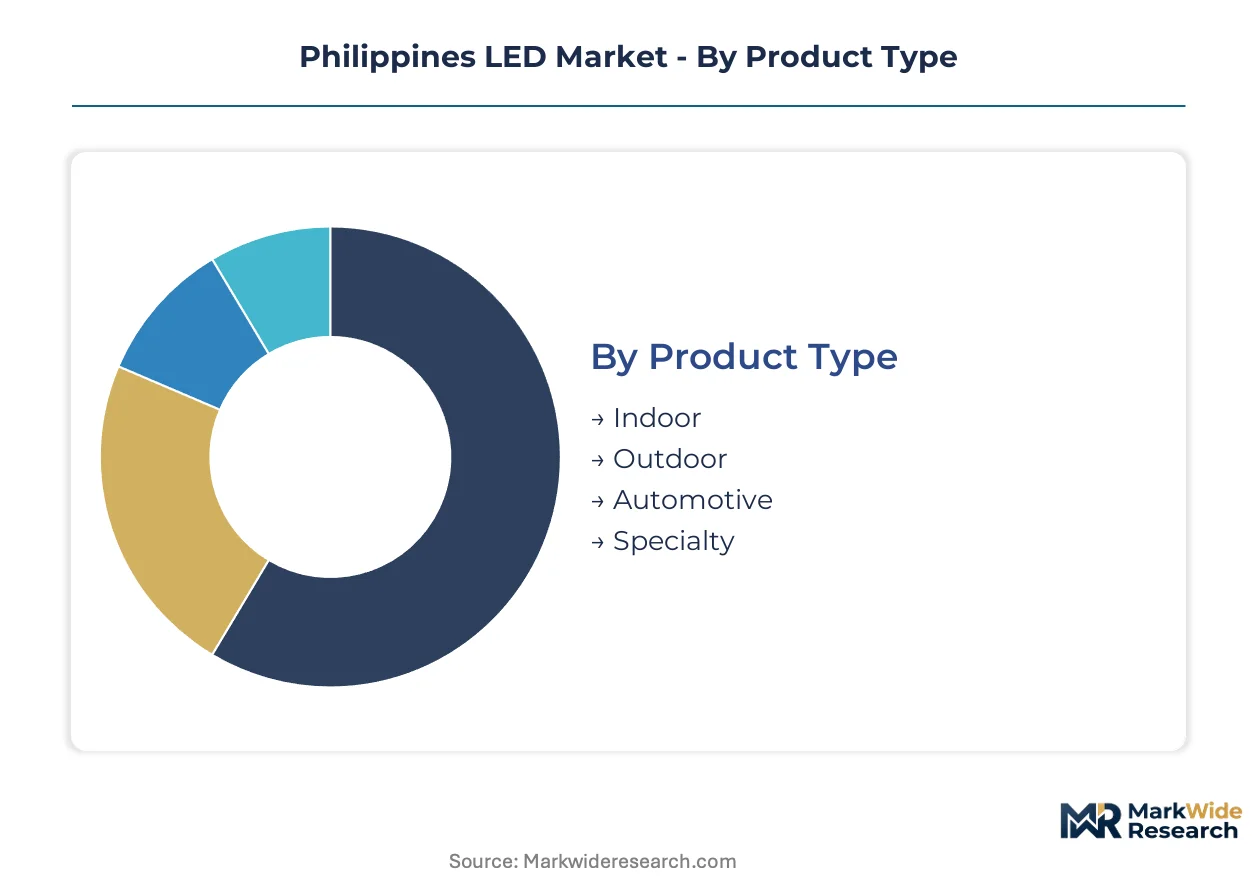
Segmentation in the Philippine LED market reveals how procurement power concentrates across distinct buyer clusters and technology tiers. Understanding these divides exposes where margin pools form and which specifications dominate tender requirements.
Product Type:
Supply concentration in indoor fixture manufacturing creates cost advantages for domestic assemblers serving Metro Manila's commercial tower developments.
- Indoor:Panel and downlight configurations dominate installation schedules in BPO office towers and Ayala Land retail complexes. Demand clusters in green-certified buildings where BERDE and LEED specifications mandate high-efficacy systems with DALI-2 control compatibility.
- Outdoor:Street and roadway luminaires absorb bulk procurement volumes from Department of Public Works and Highways tenders across Luzon and Visayas retrofit programs. Warranty compression to seven-year cycles forces manufacturers to reconfigure service networks around accelerated depreciation.
- Automotive:Headlamp and interior lighting modules serve vehicle assembly operations in Laguna and Cavite manufacturing zones.
- Specialty:Horticultural fixtures for Cavite greenhouse operations and UV-C sterilization units for hospital procurement command premium margin pools.
Today's leader: Indoor. Tomorrow's challenger: Specialty.
Technology:
Cost tier separation between mature packaging formats and emerging architectures determines which suppliers capture municipal versus premium commercial specifications.
- SMD:Surface-mount device packages dominate volume production for standard indoor and outdoor applications. Philippine distributors leverage established Taiwan and China supply chains to maintain inventory depth for government tender eligibility.
- COB:Chip-on-board architectures concentrate in high-bay industrial installations where lumen density requirements exceed SMD practical limits. Demand pulls from manufacturing zones in Batangas and Laguna seeking reduced maintenance intervals.
- OLED:Organic electroluminescent panels occupy niche architectural accent and display applications with limited local assembly presence.
- Mini LED:Finer pixel pitch architectures are expanding most quickly as display manufacturers in Clark Freeport Zone adopt the technology for digital signage production.
SMD commands current volume. Mini LED climbs the fastest.
Application:
Customer type differentiation separates specification-driven commercial projects from price-sensitive residential installations.
- Commercial:Office tower and retail complex developments in Metro Manila and Cebu drive specification of high-efficacy systems with smart control integration. Green building certification requirements filter procurement toward certified suppliers with Bureau of Product Standards pre-approval.
- Industrial:Manufacturing facility retrofits in CALABARZON and Central Luzon economic zones prioritize cooling load reduction and extended maintenance intervals.
- Advertising:Digital billboard and display networks concentrate in Metro Manila's high-traffic corridors.
- Residential:Barangay-level budgets and informal electrical contractor networks sustain demand for entry-level fixtures with minimal smart feature integration.
Commercial leads specification value. Industrial offers expansion headroom.
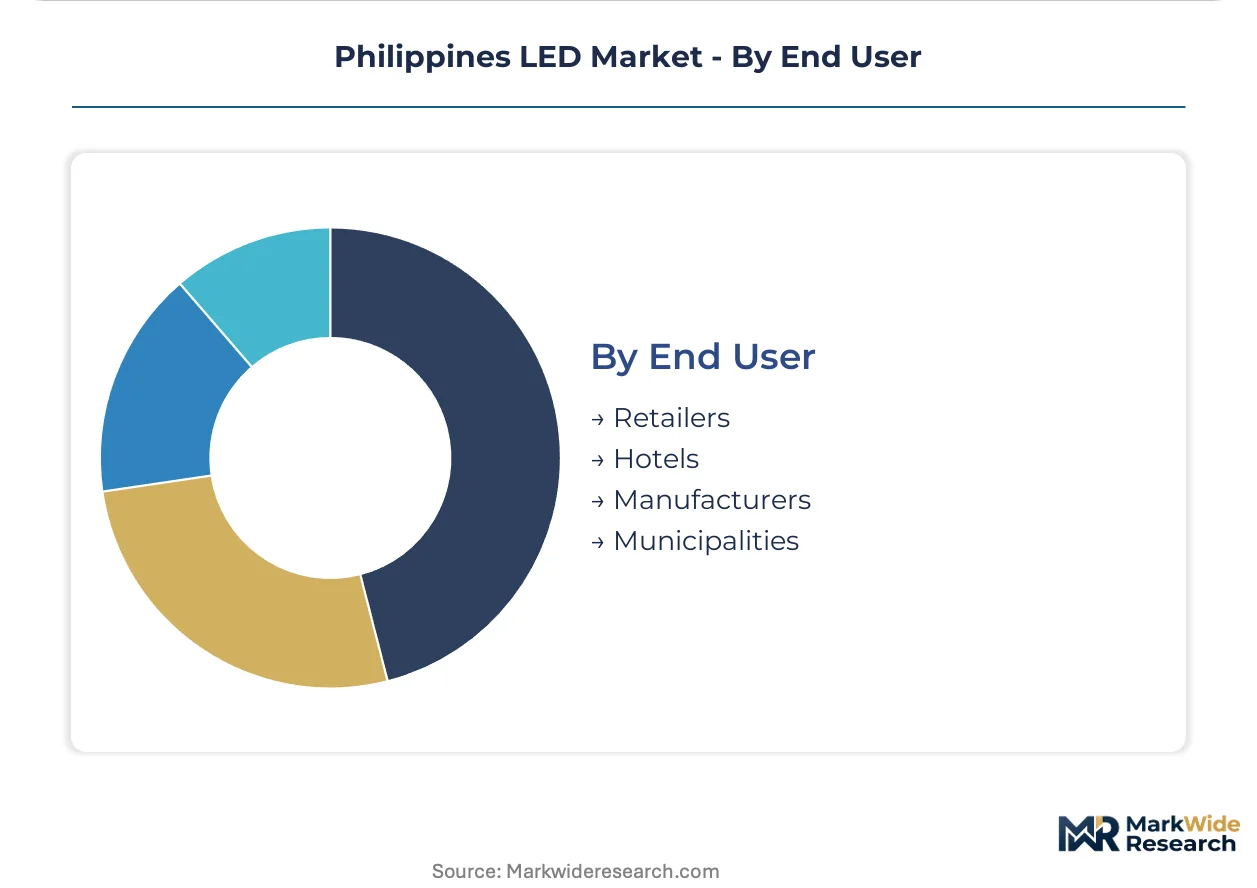
End User:
Procurement pattern variation across buyer types determines whether suppliers compete on financing structures, certification compliance, or unit economics.
- Municipalities:Provincial government units and local government authorities aggregate demand through bulk purchasing agreements displacing fragmented tender processes. Omniphil and similar distributors capture volume through regional development council coordination in Central Luzon and Western Visayas.
- Hotels:Cebu and Boracay hospitality developments specify high color-rendering-index fixtures for guest experience differentiation.
- Retailers:SM Prime and Robinsons Land procurement protocols mandate standardized fixture families across nationwide store networks.
- Manufacturers:Export processing zone facilities in Clark and Subic Bay prioritize energy cost reduction through high-efficacy retrofits.
Municipalities drive aggregated volume. Hotels command specification premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Photometric engineering talent clusters in Metro Manila and Cebu anchor the Philippines LED market's technical specification capacity, with provincial distribution networks extending procurement reach into secondary municipalities.
Metro Manila
Commercial real estate developments in Makati and Bonifacio Global City drive specification of DALI-2 compatible high-efficacy systems. The Department of Energy's Philippine Energy Efficiency Roadmap mandates minimum luminous efficacy standards for public procurement, filtering substandard imports from government tenders. Green building certification requirements under BERDE and LEED compress fixture selection timelines in Ayala Land and SM Prime tower developments.
Central Luzon
Clark Freeport Zone display manufacturers accelerate Mini LED adoption for digital signage production with finer pixel pitch requirements. The Bureau of Product Standards administers BIS-equivalent photometric and electrical safety certification, creating six-to-nine month compliance timelines for unverified imports. Regional development councils in Pampanga and Bulacan coordinate aggregated procurement across multiple provincial government units.
CALABARZON
Manufacturing facility retrofits in Batangas and Laguna prioritize cooling load reduction through premium gallium nitride chip architectures. Export processing zone incentives under the Philippine Economic Zone Authority attract energy-intensive industries seeking high-efficacy lighting infrastructure. Cavite greenhouse operations deploy horticultural fixtures for controlled-environment agriculture expansion.
Visayas
Cebu hospitality developments specify high color-rendering-index fixtures for guest experience differentiation in beachfront and urban resort properties. Municipal streetlight retrofit programs across Western Visayas compress replacement cycles from fifteen years to seven, forcing warranty reconfiguration. Iloilo and Bacolod regional development councils replicate Central Luzon's aggregated procurement models.
Mindanao
Davao del Norte and Bukidnon agricultural zones remain underpenetrated for horticultural LED replication relative to Luzon deployment density. Mindanao Development Authority corridors seek energy-service-company financing structures to overcome capital constraints in provincial government units. Cagayan de Oro commercial developments lag Metro Manila specification standards by two to three certification cycles.
Philippines LED Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across procurement tiers, with market structure consolidating around three dominant archetypes. Japanese and Korean electronics conglomerates leverage semiconductor supply chain integration to anchor premium commercial specifications. Domestic distributors capture municipal volume through provincial government unit relationships and bulk purchasing coordination. Specialized lighting manufacturers differentiate through domestic assembly capabilities and barangay-level price positioning. Competitive dynamics center on certification pre-approval acceleration and energy-service-company partnership structures that eliminate upfront capital barriers.
Among Japanese electronics conglomerates, Panasonic Manufacturing Philippines Corporation and Toshiba Philippines, Inc. occupy positions emphasizing integrated semiconductor-to-fixture supply chain control. Domestic distribution specialists exemplify the municipal procurement archetype, with Omniphil, Inc. representing aggregated demand capture across provincial government units. Signify Philippines anchors the premium commercial tier through energy-service-company financing partnerships that restructure retrofit economics for local governments.
| Leading Market Players |
|---|
| Panasonic Manufacturing Philippines Corporation |
| Omniphil, Inc. |
| Signify Philippines (Philips Lighting) |
| Osram Philippines, Inc. |
| GE Philippines, Inc. |
| Firefly Electric & Lighting Corporation (FELCO) |
| Samsung Electronics Philippines Corporation |
| Toshiba Philippines, Inc. |
| Akari Lighting & Technology Corporation |
| Others |
Cost & Logistics Intelligence
Provincial government unit bulk purchasing agreements across Central Luzon and Western Visayas are compressing unit economics for fixture manufacturers, forcing suppliers to absorb volume discounts or surrender market share to Omniphil's aggregated distribution network. This procurement consolidation is reshaping margin structures and accelerating certification pre-investment as a defensive necessity.
Pricing Analysis
Capacity additions in China's gallium nitride wafer foundries are reshaping price floors for premium LED architectures, transmitting cost compression downstream to Philippine distributors. Pricing stratifies across Bureau of Product Standards-certified, pre-certified, and uncertified tiers, with certification grade commanding the steepest premium differential. Margins are tightening in the standard indoor segment due to SMD package commoditization, while specialty horticultural and UV-C sterilization fixtures retain pricing power. Barangay-level residential procurement exhibits the highest price sensitivity, whereas green-certified commercial towers in Metro Manila prioritize performance specifications over unit cost.
Supply Chain Analysis
The Department of Trade and Industry's domestic-content preferences for public procurement are reshaping sourcing strategies, incentivizing local assembly of entry-level fixtures even when semiconductor substrates remain imported. Philippine manufacturing draws from Taiwan and China for gallium nitride wafers, from South Korea for phosphor materials, and from Japan for precision optics. Single-source vulnerability concentrates in Taiwan's foundry capacity for premium chip architectures. Distribution runs through Omniphil's provincial government unit relationships and Signify's energy-service-company financing partnerships, with direct-to-municipal sales declining as regional development councils consolidate demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Philippines LED market functions as a regulatory-arbitrage play where Bureau of Product Standards certification timelines create six-to-nine month moats against unverified imports, rewarding pre-certified inventory investment over pure cost competition.
For Market Incumbents: Deepen backward integration into gallium nitride packaging partnerships with Taiwanese foundries to secure wafer allocation ahead of capacity constraints. Accelerate DALI-2 control system certification to capture Ayala Land and SM Prime green-building specifications, defending against Korean electronics conglomerates with captive semiconductor supply. Pre-position service networks for seven-year warranty cycles before municipal retrofit programs compress replacement schedules further. For New Entrants and Emerging Players: Energy-service-company financing partnerships offer the most penetrable entry vector for provincial government units lacking upfront capital for streetlight retrofits. Target Mindanao's Davao del Norte and Bukidnon agricultural zones where horticultural LED deployment lags Luzon density by substantial margins. Lead with zero-capex retrofit structures that replicate Signify's municipal financing model without requiring incumbent-scale balance sheets. For Investors and Strategic Acquirers: Asymmetric upside sits with domestic distributors possessing pre-certified inventory depth and established provincial government unit relationships, as Bureau of Product Standards compliance timelines extend competitive moats. Long-term viability hinges on positioning for energy-service-company financing proliferation across undercapitalized municipalities. Watch for amendments to the Renewable Energy Act extending tax incentives to manufacturing zone retrofits as the critical policy inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into GaN Wafer Partnerships | Taiwanese foundry allocation secures supply continuity for premium chip architectures ahead of capacity constraints. |
| DALI-2 Control System Certification | Ayala Land and SM Prime green-building specifications mandate compatibility, filtering non-certified suppliers from tower developments. |
| Energy-Service-Company Financing Launch | Zero-upfront-capital structures expand addressable municipal budgets beyond traditional procurement limits for provincial government units. |
| Horticultural LED Geographic Expansion | Mindanao agricultural zones in Davao del Norte and Bukidnon remain underpenetrated relative to Cavite greenhouse deployment density. |
| Seven-Year Warranty Service Network Buildout | Municipal retrofit programs across Luzon and Visayas compress replacement cycles from fifteen years, demanding accelerated depreciation coverage. |
Research Approach
Bottom-up municipal and commercial end-use modeling reconciled against top-down semiconductor substrate and fixture import tracking forms the analytical core of this study. Primary interviews with Department of Energy procurement officers, Bureau of Product Standards certification managers, provincial government unit engineering departments, and energy-service-company financing directors combined with secondary validation from Bureau of Customs import records, Department of Public Works and Highways tender databases, and Philippine Economic Zone Authority facility filings. Triangulation across these sources calibrated volume estimates for streetlight retrofit programs and commercial tower specifications.
Historical trendline analysis of luminous efficacy standards evolution and municipal procurement cycle compression informed projection parameters across the analysis window. Segmentation modeling incorporated product type, technology architecture, application vertical, and end-user procurement pattern dimensions. CAGRs derived from fitting logistic adoption curves to green-building certification penetration rates and energy-service-company financing uptake trajectories. Forecast inputs included gallium nitride chip cost decline trajectories and Bureau of Product Standards certification timeline stability assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Renewable Energy Act amendment timing and Taiwanese foundry capacity allocation shifts. Projections reflect assumptions around sustained Department of Energy efficacy mandate enforcement and stable provincial government unit aggregation momentum. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Global Outdoor LED Lighting Market
LED
Programmable LED Drivers Market
LED
Bluetooth LED Bulb Market
LED
High-Intensity LED Logo and Livery Lighting Systems Market
LED
Light Emitting Diode (LED) Backlight Display Market
LED
Global Industrial and Commercial LED Lighting Market
LED
Asia Pacific Outdoor LED Lighting Market
LED
Biometrics Infrared LED Market
LED
High-Brightness Light-Emitting Diodes (LED) Headlamps Market
LED
Gan Micro LED Market
LED
North America LED Lighting Market
LED
India LED Lighting Market
LED
LED Downlight Market
LED
LED Floodlight Drivers Market
LED
Africa LED and OLED Displays and Lighting Products Market
LED
LED Light Bar Market