
 LED Services Market | 2026-2036
LED Services Market Size, Share, and Industry Trends Forecast 2026-2036
LED Services Market Intelligence
The specialized expertise in integrating smart lighting controls and IoT systems is bifurcating the service provider landscape. This creates a divide between basic installers and high-value system integrators. Signify Holding leverages its extensive portfolio of connected lighting systems to command the high-value segment. Meanwhile, Acuity Brands competes effectively in North American commercial markets through strong distribution channels and tailored solutions for facility managers.
LED services encompass the professional activities for planning, deploying, and managing lighting systems, distinct from the hardware sale. This includes network configuration for Power over Ethernet (PoE) lighting and programming for dynamic control systems. While installation services form the market's volume base, consultation and maintenance for complex commercial and industrial applications generate higher margins. These advanced services are critical for end users like architects and facility managers seeking to optimize building performance.
Regulatory frameworks such as the EU's RoHS directive and the US EPA's ENERGY STAR program set minimum performance and material standards. In China, GB standards for energy efficiency in buildings directly stimulate demand for professional retrofitting services. Service providers must now decide whether to specialize in high-margin smart building integration or scale operations for volume-based retrofit projects.
Market Dynamics
The bifurcation of service providers into basic installers and high-value system integrators is the market's central dynamic. This split is driven by demand for complex IoT and smart control integration, separating volume-based retrofits from margin-rich consultation and management services for intelligent buildings.
Growth Catalysts
- Energy Efficiency Mandates:Policies like the EU Green Deal require verifiable performance improvements, directly stimulating demand for professional retrofitting and management services.
- Commercial Real Estate Upgrades:Facility managers are upgrading entire building portfolios to smart lighting, driving large-scale demand for deployment and integration services.
- Smart City Development:Advanced services are concentrating in infrastructure projects in the United States, India, and China, requiring specialized network configuration.
Market Restraints
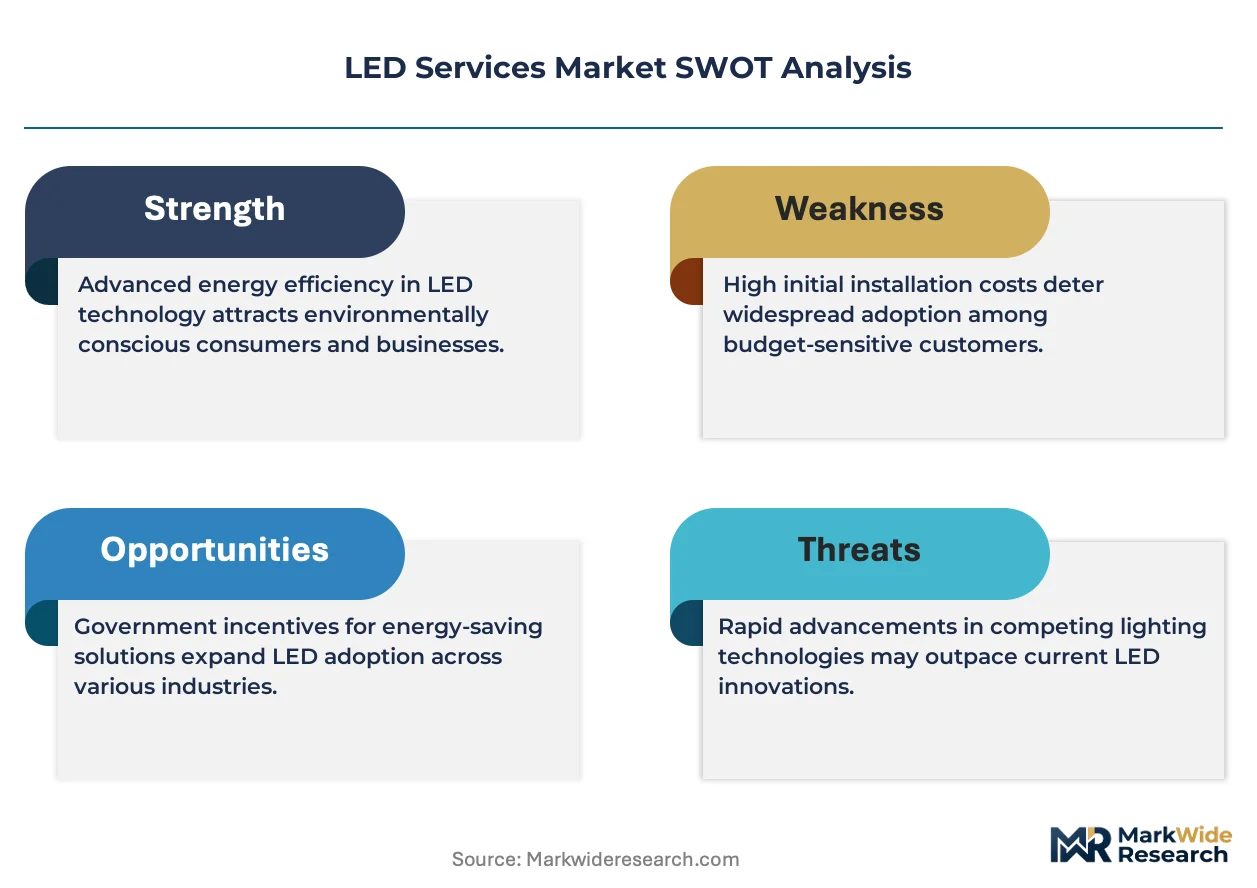
- High Initial Investment:The capital for advanced IoT-integrated systems and Power over Ethernet (PoE) infrastructure deters adoption by cost-sensitive commercial clients.
- Protocol Fragmentation:Lack of standardization in smart lighting communication protocols creates integration complexity and risks vendor lock-in for building operators.
- Talent Scarcity:A shortage of technicians with expertise in network configuration and IoT programming constrains capacity for complex system integrations.
Strategic Opportunities
- Lighting-as-a-Service (LaaS) Models:Subscription services bundling hardware and management into an operational expense can unlock demand from capital-constrained commercial customers.
- Specialized Applications:Developing expertise for human-centric lighting in offices and UV-C disinfection systems in healthcare facilities creates high-margin service niches.
- System Integration:Expanding services to integrate lighting controls with building HVAC and security systems offers higher value to facility managers.
Industry Challenges
- Legacy System Integration:Service providers face significant technical hurdles and costs when attempting to integrate modern networked lighting controls with outdated building wiring and management systems.
- Cybersecurity Threats:Securing thousands of connected lighting nodes in a large commercial building against cyberattacks is a major operational challenge, requiring specialized IT skills that are scarce.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LED Services Market |
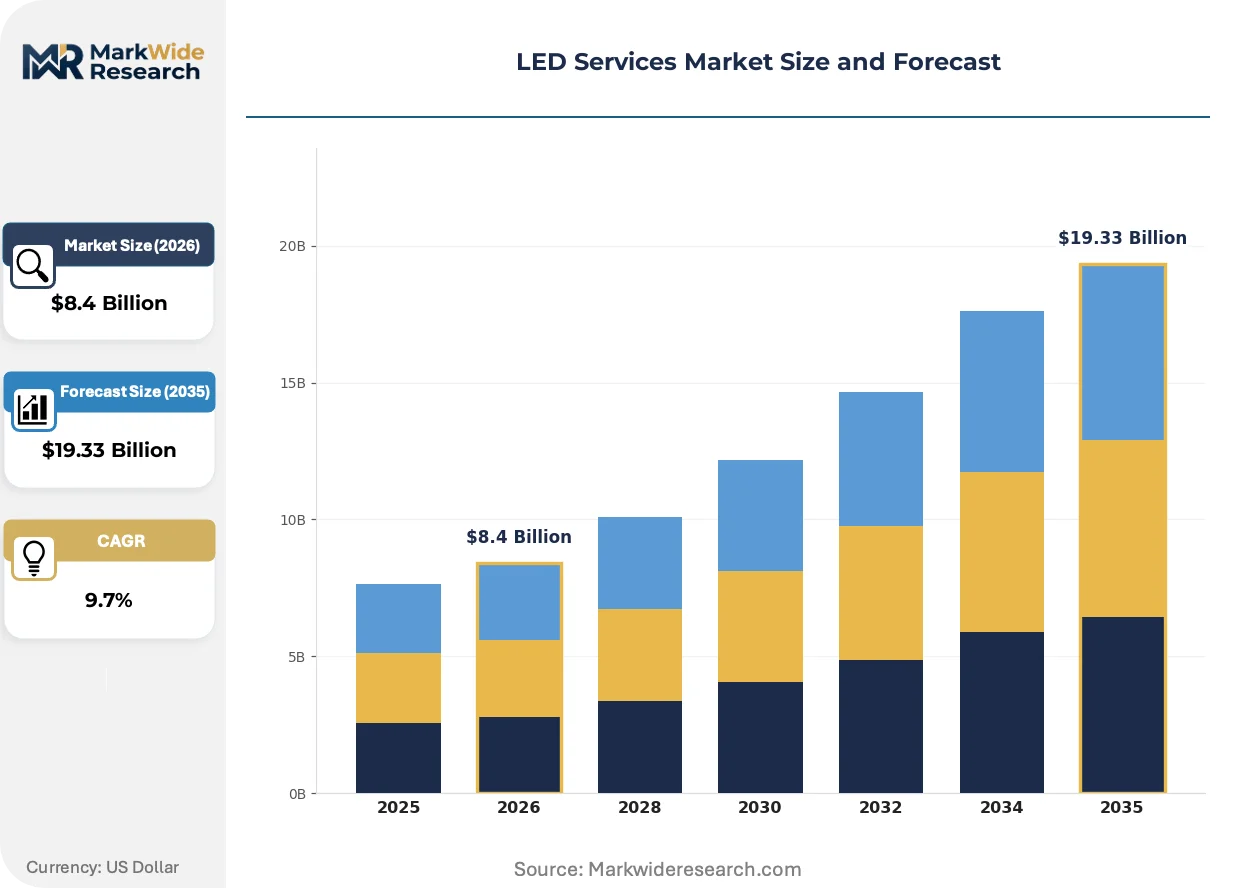
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $19.33 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Installation, Maintenance, Repair, Consultation Application: Residential, Commercial, Industrial, Outdoor Technology: Smart LEDs, RGB, OLED, Quantum Dot End User: Retailers, Architects, Event Planners, Facility Managers |
| Companies Covered | Signify Holding, Philips Lighting Holdings B.V., Acuity Brands, ams OSRAM, Cree Lighting USA LLC, OPPLE Lighting Co., Global Light LLC, Eaton Corporation, Hubbell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LED Services Market Strategic Shifts & Innovations
Service-led business models are gaining prominence over traditional hardware sales. The market's value is shifting from the physical fixture to the software, network management, and data analytics that optimize building performance and enable new capabilities.
Power over Ethernet (PoE) lighting technology delivers both low-voltage electricity and data to fixtures over standard network cables. Commercial office and smart building projects are the primary adopters, valuing its installation flexibility and granular control. This convergence of power and data is decomposing the traditional separation between electrical contracting and IT network integration services.
China's mandatory GB standards for energy efficiency in public and commercial buildings set stringent performance thresholds for lighting systems. This regulation compels building owners to undertake large-scale retrofits to avoid penalties and achieve compliance. Consequently, demand for professional auditing, project management, and retrofitting services is accelerating significantly within the Chinese commercial real estate sector.
A clear shift from one-time, project-based installation contracts toward long-term service agreements for system management and optimization is evident. This model disrupts the traditional electrical contractor's role, favoring system integrators who can guarantee performance outcomes. This change in procurement is most pronounced in large corporate real estate portfolios and public infrastructure projects in the United States.
LED Services Market Segmentation
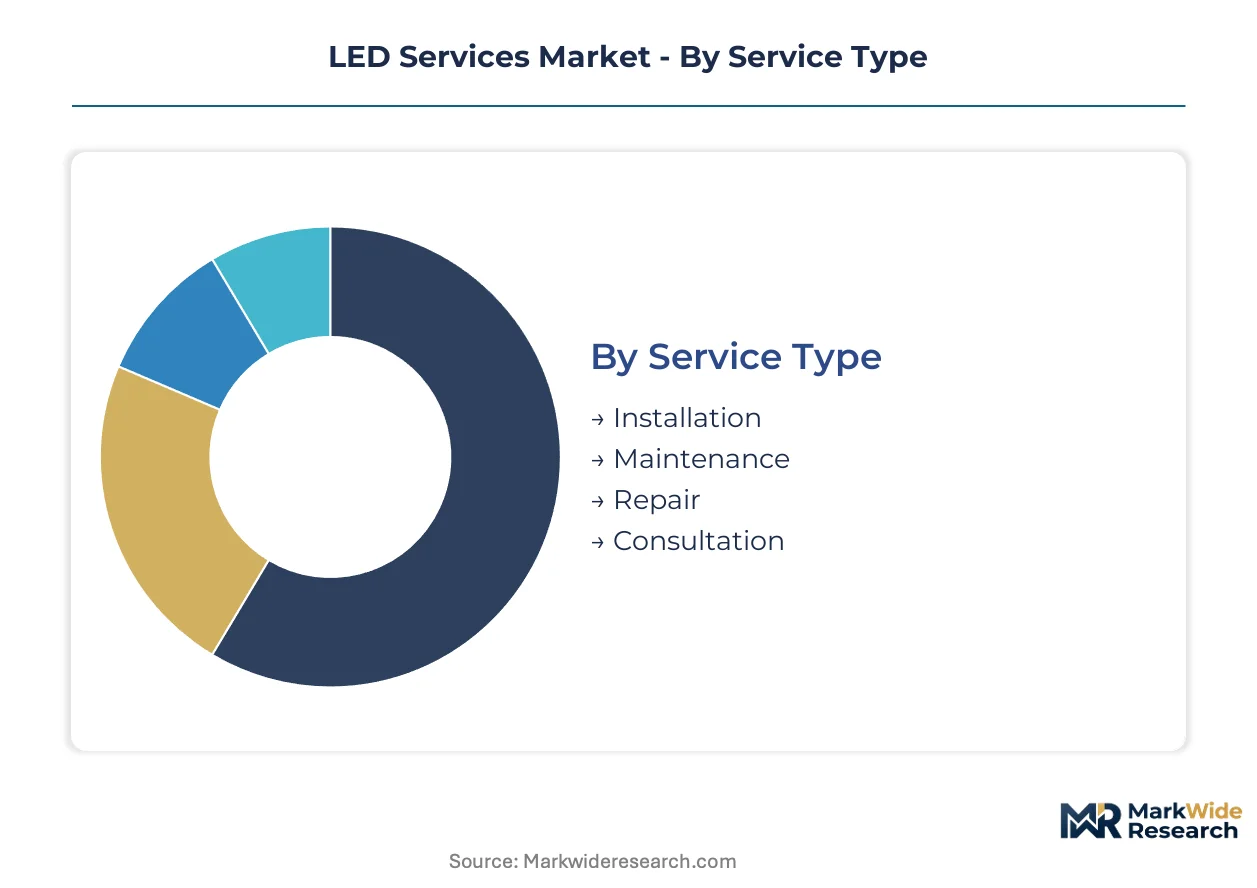
The LED services market exhibits diverse operational characteristics and value propositions across its various segments. Understanding these distinctions is critical for service providers to align their capabilities with specific client needs and market opportunities. Strategic differentiation allows companies to capture either high-volume projects or specialized, high-margin engagements.
Service Type:
The geographic spread of LED service types varies significantly, with basic installation services prevalent globally, while advanced consultation services see higher concentration in developed economies like the United States and European Union member states.
- Installation:Encompasses the physical deployment, wiring, and commissioning of LED lighting systems, forming the market's volume base. Demand concentrates in commercial real estate upgrades and smart city projects across the United States, India, and China, driven by energy efficiency mandates.
- Consultation:Provides expert guidance on system design, optimization strategies, and regulatory compliance for complex lighting projects. Large corporate real estate portfolios and public infrastructure projects in the United States increasingly seek these services to ensure verifiable performance outcomes.
- Maintenance:Focuses on routine upkeep, performance checks, and proactive adjustments for installed LED systems, crucial for ensuring long-term operational efficiency.
- Repair:Addresses malfunctions, component failures, and system breakdowns in existing LED infrastructure, ensuring minimal downtime for commercial and industrial clients.
Installation commands the established base. The steepest expansion runs through Consultation.
Application:
Different LED service applications exhibit distinct operational requirements and cost structures for service providers.
- Commercial:Involves lighting solutions for offices, retail spaces, and hospitality venues, often integrating smart controls for energy savings and enhanced user experience. Facility managers drive substantial demand for these services during building portfolio upgrades.
- Industrial:Focuses on robust, high-performance lighting for manufacturing plants, warehouses, and logistics centers, prioritizing durability, safety, and specific operational needs. Compliance with workplace safety regulations often drives demand for specialized industrial services.
- Residential:Covers basic installation and upgrade services for homes and multi-family dwellings, primarily driven by energy savings and aesthetic preferences of individual homeowners.
- Outdoor:Encompasses street lighting, public spaces, and architectural illumination, where durability, weather resistance, and network integration are paramount for smart city initiatives.
The commercial sector consistently drives significant service volumes, while industrial applications represent a high-value specialization.
Technology:
The maturity curve for LED service technologies ranges from widely adopted solutions to emerging, specialized offerings.
- Smart LEDs:Integrate sensors, communication modules, and advanced control systems, enabling dynamic lighting, data collection, and IoT connectivity for optimized building performance. Commercial office and smart building projects are the primary adopters of these integrated technologies.
- OLED:Offer diffuse, uniform light sources with flexible form factors and low heat emission, finding niche applications in high-end architectural design and specialized display lighting. Their unique aesthetic properties attract specialized design integration services.
- RGB:Provides color-changing capabilities, primarily used in entertainment venues, architectural accent lighting, and decorative installations requiring dynamic visual effects.
- Quantum Dot:Utilizes nanocrystals to enhance color purity and efficiency in specialized LED displays and lighting, representing a nascent but promising technology for specific high-fidelity applications.
Smart LED integration is a dominant force, with OLED technology carving out specialized market niches.
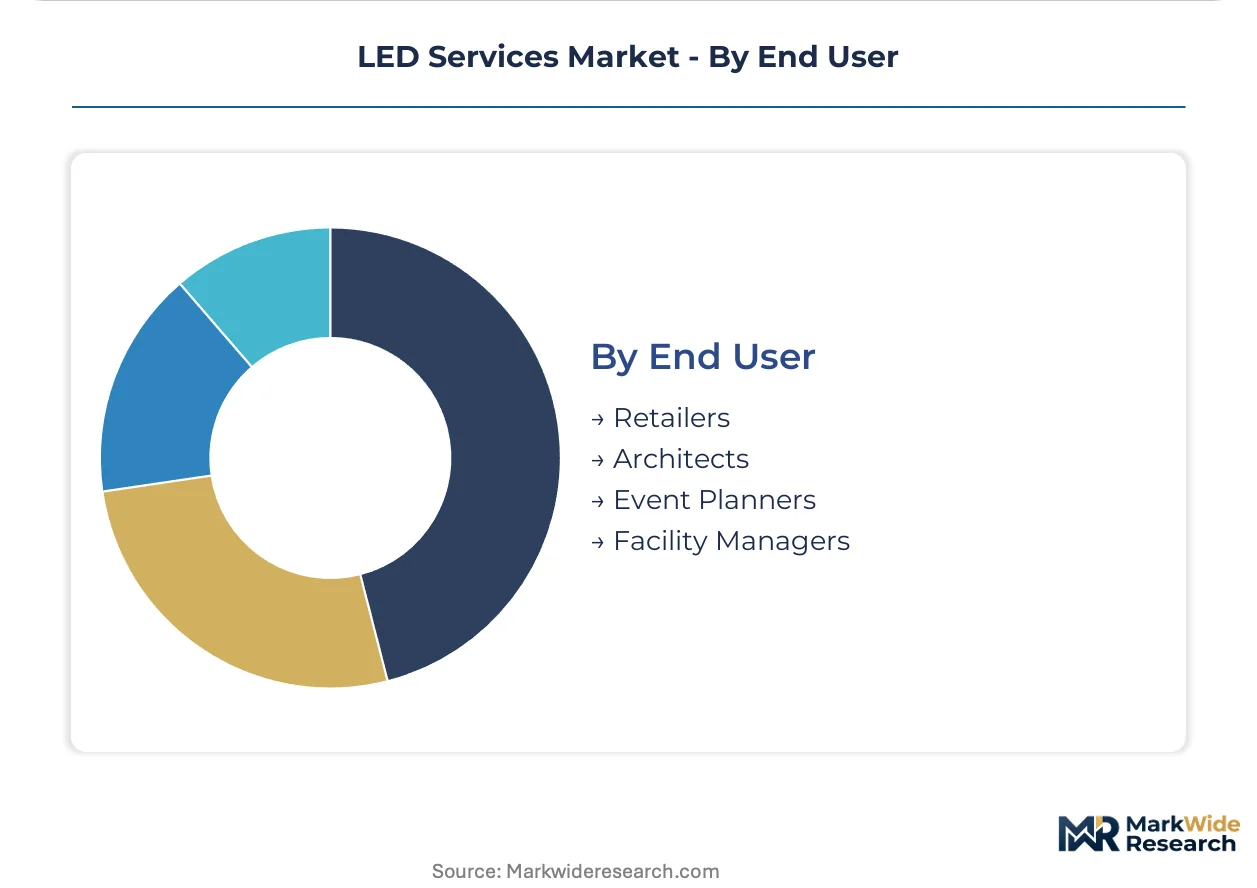
End User:
Each end-user group presents unique procurement patterns and service requirements for LED solutions.
- Facility Managers:Seek comprehensive service packages for entire building portfolios, focusing on energy optimization, system uptime, and regulatory compliance. They drive demand for long-term service agreements and integrated management solutions.
- Architects:Require specialized consultation and design integration services for new construction and major renovation projects, emphasizing aesthetic appeal, functional performance, and sustainability certifications. They influence early-stage project specifications significantly.
- Retailers:Demand dynamic lighting solutions for merchandise display, brand experience, and customer engagement, often seeking rapid deployment and flexible control systems for store environments.
- Event Planners:Need temporary, adaptable, and often color-changing lighting setups for concerts, conferences, and exhibitions, prioritizing ease of installation, removal, and on-site technical support.
Facility managers represent the largest recurring service revenue, while architects shape future project pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Ministry of Ecology and Environment (MEE) mandates for energy efficiency significantly influence the LED services market. Policies like the EU Green Deal also drive demand across European member states. In the United States, the EPA's ENERGY STAR program encourages commercial building upgrades.
China
Mandatory GB standards for energy efficiency directly stimulate demand for professional retrofitting services in China. The Ministry of Ecology and Environment (MEE) enforces stringent performance thresholds for lighting systems. Cities within the Yangtze River Delta actively pursue smart city initiatives, requiring advanced network configuration.
United States
Facility managers in the United States prioritize upgrading entire building portfolios to smart lighting systems. The EPA's ENERGY STAR program encourages efficient lighting solutions in commercial properties. Large corporate real estate portfolios across the Northeast Corridor increasingly seek long-term service agreements.
Germany
Commercial and industrial clients in Germany seek advanced consultation and integration services for complex lighting projects. The EU Green Deal requires verifiable performance improvements across building assets. Industrial clusters in Bavaria invest in specialized applications like human-centric lighting for offices.
India
Smart city development projects and large-scale infrastructure initiatives drive demand for LED services across India. The Bureau of Indian Standards (BIS) promotes quality and energy efficiency in lighting products. Major metropolitan areas like Delhi-NCR concentrate investments in advanced service deployment.
United Kingdom
Commercial real estate upgrades and public infrastructure projects stimulate demand for LED service providers in the United Kingdom. Compliance with CE marking requirements remains essential for products entering the market. London's financial district drives adoption of high-value system integration for intelligent buildings.
LED Services Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the LED services market structure. This bifurcation separates high-value system integrators focused on complex IoT integration and smart controls from volume-based basic installers handling large-scale retrofits. Key strategic archetypes include global solution providers offering comprehensive platforms, regional commercial specialists with deep local market penetration, and niche application experts addressing specific vertical demands. Companies are increasingly engaging in strategic partnerships for technology co-development and portfolio diversification to expand their service offerings across the value chain.
Within the global integrated solution provider archetype, Signify Holding leverages its extensive portfolio of connected lighting systems to command the high-value segment for smart building integration. Acuity Brands, a North American commercial market specialist, competes effectively through strong distribution channels and tailored solutions for facility managers, exemplifying a strong regional leader. OPPLE Lighting Co., a significant player in the Asian market, anchors a substantial portion of the volume-based retrofit market, particularly within Chinese commercial sectors, demonstrating expertise in large-scale basic installation services and regional compliance.
| Leading Market Players |
|---|
| Signify Holding |
| Philips Lighting Holdings B.V. |
| Acuity Brands |
| ams OSRAM |
| Cree Lighting USA LLC |
| OPPLE Lighting Co. |
| Global Light LLC |
| Eaton Corporation |
| Hubbell |
| Others |
Cost & Logistics Intelligence
LED fixture commoditization, replacing traditional lighting, simultaneously reshapes global manufacturing geography and compresses service pricing economics. This shift pushes providers towards value-added services over hardware margins.
Pricing Analysis
Geographic price disparities exist for LED services, with higher rates in developed markets like the United States and Germany for advanced integration. Project-based pricing dominates, transitioning to long-term service agreements for complex commercial applications. Service quality, including verifiable performance outcomes and specialized IoT integration, drives price differentiation. Pricing softness affects basic installation services due to intense competition from volume-focused providers, with capital-constrained commercial clients exhibiting the highest price sensitivity.
Supply Chain Analysis
China anchors LED component manufacturing and basic fixture assembly, supplying global markets with high-volume products. The supply chain draws from critical raw materials such as rare earth elements for phosphors and gallium for semiconductors. Single-source vulnerability for specialized LED drivers and smart control modules poses a structural risk. Distribution runs through a bifurcated model, with high-value system integrators managing complex projects and local electrical contractors handling volume retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The LED services market requires a strong substitution defense against commoditized hardware sales. Incumbents must navigate the threat of value erosion as physical fixtures become less differentiated.
For Market Incumbents:Fortify core market share by deepening vertical integration into smart control software platforms. Strategic partnerships for IoT system interoperability can counter fragmentation risks and the threat of vendor lock-in. Invest in advanced technician training for Power over Ethernet (PoE) installations and network configuration. Focus R&D on human-centric lighting and UV-C disinfection systems to capture higher-margin service niches.
For New Entrants and Emerging Players:Certification fast-track programs, such as ENERGY STAR for commercial properties, provide an entry point into the North American market. Target underpenetrated segments like small-to-medium commercial offices seeking basic retrofits with energy efficiency mandates. Develop specialized expertise in integrating networked lighting with existing building management systems. Offer Lighting-as-a-Service (LaaS) models as a go-to-market angle, appealing to capital-constrained clients.
For Investors and Strategic Acquirers:Secondary-cycle assets sit with regional commercial specialists and niche application experts, offering consolidation opportunities in a fragmented market. The market demonstrates long-term viability, driven by sustained energy efficiency mandates and smart building adoption over the next decade. Target system integrators with proprietary software platforms and strong recurring revenue from long-term service agreements. Watch for increasing regulatory enforcement of energy performance standards as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced IoT Platform Development | Enhances capability to integrate lighting with broader building management systems for facility managers. |
| Targeted Acquisition of System Integrators | Consolidates specialized expertise in complex network configuration and smart control programming. |
| Expansion of Lighting-as-a-Service (LaaS) | Unlocks demand from capital-constrained commercial clients by converting capital expenditure to operational expenditure. |
| Specialized Training for PoE Technicians | Addresses talent scarcity in network configuration for Power over Ethernet lighting deployments. |
| Partnerships for Regional Distribution | Leverages local market penetration and existing client relationships for volume-based retrofit projects. |
Research Approach
Desk research of regulatory documents, corporate financial reports, and industry association publications preceded structured interviews with facility managers, architects, system integrators, and electrical contractors. This primary research validated market dynamics and segmentation insights. Bottom-up data aggregation and top-down market sizing provided a robust framework for analysis. This approach ensured comprehensive validation across diverse data points.
Variance decomposition isolated the impact of key drivers like energy efficiency mandates and smart city initiatives on market growth across the analysis window. Segmentation dimensions modeled included service type, application, technology, and end-user, alongside regional adoption patterns. Compound Annual Growth Rates (CAGRs) were derived from projected revenue streams and volume forecasts. Industry-specific inputs included building retrofit rates and IoT integration costs.
Decision-makers should treat outputs as directional under current regulatory frameworks and technological adoption rates; material deviation would warrant model refresh. Forecasts reflect assumptions concerning policy stability and supply chain resilience. Recalibration cycles align with material shifts in energy efficiency mandates or smart building technology.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
LED Driver Market
LED
Biometrics Infrared LED Market
LED
Single-Digit 7 Segment LED Displays Market
LED
South America LED Lighting Market
LED
LED Downlight Market
LED
Europe Outdoor LED Lighting Market
LED
High-Brightness Light-Emitting Diodes (LED) Headlamps Market
LED
LED Control Unit Market
LED
LED Work Light Market
LED
Architectural LED Products Market
LED
High-Brightness LED Market
LED
7 Segment LED Displays Market
LED
Europe Indoor LED Lighting Market
LED
Global Waterproof LED Module Market
LED
North America Micro-LED Display Market
LED
France LED Lighting Market