
 Asia Pacific Outdoor LED Lighting Market | 2026-2036
Asia Pacific Outdoor LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Outdoor LED Lighting Market Insights
China's dual carbon goals is hardening procurement standards for municipal street lighting retrofits across provincial capitals. Seoul Semiconductor Co., Ltd. anchors its position through advanced chip-scale packaging technology for high-lumen applications. Panasonic Corporation leverages its integrated manufacturing base in Japan to sustain cost competitiveness in smart LED controllers. Signify N.V. dominates connected lighting platforms that municipalities increasingly specify in tender documents.
Asia Pacific outdoor LED lighting encompasses luminaires engineered with aluminum heat sinks and phosphor-converted white LEDs delivering efficacy above 130 lm/W, deployed for roadway illumination, perimeter security, and architectural accentuation in exterior environments. Street lights command the largest installed base due to nationwide replacement programs, while smart LED technology captures the fastest expansion as cities deploy networked controls for dimming and fault detection. Solar LED installations gain share in island nations and rural India where grid reliability remains intermittent.
China's Ministry of Ecology and Environment enforces GB standards for luminous efficacy and electromagnetic compatibility, while India's BIS mandates IS certification for LED luminaires sold to government buyers. Australia's TGA-equivalent electrical safety regulator and South Korea's MFDS-aligned national testing institute further fragment compliance requirements across the region. Stakeholders must monitor evolving procurement specifications that increasingly bundle hardware with decade-long energy performance contracts.
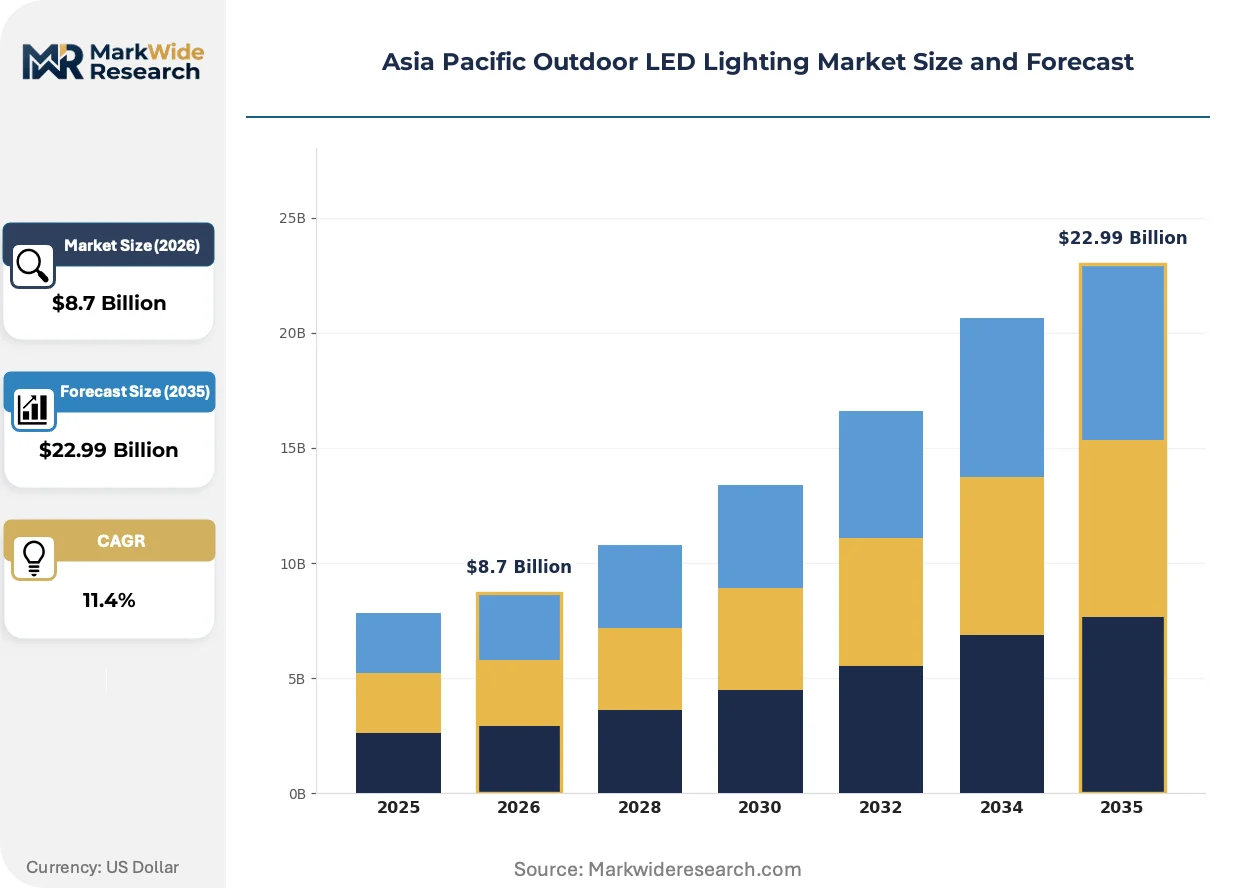
Market Dynamics
China's dual carbon goals are hardening municipal procurement standards across provincial capitals, compressing replacement cycles for legacy street lighting and accelerating specification of networked controls in tender documents.
Growth Catalysts
- Smart city infrastructure mandates:Chinese municipalities are embedding IoT-enabled controls into street lighting retrofits, creating bundled demand for luminaires and management platforms.
- India's Bureau of Energy Efficiency standards:Tightened efficacy requirements for government procurement are disqualifying legacy technologies and standardizing LED adoption in urban infrastructure.
- Island nation electrification gaps:Solar LED installations are capturing share in Indonesia and the Philippines where grid reliability constraints block conventional lighting deployment.
Market Restraints
- Aluminum heat sink cost volatility:Raw material price swings compress margin buffers for luminaire manufacturers serving price-sensitive municipal segments.
- LED chip supply concentration:Dependence on Taiwanese and Chinese semiconductor foundries exposes downstream assemblers to geopolitical supply disruptions.
- Legacy HPS lamp installed base:Decades-long depreciation schedules in smaller Indian municipalities delay full LED conversion despite operational savings.
Strategic Opportunities
- Rural India electrification:Unelectrified villages in Bihar and Uttar Pradesh represent addressable demand for solar-powered street lighting without grid dependency.
- Energy performance contracting:Australia's state-level infrastructure agencies are piloting decade-long service agreements that bundle hardware, installation, and maintenance.
- LiDAR-streetlight convergence:Integration of traffic monitoring sensors into luminaire housings is creating new revenue streams for smart city vendors in Seoul and Singapore.
Industry Challenges
- Fragmented certification timelines:India's BIS, China's GB standards, and South Korea's MFDS-aligned testing create multi-month approval bottlenecks for pan-Asian product launches.
- Legacy control system integration:Municipalities in Japan and Australia require backward compatibility with existing dimming protocols, complicating smart controller deployment.
- Field technician scarcity:Shortages of certified electricians familiar with networked lighting commissioning are extending project timelines in secondary Chinese cities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Outdoor LED Lighting Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Street Lights, Flood Lights, Architectural Lights, Tunnel Lights Installation Type: Outdoor, Indoor, Semi-Outdoor, Temporary Technology: Smart LED, Solar LED, Traditional LED, RGB LED End User: Municipalities, Commercial Properties, Residential Areas, Parks |
| Companies Covered | Nichia Corporation, Panasonic Corporation, Signify N.V., Acuity Brands Lighting Inc., Samsung Electronics Co., Ltd., ams OSRAM GmbH, Cree Lighting (IDEAL Industries), Zumtobel Group AG, Seoul Semiconductor Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Outdoor LED Lighting Market Trends and Innovations
Three forces are restructuring competitive positioning in Asia Pacific outdoor LED lighting: chip-scale packaging advances, tightening efficacy mandates, and the unbundling of hardware from energy service contracts.
Chip-scale packaging technology is converging with high-lumen street lighting applications. Seoul Semiconductor and domestic Chinese chip houses are shipping CSP LEDs that eliminate traditional package substrates, reducing thermal resistance and enabling higher density arrays. Municipal buyers in Shanghai and Shenzhen are specifying these packages for arterial road illumination where lumen maintenance targets exceed 100,000 hours.
China's Ministry of Ecology and Environment is enforcing updated GB standards for luminous efficacy and electromagnetic compatibility. The regulations are disqualifying entry-tier luminaires from government tenders and consolidating procurement around suppliers with in-house testing laboratories. Provincial capitals are responding by embedding efficacy verification clauses into bid evaluation matrices.
Municipal tender specifications are unbundling hardware purchase from long-term energy performance. State-owned infrastructure developers in India and Australia are shifting from capital expenditure models to service contracts where vendors guarantee lumen output and maintenance over contract terms. This reconfiguration favors suppliers with balance sheet capacity to carry decade-long receivables.
Asia Pacific Outdoor LED Lighting Market Segmentation
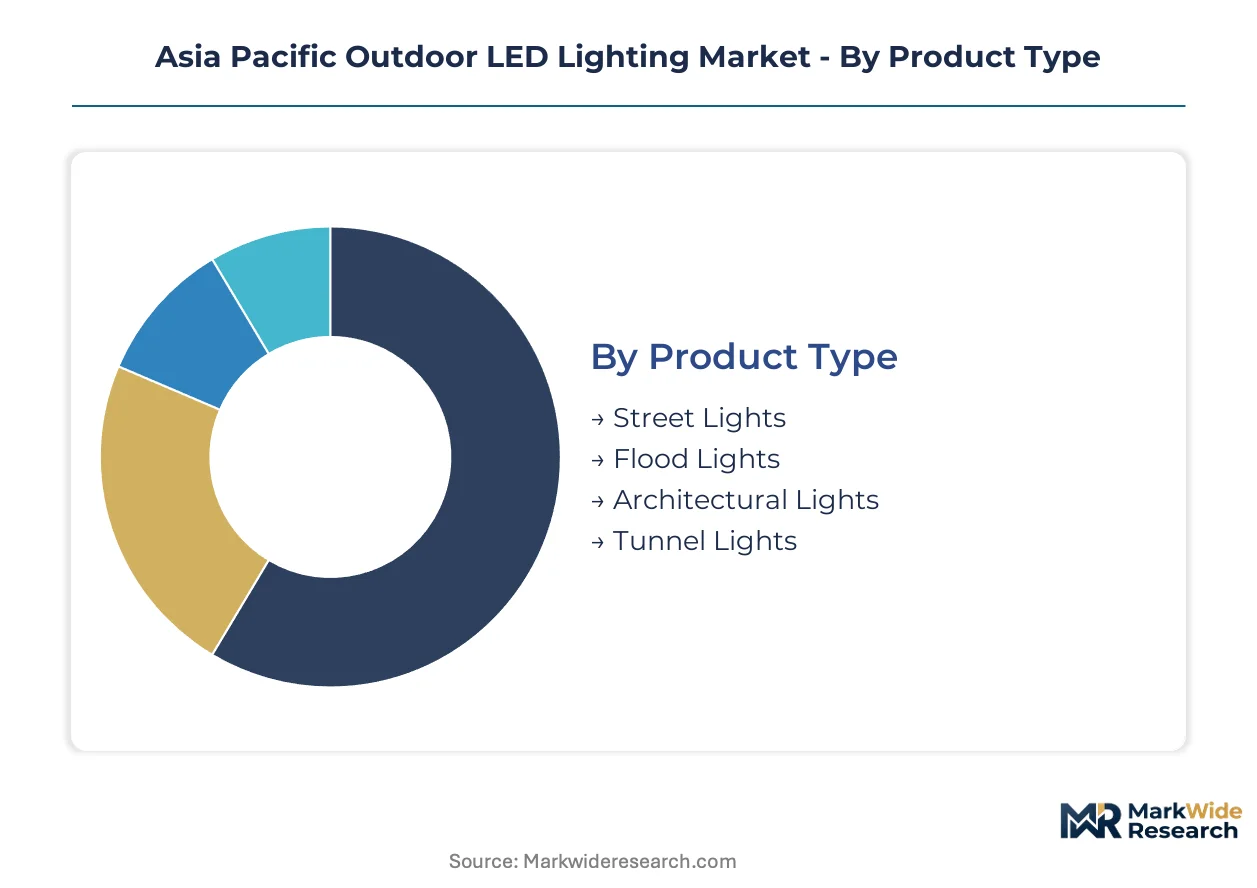
Segmentation in Asia Pacific outdoor LED lighting reveals how procurement specifications diverge across infrastructure types and buyer sophistication. Municipal tender documents increasingly bundle technology requirements with service-level agreements, reshaping vendor qualification criteria.
Product Type:
Municipal buyers prioritize lumen output consistency and thermal management over upfront cost, favoring suppliers with in-house aluminum casting and phosphor-conversion capabilities.
- Street Lights:Aluminum heat-sink housings with phosphor-converted white LEDs delivering efficacy above 130 lm/W dominate arterial road specifications. China's Yangtze River Delta municipalities and India's National Capital Region are consolidating procurement around networked controls with dimming protocols.
- Flood Lights:High-lumen arrays for perimeter security and sports facilities require IP66-rated enclosures and surge protection. Demand concentrates in Australian commercial developments and South Korean industrial zones where BIS-equivalent standards enforce electromagnetic compatibility.
- Architectural Lights:Accent luminaires for facade illumination prioritize color consistency and beam precision over raw output.
- Tunnel Lights:Asymmetric distribution patterns and emergency battery backup systems address safety-critical underground infrastructure.
Volume sits with Street Lights; growth tilts toward Architectural Lights.
Installation Type:
Grid reliability and capital availability determine whether buyers select hardwired, solar-hybrid, or temporary deployment models.
- Outdoor:Permanent pole-mounted installations for roadway and public space illumination constitute the installed base majority. China's dual carbon goals are accelerating replacement of legacy HPS lamps with networked LED retrofits across provincial capitals.
- Solar LED:Photovoltaic-integrated luminaires with battery storage capture share in Indonesia and the Philippines where grid intermittency blocks conventional deployment. Rural electrification programs in Bihar and Uttar Pradesh are specifying solar street lighting without grid dependency.
- Indoor:Covered parking structures and transit terminals require vapor-tight enclosures with corrosion-resistant finishes.
- Semi-Outdoor:Canopy and soffit applications in transit hubs demand intermediate IP ratings and flexible mounting hardware.
- Temporary:Rental luminaires for construction sites and event infrastructure prioritize rapid deployment and damage resistance over efficiency metrics.
Deployment concentrates in Outdoor permanent installations; Solar LED is climbing the fastest.
Technology:
Control sophistication separates premium specifications from commodity procurement, with networked platforms commanding evaluation preference in large-scale tenders.
- Smart LED:IoT-enabled luminaires with integrated sensors for dimming, fault detection, and traffic monitoring are capturing specification share in Seoul and Singapore. Municipalities are embedding these requirements into tender documents alongside decade-long energy performance contracts.
- Traditional LED:Fixed-output luminaires without networked controls serve price-sensitive segments and legacy retrofit projects where dimming infrastructure is absent.
- RGB LED:Color-tunable arrays for architectural accent and dynamic facade programming.
Procurement volume favors Traditional LED; Smart LED shows steepest expansion trajectory.
End User:
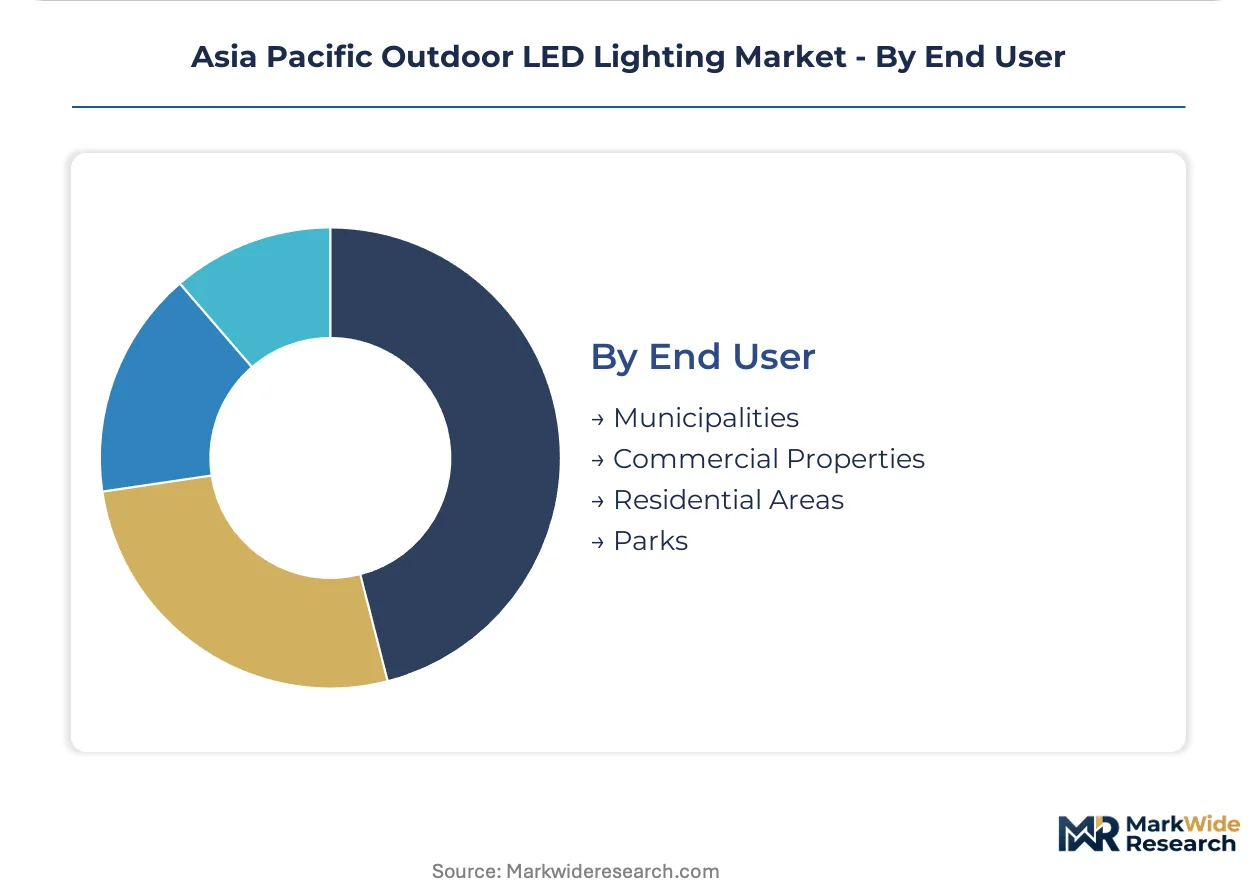
Buyer type dictates contract structure, with government entities favoring energy performance agreements and commercial developers prioritizing capital expenditure efficiency.
- Municipalities:Government infrastructure agencies specify efficacy verification clauses and bundled maintenance terms. India's Bureau of Energy Efficiency standards and China's GB requirements are disqualifying entry-tier suppliers from government tenders.
- Commercial Properties:Retail and office developers prioritize payback period and utility rebate capture over technical sophistication.
- Residential Areas:Gated communities and housing associations balance aesthetic preferences with homeowner association budget constraints.
- Parks:Landscape illumination for recreational spaces emphasizes wildlife-friendly spectral output and vandal-resistant construction.
Revenue concentrates with Municipalities; Parks segment is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of LED chips and luminaires consumed across Asia Pacific, while India and Southeast Asian nations absorb volumes through infrastructure replacement cycles. Domestic production in Japan and South Korea serves premium specification tiers with shorter supply chains.
China
Municipal procurement in Shanghai, Shenzhen, and Guangzhou drives demand for networked street lighting with efficacy above 130 lm/W. The Ministry of Ecology and Environment enforces updated GB standards for luminous efficacy and electromagnetic compatibility that disqualify entry-tier suppliers. The Yangtze River Delta cluster concentrates manufacturing of aluminum heat-sink housings and phosphor-converted LED arrays for domestic and export markets.
India
Urban infrastructure agencies in Delhi, Mumbai, and Bangalore are replacing legacy HPS lamps through centralized procurement schemes. The Bureau of Energy Efficiency mandates IS certification for LED luminaires sold to government buyers, tightening qualification requirements. Rural electrification programs in Bihar and Uttar Pradesh specify solar-powered street lighting where grid reliability remains intermittent.
Japan
Commercial developers in Tokyo and Osaka prioritize integrated smart controllers with backward compatibility for existing dimming infrastructure. METI guidelines encourage high-efficacy specifications for public space illumination. The Kansai industrial corridor hosts integrated manufacturing bases for LED controllers and precision optical components serving domestic tenders.
South Korea
Seoul and Busan municipal authorities specify IoT-enabled luminaires with embedded traffic monitoring sensors for smart city deployments. The MFDS-aligned national testing institute certifies electromagnetic compatibility for infrastructure-grade products. The Seoul Capital Area concentrates chip-scale packaging operations for high-lumen street lighting applications.
Australia
State-level infrastructure agencies in New South Wales and Victoria pilot decade-long energy performance contracts bundling hardware with maintenance guarantees. The country's electrical safety regulator enforces standards equivalent to TGA requirements for luminaire certification. Commercial developments in Sydney and Melbourne drive demand for IP66-rated flood lighting with surge protection.
Asia Pacific Outdoor LED Lighting Market Competitive Landscape
The competitive structure tilts toward diversified electronics conglomerates with captive semiconductor capabilities. Market participation clusters around three archetypes: integrated lighting platforms with software ecosystems, component specialists with chip-scale packaging expertise, and diversified industrial groups with aluminum casting and thermal management assets. Competitive moves concentrate on strategic partnerships for smart city tenders and backward integration into LED chip supply.
Within the integrated platform tier, Signify N.V. and Panasonic Corporation exemplify vendors bundling luminaires with networked control software. Seoul Semiconductor Co., Ltd. occupies a position among component specialists advancing chip-scale packaging for high-lumen density. Nichia Corporation anchors the premium efficacy segment through phosphor-conversion technology. These three represent distinct strategic postures: full-stack platform provision, upstream component specialization, and materials-science differentiation.
| Leading Market Players |
|---|
| Nichia Corporation |
| Panasonic Corporation |
| Signify N.V. |
| Acuity Brands Lighting Inc. |
| Samsung Electronics Co., Ltd. |
| ams OSRAM GmbH |
| Cree Lighting (IDEAL Industries) |
| Zumtobel Group AG |
| Seoul Semiconductor Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Chip-scale packaging adoption across Chinese and South Korean foundries is compressing thermal management costs while concentrating LED die supply among vertically integrated semiconductor houses. This dual effect reshapes procurement economics for luminaire assemblers serving municipal tender markets.
Pricing Analysis
Margin tightening in entry-tier luminaires reflects aluminum heat-sink cost volatility and disqualification of sub-130 lm/W products under China's updated GB standards. Three-tier pricing structure across premium, standard, and economy levels separates networked smart LED bundles from fixed-output retrofit units, with certification grade and volume scale as primary differentiation drivers. Cost-down pressure accelerates as provincial capitals consolidate procurement around decade-long energy performance contracts. Municipal buyers exhibit lowest price sensitivity; secondary city contractors face acute margin compression.
Supply Chain Analysis
Workforce scarcity for certified lighting commissioning technicians in secondary Chinese cities and rural Indian states extends project timelines and inflates installation cost structures. LED chip fabrication concentrates in China, Taiwan, and South Korea; aluminum heat-sink casting and phosphor-conversion operations cluster in the Yangtze River Delta. Raw material dependencies span aluminum ingots, rare-earth phosphors, and silicon carbide substrates. Single-source vulnerability around Taiwanese semiconductor foundries exposes downstream assemblers to geopolitical disruption. Distribution runs through state-owned infrastructure developers in India, municipal procurement agencies in China, and electrical contractors in Australia and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around suppliers with captive chip fabrication and balance sheet capacity for long-dated energy service contracts. China's GB efficacy enforcement and India's BIS certification tightening are forcing weaker assemblers into exit or acquisition.
For Market Incumbents: To counter margin erosion from aluminum price volatility and entry-tier disqualification, deepen backward integration into LED chip-scale packaging and phosphor-conversion operations. Anchor position by underwriting decade-long energy performance contracts for state-owned infrastructure developers in India and Australia's state-level agencies. For New Entrants and Emerging Players: Solar-hybrid luminaire technology for unelectrified villages in Bihar and Uttar Pradesh offers a white-space entry point. Target Indonesia and Philippines island deployments where grid intermittency blocks conventional lighting. Pursue direct engagement with rural electrification program administrators rather than municipal tender channels. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap assemblers possessing in-house aluminum casting and IS/GB certification infrastructure given India's Bureau of Energy Efficiency mandate expansion. Long-term viability hinges on contract carry capacity for service-based revenue models. Monitor BIS approval timelines as inflection signal for procurement access.| Strategic Initiative | Industry Significance |
|---|---|
| Chip-Scale Packaging Scale-Up | CSP LED fabrication in Seoul Capital Area reduces thermal resistance for 100,000-hour lumen maintenance targets. |
| Energy Performance Contracting | Decade-long service agreements with Australian state agencies bundle hardware, installation, and maintenance under guaranteed output terms. |
| Backward Integration into Phosphor Conversion | In-house rare-earth phosphor processing secures supply chain control over efficacy-critical components for GB-compliant luminaires. |
| Smart City Platform Integration | IoT-enabled luminaires with embedded traffic monitoring sensors capture specification share in Seoul and Singapore municipal tenders. |
| Rural Solar LED Deployment | Photovoltaic-integrated luminaires address electrification gaps in Indonesian and Philippine markets with intermittent grid reliability. |
Research Methodology
Trade databases, customs filings, and municipal procurement registries formed the secondary backbone, supplemented by SEC disclosures from listed lighting conglomerates and BIS/GB certification records. Primary interviews with municipal procurement officers, electrical contractors, LED chip fabrication executives, and energy service company project developers validated demand assumptions and pricing structures. Bottom-up luminaire shipment estimates triangulated against top-down infrastructure spending allocations across the analysis window.
Bottom-up modeling aggregated product-level volume and pricing across street light, flood light, architectural, and tunnel luminaire categories. Segmentation dimensions included installation type, control technology sophistication, and end-user procurement structure. CAGRs derived from curve-fitting historical replacement cycles against announced smart city infrastructure mandates and rural electrification program budgets. Forecast inputs incorporated aluminum price trajectory assumptions and semiconductor foundry capacity expansion plans.
Several conditions sit outside the modeled scope, including unannounced tariff adjustments on LED components, abrupt shifts in China's dual carbon policy enforcement intensity, and geopolitical disruption of Taiwanese chip supply. Forecasts reflect documented assumptions regarding municipal budget continuity and certification timeline stability. Material deviation in aluminum price volatility or BIS/GB approval bottlenecks warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Gan Substrate Market
LED
Monochrome Outdoor LED Display Market
LED
Micro LED Display Market
LED
Architectural LED Products Market
LED
Brazil LED Market
LED
LED Light Market
LED
LED Lighting Market
LED
High-Intensity LED Logo and Livery Lighting Systems Market
LED
Philippines LED Market
LED
India LED Lighting Market
LED
Thailand LED Market
LED
Europe Outdoor LED Lighting Market
LED
US LED Downlight Market
LED
LED Lamp Market
LED
OLED Blue Emitter Market
LED
LED Panel Light Drivers Market