
 7 Segment LED Displays Market | 2026-2036
7 Segment LED Displays Market Size, Share, and Industry Trends Forecast 2026-2036
7 Segment LED Displays Market Analytics
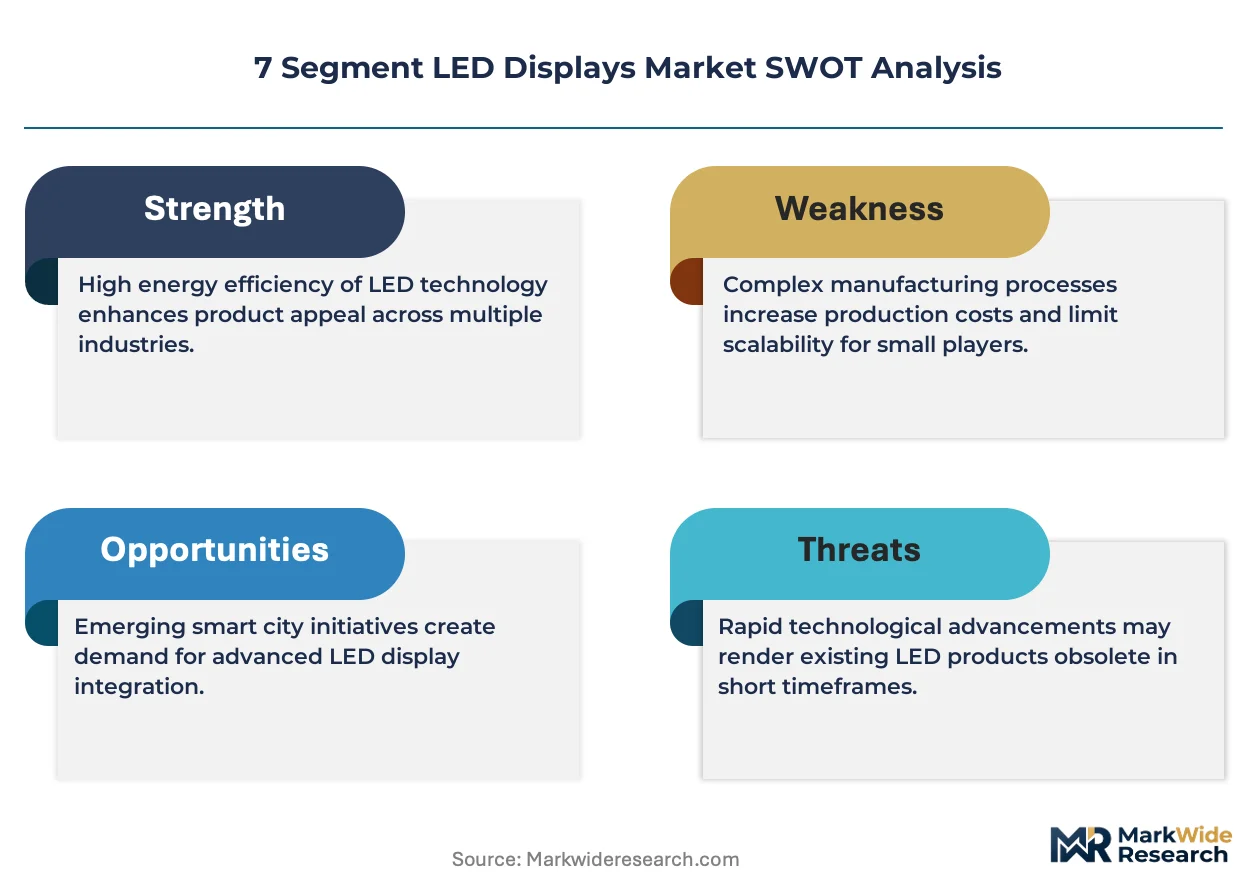
Multi-source procurement of LED dies and driver ICs is expanding across tier-one display assemblers as supply volatility reshapes sourcing strategy. Kingbright leverages captive wire-bonding capacity in Taiwan to sustain margin control across standard-size segments. Broadcom competes through high-reliability automotive-qualified offerings that anchor its position in instrument cluster supply chains. Futaba Corporation dominates vacuum fluorescent crossover applications where 7-segment LED replacements require exact pin compatibility.
A 7 segment LED display is an optoelectronic numeric indicator composed of seven individually addressable LED bars arranged in a rectangular pattern, typically operating at forward currents between 10 mA and 20 mA per segment with peak wavelengths ranging from 625 nm red to 570 nm yellow-green. These devices serve as low-cost, high-visibility numeric readouts in environments where liquid crystal alternatives fail due to ambient light constraints or wide temperature extremes. Common cathode configurations retain the largest installed base across industrial equipment applications where single-digit cost sensitivity governs specification, while RGB variants capture the fastest expansion in retail signage and transport displays where programmable color states replace multiple monochrome SKUs. Small-size segments below 0.3 inch character height concentrate volume in handheld medical devices and portable instrumentation, whereas extra-large formats above 2 inches command premium positioning in outdoor transit arrival boards.
RoHS and REACH compliance in Europe constrain substrate metallization choices and solder alloy specifications, while FDA device-labeling requirements in the United States mandate minimum contrast ratios for medical 7-segment readouts that directly influence phosphor formulation selection. China's GB standards for electronic display energy efficiency and Japan's JIS electromagnetic compatibility frameworks add further certification layers for cross-border component suppliers. Stakeholders must monitor evolving automotive AEC-Q101 qualification thresholds and transport-sector EN 50155 railway standards to preserve design-win access across mobility applications.
Market Dynamics
Supply volatility in LED die and driver IC procurement is restructuring sourcing strategies across display assemblers, forcing tier-one manufacturers toward multi-vendor qualification programs and captive wire-bonding investments to defend margin control.
Growth Catalysts
- Medical device demand in Germany:Patient monitoring equipment manufacturers are expanding RoHS-compliant common anode display procurement to meet FDA contrast-ratio mandates for critical-care readouts.
- China's MIIT efficiency standards:Domestic production upgrades are accelerating as GB standards for electronic display energy efficiency force component-level redesigns across Shenzhen and Dongguan manufacturing clusters.
- RGB programmable variants:Transport authorities in Japan are consolidating multiple monochrome SKUs into single RGB units for programmable color-state arrival boards in Tokyo and Osaka transit systems.
Market Restraints
- Phosphor cost volatility:Rare-earth phosphor formulations for high-contrast medical readouts face price instability tied to dysprosium and terbium supply concentration in Chinese refining operations.
- Substrate metallization constraints:RoHS and REACH compliance in Europe eliminates lead-bearing solder alloys, forcing costly transitions to SAC305 and other tin-silver-copper compositions.
- OLED numeric substitution:Low-cost OLED matrix displays are capturing sub-0.5-inch segment applications in consumer electronics where viewing angle flexibility outweighs 7-segment sunlight readability.
Strategic Opportunities
- India's medical device PLI scheme:Domestic manufacturing incentives are creating localized assembly opportunities for common cathode displays targeting portable diagnostic equipment.
- AEC-Q101 automotive qualification:Instrument cluster suppliers are qualifying high-reliability 7-segment variants for electric vehicle battery management system readouts requiring -40°C to +85°C operation.
- EN 50155 railway certification:Rolling stock retrofit programs across European operators are opening specification windows for shock-resistant extra-large format transit displays.
Industry Challenges
- Wire-bonding technician scarcity:Precision gold-wire bonding for high-reliability automotive and medical displays requires skilled operators in short supply across Taiwanese and Malaysian assembly hubs.
- Multi-certification timeline compression:Simultaneous pursuit of FDA device-labeling, AEC-Q101 automotive, and EN 50155 railway qualifications strains engineering resources and extends product validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 7 Segment LED Displays Market |
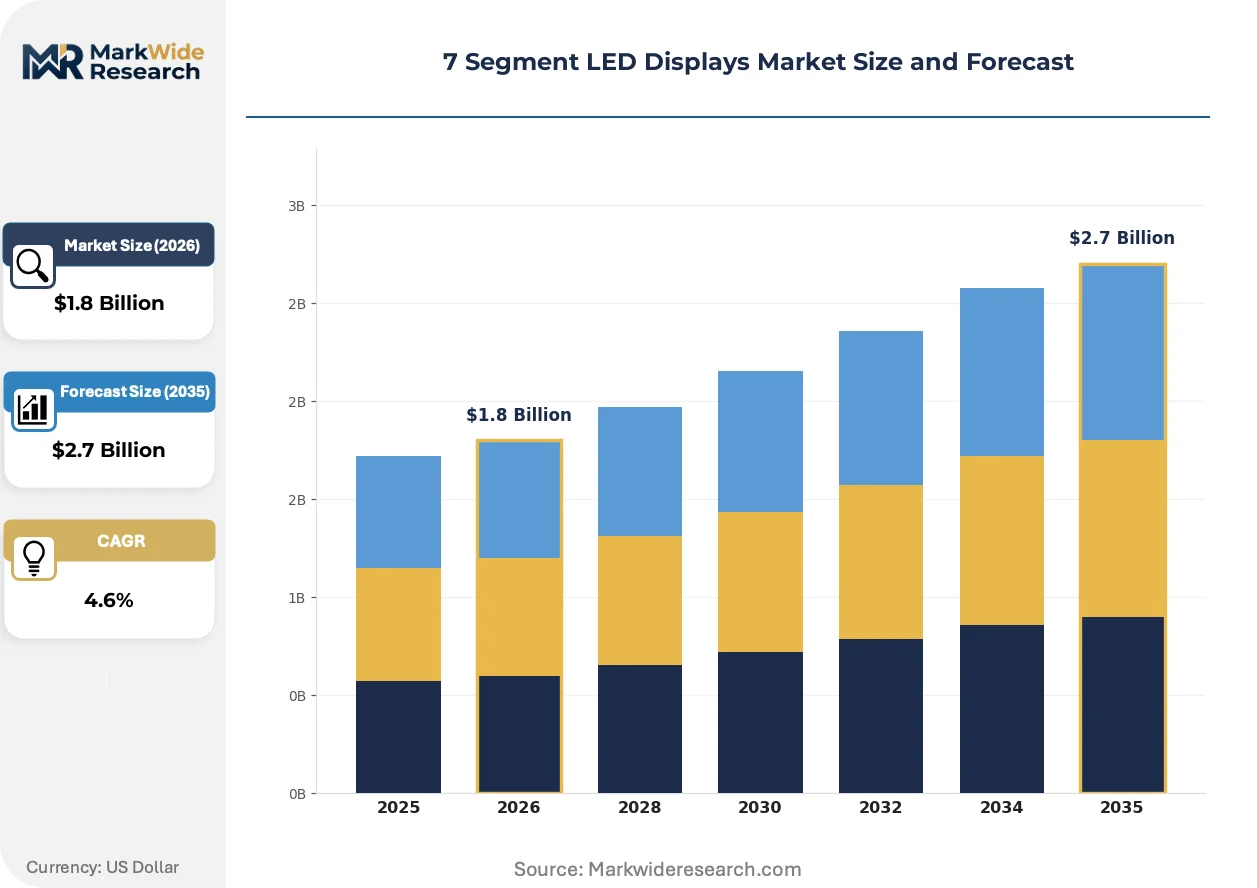
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Common Cathode, Common Anode, Dual Color, RGB Application: Consumer Electronics, Industrial Equipment, Medical Devices, Automotive End User: Retail, Education, Transport, Healthcare Size: Small, Medium, Large, Extra Large |
| Companies Covered | Kingbright, Broadcom, Lumex, Visual Communications Company, Lite-On Technology Corporation, Visha, Opteq, Futaba Corporation, Foshan NationStar Optoelectronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
7 Segment LED Displays Market Evolving Landscape
Chip-on-board packaging architectures and phosphor-converted white LED technologies are redistributing manufacturing value chains while regulatory frameworks in major economies impose new material and performance specifications.
Chip-on-board LED assembly is decentralizing production geography by eliminating traditional package-and-leadframe steps. Medical device contract manufacturers in Germany and Japan are adopting direct-die attachment for sub-0.3-inch displays, compressing lead times and enabling regionalized fulfillment for patient-monitoring OEMs.
REACH substance restrictions are forcing reformulation of encapsulant resins and phosphor binders. European display assemblers are qualifying halogen-free substrate materials ahead of anticipated ECHA candidate list expansions, with medical and railway applications facing the steepest requalification burdens.
Consolidated procurement of programmable RGB units is displacing monochrome SKU proliferation in retail and transport signage. Japanese and Korean transit operators are standardizing on single-part-number solutions with I2C-addressable color states, reducing inventory carrying costs and simplifying field replacement protocols.
7 Segment LED Displays Market Segmentation
Segment boundaries in 7-segment LED displays map directly to certification requirements and supply chain complexity. Each dimension carries distinct regulatory burdens that reshape vendor qualification timelines and customer procurement patterns.
Product Type:
Certification burdens vary sharply across electrical configurations, with automotive and medical applications imposing divergent reliability thresholds on each variant.
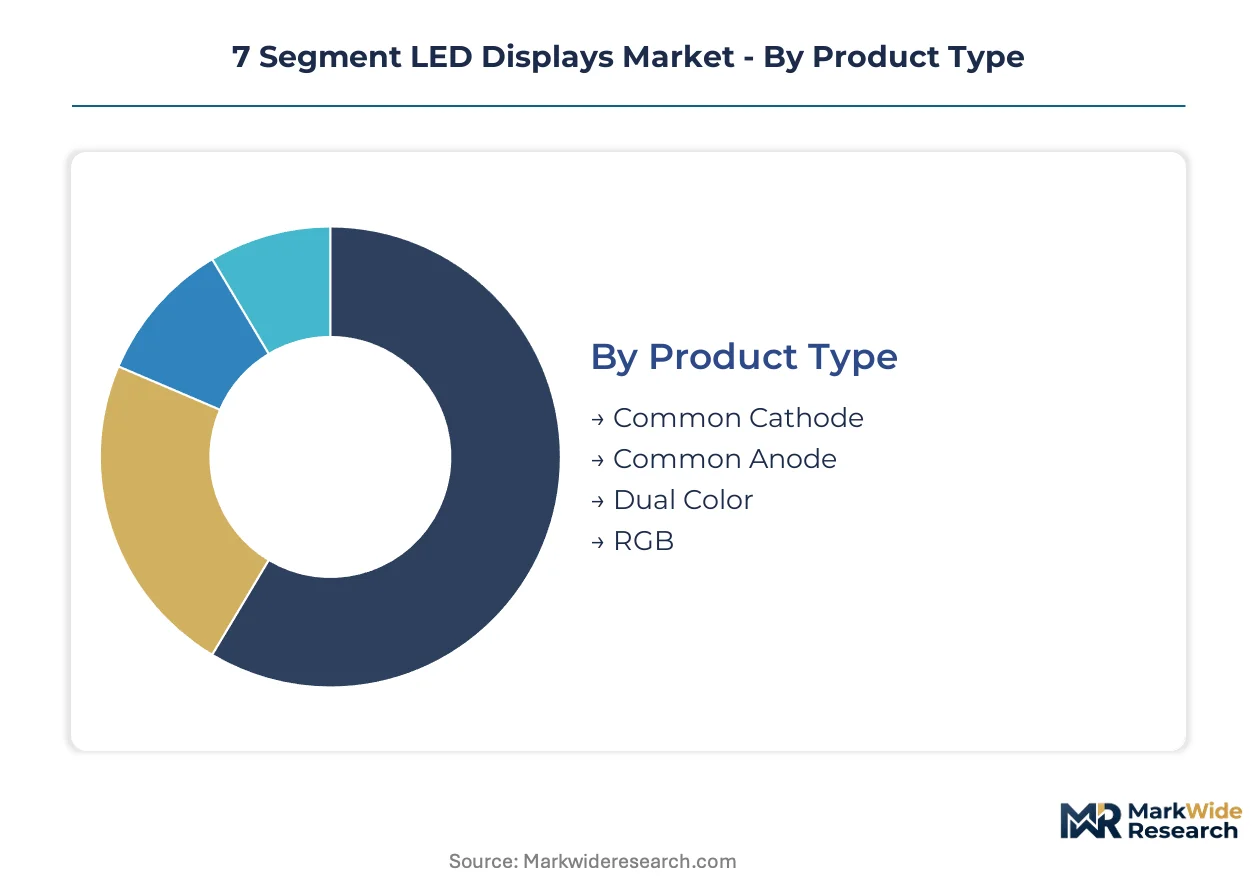
- Common Cathode:Single shared negative terminal architecture dominates industrial equipment installations where cost minimization governs specification. German machine-tool OEMs specify this configuration for numeric position readouts in factory automation systems, prioritizing parts-commonality across multi-decade equipment lifecycles.
- Common Anode:Shared positive terminal design enables simpler driver IC integration in battery-powered medical devices. Patient-monitoring manufacturers in the United States select RoHS-compliant variants to satisfy FDA contrast-ratio mandates for critical-care numeric displays.
- Dual Color:Two-state visual indication supports alarm-status differentiation in railway signaling equipment.
- RGB:Programmable color states consolidate multiple monochrome SKUs into single part numbers for Japanese transit arrival boards.
Common Cathode sits at the top of the volume ranking, with RGB climbing the fastest.
Application:
End-use environments dictate thermal cycling requirements, with mobility applications demanding the widest operating temperature spans.
- Consumer Electronics:Sub-0.5-inch displays face substitution pressure from low-cost OLED matrices in portable devices where viewing angle flexibility outweighs sunlight readability.
- Industrial Equipment:Harsh-environment numeric readouts specify wide-temperature-grade components for factory-floor exposure to metal dust and coolant mist.
- Medical Devices:FDA device-labeling requirements mandate minimum contrast ratios that directly constrain phosphor formulation selection for patient-monitoring equipment.
- Automotive:AEC-Q101 qualification thresholds govern instrument cluster and battery management system readouts requiring -40°C to +85°C operation.
Industrial Equipment commands the largest revenue base, while Automotive shows the steepest expansion trajectory.
End User:
Procurement sophistication varies by sector, with transport authorities consolidating specifications and retail fragmenting across price tiers.
- Retail:Price-sensitive POS terminal and digital signage deployments favor standard-grade common cathode displays.
- Education:Laboratory instrumentation and classroom timer applications specify medium-size segments with basic reliability ratings.
- Transport:EN 50155 railway certification and programmable RGB requirements dominate European rolling stock and Japanese transit system procurement.
- Healthcare:FDA and CDSCO medical device regulations enforce phosphor-contrast and electromagnetic compatibility standards for diagnostic equipment readouts.
Transport leads in specification consolidation, with Healthcare gaining share fastest on medical device manufacturing incentives.
Size:
Manufacturing scale and wire-bonding precision requirements invert across the size spectrum, concentrating production geography differently at each tier.
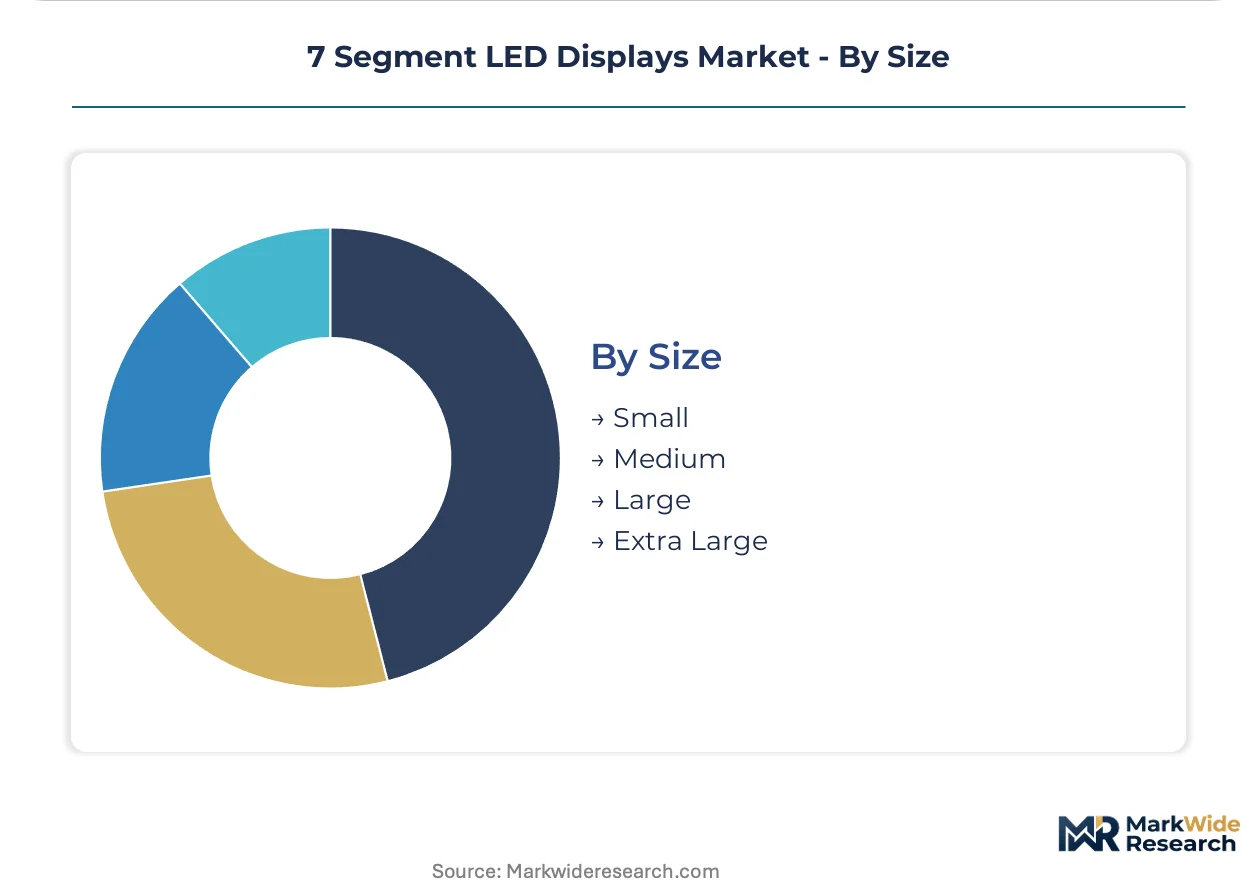
- Small:Sub-0.3-inch character height segments concentrate in handheld medical devices and portable instrumentation requiring precision gold-wire bonding.
- Medium:0.3-inch to 1.0-inch formats balance visibility and power consumption for industrial panel meters and consumer appliances.
- Large:1.0-inch to 2.0-inch displays serve indoor retail signage and educational equipment with moderate viewing distance requirements.
- Extra Large:Above-2-inch formats command premium positioning in outdoor transit arrival boards requiring shock resistance and wide-angle visibility.
Medium sizes anchor global volume, with Extra Large expanding most quickly on railway retrofit programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing 7-segment LED display assembly as compliance-cost differentials widen between jurisdictions with stringent medical-grade certification requirements and manufacturing bases with streamlined environmental frameworks.
Germany
Medical device OEMs in Baden-Württemberg and Bavaria are scaling RoHS-compliant common anode procurement for patient-monitoring equipment. REACH substance restrictions from ECHA are forcing substrate metallization transitions to SAC305 solder alloys. Precision instrumentation clusters around Stuttgart and Munich concentrate wire-bonding capacity for diagnostic readouts.
China
Domestic display assemblers in Shenzhen and Dongguan are upgrading production lines to meet MIIT energy-efficiency standards for electronic components. GB standards for display energy consumption are accelerating phosphor reformulation across Pearl River Delta manufacturing hubs. Yangtze River Delta facilities are capturing wire-bonding technician capacity for medical-grade exports.
Japan
Transit authorities in Tokyo and Osaka are consolidating monochrome SKU portfolios into programmable RGB units for arrival-board standardization. METI efficiency guidelines and JIS electromagnetic compatibility frameworks govern component selection for railway applications. Precision instrumentation demand concentrates in the Chubu region around Nagoya.
United States
FDA device-labeling requirements for minimum contrast ratios are constraining phosphor formulation choices in medical 7-segment readouts. Domestic contract manufacturers are qualifying chip-on-board architectures to compress lead times for patient-monitoring OEMs. Industrial equipment demand clusters around Midwest automation corridors.
India
Medical device manufacturers are leveraging PLI scheme incentives to localize common cathode assembly for portable diagnostic equipment. CDSCO regulations enforce electromagnetic compatibility standards for diagnostic readouts. Karnataka and Maharashtra industrial corridors are attracting wire-bonding investments from Taiwanese display assemblers.
7 Segment LED Displays Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue chip-on-board specialization and regional certification shortcuts. The vendor base stratifies across three tiers: multinational component houses with captive semiconductor capacity, mid-scale display specialists with wire-bonding expertise, and regional assemblers serving price-sensitive industrial accounts. Two archetypes dominate: reliability-focused suppliers anchoring automotive and medical supply chains, and cost-optimized fabricators capturing consumer and retail volume. Competitive moves concentrate on multi-certification qualification programs and captive upstream capacity for LED die procurement.
Among Asia-Pacific-based manufacturers, Kingbright exemplifies the wire-bonding-integrated archetype with Taiwan-based captive capacity, while Lite-On Technology Corporation occupies a position within the optoelectronics component tier. Futaba Corporation represents the vacuum-fluorescent crossover specialist segment where pin-compatible LED replacements serve legacy equipment retrofit demand. Broadcom anchors the high-reliability qualification tier through automotive-grade offerings.
| Leading Market Players |
|---|
| Kingbright |
| Broadcom |
| Lumex |
| Visual Communications Company |
| Lite-On Technology Corporation |
| Visha |
| Opteq |
| Futaba Corporation |
| Foshan NationStar Optoelectronics |
| Others |
Value Network & Pricing Analysis
Medical device OEMs in Germany and the United States are consolidating procurement specifications around RoHS-compliant common anode displays with FDA-mandated contrast ratios, forcing assemblers to absorb SAC305 solder alloy cost premiums and specialized phosphor formulations while passing selective value through to premium-tier buyers.
Pricing Analysis
Rare-earth phosphor cost pass-through from Chinese refining operations feeds directly into medical-grade display quotations, with dysprosium and terbium price volatility compressing margins on high-contrast readouts. Pricing stratifies across AEC-Q101 automotive certification tiers, FDA medical-grade contrast specifications, and standard industrial reliability levels. Cost compression in sub-0.5-inch consumer segments runs through low-cost OLED substitution pressure. Industrial equipment buyers exhibit highest price sensitivity, while automotive and medical procurement accepts premium positioning for qualification assurance.
Supply Chain Analysis
Single-source vulnerability sits with Taiwanese wire-bonding capacity for precision gold-wire medical and automotive displays, where skilled technician scarcity constrains expansion. LED die supply draws from Taiwan, China, and South Korea, while driver IC sourcing rests on Malaysian and Chinese assembly hubs. Tariff exposure on rare-earth phosphor imports from Chinese refining operations presents structural risk. Distribution runs through authorized component distributors serving medical and automotive OEMs, with direct procurement relationships dominating high-volume industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market hinges on chip-on-board packaging adoption compressing lead times and captive phosphor formulation investments capturing premium-tier medical and automotive qualification premiums.
For Market Incumbents: Hedge against OLED substitution in sub-0.5-inch consumer applications by accelerating AEC-Q101 and EN 50155 qualification pipelines for electric vehicle and railway retrofit demand. Deepen backward integration into LED die procurement through multi-source qualification programs across Taiwanese and Chinese foundries to defend margin control against supply volatility. For New Entrants and Emerging Players: Regional medical device contract manufacturers in India and Southeast Asia represent underserved buyers seeking localized common cathode assembly under CDSCO and domestic regulatory frameworks. Penetrate this segment through chip-on-board packaging specialization with compressed lead times versus established multinational suppliers. For Investors and Strategic Acquirers: Asymmetric upside sits with wire-bonding-integrated mid-scale specialists possessing captive Taiwan-based capacity and existing multi-certification portfolios. Long-term viability favors targets with demonstrated FDA, AEC-Q101, and EN 50155 qualification track records. Monitor phosphor formulation patent filings as inflection indicator for premium-tier positioning capability.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Certification Qualification Pipeline | Simultaneous AEC-Q101, FDA, and EN 50155 pursuit opens electric vehicle and railway retrofit specification windows. |
| Chip-on-Board Packaging Investment | Direct-die attachment architectures enable German and Japanese medical contract manufacturers to compress regional fulfillment lead times. |
| Captive Wire-Bonding Capacity Expansion | Taiwan-based precision gold-wire operations defend margin control against technician scarcity across Malaysian assembly hubs. |
| Phosphor Formulation Backward Integration | In-house rare-earth phosphor development captures FDA contrast-ratio premium positioning in patient-monitoring equipment. |
| RGB Programmable Unit Standardization | I2C-addressable color state consolidation reduces Japanese transit authority inventory carrying costs versus monochrome SKU proliferation. |
Research Methodology
Multiple input streams — primary interviews with display assembler procurement directors, medical device OEM engineering leads, and automotive Tier 1 supplier quality managers; secondary validation through MIIT GB standard filings, FDA 510(k) device labeling databases, and ECHA REACH candidate list updates; plus customs trade data on LED die and phosphor imports — were reconciled through bottom-up and top-down triangulation.
Historical shipment patterns were cross-referenced against expert panel inputs on regulatory timeline acceleration and certification burden evolution. Segmentation dimensions modeled span electrical configuration type, application environment thermal requirements, end-user procurement sophistication, and character height size tier across the projection horizon. CAGRs were derived from installed base replacement cycles, electric vehicle production ramp assumptions, and railway rolling stock retrofit program announcements.
Underlying measurement precision varies by segment; automotive and medical qualification tiers carry tighter precision than standard industrial and consumer electronics categories. Forecasts reflect assumptions on regulatory enforcement consistency, rare-earth supply concentration persistence, and wire-bonding technician pipeline development. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
LED Tube Drivers Market
LED
Infrared (IR) LED Market
LED
LED Modular Display Market
LED
UV LED Market
LED
Africa LED Lighting Market
LED
Germany Automotive LED Lighting Market
LED
Biometrics Infrared LED Market
LED
Four-Digit 7 Segment LED Displays Market
LED
LED Lighting Market
LED
Bi-Color LED Ring Light Market
LED
Asia Pacific Outdoor LED Lighting Market
LED
Mini LED Display Market
LED
LED Flip Chip Market
LED
LED and OLED Display Market
LED
Global Chip on Board (COB) Light Emitting Diode Market
LED
Smart LED Indoor Signage Market