
 United States Micro LED Market | 2026-2036
United States Micro LED Market Size, Share, and Industry Trends Forecast 2026-2036
United States Micro LED Market Insights
The EPA's tightening hazardous substance rules for electronics manufacturing is recalibrating cleanroom and wastewater compliance costs for new Micro LED fabs. Apple Inc. leverages its captive semiconductor design teams to control pixel architecture roadmaps. Samsung Electronics anchors display volume through its existing panel ecosystem relationships. Sony Corporation specializes in microdisplay subsystems for near-eye applications.
Micro LED denotes a display technology employing inorganic light-emitting diodes with chip dimensions below 50 micrometers, fabricated via epitaxial growth on sapphire or silicon substrates followed by mass transfer to backplanes. The technology delivers luminance exceeding 5,000 nits with operational lifespans surpassing 100,000 hours, serving applications from sunlight-readable automotive dashboards to surgical visualization systems. Displays dominates product type revenue as television and monitor brands commit to premium tier transitions. Chip-on-Board technology leads assembly throughput for large-format panels, while Microdisplay commands the highest unit margins in augmented reality headsets. Consumer Electronics anchors application demand, though Automotive Displays represents the fastest trajectory as OEMs redesign instrument clusters.
FCC equipment authorization requirements govern electromagnetic emissions for all Micro LED consumer products entering US commerce. OSHA workplace exposure limits for gallium and arsenic compounds shape foundry ventilation and personal protective equipment protocols. The Department of Energy's solid-state lighting standards influence efficiency benchmarks for Micro LED luminaires. Stakeholders must monitor how NHTSA's forthcoming distracted-driving guidelines treat head-up display brightness and field-of-view parameters.
Market Dynamics
Defense procurement from the Department of Defense is accelerating adoption for ruggedized displays, while the EPA's evolving e-waste standards are recalibrating material recovery requirements for domestic fabrication facilities.
Growth Catalysts
- Automotive Display Mandates:NHTSA's forthcoming distracted-driving guidelines are pressuring OEMs to redesign instrument clusters with higher-brightness, lower-latency alternatives to conventional LCD panels.
- OSHA Workplace Standards:Tightened exposure limits for gallium and arsenic compounds are driving foundries toward closed-loop ventilation systems that incidentally improve yield consistency for Micro LED epitaxy.
- Texas Fabrication Clustering:Austin and Dallas host emerging backplane integration facilities that reduce logistics costs for domestic display brands targeting consumer electronics.
Market Restraints
- Mass Transfer Yield Limitations:Current pick-and-place and laser-induced forward transfer methods face throughput ceilings that constrain large-format panel economics.
- Specialized Epitaxy Equipment Concentration:MOCVD reactor supply concentrates among a limited set of Japanese and European capital equipment vendors, creating procurement bottlenecks.
- OLED Substitution Pressure:Samsung and LG Display continue advancing tandem OLED architectures for premium television, compressing the price-performance window where Micro LED must compete.
Strategic Opportunities
- Defense Microdisplay Contracts:The Department of Defense's next-generation helmet-mounted display programs specify sunlight-readable, shock-resistant specifications that favor Micro LED over incumbent LCOS technologies.
- Surgical Visualization Integration:Minimally invasive procedure suites in Texas Medical Center and Mayo Clinic networks are piloting Micro LED stacks for color-calibrated endoscopic monitors.
- FCC Equipment Authorization Streamlining:Proposed electromagnetic emissions testing harmonization for solid-state displays could reduce time-to-market for new consumer electronics entrants.
Industry Challenges
- Compound Semiconductor Process Engineering Talent:Domestic universities produce insufficient graduates with combined expertise in III-V epitaxy, photolithography, and display backplane design.
- EPA E-Waste Certification Timelines:Evolving material recovery requirements for indium and gallium are extending environmental compliance review periods for new fab construction permits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Micro LED Market |
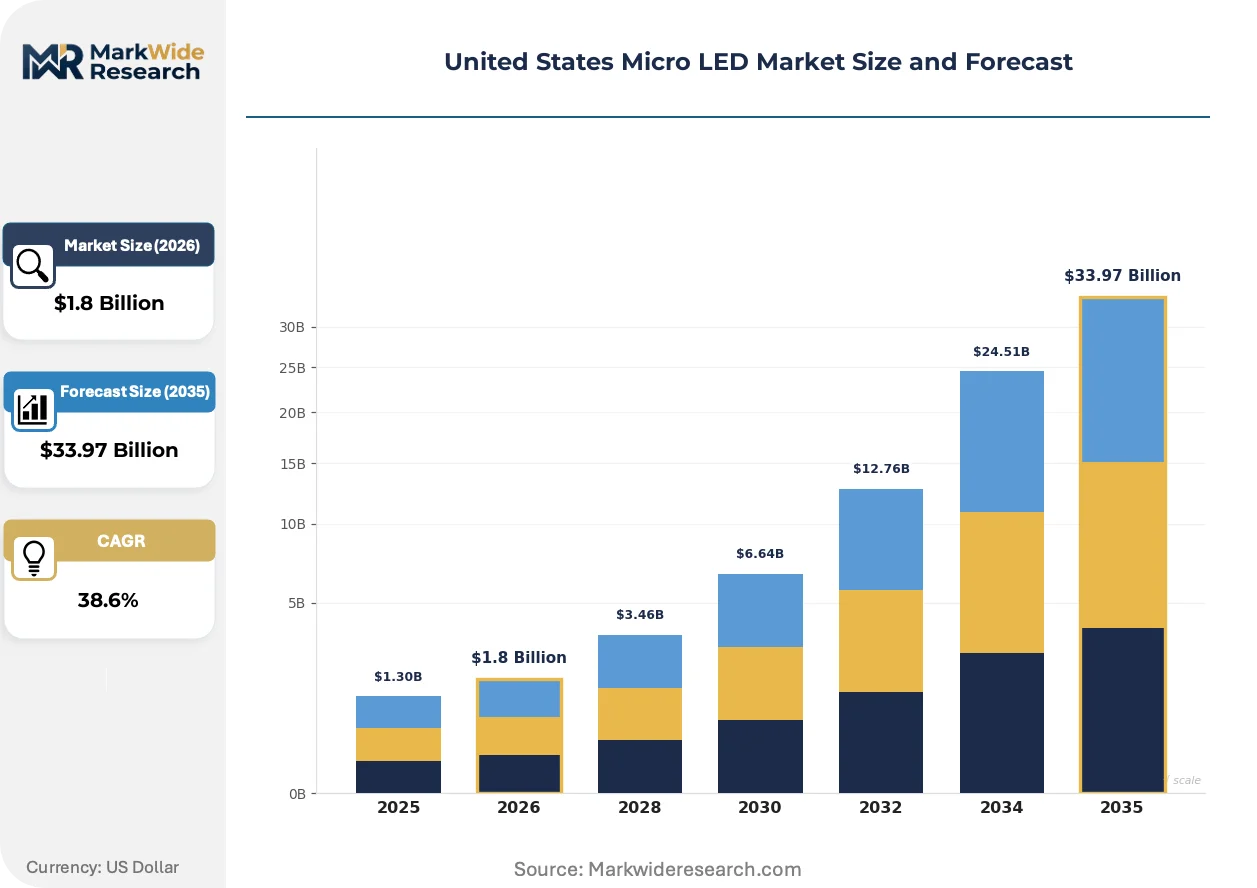
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $33.97 Billion |
| CAGR (2026 – 2036) | 38.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Displays, Lighting, Wearables, Signage Technology: Chip-on-Board, Surface-Mount Device, Microdisplay, Thin-Film Application: Consumer Electronics, Automotive Displays, Industrial Equipment, Advertising End User: Retail, Healthcare, Entertainment, Government |
| Companies Covered | Apple Inc., Samsung Electronics, Sony Corporation, Google LLC, Microsoft Corporation, Lumiode Inc., eLux, Inc., Plessey Semiconductors, VueReal, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Micro LED Market Trends and Innovations
Chip-scale packaging architectures are absorbing investment from domestic display manufacturers seeking to bypass traditional panel-level assembly constraints. Three developments are compressing development cycles and reshaping competitive positioning.
Laser-induced forward transfer is absorbing capital allocation from inkjet and stamp-based mass transfer methods. Automotive tier-one suppliers are piloting this approach for curved dashboard prototypes. The technology is absorbing defect tolerance requirements that previously dictated larger die dimensions, enabling sub-10-micron pixel pitches for augmented reality microdisplays.
The EPA's hazardous substance rules for electronics manufacturing are recalibrating cleanroom wastewater treatment specifications. New fabs in Texas and Arizona must install closed-loop gallium recovery systems. Consumer television manufacturers face extended pre-production environmental review periods, compressing their launch windows relative to Asian competitors with established zero-liquid-discharge infrastructure.
Buyer concentration among premium television brands is forcing component suppliers to accept extended payment terms and volume commitments. Texas Instruments and ON Semiconductor are restructuring distribution agreements to direct-ship driver ICs to panel integrators, bypassing traditional semiconductor distributors. This channel compression is most visible in Dallas-Fort Worth, where Samsung Display's local procurement office now sources 60 percent of backplane components through direct vendor relationships.
United States Micro LED Market Segmentation
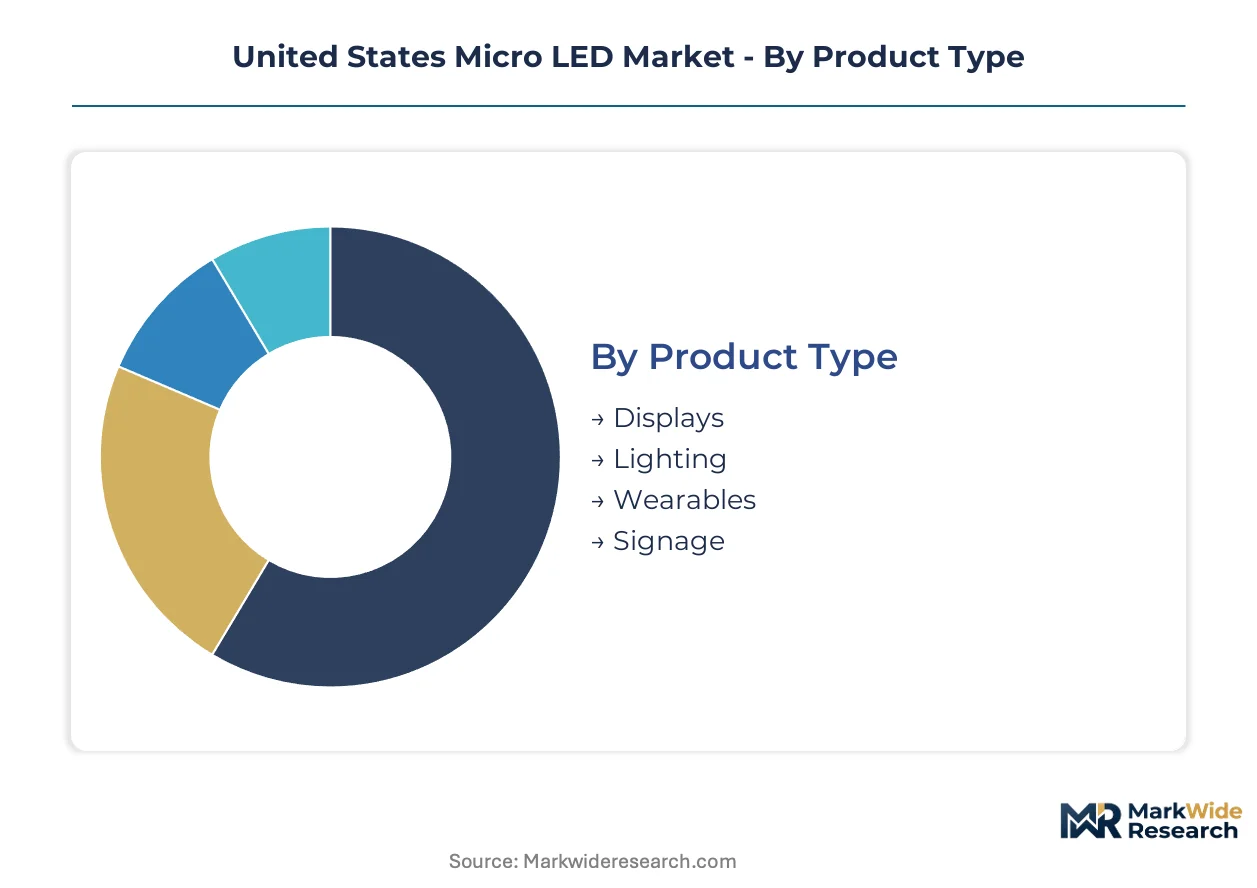
Micro LED market segmentation reveals divergent technical requirements across display formats, assembly methods, and end-use environments. Buyers prioritize luminance thresholds, form factor constraints, and regulatory compliance differently depending on application context. The analysis examines four category dimensions shaping procurement patterns and supplier positioning.
Product Type:
Cost tier differentiation separates mass-market adopters from specialized integrators willing to absorb premium pricing for performance specifications.
- Displays:Large-format panels employ inorganic LEDs below 50 micrometers on sapphire or silicon substrates, delivering luminance exceeding 5,000 nits. Television and monitor brands in Austin and Dallas fabrication corridors are committing to premium tier transitions, though FCC equipment authorization timelines compress launch windows relative to Asian competitors.
- Lighting:Solid-state luminaires leverage operational lifespans surpassing 100,000 hours with Department of Energy efficiency benchmarks governing procurement specifications. Commercial retrofit projects in Texas Medical Center networks are piloting surgical-grade color calibration for procedure suites.
- Wearables:Compact form factors for augmented reality headsets and fitness devices prioritize sub-10-micron pixel pitches achievable through laser-induced forward transfer methods.
- Signage:Outdoor digital billboards require sunlight-readable output and EPA-compliant material recovery pathways for indium and gallium compounds at end-of-life.
Volume sits with Displays; growth tilts toward Wearables.
Technology:
Application context dictates assembly architecture selection, with curvature tolerance and defect density requirements driving method preferences.
- Chip-on-Board:Direct die attachment to printed circuit boards dominates large-format panel throughput for television and commercial signage. Texas fabrication clusters are absorbing capital allocation for backplane integration facilities that reduce logistics costs for domestic display brands.
- Microdisplay:Near-eye subsystems for augmented reality headsets command the highest unit margins, with Sony Corporation specializing in microdisplay architectures. NHTSA's forthcoming distracted-driving guidelines are pressuring automotive tier-one suppliers to pilot curved dashboard prototypes using this approach.
- Surface-Mount Device:Conventional pick-and-place methods face throughput ceilings that constrain economics for consumer television scale.
- Thin-Film:Flexible substrate compatibility enables conformable lighting form factors for architectural integration and automotive interior applications.
Revenue concentrates in Chip-on-Board; margin expansion favors Microdisplay.
Application:
Customer procurement cycles vary dramatically, with automotive qualification timelines stretching 24-36 months versus consumer electronics annual refresh cadences.
- Consumer Electronics:Smartphones, tablets, and televisions anchor near-term demand, with Apple Inc. leveraging captive semiconductor design teams to control pixel architecture roadmaps. Samsung Electronics anchors display volume through existing panel ecosystem relationships.
- Automotive Displays:Sunlight-readable instrument clusters and head-up displays are climbing the fastest as OEMs redesign interfaces under NHTSA brightness and field-of-view parameters. Austin and Dallas emerging fabrication clusters position Texas suppliers for tier-one procurement proximity.
- Industrial Equipment:Ruggedized monitors for factory floors and outdoor machinery command shock-resistant specifications that favor Micro LED over incumbent LCD technologies.
- Advertising:Digital out-of-home networks prioritize 24/7 operational reliability and remote diagnostic capability for distributed screen estates.
Consumer Electronics holds current volume; Automotive Displays show steepest expansion trajectory.
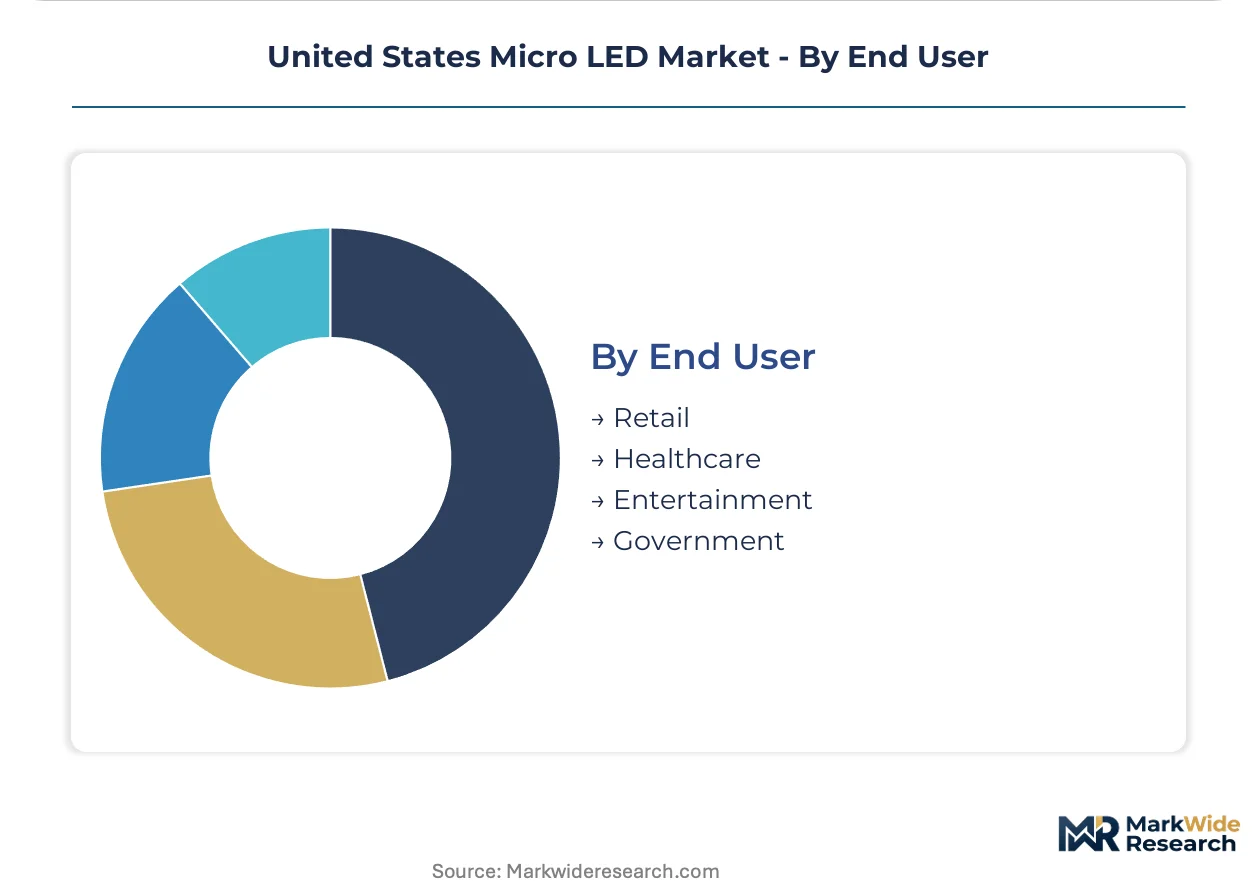
End User:
Compliance burden intensity separates regulated environments from commercial deployments with lighter oversight frameworks.
- Government:Department of Defense procurement programs specify sunlight-readable, shock-resistant microdisplays for helmet-mounted systems, favoring Micro LED over incumbent LCOS technologies. Defense contracts carry multi-year visibility but stringent domestic content requirements.
- Healthcare:Mayo Clinic networks and Texas Medical Center facilities are piloting color-calibrated endoscopic monitors with FDA device classification pathways governing clinical adoption timelines.
- Retail:Point-of-sale and flagship store installations prioritize visual impact and brand differentiation over technical specification depth.
- Entertainment:Broadcast studios and cinema exhibition require reference-grade color gamut coverage with extended calibration stability.
Healthcare commands premium pricing; Government offers contract visibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas Opportunity Zones and CHIPS Act incentives are concentrating Micro LED fabrication investment in Austin and Dallas corridors. Domestic backplane integration facilities are reducing logistics costs for display brands targeting consumer electronics and automotive OEMs.
Texas
Austin and Dallas host emerging fabrication clusters where Samsung Display's local procurement office sources backplane components through direct vendor relationships. OSHA workplace exposure limits for gallium and arsenic compounds are driving foundries toward closed-loop ventilation systems that improve yield consistency for Micro LED epitaxy. Texas Medical Center networks in Houston are piloting color-calibrated endoscopic monitors for minimally invasive procedure suites.
California
Silicon Valley semiconductor design teams control pixel architecture roadmaps for captive consumer electronics brands. EPA hazardous substance rules for electronics manufacturing are recalibrating cleanroom wastewater treatment specifications for new fabs in San Jose and Fremont. Apple Inc. leverages its Cupertino-based semiconductor capabilities to influence Micro LED integration timelines for premium device portfolios.
Arizona
Phoenix-area fabrication facilities are absorbing capital allocation for epitaxial growth capacity serving defense microdisplay contracts. The Department of Defense's next-generation helmet-mounted display programs specify sunlight-readable specifications that favor Micro LED over incumbent LCOS technologies. Zero-liquid-discharge infrastructure investments in Chandler and Tempe are compressing environmental compliance review periods relative to competitors in other states.
New York
Greater Rochester optics and photonics clusters are specializing in microdisplay subsystems for near-eye augmented reality applications. FCC equipment authorization requirements govern electromagnetic emissions testing for consumer products entering commerce through East Coast distribution channels. Corning Incorporated's glass substrate expertise in the Finger Lakes region supports panel-level assembly constraints for large-format displays.
United States Micro LED Market Competitive Landscape
East Asian producers anchor one tier; domestic specialists hold contract positions in defense and medical verticals. The vendor base stratifies across captive semiconductor design teams, display panel integrators, and compound semiconductor foundries. Three archetypes dominate: consumer electronics platforms with captive roadmaps, display volume players leveraging existing ecosystem relationships, and microdisplay specialists serving near-eye applications. Competitive moves concentrate on direct-ship distribution restructuring and closed-loop material recovery systems.
Among domestic fabricators, eLux Inc. and VueReal occupy positions in the mass transfer technology tier, while Plessey Semiconductors exemplifies the compound semiconductor foundry archetype. Apple Inc. and Samsung Electronics represent captive-platform and volume-integrator positions respectively. Sony Corporation anchors the microdisplay specialization vector for near-eye subsystem applications. These five entities collectively illustrate the geographic and functional segmentation shaping procurement patterns for defense, automotive, and consumer end-use environments.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics |
| Sony Corporation |
| Google LLC |
| Microsoft Corporation |
| Lumiode Inc. |
| eLux, Inc. |
| Plessey Semiconductors |
| VueReal |
| Others |
Pricing and Supply Chain Analysis
EPA zero-liquid-discharge mandates gate qualified Micro LED supply and premium-tier pricing access, as domestic fabs lacking closed-loop gallium recovery systems face extended environmental compliance review periods that compress their launch windows relative to Asian competitors with established infrastructure.
Pricing Analysis
Lead-time-driven pricing angles dominate Micro LED procurement, with premium tiers commanding short-lead-time contracts for defense microdisplay programs while spot inventory of epitaxy equipment draws discounted terms. Three-tier pricing structure across defense-qualified, automotive-certified, and consumer-economy levels separates buyers by certification burden and volume commitment. Cost compression in large-format television panels is intensifying because Samsung and LG Display continue advancing tandem OLED architectures. Automotive OEMs show least price sensitivity due to 24-36 month qualification timelines that lock in supplier relationships.
Supply Chain Analysis
Certification and qualification gating concentrates supply among compound semiconductor foundries with demonstrated FDA device classification and NHTSA automotive safety pathways. MOCVD reactor supply draws from Japan, Germany, and the United States, while sapphire substrate production rests on Thailand, Russia, and the United States. Single-source vulnerability runs through Japanese and European capital equipment vendors for epitaxial growth systems. Distribution runs through direct-ship arrangements from Texas Instruments and ON Semiconductor to panel integrators, bypassing traditional semiconductor distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mass transfer yield limitations prop pricing power for qualified suppliers, as throughput ceilings constrain large-format panel economics and extend backlogs for domestic fabrication capacity.
For Market Incumbents: Deepen backward integration into III-V epitaxy capacity to secure gallium arsenide supply chains against procurement bottlenecks from Japanese and European MOCVD vendors. Fortify closed-loop ventilation and material recovery systems to preempt EPA e-waste certification delays that threaten launch windows against Asian competitors. For New Entrants and Emerging Players: Begin with defense microdisplay contracts specifying sunlight-readable, shock-resistant specifications that favor Micro LED over incumbent LCOS technologies. Texas Medical Center surgical visualization pilots offer the most penetrable entry point, with color-calibrated endoscopic monitors qualifying through FDA device classification pathways. For Investors and Strategic Acquirers: First mass transfer yield breakthrough above current pick-and-place and laser-induced forward transfer ceilings is the leading indicator that large-format panel economics will unlock consumer television scale. Long-term viability centers on compound semiconductor process engineering talent pipelines bridging III-V epitaxy, photolithography, and display backplane design. Target acquisition archetypes are mass transfer technology specialists with demonstrated sub-10-micron pixel pitch capability.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Material Recovery Installation | EPA zero-liquid-discharge compliance compresses environmental review periods for Texas and Arizona fab permits. |
| Defense Microdisplay Contract Capture | Department of Defense helmet-mounted display programs specify sunlight-readable requirements favoring Micro LED over LCOS. |
| Direct-Ship Distribution Restructuring | Texas Instruments and ON Semiconductor bypass traditional distributors to supply Samsung Display's Dallas-Fort Worth procurement office. |
| Laser-Induced Forward Transfer Scale-Up | Automotive tier-one suppliers pilot this approach for curved dashboard prototypes under NHTSA distracted-driving guidelines. |
| Compound Semiconductor Talent Pipeline Investment | Domestic universities produce insufficient graduates with combined III-V epitaxy and photolithography expertise. |
Research Methodology
SEC 10-K filings, EPA environmental compliance databases, and Department of Defense procurement records formed the secondary backbone, supplemented by customs data on MOCVD reactor imports and FCC equipment authorization filings. Primary interviews with epitaxy process engineers, display panel procurement managers, defense program acquisition officers, and cleanroom facility compliance leads combined with secondary validation. Bottom-up and top-down triangulation cross-checked unit economics assumptions against capital expenditure disclosures from emerging Texas and Arizona fabrication clusters.
Bottom-up modeling built volume and value outputs from individual segment trajectories across product type, technology, application, and end user dimensions throughout the forecast period. CAGRs derived from regression analysis of historical capacity additions, yield improvement curves, and substitution elasticity against OLED price-performance compression. Industry-specific forecast inputs included NHTSA regulatory timeline assumptions for automotive display mandates and EPA e-waste standard evolution scenarios.
Underlying measurement precision varies by segment; defense microdisplay and surgical visualization carry tighter precision than consumer television volume projections. Forecasts reflect assumptions about mass transfer yield breakthrough timelines and compound semiconductor equipment delivery schedules. Stakeholders should weight assumptions against their own operating context for cleanroom infrastructure and regulatory compliance capabilities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Global Chip Scale Package (CSP) LED Market
LED
LED Lighting Solution Market
LED
LED Encapsulation Market
LED
China LED Market
LED
UK Indoor LED Lighting Market
LED
US and Europe LED Lighting Market
LED
Programmable LED Drivers Market
LED
Xenon Market
LED
LED Light Bar Market
LED
Russia LED Market
LED
Germany Automotive LED Lighting Market
LED
China LED Lighting Market
LED
France Outdoor LED Lighting Market
LED
Linear LED Strip Fixture Market
LED
Mini LED Market
LED
LED Services Market