
 Global Diodes Market | 2026-2036
Global Diodes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Diodes Market Foresight
Wide-bandgap semiconductor migration is fragmenting the traditional silicon diode hierarchy across high-voltage applications. Infineon Technologies AG anchors European automotive qualification pipelines with in-house SiC and GaN portfolios. onsemi leverages its integrated substrate and fab capacity to control cost curves in power rectifiers. Vishay Intertechnology Inc. specializes in discrete component miniaturization for space-constrained consumer and industrial designs.
A diode is a two-terminal semiconductor device permitting unidirectional current flow, typically fabricated from doped silicon, silicon carbide, or gallium nitride with junction voltages ranging from 0.3V to 3.5V depending on material, serving circuit protection, rectification, and signal modulation functions across electronic systems. Schottky diodes occupy premium margin pools in switching power supplies due to lower forward voltage drop, while silicon carbide technology leads fastest adoption in automotive traction inverters where thermal performance outweighs cost sensitivity. Rectifier diodes sustain volume dominance in legacy industrial power supplies even as OEMs shift procurement toward higher-efficiency alternatives.
REACH and RoHS frameworks in Europe restrict hazardous substance content in diode packaging and substrates, compelling material substitutions that extend qualification cycles. The EPA and NHTSA in the United States shape automotive diode demand through emissions and fuel-economy mandates that expand electrified powertrain content. China's SAMR and GB standards enforce domestic semiconductor reliability benchmarks that foreign suppliers must satisfy for market access. Stakeholders must monitor substrate supply concentration and evolving automotive-grade certification requirements to secure position in next-generation power electronics procurement.
Market Dynamics
Silicon carbide substrate qualification timelines are compressing as automotive OEMs demand higher thermal performance in electrified powertrains, forcing packaging clusters in East Asia to retool for faster automotive-grade certification cycles.
Growth Catalysts
- EV powertrain electrification:Automotive OEMs are specifying heavier diode loads per vehicle, with traction inverters and onboard chargers requiring discrete power components that withstand elevated switching frequencies.
- China's NMPA-aligned certification:Streamlined semiconductor reliability protocols are accelerating market access for automotive-grade diodes, reducing traditional 18-month qualification windows.
- SiC substrate maturation:Epitaxial growth improvements and defect density reductions are expanding addressable applications beyond premium automotive into industrial motor drives.
Market Restraints
- Substrate supply concentration:High-purity silicon carbide wafers concentrate among a limited set of boule growers, creating input cost volatility for diode fabricators without captive supply.
- REACH material substitutions:European restrictions on hazardous substances in packaging and substrates compel material changes that extend qualification cycles and raise compliance costs.
- Silicon rectifier persistence:Legacy industrial power supplies continue specifying standard silicon diodes where thermal performance requirements do not justify wide-bandgap premiums.
Strategic Opportunities
- India's PLI scheme for semiconductors:Production-linked incentives for domestic packaging and test facilities are creating new manufacturing nodes for automotive and industrial diode suppliers.
- GaN-SiC convergence in consumer adapters:Gallium nitride transistors paired with silicon carbide diodes are opening high-frequency, space-constrained applications in premium laptop and mobile fast-charging segments.
- EU Green Deal industrial retrofit mandates:Energy efficiency requirements for motor systems are driving replacement cycles in European manufacturing facilities, expanding demand for high-efficiency rectification.
Industry Challenges
- Automotive-grade AEC-Q101 certification:Extended temperature cycling and humidity testing requirements strain qualification timelines, particularly for suppliers transitioning from industrial to automotive specifications.
- Packaging talent scarcity:Copper clip and ribbon bonding expertise for high-current diode modules concentrates among senior engineers in East Asian packaging clusters, limiting rapid capacity expansion elsewhere.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Diodes Market |
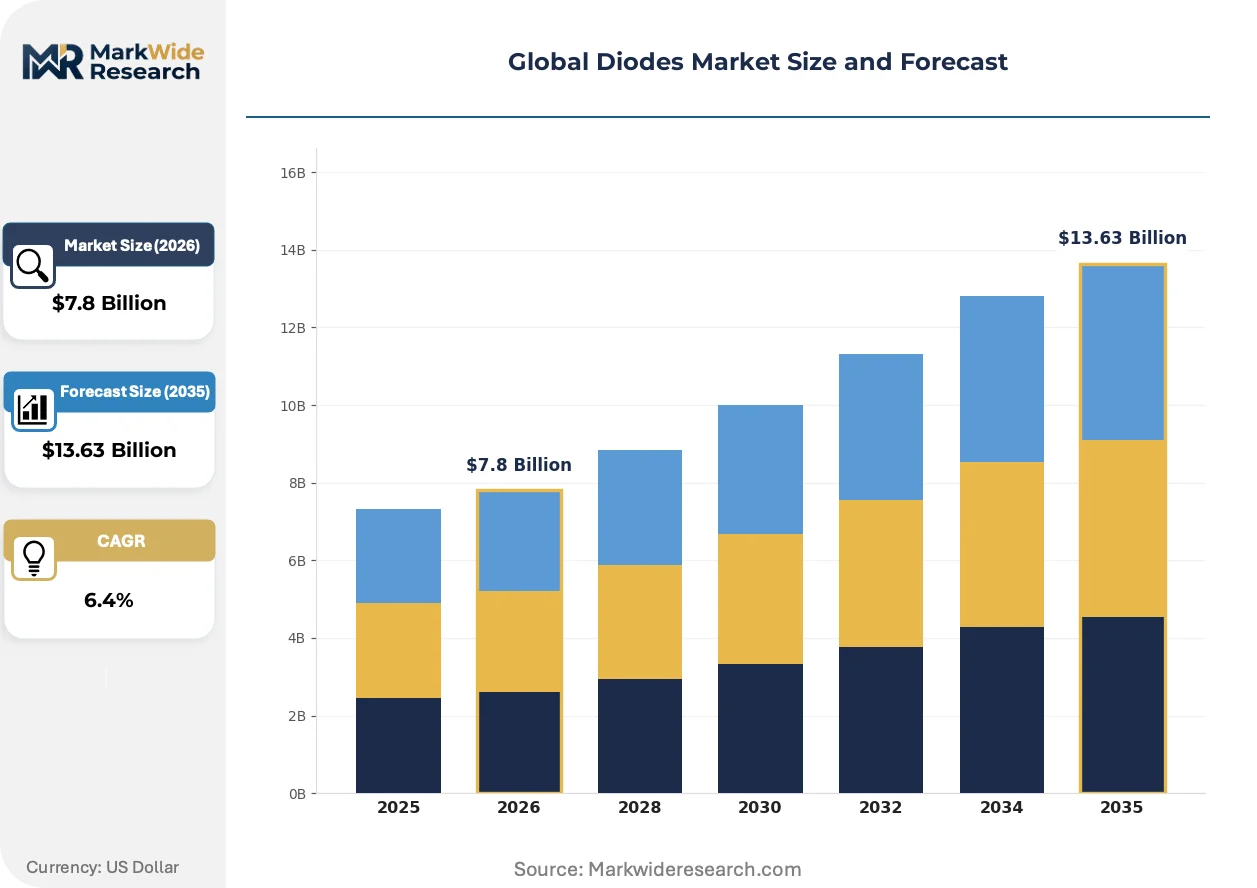
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rectifier Diodes, Zener Diodes, Schottky Diodes, Light Emitting Diodes, Photodiodes Technology: Silicon, Gallium Arsenide, Silicon Carbide, Germanium, Gallium Nitride Application: Consumer Electronics, Telecommunications, Power Supplies, Automotive Electronics, Lighting Systems End User Industry: OEMs, Telecommunications Equipment Manufacturers, Lighting Manufacturers, Electronic Assemblers, Industrial Electronics Firms |
| Companies Covered | Infineon Technologies AG, onsemi, Vishay Intertechnology Inc., STMicroelectronics NV, Diodes Incorporated, ROHM Co. Ltd., NXP Semiconductors NV, Toshiba Electronic Devices and Storage Corp., Microchip Technology Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Diodes Market Shifts & Advancements
Wide-bandgap semiconductor migration is fragmenting established component hierarchies, with thermal performance specifications now dictating procurement decisions ahead of unit cost considerations in premium applications.
Silicon carbide Schottky diodes are digitizing power conversion architectures by enabling higher switching frequencies with reduced thermal management overhead. Automotive traction inverter suppliers are adopting these devices aggressively, with procurement volumes scaling in proportion to EV platform launches. This frequency capability is digitizing the traditional trade-off between efficiency and magnetic component size, collapsing inductor and capacitor requirements in onboard chargers.
REACH and RoHS frameworks in Europe are tightening hazardous substance restrictions on diode packaging materials and substrate metallization layers. Manufacturers must reformulate leadframe platings and molding compounds to maintain market access, with compliance costs falling disproportionately on mid-volume industrial suppliers. German automotive electronics clusters are responding by consolidating procurement with qualified suppliers holding pre-certified material portfolios.
Buyer concentration among tier-one automotive electronics suppliers is compressing switching cycles and demanding vendor-managed inventory arrangements. Direct procurement relationships with inverter and charger manufacturers are displacing traditional distribution channels for high-reliability diode categories. This concentration is most visible in South Korea and Japan, where integrated chaebol and keiretsu structures favor captive or preferred supplier relationships over open market sourcing.
Global Diodes Market Segmentation
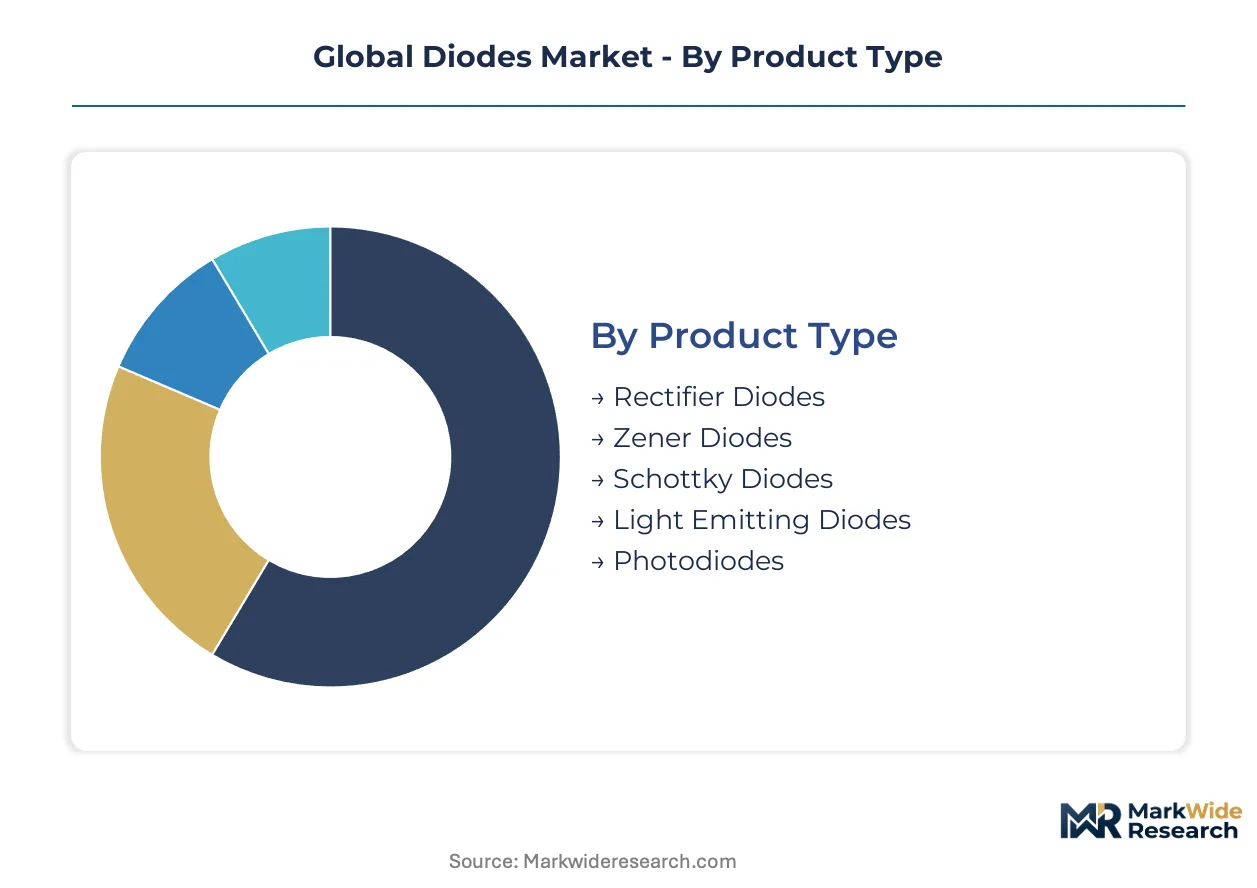
Diode segmentation reveals how material science, voltage requirements, and thermal specifications fragment procurement patterns across end-use industries. Each dimension carries distinct margin profiles and qualification burdens that reshape supplier positioning.
Product Type:
After-sales service intensity varies sharply by product type, with automotive-grade rectifiers demanding traceability systems and failure analysis support that consumer-grade LEDs rarely require.
- Rectifier Diodes:Silicon-based unidirectional current devices handling AC-to-DC conversion in power supplies and industrial motor drives. Demand concentrates in German automotive electronics clusters serving EV onboard charger manufacturers facing NHTSA electromagnetic compatibility mandates.
- Schottky Diodes:Metal-semiconductor junction devices with sub-0.5V forward voltage drop enabling high-frequency switching. Procurement is accelerating in South Korean consumer adapter factories pairing these with GaN transistors for space-constrained fast-charging applications.
- Zener Diodes:Reverse-biased voltage regulation components maintaining stable reference levels across circuit protection networks.
- Light Emitting Diodes:Electroluminescent p-n junctions converting electrical current to visible light in solid-state illumination systems.
- Photodiodes:Reverse-biased light sensors generating photocurrent for optical communication and sensing applications.
Rectifier diodes hold the largest share; momentum sits with Schottky variants in high-frequency power conversion.
Technology:
Cost tier stratification separates premium wide-bandgap substrates from commodity silicon, with each technology commanding distinct qualification timelines and thermal performance premiums.
- Silicon Carbide:Wide-bandgap semiconductor with 3x thermal conductivity of silicon enabling 175°C+ junction temperatures. Infineon and onsemi are scaling 6-inch and 8-inch wafer production for traction inverter modules in European and Chinese EV platforms.
- Gallium Nitride:High-electron-mobility material supporting megahertz-range switching frequencies in compact adapters. Adoption is climbing fastest in premium laptop charging segments where magnetic component miniaturization justifies substrate cost premiums.
- Silicon:Mature semiconductor substrate dominating legacy industrial rectification where thermal margins permit standard junction temperatures.
- Gallium Arsenide:Compound semiconductor substrate for high-frequency RF and photonic applications requiring direct bandgap properties.
- Germanium:Narrow-bandgap material reserved for specialized infrared detection and low-voltage signal processing.
Silicon sustains volume dominance; SiC substrates are gaining share fastest in automotive electrification.
Application:
Customer type fragmentation separates high-reliability automotive procurement from price-sensitive consumer electronics sourcing, with distinct vendor qualification requirements.
- Automotive Electronics:AEC-Q101-certified devices for powertrain, lighting, and infotainment systems. Tier-one suppliers in Japan and South Korea are consolidating procurement with qualified vendors holding pre-certified material portfolios under REACH and RoHS frameworks.
- Power Supplies:Industrial and consumer rectification equipment requiring efficiency optimization. Demand is concentrating in East Asian packaging clusters serving server and telecom infrastructure builders.
- Consumer Electronics:Portable device charging and circuit protection applications.
- Telecommunications:Base station and fiber optic infrastructure signal conditioning.
- Lighting Systems:Solid-state illumination drivers and control circuits.
Power supplies hold the largest share; automotive electronics are expanding most quickly under electrification mandates.
End User Industry:
Supply concentration patterns favor integrated OEMs with captive design capabilities, while fragmented assemblers rely on distribution channels with longer lead times.
- OEMs:Original equipment manufacturers with direct component specification authority. German and Japanese automotive OEMs are compressing qualification windows through NMPA-aligned certification protocols and vendor-managed inventory arrangements.
- Telecommunications Equipment Manufacturers:5G infrastructure and fiber optic system builders specifying high-reliability signal conditioning components.
- Industrial Electronics Firms:Factory automation and motor drive manufacturers.
- Lighting Manufacturers:Solid-state illumination system integrators.
- Electronic Assemblers:Contract manufacturers serving mid-volume industrial and consumer applications.
OEMs command the largest procurement volumes; telecommunications equipment manufacturers are climbing fastest on 5G infrastructure deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports packaged diode components to German automotive electronics clusters, while Japanese substrate suppliers feed South Korean power module manufacturers. This triangular trade pattern concentrates value capture in East Asian packaging hubs and European qualification pipelines.
China
Domestic EV platform launches by BYD and NIO are absorbing record volumes of silicon carbide rectifiers. SAMR and GB standards enforce semiconductor reliability benchmarks that compress traditional qualification timelines for foreign suppliers. Yangtze River Delta packaging clusters in Suzhou and Wuxi are retooling for automotive-grade AEC-Q101 certification cycles.
Germany
BMW and Volkswagen electrification roadmaps are specifying heavier diode loads per traction inverter. REACH and RoHS frameworks restrict hazardous substances in packaging materials, compelling leadframe plating substitutions. Bavarian automotive electronics corridors around Munich and Ingolstadt are consolidating procurement with qualified vendors holding pre-certified material portfolios.
Japan
Toyota and Honda hybrid powertrains sustain demand for high-temperature rectifier modules. METI industrial policy directs subsidy flows toward wide-bandgap semiconductor commercialization. Kansai manufacturing belts around Osaka and Kyoto host concentrated packaging expertise for copper clip and ribbon bonding processes.
South Korea
Hyundai-Kia EV platforms are scaling procurement of fast-switching Schottky diodes for onboard chargers. MFDS-aligned reliability protocols mirror China's NMPA acceleration of automotive-grade certification. Seoul-Incheon packaging corridors serve Samsung SDI and LG Energy Solution with vendor-managed inventory arrangements.
United States
EPA and NHTSA emissions mandates expand electrified powertrain content across Detroit Three lineups. Domestic substrate supply constraints are forcing diode fabricators toward captive or long-term supply agreements. Michigan and Ohio automotive corridors are attracting packaging investments to reduce East Asian supply exposure.
Global Diodes Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market strata. The vendor base clusters around three strategic archetypes: integrated substrate-fab operators, discrete component miniaturization specialists, and automotive qualification pipeline anchors. Dominant competitive moves include backward integration into silicon carbide boule growing and strategic partnerships with East Asian packaging clusters.
Among European automotive qualification anchors, Infineon Technologies AG exemplifies the integrated substrate-fab archetype with in-house SiC and GaN portfolios. onsemi occupies a position as a scale-driven fabricator leveraging captive epitaxial capacity. Vishay Intertechnology Inc. represents the discrete miniaturization specialist tier serving space-constrained industrial and consumer designs.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| onsemi |
| Vishay Intertechnology Inc. |
| STMicroelectronics NV |
| Diodes Incorporated |
| ROHM Co. Ltd. |
| NXP Semiconductors NV |
| Toshiba Electronic Devices and Storage Corp. |
| Microchip Technology Inc. |
| Others |
Supply & Pricing Matrix
Suzhou packaging clusters anchor diode module assembly capacity and translate wafer supply tightness into tiered pricing power for automotive-grade devices. Yangtze River Delta foundries feed German automotive electronics corridors, where REACH-compliant material portfolios command certification premiums over standard industrial grades.
Pricing Analysis
Silicon-to-silicon-carbide pricing gaps stratify procurement across three performance tiers: legacy silicon rectifiers, premium SiC Schottky devices, and emerging GaN-integrated modules. Three-tier pricing structure across automotive-grade, industrial-standard, and economy consumer levels reflects AEC-Q101 certification burden and substrate thermal ratings. Pricing pressure stems from East Asian packaging cluster overcapacity in standard-grade segments, while automotive buyers show lowest price sensitivity due to thermal performance mandates from NHTSA and EPA electrification rules.
Supply Chain Analysis
Extended payment terms from tier-one automotive electronics suppliers strain working capital for mid-volume diode fabricators without captive substrate supply. High-purity silicon carbide wafers concentrate among boule growers in Japan and the United States, while packaging and test capacity clusters in China, South Korea, and Taiwan. Raw material dependencies span SiC substrates, copper leadframes, and epoxy molding compounds. Single-source vulnerability in 6-inch and 8-inch SiC wafer supply creates input cost volatility. Distribution runs through direct procurement relationships with inverter manufacturers displacing traditional component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wide-bandgap semiconductor migration is accelerating market disruption as automotive OEMs specify heavier diode loads per EV platform under EPA and NHTSA mandates. This technological inflection compresses qualification timelines and fragments established silicon supply hierarchies.
For Market Incumbents: Insulate automotive-grade margin pools through backward integration into silicon carbide epitaxial capacity and pre-certified REACH material portfolios. Lock in multi-year substrate supply agreements with Japanese boule growers to offset single-source vulnerability. Deepen vendor-managed inventory arrangements with Seoul-Incheon packaging corridors serving Hyundai-Kia and Samsung SDI.
For New Entrants and Emerging Players: Pursue India's PLI scheme for semiconductor packaging to establish automotive-grade test capacity outside East Asian concentration. Target industrial motor drive retrofit demand under EU Green Deal mandates where AEC-Q101 certification burden is lighter. Position through GaN-SiC convergence in premium consumer adapter segments pairing fast-switching diodes with gallium nitride transistors.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated substrate-fab operators with captive SiC epitaxy and established AEC-Q101 qualification pipelines. Long-term viability hinges on automotive electrification sustaining beyond initial EV platform launches. Watch NMPA-aligned certification protocol adoption rates as inflection indicator for market access velocity in China.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Epitaxy | Captive substrate supply insulates fabricators from boule-grower concentration in Japan and the United States. |
| AEC-Q101 Certification Investment | Automotive-grade qualification opens procurement pipelines with BMW, Volkswagen, and tier-one Japanese suppliers. |
| Vendor-Managed Inventory Arrangements | Direct relationships with LG Energy Solution and Samsung SDI displace distribution channel dependency. |
| REACH-Compliant Material Portfolio | Pre-certified leadframe platings maintain access to German automotive electronics clusters under ECHA frameworks. |
| GaN-SiC Module Development | High-frequency pairing targets premium laptop and mobile fast-charging segments in South Korean consumer factories. |
Research Methodology
A spread of perspectives from diode procurement managers at tier-one automotive suppliers, packaging engineers in Suzhou and Incheon, substrate specialists at Japanese boule growers, and regulatory affairs leads navigating REACH and NMPA protocols converged on the working assumptions. Primary fieldwork combined with secondary validation from SEC filings, customs trade data, SAMR certification registries, and EPA emissions mandate documentation. Bottom-up unit economics triangulated against top-down EV platform deployment schedules across the analysis window.
Demand-supply balance modeling segmented the market by substrate technology, voltage rating, end-use application, and geographic production cluster. CAGRs derived from vehicle electrification content trajectories, industrial retrofit cycle timing, and consumer adapter upgrade rates. Forecast inputs incorporated SiC wafer diameter transition timelines, packaging capacity utilization in East Asian clusters, and certification protocol harmonization between China's NMPA and European AEC-Q101 standards.
Macroeconomic conditions sit as an overlay; deviation in EV adoption rates, semiconductor capital expenditure cycles, or China-EU trade policy would shift the trajectory. Forecasts reflect documented assumptions about substrate defect density improvements and automotive OEM platform launch schedules. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
IGCT Market
Semiconductor Devices
Global Vacuum Capacitors Market
Semiconductor Devices
IGBT and Super Junction MOSFET Market
Semiconductor Devices
APAC Semiconductor Device in Consumer Industry Market
Semiconductor Devices
Global Precision Parts Market
Semiconductor Devices
Underfill Market
Semiconductor Devices
Home Appliance MCU Market
Semiconductor Devices
Global Through Silicon via (TSV) Technology Market
Semiconductor Devices
Global Probe Card Market
Semiconductor Devices
Global Cryptocurrency Mining Hardware Market
Semiconductor Devices
Bipolar Junction Transistors Market
Semiconductor Devices
Global Layer Pads Market
Semiconductor Devices
Reachers Market
Semiconductor Devices
Coated Silicon Wafer Market
Semiconductor Devices
Semiconductor Device in Aerospace and Defense Industry Market
Semiconductor Devices
Precision Link Carrier Market