
 Sulfur Guard Catalyst Market | 2026-2036
Sulfur Guard Catalyst Market Size, Share, and Industry Trends Forecast 2026-2036
Sulfur Guard Catalyst Market Analytics
Specialized catalyst engineering talent is bifurcating the competitive landscape, with elite formulation chemists clustering at integrated technology leaders. Albemarle Corp leverages its bromine and lithium expertise to sustain proprietary metal oxide catalyst platforms. Haldor Topsoe anchors its position through deep R&D investment in hydroprocessing technologies. Johnson Matthey competes via advanced zeolite architectures for sulfur guard applications.
Sulfur guard catalysts are porous solid materials—typically activated carbon, zeolite, or metal oxide substrates impregnated with active metals such as nickel, cobalt, or zinc—that chemisorb sulfur compounds from hydrocarbon feedstocks at temperatures ranging from ambient to 400°C, protecting downstream reforming and synthesis catalysts from irreversible poisoning. Fixed bed configurations dominate installed refinery base due to mechanical simplicity and predictable pressure drop, while fluidized bed designs are capturing incremental share in high-throughput gas processing units where catalyst circulation enables continuous regeneration. Metal oxide technology leads margin pools because of superior hydrogen sulfide capacity and regenerability, whereas organic sulfur compound guard systems occupy niche positions in ultra-low sulfur product finishing.
EPA Tier 3 standards and the EU F-Gas Regulation are forcing refiners to deepen sulfur removal, directly expanding catalyst replacement cycles and specification thresholds. REACH compliance in Europe and OSHA process safety mandates in the United States shape manufacturing site approvals and product registration requirements. Stakeholders must monitor how carbon border adjustment mechanisms and evolving biofuel blending mandates redefine catalyst performance benchmarks for co-processing feedstocks.
Market Dynamics
Refinery sulfur specifications are tightening faster than catalyst replacement cycles, forcing operators to upgrade guard bed configurations ahead of planned turnarounds. EPA Tier 3 gasoline standards and Europe's F-Gas Regulation are compressing the window between compliance deadlines and catalyst procurement lead times.
Growth Catalysts
- EPA Tier 3 sulfur limits:US refiners must reduce gasoline sulfur to 10 ppm, mandating deeper hydrotreating and more frequent guard catalyst replacement cycles in FCC pretreatment units.
- Stranded gas monetization:Sour gas processing capacity in the US Gulf Coast and Germany's Rhine-Ruhr cluster is expanding to handle high-sulfur feedstocks from depleted conventional reservoirs.
- Metal oxide regenerability:Regenerable zinc oxide and nickel-molybdenum formulations are extending catalyst service life, improving lifecycle economics for continuous reforming operations.
Market Restraints
- Cobalt supply concentration:Active metal precursors rely on cobalt mining concentrated in the Democratic Republic of Congo, exposing catalyst manufacturers to price volatility and ethical sourcing scrutiny.
- Zeolite manufacturing bottlenecks:Specialized hydrothermal synthesis capacity for ultra-stable Y-zeolite substrates is concentrated among integrated chemical conglomerates, limiting formulation flexibility for mid-tier catalyst producers.
- REACH registration timelines:New metal oxide compositions face extended European Chemicals Agency evaluation periods, delaying commercial deployment by 18-24 months compared to other jurisdictions.
Strategic Opportunities
- Biofuel co-processing mandates:Renewable diesel and sustainable aviation fuel blending requirements in Germany and the Netherlands are creating demand for guard catalysts tolerant of oxygenated and olefinic feedstock contaminants.
- Modular skid-mounted units:Compact, pre-engineered guard bed systems are penetrating small-scale hydrogen production and chemical synthesis installations previously served by field-erected configurations.
- Carbon border adjustment mechanisms:The EU's CBAM is incentivizing US and Middle Eastern refiners to document catalyst carbon intensity, favoring suppliers with verified low-emission manufacturing processes.
Industry Challenges
- Formulation chemist scarcity:Expertise in hydrothermal zeolite synthesis and metal-support interaction modeling is concentrating at legacy catalyst producers, constraining R&D throughput at emerging competitors.
- Legacy refinery integration:Retrofitting guard beds into 1970s-era hydrotreaters with limited plot space requires custom reactor designs that extend engineering procurement construction schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sulfur Guard Catalyst Market |
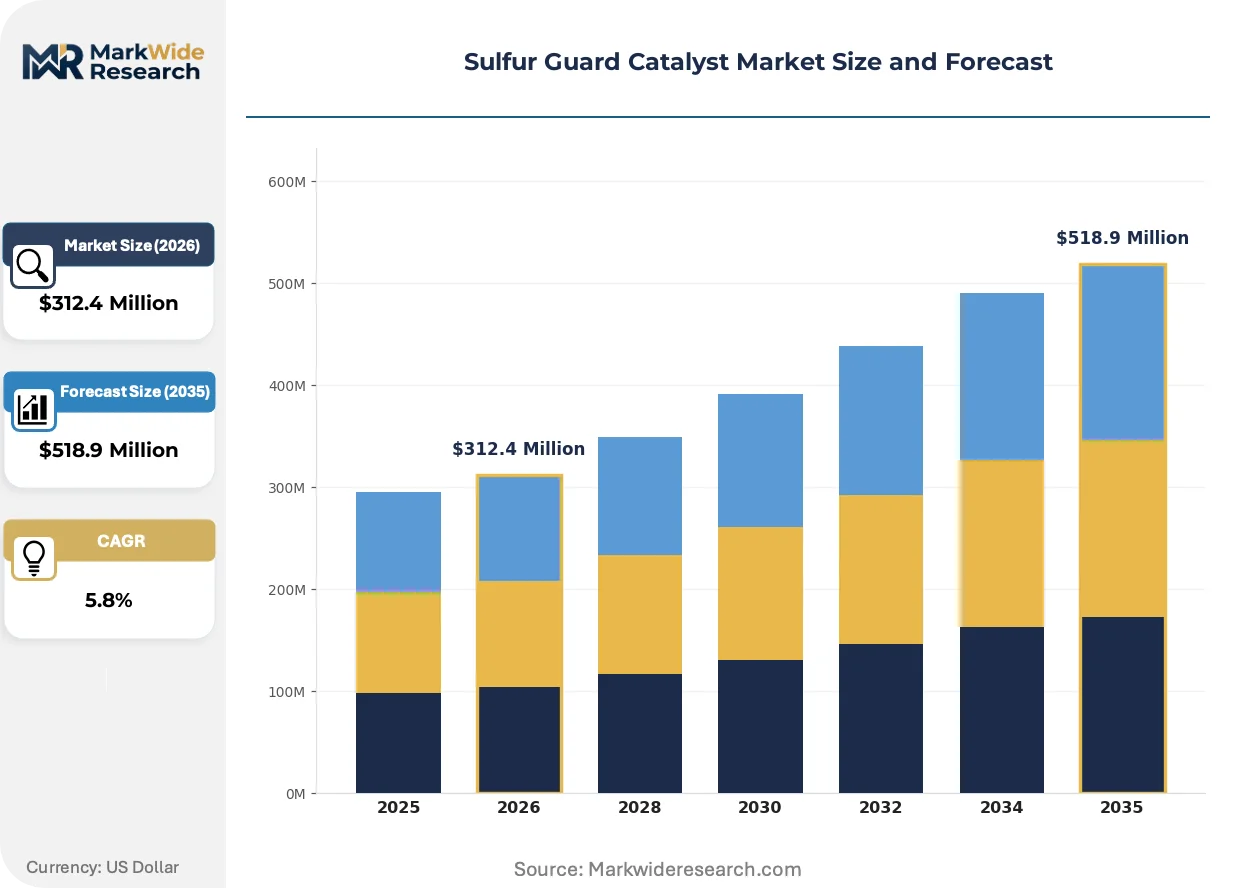
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Bed, Fluidized Bed, Slurry, Foam Application: Hydrocracking, Hydrotreating, Gas Processing, Desulfurization End User: Refineries, Petrochemical Plants, Chemical Manufacturers, Power Plants Technology: Activated Carbon, Zeolite, Metal Oxides, Organic Sulfur Compounds |
| Companies Covered | Honeywell UOP, Albemarle Corp, Haldor Topsoe, Johnson Matthey, BASF, Clariant, Shell, Axens, WR Grace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sulfur Guard Catalyst Market Evolving Landscape
Guard catalyst architecture is shifting from static protection layers to intelligent, condition-responsive systems that optimize sulfur capture efficiency. Formulation science and reactor engineering are converging to extend service intervals while handling increasingly contaminated feedstock streams.
Layered bimetallic nickel-cobalt formulations on tailored alumina supports are supplanting single-metal zinc oxide guard beds in high-severity hydrotreating applications. US Gulf Coast refiners operating on heavy sour crudes are adopting these configurations to achieve sub-0.5 ppm sulfur breakthrough protection. The transition is compressing demand for conventional zinc oxide pellets while expanding the addressable market for precision-engineered metal oxide systems.
Europe's F-Gas Regulation is accelerating phase-out of fluorinated greenhouse gases used in certain catalyst activation and regeneration processes. German and Dutch chemical manufacturers are reformulating activation protocols to eliminate sulfur hexafluoride and perfluorinated compounds from zeolite preparation. The regulatory pressure is redirecting R&D investment toward aqueous and plasma-based activation methods that avoid fluorinated intermediates entirely.
Refinery procurement teams are consolidating catalyst supply relationships to reduce qualification overhead and secure volume commitments. Integrated operators with multiple hydrotreating units are negotiating multi-site framework agreements that bundle guard catalyst supply with technical service and spent catalyst reclamation. The consolidation is most visible among US independent refiners seeking to standardize specifications across geographically dispersed facilities while extracting scale pricing from formulation specialists.
Sulfur Guard Catalyst Market Segmentation
Sulfur guard catalyst procurement decisions cascade through reactor configuration, hydrotreating severity, and feedstock contamination profiles. Each segmentation dimension reveals distinct margin pools and technical barriers that reshape supplier-customer relationships.
Product Type:
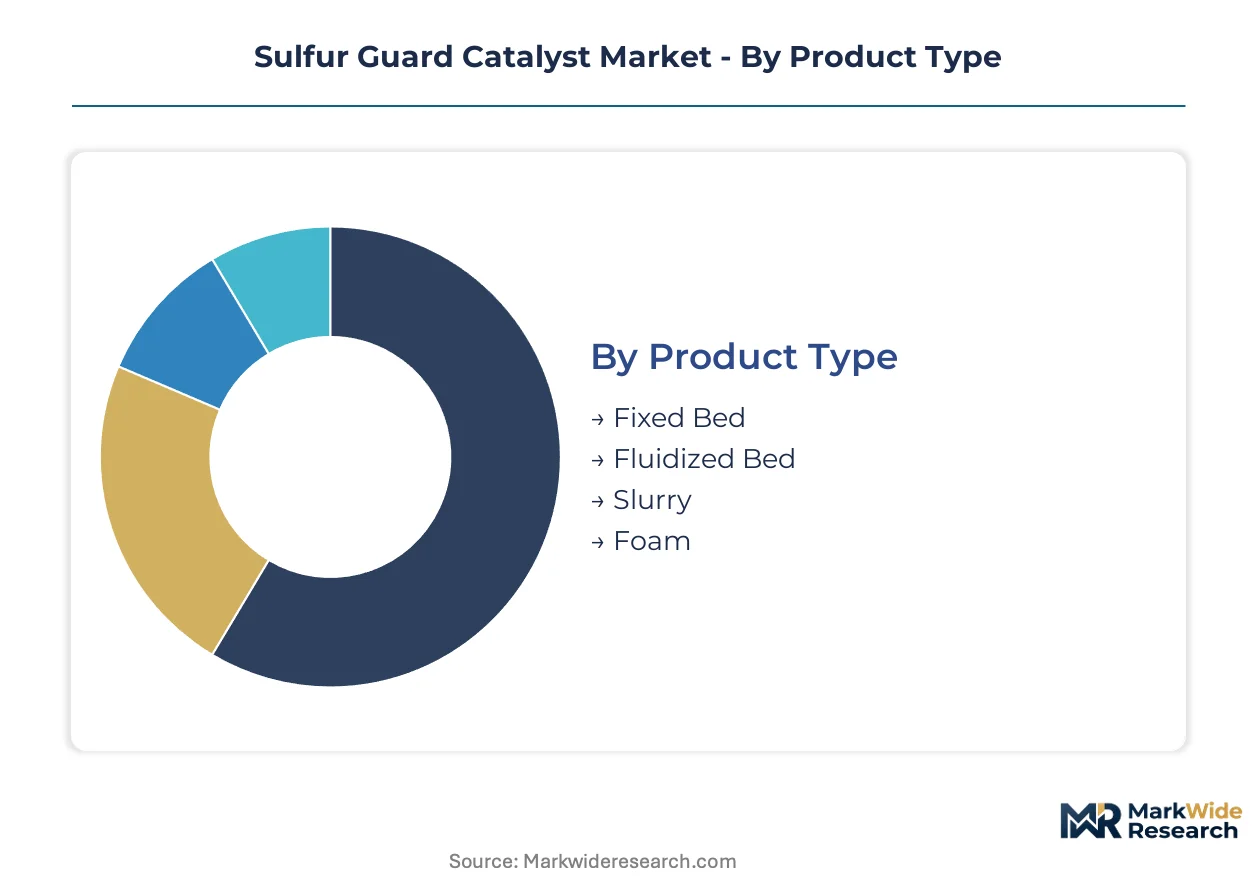
Fixed bed configurations command premium pricing in refinery retrofits where plot space constraints limit mechanical alternatives. Fluidized bed systems capture expanding margin pools in high-throughput gas processing where continuous regeneration justifies capital intensity.
- Fixed Bed:Pellet or extruded catalyst loaded into static reactors dominates installed refinery base across the United States Gulf Coast. Mechanical simplicity and predictable pressure drop profiles protect downstream reforming catalysts in FCC pretreatment units at Marathon Petroleum and Valero facilities.
- Fluidized Bed:Circulating catalyst systems enable continuous regeneration without unit shutdown, concentrating demand in Permian Basin gas processing plants handling high-sulfur associated gas. The configuration extends service intervals but requires specialized pneumatic conveying infrastructure.
- Slurry:Finely dispersed catalyst in liquid suspension serves niche ebullated-bed hydrocracking applications.
- Foam:Open-cell ceramic structures provide ultra-low pressure drop for high-space-velocity hydrogen production units.
The dominant share belongs to Fixed Bed, while Fluidized Bed is closing the gap fastest.
Application:
Volume concentrates in hydrotreating units where EPA Tier 3 gasoline sulfur standards mandate sub-10 ppm protection. Hydrocracking applications sustain premium pricing through severe operating conditions and catalyst replacement frequency.
- Hydrocracking:Severe hydrogenation environments at 200-400 bar pressure demand guard beds with exceptional mechanical stability and hydrogen sulfide capacity. Chevron's Pascagoula and ExxonMobil's Baytown complexes specify layered nickel-cobalt formulations for vacuum gas oil feedstocks.
- Hydrotreating:Naphtha and diesel hydrotreaters represent the volume anchor, with FCC feed pretreatment driving replacement cycles at US refineries adapting to Tier 3 mandates. German refineries in the Rhine-Ruhr cluster prioritize regenerable metal oxide systems for continuous reforming integration.
- Gas Processing:Acid gas removal units protect amine systems and sulfur recovery trains.
- Desulfurization:Tail gas and Claus unit guard applications complete sulfur recovery loops.
Hydrotreating maintains installed base leadership, though Hydrocracking exhibits the steepest expansion trajectory as refiners process heavier sour crudes.
End User:
Refinery procurement teams consolidate multi-site framework agreements, compressing supplier margins while securing technical service bundling. Petrochemical plants tolerate higher per-kilogram pricing for specialized synthesis gas protection.
- Refineries:Integrated operators with geographically dispersed hydrotreating units negotiate standardized specifications across FCC pretreatment, diesel hydrotreating, and naphtha reforming guard beds. Independent refiners seek volume pricing from formulation specialists while reducing qualification overhead.
- Petrochemical Plants:Steam methane reforming and partial oxidation units for ammonia and methanol synthesis demand ultra-low sulfur breakthrough protection. BASF's Ludwigshafen complex and LyondellBasell's Channelview facility specify zeolite-based guard systems for syngas applications.
- Chemical Manufacturers:Specialty chemical hydrogenation processes require contaminant-tolerant guard configurations.
- Power Plants:Integrated gasification combined cycle facilities protect turbine catalysts from fuel-bound sulfur.
Refineries retain the dominant procurement volume, while Petrochemical Plants are gaining share fastest on syngas capacity expansion.
Technology:
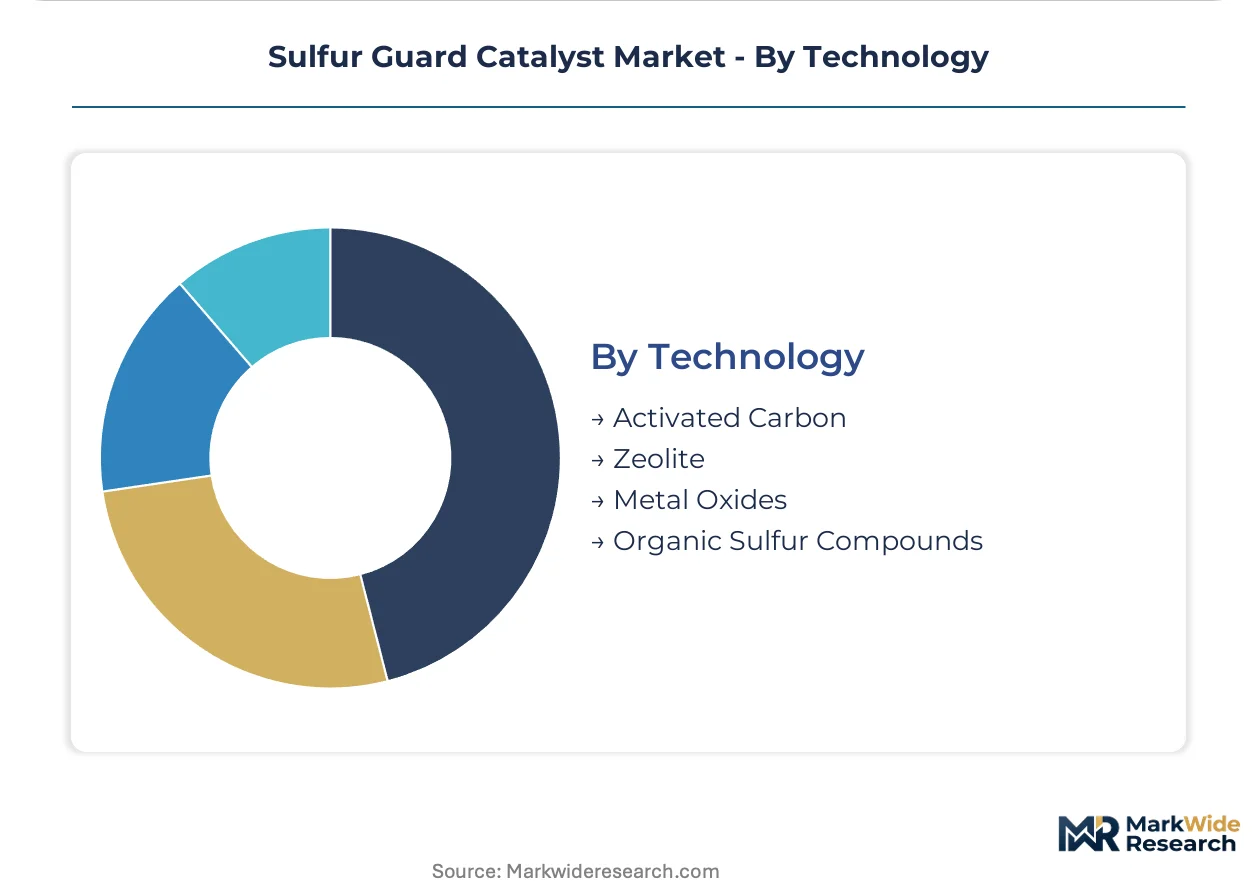
Metal oxide platforms anchor margin pools through regenerability and hydrogen sulfide capacity, while zeolite architectures command premium positioning in ultra-low sulfur synthesis gas applications.
- Metal Oxides:Zinc oxide and nickel-molybdenum formulations deliver superior hydrogen sulfide chemisorption capacity with thermal regenerability. US Gulf Coast refiners operating on heavy sour crudes adopt bimetallic configurations to achieve sub-0.5 ppm sulfur breakthrough protection.
- Zeolite:Ultra-stable Y-zeolite and specialized ZSM-5 architectures provide shape-selective sulfur compound rejection for synthesis gas and petrochemical feedstocks. German and Dutch manufacturers reformulate activation protocols to eliminate fluorinated compounds under F-Gas Regulation pressure.
- Activated Carbon:Lower-cost organic sulfur removal for trace contaminant polishing applications.
- Organic Sulfur Compounds:Niche positioning in mercaptan and thiophene-specific capture for product finishing.
Metal Oxides hold the dominant technology share, while Zeolite is climbing the fastest on syngas and hydrogen economy demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's Rhine-Ruhr chemical corridor, where specialized zeolite manufacturing commands premium positioning, while US Gulf Coast refiners leverage scale procurement to compress supplier margins on standardized metal oxide formulations.
United States
EPA Tier 3 gasoline sulfur standards mandate 10 ppm maximum sulfur content, accelerating guard catalyst replacement cycles at FCC pretreatment units. OSHA process safety mandates shape manufacturing site approvals and product registration requirements. The Gulf Coast refining corridor from Houston to Baton Rouge anchors procurement volume, with Marathon Petroleum and Valero facilities standardizing specifications across geographically dispersed hydrotreating units.
Germany
REACH compliance and the EU F-Gas Regulation are forcing reformulation of activation protocols to eliminate fluorinated compounds from zeolite preparation. The country's national chemicals regulator extends evaluation timelines for new metal oxide compositions, delaying commercial deployment. The Rhine-Ruhr cluster around Ludwigshafen and Leverkusen concentrates demand for ultra-low sulfur synthesis gas protection in ammonia and methanol production.
Netherlands
Sustainable aviation fuel blending requirements are creating demand for guard catalysts tolerant of oxygenated and olefinic feedstock contaminants. The EU Green Deal implementation pressures refiners to document catalyst carbon intensity. The Rotterdam-Antwerp port complex serves as Europe's largest refining hub, with integrated operators negotiating multi-site framework agreements that bundle supply with technical service.
China
The country's dual carbon goals and tightening sulfur specifications in refined product standards are expanding hydrotreating capacity. The national environmental regulator enforces emissions controls that indirectly shape catalyst performance benchmarks. The Yangtze River Delta petrochemical corridor around Shanghai and Ningbo concentrates new syngas capacity investment, driving zeolite-based guard system procurement.
Saudi Arabia
Sour crude processing expansion and stranded gas monetization projects are extending sulfur guard catalyst demand into high-severity hydrocracking applications. The national oil company maintains centralized procurement authority over catalyst specifications. The Eastern Province industrial zone around Jubail anchors refining and petrochemical integration, with new hydrogen production units specifying sub-0.5 ppm sulfur breakthrough protection.
Sulfur Guard Catalyst Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated chemical conglomerates commanding premium positioning through proprietary metal oxide platforms while regional manufacturers compete on volume pricing for standardized formulations. The vendor base clusters around three strategic tiers: formulation specialists with captive raw material integration, technology licensors with reactor-engineering bundling, and regional fabricators serving spot replacement demand. Consolidation pressure intensifies as refinery procurement teams reduce supplier qualification overhead through multi-site framework agreements.
Within the integrated technology tier, Albemarle Corp leverages its bromine and lithium expertise to sustain proprietary catalyst platforms, while Haldor Topsoe anchors its position through deep R&D investment in hydroprocessing technologies. Johnson Matthey occupies a position in advanced zeolite architectures for sulfur guard applications. These three exemplify the concentration of specialized catalyst engineering talent at legacy producers, constraining R&D throughput at emerging competitors.
| Leading Market Players |
|---|
| Honeywell UOP |
| Albemarle Corp |
| Haldor Topsoe |
| Johnson Matthey |
| BASF |
| Clariant |
| Shell |
| Axens |
| WR Grace |
| Others |
Value Network & Pricing Analysis
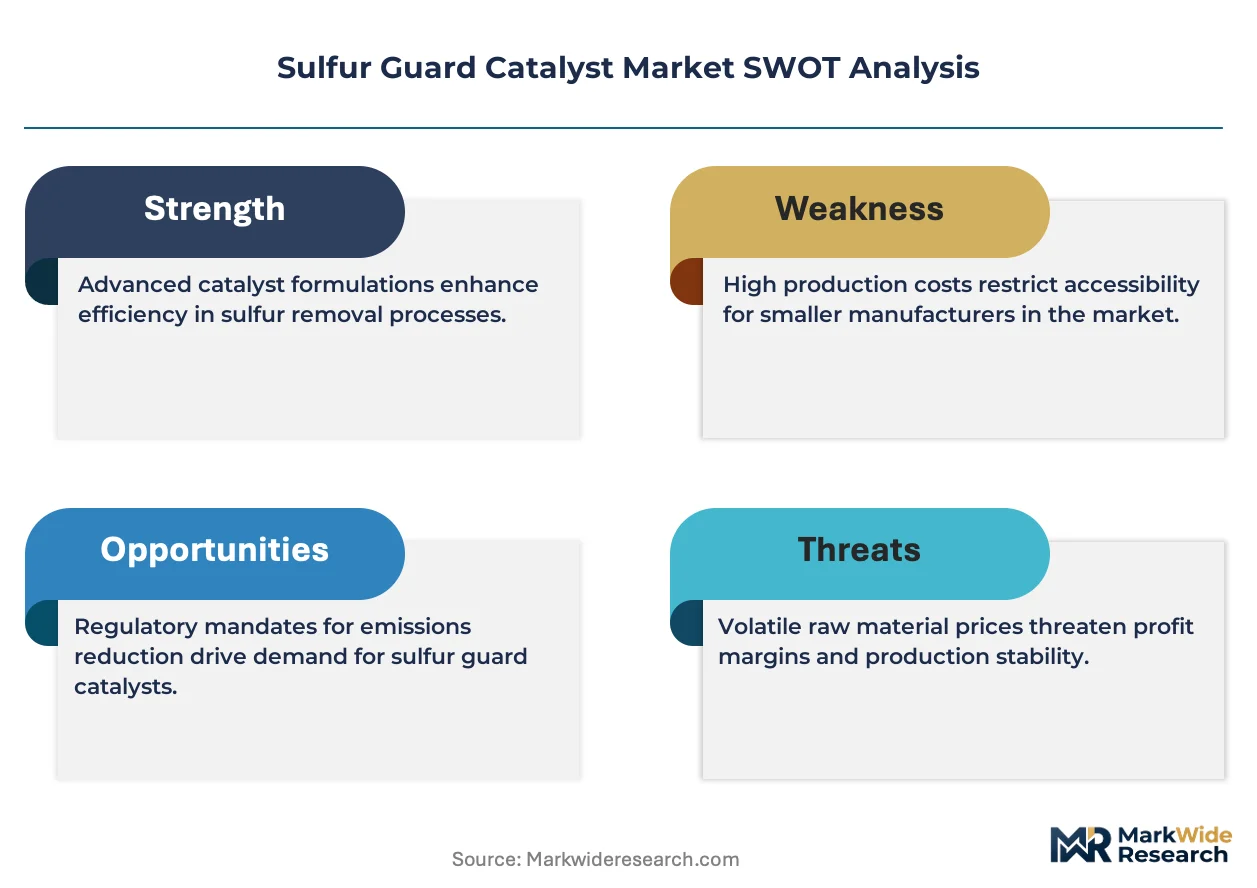
Bimetallic nickel-cobalt formulations displacing single-metal zinc oxide guard beds are redrawing procurement geography and compressing margin pools for legacy pellet suppliers while elevating premium positioning for precision-engineered metal oxide specialists. This substitution dynamic concentrates pricing power among integrated technology leaders with captive hydrothermal synthesis capacity, forcing mid-tier producers toward volume-contract erosion.
Pricing Analysis
The customization-premium spread separates configured-to-order layered metal oxide systems from standardized zinc oxide pellets across a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on hydrogen sulfide capacity certification and regeneration cycle guarantees, with US Gulf Coast refiners extracting volume discounts through multi-site framework agreements. Cost compression in the standard tier is intensifying because REACH registration delays extend supplier qualification timelines. Independent refiners exhibit highest price sensitivity, while petrochemical syngas applications tolerate premium positioning for sub-0.5 ppm breakthrough protection.
Supply Chain Analysis
Strategic stockpile preferences dominate catalyst procurement, with refiners maintaining 6-12 month inventory buffers against cobalt precursor volatility and zeolite manufacturing bottlenecks. Geographic supply concentration centers on the United States, Germany, and China, with hydrothermal synthesis capacity for ultra-stable Y-zeolite substrates drawing from integrated chemical conglomerates. Raw material dependencies rest on cobalt concentrates from the Democratic Republic of Congo, specialty alumina from Australia, and rare earth promoters from China. Single-source vulnerability in cobalt mining exposes formulators to ethical sourcing scrutiny and price spikes. Distribution runs through direct technical service relationships rather than distributor networks, with spent catalyst reclamation bundled into supply contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sulfur guard catalyst market sits at a regulatory-inflection disruption, with EPA Tier 3 mandates and Europe's F-Gas Regulation compressing replacement cycles and forcing activation protocol reformulation. This technological shift favors suppliers with integrated R&D infrastructure and captive raw material security.
For Market Incumbents: Compound technology leadership through backward integration into specialty alumina and zeolite precursor production, locking out mid-tier competitors from formulation flexibility. Deepen R&D investment in aqueous activation methods that eliminate fluorinated compounds, anticipating F-Gas Regulation enforcement timelines. Secure multi-site framework agreements with US independent refiners before qualification overhead consolidation completes.
For New Entrants and Emerging Players: Anchor in modular skid-mounted guard bed systems for small-scale hydrogen production, a segment underserved by field-erected configurations from legacy suppliers. Target biofuel co-processing applications in the Netherlands and Germany, where oxygenated feedstock tolerance creates specification gaps. Pursue partnership licensing with regional EPC contractors to bypass direct refinery qualification barriers.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated technology leaders with captive manufacturing and regenerable formulation portfolios. Long-term viability over the next decade rests on exposure to syngas and hydrogen economy demand rather than pure refinery cyclicality. Target acquisition archetype: mid-tier metal oxide specialists with proven regeneration technology but limited geographic footprint. The signal to watch is carbon border adjustment mechanism implementation timelines, which will revalue low-emission manufacturing process documentation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Alumina | Captive precursor supply secures formulation flexibility against zeolite manufacturing bottlenecks. |
| Green Activation Protocol Development | Aqueous and plasma-based methods eliminate sulfur hexafluoride under F-Gas Regulation pressure. |
| Multi-Site Framework Agreement Expansion | Standardized specifications across Marathon Petroleum and Valero facilities extract volume pricing power. |
| Modular Skid-Mounted System Launch | Compact pre-engineered units penetrate small-scale hydrogen production previously served by field-erected configurations. |
| Spent Catalyst Reclamation Partnership | Technical service bundling with supply contracts locks in refinery procurement consolidation trends. |
Research Methodology
The analysis maps metal oxide platforms, zeolite architectures, and activated carbon substrates, each validated through technical directors at catalyst formulation houses, refinery procurement leads, and petrochemical syngas engineers. Primary interviews with plant managers at US Gulf Coast facilities, R&D directors at integrated chemical conglomerates, and EPC contractors specializing in hydroprocessing units combined with secondary validation from SEC 10-K filings, customs trade data, and EPA compliance disclosures. Bottom-up capacity estimates and top-down demand projections triangulate volume and value outputs.
Consistency checks against external benchmarks validated modeled outputs across the projection horizon, with segmentation dimensions including reactor configuration, hydrotreating severity, feedstock contamination profile, and end-use industry. CAGRs derived from replacement cycle frequency analysis, regulatory deadline compression effects, and capacity expansion announcements. Industry-specific forecast inputs encompass cobalt price volatility indices and REACH registration pipeline status.
Material uncertainties — cobalt supply disruption, F-Gas Regulation enforcement variance, and biofuel mandate acceleration — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory timeline adherence and substitution elasticity between metal oxide technologies. Revision becomes warranted when carbon border adjustment mechanism coverage expansion crosses thresholds that revalue manufacturing process documentation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Fuel Cell Catalyst Market
Catalysts
Refining Catalysts Market
Catalysts
Middle-East and Africa Refining Catalysts Market
Catalysts
Biodiesel Catalyst Market
Catalysts
Platinum-Based Catalysts Market
Catalysts
Europe Homogeneous Precious Metal Catalyst Market
Catalysts
Phosphorus Based Catalyst Market
Catalysts
South America Refining Catalysts Market
Catalysts
Global FCC Catalyst Market
Catalysts
Asia and Middle East Polyolefin Catalyst Market
Catalysts
North America Refining Catalysts Market
Catalysts
Industrial Catalyst Market
Catalysts
Solid Acid Catalysts Market
Catalysts
Stationary Emission Control Catalyst Market
Catalysts
Heavy Oil Cracking Catalyst Market
Catalysts
North America Zeolite Market