
 Sulfur Recovery Technology Market | 2026-2036
Sulfur Recovery Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Sulfur Recovery Technology Market Analytics
Ceramic catalyst substrates are shifting toward advanced alumina-titania composites in Claus reactor beds, cutting replacement cycles and improving H2S conversion efficiency. Shell plc leverages its proprietary SCOT tail gas treatment technology to anchor premium positioning across Middle Eastern refinery contracts. Jacobs Engineering Group sustains engineering procurement dominance through integrated sulfur block designs that combine Claus, SCOT, and amine regeneration. Linde plc differentiates via cryogenic carbon capture tie-ins that lower sulfur plant carbon intensity.
Sulfur recovery technology encompasses thermal, catalytic, and biological processes that extract elemental sulfur from hydrogen sulfide-bearing acid gas streams, typically operating at reaction temperatures between 200°C and 1,200°C depending on process stage. Claus process units remain the structural backbone, commanding the majority of installed base revenue as operators extend asset life through catalyst upgrades rather than greenfield builds. Tail gas treatment is displacing conventional incineration in new project specifications as environmental permits tighten on SO2 stack limits. Modular systems are gaining share among mid-scale natural gas processors seeking faster commissioning timelines in remote basins.
EPA sulfur dioxide standards under the Clean Air Act and EU F-Gas Regulation compliance timelines are forcing refinery operators to retrofit existing trains or face operating permit restrictions. OSHA process safety management requirements and ISO 14001 environmental management certifications shape contractor qualification criteria for major sulfur recovery engineering contracts. Stakeholders must evaluate catalyst supply security and regional engineering capacity before committing to multi-year Claus expansion schedules.
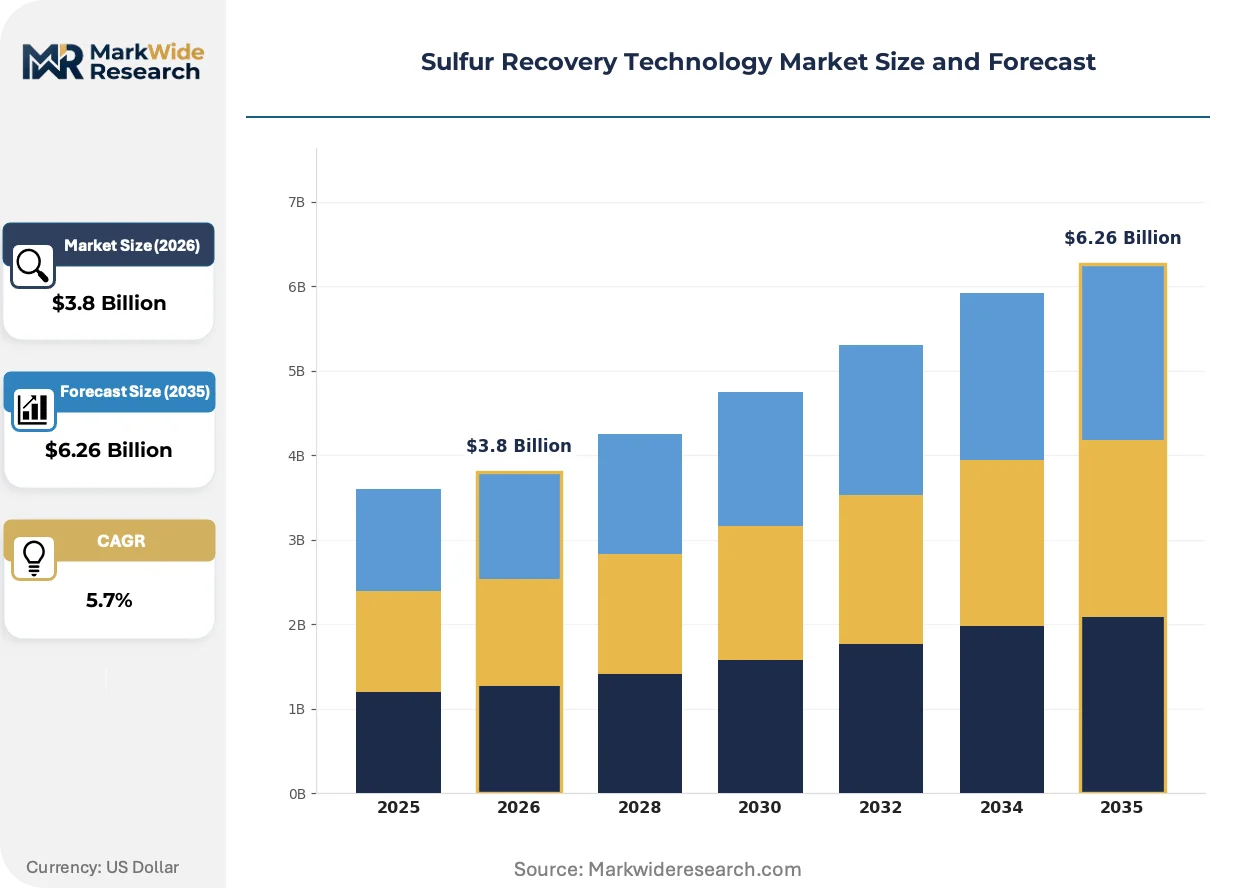
Market Dynamics
Refinery operators face mounting pressure to retrofit aging Claus sulfur recovery trains as EPA sulfur dioxide limits tighten under Clean Air Act amendments, forcing capital allocation toward tail gas treatment upgrades rather than incremental catalyst replacements.
Growth Catalysts
- Shale gas processing expansion:United States midstream operators are commissioning large-scale sulfur recovery blocks at Permian and Appalachian basin gathering facilities to handle rising hydrogen sulfide concentrations in associated gas.
- F-Gas Regulation compliance:European Union refineries must eliminate vented sulfur compounds by statutory deadlines, accelerating tail gas treatment unit installations across Rotterdam and Antwerp refining clusters.
- Alumina-titania catalyst substrates:Advanced ceramic composites are extending Claus reactor bed cycles from three to five years, reducing turnaround frequency and maintenance labor requirements.
Market Restraints
- Specialty catalyst supply concentration:Production of high-activity Claus catalysts concentrates among three European and Japanese chemical manufacturers, creating procurement vulnerability for North American operators.
- Molybdenum and cobalt price volatility:Hydrogenation catalyst costs swing with mining output from Chile and the Democratic Republic of Congo, compressing project returns on fixed-price engineering contracts.
- Sub-99% sulfur recovery ceiling:Conventional Claus trains cannot economically achieve the 99.9% recovery rates now required for new environmental permits without costly tail gas treatment add-ons.
Strategic Opportunities
- Biological sulfur recovery:Bio-oxidation processes using Thiobacillus bacteria are opening mid-scale natural gas treatment in remote basins where thermal Claus units prove uneconomical.
- India refining capacity additions:Reliance Industries and Indian Oil Corporation are expanding Jamnagar and Paradip complexes, creating demand for integrated sulfur block engineering and catalyst supply.
- Cryogenic carbon capture convergence:Linde and Air Products are bundling CO2 liquefaction with sulfur recovery units to position refinery projects for low-carbon hydrogen production incentives.
Industry Challenges
- Sulfur block process integration:Engineering contractors struggle to synchronize Claus, SCOT tail gas treatment, and amine regeneration commissioning schedules, delaying refinery restart timelines.
- OSHA PSM compliance documentation:Refinery operators must maintain exhaustive process safety management records for sulfur recovery train modifications, extending permit approval cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sulfur Recovery Technology Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Claus Process, Tail Gas Treatment, Thio-Cat Process, Biotechnological Methods End User: Refineries, Petrochemical Plants, Natural Gas Processing, Chemical Manufacturers Application: Hydrocarbon Processing, Sulfur Production, Waste Treatment, Air Pollution Control Capacity: Small Scale, Medium Scale, Large Scale, Modular Systems |
| Companies Covered | Shell plc, Jacobs Engineering Group, Fluor Corporation, Bechtel Corporation, Linde plc, WorleyParsons Limited, Chiyoda Corporation, Honeywell International, Technip Energies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sulfur Recovery Technology Market Evolving Landscape
Process intensification and digital monitoring systems are compressing sulfur recovery plant footprints while tightening emissions performance, reshaping how engineering contractors bid integrated Claus-SCOT packages.
Alumina-titania composite catalyst substrates are absorbing higher thermal stress in sub-dewpoint Claus reactor operations, enabling superclaus process variants that push conversion efficiency past conventional limits. United States Gulf Coast refiners are retrofitting first-generation trains with these materials during 2025-2027 turnaround windows. The technology is absorbing market share from traditional activated alumina formulations by eliminating the sulfur condensation that previously poisoned catalyst beds.
EPA's revised National Ambient Air Quality Standards for sulfur dioxide are compelling operators to install continuous emissions monitoring systems and redundant tail gas treatment capacity. Refineries in the Houston Ship Channel and Philadelphia corridor face the steepest compliance timelines. The regulation is forcing project specifications toward 99.9% recovery guarantees rather than the 99.5% thresholds that dominated prior contracting cycles.
After-sales service contracts are unbundling from original equipment supply, with refineries now procuring catalyst changeout, reactor inspection, and performance guarantees through separate competitive tenders. This procurement fragmentation favors specialized catalyst suppliers over integrated engineering houses. The shift is most pronounced among independent United States refiners lacking captive technical services divisions.
Sulfur Recovery Technology Market Segmentation
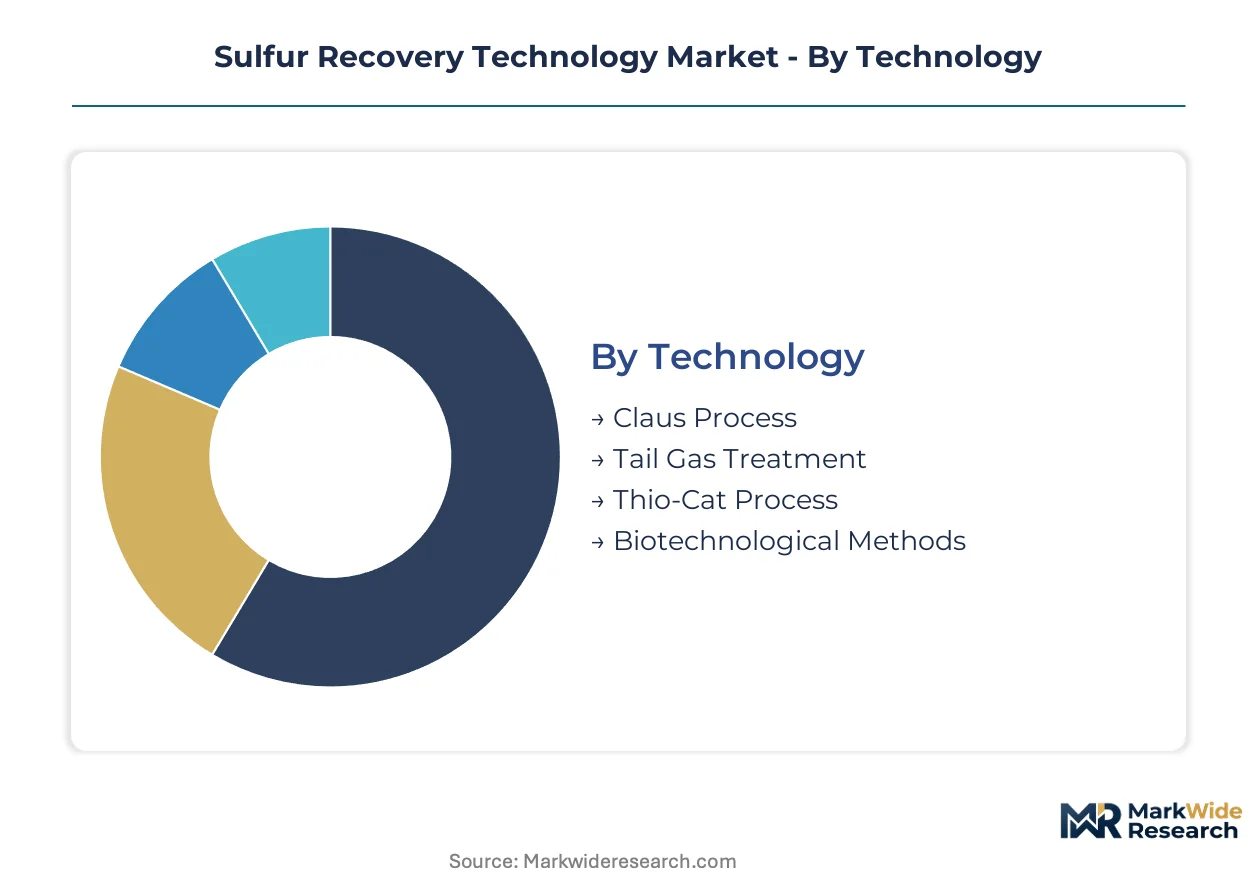
Sulfur recovery technology segments diverge sharply by capital intensity and emissions stringency. Refinery operators weight technology choices against permit compliance timelines, while gas processors prioritize modular deployment speed in remote basins.
Technology:
Claus process variants dominate installed base revenue, while tail gas treatment commands premium pricing per ton of sulfur recovered.
- Claus Process:Thermal and catalytic stages operate between 200°C and 1,200°C to convert hydrogen sulfide into elemental sulfur via partial oxidation. Refineries across the United States Gulf Coast extend asset life through alumina-titania catalyst upgrades rather than greenfield construction.
- Tail Gas Treatment:SCOT and Beavon-Stretford variants capture residual sulfur compounds from Claus exhaust, pushing total recovery toward 99.9% thresholds demanded by EPA National Ambient Air Quality Standards. European Union F-Gas Regulation compliance deadlines accelerate adoption across Rotterdam and Antwerp refining clusters.
- Thio-Cat Process:Liquid redox systems using chelated iron catalysts handle low-pressure acid gas streams where conventional thermal routes prove uneconomical.
- Biotechnological Methods:Thiobacillus-based bio-oxidation opens mid-scale natural gas treatment in remote Permian and Appalachian basins lacking pipeline infrastructure.
Today's leader: Claus Process. Tomorrow's challenger: Tail Gas Treatment.
End User:
Refinery capital deployment concentrates on tail gas retrofit cycles, while gas processing builds new capacity around shale basin expansion.
- Refineries:Complex integrated sites require synchronized Claus, SCOT, and amine regeneration commissioning. OSHA process safety management documentation extends permit approval timelines for modifications at Houston Ship Channel and Philadelphia corridor facilities.
- Natural Gas Processing:Midstream operators commission large-scale sulfur recovery blocks at Permian and Appalachian gathering facilities to handle rising hydrogen sulfide concentrations in associated shale gas. Modular specifications prioritize faster commissioning over maximum conversion efficiency.
- Petrochemical Plants:Steam cracker and aromatics complexes generate acid gas streams requiring dedicated recovery trains integrated with hydrogen production units.
- Chemical Manufacturers:Carbon disulfide and specialty sulfur compound producers operate smaller captive recovery systems with batch operational profiles.
Refineries anchor current procurement volumes. Natural gas processing offers the steepest expansion trajectory.
Application:
Hydrocarbon processing generates the acid gas feedstock volumes that justify thermal process economics, while air pollution control drives tail gas treatment specifications.
- Hydrocarbon Processing:Crude oil distillation and conversion units produce concentrated hydrogen sulfide streams requiring immediate treatment to prevent refinery fuel gas contamination.
- Air Pollution Control:Continuous emissions monitoring systems and redundant tail gas treatment capacity respond to EPA sulfur dioxide standard enforcement.
- Sulfur Production:Elemental sulfur recovery as a marketable byproduct supports project economics at high-sulfur crude processing facilities.
- Waste Treatment:Spent acid and sour water stripper gas handling requires specialized recovery configurations outside standard Claus designs.
Hydrocarbon processing commands equipment scale. Air pollution control dictates technology selection.
Capacity:
Large-scale integrated blocks dominate refinery capital spending, while modular systems capture share among independent gas processors.
- Large Scale:Integrated sulfur blocks exceeding 500 tons per day capacity combine multiple Claus trains with common tail gas treatment and sulfur forming facilities. Reliance Industries and Indian Oil Corporation specify these configurations for Jamnagar and Paradip complex expansions.
- Modular Systems:Skid-mounted Claus and tail gas packages compress commissioning timelines to 12-18 months versus 36 months for stick-built alternatives. Remote basin natural gas processors favor these for faster revenue realization.
- Medium Scale:Standalone Claus trains serving single-train refineries or large chemical complexes balance capital efficiency against operational flexibility.
- Small Scale:Biological and liquid redox systems handle sub-50 ton per day acid gas volumes where thermal economics fail.
Large scale captures value concentration. Modular systems gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Houston Ship Channel anchors sulfur recovery technology deployment, hosting the densest concentration of Claus unit retrofits and tail gas treatment installations worldwide.
United States
Permian and Appalachian basin shale gas processing drives large-scale sulfur recovery block commissioning at midstream gathering facilities. EPA National Ambient Air Quality Standards enforcement compels Houston Ship Channel and Philadelphia corridor refineries to install redundant tail gas treatment capacity. Gulf Coast operators prioritize alumina-titania catalyst upgrades during 2025-2027 turnaround windows.
Saudi Arabia
Reliance on high-sulfur crude processing sustains demand for integrated sulfur block engineering at coastal refining complexes. The country's national environmental regulator mandates continuous emissions monitoring systems for all sulfur recovery trains. Jubail Industrial City hosts concentrated Claus-SCOT unit construction tied to petrochemical expansion.
India
Jamnagar and Paradip refinery complex expansions by Reliance Industries and Indian Oil Corporation create procurement demand for catalyst supply and engineering services. Central Electricity Authority guidelines shape sulfur handling specifications at integrated refining-power facilities. Gujarat's coastal refining belt concentrates capital deployment into large-scale sulfur forming facilities.
Germany
EU F-Gas Regulation compliance deadlines accelerate tail gas treatment unit adoption across Rhine-Ruhr refining clusters. REACH chemical safety protocols govern catalyst procurement specifications for Claus reactor modifications. Antwerp-Rotterdam-Rhine corridor operators face the steepest retrofit timelines for sub-99% recovery train replacements.
China
Dual carbon goals and MEE emissions standards push Sinopec and PetroChina toward cryogenic carbon capture bundling with sulfur recovery units. Shandong Province refining capacity expansions concentrate demand for modular Claus packages with faster commissioning profiles. Yangtze River Delta petrochemical complexes integrate sulfur blocks with hydrogen production facilities.
Sulfur Recovery Technology Market Competitive Landscape
Technology licensing dominates the current landscape, with engineering contractors leveraging proprietary process designs to secure multi-year refinery service agreements. The vendor base organizes around three archetypes: integrated engineering houses with captive catalyst supply, specialized catalyst manufacturers with aftermarket service networks, and industrial gas specialists bundling carbon capture with sulfur recovery. Strategic partnerships and geographic expansion represent the dominant competitive vectors, as regional engineering capacity constraints limit greenfield project execution speed.
Among Anglo-Dutch integrated majors, Shell plc exemplifies the technology-licensing archetype through proprietary SCOT tail gas treatment positioning. Jacobs Engineering Group and Linde plc occupy differentiated positions within the engineering-procurement tier, with the former representing integrated sulfur block design capability and the latter anchoring cryogenic carbon capture convergence strategies. These three entities collectively illustrate how competitive positioning fragments across process technology ownership, project execution scale, and adjacent decarbonization service bundling.
| Leading Market Players |
|---|
| Shell plc |
| Jacobs Engineering Group |
| Fluor Corporation |
| Bechtel Corporation |
| Linde plc |
| WorleyParsons Limited |
| Chiyoda Corporation |
| Honeywell International |
| Technip Energies |
| Others |
Value Network & Pricing Analysis
Molybdenum and cobalt feedstock costs cascade through hydrogenation catalyst pricing tiers, with volatility in Chilean and Congolese mining output compressing margins on fixed-price engineering contracts and forcing buyers toward indexed procurement structures.
Pricing Analysis
Input-cost pass-through dominates sulfur recovery technology pricing, with alumina-titania composite substrates commanding premium positioning against standard activated alumina formulations. Price differentiation hinges on catalyst activity guarantees and bundled after-sales service contracts, with integrated engineering houses capturing margin from performance-based guarantees while specialized suppliers compete on unit economics. Pricing pressure intensifies in the Claus catalyst tier as European and Japanese manufacturers consolidate production, squeezing independent United States refiners lacking volume leverage. Natural gas processors exhibit highest price sensitivity due to modular procurement patterns, while coastal refineries facing EPA compliance deadlines absorb cost premiums for guaranteed recovery rates.
Supply Chain Analysis
Single-source vulnerability sits with European and Japanese specialty catalyst manufacturers, concentrating high-activity Claus catalyst production among three dominant suppliers and creating procurement bottlenecks for North American operators. Geographic supply concentration centers on Germany, Japan, and the Netherlands for advanced ceramic substrates, with hydrogenation catalyst precursors drawing from Chilean molybdenum and Congolese cobalt extraction. Supply chain risk manifests in commodity price volatility transmitted through long-lead catalyst orders. Distribution runs through engineering-procurement-construction contractors who bundle catalyst supply with installation services, though procurement fragmentation is unbundling after-sales contracts from original equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sulfur recovery technology offers margin expansion through alumina-titania catalyst upgrade cycles and tail gas treatment premiumization, with environmental compliance deadlines forcing buyer acceptance of higher-performance pricing tiers.
For Market Incumbents: Anticipate biological sulfur recovery and cryogenic carbon capture convergence as substitute threats, and respond through backward integration into catalyst substrate manufacturing and SCOT technology licensing depth. Secure capacity reservations with Chilean and Congolese mining consortiums to hedge hydrogenation catalyst cost volatility. Prioritize EPA compliance documentation services as a recurring revenue anchor independent of equipment sales cycles. For New Entrants and Emerging Players: Midstream operators in remote shale basins represent the most penetrable buyer segment, with biological Thiobacillus-based systems opening white-space below thermal Claus unit economics. Target modular deployment contracts in the Permian and Appalachian regions where faster commissioning timelines override maximum conversion efficiency specifications. Partner with regional engineering-procurement firms lacking captive catalyst supply to access refinery retrofit procurement channels. For Investors and Strategic Acquirers: Consolidation pressure builds where specialized catalyst manufacturers face margin compression from raw material volatility yet retain irreplaceable formulation expertise. Frame long-term viability around environmental regulation stringency as a structural demand driver with limited technology substitution risk. Acquisition targets should display captive catalyst technology or integrated sulfur block engineering capability. Watch EPA National Ambient Air Quality Standards enforcement intensity as the signal for retrofit demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Catalyst Substrate Backward Integration | In-house alumina-titania production secures margin capture from European supply concentration. |
| SCOT Technology Licensing Expansion | Proprietary tail gas treatment positioning anchors premium contracting across Middle Eastern refinery clusters. |
| Cryogenic Carbon Capture Bundling | Linde-style CO2 liquefaction integration positions projects for low-carbon hydrogen production incentives. |
| Biological Process R&D Investment | Thiobacillus-based systems open mid-scale natural gas treatment in infrastructure-constrained basins. |
| After-Sales Service Unbundling | Separate competitive tenders for catalyst changeout and performance guarantees fragment procurement toward specialists. |
Research Methodology
Multiple input streams — primary interviews with refinery operations directors, catalyst procurement managers, and EPC project developers; secondary validation through EPA enforcement databases, EU F-Gas Regulation compliance filings, and SEC 10-K disclosures from integrated engineering houses; plus customs data on alumina-titania substrate trade flows — were reconciled through bottom-up and top-down triangulation to establish market sizing and growth trajectory parameters.
Historical capacity installation patterns were cross-referenced against panel input from sulfur block engineering specialists to construct the analytical framework across the projection horizon. Segmentation dimensions modeled include technology type, end-user industry, capacity tier, and regional regulatory cluster. CAGRs were derived from fitted trend analysis incorporating shale gas processing expansion rates, refinery turnaround schedules, and environmental permit issuance timelines as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to molybdenum-cobalt price volatility, EPA enforcement intensity variations, and biological process technology maturation. Forecasts reflect documented assumptions regarding regulatory compliance deadlines and catalyst replacement cycle extensions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Drag Reducing Agents Market
Industrial Chemicals
Europe Surface Treatment Chemicals Market
Industrial Chemicals
HFO (Hydrofluoro-Olefin) Refrigerants Market
Industrial Chemicals
Global Antifreeze Market
Industrial Chemicals
Global Activated Carbon Canisters Market
Industrial Chemicals
Chrome Plating Market
Industrial Chemicals
Industrial Grade Urea Market
Industrial Chemicals
Permeate Market
Industrial Chemicals
Enzymes for Laundry Detergent Market
Industrial Chemicals
Global Desalting and Buffer Exchange Market
Industrial Chemicals
Deoiler Chemicals Market
Industrial Chemicals
Sulfolane Market
Industrial Chemicals
Global Odor Control Systems Market
Industrial Chemicals
Dimethylacetamide (Dmac) Market
Industrial Chemicals
Lime Manufacturing Market
Industrial Chemicals
CDU Heat Exchanger Antifoulants Market