
 Fuel Cell Catalyst Market | 2026-2036
Fuel Cell Catalyst Market Size, Share, and Industry Trends Forecast 2026-2036
Fuel Cell Catalyst Market Intelligence
Platinum-group metal substitution research is fragmenting the technology stack across low-Pt alloy formulations and single-atom catalysis architectures. Johnson Matthey anchors European supply through its Royston manufacturing complex and membrane electrode assembly integration. Umicore competes via closed-loop precious metal recycling that recovers platinum from spent automotive catalysts. BASF differentiates through high-throughput materials screening that accelerates non-platinum metal discovery timelines.
A fuel cell catalyst accelerates the electrochemical oxidation of hydrogen and reduction of oxygen at the anode and cathode, typically comprising platinum nanoparticles dispersed on high-surface-area carbon black supports with loadings historically ranging from 0.2 to 0.4 mg Pt per square centimeter. Its primary commercial purpose is to minimize activation overpotential losses while maximizing current density output in proton exchange membrane systems. Platinum-based formulations still dominate installed capacity, though alloy catalysts incorporating cobalt or nickel represent the fastest-expanding research frontier as automakers target 80% platinum reduction. Carbon-supported architectures sustain the broadest manufacturing base, while composite catalysts merging metal-organic frameworks with conductive polymers concentrate emerging patent filings.
The EPA's Clean Trucks Plan and California Air Resources Board's Advanced Clean Trucks regulation mandate zero-emission powertrains for medium and heavy-duty segments, directly expanding membrane electrode assembly procurement. REACH authorization requirements for cobalt compounds and the EU's F-Gas Regulation on fluorinated membrane materials reshape raw material access and catalyst binder selection across European manufacturing. China's MIIT dual carbon targets and South Korea's K-NEPA hydrogen certification impose parallel domestic content and carbon intensity standards. Stakeholders must monitor how platinum price volatility intersects with national critical minerals stockpiling strategies to determine catalyst formulation commitments and geographic sourcing footprints.
Market Dynamics
Platinum loadings in proton exchange membrane stacks face mounting compression as heavy-duty fleet operators demand total cost parity with diesel powertrains, forcing catalyst suppliers to re-engineer active site architectures without sacrificing durability under transient load cycles.
Growth Catalysts
- Advanced Clean Trucks:California Air Resources Board mandates zero-emission powertrains for Class 8 tractors, expanding membrane electrode assembly procurement across long-haul logistics operators.
- Hydrogen banking provisions:EU Green Deal mechanisms de-risk capital deployment for electrolyzer-integrated refueling stations, pulling catalyst demand into Germany's Ruhr industrial cluster.
- Single-atom architectures:Research programs at Japan's METI accelerate non-precious metal active site validation, narrowing the performance gap with platinum benchmarks.
Market Restraints
- Platinum price volatility:South African supply concentration and speculative trading in London Metal Exchange contracts create input cost instability for catalyst formulators.
- REACH authorization friction:ECHA's cobalt compound restrictions complicate low-Pt alloy formulations and force binder chemistry revisions across European manufacturing.
- Fluorinated membrane scarcity:EU F-Gas Regulation phase-down limits perfluorinated sulfonic acid ionomer availability, constraining membrane-catalyst interface engineering.
Strategic Opportunities
- Ulsan petrochemical corridor:South Korea's K-NEPA hydrogen certification creates captive demand for high-purity catalysts in integrated refinery-to-fuel-cell value chains.
- Closed-loop recycling infrastructure:Spent automotive catalyst recovery networks unlock secondary platinum supply streams, reducing virgin metal dependency for electrode manufacturers.
- Metal-organic framework convergence:Hybrid architectures combining conductive polymers with porous coordination polymers open patent white space in next-generation cathode formulations.
Industry Challenges
- Electrochemist talent scarcity:Specialized expertise in rotating disk electrode diagnostics and fuel cell stack integration commands premium compensation, constraining R&D team scaling.
- MEA certification timelines:DOE durability protocols and OEM-specific accelerated stress tests extend qualification cycles, delaying revenue recognition for new catalyst formulations.
- Carbon support supply reconfiguration:Transition from petroleum-derived to biomass-sourced high-surface-area carriers requires furnace process revalidation and particle size distribution re-optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fuel Cell Catalyst Market |
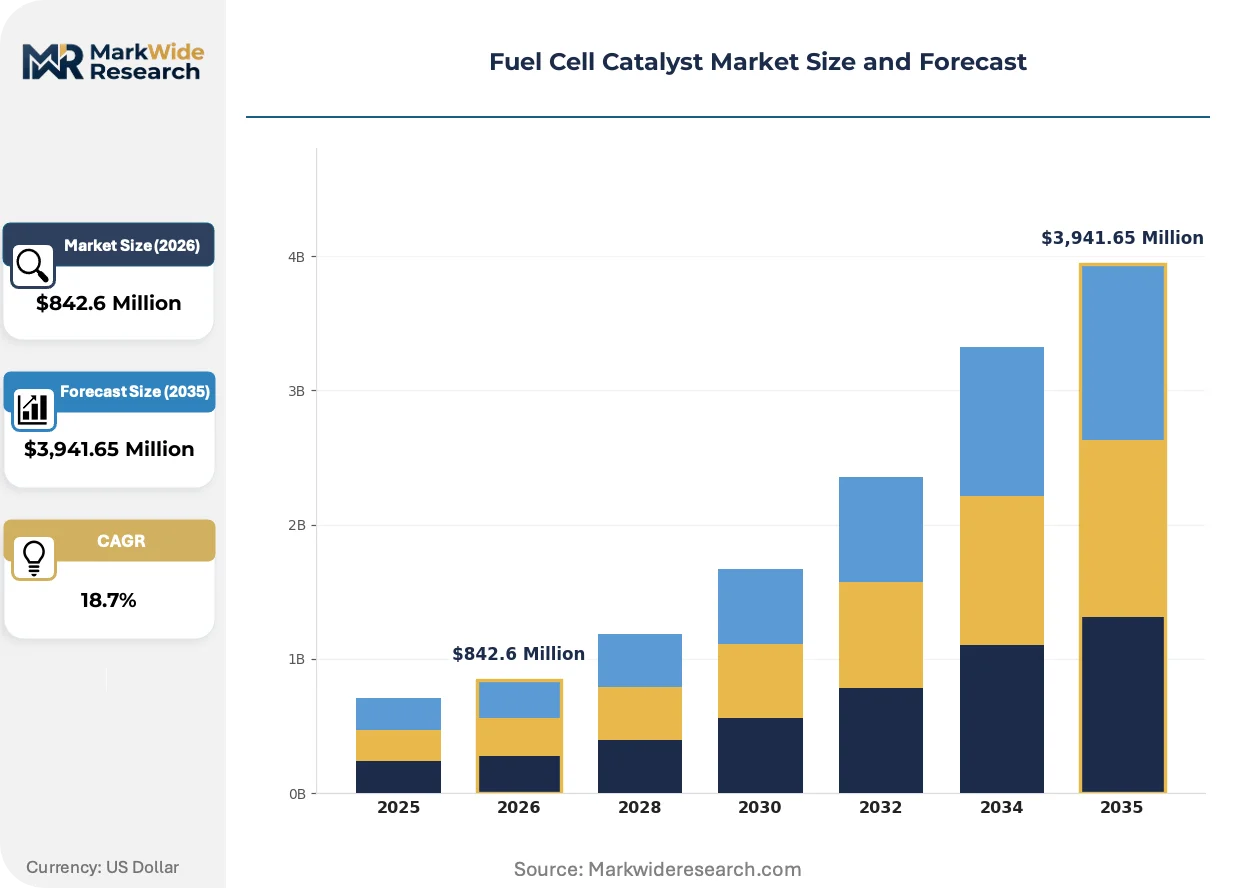
| Market Size in 2026 | $842.6 Million |
| Market Size in 2035 | $3,941.65 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Platinum-Based, Non-Platinum Metal, Carbon-Supported, Composite Catalysts, Alloy Catalysts Technology: Polymer Electrolyte Membrane, Alkaline, Phosphoric Acid, Solid Oxide, Direct Methanol Application: Residential Power, Portable Electronics, Commercial Vehicles, Stationary Power, Aerospace End User: Power Suppliers, Vehicle Manufacturers, Electronic Device Makers, Aerospace Engineers, Industrial Integrators |
| Companies Covered | Umicore, Johnson Matthey, 3M, Heraeus, Haldor Topsoe, Tanaka Holdings Co., Ltd., De Nora, BASF, Clariant, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fuel Cell Catalyst Market Strategic Shifts & Innovations
Catalyst innovation is compressing traditional platinum dependency through atomic-scale engineering and manufacturing process intensification. Formulation strategies now prioritize durability under start-stop cycling over peak power density. Supply chain actors are repositioning around closed-loop metal recovery and regionalized membrane electrode assembly production.
Single-atom catalysis is migrating from academic demonstration to pilot-scale electrode manufacturing. Toyota and Hyundai heavy-duty divisions are qualifying iron-nitrogen coordinated active sites for 2027 platform launches. This technology is migrating from platinum-group metal benchmarks toward 90% cost reduction targets while maintaining oxygen reduction reaction kinetics within 50 millivolts of conventional loadings.
REACH authorization requirements for cobalt compounds are forcing binder and alloy composition pivots across European catalyst suppliers. ECHA's sunset date pressures are accelerating nickel-manganese substitution research and fluorine-free ionomer development. German membrane electrode assembly integrators are responding by qualifying Asian-sourced cobalt-free cathode formulations ahead of 2026 authorization deadlines.
Fleet procurement teams are consolidating membrane electrode assembly sourcing under decade-long hydrogen supply agreements rather than component spot purchasing. California zero-emission freight corridor operators now bundle catalyst replacement schedules into vehicle lease structures, transferring technical risk to system integrators. This model concentrates procurement leverage with Nikola and Daimler Truck North America fleet service divisions.
Fuel Cell Catalyst Market Segmentation
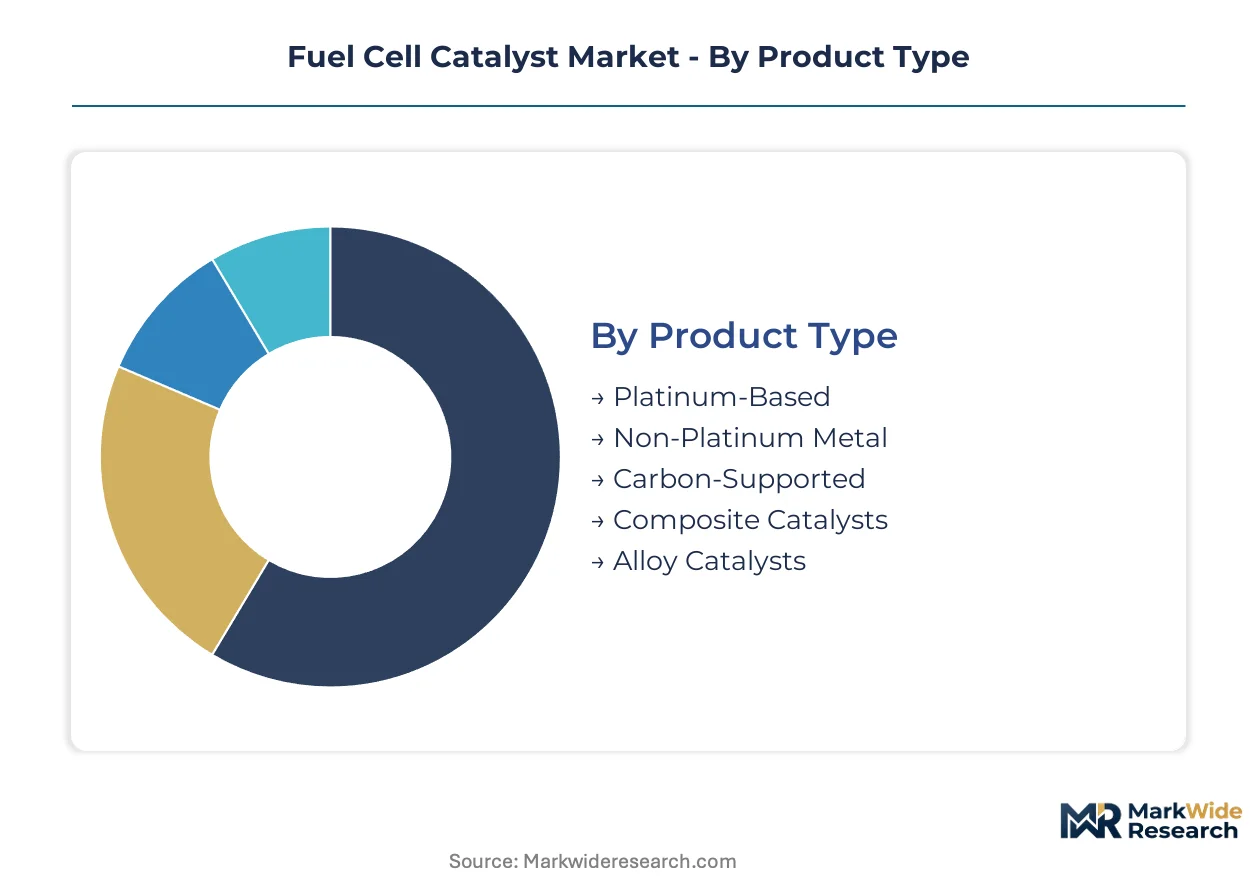
Catalyst formulation choices determine membrane electrode assembly replacement intervals and fleet total cost of ownership. Procurement teams segment supply by durability certification tiers and regional hydrogen purity standards rather than upfront unit pricing alone.
Product Type:
After-sales-service intensity varies sharply across catalyst chemistries, with platinum-based formulations requiring scheduled recovery protocols while emerging alternatives demand unproven field validation.
- Platinum-Based:Nanoparticle dispersions on high-surface-area carbon black sustain the dominant installed base. Demand concentrates in California's zero-emission freight corridors where CARB compliance mandates membrane electrode assembly procurement from certified suppliers.
- Alloy Catalysts:Cobalt or nickel incorporation targets platinum loadings below 0.1 mg per square centimeter. Germany's Ruhr industrial cluster drives qualification programs as OEMs electrify long-haul logistics under EU Green Deal hydrogen banking provisions.
- Non-Platinum Metal:Iron-nitrogen coordinated active sites are narrowing performance gaps with PGM benchmarks.
- Carbon-Supported:Petroleum-derived and biomass-sourced carriers sustain broad manufacturing compatibility.
- Composite Catalysts:Metal-organic framework and conductive polymer hybrids concentrate emerging patent filings.
By volume, Platinum-Based leads. By growth pace, Alloy Catalysts are gaining share fastest.
Technology:
Cost tier stratification separates proton exchange membrane stacks for automotive applications from alkaline systems targeting stationary power economics.
- Polymer Electrolyte Membrane:Perfluorinated sulfonic acid ionomers enable high current density at moderate temperatures. South Korea's Ulsan petrochemical corridor anchors demand through K-NEPA hydrogen certification requirements for integrated refinery-to-fuel-cell value chains.
- Alkaline:Hydroxide-conducting electrolytes eliminate platinum dependency entirely. Japan's METI research programs validate non-precious metal cathodes for commercial vehicle integration.
- Phosphoric Acid:Mature technology serving stationary cogeneration with established durability records.
- Solid Oxide:Ceramic electrolyte architectures operate at elevated temperatures incompatible with rapid start-stop cycling.
- Direct Methanol:Liquid fuel compatibility favors portable electronics applications with constrained hydrogen infrastructure access.
Polymer Electrolyte Membrane commands the premium tier. Alkaline systems show the steepest cost reduction trajectory.
Application:
Customer type differentiation separates fleet operators demanding decade-long service agreements from residential buyers prioritizing upfront capital efficiency.
- Commercial Vehicles:Class 8 tractors and regional delivery trucks dominate catalyst procurement volumes. EPA Clean Trucks Plan mandates expand membrane electrode assembly sourcing through Nikola and Daimler Truck North America fleet service divisions.
- Stationary Power:Industrial cogeneration and grid-scale storage require catalyst durability exceeding 40,000 operating hours. Germany's industrial clusters bundle catalyst replacement into power purchase agreements.
- Residential Power:Sub-kilowatt combined heat and systems serve building-scale applications.
- Portable Electronics:Miniaturized stacks prioritize power density over catalyst longevity.
- Aerospace:Auxiliary power units and unmanned aerial vehicles impose stringent mass constraints.
Commercial Vehicles anchor procurement volumes. Stationary Power offers the longest contract tenors.
End User:
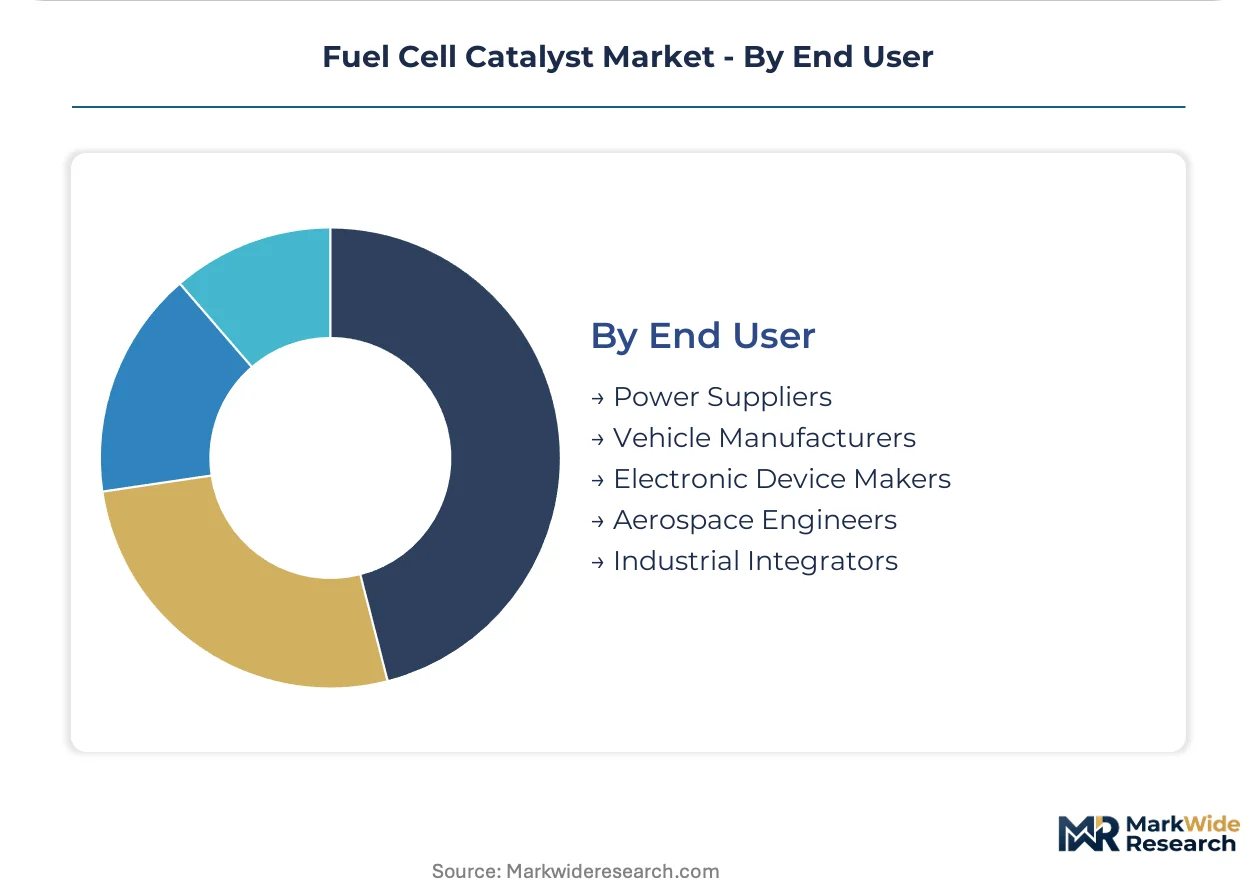
Supply concentration shapes procurement leverage, with vehicle manufacturers consolidating membrane electrode assembly sourcing under hydrogen supply agreements rather than component spot purchasing.
- Vehicle Manufacturers:Heavy-duty OEMs qualify catalyst formulations against DOE durability protocols and proprietary accelerated stress tests. California zero-emission freight corridor operators transfer technical risk to system integrators through bundled lease structures.
- Industrial Integrators:Petrochemical and steel sector hydrogen adoption drives demand for high-purity catalysts in process-integrated applications. South Korea's Ulsan corridor exemplifies this captive demand pattern.
- Power Suppliers:Utility-scale electrolyzer deployments require catalyst scale-up validation.
- Electronic Device Makers:Consumer electronics prioritize miniaturization and rapid start-up.
- Aerospace Engineers:Satellite and aircraft programs impose radiation-hardening and vibration-resistance specifications.
Vehicle Manufacturers concentrate procurement leverage. Industrial Integrators offer the most predictable demand visibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German membrane electrode assembly exports flow primarily into California's zero-emission freight corridors and South Korea's Ulsan petrochemical complex, establishing a transatlantic-Pacific trade corridor anchored by platinum-group metal processing expertise.
United States
California's Advanced Clean Trucks regulation mandates zero-emission powertrains for Class 8 tractors, pulling membrane electrode assembly procurement into the Central Valley logistics belt. The EPA's Clean Trucks Plan extends these requirements to interstate commerce, expanding catalyst demand across the Southwest freight corridor. Nikola and Daimler Truck North America fleet service divisions now bundle catalyst replacement schedules into decade-long vehicle lease structures.
Germany
The EU Green Deal's hydrogen banking provisions de-risk capital deployment for electrolyzer-integrated refueling stations, concentrating catalyst demand in the Ruhr industrial cluster. ECHA's REACH authorization requirements for cobalt compounds force binder chemistry revisions across membrane electrode assembly manufacturing. Johnson Matthey anchors European supply through its Royston manufacturing complex and integrated precious metal refining operations.
South Korea
K-NEPA hydrogen certification creates captive demand for high-purity catalysts in integrated refinery-to-fuel-cell value chains. The Ulsan petrochemical corridor hosts the densest concentration of heavy-duty fuel cell commercial vehicle deployments outside California. Domestic content requirements under MIIT-aligned dual carbon targets reshape catalyst sourcing footprints for Korean membrane electrode assembly integrators.
Japan
METI hydrogen roadmaps accelerate platinum-group metal substitution research through single-atom catalysis validation programs. Toyota and Hyundai heavy-duty divisions qualify iron-nitrogen coordinated active sites for 2027 platform launches. The Chubu region's materials science infrastructure supports pilot-scale electrode manufacturing for non-precious metal cathode formulations.
China
MIIT dual carbon targets and domestic content standards reshape catalyst formulation commitments for proton exchange membrane stack manufacturers. The Yangtze River Delta concentrates membrane electrode assembly production capacity serving both domestic heavy-duty fleets and export markets. Platinum price volatility intersects with national critical minerals stockpiling strategies to determine geographic sourcing footprints for Chinese integrators.
Fuel Cell Catalyst Market Key Industry Players
Channel-controlling players compete with product-specialist players across a tiered structure where precious metal refiners, chemical conglomerates, and dedicated catalyst formulators each occupy distinct value chain positions. The vendor base clusters around three strategic archetypes: integrated precious metal recyclers with closed-loop recovery networks, high-throughput materials screeners accelerating non-platinum metal discovery, and membrane electrode assembly integrators controlling downstream channel access. Dominant competitive moves include strategic partnerships between catalyst suppliers and heavy-duty OEMs, plus geographic expansion into hydrogen corridor clusters to secure fleet procurement leverage.
Among European precious metal specialists, Johnson Matthey and Umicore exemplify the integrated refiner-formulator archetype, each anchoring regional supply security through captive metal recovery and membrane electrode assembly integration. BASF occupies a position within the high-throughput materials screening tier, representing the chemical conglomerate model of catalyst development. These three entities collectively illustrate how competitive positioning fragments across metal control, manufacturing scale, and research velocity rather than consolidating around uniform capabilities.
| Leading Market Players |
|---|
| Umicore |
| Johnson Matthey |
| 3M |
| Heraeus |
| Haldor Topsoe |
| Tanaka Holdings Co., Ltd. |
| De Nora |
| BASF |
| Clariant |
| Others |
Cost & Logistics Intelligence
Undercapacity in South African platinum refining capacity drives contract renegotiation urgency among membrane electrode assembly integrators, compressing supplier margins while amplifying spot market exposure for catalyst formulators serving California's zero-emission freight corridors.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange platinum spot pricing dominate heavy-duty fleet procurement, with membrane electrode assembly suppliers passing through 85-90% of metal cost fluctuations. Price differentiation separates CARB-certified premium tiers from uncertified economy formulations, while volume-scale discounts concentrate with Nikola and Daimler Truck North America fleet service divisions. Pricing pressure stems from cobalt compound REACH authorization costs forcing binder chemistry pivots. After-sales service bundling renders fleet operators least price-sensitive, while independent retrofit installers exhibit highest elasticity.
Supply Chain Analysis
Supplier-financing facilities extended by Johnson Matthey and Umicore stabilize working capital for German membrane electrode assembly integrators facing 180-day qualification timelines. Geographic supply concentrates in South Africa for platinum group metals, China for high-surface-area carbon black, and Germany for perfluorinated sulfonic acid ionomers. Raw material dependencies rest on petroleum-derived carbon carriers, cobalt-nickel alloy precursors, and fluorinated membrane materials. Single-source vulnerability in South African PGM refining creates structural risk. Distribution runs through integrated precious metal refiners with captive recovery networks rather than spot commodity markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery anchored to heavy-duty fleet electrification capex cycles, with platinum price troughs historically preceding membrane electrode assembly procurement surges by 12-18 months.
For Market Incumbents: Insulate formulation portfolios against platinum price volatility by accelerating closed-loop recycling infrastructure deployment across Germany's Ruhr cluster. Secure backward integration into spent automotive catalyst recovery networks before cobalt REACH sunset dates force binder chemistry disruptions. Anchor membrane electrode assembly integration capabilities to lock out pure-play catalyst formulators.
For New Entrants and Emerging Players: Pursue qualification gaps in iron-nitrogen coordinated single-atom architectures where Toyota and Hyundai heavy-duty divisions seek non-precious metal cathode suppliers for 2027 platform launches. Target South Korea's Ulsan petrochemical corridor where K-NEPA certification creates captive demand for high-purity catalysts absent established supplier relationships. Lead with metal-organic framework hybrid patent filings to establish intellectual property moats ahead of incumbent research velocity.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among membrane electrode assembly integrators bundling catalyst replacement schedules into decade-long hydrogen supply agreements. Five-to-ten year viability favors suppliers with demonstrated DOE durability protocol certification and established OEM qualification relationships. Monitor platinum price floor breaches as inflection signal for fleet procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Recycling Infrastructure | Johnson Matthey's Royston complex recovers platinum from spent automotive catalysts, reducing virgin metal dependency for electrode manufacturers. |
| Single-Atom Catalysis Scale-Up | Toyota and Hyundai heavy-duty divisions validate iron-nitrogen active sites, narrowing performance gaps with PGM benchmarks for 2027 launches. |
| Regional Membrane Electrode Assembly Production | German exports to California freight corridors and Ulsan petrochemical complex establish transatlantic-Pacific trade anchored by PGM processing expertise. |
| Cobalt-Free Binder Chemistry Pivot | ECHA REACH authorization deadlines force nickel-manganese substitution research and fluorine-free ionomer development across European manufacturing. |
| Hydrogen Supply Agreement Bundling | Nikola and Daimler Truck North America fleet service divisions consolidate procurement leverage through decade-long catalyst replacement schedules. |
Research Approach
Findings reconcile primary fieldwork against secondary review of SEC filings, EU ECHA authorization databases, and DOE hydrogen program disclosures. Primary interviews engaged membrane electrode assembly procurement managers at heavy-duty OEMs, precious metal refining operations directors, and fuel cell stack integration engineers. Secondary validation drew from CARB regulatory filings, MIIT dual carbon target documentation, and K-NEPA certification records. Bottom-up catalyst demand modeling triangulated against top-down fleet electrification projections.
Forecast inputs incorporate platinum loading reduction trajectories, membrane electrode assembly replacement interval assumptions, and regional hydrogen corridor deployment schedules across the analysis window. Segmentation dimensions span catalyst formulation chemistry, fuel cell technology architecture, vehicle application class, and end-user procurement concentration. CAGRs derive from installed base growth rates modified by durability improvement factors and fleet operator total cost of ownership sensitivity. Industry-specific inputs include DOE durability protocol evolution and OEM-specific accelerated stress test qualification timelines.
Macroeconomic conditions sit as an overlay; deviation in platinum price volatility, South African mining output disruptions, or EU F-Gas Regulation enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions regarding cobalt compound authorization timelines and heavy-duty fleet electrification mandates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Solid Acid Catalysts Market
Catalysts
Stationary Catalytic Systems Market
Catalysts
Biodiesel Catalyst Market
Catalysts
Homogeneous Catalyst Market
Catalysts
Platinum-Based Catalysts Market
Catalysts
Industrial Catalytic Converters Market
Catalysts
Copper Bismuth Catalyst Market
Catalysts
Asia-Pacific Refining Catalysts Market
Catalysts
Global Light Powered Catalyst Market
Catalysts
Rhodium Carbon Catalyst Market
Catalysts
Europe Homogeneous Precious Metal Catalyst Market
Catalysts
Biorenewable Catalysts Market
Catalysts
Global Boron Trifluoride Methanol Complex Market
Catalysts
Refining Catalysts Market
Catalysts
Global Zeolites Market
Catalysts
Chemical Processing Catalysts Market