
 Stationary Emission Control Catalyst Market | 2026-2036
Stationary Emission Control Catalyst Market Size, Share, and Industry Trends Forecast 2026-2036
Stationary Emission Control Catalyst Market Outlook
Aftermarket catalyst regeneration and reactivation services is rewriting margin distribution across the value chain. BASF SE leverages its integrated precious metals refining network to sustain captive supply security for coated substrate production. Johnson Matthey anchors European demand through dense service station coverage and long-term utility contracts. Haldor Topsoe A/S specializes in high-activity deNOx formulations that dominate biomass and waste-to-energy installations.
Stationary emission control catalysts are engineered porous ceramic or metallic substrates washcoated with platinum-group metals, zeolites, or base metal oxides, designed to facilitate redox reactions at operating temperatures between 150°C and 450°C. These systems abate nitrogen oxides, carbon monoxide, and unburned hydrocarbons from flue gases generated by continuous combustion or chemical processing operations. Selective catalytic reduction and oxidation catalysts command the largest installed base, while three-way catalysts gain share in stationary engines requiring simultaneous NOx, CO, and hydrocarbon control. Heterogeneous catalysis remains the dominant technology platform, though photocatalysis shows structural promise for low-temperature volatile organic compound destruction in chemical manufacturing.
EPA Mercury and Air Toxics Standards, EU Industrial Emissions Directive, and China's MEE ultra-low emission retrofit mandates collectively tighten allowable stack concentrations and compress catalyst replacement intervals. Product registration with national environmental authorities now gates market access more stringently than capital cost in utility procurement decisions. Stakeholders must monitor regulatory divergence between jurisdictions to align R&D pipelines with diverging certification requirements and emission limit values.
Market Dynamics
Retrofit mandates from China's MEE and the EU Industrial Emissions Directive are compressing catalyst replacement cycles while regenerative service models capture margin from traditional manufacturing. Supply security for platinum-group metals now determines competitive positioning more than coating technology differentiation.
Growth Catalysts
- Ultra-low emission retrofit waves:China's MEE enforcement drives selective catalytic reduction installations across coal-fired power fleets, creating sustained demand for high-activity vanadium and zeolite formulations.
- Biomass energy expansion:Waste-to-energy installations in Germany and Nordic markets require specialized deNOx catalysts tolerant to high dust and alkali poisoning.
- REACH compliance acceleration:The EU Green Deal tightens emission limit values for industrial processes, shortening certified catalyst service intervals from five years to three.
Market Restraints
- Platinum-group metal price volatility:Rhodium and palladium supply concentrated in South African and Russian mining operations creates input cost unpredictability for coated substrate producers.
- Ceramic substrate supply concentration:High-purity cordierite and silicon carbide manufacturing clusters in Japan and Germany limit geographic diversification options.
- Low-temperature activity limits:Existing zeolite formulations fail to achieve sufficient NOx conversion below 180°C, constraining applications in chemical process vents.
Strategic Opportunities
- India industrial corridor buildout:The PLI scheme for manufacturing and tightening CEA emission norms for thermal power create first-mover positioning for catalyst suppliers establishing local coating facilities.
- Photocatalysis integration:UV-activated titanium dioxide systems for volatile organic compound destruction at ambient temperatures open chemical manufacturing applications unreachable by thermal catalysis.
- Circular service models:Catalyst regeneration and precious metals recovery contracts transform one-time equipment sales into recurring revenue streams with utility customers.
Industry Challenges
- Specialized coating technician scarcity:Precise washcoating of platinum-group metals onto complex honeycomb geometries requires skills concentrated among aging European and Japanese workforces.
- Multi-jurisdiction certification timelines:Separate EPA, ECHA, and MEE product registrations for each catalyst formulation extend market entry cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stationary Emission Control Catalyst Market |
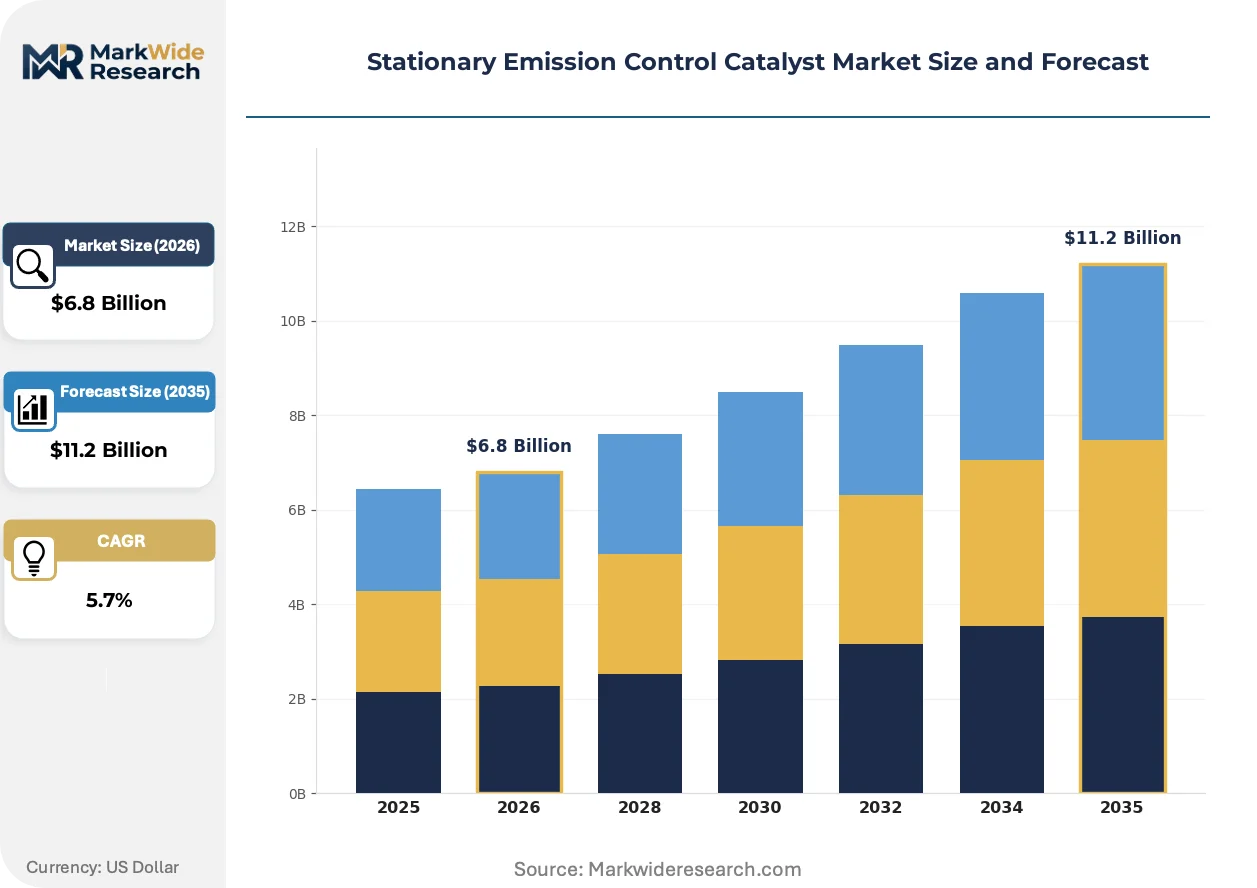
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oxidation Catalysts, Reduction Catalysts, Three-Way Catalysts, Selective Catalytic Reduction Technology: Homogeneous Catalysis, Heterogeneous Catalysis, Enzyme Catalysis, Photocatalysis Application: Power Generation, Industrial Processes, Waste Incineration, Chemical Manufacturing End User: Utilities, Manufacturing Plants, Oil & Gas Industry, Cement Industry |
| Companies Covered | Cormetech Inc., Hitachi Zosen Corporation, BASF SE, DCL International Inc., Corning Inc., Johnson Matthey, Cataler Corporation, Haldor Topsoe A/S, Umicore, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stationary Emission Control Catalyst Market Strategic Shifts
Digital integration of catalyst performance monitoring with predictive replacement scheduling is restructuring service relationships between suppliers and utility operators. Real-time emissions data feeds directly influence procurement decisions.
Smart sensor-embedded catalyst substrates are digitizing maintenance protocols across power generation fleets. Duke Energy and RWE deploy continuous temperature and pressure monitoring to optimize regeneration timing. This digitizing of asset management compresses service intervals while reducing unplanned downtime penalties.
The EU F-Gas Regulation phase-down is accelerating ammonia-based selective catalytic reduction over urea systems in industrial boilers. Manufacturers face reformulation requirements for storage and handling systems. Chemical processing clusters in the Netherlands and Belgium retrofit first due to proximity to ammonia supply infrastructure.
Power utilities unbundle catalyst procurement from original equipment supplier contracts. Engie and Enel now source coatings independently from substrate manufacturers, reversing decades of bundled purchasing. This behavior shift concentrates price negotiation leverage with procurement departments in German and French headquarters.
Stationary Emission Control Catalyst Market Segmentation
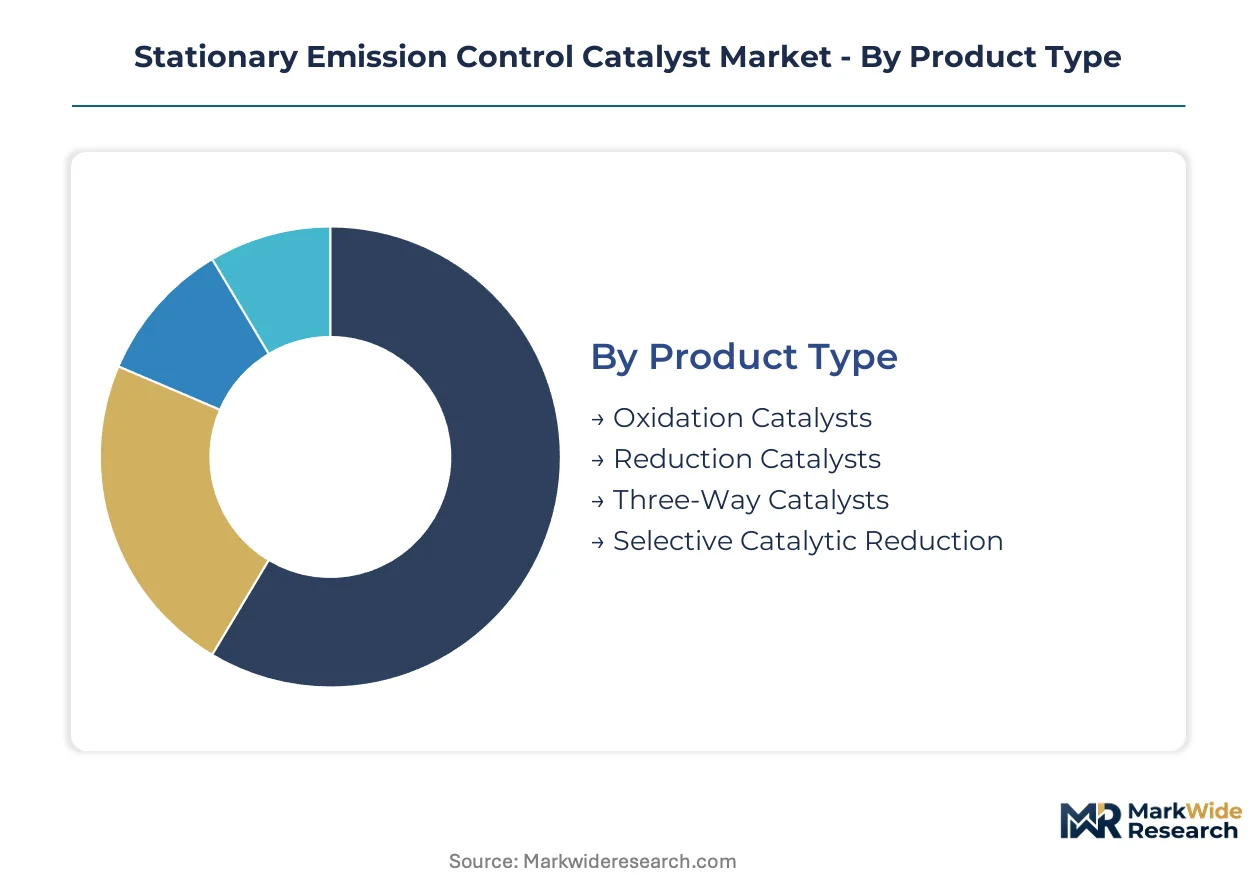
Segmentation in stationary emission control catalysts reveals how regulatory stringency and combustion chemistry reshape procurement patterns. Product type and technology choices determine precious metal loading requirements, while application and end-user distinctions govern replacement cycle economics.
Product Type:
Cost tier stratification across catalyst formulations reflects precious metal intensity and substrate complexity.
- Selective Catalytic Reduction:Zeolite or vanadium-based formulations facilitate ammonia-mediated NOx reduction at 300-450°C operating windows. Coal-fired utilities in China deploy these systems under MEE ultra-low emission mandates, compressing replacement intervals from seven years to four.
- Oxidation Catalysts:Platinum-palladium coatings on cordierite substrates convert CO and unburned hydrocarbons to CO2 and water. Industrial boiler operators in Germany favor these for compliance with EU Industrial Emissions Directive limits on carbon monoxide stack concentrations.
- Three-Way Catalysts:Simultaneous NOx, CO, and hydrocarbon control for stationary engines burning natural gas or biogas.
- Reduction Catalysts:Base metal oxide formulations for non-selective NOx reduction in chemical process vents.
Selective Catalytic Reduction holds installed capacity. Three-Way Catalysts is rotating up the share rankings.
Technology:
Maturity levels across catalytic platforms determine R&D allocation and patent filing intensity.
- Heterogeneous Catalysis:Solid-phase catalysts with platinum-group metals dispersed on porous ceramic supports dominate commercial installations. This platform anchors utility procurement in the United States where EPA Mercury and Air Toxics Standards mandate proven performance documentation.
- Photocatalysis:UV-activated titanium dioxide systems destroy volatile organic compounds at ambient temperatures without thermal energy input. Chemical manufacturing clusters in the Netherlands pilot these for F-Gas Regulation compliance where process vents run too cool for conventional thermal activation.
- Homogeneous Catalysis:Liquid-phase catalysts dissolved in reactant streams for specialized chemical synthesis applications.
- Enzyme Catalysis:Biocatalytic systems for emission control in fermentation and bioprocessing operations.
Heterogeneous Catalysis commands the technology base. Photocatalysis is gaining commercial traction fastest.
Application:
Volume concentration varies by stack gas composition, particulate burden, and regulatory enforcement intensity.
- Power Generation:High-capacity selective catalytic reduction systems on coal and gas-fired turbines handle flue gas volumes exceeding one million Nm³/hour. Utilities in China and Germany drive procurement volumes as MEE and EU Green Deal timelines accelerate retrofit waves.
- Waste Incineration:DeNOx catalysts in biomass and refuse-derived fuel plants tolerate high dust loads and alkali poisoning. Installations in Nordic markets and Germany require specialized high-activity formulations for dioxin and NOx simultaneous control.
- Industrial Processes:Steel, glass, and cement kilns deploy oxidation and reduction catalysts for process-specific emission profiles.
- Chemical Manufacturing:Specialized catalysts for petrochemical crackers, ammonia plants, and specialty chemical reactors.
Power Generation anchors volume demand. Waste Incineration is climbing the fastest.
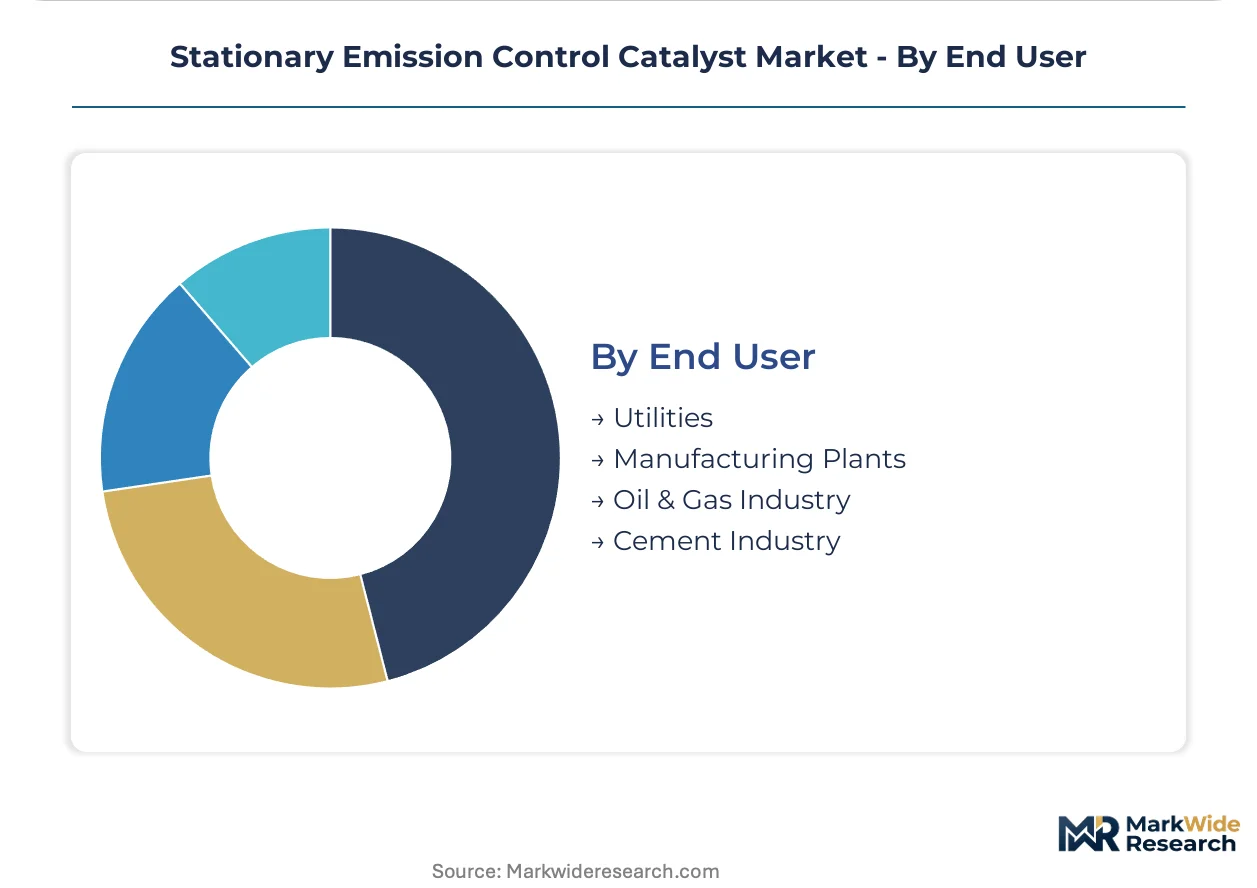
End User:
Customer type determines contract structure, service integration depth, and procurement centralization.
- Utilities:Centralized procurement departments at Engie, Enel, and Duke Energy unbundle catalyst coatings from original equipment supplier contracts. Long-term service agreements with regeneration clauses now dominate European and North American utility sourcing.
- Cement Industry:Rotary kiln operators face escalating NOx limits under national implementations of EU Industrial Emissions Directive best available techniques. Plants in Germany and Poland retrofit selective catalytic reduction ahead of 2025 compliance deadlines.
- Manufacturing Plants:Discrete industrial boiler operators with fragmented ownership and variable maintenance sophistication.
- Oil & Gas Industry:Refinery fluid catalytic crackers and sulfur recovery units with specialized catalyst requirements.
Utilities concentrate contract value. Cement Industry is ascending in procurement priority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Chinese utilities prioritize high-capacity selective catalytic reduction systems for coal fleet retrofits. German industrial operators favor oxidation catalysts for process compliance. Nordic markets drive specialized deNOx formulations for waste-to-energy.
China
Coal-fired power utilities dominate catalyst procurement volumes under MEE ultra-low emission mandates. The ministry enforces stack concentration limits that compress replacement cycles from seven years to four. Installations concentrate in Shandong and Shanxi provinces where provincial environmental bureaus accelerate retrofit timelines.
Germany
Cement kiln operators and industrial boiler fleets drive oxidation catalyst demand for EU Industrial Emissions Directive compliance. REACH regulations and the EU Green Deal tighten emission limit values. The Rhine-Ruhr industrial corridor sees concentrated retrofit activity ahead of 2025 best available technique deadlines.
United States
Utility procurement departments unbundle catalyst coatings from original equipment contracts under EPA Mercury and Air Toxics Standards. Duke Energy and independent power producers drive regenerative service model adoption. Activity clusters in the Ohio River Valley and Texas ERCOT markets where coal-gas fleet transitions create replacement waves.
India
Thermal power expansion under CEA emission norms and the PLI scheme for manufacturing creates first-mover positioning opportunities. Central Electricity Authority mandates drive selective catalytic reduction installations. Gujarat and Maharashtra industrial corridors attract coating facility investments from multinational suppliers.
Japan
High-purity cordierite and silicon carbide substrate manufacturing anchors upstream supply. METI efficiency standards and carbon neutrality targets drive catalyst performance requirements. Nagoya and Osaka industrial clusters concentrate ceramic honeycomb production for regional utility and chemical process markets.
Stationary Emission Control Catalyst Market Competitive Environment
Capability concentration sits with integrated precious metals refiners; scale advantage sits with dense service network operators. The market structures around three tiers: multinational chemical conglomerates with captive PGM supply, specialized catalyst formulators with utility service contracts, and regional substrate manufacturers. Dominant competitive moves include backward integration into precious metals recovery and geographic expansion through local coating facility establishment.
Within the integrated chemical tier, BASF SE and Umicore exemplify archetypes combining refining networks with coated substrate production. Johnson Matthey anchors the specialized service tier through European utility relationships. Haldor Topsoe A/S occupies a position among high-activity formulation specialists serving biomass and waste-to-energy installations. Corning Inc. represents the substrate manufacturing archetype with ceramic honeycomb capabilities. These players illustrate how supply security for platinum-group metals now determines positioning more than coating technology differentiation alone.
| Leading Market Players |
|---|
| Cormetech Inc. |
| Hitachi Zosen Corporation |
| BASF SE |
| DCL International Inc. |
| Corning Inc. |
| Johnson Matthey |
| Cataler Corporation |
| Haldor Topsoe A/S |
| Umicore |
| Others |
Value Chain & Pricing Dynamics
Japanese and German high-purity cordierite manufacturing clusters concentrate upstream substrate supply, anchoring margin pools with coating specialists who control platinum-group metal loading specifications and regeneration service contracts. This geographic concentration of ceramic honeycomb production creates asymmetric pricing power that flows downstream to integrated refiners with captive PGM networks.
Pricing Analysis
Long-term offtake agreements between utilities and coating suppliers dominate procurement, with Engie and Enel unbundling coatings from original equipment contracts to negotiate direct volume commitments. Price differentiation rests on precious metal loading intensity and EPA-ECHA-MEE certification tier, with standard-grade zeolite formulations facing cost compression from regenerative service models while premium high-activity vanadium catalysts retain margin. Price erosion runs through mid-tier oxidation catalysts as ceramic substrate oversupply intensifies competition. Cement kiln operators exhibit highest price sensitivity due to fragmented ownership and variable maintenance sophistication, whereas Chinese power utilities under MEE mandates prioritize performance over unit cost.
Supply Chain Analysis
Tariff exposure between South African platinum mining operations and Chinese coating facilities dominates supply chain risk assessment for rhodium and palladium inputs. Raw material dependencies center on South African PGM concentrates, Japanese cordierite substrates, and German silicon carbide honeycombs. Single-source vulnerability concentrates in high-purity ceramic manufacturing where Nagoya and Osaka industrial clusters control technical specifications. Distribution runs through regional coating facilities in Germany, China, and India that washcoat substrates for utility and industrial end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photocatalysis systems for ambient-temperature VOC destruction present a credible substitution threat that incumbents must navigate through formulation innovation and service model expansion.
For Market Incumbents: Harden defensive positioning through backward integration into precious metals recovery networks and captive regeneration service infrastructure. BASF SE's integrated refining model exemplifies the margin protection achievable through upstream control over rhodium and palladium supply. Certification investment across EPA, ECHA, and MEE jurisdictions creates switching costs that lock utility procurement departments into established supplier relationships. For New Entrants and Emerging Players: Pursue white-space positioning in India's Gujarat and Maharashtra industrial corridors where CEA emission norms and PLI scheme incentives create first-mover advantages for local coating facility establishment. Waste-to-energy installations in Nordic markets represent the most penetrable segment due to specialized high-activity formulation requirements that favor technical specialists over integrated conglomerates. Joint venture structures with regional substrate manufacturers offer the strongest go-to-market angle for bypassing established service networks. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed coating specialists holding dense European utility service contracts but lacking PGM refining integration. Long-term viability across the analysis window favors targets with regeneration service revenue streams and multi-jurisdiction certification portfolios. Watch MEE enforcement intensity in Shandong and Shanxi provinces as the inflection signal for Chinese retrofit wave timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PGM Recovery | BASF SE's captive refining network eliminates rhodium supply disruption risk for coated substrate production. |
| Local Coating Facility Establishment | India's PLI scheme rewards Gujarat and Maharashtra investments with tariff advantages for CEA-mandated SCR installations. |
| Regeneration Service Model Expansion | Johnson Matthey's European utility contracts transform one-time equipment sales into recurring revenue streams. |
| Multi-Jurisdiction Certification Investment | Simultaneous EPA, ECHA, and MEE registrations compress market entry cycles for new formulations. |
| Photocatalysis R&D Partnership | UV-activated titanium dioxide pilots in Dutch chemical clusters open F-Gas Regulation compliance pathways. |
Study Parameters
Desk research of customs trade data, SEC 10-K filings, and national environmental authority product registries preceded structured interviews with utility procurement directors, catalyst coating technicians, PGM refining operations managers, and ceramic substrate manufacturing engineers. Primary fieldwork with plant engineers at coal-fired power stations and cement kiln operators validated replacement cycle assumptions. Secondary sources included EIA generation data, MEE enforcement bulletins, and EU Industrial Emissions Directive implementation reports. Bottom-up unit economics triangulated against top-down sector spending estimates.
Assumption sets held regulatory enforcement timelines and PGM price bands fixed while varying coal-gas fleet transition speeds and chemical manufacturing output levels. The analytical framework modeled segmentation across catalyst formulation type, combustion application, end-user procurement sophistication, and regional regulatory cluster. CAGRs derived from installed base depreciation curves and retrofit mandate compliance schedules. Forecast inputs incorporated MEE ultra-low emission retrofit waves and EU Green Deal best available technique deadlines.
Macroeconomic conditions sit as an overlay; deviation in industrial electricity demand and construction activity would shift the trajectory. Forecasts reflect documented assumptions about enforcement intensity and precious metal supply stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Organic Catalyst Market
Catalysts
South America Refining Catalysts Market
Catalysts
Hydro-Processing Catalysts Market
Catalysts
Precious Metal Catalysts Market
Catalysts
Catalyst Carrier Market
Catalysts
Steam Methane Reforming Market
Catalysts
Fuel Cell Catalyst Market
Catalysts
Heavy Oil Cracking Catalyst Market
Catalysts
Europe Refining Catalysts Market
Catalysts
Catalase Market
Catalysts
Asia-Pacific Refining Catalysts Market
Catalysts
Global Phase Transfer Catalyst Market
Catalysts
Rhodium Carbon Catalyst Market
Catalysts
Global Chemical Catalyst Market
Catalysts
Environmental Catalysts Market
Catalysts
Catalyst for Hydrogen Production from Water Electrolysis Market