
 Heavy Oil Cracking Catalyst Market | 2026-2036
Heavy Oil Cracking Catalyst Market Size, Share, and Industry Trends Forecast 2026-2036
Heavy Oil Cracking Catalyst Market Outlook
EPA refinery sector rules is rebalancing the cost-of-entry calculus for North American catalyst suppliers. BASF leverages its integrated zeolite manufacturing network to sustain formulation leadership across FCC and hydrocracking platforms. Albemarle Corporation anchors its position through captive rare earth processing and long-term supply agreements with Gulf Coast refiners.
Heavy oil cracking catalysts are engineered porous solids, typically containing Y-type zeolites in a silica-alumina matrix with active metals such as nickel or vanadium tolerance additives, manufactured via spray-drying and calcination to achieve controlled acidity and pore architecture for breaking high-molecular-weight hydrocarbons into lighter, more valuable products. Fluid catalytic cracking formulations dominate volume demand due to their established integration in residue upgrading units, while hydrocracking catalysts command premium positioning as refiners target stricter middle-distillate yields. Zeolite-based products lead the product type landscape, though transition metal-enhanced variants are gaining traction for processing metal-contaminated heavy feeds.
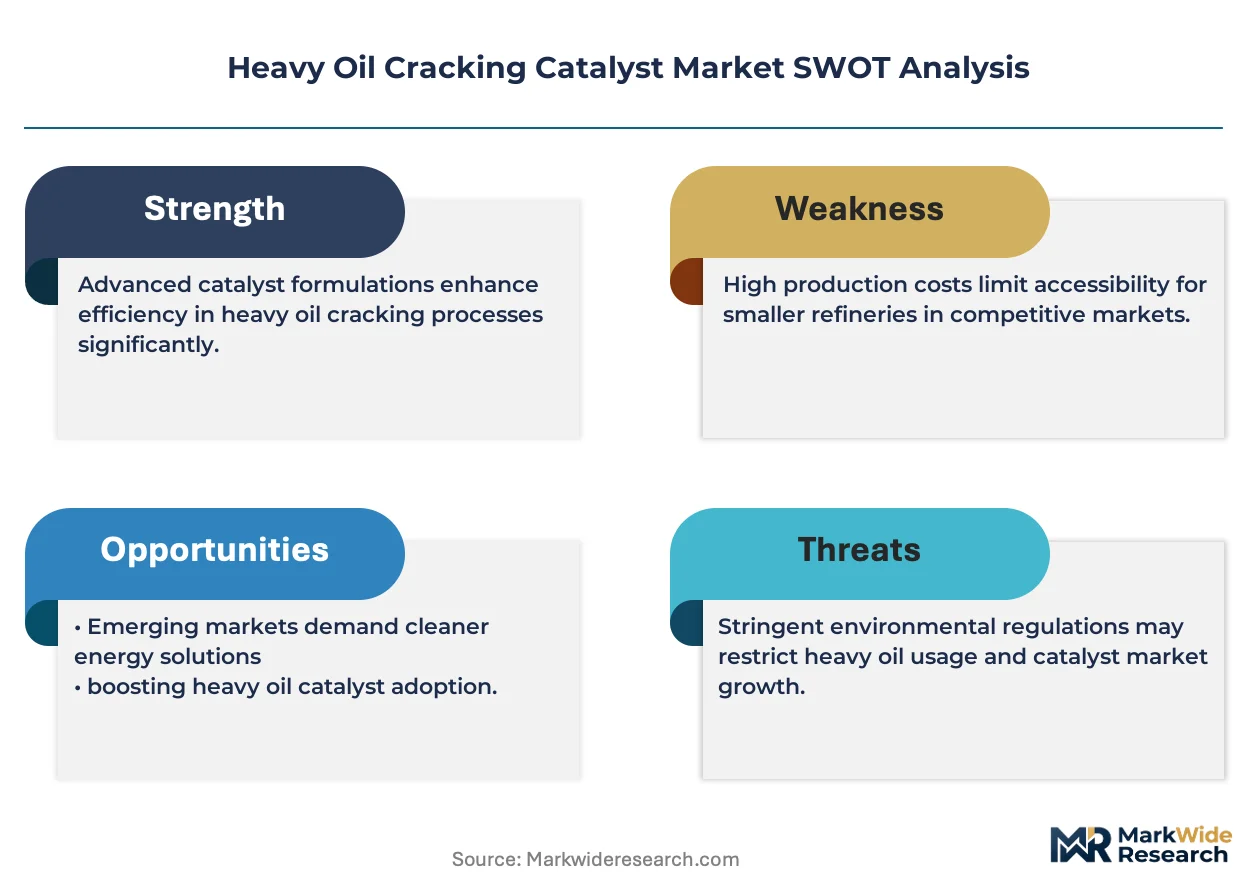
EPA emissions mandates, EU F-Gas Regulation, and China's GB standards collectively tighten the specification envelope for catalyst durability and regeneration performance. These frameworks push refiners toward higher-activity formulations that reduce coke make and cut regenerator emissions per barrel processed. Stakeholders must weigh catalyst lifecycle cost against unit retrofit requirements as regulatory baselines diverge across operating jurisdictions.
Market Dynamics
Refinery feedstock quality deterioration is compressing catalyst replacement cycles as operators process heavier, metal-contaminated crude slates that accelerate zeolite deactivation and force more frequent regenerations.
Growth Catalysts
- EU F-Gas Regulation:Emissions caps on refinery operations are mandating higher-activity catalyst formulations that minimize regenerator CO2 output per barrel processed.
- Residue upgrading expansion:Middle Eastern refiners are installing new hydrocracking trains to convert vacuum residue into middle distillates, directly lifting demand for specialized heavy oil cracking catalysts.
- China's GB standards alignment:Teapot refiners upgrading to meet national emission benchmarks are retrofitting FCC units with metal-tolerant catalyst systems.
Market Restraints
- Rare earth oxide volatility:Lanthanum and cerium price swings embedded in zeolite formulations create margin pressure for catalyst manufacturers without captive mining assets.
- Single-source supply risk:High-purity alumina supply concentrates in specific bauxite-processing corridors, exposing formulators to geographic disruption.
- Regenerability ceiling:Vanadium and nickel accumulation in spent catalysts imposes hard limits on cycle counts, forcing premature replacement regardless of zeolite integrity.
Strategic Opportunities
- India residue processing gap:Reliance Industries and public-sector refiners lag global peers in residue conversion depth, creating retrofit demand for hydrocracking catalysts.
- Biomass co-processing integration:FCC units adapting to bio-oil feeds require modified acidity profiles that open formulation white space beyond petroleum-optimized products.
- Carbon border adjustment mechanism:EU import levies on high-carbon intensity refined products incentivize catalyst investments that cut unit emissions intensity.
Industry Challenges
- Catalyst characterization expertise:Refiners lack in-house capability to correlate spent catalyst analysis with operational adjustments, creating dependency on supplier diagnostics.
- Legacy unit metallurgy constraints:Older FCC regenerators cannot withstand the temperature profiles required by high-activity modern formulations without capital overhaul.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heavy Oil Cracking Catalyst Market |
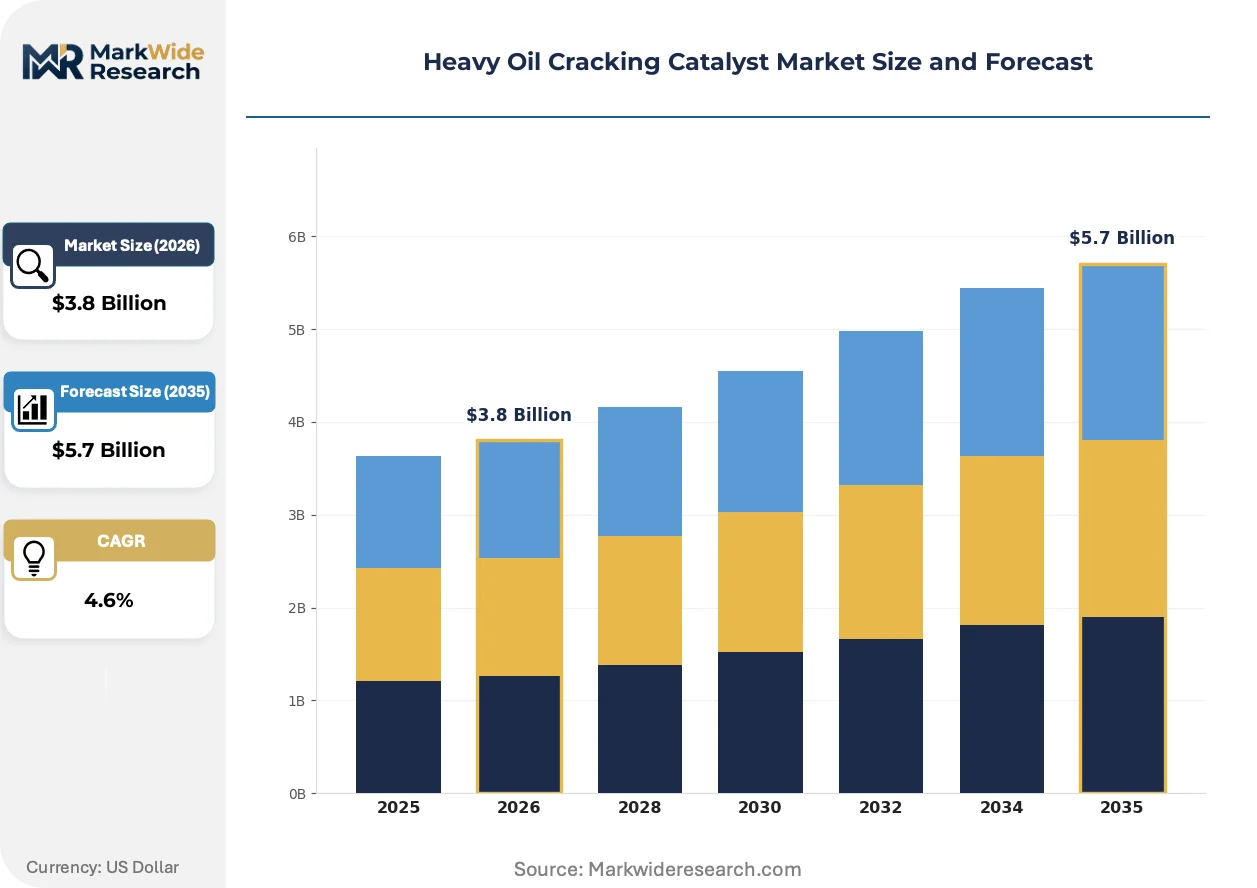
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Zeolites, Non-Zeolitic, Transition Metals, Hydrotreating Catalysts Application: Petroleum Refining, Petrochemical Production, Synthetic Fuel Manufacturing, Renewable Energy End User: Refineries, Chemical Plants, Oil & Gas Producers, Energy Corporations Technology: Fluid Catalytic Cracking, Hydrocracking, Thermal Cracking, Catalytic Hydrocracking |
| Companies Covered | Honeywell UOP, BASF, Shell Catalysts & Technologies, Axens, Grace, ExxonMobil, Albemarle Corporation, Sinopec, Advanced Refining Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heavy Oil Cracking Catalyst Market Strategic Shifts
Zeolite architecture engineering and emissions-linked procurement criteria are restructuring how refiners evaluate catalyst lifecycle economics and supplier relationships.
Transition metal-enhanced Y-zeolites with tailored mesoporosity distributions are rewriting performance benchmarks for metal-contaminated feed processing. Gulf Coast refiners running high-vanadium Venezuelan and Mexican crudes are adopting these systems at replacement cycle compression rates of 15-20 percent versus conventional matrices. The technology is rewriting the tradeoff between catalyst cost per pound and unit throughput economics.
EPA refinery sector rules tightening on particulate and greenhouse gas emissions are forcing regenerator design modifications that favor low-coke-make catalyst formulations. The industrial consequence is a specification divergence between US-focused suppliers and those serving less regulated markets. FCC operators in Texas and Louisiana are absorbing 8-12 percent formulation premiums for emissions-optimized products versus standard grades.
Refiner procurement teams are unbundling catalyst supply from technical service contracts that previously locked in multi-year single-source arrangements. The channel being disrupted is the integrated supply-plus-optimization model dominated by major formulators; spot purchasing with third-party technical advisors is displacing it. This pattern is most visible among independent North American refiners with in-house reaction engineering capabilities.
Heavy Oil Cracking Catalyst Market Segmentation
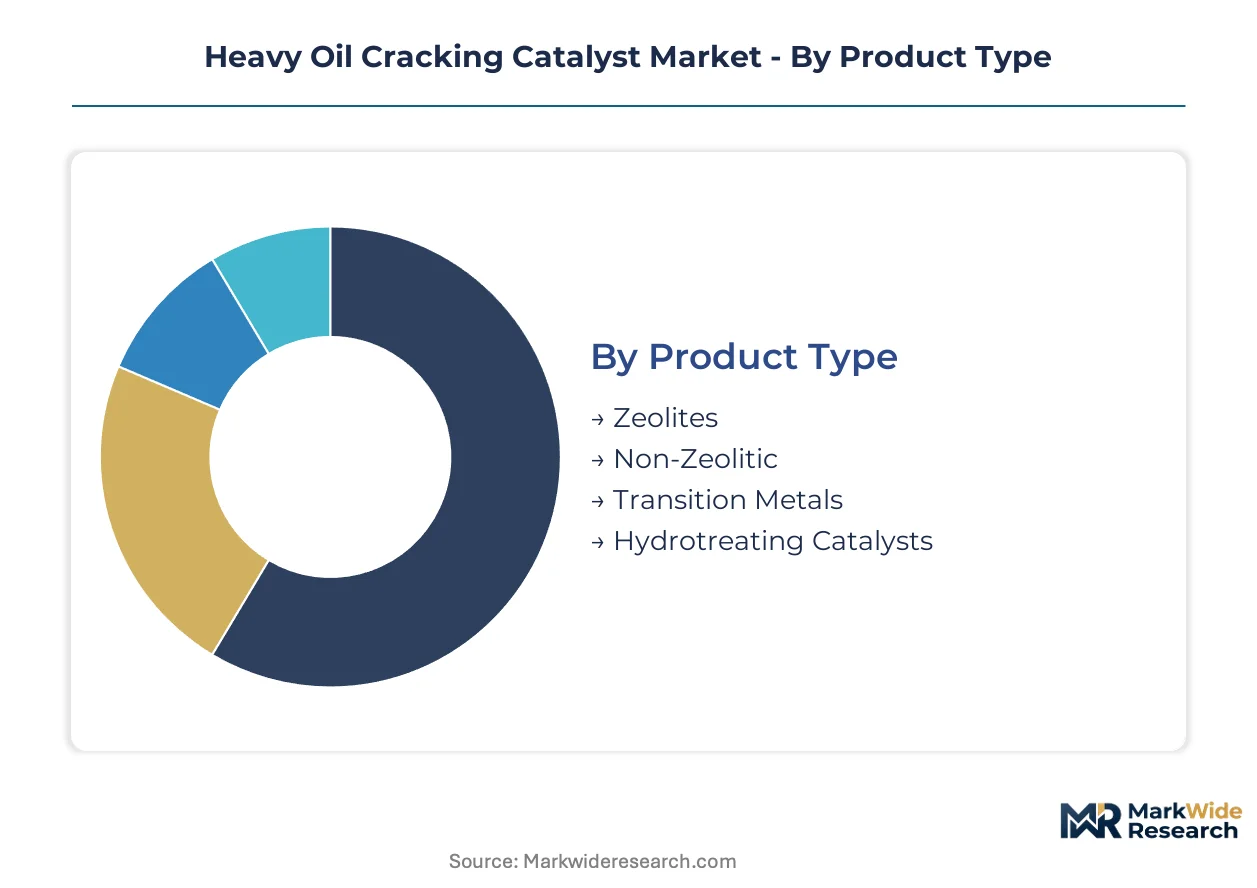
Refinery operators select catalyst formulations based on feedstock metal content, unit metallurgy constraints, and emissions compliance obligations. Segmentation clarity matters because the same porous solid performs differently across FCC regenerators versus hydrocracking reactors. Procurement teams weight lifecycle cost against retrofit requirements when matching product categories to specific upgrading trains.
Product Type:
Formulation chemistry dictates tolerance thresholds for vanadium and nickel contamination, the dominant buyer-decision driver in residue processing.
- Zeolites:Y-type faujasite structures in silica-alumina matrices deliver controlled acidity for breaking high-molecular-weight hydrocarbons. Demand concentrates in China's teapot refiners upgrading FCC units to meet GB emission benchmarks, with Sinopec specifying metal-tolerant variants for heavy crude slates.
- Transition Metals:Nickel and vanadium tolerance additives embedded in zeolite frameworks extend cycle life when processing contaminated feeds. Gulf Coast refiners running Venezuelan and Mexican crudes adopt these systems at compressed replacement cycles of 15-20 percent versus conventional matrices.
- Non-Zeolitic:Amorphous silica-alumina and composite oxide formulations serve niche applications where zeolite acidity proves too aggressive for specific feedstock blends.
- Hydrotreating Catalysts:Sulfided base metal sulfides on alumina supports remove sulfur and nitrogen ahead of cracking stages, protecting downstream zeolite integrity.
Volume sits with Zeolites; growth tilts toward Transition Metals.
Application:
Process intensity and product slate requirements segment demand across downstream value chains.
- Petroleum Refining:Residue upgrading units in Middle Eastern refineries convert vacuum residue into middle distillates, lifting demand for hydrocracking catalysts with tailored mesoporosity distributions. Reliance Industries and Indian public-sector refiners lag global peers in conversion depth, creating retrofit demand.
- Petrochemical Production:FCC light olefin maximization drives formulation adjustments to favor propylene and ethylene yields over transportation fuels.
- Synthetic Fuel Manufacturing:Coal-to-liquids and gas-to-liquids facilities require modified acidity profiles for Fischer-Tropsch wax cracking.
- Renewable Energy:FCC units adapting to bio-oil feeds need acidity modifications that open formulation white space beyond petroleum-optimized products.
Revenue concentrates in Petroleum Refining; expansion accelerates most quickly in Renewable Energy co-processing applications.
End User:
Asset vintage and technical capabilities differentiate procurement sophistication across customer types.
- Refineries:Integrated operators with in-house reaction engineering capabilities unbundle catalyst supply from technical service contracts, displacing multi-year single-source arrangements. Independent North American refiners lead this procurement shift.
- Chemical Plants:Petrochemical crackers prioritize olefin selectivity over liquid yield, driving specialized formulation requests.
- Oil & Gas Producers:Upstream-integrated operators seek catalyst systems for field upgrading of heavy crude before pipeline injection.
- Energy Corporations:Diversified utilities exploring bio-oil co-processing require modified catalyst systems with unproven long-term regeneration performance.
Contract value aggregates at Refineries; technical service intensity peaks with Energy Corporations.
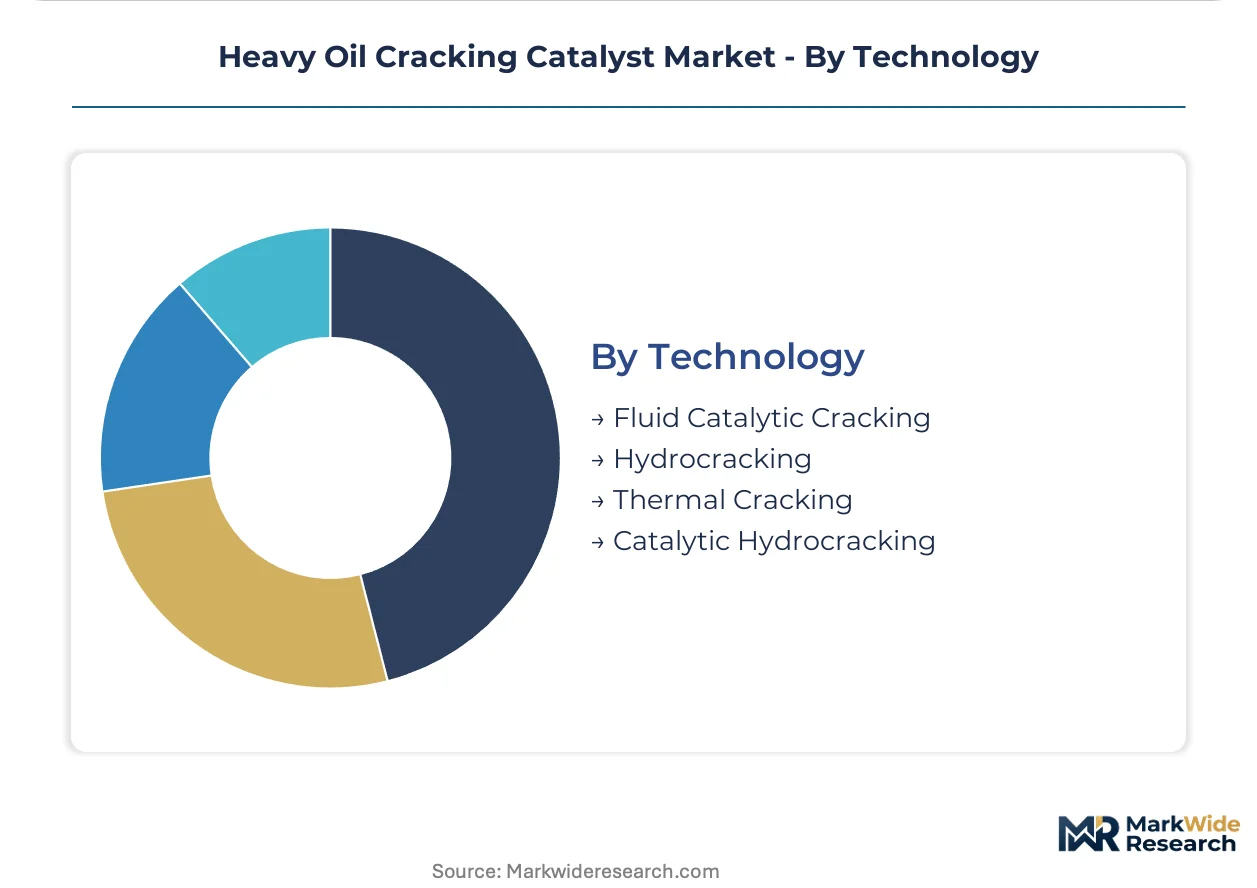
Technology:
Capital investment cycles and unit operating pressure define the technology selection envelope.
- Fluid Catalytic Cracking:Established residue upgrading integration dominates volume demand, though regenerator temperature constraints limit adoption of highest-activity formulations in legacy units.
- Hydrocracking:Premium positioning as refiners target stricter middle-distillate yields, with Middle Eastern operators installing new trains to process heavier crude slates.
- Thermal Cracking:Coking and visbreaking technologies operate without catalysts, serving as competitive alternatives for lowest-cost residue disposal.
- Catalytic Hydrocracking:Dual-function acid and hydrogenation sites in single reactors command formulation premiums for maximum diesel production.
Installed base favors Fluid Catalytic Cracking; capacity additions favor Hydrocracking.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Saudi Arabia's Eastern Province and China's coastal petrochemical corridors concentrate new hydrocracking capacity installations. Tax incentives for residue upgrading investments are redirecting catalyst procurement flows toward these jurisdictions. Refinery clusters in Jubail and Ningbo anchor regional demand concentration.
United States
Gulf Coast refiners processing Venezuelan and Mexican heavy crudes drive metal-tolerant catalyst consumption. EPA refinery sector rules mandate regenerator emissions reductions that favor low-coke-make formulations. The Houston-Beaumont-Port Arthur corridor hosts the densest concentration of FCC unit retrofits.
China
Sinopec and independent teapot refiners upgrade residue processing units to meet GB emission benchmarks. MIIT industrial policy directs capacity expansion toward higher-conversion hydrocracking trains. The Ningbo-Zhoushan petrochemical zone anchors East China catalyst demand.
Saudi Arabia
SABIC and Aramco downstream integration projects expand vacuum residue conversion capacity. The country's national industrial regulator enforces escalating emissions standards for refinery operations. Jubail Industrial City concentrates new hydrocracking train installations.
Germany
Refiners adapt to EU F-Gas Regulation caps on process emissions through catalyst formulation upgrades. ECHA chemical registration requirements shape import specifications for zeolite-based products. The Rhine-Ruhr industrial cluster hosts residue upgrading retrofit activity.
India
Reliance Industries and public-sector refiners lag global peers in residue conversion depth, creating retrofit demand. BIS standards alignment pressures teapot operators toward catalyst system upgrades. The Jamnagar refinery complex anchors West India procurement volumes.
Heavy Oil Cracking Catalyst Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across formulation and service delivery vectors. The supplier base concentrates around integrated chemical majors with captive zeolite manufacturing and rare earth processing capabilities. Two archetypes dominate: technology licensors with embedded catalyst supply, and independent formulators competing on technical service intensity. Competitive moves center on backward integration into rare earth supply chains and geographic expansion through joint ventures in high-growth refining corridors.
Among diversified chemical conglomerates, BASF and Albemarle Corporation exemplify the integrated archetype through upstream control over critical raw material inputs. Honeywell UOP and Axens occupy positions as technology licensors with catalyst supply embedded in process licensing agreements. Sinopec represents the state-integrated national champion model, with refining operations and catalyst production under common ownership.
| Leading Market Players |
|---|
| Honeywell UOP |
| BASF |
| Shell Catalysts & Technologies |
| Axens |
| Grace |
| ExxonMobil |
| Albemarle Corporation |
| Sinopec |
| Advanced Refining Technologies |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed producers in China and Saudi Arabia anchor supply-side discipline through state-coordinated rare earth stockpiling and long-term offtake guarantees, compressing pricing power for independent formulators lacking captive upstream assets. This ownership pattern tethers catalyst pricing to geopolitical inventory releases rather than pure cost-plus mechanics.
Pricing Analysis
Short lead-time premiums dominate transaction structures, with Gulf Coast refiners absorbing surcharges for expedited metal-tolerant formulations during unplanned regenerator turnarounds. Three-tier pricing structure across premium emissions-optimized, standard residue-processing, and economy FCC-replacement levels stratifies buyer segments. Cost compression in standard-grade zeolites is intensifying because Chinese teapot refiners consolidate procurement volumes through Sinopec-aligned distributors. Independent North American refiners exhibit highest price sensitivity due to unbundled technical service contracts, while Middle Eastern national oil companies show lowest sensitivity given integrated project financing.
Supply Chain Analysis
Single-source vulnerability sits with Chinese rare earth oxide separation capacity, where lanthanum and cerium processing concentrates in Jiangxi and Inner Mongolia corridors. High-purity alumina feeds from Australian bauxite and Guinean mines, with specialty zeolite manufacturing anchored in Germany, China, and the US. Tariff exposure on finished catalyst imports into the EU and India disrupts cross-border flows from Asian formulators. Distribution runs through refinery-integrated technical service contracts and spot procurement via third-party engineering advisors, with channel control fragmenting among regional distributors in the Middle East and South Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Transition metal-enhanced Y-zeolites with tailored mesoporosity are displacing conventional silica-alumina matrices in high-vanadium feed processing, compressing replacement cycles and rewriting lifecycle economics for legacy formulation portfolios.
For Market Incumbents: Anticipate procurement unbundling by independent refiners with in-house reaction engineering capabilities, threatening integrated supply-plus-optimization revenue streams. Backward integration into rare earth oxide separation secures margin protection against Chinese export quota volatility. Channel control through embedded technical diagnostics contracts defends position against spot-purchasing intermediaries in North America. For New Entrants and Emerging Players: Teapot refiners in China's coastal provinces represent the most penetrable buyer archetype, lacking sophisticated spent catalyst analysis capabilities and dependent on supplier-provided operational adjustments. Biomass co-processing FCC units in European utilities offer formulation white space beyond petroleum-optimized products. A go-to-market angle anchored in third-party technical advisory services bypasses entrenched licensor-catalyst bundles. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap formulators with captive zeolite manufacturing and rare earth processing assets in North America, positioned for EPA emissions rule compliance premiums. Long-term viability hinges on 5-10 year residue upgrading capacity expansion in India and the Middle East. The signal to watch is hydrocracking train final investment decisions in Saudi Arabia's Jubail Industrial City and India's Jamnagar complex.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Oxide Separation | Captive lanthanum and cerium supply insulates BASF and Albemarle from Chinese export quota volatility. |
| Joint Venture in Middle East Hydrocracking Corridor | Localized production in Jubail Industrial City captures SABIC and Aramco downstream integration project demand. |
| Emissions-Optimized Formulation Launch | Low-coke-make catalysts command 8-12 percent premiums from EPA-regulated Gulf Coast refiners. |
| Long-term Supply Agreement with Independent Refiners | Multi-year contracts with spot-purchasing North American operators stabilize volume against procurement unbundling. |
| Biomass Co-processing Catalyst Development | Modified acidity profiles for bio-oil feeds open white space in EU carbon border adjustment mechanism compliance. |
Study Parameters
Document review covered SEC 10-K filings from diversified chemical conglomerates, ECHA chemical registration databases, and customs trade data on rare earth oxide imports, complemented by interviews with refinery operations managers, catalyst procurement leads at integrated oil companies, FCC unit process engineers, and technical service directors at major formulators. Bottom-up unit-level capacity data triangulated against top-down refinery throughput projections from energy agencies.
Cross-reference between historical replacement cycle patterns and expert panel input on metal-tolerant formulation adoption shaped the analytical framework across the analysis window. Segmentation dimensions modeled include zeolite type, transition metal enhancement level, application technology, and regional regulatory cluster. CAGRs derived from installed base depreciation schedules and capacity addition pipelines, with hydrocracking train commissioning timelines and FCC regenerator retrofit cycles as industry-specific forecast inputs.
Revisions become necessary when rare earth export restrictions, refinery emissions rule amendments, or unplanned residue upgrading project cancellations materialize across major demand corridors. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Asia and Middle East FCC Catalyst Market
Catalysts
Rhodium Carbon Catalyst Market
Catalysts
Europe Homogeneous Precious Metal Catalyst Market
Catalysts
Platinum-Based Catalysts Market
Catalysts
South America Refining Catalysts Market
Catalysts
Global Light Powered Catalyst Market
Catalysts
Primary Reforming Catalyst Market
Catalysts
Biodiesel Catalyst Market
Catalysts
Sulfur Guard Catalyst Market
Catalysts
Asia and Middle East Polyolefin Catalyst Market
Catalysts
Chemical Processing Catalysts Market
Catalysts
Solid Acid Catalysts Market
Catalysts
Catalyst Regeneration Market
Catalysts
Hydro-Processing Catalysts Market
Catalysts
Europe Refining Catalysts Market
Catalysts
Fluid Catalytic Cracking Catalyst Market