
 South America Refining Catalysts Market | 2026-2036
South America Refining Catalysts Market Size, Share, and Industry Trends Forecast 2026-2036
South America Refining Catalysts Market Analytics
Brazil's refinery upgrade cycle is reconfiguring procurement patterns for hydrocracking and hydrotreating catalysts across the region. Albemarle Corporation leverages its bromine-derived catalyst expertise to dominate FCC additive supply to Brazilian refiners. Haldor Topsoe A/S anchors its position through syngas and hydroprocessing technology leadership, while BASF SE competes via integrated precious metal management and catalyst recycling capabilities.
Refining catalysts are heterogeneous substances—typically comprising alumina, zeolite, or metal oxide supports impregnated with cobalt, molybdenum, nickel, or platinum group metals—that accelerate petroleum conversion reactions under high temperature and pressure conditions. These materials enable hydrodesulfurization, hydrocracking, and catalytic reforming processes that transform crude fractions into transportation fuels and petrochemical feedstocks. Hydrotreating catalysts command the largest product-type position due to universal sulfur reduction mandates, while hydrocracking catalysts represent the fastest-expanding segment as refiners seek middle-distillate yield improvement. Fixed-bed technology maintains dominant installation share given operational simplicity, though fluidized-bed systems gain traction for continuous regeneration flexibility in high-throughput units.
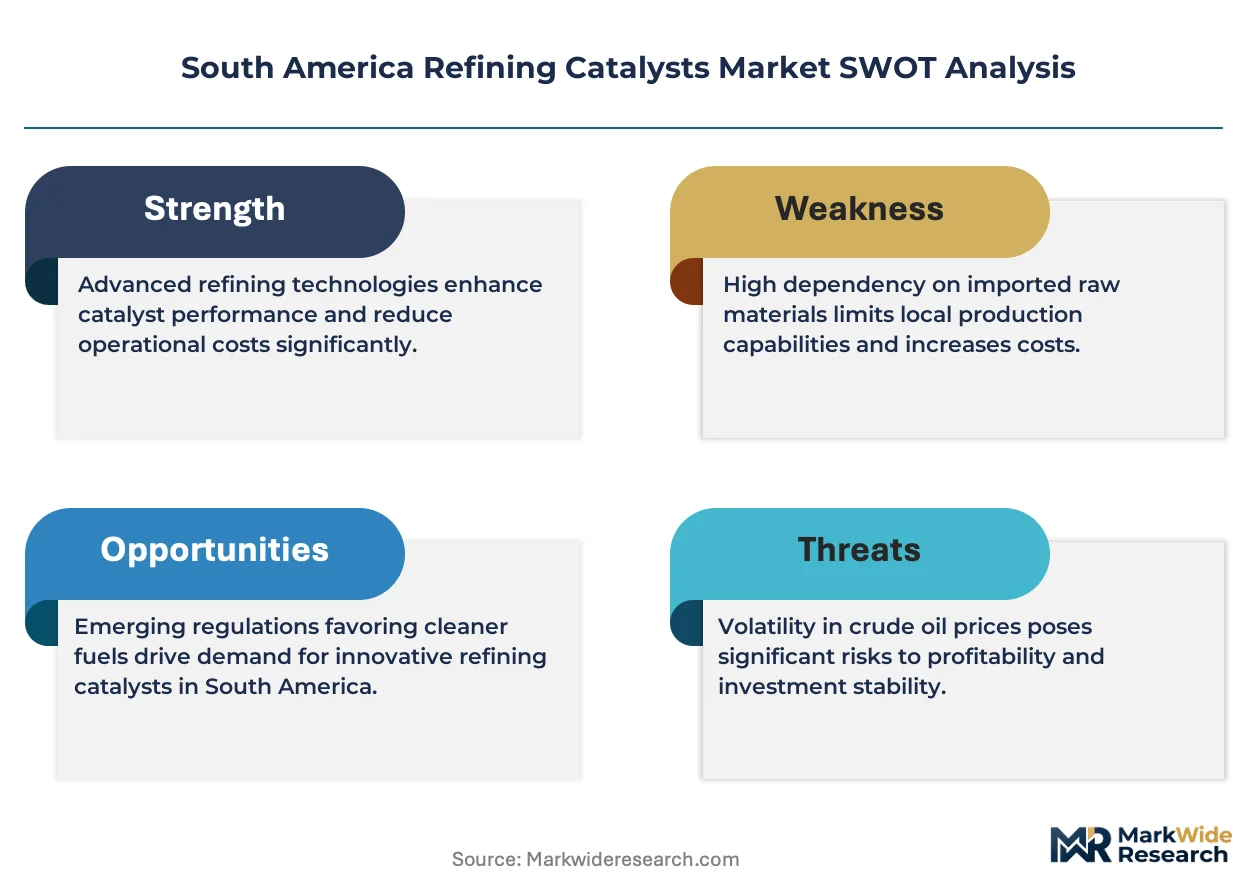
Brazil's ANP enforces sulfur content limits that directly determine catalyst replacement cycles and specification requirements for domestic refiners. Argentina's Secretariat of Energy and Chile's SEC coordinate fuel standards that align with Mercosur environmental protocols, creating cross-border compliance obligations for catalyst suppliers. Refiners must monitor how regional low-carbon fuel policies reshape catalyst performance benchmarks and procurement timelines.
Market Dynamics
Brazil's ANP sulfur mandates are compressing catalyst replacement cycles while Petrobras accelerates hydrotreater deployments across its Southeast refining cluster. This regulatory-engineering nexus is reconfiguring supplier relationships and technical specifications throughout the regional value chain.
Growth Catalysts
- ANP Resolution 784:Brazil's national petroleum agency enforces 10 ppm diesel sulfur limits that mandate continuous hydrotreating catalyst refresh cycles across Petrobras-operated facilities.
- Petrochemical integration:Refiners in Argentina's Bahía Blanca complex are expanding hydrocracking capacity to capture higher middle-distillate yields from domestic shale feedstocks.
- Zeolite formulation advances:Next-generation Y-zeolite supports with hierarchical mesoporosity enable deeper sulfur removal at lower hydrogen partial pressures.
Market Restraints
- PGM price volatility:Platinum and palladium cost swings from South African supply disruptions strain catalyst procurement budgets for reforming units.
- Single-source alumina dependency:High-purity gamma-alumina supply concentrates among three global producers, creating input vulnerability for regional catalyst manufacturers.
- Hydrogen infrastructure gaps:Limited merchant hydrogen availability in Chile's Biobío region constrains hydrotreater utilization rates at ENAP refineries.
Strategic Opportunities
- Colombia's refining revival:Ecopetrol's Cartagena and Barrancabermeja modernization programs create fresh demand for resid hydroprocessing catalysts.
- Spent catalyst regeneration:Closed-loop metal recovery services address molybdenum and cobalt reclamation under tightening Mercosur waste protocols.
- Biomass co-processing:ANP RenovaBio incentives enable hydrotreater retrofitting for renewable diesel production from soybean and animal tallow feedstocks.
Industry Challenges
- Specialized catalyst engineering talent:Shortages of hydroprocessing kinetic modelers and fixed-bed reactor designers delay unit commissioning timelines.
- Legacy refinery integration:Retrofitting 1970s-vintage atmospheric residue desulfurization units with modern high-activity catalysts requires extensive reactor internals modification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Refining Catalysts Market |
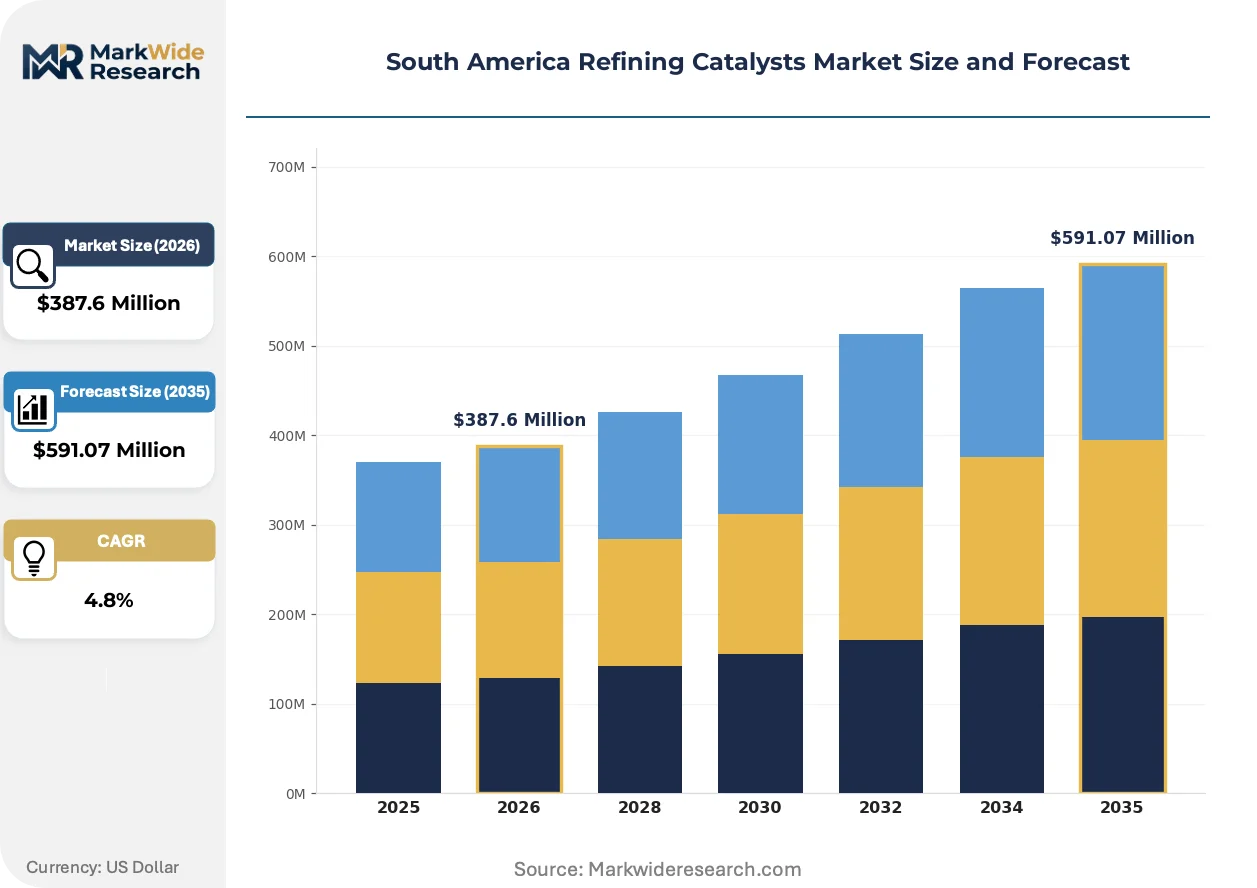
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $591.07 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrocracking Catalysts, Hydrotreating Catalysts, Reforming Catalysts, Others Application: Petrochemical Production, Fuel Production, Diesel Hydrotreater, Gasoline Production End User: Refineries, Chemical Plants, Oil Companies, Independent Refiners Technology: Fixed Bed, Fluidized Bed, Continuous Stirred Tank, Others |
| Companies Covered | BASF SE, Albemarle Corporation, Haldor Topsoe A/S, W. R. Grace & Co.-Conn., Axens, Clariant, Johnson Matthey, DuPont, Evonik Industries AG, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Refining Catalysts Market Evolving Landscape
Digital catalyst performance monitoring and advanced material architectures are compressing the gap between laboratory formulation and commercial deployment. These developments are altering how refiners specify, procure, and manage catalyst inventories across multi-year operating cycles.
Transition metal phosphide catalysts, particularly nickel phosphide supported on mesoporous alumina, deliver superior hydrodesulfurization activity at reduced hydrogen consumption. Petrobras pilot units in São Paulo state are validating these materials for ultra-low sulfur diesel production. Conventional cobalt-molybdenum sulfide formulations is rendering obsolete for deep desulfurization duty.
ANP's progressive sulfur reduction schedule, culminating in 10 ppm gasoline and diesel specifications, forces continuous catalyst performance upgrades. Refiners must replace hydrotreating beds more frequently to maintain compliance, shortening procurement cycles from 5-year to 3-year intervals. Brazil's Southeast industrial corridor experiences the most intense specification pressure.
Refiners are consolidating catalyst procurement under performance-based supply agreements that bundle fresh catalyst, technical service, and spent material reclamation. This displaces traditional transactional purchasing of discrete catalyst loads. Argentine operators at the Luján de Cuyo complex pioneered this model, now spreading to Brazilian facilities seeking total cost visibility.
South America Refining Catalysts Market Segmentation
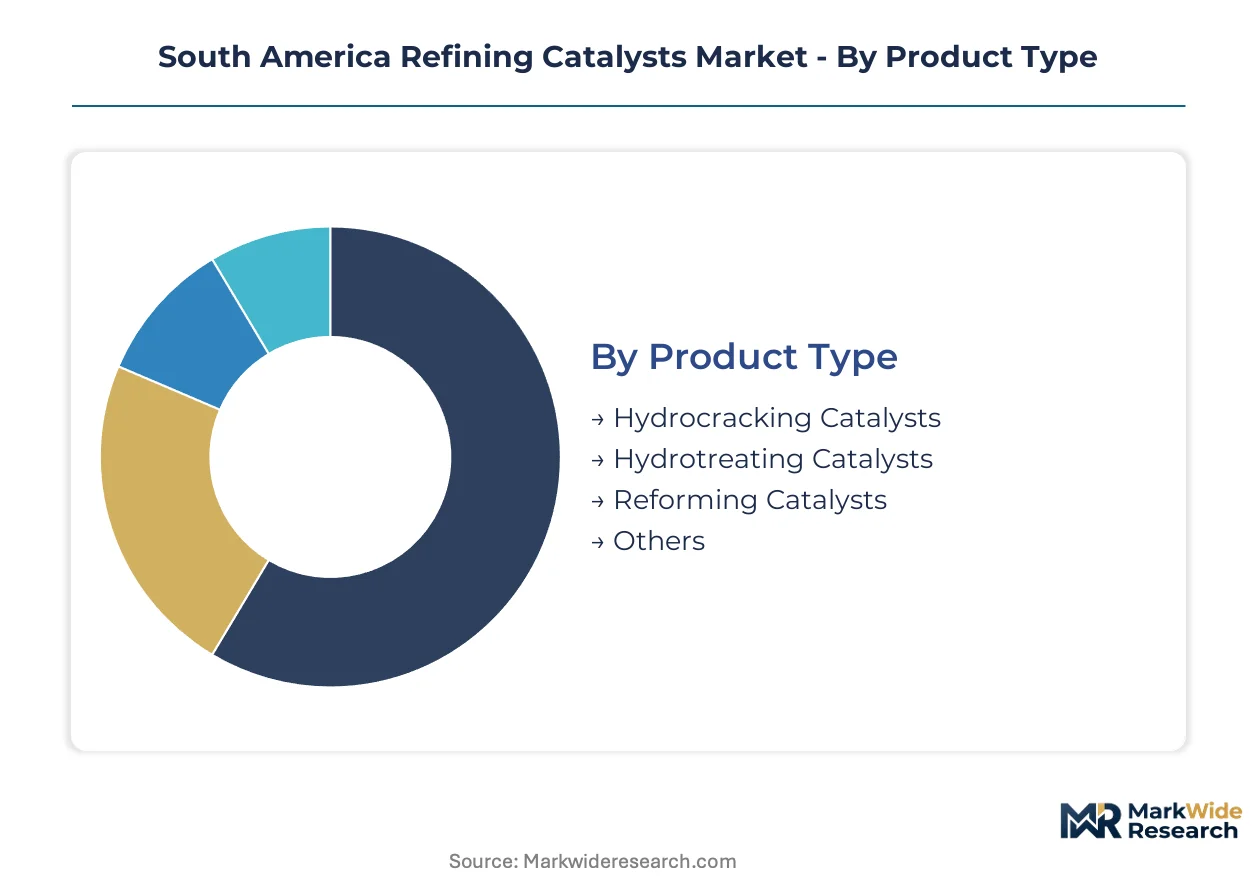
Refining catalyst procurement patterns vary sharply by replacement frequency and technical specification intensity across South America's refining base. Segment-level analysis reveals where suppliers capture recurring revenue versus one-time installation opportunities.
Product Type:
Hydrotreating catalysts turn over fastest due to ANP-mandated sulfur compliance cycles, while reforming catalysts operate on multi-year regeneration schedules.
- Hydrocracking Catalysts:Dual-function acidic zeolite supports combined with noble metal hydrogenation sites crack heavy vacuum gas oil into diesel and naphtha. Argentina's Bahía Blanca refiners deploy these for Vaca Muerta shale conversion, driving replacement every 4-5 years under high-severity operation.
- Hydrotreating Catalysts:Cobalt-molybdenum or nickel-molybdenum sulfide active phases on alumina supports remove sulfur, nitrogen, and metals from distillate streams. Petrobras Southeast refineries refresh these beds every 2-3 years to maintain 10 ppm diesel compliance, creating the region's most predictable demand stream.
- Reforming Catalysts:Platinum-rhenium or platinum-tin bimetallic formulations on chlorided alumina convert naphtha to high-octane aromatics. Regeneration cycles extend catalyst life to 7-10 years at Brazilian catalytic reformers.
- Others:FCC additives, alkylation catalysts, and isomerization materials serve specialized process units with sporadic procurement timing.
Hydrotreating Catalysts anchors the volume base while Hydrocracking Catalysts gains share at the steepest rate.
Application:
Fuel-focused applications dominate procurement spend due to ANP transport fuel mandates, while petrochemical integration creates premium specification demand.
- Fuel Production:Catalysts for gasoline, diesel, and jet fuel manufacturing face the strictest regulatory performance thresholds. Brazil's Southeast corridor concentrates procurement for ultra-low sulfur road fuels.
- Diesel Hydrotreater:Dedicated deep desulfurization units process cracked and straight-run diesel fractions. ANP Resolution 784 compliance forces continuous catalyst refresh at Petrobras facilities.
- Petrochemical Production:High-purity aromatics and olefins manufacturing requires specialized reforming and steam cracking catalysts. Argentina's petrochemical complexes drive regional demand for these premium formulations.
- Gasoline Production:Catalytic reforming and isomerization catalysts upgrade naphtha octane for finished gasoline blending. Chile's ENAP refineries prioritize these applications for domestic motor fuel supply.
Fuel Production anchors the volume base while Petrochemical Production commands the highest margin tier.
End User:
National oil company refineries operate on systematic catalyst replacement programs, while independent operators respond opportunistically to spot market conditions.
- Refineries:Integrated downstream complexes with dedicated hydrotreating, hydrocracking, and reforming units. Brazil's Petrobras-operated facilities maintain the region's largest standing catalyst inventories.
- Oil Companies:Vertically integrated majors with proprietary technical specifications and preferred supplier relationships. These entities negotiate multi-year performance-based supply agreements.
- Chemical Plants:Petrochemical producers consuming catalysts for feedstock preparation and derivative manufacturing. Argentina's Bahía Blanca cluster represents the primary regional concentration.
- Independent Refiners:Smaller, non-integrated processors purchasing catalysts on transactional terms. These operators delay replacement cycles when margins compress.
Refineries anchors the volume base while Chemical Plants expand procurement most quickly amid regional petrochemical buildout.
Technology:
Fixed-bed simplicity dominates existing installed base, though continuous regeneration systems gain traction for high-throughput units seeking operational flexibility.
- Fixed Bed:Packed catalyst beds in vertical reactors with periodic shutdown for replacement or regeneration. The technology commands dominant share across South America's mature refining infrastructure due to lower capital intensity and operational familiarity.
- Fluidized Bed:Catalyst particles suspended in upward-flowing hydrocarbon vapor enable continuous regeneration and temperature control. Petrobras FCC units and select reforming applications deploy this architecture for throughput optimization.
- Continuous Stirred Tank:Mechanically agitated slurry reactors for specialized hydroprocessing applications. Limited regional deployment concentrates in pilot-scale and demonstration units.
- Others:Ebullated-bed and moving-bed configurations for resid processing and specific hydrocracking duties.
Fixed Bed anchors the volume base while Fluidized Bed captures new installation preference at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Trans-Andean pipeline network and Brazil's Southeast industrial corridor anchor refining catalyst demand across South America. These infrastructure assets concentrate hydrotreating and hydrocracking procurement in coastal refining clusters tied to Atlantic shipping lanes.
Brazil
Petrobras operates the region's largest catalyst consumption base through its Southeast refining cluster. ANP Resolution 784 mandates 10 ppm diesel sulfur limits that compress replacement cycles to 2-3 years. The São Paulo state refining complex drives continuous hydrotreater refresh demand for ultra-low sulfur fuel compliance.
Argentina
Vaca Muerta shale development is expanding hydrocracking capacity at Bahía Blanca refineries. The Secretariat of Energy coordinates fuel standards with Mercosur environmental protocols. The Luján de Cuyo complex pioneered performance-based catalyst supply agreements now spreading regionally.
Chile
ENAP refineries in the Biobío region face hydrogen infrastructure constraints that limit hydrotreater utilization. SEC fuel-quality mandates align with cross-border Mercosur compliance obligations. The Concón refinery cluster concentrates procurement for catalytic reforming and isomerization applications.
Colombia
Ecopetrol's Cartagena and Barrancabermeja modernization programs generate resid hydroprocessing catalyst demand. The national oil company's upgrade cycle targets middle-distillate yield improvement from heavy crude fractions. The Caribbean coast refining corridor attracts supplier technical service investments.
South America Refining Catalysts Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the supply architecture. The South America refining catalysts market structures around a consolidated top tier with long-term technical service relationships and a fragmented base of regional distributors. Three archetypes dominate: integrated precious metal managers, zeolite formulation specialists, and hydroprocessing technology licensors. Competitive moves concentrate on performance-based supply contracts and spent catalyst metal recovery services.
Among European-based chemical conglomerates, BASF SE and Clariant occupy positions emphasizing integrated material management and catalyst recycling capabilities. Johnson Matthey represents the precious metal management archetype through its platinum group metal stewardship. Albemarle Corporation anchors the specialty chemicals tier with bromine-derived catalyst expertise. These entities exemplify how supplier relationships reconfigure around bundled technical service and closed-loop reclamation obligations.
| Leading Market Players |
|---|
| BASF SE |
| Albemarle Corporation |
| Haldor Topsoe A/S |
| W. R. Grace & Co.-Conn. |
| Axens |
| Clariant |
| Johnson Matthey |
| DuPont |
| Evonik Industries AG |
| Others |
Value Network & Pricing Analysis
Single-source gamma-alumina dependency concentrates pricing power among three global producers while compressing procurement flexibility for regional catalyst manufacturers. ANP sulfur mandates accelerate replacement cycles, forcing Brazilian refiners to absorb premium pricing for high-activity hydrotreating formulations without alternative supplier leverage.
Pricing Analysis
Volume-discount tiering structures separate multi-year performance-based contracts from transactional spot purchases. Pricing stratifies across premium high-activity formulations, standard cobalt-molybdenum sulfide grades, and economy regenerated catalyst tiers. Cost compression in standard hydrotreating grades is intensifying because Petrobras consolidates procurement under bundled technical service agreements. Independent refiners exhibit highest price sensitivity, deferring replacement cycles during margin compression, while national oil companies prioritize specification compliance over unit cost.
Supply Chain Analysis
Upstream feedstock supply for catalyst precursors draws from South African platinum group metal mines, Chinese rare earth processing facilities, and German specialty chemical manufacturers. High-purity alumina feeds from North American and European calcination plants, while zeolite synthesis concentrates in Chinese and Dutch production hubs. Single-source vulnerability in PGM supply creates procurement risk exposure for Brazilian reforming unit operators. Distribution runs through integrated supplier technical service teams co-located at major refining clusters rather than arm's-length distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South America refining catalysts market rewards specialized hydroprocessing kinetic modeling capabilities that remain scarce across the regional talent pool. Engineering firms capable of bridging laboratory formulation validation with commercial reactor commissioning command disproportionate supplier influence.
For Market Incumbents: Build technical service moats by embedding process engineering teams at Petrobras Southeast refineries and securing exclusive spent catalyst metal reclamation rights under Mercosur waste protocols. Defend against emerging transition metal phosphide substitutes by accelerating pilot-to-commercial validation timelines. Capacity addition in Colombia's Caribbean coast corridor captures Ecopetrol modernization demand before competitor technical service deployment. For New Entrants and Emerging Players: Pursue white-space opportunities in Argentina's Vaca Muerta shale hydrocracking catalyst specifications where incumbent technical relationships remain underdeveloped. Target Chile's Biobío region hydrogen-constrained hydrotreater optimization niche requiring specialized low-pressure formulation expertise. Lead with performance-guaranteed pilot unit trials to overcome refiner risk aversion toward unproven suppliers. For Investors and Strategic Acquirers: The market sits at a regulatory-compression phase that favors integrated precious metal stewards with closed-loop reclamation infrastructure. Long-term viability across the analysis window rests on securing cobalt and molybdenum supply agreements independent of South African PGM volatility. Acquisition target archetype: regional catalyst regeneration specialists with ANP-certified waste handling permits. The signal to watch is ANP adoption of renewable diesel co-processing specifications that would retrofit hydrotreater catalyst demand profiles.| Strategic Initiative | Industry Significance |
|---|---|
| Performance-Based Supply Contract Consolidation | Petrobras bundles catalyst, technical service, and metal recovery under single-source agreements displacing transactional purchasing. |
| Spent Catalyst Regeneration Infrastructure | Closed-loop molybdenum and cobalt reclamation addresses tightening Mercosur environmental compliance obligations. |
| Transition Metal Phosphide Validation | Nickel phosphide formulations at São Paulo pilot units promise reduced hydrogen consumption for ultra-low sulfur diesel production. |
| Hydroprocessing Talent Acquisition | Specialized fixed-bed reactor designers and kinetic modelers accelerate commissioning timelines for legacy unit retrofits. |
| Biomass Co-Processing Retrofit | ANP RenovaBio incentives enable hydrotreater adaptation for renewable diesel from soybean and tallow feedstocks. |
Research Methodology
Initial hypotheses were tested against primary input from hydroprocessing unit managers at Petrobras and Ecopetrol facilities, catalyst procurement leads at Argentine petrochemical complexes, and technical directors at regional supplier engineering teams, then refined through secondary validation. Trade data from Brazilian and Colombian customs authorities, ANP regulatory filings, SEC disclosures from listed catalyst manufacturers, and Mercosur environmental protocol documents anchored supply-side assessment. Bottom-up catalyst consumption estimates by refinery unit were triangulated against top-down market value reconstruction.
Demand-supply-balance framing anchored the analytical approach across the projection horizon. Segmentation dimensions modeled include product type tier, application severity, end-user procurement structure, and reactor technology architecture. CAGRs were derived from replacement cycle compression under ANP Resolution 784 and capacity expansion timelines at Bahía Blanca and Cartagena refining complexes. Industry-specific inputs incorporated hydrogen availability constraints in Chile's Biobío region and Vaca Muerta shale quality variation affecting hydrocracking catalyst specification.
Macroeconomic conditions sit as an overlay; deviation in crude price differentials, Brazilian real exchange rates, or South African PGM supply disruptions would shift the trajectory. Forecasts reflect documented assumptions regarding ANP regulatory enforcement continuity and Petrobras capital allocation priorities. Material shifts in Mercosur environmental protocol adoption timelines or breakthrough commercialization of non-sulfide hydrotreating catalysts would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Heavy Oil Cracking Catalyst Market
Catalysts
Petrochemical Catalyst Market
Catalysts
Fuel Cell Catalyst Market
Catalysts
Polymer Catalyst Market
Catalysts
BDO Synthesis Catalyst Market
Catalysts
Emission Control Catalyst for Marine Market
Catalysts
Refining Catalysts Market
Catalysts
Stationary Catalytic Systems Market
Catalysts
Marine Selective Catalytic Reduction Systems Market
Catalysts
Polyolefin Catalyst Market
Catalysts
North America Industrial Catalyst Market
Catalysts
Europe Refining Catalysts Market
Catalysts
Inorganic Catalyst Market
Catalysts
Biorenewable Catalysts Market
Catalysts
Hydrogenation Catalyst Market
Catalysts
Photocatalyst Market