
 Asia and Middle East Polyolefin Catalyst Market | 2026-2036
Asia and Middle East Polyolefin Catalyst Market Size, Share, and Industry Trends Forecast 2026-2036
Asia and Middle East Polyolefin Catalyst Market Outlook
Specialized polymer engineering talent is rotating away from commodity catalyst production toward advanced metallocene and single-site system development across East Asian research centers. Sinopec Catalyst Co. Ltd. leverages its captive refinery integration to dominate domestic supply chains within China. Toho Titanium Co. Ltd. anchors titanium tetrachloride precursor output for regional Ziegler-Natta manufacturers. Albemarle Corporation extends its licensing reach through technology transfer partnerships with Middle Eastern polyolefin producers seeking catalyst self-sufficiency.
Asia and Middle East polyolefin catalysts comprise transition-metal compounds—typically titanium, zirconium, or chromium supported on magnesium chloride or silica carriers—that initiate olefin polymerization at controlled molecular weights and tacticities, operating at pressures from 10 to 40 bar and temperatures between 70°C and 110°C. Ziegler-Natta systems sustain the majority of installed capacity owing to their cost efficiency in bulk-phase and slurry-phase polyethylene plants, though metallocene catalysts command premium positioning in film and automotive applications requiring narrow polydispersity. Gas-phase technology leads reactor deployments across Saudi Arabia's mega-complexes, while liquid-phase bulk polymerization dominates South Korean and Japanese polypropylene operations.
China's MIIT enforces GB standards for catalyst residue limits in food-contact plastics, compelling domestic producers to upgrade purification protocols or lose packaging sector contracts. REACH-aligned substance registrations from European importers affect catalyst precursor trade flows into Middle Eastern free zones, where SAMR-equivalent conformity assessments are gaining traction among Chinese equipment exporters. Japan's METI coordinates JIS standard harmonization with ASEAN technical committees, smoothing cross-border qualification timelines for catalyst suppliers. Stakeholders must track how Saudi Arabia's downstream localization mandates and India's PLI scheme for chemicals alter the geographic calculus for new catalyst manufacturing investments.
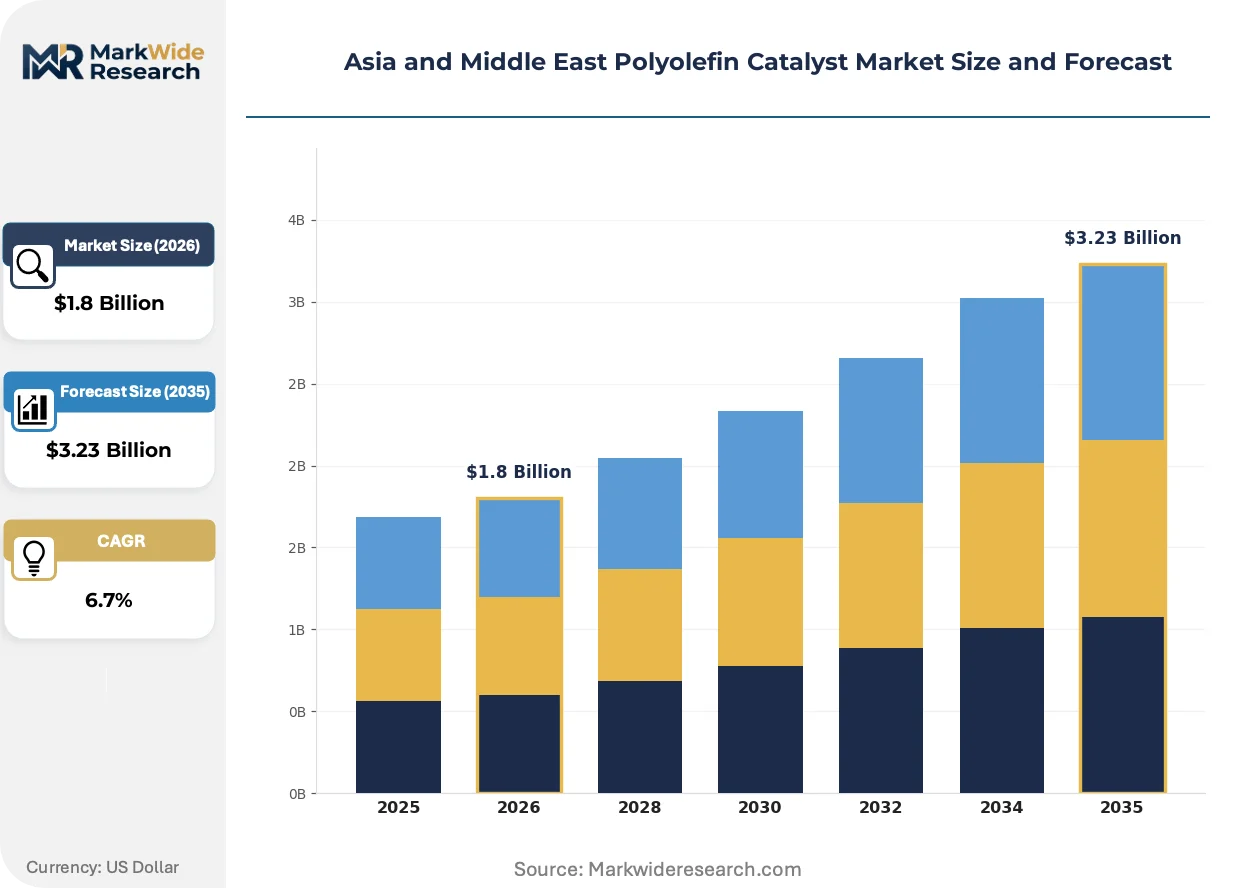
Market Dynamics
China's dual carbon goals and Saudi Arabia's downstream diversification policies are redirecting capital toward higher-activity catalyst systems, compressing the window for legacy Ziegler-Natta producers to upgrade before demand shifts decisively toward metallocene-grade output.
Growth Catalysts
- India's PLI scheme for chemicals:Production-linked incentives are accelerating petrochemical corridor development near Gujarat and Maharashtra, creating captive demand for advanced polymerization catalysts.
- Metallocene-grade polyethylene procurement:Packaging sector buyers across Southeast Asia are expanding orders for narrow polydispersity resins, pulling catalyst suppliers toward single-site system capacity.
- Saudi downstream localization mandates:Domestic content requirements are forcing technology transfer partnerships that build regional catalyst self-sufficiency and reduce import dependency.
Market Restraints
- Titanium tetrachloride supply concentration:Precursor output remains anchored to Japanese and Chinese chlor-alkali complexes, exposing regional manufacturers to input volatility and logistics bottlenecks.
- GB standards for catalyst residue limits:China's MIIT-enforced food-contact plastic regulations compel costly purification protocol upgrades, squeezing margin for domestic producers lacking integrated refining.
- Gas-phase reactor lock-in:Saudi Arabia's mega-complexes operate at scale efficiencies that resist retrofit to liquid-phase metallocene systems, delaying technology transitions.
Strategic Opportunities
- ASEAN technical committee harmonization:Japan's METI-coordinated JIS standard alignment is smoothing cross-border qualification timelines for catalyst suppliers entering Vietnam and Indonesia.
- REACH-aligned substance registrations:European importer compliance requirements are creating premium positioning for Middle Eastern free zone producers with pre-certified precursor supply chains.
- Automotive lightweighting applications:Narrow polydispersity polypropylene demand from electric vehicle battery housing manufacturers in South Korea is opening specialty catalyst service contracts.
Industry Challenges
- Specialized polymer engineering talent rotation:Research centers across East Asia are losing commodity catalyst expertise to advanced metallocene and single-site system development, creating knowledge gaps in legacy plant support.
- SAMR-equivalent conformity assessments:Chinese equipment exporters to Middle Eastern free zones face divergent certification timelines that delay catalyst delivery schedules and compress project windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia and Middle East Polyolefin Catalyst Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ziegler-Natta, Metallocene, Chromium, Others Technology: Gas Phase, Bulk Phase, Slurry Phase, Liquid Phase Application: Bottles, Films, Pipes, Automotive Parts End User: Packaging, Consumer Goods, Automotive, Construction |
| Companies Covered | Sinopec Catalyst Co. Ltd., Toho Titanium Co. Ltd., Mitsubishi Chemical Corporation, Mitsui Chemicals Inc., Japan Polypropylene Corporation, Clariant AG, Albemarle Corporation, INEOS Capital Limited, W. R. Grace and Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia and Middle East Polyolefin Catalyst Market Strategic Shifts
Active bifurcation between commodity and specialty catalyst production is reshaping competitive positioning across the Asia and Middle East polyolefin catalyst market, with technology licensing models and supply chain configurations diverging along performance-tier lines.
Metallocene catalyst technology is bifurcating the installed base between bulk-phase polyethylene plants and film-grade operations requiring precise molecular weight control. Automotive and flexible packaging buyers in South Korea and Japan are adopting single-site systems at accelerated procurement cycles. This technological divide is compressing margins for Ziegler-Natta producers without integrated metallocene R&D pipelines while enabling premium pricing for narrow polydispersity specialists.
REACH-aligned substance registration requirements from European importers are altering catalyst precursor trade flows into Middle Eastern free zones. Producers without pre-certified supply chains face exclusion from premium contract tiers. Chinese equipment exporters are responding by accelerating SAMR-equivalent conformity assessments to maintain access to Saudi and UAE petrochemical complexes.
Buyer concentration among Southeast Asian packaging conglomerates is consolidating procurement authority and compressing supplier qualification timelines. Direct technical service relationships are displacing distributor-mediated catalyst supply in Thailand and Vietnam. This channel shift is most visible in metallocene-grade polyethylene procurement, where end-users demand formulation support that legacy trading structures cannot deliver.
Asia and Middle East Polyolefin Catalyst Market Segmentation
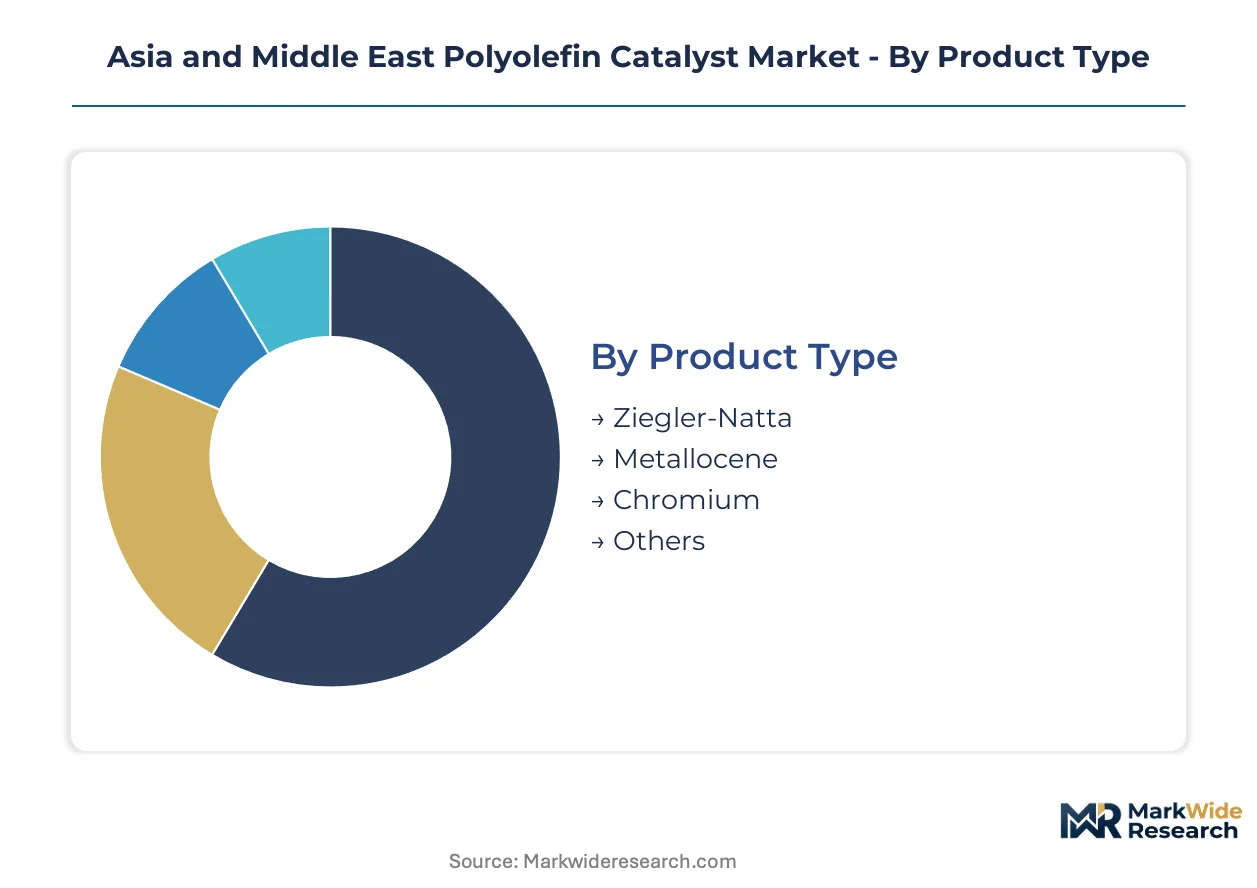
Polyolefin catalyst segmentation across Asia and the Middle East reflects divergent regulatory pressures on residue limits, reactor technology lock-ins at Saudi mega-complexes, and shifting procurement patterns among Southeast Asian packaging conglomerates. Understanding these category boundaries enables suppliers to align R&D pipelines with the specific performance tiers commanding premium positioning.
Product Type:
MIIT-enforced GB standards for catalyst residue limits in food-contact plastics create divergent compliance burdens across product categories, forcing domestic Chinese producers toward higher-purity systems while legacy manufacturers face margin compression.
- Ziegler-Natta:Titanium-based systems supported on magnesium chloride carriers dominate installed capacity across bulk-phase polyethylene plants. Demand concentrates most visibly in India's Gujarat and Maharashtra petrochemical corridors, where cost efficiency outweighs narrow polydispersity requirements for commodity packaging applications.
- Metallocene:Single-site zirconium catalysts enable precise molecular weight control for film-grade operations. Procurement from Southeast Asian packaging buyers is expanding most quickly in Thailand and Vietnam, pulled by flexible packaging applications requiring superior optical clarity and seal strength.
- Chromium:Silica-supported Phillips-type systems sustain high-density polyethylene output at Saudi gas-phase mega-complexes. Downstream localization mandates are accelerating technology transfer partnerships for regional self-sufficiency.
- Others:Post-metallocene and hybrid systems occupy niche positions in South Korean automotive lightweighting applications. Electric vehicle battery housing manufacturers in Busan and Ulsan are piloting these catalysts for narrow polydispersity polypropylene.
Established volume favors Ziegler-Natta; emerging adoption favors Metallocene.
Technology:
Reactor configuration determines catalyst selection through operating pressure and temperature windows, with gas-phase systems at 10-40 bar creating distinct formulation requirements from liquid-phase bulk polymerization.
- Gas Phase:Fluidized-bed reactors operating at 70-110°C dominate Saudi Arabia's mega-complexes. Scale efficiencies at Yanbu and Jubail resist retrofit to alternative systems, locking in specific catalyst morphologies.
- Bulk Phase:Liquid propylene serves as both monomer and diluent in South Korean and Japanese polypropylene operations. SK Innovation and Lotte Chemical facilities in Ulsan anchor regional demand for high-activity Ziegler-Natta systems.
- Slurry Phase:Diluent-based polyethylene production persists at legacy Chinese installations. Sinopec's captive refinery integration enables cost-competitive operation despite lower activity coefficients.
- Liquid Phase:Homogeneous polymerization systems enable metallocene-grade output with precise tacticity control. Japanese research centers in Osaka and Nagoya are advancing single-site formulations for this reactor class.
Gas Phase commands current capacity share; Liquid Phase is climbing the fastest on metallocene conversion.
Application:
End-use performance specifications dictate molecular weight distribution requirements, with food-contact regulations from China's SAMR and Japan's MHLW imposing distinct purity thresholds across application categories.
- Bottles:Blow-molded HDPE and PP containers require balanced stiffness and impact resistance. Chinese dairy and beverage packaging producers near Shanghai are upgrading to metallocene-grade resins for thinner-wall designs.
- Films:Cast and blown polyethylene films demand narrow polydispersity for optical properties and seal performance. Thai and Vietnamese flexible packaging converters are consolidating procurement authority around direct technical service relationships.
- Pipes:Pressure-rated PE100 and PE80 compounds for infrastructure use prioritize creep resistance over clarity. India's Jal Jeevan Mission water supply programs are driving pipe-grade resin demand in Gujarat extrusion clusters.
- Automotive Parts:Interior and under-hood polypropylene applications require heat resistance and dimensional stability. South Korean electric vehicle manufacturers are specifying narrow polydispersity grades for battery housing components.
Films attract the steepest technology upgrade trajectory; Pipes sustain stable replacement demand.
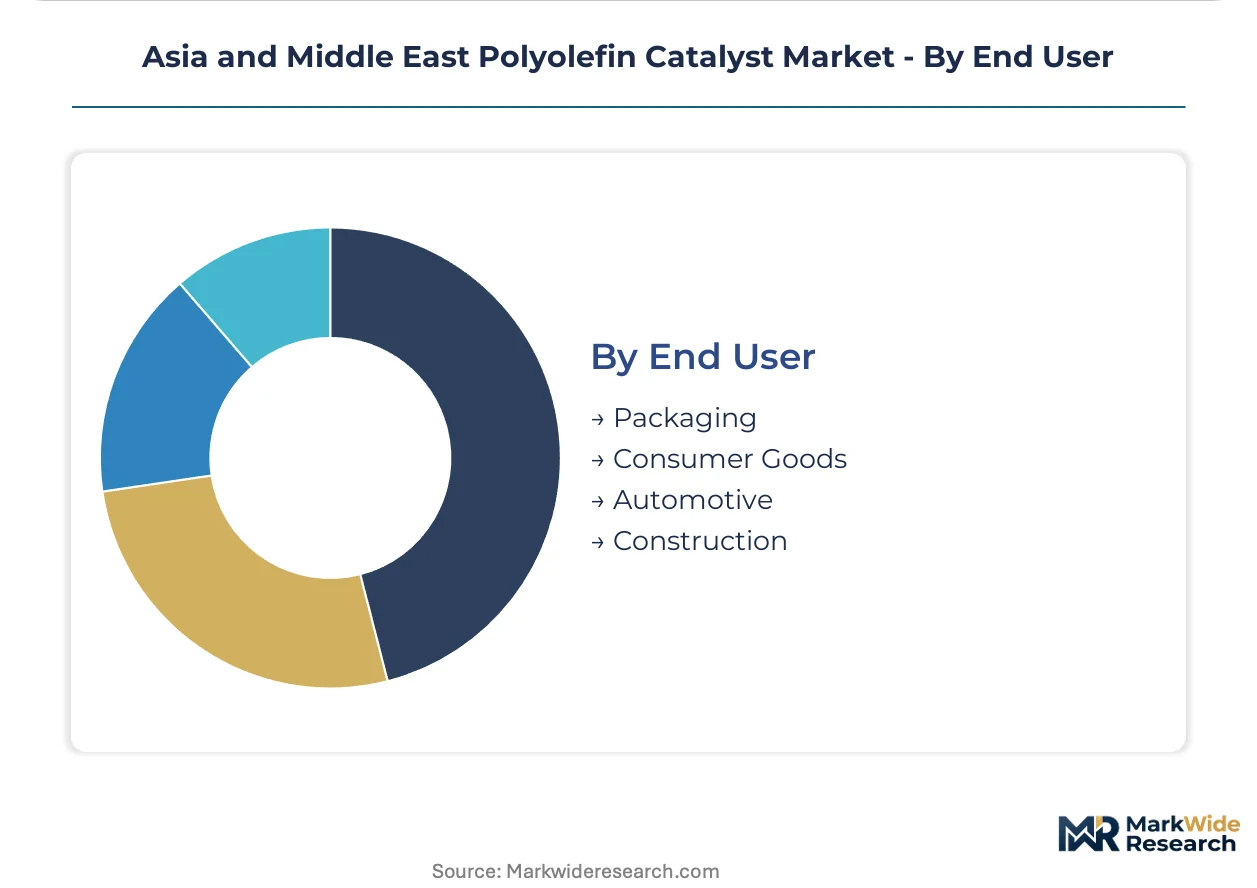
End User:
Customer concentration patterns vary sharply across sectors, with packaging conglomerates consolidating procurement authority while automotive buyers fragment across tiered supplier tiers.
- Packaging:Flexible and rigid packaging converters represent the largest catalyst consumption segment. Southeast Asian buyers in Thailand, Vietnam, and Indonesia are displacing distributor-mediated supply with direct technical partnerships.
- Consumer Goods:Durable household products and personal care packaging sustain steady Ziegler-Natta demand. Chinese domestic brands are upgrading to GB-compliant catalyst systems for export market access.
- Automotive:Electric vehicle lightweighting programs in South Korea and Japan are creating specialty catalyst service contracts. Battery housing and interior panel specifications favor narrow polydispersity polypropylene.
- Construction:Pipe, geomembrane, and insulation applications prioritize cost efficiency over performance premiums. Saudi infrastructure spending and India's urban water projects sustain regional demand.
Packaging dominates procurement scale; Automotive offers the fastest margin expansion potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT-enforced GB standards for catalyst residue limits in food-contact plastics anchor China's regulatory influence across the Asia and Middle East polyolefin catalyst market, redirecting capital toward higher-purity systems while compressing margins for legacy producers lacking integrated refining capabilities.
China
Sinopec's captive refinery integration dominates domestic supply chains for Ziegler-Natta systems, while Yangtze River Delta packaging producers upgrade to metallocene-grade resins for thinner-wall dairy and beverage containers. Dual carbon goals from Beijing are accelerating technology transitions toward higher-activity catalyst systems. Shanghai and Ningbo clusters concentrate the fastest procurement expansion for narrow polydispersity polyethylene.
Saudi Arabia
Downstream localization mandates are forcing technology transfer partnerships that build regional catalyst self-sufficiency and reduce import dependency. Gas-phase mega-complexes at Yanbu and Jubail operate at scale efficiencies that resist retrofit to liquid-phase metallocene systems. SFDA-aligned conformity assessments are gaining traction among equipment exporters seeking access to petrochemical corridors.
India
PLI scheme incentives for chemicals are accelerating petrochemical corridor development near Gujarat and Maharashtra, creating captive demand for advanced polymerization catalysts. Jal Jeevan Mission water supply programs are driving pipe-grade resin demand in Gujarat extrusion clusters. BIS standards for infrastructure applications are tightening quality thresholds for pressure-rated PE100 compounds.
Japan
METI-coordinated JIS standard harmonization with ASEAN technical committees is smoothing cross-border qualification timelines for catalyst suppliers entering Vietnam and Indonesia. Osaka and Nagoya research centers are advancing single-site formulations for liquid-phase reactor classes. Toho Titanium anchors titanium tetrachloride precursor output for regional Ziegler-Natta manufacturers.
South Korea
Electric vehicle battery housing manufacturers in Busan and Ulsan are specifying narrow polydispersity polypropylene grades, opening specialty catalyst service contracts. SK Innovation and Lotte Chemical facilities in Ulsan anchor regional demand for high-activity Ziegler-Natta systems. MFDS-aligned substance registrations are creating premium positioning for producers with pre-certified precursor supply chains.
Asia and Middle East Polyolefin Catalyst Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Asia and Middle East polyolefin catalyst market, with consolidated domestic champions leveraging captive refinery integration against specialized technology licensors commanding premium positioning through proprietary formulations. The vendor base separates into three strategic tiers: integrated petrochemical conglomerates with backward control over precursor supply, independent catalyst specialists focused on single-site system development, and technology licensors extracting value through know-how transfer partnerships. Dominant competitive moves center on strategic partnerships for regional manufacturing localization and portfolio diversification toward metallocene-grade capacity.
Among Japanese and Chinese fabricators, Toho Titanium Co. Ltd., Sinopec Catalyst Co. Ltd., and Mitsubishi Chemical Corporation occupy positions spanning precursor supply through finished catalyst formulation. Toho Titanium exemplifies the specialized precursor tier anchoring regional chlor-alkali integration. Sinopec Catalyst represents the vertically integrated archetype leveraging captive refinery economics. Mitsubishi Chemical sits within the diversified chemical conglomerate tier with cross-polymer technology capabilities.
| Leading Market Players |
|---|
| Sinopec Catalyst Co. Ltd. |
| Toho Titanium Co. Ltd. |
| Mitsubishi Chemical Corporation |
| Mitsui Chemicals Inc. |
| Japan Polypropylene Corporation |
| Clariant AG |
| Albemarle Corporation |
| INEOS Capital Limited |
| W. R. Grace and Company |
| Others |
Value Chain & Pricing Dynamics
Scale efficiencies at Saudi gas-phase mega-complexes anchor regional price floors, compressing margins for smaller liquid-phase operators in South Korea and Japan while concentrating procurement leverage among Southeast Asian packaging conglomerates. This structural asymmetry rewards backward-integrated producers with captive titanium tetrachloride supply and penalizes merchant catalyst manufacturers exposed to precursor volatility.
Pricing Analysis
Price spreads between Chinese domestic supply and Middle Eastern import tiers reflect purification protocol costs imposed by MIIT-enforced GB standards for food-contact plastics. Three-tier pricing structure across premium metallocene, standard Ziegler-Natta, and economy slurry-grade systems differentiates by certification level and volume scale. Pricing pressure stems from India's PLI scheme accelerating domestic capacity buildout. Packaging converters in Thailand and Vietnam exhibit highest price sensitivity, while South Korean automotive buyers prioritize performance premiums over unit economics.
Supply Chain Analysis
Strategic stockpiling of titanium tetrachloride precursors dominates Japanese and Chinese chlor-alkali operations, contrasting with just-in-time catalyst formulation at Middle Eastern free zone processors. Supply concentrates in China, Japan, and Saudi Arabia, with precursor output anchored to coastal chlor-alkali complexes. Raw material dependencies span titanium tetrachloride, magnesium chloride carriers, and silica supports. Single-source vulnerability from Toho Titanium's regional precursor dominance creates chokepoint exposure. Distribution runs through direct technical service relationships displacing distributor channels in Thailand and Vietnam.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent catalyst producers face substitution pressure from bio-based polymer alternatives and recycled content mandates, requiring defensive portfolio repositioning before technology lock-in hardens around metallocene-grade specifications.
For Market Incumbents: Secure captive precursor supply through backward integration into chlor-alkali operations or long-term offtake agreements with Toho Titanium, defending against margin compression from GB standard compliance costs. Accelerate metallocene R&D pipelines to offset Ziegler-Natta demand erosion in Southeast Asian packaging procurement. Channel control through direct technical service relationships in Vietnam and Indonesia represents the priority defensive lever.
For New Entrants and Emerging Players: Anchor in India's Gujarat petrochemical corridor, where PLI scheme incentives and Jal Jeevan Mission pipe demand create white-space for high-activity Ziegler-Natta supply without incumbent technology lock-in. Target post-metallocene hybrid systems for South Korean electric vehicle battery housing applications, where formulation partnerships with SK Innovation and Lotte Chemical enable specification-driven entry. Licensing partnerships with Japanese research centers in Osaka and Nagoya offer the most penetrable go-to-market angle.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among technology licensors with royalty-bearing partnerships across Saudi downstream localization mandates, where transfer agreements generate sustained income streams independent of commodity catalyst cycles. Long-term viability favors acquisition targets with metallocene-grade certification and pre-registered REACH-aligned substance portfolios. Watch for inflection when Saudi SFDA-aligned conformity assessments accelerate technology transfer timelines, signaling regional self-sufficiency tipping points.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Captive titanium tetrachloride production insulates Sinopec from Japanese chlor-alkali volatility. |
| Technology Licensing Partnership | Albemarle's know-how transfers build Saudi catalyst self-sufficiency under downstream localization mandates. |
| Metallocene R&D Pipeline Expansion | Japanese research centers in Osaka advance single-site formulations for liquid-phase reactor classes. |
| Direct Technical Service Deployment | Channel shift in Thailand and Vietnam displaces distributor-mediated supply with formulation partnerships. |
| REACH-Aligned Substance Registration | Pre-certified Middle Eastern free zone producers capture premium contract tiers from European importers. |
Study Parameters
A spread of perspectives from catalyst plant managers, polyolefin procurement leads at packaging converters, technical R&D directors at petrochemical complexes, and distribution channel partners converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through customs/trade data, SEC filings from listed chemical conglomerates, and technical standards documentation from METI and MIIT. Bottom-up capacity and utilization estimates triangulated against top-down demand projections from end-use sector analysis.
Segmentation dimensions modeled span catalyst product type, reactor technology configuration, application performance tier, and end-user concentration patterns across the analysis window. CAGRs derived from regression against historical capacity additions, feedstock cost trajectories, and regulatory compliance cost curves. Industry-specific forecast inputs include Saudi downstream localization mandate implementation pace and India's PLI scheme disbursement schedules.
Decision-makers should treat outputs as directional under assumptions of sustained dual carbon policy enforcement in China and continued Saudi technology transfer appetite; material deviation would warrant model refresh. Revision becomes warranted when metallocene conversion rates in Southeast Asian packaging procurement cross threshold acceleration points or when titanium tetrachloride supply disruptions exceed historical volatility bands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Catalyst for Hydrogen Production from Water Electrolysis Market
Catalysts
Petrochemical Catalyst Market
Catalysts
Europe PGM Catalyst Market
Catalysts
Global Emission Control Catalyst (ECC) Market
Catalysts
Sulfur Guard Catalyst Market
Catalysts
Stationary Catalytic Systems Market
Catalysts
Industrial Catalyst Market
Catalysts
CO2 Reforming Catalysts Market
Catalysts
Refining Catalysts Market
Catalysts
Asia-Pacific Refining Catalysts Market
Catalysts
Hydro-Processing Catalysts Market
Catalysts
North America Zeolite Market
Catalysts
Steam Methane Reforming Market
Catalysts
Primary Reforming Catalyst Market
Catalysts
Stationary Emission Control Catalyst Market
Catalysts
Europe Homogeneous Precious Metal Catalyst Market