
 Solid Acid Catalysts Market | 2026-2036
Solid Acid Catalysts Market Size, Share, and Industry Trends Forecast 2026-2036
Solid Acid Catalysts Market Analytics
Performance-guaranteed catalyst regeneration services is realigning how solid acid catalysts get sold, shifting contracts from unit volumes to guaranteed throughput outcomes. Clariant leverages its integrated catalyst-recycling infrastructure across European and North American refineries to capture recurring revenue streams. BASF anchors its position through proprietary zeolite manufacturing scale at Ludwigshafen, while Evonik Industries specializes in high-purity ion exchange resins for pharmaceutical alkylation processes.
Solid acid catalysts are heterogeneous materials with defined pore structures and surface acidity measured by Hammett acidity functions, typically synthesized through hydrothermal crystallization or sulfonation of polymeric backbones to replace corrosive liquid acids in continuous-flow reactors. Zeolites dominate petrochemical cracking applications due to their thermal stability and shape-selective micropore architectures, while sulfonic acid resins capture margin pools in fine chemicals esterification where lower temperatures reduce energy costs. Organic acid catalysts represent the fastest-growing category in biofuel production as biodiesel manufacturers seek alternatives to homogeneous base catalysts that generate wastewater treatment liabilities.
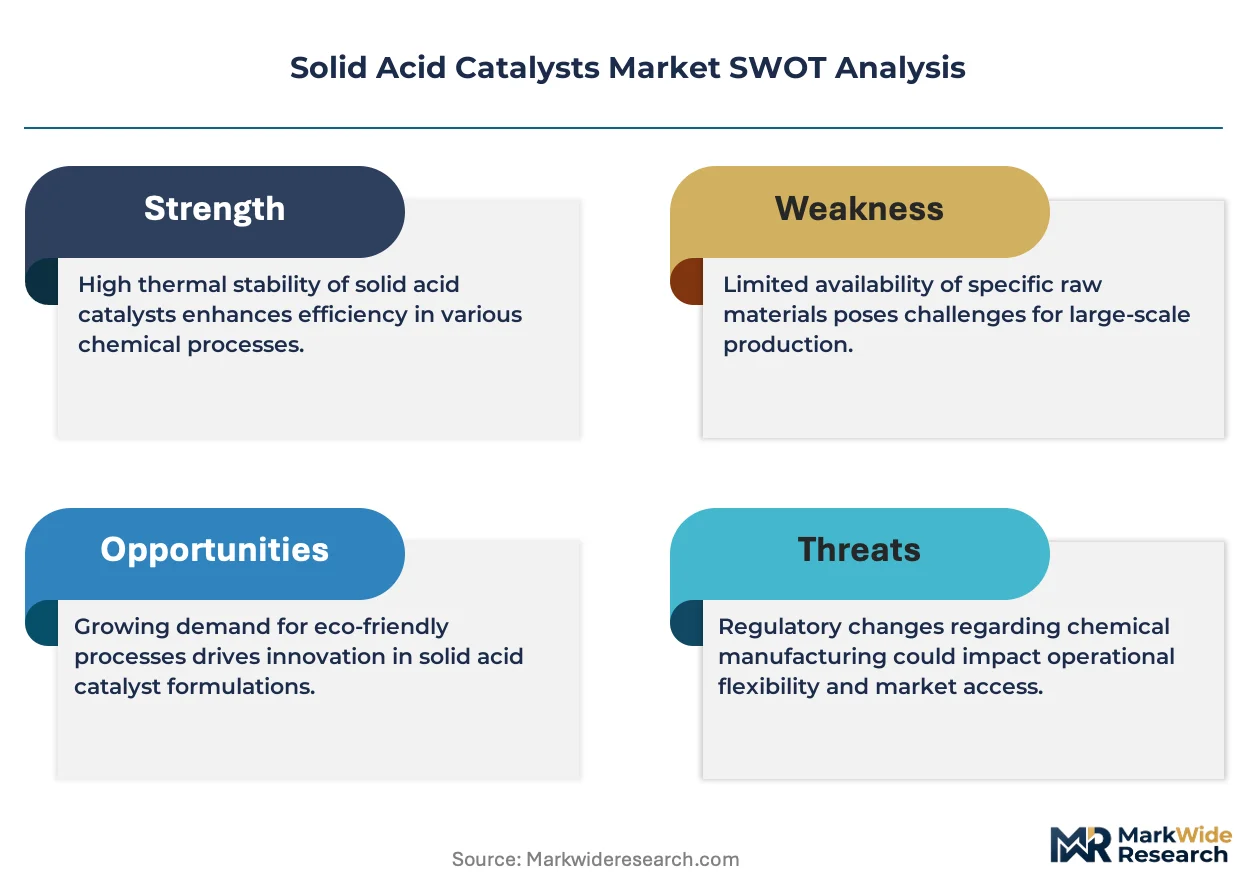
EPA renewable fuel standards and the EU Green Deal F-Gas Regulation are tightening emissions benchmarks for petrochemical and biofuel operations, directly mandating catalyst efficiency thresholds that favor solid acid systems over liquid alternatives. BIS certification requirements in India and REACH compliance in Europe further segment market access by demanding traceable catalyst composition disclosures and spent catalyst handling protocols. Stakeholders must monitor evolving carbon border adjustment mechanisms and biofuel blending mandates to anticipate which catalyst chemistries will secure offtake commitments.
Market Dynamics
EPA renewable fuel standards and EU Green Deal mandates are forcing petrochemical and biofuel producers to abandon corrosive liquid acid systems, creating procurement urgency for heterogeneous solid acid catalysts with traceable composition disclosures and regeneration protocols.
Growth Catalysts
- Biodiesel Esterification Mandates:EPA renewable volume obligations and EU F-Gas Regulation are accelerating zeolite and sulfonic acid catalyst replacement of homogeneous base catalysts in continuous-flow biodiesel reactors.
- India PLI-Linked Biofuel Investments:Production-linked incentive schemes for ethanol and biodiesel capacity are expanding procurement of organic acid catalysts at Reliance Industries and Indian Oil refineries.
- Zeolite Thermal Stability Advantages:Shape-selective micropore architectures in hydrothermally crystallized zeolites enable higher-temperature petrochemical cracking with reduced coking versus amorphous silica-alumina alternatives.
Market Restraints
- Rare Earth Input Volatility:Lanthanum and cerium price swings in Chinese concentrate supply chains destabilize per-unit catalyst economics for fluid catalytic cracking additive manufacturers.
- REACH Compliance Friction:ECHA registration requirements for novel sulfonic acid resin compositions impose 18-24 month certification timelines that freeze formulation innovation cycles.
- Homogeneous Base Catalyst Substitution Threat:Sodium methoxide remains cost-competitive in batch biodiesel processing where wastewater treatment infrastructure already exists.
Strategic Opportunities
- Indonesia Palm Oil Biodiesel Expansion:B35 and B40 blending mandates are creating first-mover openings for solid acid catalyst suppliers in Southeast Asian esterification capacity.
- Pharmaceutical Alkylation Precision:High-purity ion exchange resin demand from CDMOs in Switzerland and Singapore offers margin pools above commodity petrochemical applications.
- Catalyst-as-a-Service Models:Performance-guaranteed regeneration contracts with European refineries are converting capex-heavy procurement into recurring revenue streams.
Industry Challenges
- Hydrothermal Crystallization Expertise Gap:Synthesis of hierarchical zeolites with controlled mesoporosity requires scarce materials science PhDs and specialized pilot-scale reactor operators.
- Spent Catalyst Handling Protocol Complexity:BIS certification in India and state-level hazardous waste rules in Gujarat and Maharashtra impose divergent logistics requirements on multinational suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solid Acid Catalysts Market |
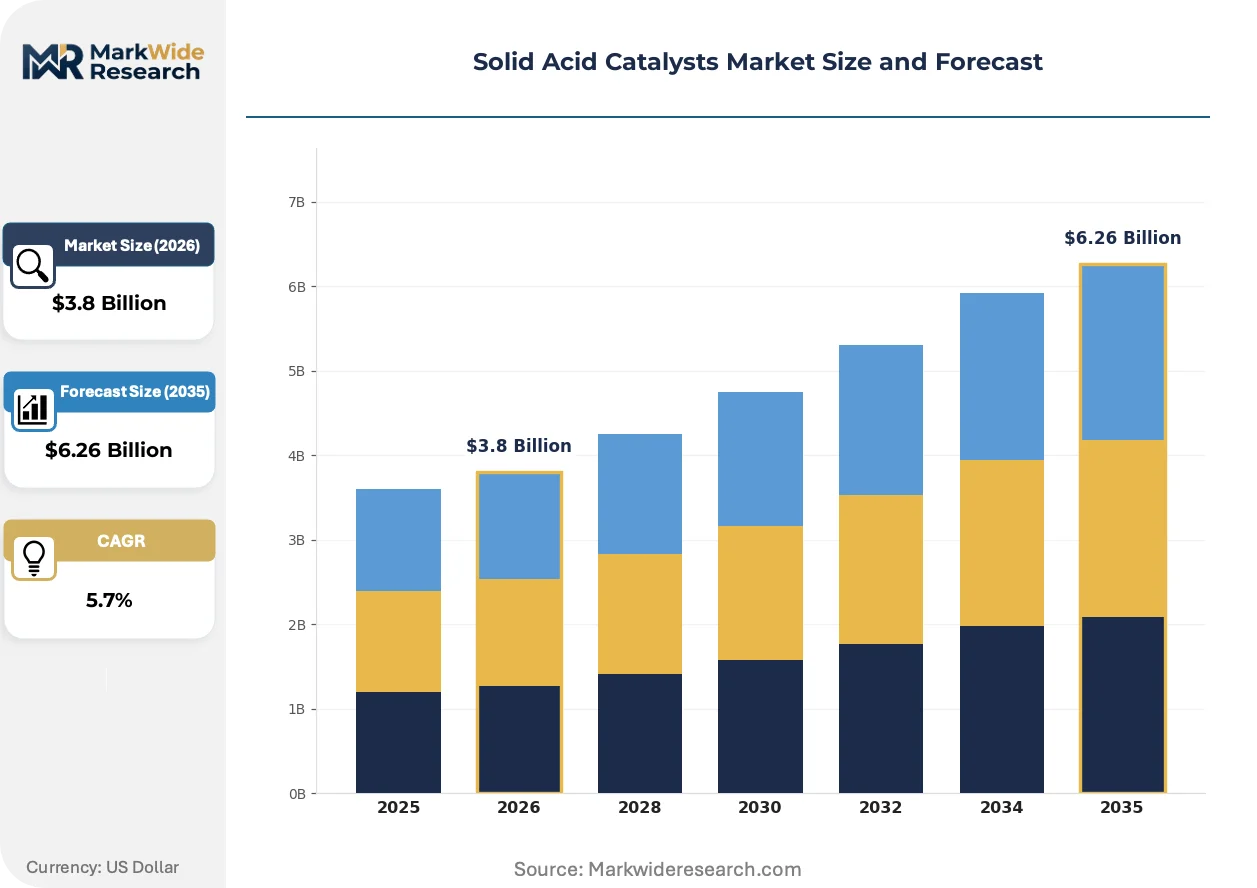
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Zeolites, Sulfonic Acid, Ion Exchange Resins, Organic Acid End User: Petrochemical Industry, Biofuels Production, Fine Chemicals, Pharmaceuticals Application: Friedel-Crafts Reaction, Esterification, Alkylation, Isomerization Technology: Absorption, Catalytic Cracking, Hydrogenation, Polymerization |
| Companies Covered | Clariant, Grace, Honeywell UOP, Evonik Industries, Albemarle, Johnson Matthey, BASF, SINOCATA, EP Minerals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solid Acid Catalysts Market Evolving Landscape
Biofuel producers are abandoning homogeneous catalysts for continuous-flow heterogeneous systems, while regulatory agencies tighten emissions benchmarks that favor regenerable solid acids. These shifts are compressing technology adoption cycles and rewiring procurement relationships across the value chain.
Organosilane-functionalized zeolites with engineered mesopore hierarchies are overtaking conventional microporous frameworks in hydrocracking applications. Reliance Industries and Sinopec are deploying these materials in revamped FCC units to process heavier residuum feeds. The structural consequence is overtaking of amorphous silica-alumina catalysts in high-severity operations where diffusional limitations previously constrained conversion yields.
EU F-Gas Regulation phase-down schedules are forcing petrochemical operators to document catalyst thermal efficiency and fluorinated byproduct formation rates. BASF and Clariant have reformulated zeolite acid site densities to meet ECHA disclosure thresholds for import authorization. Fine chemicals manufacturers in Ludwigshafen and Antwerp are now specifying Hammett acidity function ranges in procurement tenders to preempt regulatory rejection.
Refinery procurement teams are consolidating catalyst supply relationships around integrated regeneration service providers. European refiners in Rotterdam and Le Havre are bundling fresh catalyst supply with spent material recovery in multi-year throughput guarantees. This consolidation is most visible in German and Dutch petrochemical clusters where REACH compliance costs favor single-source accountability over fragmented multi-vendor arrangements.
Solid Acid Catalysts Market Segmentation
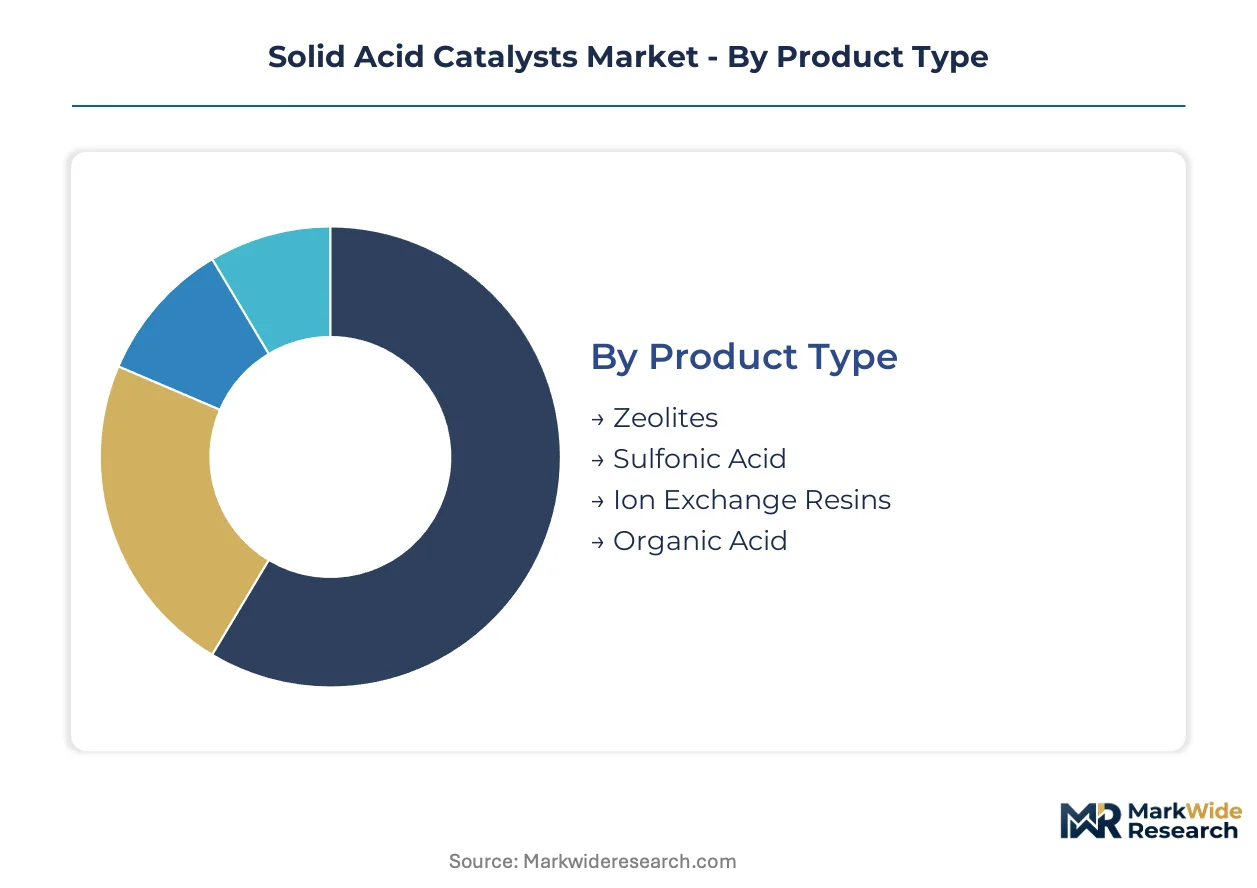
Segmentation in solid acid catalysts reveals how procurement priorities diverge across process chemistry requirements and regulatory exposure. Buyers select catalyst families based on thermal stability needs, regeneration economics, and compliance with emissions mandates in their operating geographies.
Product Type:
Zeolites command premium pricing in high-temperature operations where thermal degradation destroys organic alternatives.
- Zeolites:Hydrothermally crystallized aluminosilicates with defined micropore architectures deliver shape-selective catalysis in fluid catalytic cracking units. Demand concentrates in India and China where Reliance Industries and Sinopec are expanding residuum processing capacity under stricter EPA and EU emissions benchmarks that displace amorphous silica-alumina alternatives.
- Sulfonic Acid:Polymeric resins with anchored sulfonic acid groups enable low-temperature esterification with reduced energy intensity. Fine chemicals manufacturers in Ludwigshafen and Antwerp specify Hammett acidity function ranges in procurement tenders to satisfy ECHA disclosure thresholds under REACH and EU F-Gas Regulation phase-down schedules.
- Ion Exchange Resins:High-purity styrene-divinylbenzene matrices with controlled cross-linking densities serve pharmaceutical alkylation where trace metal contamination risks batch rejection.
- Organic Acid:Heterogeneous carboxylic acid catalysts derived from renewable feedstocks are expanding most quickly in biodiesel esterification as producers abandon homogeneous base catalysts to eliminate wastewater treatment liabilities.
Zeolites lead volumes today; organic acid catalysts are gaining share fastest.
End User:
Process scale and batch complexity determine whether buyers prioritize regeneration services or single-use economics.
- Petrochemical Industry:Integrated refineries with continuous-flow reactors demand catalysts with demonstrated thermal stability above 500°C and established regeneration protocols. Indian Oil and Reliance Industries are procuring hierarchical zeolites with engineered mesoporosity to process heavier crude slates under BIS certification requirements.
- Biofuels Production:Biodiesel manufacturers shifting from batch to continuous-flow systems require solid acid catalysts that eliminate soap formation and simplify glycerol separation. Indonesia's B35 and B40 blending mandates are creating procurement urgency for sulfonic acid resins in Southeast Asian palm oil esterification capacity.
- Fine Chemicals:Multi-product batch manufacturers value catalysts with rapid switching capability and minimal cross-contamination risk between product campaigns.
- Pharmaceuticals:CDMOs in Switzerland and Singapore specify ion exchange resins with documented trace metal profiles to satisfy Swissmedic and national pharmaceutical regulator requirements for active pharmaceutical ingredient alkylation steps.
Petrochemical industry absorbs the largest catalyst volumes; biofuels production shows the steepest expansion trajectory.
Application:
Reaction mechanism and substrate polarity dictate acid site strength requirements and pore size optimization.
- Friedel-Crafts Reaction:Electrophilic aromatic substitution demands superacidic sites with Hammett acidity functions below -12, typically delivered by zeolites with framework aluminum substitution patterns optimized for acylation and alkylation of aromatic feedstocks.
- Esterification:Carboxylic acid and alcohol coupling proceeds at lower temperatures with sulfonic acid resins, reducing energy costs in fatty acid methyl ester production for biodiesel.
- Alkylation:Isobutane-olefin coupling in gasoline upgrading requires catalysts with controlled acid site density to minimize oligomerization side reactions and extend cycle length between regenerations.
- Isomerization:Paraffin and xylene isomerization for octane enhancement and para-xylene production exploits shape-selective zeolite pore apertures that discriminate between desired and undesired isomer structures.
Esterification dominates current procurement volumes; alkylation is expanding most quickly with refinery upgrading investments.
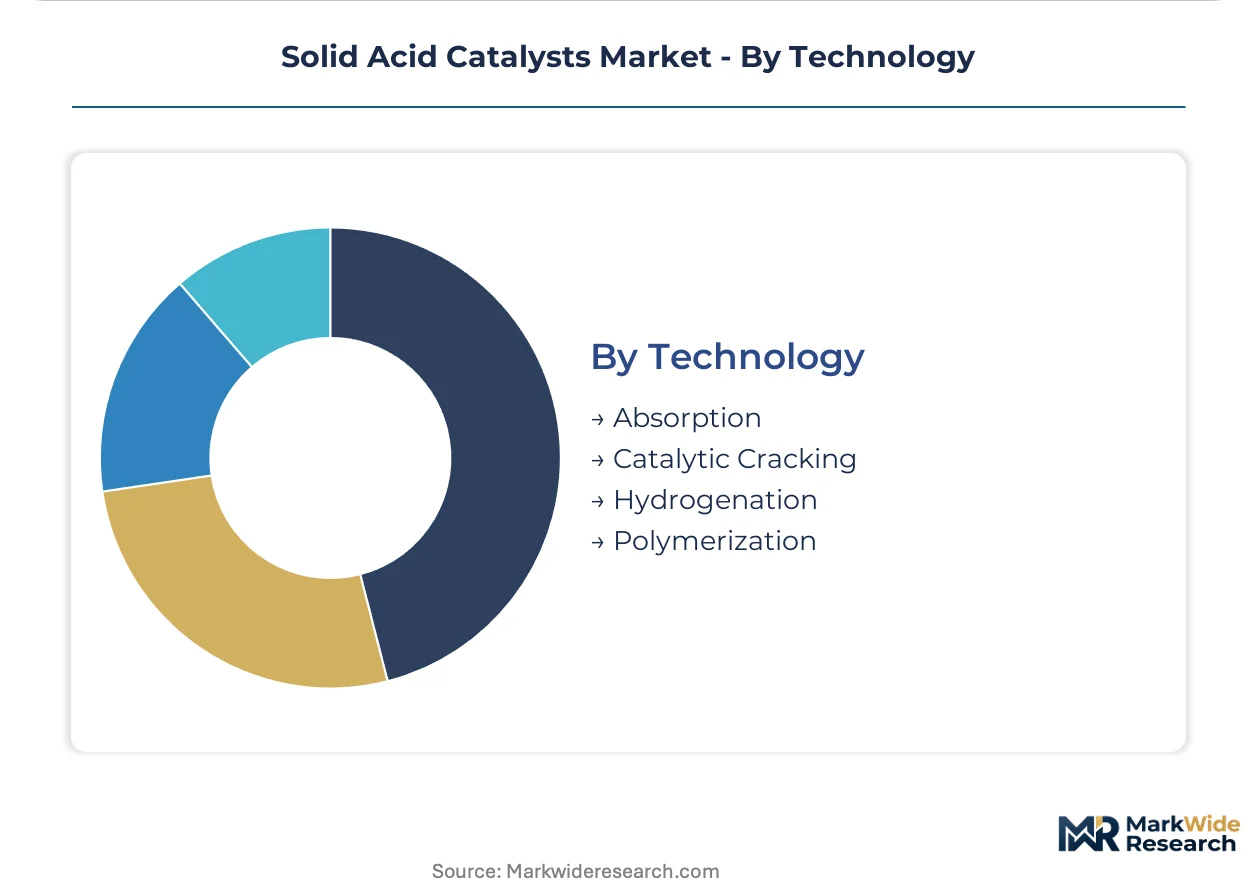
Technology:
Process integration level determines whether catalyst performance is measured by conversion per pass or by total throughput over regeneration cycles.
- Absorption:Acid site immobilization on high-surface-area supports enables gas-phase pollutant removal and reactant pre-concentration in environmental and petrochemical applications.
- Catalytic Cracking:Zeolite-based fluid catalytic cracking units process vacuum gas oil and residuum feeds to produce transportation fuels, with rare earth-stabilized Y-zeolites dominating Indian and Chinese refinery expansions.
- Hydrogenation:Bifunctional catalysts combining metal hydrogenation sites with solid acid cracking sites enable hydrocracking of heavy feeds to lighter, higher-value products.
- Polymerization:Acidic catalysts initiate cationic polymerization of isobutylene and other olefins for synthetic rubber and lubricant additive production.
Catalytic cracking generates the largest catalyst demand; hydrogenation is climbing the fastest with residuum upgrading mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's petrochemical capacity expansion outpaces India's biofuel-linked procurement, though both countries drive zeolite demand through divergent regulatory pathways. The United States and Germany anchor mature markets with regeneration-service integration, while Indonesia's palm oil biodiesel mandates create emergent esterification demand.
United States
EPA renewable volume obligations force biodiesel producers toward continuous-flow heterogeneous systems. The agency's emissions benchmarks favor solid acid catalysts with documented thermal efficiency profiles. Refinery clusters along the Gulf Coast are consolidating procurement around integrated regeneration service providers to manage spent catalyst handling under state-level hazardous waste protocols.
Germany
REACH compliance requirements and EU F-Gas Regulation phase-down schedules shape catalyst specification in Ludwigshafen and Antwerp chemical corridors. ECHA disclosure thresholds for novel sulfonic acid resin compositions impose extended certification timelines. German petrochemical operators bundle fresh catalyst supply with spent material recovery in multi-year throughput guarantees.
China
Sinopec and private refiners expand residuum processing capacity using hierarchical zeolites with engineered mesoporosity. MIIT industrial upgrading directives and dual carbon goals accelerate displacement of amorphous silica-alumina alternatives. Yangtze River Delta chemical clusters concentrate hydrothermal crystallization expertise for domestic zeolite manufacturing scale.
India
PLI-linked biofuel investments at Reliance Industries and Indian Oil expand organic acid catalyst procurement for ethanol and biodiesel capacity. BIS certification requirements demand traceable composition disclosures and spent catalyst handling protocols. Gujarat and Maharashtra state-level hazardous waste rules impose divergent logistics requirements on multinational suppliers operating in these jurisdictions.
Indonesia
B35 and B40 palm oil biodiesel blending mandates create procurement urgency for sulfonic acid resins in Southeast Asian esterification capacity. The country's national energy regulator enforces blending thresholds that eliminate homogeneous base catalyst economics. Java-based processing clusters represent first-mover openings for solid acid catalyst suppliers establishing regional service infrastructure.
Solid Acid Catalysts Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated multinational chemical conglomerates commanding petrochemical cracking applications while regional fabricators capture biodiesel esterification niches. The vendor base organizes around three archetypes: zeolite synthesis specialists with hydrothermal crystallization capabilities, sulfonic acid resin formulators serving fine chemicals precision requirements, and regeneration-service integrators converting capex-heavy procurement into recurring revenue. Capacity expansion and strategic partnerships dominate competitive moves, particularly around catalyst recycling infrastructure and palm oil biodiesel capacity in Southeast Asia.
Among European-headquartered diversified chemical conglomerates, Clariant and BASF occupy positions reflecting integrated catalyst-recycling infrastructure and proprietary zeolite manufacturing scale respectively. Evonik Industries represents the high-purity ion exchange resin specialization tier serving pharmaceutical alkylation precision requirements. SINOCATA anchors Chinese-origin supply capabilities in the regional zeolite fabrication segment.
| Leading Market Players |
|---|
| Clariant |
| Grace |
| Honeywell UOP |
| Evonik Industries |
| Albemarle |
| Johnson Matthey |
| BASF |
| SINOCATA |
| EP Minerals |
| Others |
Value Network & Pricing Analysis
Sovereign-backed Chinese producers and family-owned German mid-caps control zeolite synthesis capacity, creating divergent pricing discipline across procurement tiers. Their ownership structures tether supply behavior to long-term industrial policy goals in Beijing and Ludwigshafen, compressing margin flexibility for spot-market buyers while insulating contract customers from rare earth volatility.
Pricing Analysis
Capacity additions in China are reshaping price floors for commodity-grade zeolites while premium sulfonic acid resins hold firm. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade ion exchange resins from petrochemical cracking catalysts and biodiesel esterification grades. Price differentiation stems from REACH certification timelines and thermal stability guarantees. Cost compression in standard-tier zeolites is intensifying because Yangtze River Delta producers expanded hydrothermal crystallization output. Biofuel manufacturers exhibit highest price sensitivity; pharmaceutical CDMOs accept premium positioning for documented trace metal profiles.
Supply Chain Analysis
Freight costs from Yangtze River Delta ports to Rotterdam and Le Havre distort landed pricing for European refiners against regional regeneration alternatives. Supply concentrates in China, Germany, and India, with rare earth concentrate processing anchored in Chinese concentrate supply chains. Raw material dependencies include lanthanum, cerium, and high-purity styrene-divinylbenzene monomers. Single-source vulnerability in rare earth stabilization chemistry threatens fluid catalytic cracking additive economics. Distribution runs through integrated catalyst-recycling service contracts that bundle fresh supply with spent material recovery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory ratchet effects, with EPA renewable volume obligations and EU F-Gas Regulation phase-down schedules creating irreversible substitution demand for heterogeneous systems.
For Market Incumbents: Anchor regeneration service infrastructure in Rotterdam and Le Havre to capture recurring revenue from European refiners consolidating procurement. Deepen backward integration into rare earth concentrate processing to offset Chinese supply volatility. Defend against homogeneous base catalyst substitution in batch biodiesel processing by bundling continuous-flow reactor engineering with catalyst supply contracts. For New Entrants and Emerging Players: Engineered mesoporosity in hierarchical zeolites offers entry into residuum upgrading capacity at Sinopec and Reliance Industries. Target Indonesia's B35 and B40 palm oil biodiesel mandates for first-mover sulfonic acid resin deployment. Pursue catalyst-as-a-service contracts with Java-based processing clusters to bypass capital-intensive manufacturing scale requirements. For Investors and Strategic Acquirers: Integrated chemical conglomerates with catalyst recycling networks are the most active acquirers in this space. Long-term viability hinges on regulatory enforcement durability across multiple jurisdictions. Target mid-tier zeolite fabricators with hydrothermal crystallization expertise but limited regeneration infrastructure. Watch ECHA registration timelines for novel sulfonic acid compositions as inflection indicator for formulation innovation cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Processing | Secures lanthanum supply for fluid catalytic cracking additives against Chinese concentrate volatility. |
| Catalyst-as-a-Service Contract Expansion | Converts capex-heavy refinery procurement into recurring revenue through guaranteed throughput outcomes. |
| Pharmaceutical Alkylation Certification Investment | Captures margin pools above petrochemical applications via Swissmedic-compliant ion exchange resin supply. |
| Indonesia Biodiesel Capacity Joint Venture | Positions sulfonic acid resins for B35 and B40 palm oil esterification mandate compliance. |
| Hierarchical Zeolite R&D Partnership | Accelerates deployment of engineered mesoporosity for heavier residuum feed processing at Sinopec. |
Research Methodology
Multiple input streams — technical R&D directors at zeolite synthesis facilities, procurement leads at Indian and Chinese refineries, catalyst recycling service operators, and fine chemicals manufacturers — were reconciled against secondary validation from customs trade data, ACC and Cefic industry reports, SEC 10-K filings, and BIS certification registries. Bottom-up catalyst volume estimates from individual production facilities were triangulated with top-down petrochemical capacity expansion announcements across the analysis window.
Historical capacity utilization patterns were cross-referenced against panel input from plant managers and distribution channel partners to construct segment-level forecasts. The modeling framework spans product type, end-use industry, application chemistry, and regional regulatory cluster dimensions. CAGRs were derived from regression analysis of procurement intensity against capacity addition timelines, incorporating EPA renewable volume obligation enforcement trajectories and EU F-Gas Regulation phase-down schedules as demand drivers.
The model holds under sustained biofuel mandate enforcement and REACH certification continuity; deviation in rare earth export restrictions or homogeneous catalyst cost breakthroughs would shift trajectory. Forecasts embed assumptions about hydrothermal crystallization expertise scarcity and regeneration service infrastructure buildout rates. Stakeholders should weight assumptions against their own operating context and regulatory exposure profiles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Polyolefin Catalyst Market
Catalysts
Asia and Middle East FCC Catalyst Market
Catalysts
Emission Control Catalyst for Marine Market
Catalysts
CO2 Reforming Catalysts Market
Catalysts
Asia and Middle East Polyolefin Catalyst Market
Catalysts
Fluid Catalytic Cracking Catalyst Market
Catalysts
Stationary Catalytic Systems Market
Catalysts
Asia-Pacific Refining Catalysts Market
Catalysts
Marine Selective Catalytic Reduction Systems Market
Catalysts
Natural Zeolites Market
Catalysts
Chemical Processing Catalysts Market
Catalysts
Fuel Cell Catalyst Market
Catalysts
Hydrotreating Catalyst Market
Catalysts
Global Phase Transfer Catalyst Market
Catalysts
Residue Hydrodesulphurization Catalyst Market
Catalysts
Refinery Catalyst Market