
 Industrial Catalyst Market | 2026-2036
Industrial Catalyst Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Catalyst Market Intelligence
Modular catalyst loading and segmented reactor configurations are decoupling procurement from traditional full-reactor overhaul cycles, letting buyers swap individual bed layers rather than complete charges. BASF SE leverages its integrated catalyst and process technology portfolio to capture bundled refinery contracts. Johnson Matthey anchors its position through deep specialization in emission-control catalysts for stationary and automotive sources. Clariant AG competes by dominating the syngas and methanol catalyst segments with tailored cobalt and copper formulations.
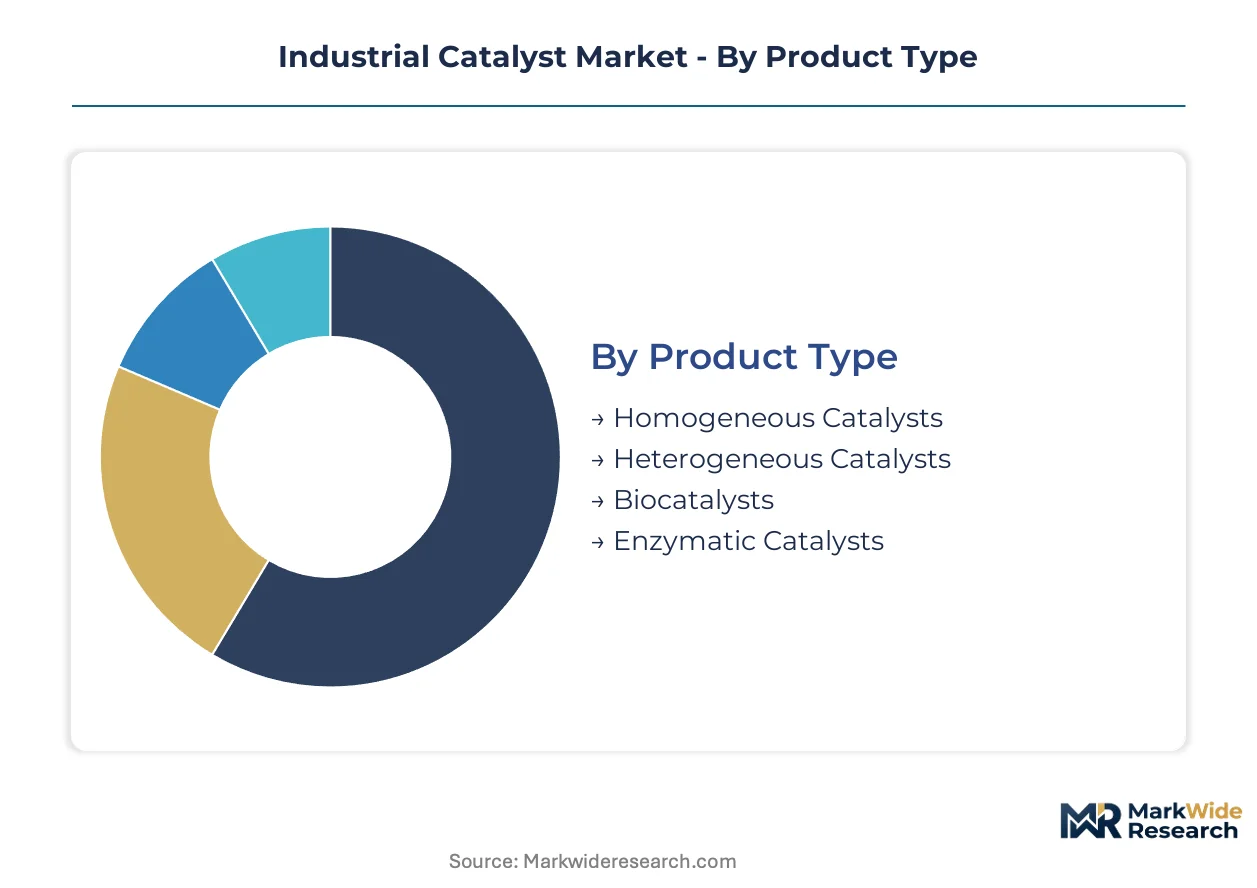
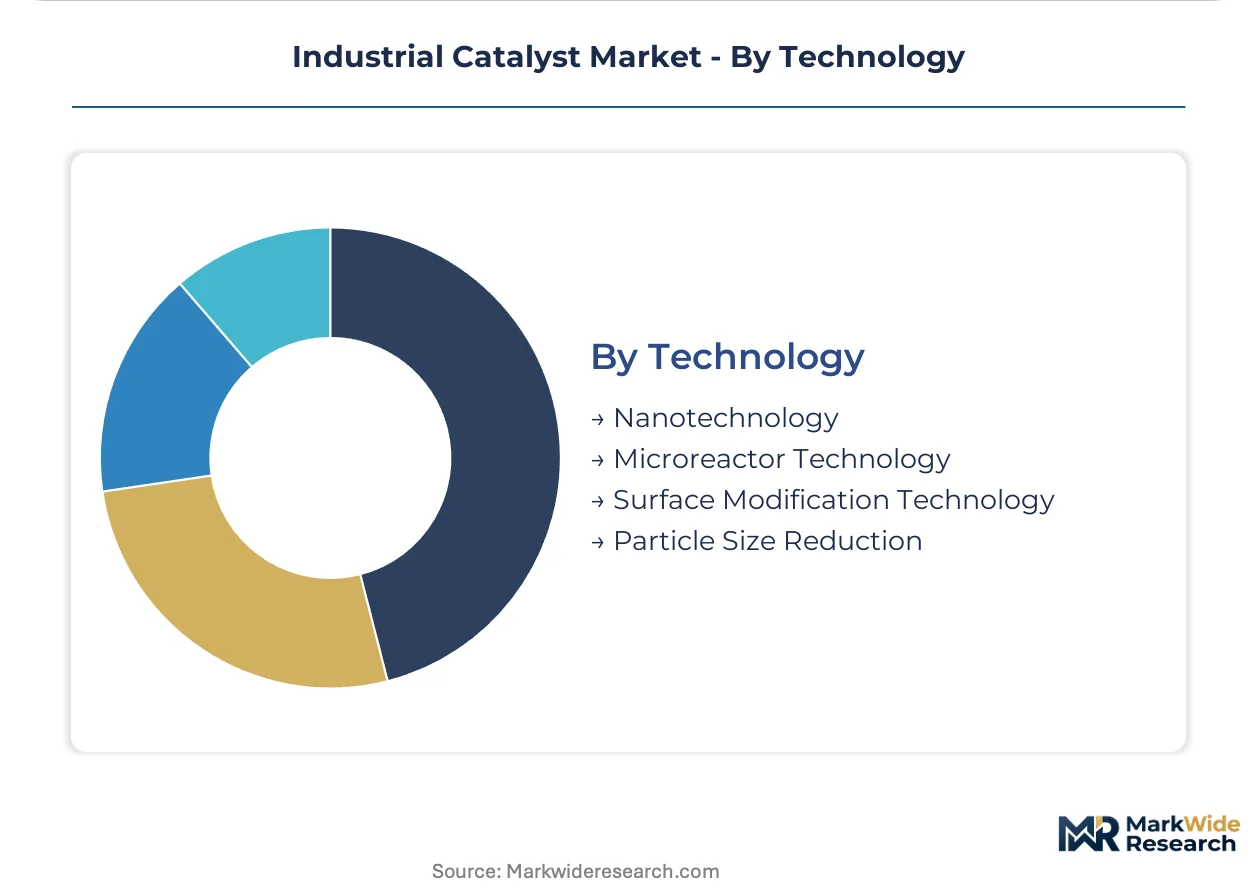
An industrial catalyst is a substance that accelerates chemical reactions without being consumed, typically composed of active metals such as platinum, palladium, nickel, or cobalt deposited on porous alumina, silica, or zeolite supports, and manufactured through impregnation, precipitation, or sol-gel methods to achieve specific surface areas and pore distributions. Heterogeneous catalysts lead the product landscape due to their ease of separation and regeneration in continuous-flow operations. Petrochemical refining commands the largest application share because fluid catalytic cracking and hydroprocessing units require constant catalyst replenishment at massive scale. Nanotechnology-enabled catalyst formulations represent the fastest-growing technology segment as atomic-level control over active-site density improves selectivity and reduces precious-metal loading.
EPA emissions standards and REACH chemical safety registrations shape formulation choices by restricting hazardous precursor chemicals and mandating lower-temperature activity to cut energy use. OSHA process safety management rules and ISO 9001 quality systems govern manufacturing plant certifications, creating compliance barriers for new entrants without established quality infrastructure. Stakeholders must monitor how evolving carbon-border adjustment mechanisms and clean-hydrogen subsidies redirect investment toward catalyst systems that enable renewable feedstock conversion rather than conventional fossil processing.
Market Dynamics
Refinery operators are extending catalyst replacement cycles to process heavier crude slates while simultaneously upgrading to higher-activity formulations to meet tightening emissions limits, creating a dual pressure on formulation suppliers to deliver durability and reactivity in single systems.
Growth Catalysts
- EPA Tier 3 and REACH compliance mandates:Refineries across the United States and European Union must install higher-activity catalyst beds to reduce sulfur and nitrogen oxide emissions, forcing systematic replacement of legacy formulations.
- China's integrated refining-chemical complex buildout:State-owned energy groups are commissioning world-scale facilities that require continuous catalyst replenishment at volumes unmatched by any other national market.
- Nanostructured zeolite frameworks:Atomic-level control over active-site density in FCC and hydrocracking units improves selectivity while lowering precious-metal loading, accelerating adoption in margin-sensitive operations.
Market Restraints
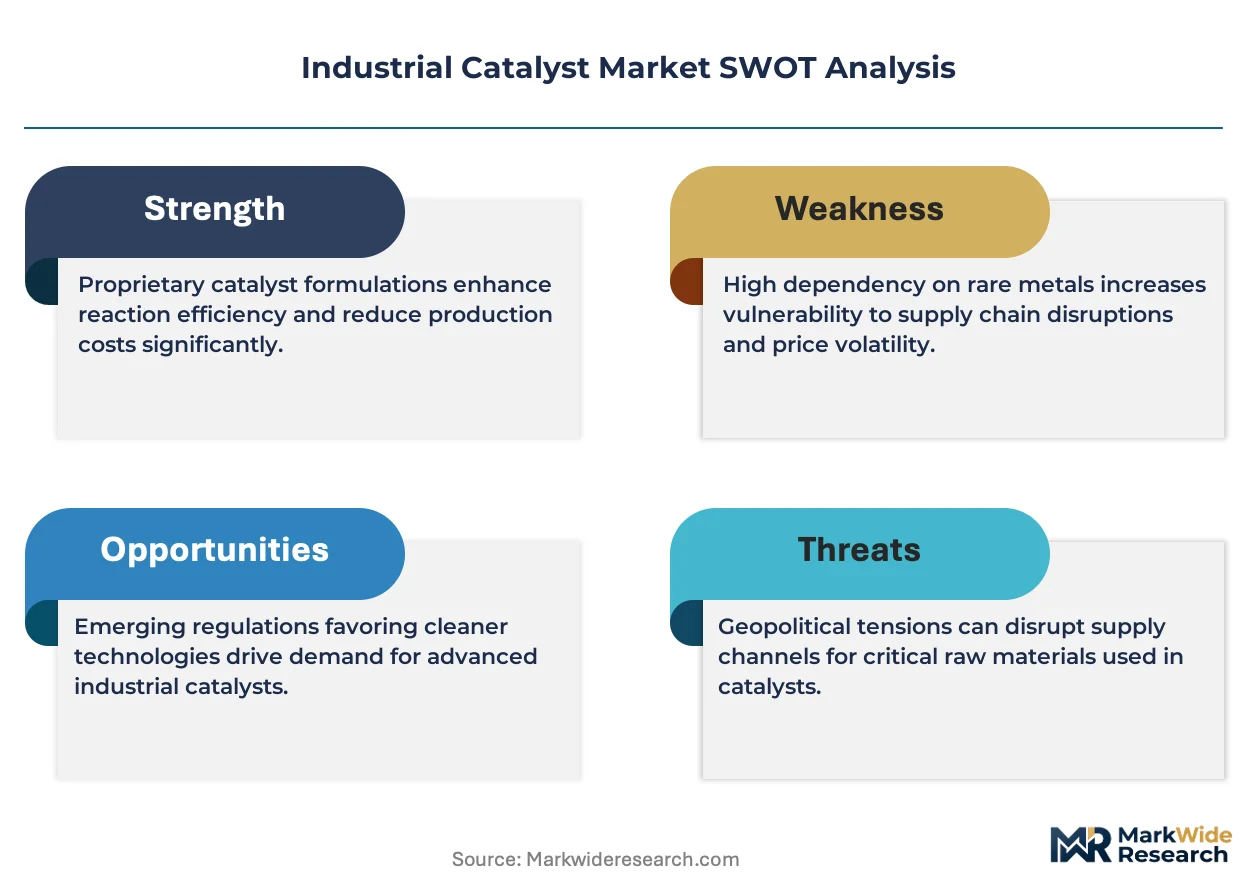
- Platinum group metal price volatility:Palladium and rhodium supply concentration in South Africa and Russia exposes catalyst manufacturers to input cost spikes that compress formulation margins.
- REACH authorization delays:Extended chemical safety review timelines for cobalt and nickel precursors block new formulation introductions for 18-36 months after laboratory validation.
- Fixed-bed regeneration limits:Sintering and metal leaching in hydroprocessing catalysts cap reuse cycles at 3-5 regenerations, forcing premature replacement versus theoretical catalyst life.
Strategic Opportunities
- India's petrochemical capacity expansion:Reliance Industries and Indian Oil are building refinery-chemical integration units that will require dedicated catalyst supply partnerships with localized technical service.
- Biomass-to-chemicals conversion:Pyrolysis oil upgrading and lignin depolymerization catalysts represent greenfield application space with no incumbent formulation suppliers.
- EU Green Deal hydrogen subsidies:Electrolysis and blue hydrogen production incentives are redirecting R&D budgets toward catalyst systems that enable renewable feedstock conversion rather than fossil processing.
Industry Challenges
- Computational catalysis talent scarcity:The intersection of density functional theory modeling and reactor engineering requires PhD-level specialists that formulation houses struggle to recruit from academic programs.
- ISO 9001 and OSHA PSM certification timelines:New manufacturing facilities face 12-18 month qualification periods before supplying major refinery operators, delaying revenue generation.
- Legacy refinery reactor incompatibility:Drop-in replacement of next-generation catalysts requires custom sizing and density matching to existing distributor designs, complicating technical sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Catalyst Market |
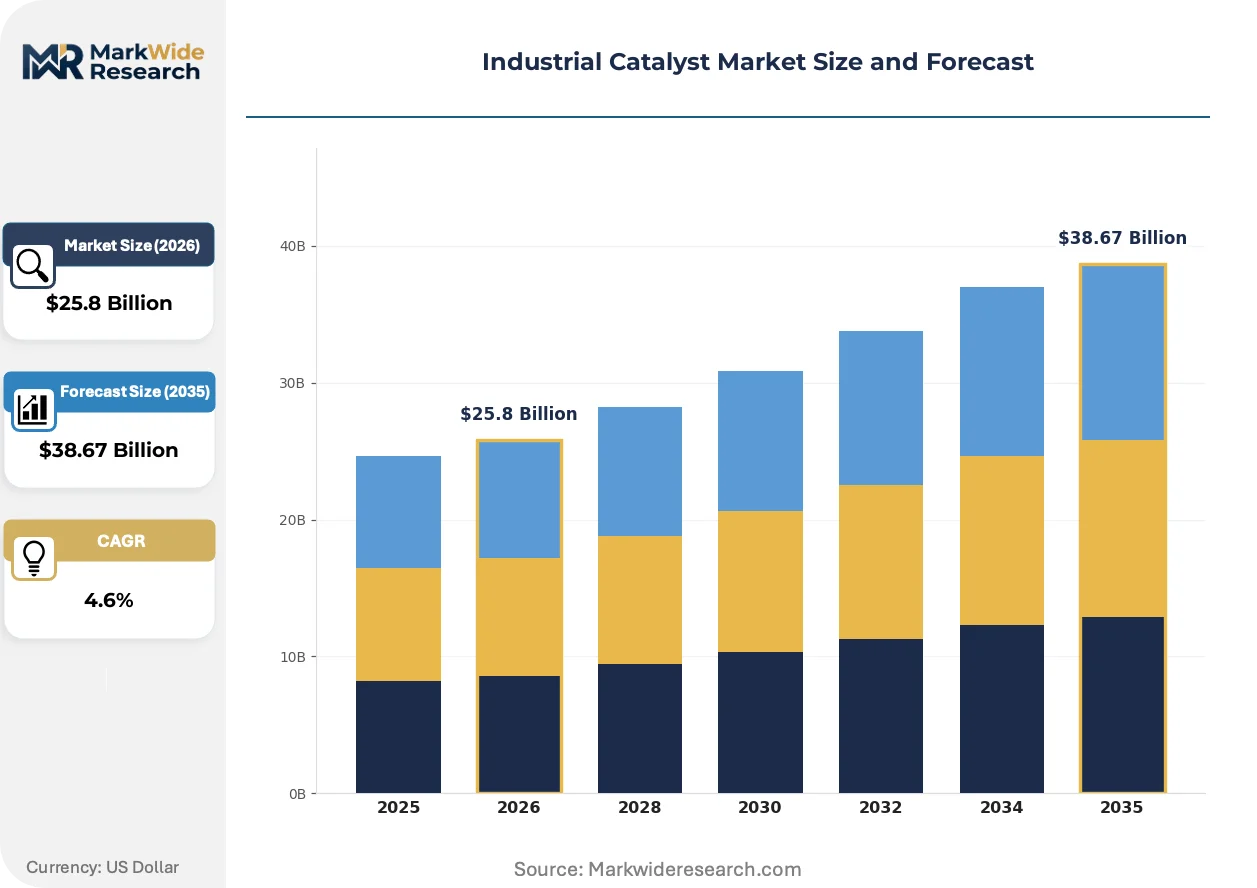
| Market Size in 2026 | $25.8 Billion |
| Market Size in 2035 | $38.67 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Homogeneous Catalysts, Heterogeneous Catalysts, Biocatalysts, Enzymatic Catalysts Application: Chemical Synthesis, Petrochemical Refining, Environmental Protection, Energy Production End User: Petrochemical Industry, Pharmaceutical Industry, Agrochemical Industry, Chemical Manufacturing Technology: Nanotechnology, Microreactor Technology, Surface Modification Technology, Particle Size Reduction |
| Companies Covered | BASF SE, Johnson Matthey, Clariant AG, W.R. Grace, Albemarle Corporation, Evonik Industries AG, Haldor Topsøe, Chevron Phillips Chemical Company, Arkema SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Catalyst Market Strategic Shifts & Innovations
Atomic-scale engineering of active sites and modular reactor architectures are compressing traditional procurement cycles while regulatory emissions limits force simultaneous upgrades to higher-activity, lower-temperature formulations.
Single-atom catalyst deposition is consolidating the competitive landscape around suppliers with advanced characterization capabilities. BASF and Johnson Matthey are deploying these systems in automotive emission-control and selective hydrogenation units. The technology is consolidating procurement decisions toward integrated technology licensors who can guarantee performance across the catalyst-process interface.
REACH authorization and EPA New Source Performance Standards are restricting hazardous precursor chemicals while mandating lower-temperature catalytic activity to cut energy intensity. Formulators must reformulate around restricted cobalt and nickel salts while maintaining hydrodesulfurization performance. European refiners are responding by pre-purchasing multi-year catalyst inventories ahead of anticipated chemical bans.
Buyers are unbundling catalyst supply from full-reactor overhaul contracts, negotiating bed-layer replacement schedules independent of vessel maintenance turnarounds. This disintermediation of integrated service packages favors specialized catalyst suppliers over full-service engineering firms. The pattern is most visible in United States Gulf Coast refineries where modular loading protocols have cut replacement downtime from 21 days to 72 hours.
Industrial Catalyst Market Segmentation
Industrial catalyst procurement varies sharply by operational scale and technical sophistication. Large integrated refineries prioritize regeneration economics and bed-life extension, while specialty chemical producers optimize for batch flexibility and rapid formulation switching.
Product Type:
Buyers differentiate primarily by separation economics and regeneration feasibility in continuous versus batch operations.
- Heterogeneous Catalysts:These formulations combine active metals on porous alumina, silica, or zeolite supports that permit straightforward filtration and thermal regeneration. Petrochemical refineries in China and the United States Gulf Coast specify these for fluid catalytic cracking units where catalyst circulation rates exceed thousands of tons daily. Stricter EPA Tier 3 sulfur limits are forcing upgrades to higher-activity zeolite frameworks that withstand heavier crude processing without accelerated deactivation.
- Homogeneous Catalysts:Dissolved metal complexes operate in single-phase liquid systems where mass transfer limitations disappear. Pharmaceutical manufacturers in Switzerland and Germany specify these for asymmetric hydrogenation steps requiring stereoselectivity above 99%. REACH authorization delays for cobalt and nickel precursors are compressing formulation development timelines and forcing early inventory builds.
- Biocatalysts:Engineered enzymes from extremophile microorganisms enable selective transformations under ambient temperature and pressure.
- Enzymatic Catalysts:Immobilized protein structures derived from fermentation processes serve food and pharmaceutical applications demanding chirality control.
Heterogeneous catalysts lead volumes today; biocatalysts are gaining share fastest.
Application:
Margin pressure and feedstock quality dictate replacement frequency and formulation specification intensity.
- Petrochemical Refining:Hydroprocessing and catalytic cracking units consume catalyst at massive scale as operators process heavier crude slates with elevated sulfur and metal content. Chinese state-owned refiners are commissioning world-scale complexes with continuous replenishment requirements unmatched elsewhere. Modular bed-layer replacement protocols have cut turnaround times from 21 days to 72 hours at United States Gulf Coast facilities.
- Chemical Synthesis:Batch and continuous reactors in fine chemical production employ precious-metal catalysts for hydrogenation, oxidation, and carbon-carbon coupling. German and Swiss pharmaceutical intermediates manufacturers specify single-atom catalyst deposition for selective hydrogenation where metal loading directly determines cost position.
- Environmental Protection:Stationary source emission control and automotive exhaust aftertreatment rely on platinum group metal formulations.
- Energy Production:Fuel cell electrodes and electrolysis catalysts are redirecting R&D budgets toward renewable feedstock conversion systems.
Petrochemical refining dominates absolute consumption; energy production applications are climbing the fastest.
End User:
Volume scale and technical service requirements separate commodity purchasers from specialty formulation buyers.
- Petrochemical Industry:Integrated refining-chemical complexes operate catalyst-intensive processes where annual consumption reaches thousands of tons per facility. Indian Oil and Reliance Industries are building new capacity requiring dedicated supply partnerships with localized technical service teams. EPA and MEE emissions standards are synchronizing around lower-temperature activity mandates that favor next-generation formulations.
- Pharmaceutical Industry:Chiral synthesis and active pharmaceutical ingredient manufacturing demand enantioselective catalysts with batch-to-batch consistency documentation. Swiss and German manufacturers specify ISO 9001-certified suppliers with validated analytical methods for trace metal content.
- Agrochemical Industry:Herbicide and pesticide intermediates production employs solid acid catalysts for alkylation and acylation steps.
- Chemical Manufacturing:Commodity and specialty chemical producers balance catalyst cost against selectivity and cycle time optimization.
The petrochemical industry anchors procurement volumes; pharmaceutical applications show the steepest expansion trajectory.
Technology:
Characterization capability and process integration depth determine supplier differentiation in advanced formulations.
- Nanotechnology:Atomic-level control over active-site density in zeolite frameworks and supported metal clusters improves selectivity while reducing precious-metal loading. BASF and Johnson Matthey are deploying single-atom catalyst systems in automotive emission-control units where characterization capabilities consolidate procurement decisions toward integrated technology licensors.
- Surface Modification Technology:Controlled functionalization of support materials tunes acid-base properties and metal-support interactions for specific feedstock compositions. Clariant AG applies these methods to syngas and methanol catalyst segments with tailored cobalt and copper formulations.
- Microreactor Technology:Structured catalyst packings in millimeter-scale channels intensify heat and mass transfer for hazardous reactions.
- Particle Size Reduction:Spray drying and jet milling operations achieve specific surface areas and pore distributions for diffusion-limited applications.
Nanotechnology-enabled formulations command premium positioning today; microreactor technology is expanding most quickly in flow chemistry adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The industrial catalyst industry traces its modern scaling to German chemical engineering laboratories in the early 20th century, where fixed-bed hydrogenation systems were first commercialized. BASF and IG Farben's Ludwigshafen operations established the template for integrated catalyst-process technology that now dominates global refining and chemical production.
United States
Gulf Coast refineries in Texas and Louisiana process heavier domestic shale crudes that accelerate catalyst depletion rates. EPA Tier 3 sulfur regulations mandate lower-temperature hydrodesulfurization activity, forcing systematic upgrades to higher-activity zeolite formulations. The Houston Ship Channel corridor hosts the densest concentration of fluid catalytic cracking units globally, with operators adopting modular bed-layer replacement protocols that cut turnaround times to 72 hours.
China
State-owned energy groups commission world-scale integrated refining-chemical complexes in Zhejiang and Guangdong provinces with unmatched continuous catalyst replenishment requirements. MEE emissions standards synchronize with EPA Tier 3 limits around lower-temperature activity mandates. The Ningbo-Zhoushan petrochemical cluster operates catalyst circulation rates exceeding thousands of tons daily across fluid catalytic cracking installations.
Germany
Ruhr Valley chemical parks and Ludwigshafen production hubs anchor European catalyst demand for hydroprocessing and emission-control applications. REACH authorization timelines for cobalt and nickel precursors compress formulation development windows and force early inventory builds. The BASF SE headquarters complex maintains integrated catalyst and process technology capabilities that capture bundled refinery contracts across the EU.
India
Reliance Industries and Indian Oil construct refinery-chemical integration units in Gujarat and Maharashtra requiring dedicated catalyst supply partnerships with localized technical service. BIS quality certifications and PLI scheme incentives shape supplier selection criteria for domestic manufacturing scale-up. The Jamnagar refining complex operates catalyst-intensive processes with annual consumption volumes driving regional procurement negotiations.
Saudi Arabia
SABIC and Saudi Aramco operate world-scale petrochemical complexes in Jubail and Yanbu with continuous catalyst replenishment requirements tied to heavy crude processing. The country's national environmental regulator mandates emission reductions that parallel EPA and MEE standards. The King Abdullah Petroleum Studies and Research Center sponsors catalyst R&D programs targeting renewable feedstock conversion systems.
Industrial Catalyst Market Key Industry Players
The competitive structure tilts toward integrated technology licensors with captive process engineering capabilities. Three tiers of participants populate the landscape: diversified chemical conglomerates with catalyst divisions, specialized catalyst houses with deep formulation expertise, and regional fabricators serving local refinery maintenance cycles. Consolidation pressure intensifies as single-atom catalyst deposition technologies concentrate procurement decisions around suppliers with advanced characterization infrastructure. Strategic moves center on backward integration into precursor chemical production and geographic expansion through technical service localization.
Among European-based diversified chemical conglomerates, BASF SE and Evonik Industries AG exemplify the integrated technology licensor archetype that bundles catalyst supply with process design guarantees. Johnson Matthey represents the specialized emission-control catalyst house with deep expertise in platinum group metal formulations. These three occupy positions where characterization capabilities and reactor engineering integration determine competitive viability.
| Leading Market Players |
|---|
| BASF SE |
| Johnson Matthey |
| Clariant AG |
| W.R. Grace |
| Albemarle Corporation |
| Evonik Industries AG |
| Haldor Topsøe |
| Chevron Phillips Chemical Company |
| Arkema SA |
| Others |
Cost & Logistics Intelligence
Palladium price indices on the London Metal Exchange cascade through catalyst formulation economics into three distinct procurement tiers. Refinery operators purchasing platinum group metal formulations face cost pass-through mechanisms that stratify pricing across premium nanostructured zeolites, standard alumina-supported systems, and economy-grade regenerated charges.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement for integrated refineries, with pricing stratifying across premium single-atom catalyst systems, standard high-activity zeolite formulations, and economy-grade regenerated charges. Price differentiation hinges on ISO 9001 certification tier and volume scale commitments above thousand-ton annual volumes. Cost compression in the economy tier is intensifying because South African palladium supply disruptions force reformulation around nickel and cobalt alternatives. Specialty chemical manufacturers show highest price sensitivity due to batch-scale procurement, while Chinese state-owned refiners absorb premium tier costs through integrated complex economics.
Supply Chain Analysis
Platinum group metal supply rests on South African mining operations and Russian palladium exports, with alumina and zeolite support materials drawing from Chinese and German specialty chemical producers. Precursor chemicals including cobalt nitrate, nickel sulfate, and rare earth stabilizers feed from Chinese and Australian processing hubs. Single-source vulnerability concentrates in South African palladium refining capacity, where operational disruptions transmit directly into formulation cost spikes. Distribution runs through regional technical service centers that co-locate catalyst loading crews with major refining clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where refinery operators prioritize bed-life extension and regeneration economics over upfront cost minimization. The demand shift toward EPA Tier 3 and REACH-compliant higher-activity formulations justifies premium positioning for suppliers with advanced characterization capabilities.
For Market Incumbents: Cement procurement lock-in through captive regeneration services and multi-year technical service contracts that embed catalyst supply into refinery maintenance schedules. Defend against modular bed-layer disintermediation by acquiring regional loading contractors in the United States Gulf Coast and Zhejiang province. Prioritize backward integration into cobalt and nickel precursor production to circumvent REACH authorization delays.
For New Entrants and Emerging Players: Small-scale Indian refiners building first-generation hydroprocessing units represent the most penetrable buyer archetype, with Reliance Industries and Indian Oil joint ventures requiring localized technical partnerships. Biomass-to-chemicals conversion catalysts for pyrolysis oil upgrading offer white-space positioning with no incumbent formulation suppliers. Pursue joint development agreements with European electrolysis equipment manufacturers targeting EU Green Deal hydrogen subsidies.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized catalyst houses possessing single-atom deposition capabilities and established REACH registration portfolios. Long-term viability over the next decade favors suppliers with integrated process technology licensing rather than pure formulation manufacturing. Watch for carbon-border adjustment mechanism implementation in the European Union as the inflection signal redirecting R&D budgets toward renewable feedstock conversion systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Chemicals | Captive cobalt and nickel salt production bypasses REACH authorization bottlenecks for BASF and Johnson Matthey. |
| Joint Venture with Indian Refinery Operators | Localized technical service partnerships capture Reliance Industries and Indian Oil capacity buildout in Gujarat. |
| Single-Atom Catalyst Platform Launch | Atomic-level active-site control consolidates procurement decisions toward integrated technology licensors. |
| Long-Term Supply Agreement with PGM Refiners | Fixed-price palladium offtake hedges South African supply volatility for emission-control formulation margins. |
| Green Manufacturing Transition | Lower-temperature catalyst activity aligns with EU Green Deal energy intensity mandates and MEE standards. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured discussions with refinery procurement directors, catalyst plant managers, and technical R&D directors at formulation houses with secondary validation. Primary fieldwork encompassed downstream OEM procurement leads at petrochemical complexes and distribution channel partners managing catalyst logistics. Secondary sources included customs and trade data from major catalyst exporting jurisdictions, SEC 10-K filings from diversified chemical conglomerates, and European Chemicals Agency REACH registration databases. Bottom-up volume modeling triangulated against top-down market sizing from industry association reports.
Historical reference periods anchored the forecast window through verified shipment volumes and replacement cycle documentation across fluid catalytic cracking and hydroprocessing installations. Segmentation dimensions modeled encompassed catalyst type, application intensity, end-user industry scale, and regional regulatory cluster. CAGRs derived from regression analysis of replacement frequency trends and capacity expansion pipelines. Industry-specific inputs included refinery crude slate heavification rates and nanotechnology adoption curves in zeolite framework engineering.
Underlying measurement precision varies by segment; petrochemical refining applications carry tighter precision than emerging biomass conversion categories due to established reporting conventions. Forecasts reflect documented assumptions around regulatory implementation timelines and platinum group metal price trajectories. Supply disruption in South African palladium refining, REACH authorization acceleration, and Chinese state-owned enterprise procurement centralization warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Global Catalyst Market
Catalysts
Organic Catalyst Market
Catalysts
North America Refining Catalysts Market
Catalysts
Sulfur Guard Catalyst Market
Catalysts
Petrochemical Catalyst Market
Catalysts
Polyurethane Catalysts Market
Catalysts
Stationary Emission Control Catalyst Market
Catalysts
Inorganic Catalyst Market
Catalysts
Catalase Market
Catalysts
Global Phase Transfer Catalyst Market
Catalysts
CO2 Reforming Catalysts Market
Catalysts
Hydrogenation Catalyst Market
Catalysts
Polymerization Catalysts Market
Catalysts
South America Refining Catalysts Market
Catalysts
BDO Synthesis Catalyst Market
Catalysts
Asia and Middle East FCC Catalyst Market