
 Refining Catalysts Market | 2026-2036
Refining Catalysts Market Size, Share, and Industry Trends Forecast 2026-2036
Refining Catalysts Market Analytics
EPA Tier 3 sulfur standards is consolidating the cost-of-entry calculus for catalyst suppliers serving North American refiners. Albemarle Corporation leverages its integrated rare earth supply chain to control reforming catalyst costs across the U.S. Gulf Coast. Johnson Matthey Plc anchors its position through sustained R&D intensity in hydrogenation technologies. W. R. Grace & Co. specializes in fluid catalytic cracking catalysts, dominating manufacturing scale for high-zeolite formulations.
Refining catalysts are heterogeneous substances, typically comprising zeolites, alumina, or metal sulfides on porous supports, engineered to accelerate petroleum conversion reactions at 300–500°C and 50–200 bar. They enable the cracking, reforming, and hydroprocessing of crude oil fractions into transportation fuels and petrochemical feedstocks. Fluid catalytic cracking catalysts command the largest volume share due to gasoline production demand across legacy refineries. Hydrocracking catalysts are expanding fastest as refiners pivot toward middle distillate yields and lubricating oil production. Reforming catalysts occupy concentrated margin pools tied to platinum-group metal loadings and regeneration cycles.
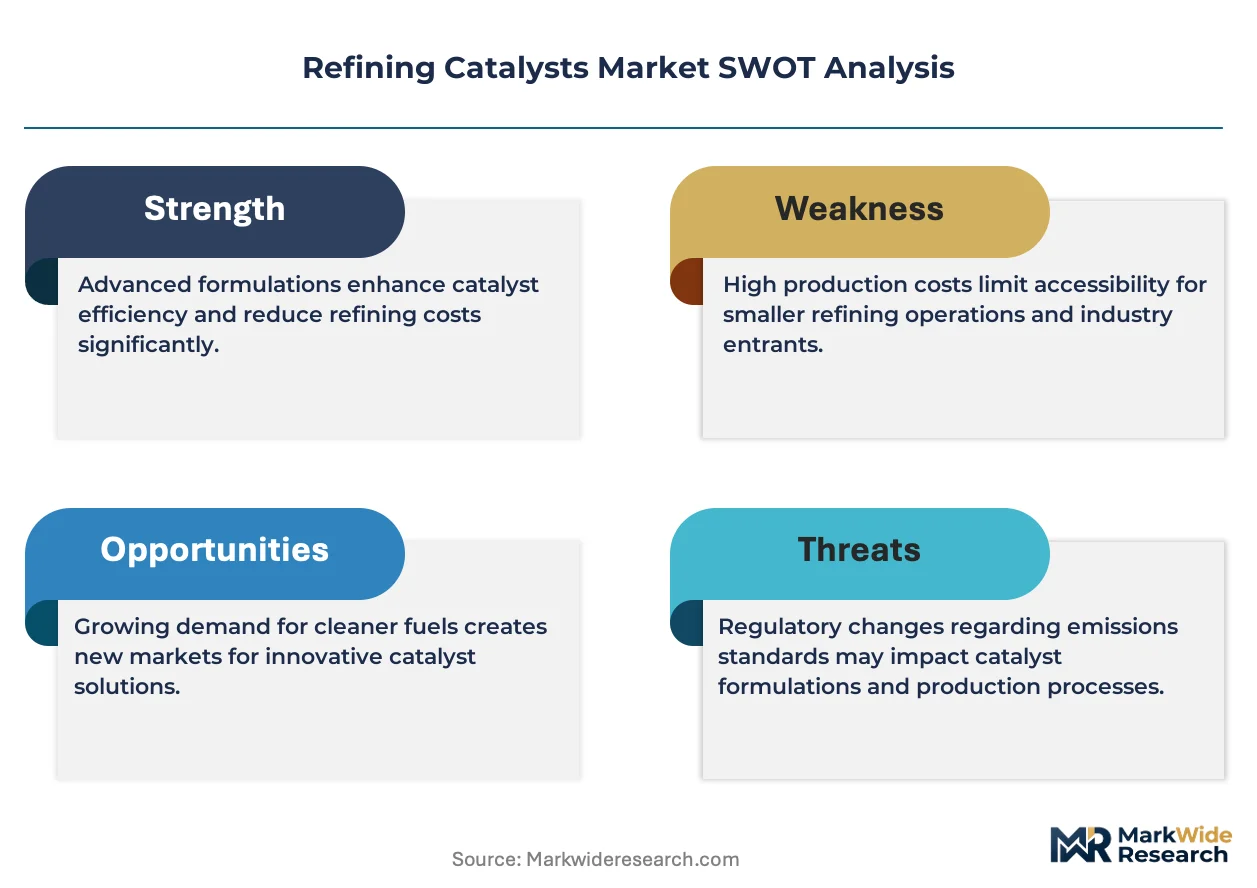
The U.S. EPA enforces sulfur content ceilings under Tier 3, compelling refiners to upgrade hydroprocessing catalysts for gasoline and diesel streams. The EU F-Gas Regulation and REACH framework restrict fluorinated compounds and mandate catalyst lifecycle disclosures for imported refining units. China's MEE enforces dual carbon goals that push refiners toward higher-efficiency catalytic hydrogenation systems. Stakeholders must monitor how tightening sulfur specifications across these jurisdictions reshape catalyst replacement cycles and procurement criteria.
Market Dynamics
Refining catalyst procurement is consolidating around integrated petrochemical complexes in China, where state-backed refiners are building hydroprocessing capacity to handle heavier crude slates and stricter sulfur specifications.
Growth Catalysts
- EPA Tier 3 sulfur ceilings:U.S. refiners must upgrade hydroprocessing catalysts for gasoline and diesel streams, accelerating replacement cycles for high-activity hydrogenation systems.
- Zeolite formulation advances:High-zeolite FCC catalysts now achieve higher gasoline yields from resid feeds, pulling demand from legacy refineries in the U.S. Gulf Coast and Rotterdam.
- China's dual carbon goals:MEE enforcement pushes refiners toward higher-efficiency catalytic hydrogenation systems, concentrating procurement in integrated complexes.
Market Restraints
- Platinum-group metal volatility:Reforming catalyst costs fluctuate with palladium and platinum spot markets, compressing margin pools for suppliers dependent on spot metal sourcing.
- Rare earth supply concentration:Lanthanum and cerium for FCC catalysts concentrate in Chinese processing facilities, exposing non-integrated suppliers to export quota risks.
- REACH catalyst lifecycle disclosures:EU importers of refining units must document full catalyst regeneration and disposal chains, adding compliance friction for non-European suppliers.
Strategic Opportunities
- Middle distillate pivot:Hydrocracking catalyst demand is accelerating as refiners shift from gasoline to diesel, jet fuel, and lubricating oil production.
- Biomass co-processing:FCC catalysts engineered for renewable feedstock integration open white space in European refineries facing RED III mandates.
- Digital catalyst monitoring:IoT-enabled regeneration cycle optimization creates service revenue streams beyond commodity catalyst sales.
Industry Challenges
- Hydroprocessing catalyst R&D talent scarcity:Specialized hydrogenation kinetics expertise concentrates at a handful of university programs and incumbent suppliers.
- Legacy refinery catalyst retrofit complexity:Older FCC units require custom formulation matching to avoid unit shutdowns during changeouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refining Catalysts Market |
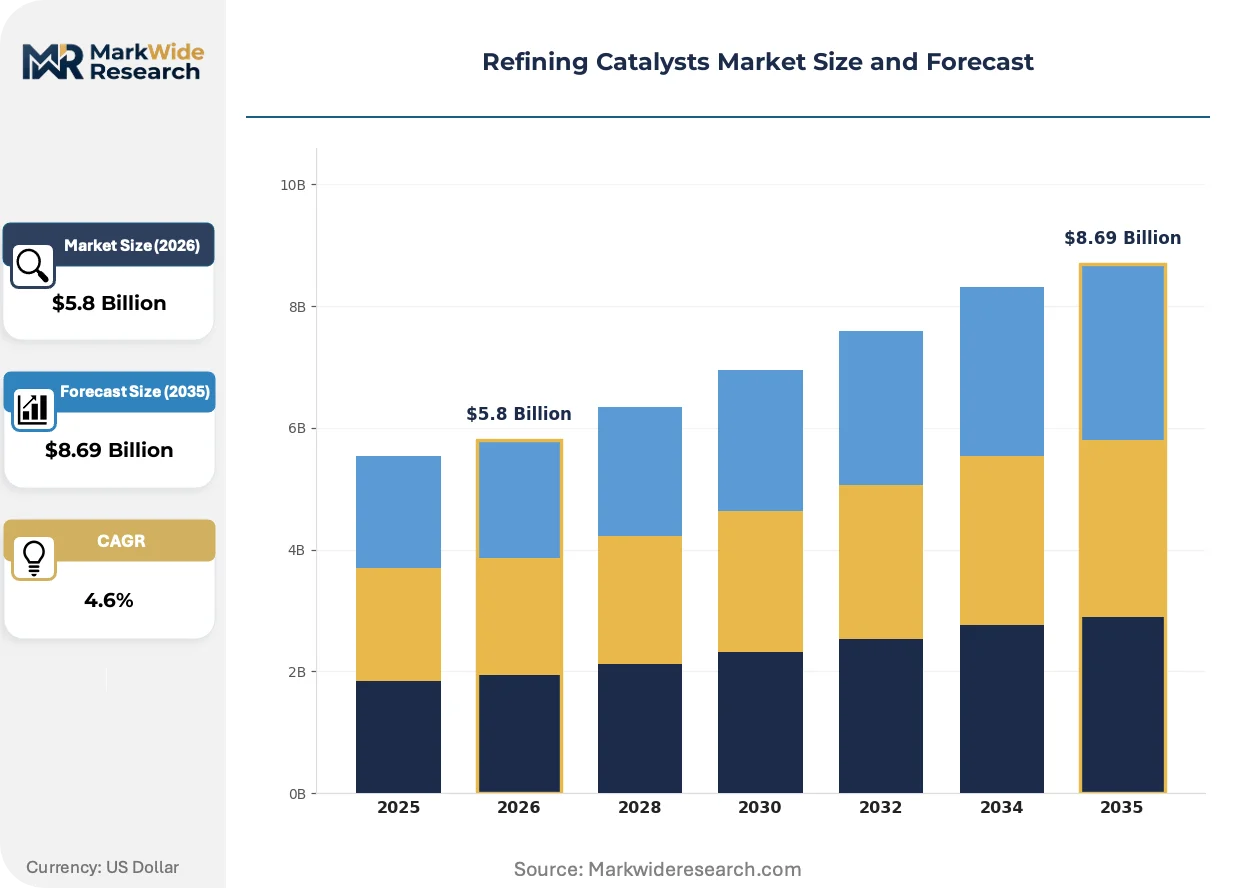
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $8.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrocracking Catalysts, Fluid Catalytic Cracking Catalysts, Reforming Catalysts, Adsorption Catalysts Application: Gasoline Production, Diesel Production, Petrochemical Synthesis, Lubricating Oil Production End User: Refineries, Petrochemical Plants, Oil & Gas Companies, Specialty Chemical Manufacturers Technology: Hydroprocessing, Catalytic Hydrogenation, Isomerization, Oxidative Dehydrogenation |
| Companies Covered | Haldor Topsoe A/S, Johnson Matthey Plc, BASF SE, Clariant AG, ExxonMobil Corporation, Albemarle Corporation, W. R. Grace & Co., Shell Catalyst & Technologies, Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refining Catalysts Market Evolving Landscape
Catalyst technology is pivoting from commodity formulations toward precision-engineered systems that optimize for specific crude slates and regulatory thresholds. Suppliers are embedding sensors and data layers into catalyst regeneration cycles.
Zeolite-metal composite catalysts is converging with advanced manufacturing techniques to produce hierarchical pore structures that resist coking in resid-heavy feeds. U.S. Gulf Coast refiners are piloting these systems for vacuum gas oil conversion. The structural consequence is compressing the performance gap between premium and standard FCC formulations, forcing suppliers to differentiate on service integration rather than base activity metrics.
The EU F-Gas Regulation restricts fluorinated compounds in catalyst manufacturing processes and mandates disclosure of greenhouse gas footprints for imported refining units. European refiners in Rotterdam and Antwerp are now requiring lifecycle assessments from catalyst suppliers before contract renewal. FCC catalyst procurement in the EU is shifting toward suppliers with verified low-fluorine production chains.
Refiners are unbundling catalyst supply from technical service contracts, separating commodity procurement from regeneration optimization and unit troubleshooting. This disintermediation is compressing margins for full-service suppliers while creating openings for specialized catalyst management consultancies. The pattern is most visible in China's state-backed refining sector, where procurement offices now run competitive tenders for catalyst and service separately.
Refining Catalysts Market Segmentation
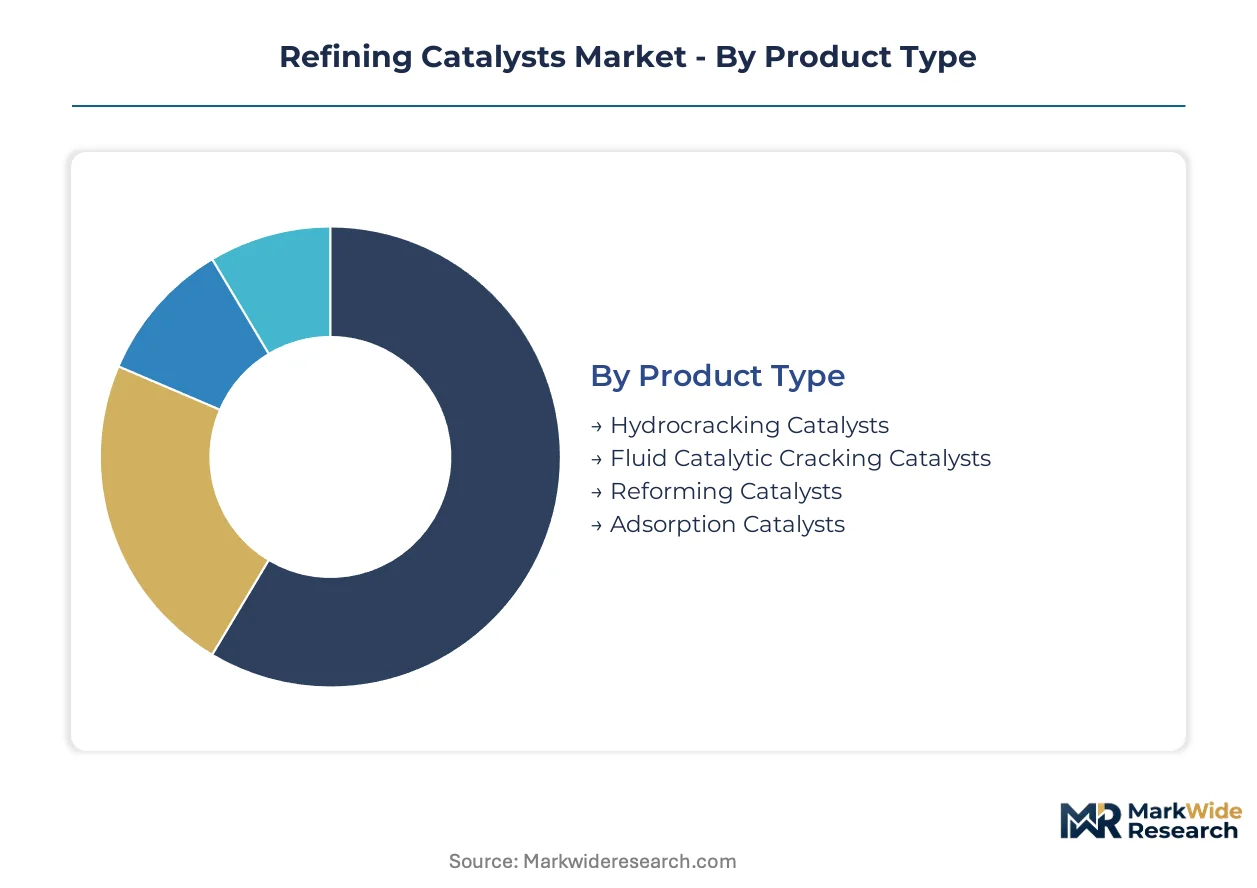
Refining catalyst procurement patterns diverge sharply across product categories, with replacement cycles and upgrade economics dicting supplier selection criteria. Understanding how each segment maps to specific refinery configurations and regulatory thresholds enables precise positioning for catalyst manufacturers and service providers.
Product Type:
Upgrade urgency varies by catalyst family, with regulatory sulfur ceilings and resid processing demands compressing replacement intervals for hydroprocessing systems while reforming catalysts follow metal price cycles.
- Fluid Catalytic Cracking Catalysts:Zeolite-alumina composites engineered for gasoline yield optimization dominate procurement volumes across legacy refineries. Demand concentrates in U.S. Gulf Coast facilities processing heavier crude slates, where resid feed compatibility determines formulation selection and regeneration frequency.
- Hydrocracking Catalysts:Metal-sulfide systems on porous supports enable middle distillate production from vacuum gas oil fractions. Procurement is accelerating in China's integrated petrochemical complexes as state-backed refiners pivot from gasoline toward diesel, jet fuel, and lubricating oil yields.
- Reforming Catalysts:Platinum-group metal loadings on chlorinated alumina supports drive octane enhancement in naphtha streams.
- Adsorption Catalysts:Molecular sieve systems remove sulfur and nitrogen contaminants from refined product streams.
Fluid Catalytic Cracking Catalysts sits at the top of the volume ranking, with Hydrocracking Catalysts climbing the fastest.
Application:
Cost tier differentiation separates premium formulations for ultra-low sulfur diesel from standard grades serving conventional product specifications.
- Gasoline Production:FCC catalysts optimized for high-octane yield from resid-heavy feeds command premium pricing in North American refineries. U.S. EPA Tier 3 sulfur ceilings force continuous formulation upgrades, shortening replacement cycles for gasoline-focused units.
- Diesel Production:Hydroprocessing catalysts achieving ultra-low sulfur specifications face steep demand growth as marine fuel regulations tighten. European refineries in Rotterdam and Antwerp prioritize lifecycle assessment compliance under EU F-Gas mandates when selecting diesel hydrotreating systems.
- Petrochemical Synthesis:Specialized catalysts convert naphtha and gas oil into olefins and aromatics feedstocks.
- Lubricating Oil Production:Hydrocracking catalysts with selective dewaxing functionality target base oil manufacturing.
Gasoline Production retains the largest installed base, though Diesel Production is expanding most quickly as marine and transportation sulfur standards tighten.
End User:
Customer type dictates procurement sophistication, with integrated petrochemical complexes running competitive tender separations between catalyst supply and technical services.
- Refineries:Legacy facilities with FCC and reforming units constitute the core replacement market, with upgrade decisions tied to crude slate flexibility requirements. China's state-backed refining sector is unbundling catalyst procurement from regeneration services, compressing margins for full-service suppliers.
- Petrochemical Plants:Integrated complexes demand high-activity hydrogenation systems for feedstock conversion, with procurement concentrating in coastal China and the U.S. Gulf Coast. MEE enforcement of dual carbon goals pushes these facilities toward higher-efficiency catalytic systems.
- Oil & Gas Companies:Upstream-integrated operators prioritize catalyst standardization across multiple refining assets.
- Specialty Chemical Manufacturers:Niche producers require custom catalyst formulations for specific synthesis applications.
Refineries command the dominant procurement volume, while Petrochemical Plants are gaining share fastest through China's integrated complex buildout.
Technology:
Maturity gradients separate established hydroprocessing platforms from emerging hydrogenation approaches facing talent scarcity constraints.
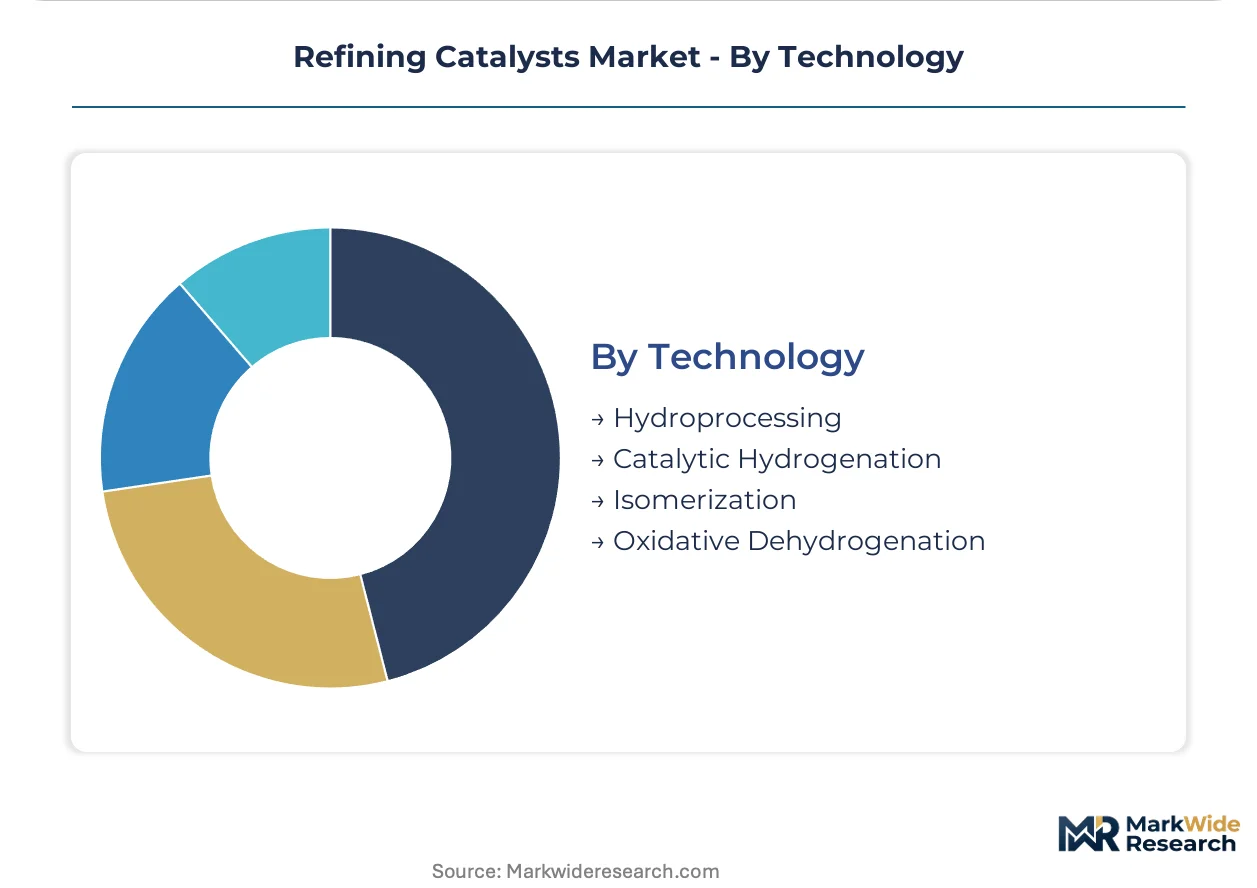
- Hydroprocessing:Hydrotreating and hydrocracking systems for sulfur removal and molecular weight reduction anchor the technology portfolio. U.S. refiners upgrade these systems aggressively to meet EPA Tier 3 gasoline and diesel sulfur ceilings.
- Catalytic Hydrogenation:High-pressure systems for aromatic saturation and olefin conversion serve lubricating oil and middle distillate production. China's MEE dual carbon enforcement is accelerating adoption of higher-efficiency hydrogenation configurations in state-backed complexes.
- Isomerization:Acidic zeolite or chlorided alumina catalysts convert straight-chain paraffins to branched isomers for octane enhancement.
- Oxidative Dehydrogenation:Emerging metal oxide systems target olefin production with reduced hydrogen consumption.
Hydroprocessing maintains the deepest installed base, with Catalytic Hydrogenation showing the steepest expansion trajectory as middle distillate demand rises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized hydrogenation kinetics expertise concentrates in university programs near Houston, Rotterdam, and Beijing. This talent distribution shapes where catalyst manufacturers locate R&D facilities and technical service centers. Procurement patterns follow these concentrations.
United States
EPA Tier 3 sulfur ceilings force continuous hydroprocessing catalyst upgrades across Gulf Coast refineries. The U.S. Gulf Coast cluster processes heavier crude slates, demanding resid-compatible FCC formulations with shortened regeneration cycles. Houston anchors technical service operations for hydrogenation system optimization.
China
State-backed refiners build integrated petrochemical complexes requiring high-activity catalytic hydrogenation systems. MEE enforcement of dual carbon goals pushes facilities toward efficiency-maximizing configurations. Procurement concentrates in coastal provinces where Sinopec and Petrobras operate megacomplexes.
Germany
REACH catalyst lifecycle disclosure mandates create compliance friction for imported refining units. The EU F-Gas Regulation restricts fluorinated compounds in manufacturing processes. Antwerp-Rotterdam refining corridor prioritizes suppliers with verified low-fluorine production chains and full regeneration documentation.
Japan
METI efficiency standards drive adoption of advanced zeolite-metal composite catalysts for vacuum gas oil conversion. Chubu region refineries pilot hierarchical pore structures that resist coking in resid-heavy feeds. Technical partnerships between catalyst suppliers and engineering contractors concentrate in Nagoya-Osaka corridor.
Saudi Arabia
Downstream integration strategies expand hydrocracking capacity for lubricating oil and middle distillate production. The kingdom's refining sector sources catalysts through long-term supply agreements tied to crude flexibility requirements. Jubail Industrial City hosts the largest concentration of catalyst technical service operations in the Middle East.
Refining Catalysts Market Competitive Landscape
The competitive structure tilts toward integrated chemical conglomerates with captive rare earth supply chains. Three tiers separate global technology licensors, regional formulation specialists, and commodity catalyst fabricators. Strategic moves concentrate on backward integration into rare earth processing and technology licensing partnerships for hydrocracking systems.
Among integrated chemical conglomerates, BASF SE and Clariant AG exemplify the diversified materials science archetype, while Albemarle Corporation anchors the rare earth-integrated supplier tier. Johnson Matthey Plc occupies a position bridging catalyst technology and precious metal management services. These three entities represent distinct competitive vectors: formulation breadth, upstream supply control, and technical service integration.
| Leading Market Players |
|---|
| Haldor Topsoe A/S |
| Johnson Matthey Plc |
| BASF SE |
| Clariant AG |
| ExxonMobil Corporation |
| Albemarle Corporation |
| W. R. Grace & Co. |
| Shell Catalyst & Technologies |
| Honeywell International Inc. |
| Others |
Value Network & Pricing Analysis
China's state-backed refining sector concentrates procurement volume in integrated petrochemical complexes, compressing supplier margins through competitive unbundling of catalyst supply from technical services. This buyer concentration forces pricing stratification across premium, standard, and economy tiers tied to regeneration service bundling and rare earth supply security.
Pricing Analysis
The bundled-vs-unbundled service split now dominates catalyst procurement economics. Three-tier pricing structure across premium, standard, and economy levels reflects platinum-group metal loadings and zeolite formulation grades. Cost compression in standard-tier FCC catalysts is intensifying because China's rare earth processing concentration enables aggressive spot-market sourcing. Integrated petrochemical complexes show least price sensitivity due to lifecycle cost optimization mandates, while legacy U.S. Gulf Coast refineries face acute margin pressure from EPA Tier 3 upgrade cycles.
Supply Chain Analysis
Single-source vulnerability sits with Chinese rare earth processing facilities controlling lanthanum and cerium supply for FCC catalysts. Raw material sourcing draws from Chinese rare earth refineries, South African platinum-group metal suppliers, and German specialty chemical manufacturers. Tariff exposure on catalyst precursors shipped to EU refineries under REACH documentation requirements compounds logistics chokepoint risks at Rotterdam-Antwerp ports. Distribution runs through long-term supply agreements anchored to crude flexibility specifications rather than spot procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA Tier 3 sulfur ceilings and EU F-Gas mandates continuously force catalyst replacement cycles, embedding demand visibility for suppliers with compliant formulation pipelines.
For Market Incumbents: Deploy backward integration into rare earth processing to secure cost position against Chinese supply concentration. Lock in multi-year regeneration service contracts with U.S. Gulf Coast refiners before technical service unbundling accelerates. Defend against emerging digital catalyst monitoring specialists by embedding IoT layers into existing hydrogenation system deployments. For New Entrants and Emerging Players: Enter via biomass co-processing catalyst formulations for European refineries facing RED III renewable feedstock mandates. White space concentrates in FCC catalysts engineered for resid-heavy renewable blends, where incumbent formulation pipelines lag regulatory timelines. Go-to-market leverage rests on lifecycle assessment documentation capabilities that satisfy EU F-Gas disclosure requirements without legacy compliance baggage. For Investors and Strategic Acquirers: Chemical conglomerates with captive rare earth supply chains are the most active acquirer in this space, consolidating formulation specialists to fill technology gaps. Long-term viability favors targets with hydrocracking catalyst expertise aligned to middle distillate pivot demand. Watch for MEE enforcement intensity in China's coastal provinces as the signal for accelerated procurement concentration in state-backed complexes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Processing | Albemarle Corporation's captive lanthanum supply secures FCC catalyst cost position against Chinese export quota volatility. |
| Digital Catalyst Monitoring Platform Launch | IoT-enabled regeneration optimization creates recurring service revenue beyond commodity catalyst sales at U.S. refineries. |
| Biomass Co-Processing Formulation Development | FCC catalysts engineered for renewable feedstocks capture RED III compliance budgets at Rotterdam-Antwerp refineries. |
| Hydrocracking Technology Licensing Agreement | Johnson Matthey Plc's hydrogenation IP partnerships accelerate middle distillate pivot capacity in China's integrated complexes. |
| Long-term Supply Agreement with State Refiners | Sinopec and Petrobras procurement concentration rewards suppliers with documented dual carbon goal alignment under MEE enforcement. |
Research Methodology
Bottom-up refinery configuration modeling reconciled against top-down catalyst production tracking forms the analytical core. Primary interviews with hydroprocessing unit managers, catalyst procurement leads at integrated petrochemical complexes, rare earth supply chain directors, and technical R&D heads at major suppliers combined with secondary validation. Trade data from customs filings, EPA enforcement databases, MEE policy circulars, and SEC disclosures from listed chemical conglomerates enabled cross-reference. Top-down and bottom-up estimates converged through iterative reconciliation of replacement cycle assumptions against capacity buildout announcements.
Historical trendline analysis of catalyst consumption per barrel of crude processed established baseline intensity ratios across the projection horizon. Segmentation modeling captured product type, application, end user, and technology dimensions with regional regulatory cluster overlays. CAGRs derived from regression of replacement cycle compression rates against sulfur specification tightening trajectories. Forecast inputs incorporated crude slate heaviness indices and dual carbon policy enforcement intensity from Chinese regulatory filings.
Inputs from refinery operations databases and catalyst supplier disclosures were available through the study window; gaps in proprietary formulation cost structures introduce uncertainty bands around margin projections. Forecasts reflect documented assumptions regarding EPA Tier 3 implementation pace and EU F-Gas disclosure adoption timelines. Rare earth export policy shifts or abrupt marine sulfur standard revisions could materially alter replacement cycle economics. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Zeolite Molecular Sieve Market
Catalysts
Global FCC Catalyst Market
Catalysts
Rhodium Carbon Catalyst Market
Catalysts
Fluid Catalytic Cracking Catalyst Market
Catalysts
Refinery Catalyst Market
Catalysts
Catalyst Regeneration Market
Catalysts
Sulfur Guard Catalyst Market
Catalysts
Copper Bismuth Catalyst Market
Catalysts
Steam Methane Reforming Market
Catalysts
Stationary Emission Control Catalyst Market
Catalysts
Oxalate Hydrogenation Catalyst Market
Catalysts
Global Light Powered Catalyst Market
Catalysts
Global Catalyst Market
Catalysts
Primary Reforming Catalyst Market
Catalysts
CO2 Reforming Catalysts Market
Catalysts
Global Emission Control Catalyst (ECC) Market